
 Prenatal Diagnostics Market | 2026-2036
Prenatal Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal Diagnostics Market Outlook
Reimbursement for cell-free DNA screening is reshaping margin distribution between laboratory service providers and clinical interpretation platforms. Illumina, Inc. leverages its sequencing instrument installed base to sustain reagent pull-through in high-volume prenatal screening programs. F. Hoffmann-La Roche Ltd. competes through integrated workflow automation that anchors its position in centralized laboratory networks. Natera, Inc. specializes in proprietary bioinformatics pipelines that differentiate its non-invasive testing portfolio from commodity alternatives.
Prenatal diagnostics encompasses biochemical, cytogenetic, and molecular techniques applied during gestation to assess fetal health status, including cell-free DNA analysis from maternal plasma, karyotyping, and microarray-based comparative genomic hybridization with detection thresholds reaching sub-chromosomal microdeletions. These technologies enable early identification of aneuploidies and single-gene disorders to inform pregnancy management decisions. Non-invasive prenatal testing commands the dominant share of product type revenue due to superior safety profiles and expanding gestational-age windows, while ultrasound retains foundational utility for anatomical assessment despite lower per-procedure yields. Among delivery modes, in-hospital testing dominates transaction volumes, though telemedicine-enabled genetic counseling is capturing margin pools by reducing specialist access barriers in underserved geographies.
FDA oversight of laboratory-developed tests and CLIA certification requirements shape analytical validity standards for cell-free DNA platforms entering clinical use. EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment burdens on European market access that favor established manufacturers with notified body relationships. WHO prequalification initiatives for essential diagnostics are creating procurement pathways in lower-resource settings that demand cost-optimized test formats. Stakeholders must monitor evolving payer coverage determinations for expanded carrier screening panels as these decisions will determine addressable population thresholds and test menu breadth.
Market Dynamics
Non-invasive prenatal testing technology is displacing invasive diagnostic procedures across hospital obstetric departments, compressing the addressable market for amniocentesis and chorionic villus sampling while expanding screening volumes through safer, earlier detection windows.
Growth Catalysts
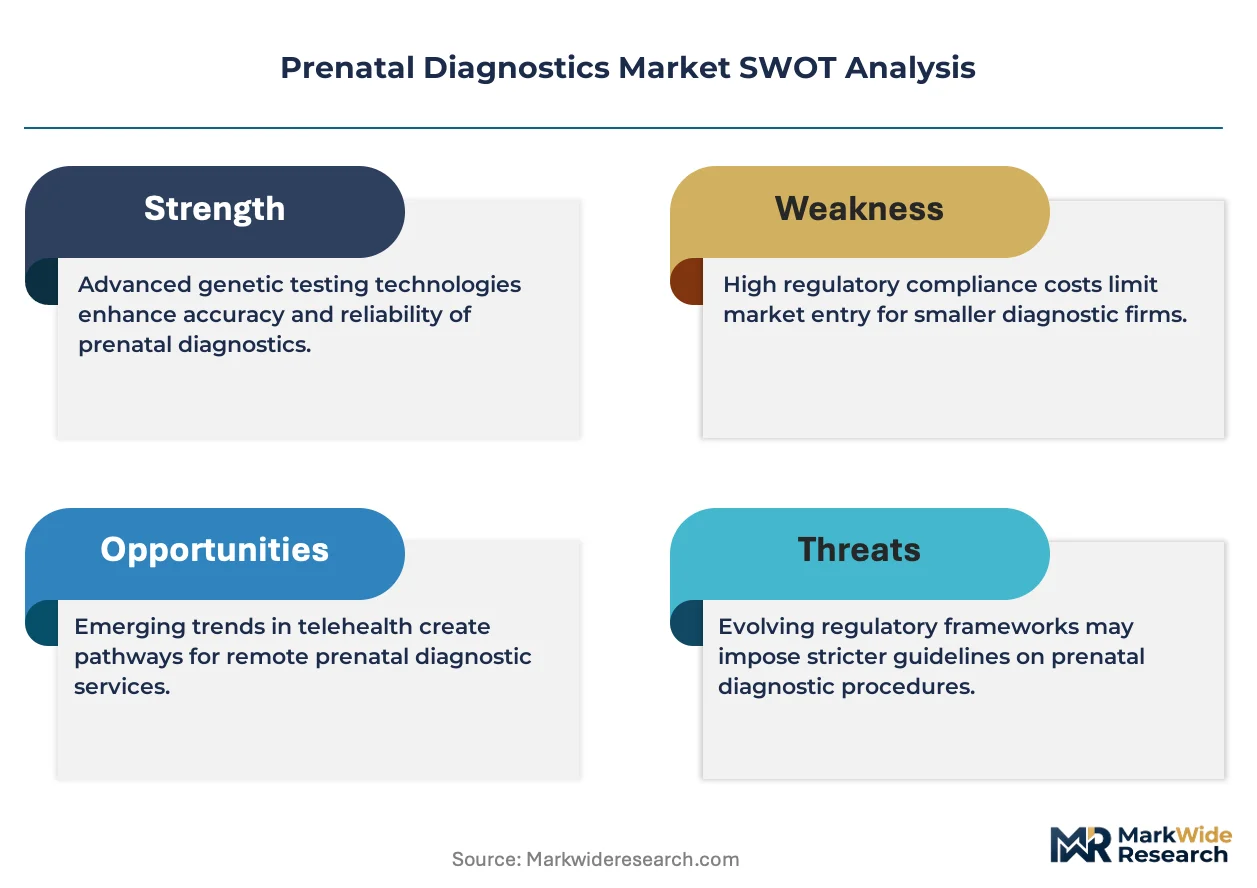
- FDA guidance frameworks:Updated oversight of laboratory-developed tests has clarified analytical validity standards for cell-free DNA platforms, accelerating clinical adoption in US integrated health systems.
- Expanded gestational-age windows:Technical refinements in maternal plasma extraction now enable reliable screening from 10 weeks gestation, broadening eligible patient populations and test frequency.
- Integrated health systems:Hospital-based obstetric departments in the United States are consolidating prenatal screening workflows, driving standardized test menus and volume commitments.
Market Restraints
- Reimbursement variability:Payer coverage determinations for expanded carrier screening panels remain inconsistent across US state Medicaid programs, constraining addressable population thresholds.
- Sequencing reagent concentration:Supply of proprietary polymerases and fluorescent nucleotides concentrates among three specialty chemical manufacturers, creating input cost volatility for assay developers.
- Technical detection floors:Cell-free DNA platforms face fundamental sensitivity limits for sub-chromosomal microdeletions below 5 megabases, preserving niche demand for invasive confirmatory testing.
Strategic Opportunities
- WHO prequalification pathways:Essential diagnostics initiatives for lower-resource settings are creating procurement channels that reward cost-optimized test formats with simplified cold-chain requirements.
- Telemedicine-enabled counseling:Remote genetic counseling platforms are reducing specialist access barriers in rural US counties and underserved European regions, capturing margin pools previously lost to geographic friction.
- Single-gene disorder expansion:Convergence of cell-free DNA analysis with targeted next-generation sequencing is opening screening for autosomal recessive conditions beyond aneuploidy detection.
Industry Challenges
- Bioinformatics talent scarcity:Clinical interpretation platforms require computational biologists with dual training in obstetric medicine and variant classification, a skill combination concentrated at academic medical centers.
- CLIA certification timelines:Analytical validity documentation for new cell-free DNA assays faces 18-24 month review cycles, compressing product launch windows against competitive pressure.
- Legacy ultrasound integration:Hospital IT systems require custom middleware to harmonize NIPT results with anatomical imaging workflows, extending implementation timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal Diagnostics Market |
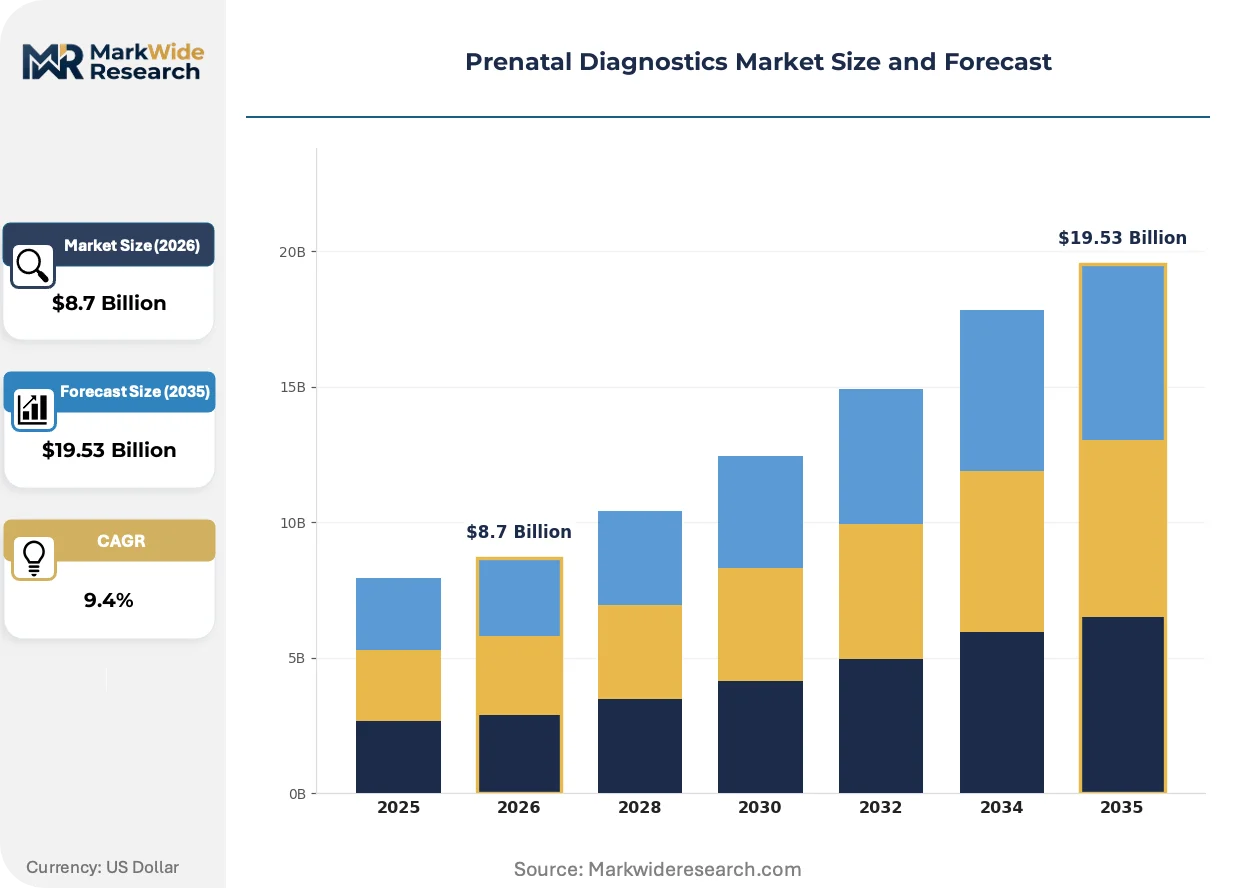
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Invasive Prenatal Testing, Amniocentesis, Chorionic Villus Sampling, Ultrasound Delivery Mode: In-Hospital, Home-Based, Mobile Services, Telemedicine End User: Obstetricians, Genetic Counselors, Laboratories, Healthcare Providers Application: Chromosomal Disorders, Genetic Disorders, Blood Type Determination, Gender Identification |
| Companies Covered | Illumina, Inc., F. Hoffmann-La Roche Ltd., Natera, Inc., Laboratory Corporation of America Holdings, Eurofins Scientific SE, BGI Genomics Co., Ltd., Centogene NV, Berry Genomics, Revvity, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal Diagnostics Market Strategic Shifts
Digital infrastructure is restructuring how prenatal screening data flows between laboratories, clinicians, and patients, collapsing traditional boundaries between sample processing and clinical decision support.
Artificial intelligence-based variant interpretation is virtualizing the clinical reporting pipeline, automating benign polymorphism filtering and pathogenicity scoring that previously required manual curator review. High-volume prenatal screening programs at US academic medical centers are deploying these tools to maintain turnaround times as test menus expand. This compression of interpretation labor is enabling laboratories to scale screening volumes without proportional staffing increases.
EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment burdens on European market access that favor established manufacturers with notified body relationships. Small assay developers face capital requirements for technical documentation and quality management system certification that exceed prior CE-marking thresholds. The regulation is compressing the vendor base in Germany, France, and the Netherlands toward integrated diagnostic companies with dedicated regulatory affairs functions.
Direct-to-consumer genetic testing platforms are fragmenting traditional referral pathways, with patients presenting to obstetric practices having already purchased carrier screening or ancestry-informed risk assessments. This bypass of clinical gatekeeping is forcing US hospital laboratories to develop reconciliation protocols for externally generated data. The phenomenon is most visible in California and Massachusetts metropolitan corridors where consumer genomics penetration exceeds national averages.
Prenatal Diagnostics Market Segmentation
Segmentation in prenatal diagnostics reveals how technology platforms, care delivery models, and clinical workflows allocate margin across the value chain. Understanding these divisions exposes where sequencing reagent pull-through concentrates and where telemedicine-enabled counseling captures previously inaccessible patient populations.
Product Type:
After-sales service intensity varies dramatically across product categories, with sequencing instrument maintenance contracts and bioinformatics update subscriptions creating recurring revenue streams that reshape manufacturer-customer relationships.
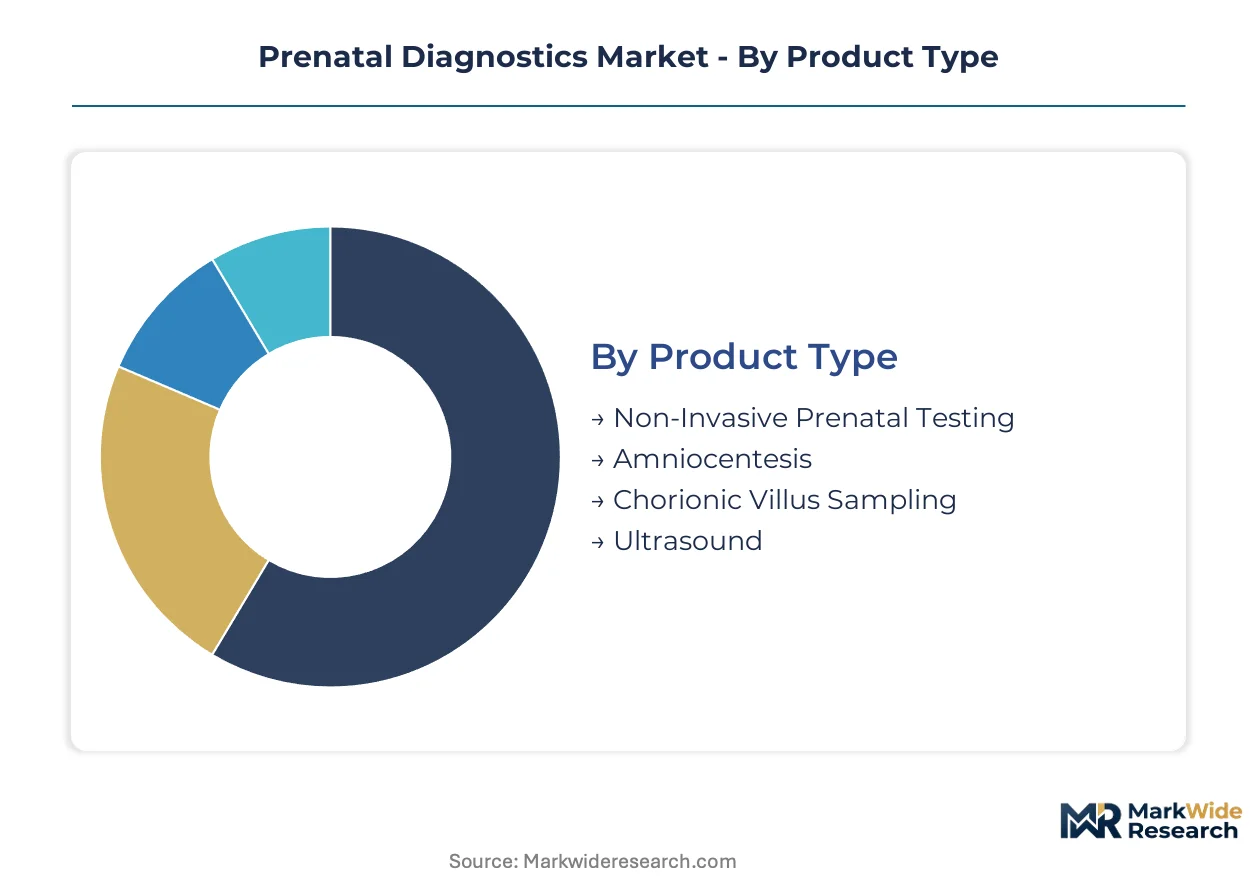
- Non-Invasive Prenatal Testing:Cell-free DNA analysis from maternal plasma enables screening from 10 weeks gestation with superior safety profiles. Demand concentrates in United States integrated health systems consolidating standardized test menus under FDA-cleared platforms.
- Amniocentesis:Invasive procedure involving amniotic fluid aspiration for karyotyping and microarray analysis retains confirmatory utility despite declining volumes. Niche demand persists for sub-chromosomal microdeletions below cell-free DNA detection thresholds.
- Chorionic Villus Sampling:First-trimester placental tissue biopsy provides earlier diagnostic certainty for high-risk pregnancies. Procedure volumes compress as non-invasive alternatives expand gestational-age windows.
- Ultrasound:Anatomical imaging retains foundational screening utility with lower per-procedure yields. Hospital IT systems require custom middleware to harmonize results with molecular testing workflows.
Non-Invasive Prenatal Testing holds the largest share; momentum sits with Ultrasound as artificial intelligence-based interpretation automates anatomical assessment.
Delivery Mode:
Cost tier stratification separates capital-intensive hospital infrastructure from asset-light remote service models, with reimbursement differentials determining viable geographic penetration.
- In-Hospital:Centralized laboratory networks anchor high-volume screening programs with integrated workflow automation. United States academic medical centers deploy artificial intelligence-based variant interpretation to maintain turnaround times.
- Home-Based:Direct-to-consumer sample collection kits fragment traditional referral pathways, forcing reconciliation protocols for externally generated data in California and Massachusetts metropolitan corridors.
- Mobile Services:Deployable ultrasound and phlebotomy units extend screening access to rural counties with specialist shortages. WHO prequalification pathways reward cost-optimized formats with simplified cold-chain requirements.
- Telemedicine:Remote genetic counseling platforms reduce access barriers in underserved geographies, capturing margin pools previously lost to geographic friction in rural United States counties.
In-Hospital dominates transaction volumes; Telemedicine is expanding most quickly as regulatory clarity enables cross-state practitioner licensing.
End User:
Customer type determines purchasing authority, with obstetric departments controlling test menu standardization while genetic counselors influence patient-facing interpretation workflows.
- Obstetricians:Hospital-based obstetric departments drive volume commitments through consolidated screening protocols. CLIA certification timelines for new assays compress product launch windows against competitive pressure.
- Genetic Counselors:Clinical interpretation platforms require computational biologists with dual training in obstetric medicine and variant classification, a skill combination concentrated at academic medical centers.
- Laboratories:Reagent pull-through concentrates among high-throughput screening programs with installed sequencing instrument bases. Supply of proprietary polymerases creates input cost volatility.
- Healthcare Providers:Integrated health systems standardize prenatal screening workflows across affiliated clinics, driving menu breadth and frequency commitments.
Obstetricians hold the largest share; momentum sits with Genetic Counselors as telemedicine platforms expand specialist access.
Application:
Volume concentration follows aneuploidy detection while margin expansion targets expanded carrier screening panels with inconsistent payer coverage across United States state Medicaid programs.
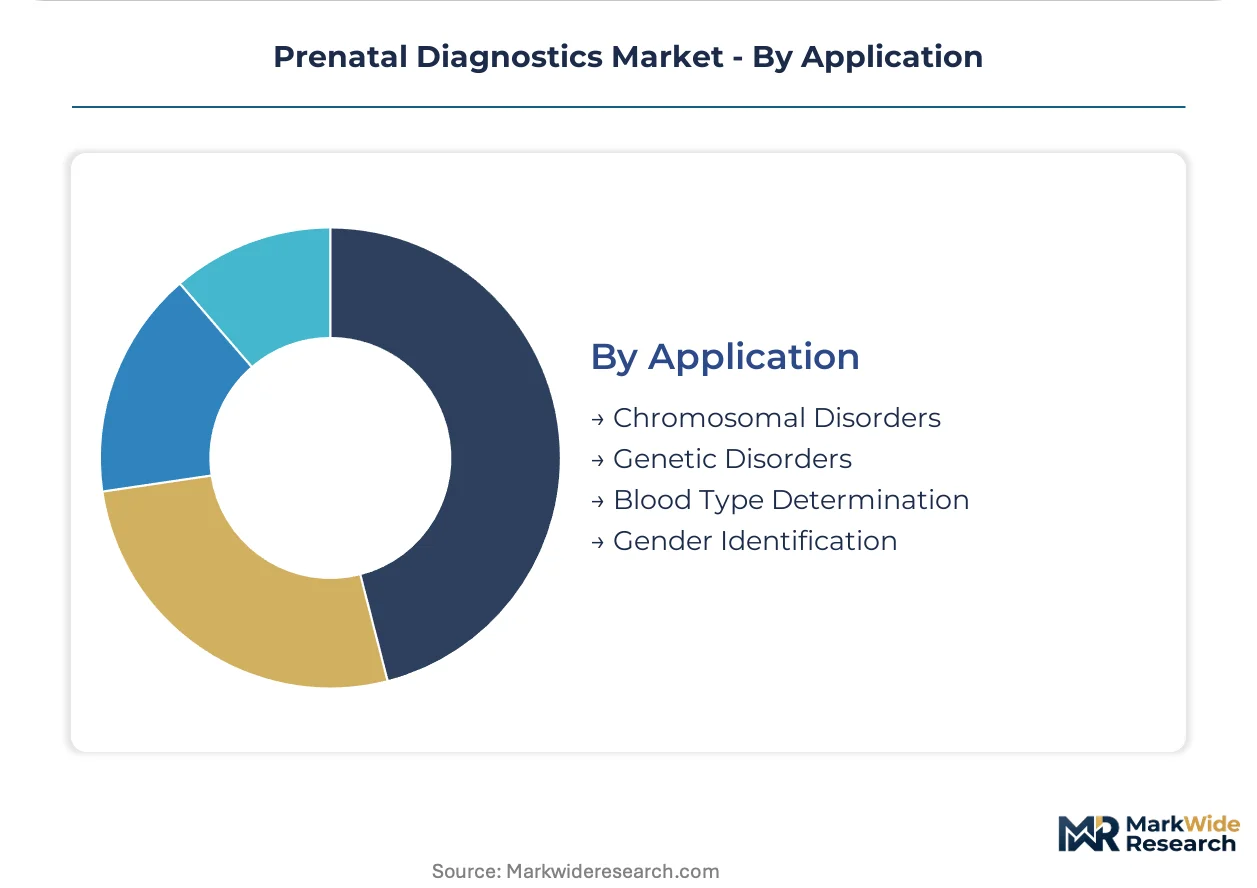
- Chromosomal Disorders:Trisomy screening commands dominant transaction volumes with established clinical utility and reimbursement pathways. Technical refinements in maternal plasma extraction broaden eligible patient populations.
- Genetic Disorders:Single-gene disorder screening converges cell-free DNA analysis with targeted next-generation sequencing for autosomal recessive conditions. EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment burdens favoring established manufacturers.
- Blood Type Determination:Fetal RhD genotyping from maternal plasma reduces unnecessary immunoglobulin administration. Applications concentrate in European and United States high-risk pregnancy protocols.
- Gender Identification:Early fetal sex determination serves hemophilia and Duchenne muscular dystrophy carrier screening workflows. Regulatory restrictions vary across United States state jurisdictions.
Chromosomal Disorders holds the largest share; Genetic Disorders shows the steepest expansion trajectory as sequencing costs enable broader panel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: the United States prioritizes high-throughput screening consolidation, while European markets emphasize regulatory conformity, and Asia-Pacific concentrates on cost-optimized test formats for population-scale programs.
United States
Integrated health systems in California and Massachusetts drive volume concentration through standardized cell-free DNA menus. FDA guidance frameworks clarify analytical validity standards for laboratory-developed tests, accelerating clinical adoption. The Greater Boston corridor anchors artificial intelligence-based variant interpretation deployment at academic medical centers.
Germany
Centralized laboratory networks in North Rhine-Westphalia and Bavaria favor automated workflow integration for high-volume screening. EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment burdens that compress the vendor base toward established manufacturers. The Munich-Stuttgart axis concentrates notified body relationships and quality management certification expertise.
China
Population-scale screening initiatives in the Yangtze River Delta and Pearl River Delta demand cost-optimized test formats with simplified logistics. NMPA oversight of in vitro diagnostic medical devices shapes market entry pathways for sequencing platforms. Shenzhen and Shanghai anchor domestic manufacturing clusters for polymerase and fluorescent nucleotide supply.
United Kingdom
NHS England's consolidated procurement frameworks drive standardized test menu adoption across obstetric networks. MHRA post-Brexit regulatory autonomy creates divergence from EU conformity assessment timelines. The London-Oxford-Cambridge triangle concentrates bioinformatics talent and clinical interpretation platform development.
India
Private hospital chains in Maharashtra and Karnataka expand screening access for affluent patient segments amid limited public coverage. CDSCO medical device regulations impose import licensing requirements on sequencing instrument suppliers. The Mumbai-Pune corridor anchors reference laboratory networks serving tier-1 metropolitan demand.
Prenatal Diagnostics Market Competitive Environment
Capability concentration sits with specialized bioinformatics developers; scale advantage sits with integrated diagnostic conglomerates. The market structures around three tiers: sequencing instrument manufacturers capturing reagent pull-through, laboratory service providers consolidating screening volumes, and clinical interpretation platforms differentiating through proprietary algorithms. Dominant competitive moves include workflow automation partnerships and regulatory certification acceleration.
Within the sequencing platform tier, Illumina, Inc. and BGI Genomics Co., Ltd. occupy positions that exemplify contrasting geographic anchors—US-based instrument dominance versus China-based cost-optimized manufacturing. F. Hoffmann-La Roche Ltd. represents the integrated diagnostic archetype, with workflow automation capabilities that anchor centralized laboratory relationships. These three entities illustrate how competitive positioning fragments across technology control points rather than consolidating under unified portfolios.
| Leading Market Players |
|---|
| Illumina, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Natera, Inc. |
| Laboratory Corporation of America Holdings |
| Eurofins Scientific SE |
| BGI Genomics Co., Ltd. |
| Centogene NV |
| Berry Genomics |
| Revvity, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shenzhen-Shanghai polymerase freight corridor channels fluorescent nucleotide shipments through NMPA-licensed customs zones, concentrating input cost volatility among three specialty chemical manufacturers while downstream price differentiation splits between high-throughput hospital networks and cost-optimized mobile screening units.
Pricing Analysis
Long-term reagent offtake contracts anchor pricing for Illumina sequencing instrument operators, while spot procurement dominates smaller assay developers lacking volume commitments. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification tier and bioinformatics service bundling. Cost compression in economy-tier cell-free DNA panels is intensifying because WHO prequalification pathways reward stripped-down cold-chain formats. Academic medical centers show least price sensitivity due to bundled workflow automation; rural mobile services face acute margin pressure from reimbursement variability.
Supply Chain Analysis
Export-control restrictions on next-generation sequencing platforms limit instrument flows from the United States to Chinese laboratory networks, compressing vendor alternatives in the Yangtze River Delta. Manufacturing concentrates in China, the United States, and Germany for polymerases, sequencing consumables, and automated liquid handlers respectively. The supply chain draws from proprietary fluorescent nucleotides, maternal plasma collection tubes, and cloud-based variant interpretation infrastructure. Single-source vulnerability concentrates in specialty enzyme suppliers. Distribution runs through centralized laboratory networks with direct-to-consumer kits fragmenting last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States integrated health systems consolidating standardized test menus, compressing vendor margins and forcing renegotiation of long-term reagent contracts.
For Market Incumbents: Insulate sequencing instrument installed bases through exclusive bioinformatics update subscriptions that lock hospital laboratories into proprietary variant interpretation pipelines. Deepen backward integration into polymerase manufacturing to dampen input cost volatility from the three dominant specialty chemical suppliers. Anchor CLIA-certified laboratory partnerships before FDA guidance frameworks harden analytical validity documentation requirements. For New Entrants and Emerging Players: Pursue telemedicine-enabled genetic counseling white space in rural United States counties and underserved European regions where specialist access barriers preserve margin pools. Target mobile screening services in lower-resource settings eligible for WHO prequalification procurement channels. Lead with simplified cold-chain logistics and cost-optimized test formats rather than competing on detection sensitivity. For Investors and Strategic Acquirers: Clinical interpretation platforms with proprietary AI-based variant filtering algorithms represent the most defensible acquisition archetype as test menu expansion outpaces manual curation capacity. Monitor FDA coverage determinations for expanded carrier screening panels as the inflection signal; favorable rulings would unlock addressable population thresholds and justify premium valuations for menu-breadth leaders.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Acceleration | Shortens 18-24 month assay review cycles to outpace competitive launches under FDA oversight. |
| Telemedicine Counseling Platform | Captures margin pools in rural counties by reducing specialist access barriers. |
| Polymerase Backward Integration | Dampens input cost volatility from concentrated specialty chemical suppliers. |
| WHO Prequalification Pathway | Unlocks procurement channels in lower-resource settings demanding simplified logistics. |
| AI Variant Interpretation Deployment | Automates benign polymorphism filtering to scale screening volumes without proportional staffing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA In Vitro Diagnostic Medical Devices Regulation submissions, and CMS Medicare reimbursement databases. Interviews with laboratory directors at academic medical centers, genetic counselors in telemedicine platforms, sequencing instrument procurement managers, and CLIA certification consultants anchor demand-side validation. Supply-side perspectives draw from diagnostic reagent manufacturers and notified body representatives. Bottom-up test volume estimates triangulate against top-down health system expenditure data.
Forecast inputs span product type segmentation across non-invasive prenatal testing, amniocentesis, chorionic villus sampling, and ultrasound; delivery mode splits between in-hospital, home-based, mobile services, and telemedicine; end-user concentration among obstetricians, genetic counselors, laboratories, and healthcare providers; and application segmentation from chromosomal disorders through single-gene disorder expansion. CAGRs derive from fitted adoption curves weighted by gestational-age window expansion and payer coverage trajectory. Reagent pull-through modeling incorporates installed sequencing instrument base depreciation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by BGI Genomics or domestic Chinese manufacturers to undercut reagent pricing would shift outcomes. Material shifts in FDA laboratory-developed test guidance or EMA conformity assessment timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Antimicrobial Resistance Diagnostics Market
Diagnostics
Point of Care (Poc) Molecular Diagnostics Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Global Creatinine Measurement Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Immunodiagnostics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Europe Antinuclear Antibody Test Market
Diagnostics
Autoimmunity Immunoassay Market