
 Global Saliva Collection and Diagnosis Market | 2026-2036
Global Saliva Collection and Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saliva Collection and Diagnosis Market Foresight
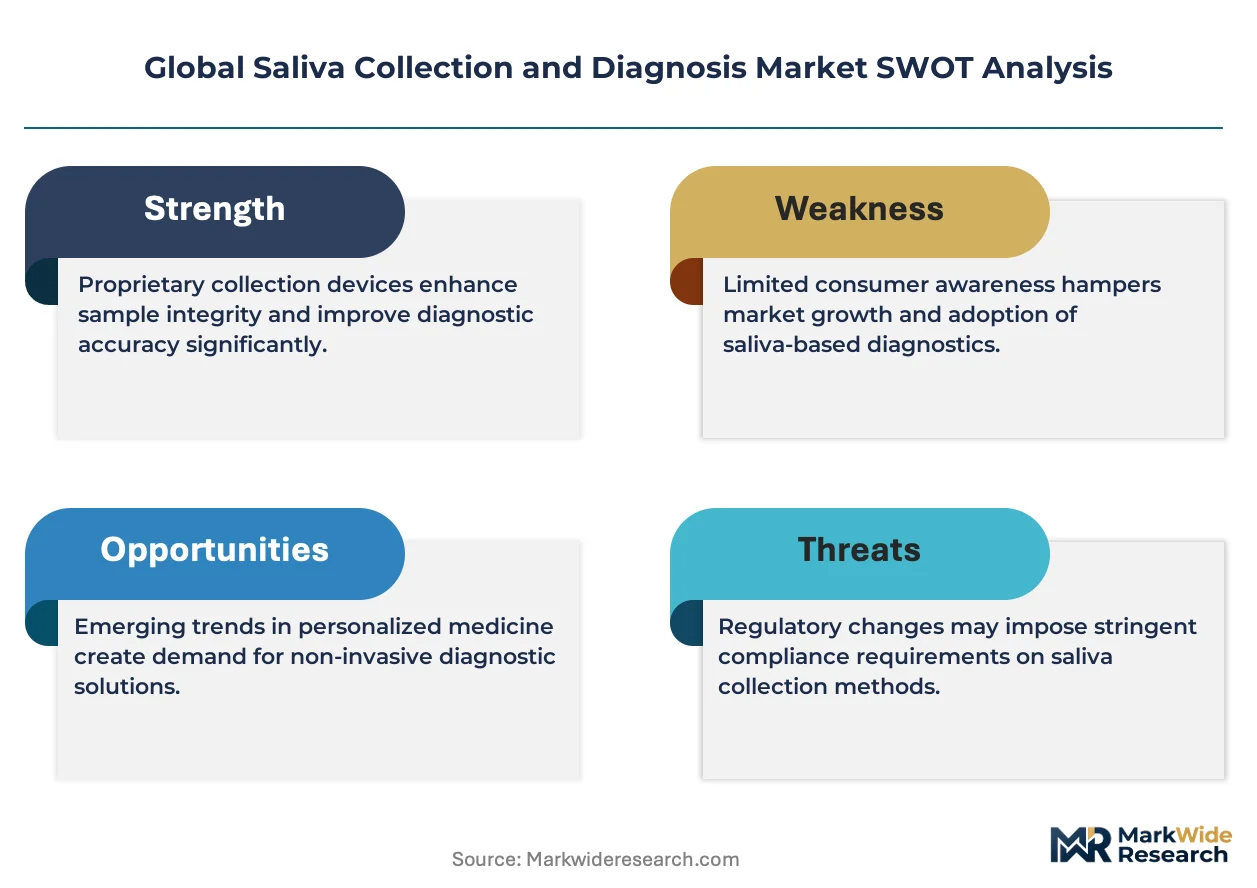
CE marking under the EU In Vitro Diagnostic Regulation is unwinding market access for smaller kit manufacturers across Europe. Thermo Fisher Scientific leverages its integrated reagent-instrument workflow to sustain leadership in PCR-based saliva diagnostics. Neogen Corporation anchors its position through veterinary and food safety crossover applications of saliva extraction technologies. Abbott Laboratories competes via point-of-care immunoassay platforms calibrated for minimally processed oral fluid specimens.
Saliva collection and diagnosis encompasses the engineered capture, stabilization, extraction, and analytical processing of oral fluid specimens for biomarker detection, typically requiring pH-buffered collection tubes with antimicrobial preservatives and temperature-stable transport matrices to maintain nucleic acid and protein integrity. The primary commercial purpose is to enable non-invasive disease surveillance, pharmacokinetic monitoring, and genetic screening without venipuncture. Collection devices and diagnostic kits together command the largest revenue share, while microfluidics-enabled biosensors represent the fastest-expanding technology segment as lab-on-chip formats reduce sample volume requirements and turnaround times. Diagnostic laboratories remain the dominant end-user channel, though point-of-care facilities are capturing disproportionate growth as CLIA-waived saliva assays proliferate.
The FDA oversees premarket notification and clinical validation requirements for saliva-based IVDs in the United States, while the EMA's In Vitro Diagnostic Regulation mandates notified body certification for European market entry, collectively elevating quality system burdens for kit developers. ISO 13485 compliance and CAP laboratory accreditation further constrain which suppliers can serve institutional buyers. Stakeholders must monitor regulatory divergence between decentralized testing frameworks and centralized laboratory oversight as reimbursement policies for at-home saliva collection crystallize.
Market Dynamics
Decentralized testing authorization is compressing the traditional laboratory channel as CLIA-waived saliva assays migrate collection from centralized facilities to retail pharmacies and direct-to-consumer platforms. This structural reconfiguration redistributes value capture toward collection device manufacturers and point-of-care platform developers while eroding reference laboratory margins.
Growth Catalysts
- Liquid biopsy expansion:FDA guidance on circulating tumor DNA detection in oral fluid is opening oncology surveillance applications previously restricted to plasma specimens. Academic medical centers in the United States are validating saliva-based mutational profiling protocols for longitudinal monitoring.
- Pharmacogenomic screening:Payers in Germany and the Netherlands are reimbursing CYP2C19 and CYP2D6 genotyping from saliva for psychiatric medication selection. This indication expansion pulls collection kit volumes into therapeutic drug monitoring workflows.
- Stabilization chemistry advances:Room-temperature nucleic acid preservation formulations are eliminating cold-chain logistics for direct-to-consumer genetic testing. This operational simplification enables sample collection in tropical and resource-limited settings.
Market Restraints
- Polymer supply concentration:Specialized medical-grade polypropylene for collection tube manufacturing concentrates among German and Austrian compounders. Disruptions in propylene feedstock propagate directly into device lead times.
- Analytical sensitivity ceilings:Saliva's lower analyte concentration versus serum requires extraction volume scaling or pre-concentration steps. This technical limitation constrains miniaturization targets for microfluidic cartridge developers.
- IVDR certification timelines:European notified body capacity bottlenecks are extending CE marking cycles for novel collection devices. Smaller manufacturers face capital depletion during extended conformity assessment periods.
Strategic Opportunities
- Veterinary diagnostics crossover:Companion animal saliva cortisol and antibody testing protocols are adapting human collection device geometries. Brazil and Mexico present underpenetrated markets for dual-species platform positioning.
- Microfluidics-PCR convergence:Lab-on-chip systems integrating extraction and amplification are reducing sample-to-answer intervals below thirty minutes. Emergency departments represent the primary adoption channel for this format.
- At-home collection reimbursement:CMS reconsideration of remote specimen collection codes for preventive screening is creating policy tailwinds. Medicare Advantage plans are piloting saliva-based colorectal cancer screening as a covered benefit.
Industry Challenges
- Multi-omics integration complexity:Simultaneous DNA, RNA, and protein recovery from single saliva specimens demands incompatible buffer chemistries. Kit developers face formulation compromises that degrade yield for one analyte class.
- CLIA personnel certification gaps:Point-of-care saliva testing expansion outpaces medical laboratory technician training programs. Workforce shortages in rural United States counties limit deployment of waived molecular platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saliva Collection and Diagnosis Market |
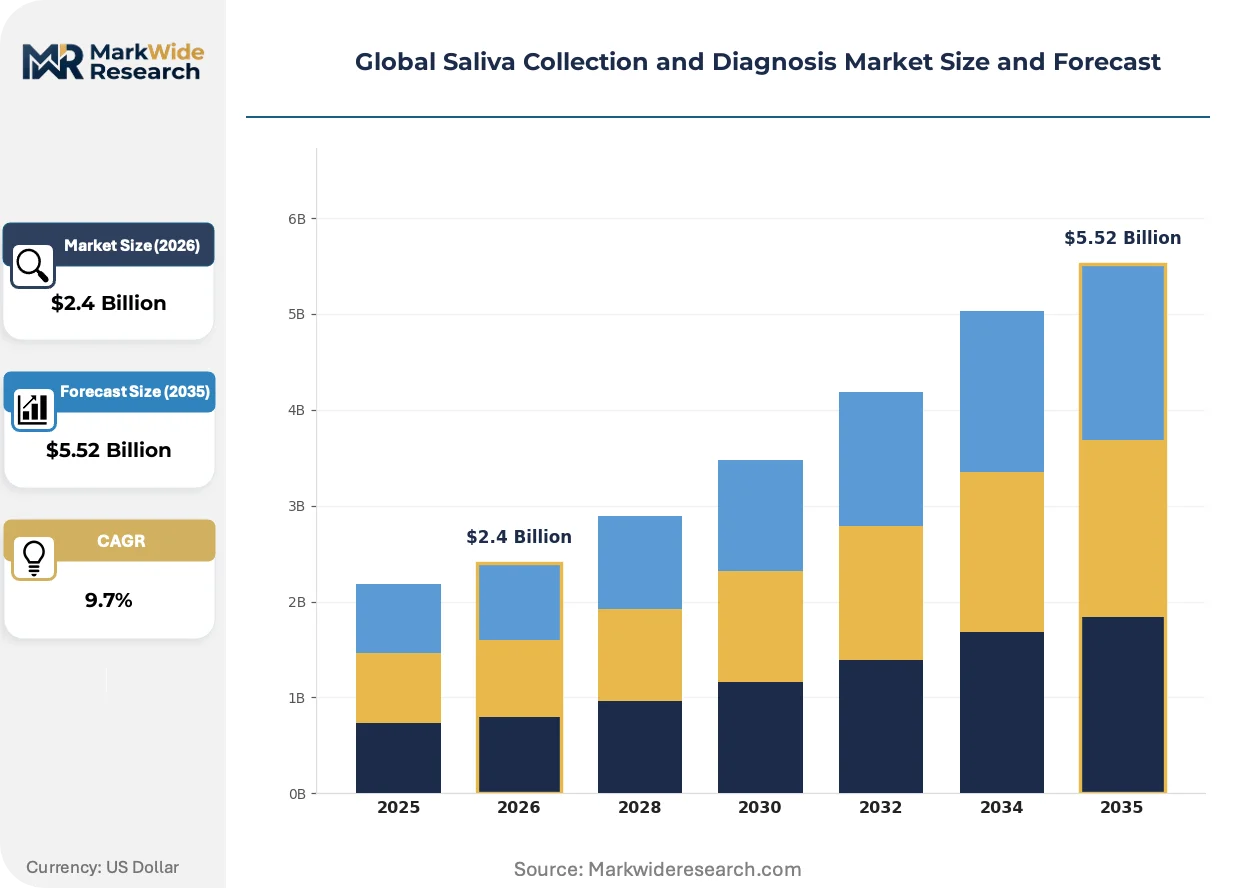
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collection Devices, Diagnostic Kits, Preservation Reagents, Extraction Kits, Storage Containers Application: Infectious Disease Detection, Genetic Testing, Hormonal Analysis, Drug Monitoring, Cancer Screening, Nutritional Assessment End User: Diagnostic Laboratories, Research Institutes, Point-of-Care Facilities, Biotechnology Firms, Forensic Centers Technology: PCR-Based Assays, Immunoassays, Biosensors, Microfluidics, Mass Spectrometry |
| Companies Covered | Thermo Fisher Scientific, Inc., Neogen Corporation, Abbott Laboratories, Sarstedt AG & Co. KG, Autogen, Inc., Oasis Diagnostics Corporation, Porex Technologies Corp., Salimetrics, LLC, OraSure Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saliva Collection and Diagnosis Market Shifts & Advancements
Saliva diagnostics is fragmenting across three simultaneous vectors: molecular detection sophistication, regulatory jurisdiction complexity, and care setting migration. These intersecting pressures are reshaping product architecture and commercial strategy for device and assay developers alike.
Microfluidic cartridge platforms are bifurcating the sample processing landscape. These devices integrate filtration, lysis, and purification in disposable formats under ten milliliters. Large health systems in the United States are piloting cartridge-based respiratory panels in urgent care settings. The technology is bifurcating high-complexity laboratory work into distributed, operator-agnostic workflows that compress turnaround without capital-intensive automation.
REACH chemical restriction proposals are forcing reformulation of preservation buffers across European product lines. ECHA scrutiny of boric acid and certain antimicrobial compounds is triggering substance substitution programs. Manufacturers serving the European market are accelerating validation of alternative stabilizers ahead of sunset date uncertainty.
Direct purchasing by employer wellness programs is disintermediating traditional clinical laboratory distribution. Large self-insured employers in the United States are contracting directly with kit manufacturers for annual genetic screening benefits. This channel shift concentrates volume among platforms offering API-integrated reporting and population health dashboards.
Global Saliva Collection and Diagnosis Market Segmentation
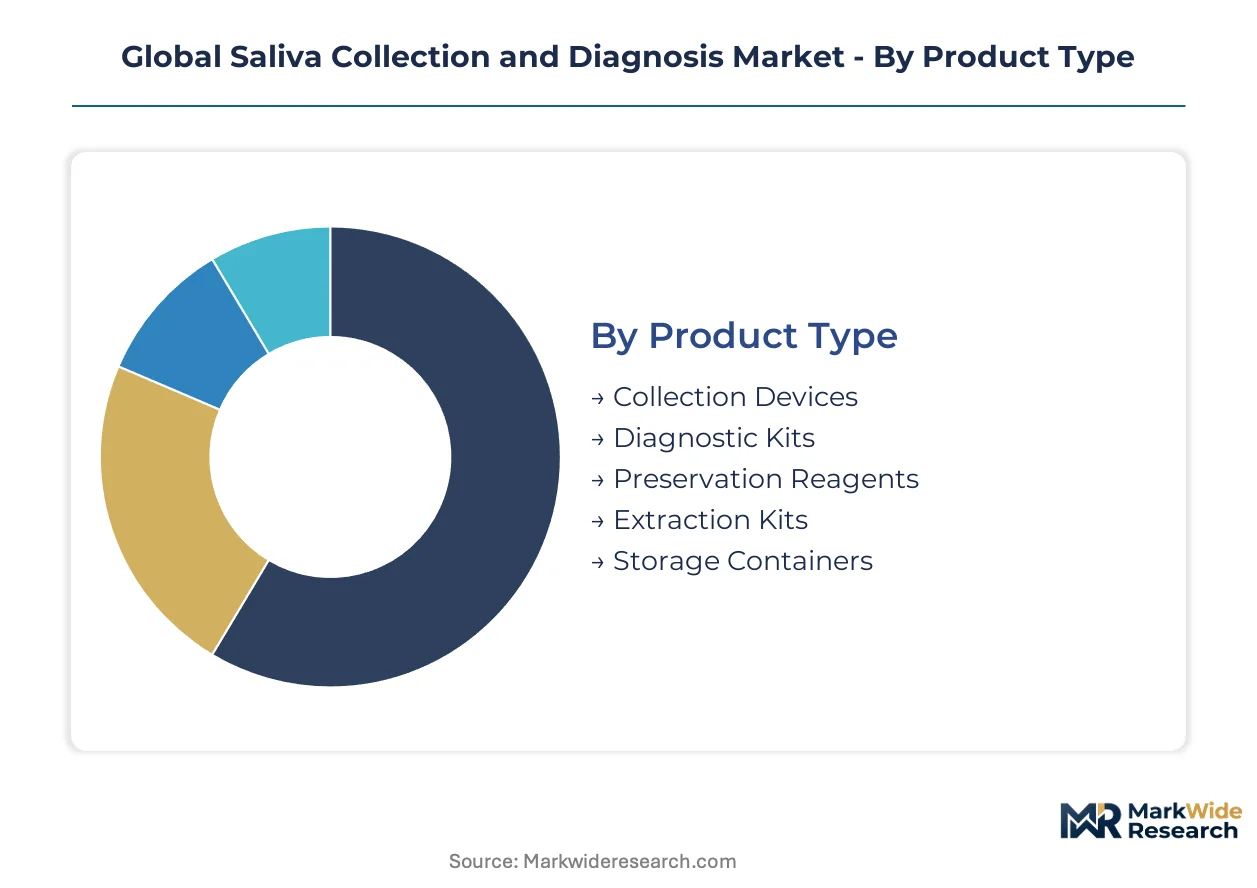
Saliva diagnostics fragments across four distinct commercial axes: physical product formats, clinical use cases, institutional buyer types, and underlying detection technologies. Each axis carries divergent margin profiles, regulatory burdens, and competitive dynamics that shape supplier strategy.
Product Type:
Margin pools concentrate in consumable formats that lock in recurring revenue through proprietary collection geometries and stabilization chemistries.
- Collection Devices:Engineered tubes and swabs with pH-buffered matrices and antimicrobial preservatives that maintain nucleic acid integrity during ambient transport. Demand clusters in the United States among large health systems standardizing on single-vendor workflows to reduce preanalytical variability.
- Diagnostic Kits:Pre-configured reagent sets for PCR, immunoassay, or biosensor platforms that bundle primers, probes, and controls for specific analyte classes. Reference laboratories in Germany and the Netherlands are pulling volumes for pharmacogenomic screening panels.
- Preservation Reagents:Room-temperature stabilizers eliminating cold-chain dependency for direct-to-consumer genetic testing.
- Extraction Kits:Silica membrane and magnetic bead formats for nucleic acid purification from crude saliva.
- Storage Containers:Temperature-stable transport vessels for biobanking and longitudinal specimen archiving.
The dominant share belongs to Collection Devices, while Diagnostic Kits are closing the gap fastest.
Application:
Volume distribution tracks reimbursement authorization patterns across national health systems and private payer networks.
- Infectious Disease Detection:Respiratory and sexually transmitted infection panels leveraging saliva's non-invasive collection advantage. Urgent care networks in the United States are adopting CLIA-waived molecular platforms for point-of-care deployment.
- Genetic Testing:Ancestry, carrier screening, and pharmacogenomic applications requiring high-yield DNA recovery. Brazil and Mexico present underpenetrated markets for wellness-directed consumer uptake.
- Hormonal Analysis:Cortisol and testosterone monitoring for endocrine disorders and sports medicine.
- Drug Monitoring:Forensic and workplace compliance testing for illicit substances and therapeutic drug levels.
- Cancer Screening:Liquid biopsy protocols for circulating tumor DNA detection in oral fluid.
- Nutritional Assessment:Micronutrient and metabolic marker profiling for personalized wellness programs.
Infectious Disease Detection commands institutional procurement budgets, though Genetic Testing is expanding most quickly via direct-to-consumer channels.
End User:
Channel power is shifting from centralized laboratories toward distributed collection points as regulatory frameworks accommodate decentralized testing.
- Diagnostic Laboratories:High-complexity facilities performing batch processing for health systems and commercial payers.
- Research Institutes:Academic medical centers validating novel biomarker signatures and longitudinal protocols.
- Point-of-Care Facilities:Retail pharmacies, urgent care clinics, and employer wellness sites requiring operator-agnostic workflows with rapid turnaround.
- Biotechnology Firms:Drug developers incorporating saliva pharmacokinetic monitoring into clinical trial designs.
- Forensic Centers:Law enforcement and legal system applications for DNA identification and toxicology screening.
Diagnostic Laboratories retain the largest installed base, while Point-of-Care Facilities are gaining share fastest through CLIA-waived assay proliferation.
Technology:
Platform selection determines capital intensity, personnel requirements, and regulatory pathway complexity for assay developers.
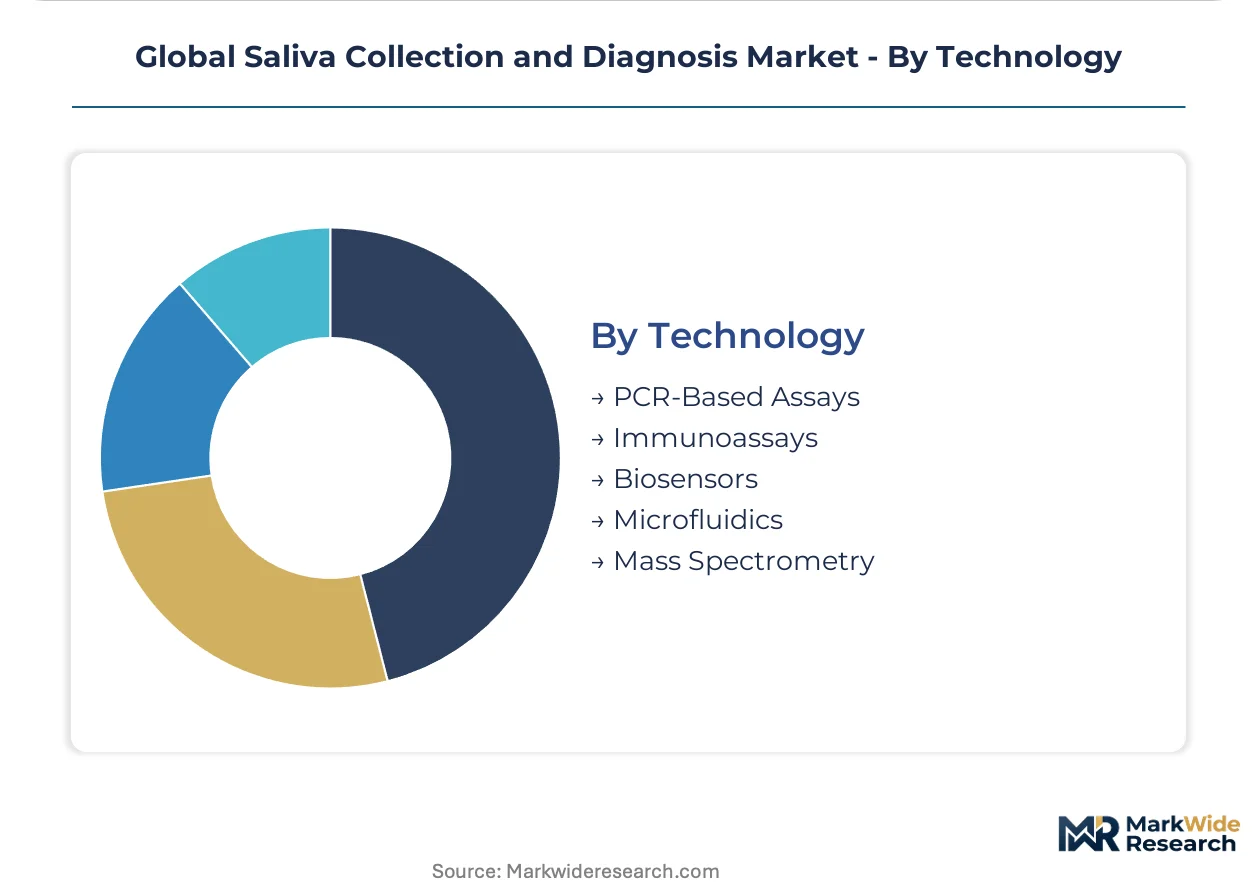
- PCR-Based Assays:Gold-standard nucleic acid amplification with established FDA premarket notification pathways and extensive clinical validation literature.
- Immunoassays:Antibody-antigen detection formats dominating point-of-care deployment for protein biomarkers.
- Biosensors:Electrochemical and optical transducers enabling label-free detection with minimal sample processing.
- Microfluidics:Lab-on-chip systems integrating extraction, amplification, and detection in sub-milliliter volumes. Emergency departments in the United States are piloting cartridge-based respiratory panels.
- Mass Spectrometry:High-resolution analyte identification for metabolomic and proteomic applications requiring specialized operator expertise.
PCR-Based Assays anchor current revenue, though Microfluidics is climbing the fastest as miniaturization targets compress sample-to-answer intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large health systems and reference laboratories in the United States drive standardization protocols that smaller markets emulate. Clinical diagnostic laboratories across Germany and the Netherlands are expanding saliva-based testing menus for pharmacogenomic applications. Brazil and Mexico present underpenetrated demand for direct-to-consumer genetic screening.
United States
Academic medical centers in Boston and San Francisco are validating saliva-based mutational profiling protocols for longitudinal oncology monitoring. The FDA's evolving guidance on liquid biopsy and at-home sample collection is reshaping product development priorities for kit manufacturers. Medicare Advantage plans are piloting saliva-based colorectal cancer screening as a covered benefit in the Southeast.
Germany
Payers are reimbursing CYP2C19 and CYP2D6 genotyping from saliva for psychiatric medication selection. REACH chemical restriction proposals are forcing reformulation of preservation buffers across European product lines. The Rhine-Ruhr metropolitan region hosts concentration of specialized medical-grade polypropylene compounders supplying collection tube manufacturers.
Netherlands
Reference laboratories are pulling volumes for pharmacogenomic screening panels into therapeutic drug monitoring workflows. The EMA's In Vitro Diagnostic Regulation mandates notified body certification for European market entry. The Amsterdam-Leiden corridor anchors clinical validation facilities for room-temperature nucleic acid preservation formulations.
Brazil
Companion animal saliva cortisol and antibody testing protocols are adapting human collection device geometries for veterinary crossover applications. The country's national pharmaceutical regulator is evaluating CLIA-equivalent frameworks for point-of-care molecular platforms. São Paulo state concentrates diagnostic laboratory infrastructure serving the Mercosur trade bloc.
China
Manufacturers are accelerating validation of alternative stabilizers ahead of sunset date uncertainty in European export markets. The NMPA is streamlining premarket notification pathways for saliva-based IVDs with established FDA clearances. The Yangtze River Delta clusters microfluidics-enabled biosensor developers targeting sub-thirty-minute sample-to-answer intervals.
Global Saliva Collection and Diagnosis Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with integrated reagent-instrument workflows. The competitive terrain bifurcates between scale-driven platform developers and specialized collection device manufacturers. Three archetypes dominate: conglomerates with end-to-end workflow control, mid-cap specialists in stabilization chemistry, and point-of-care platform developers. M&A activity concentrates on microfluidics capabilities and veterinary diagnostics crossover technologies.
Within the conglomerate tier, Thermo Fisher Scientific, Inc. and Abbott Laboratories exemplify integrated workflow positioning that sustains leadership in PCR-based and point-of-care formats respectively. Neogen Corporation occupies a position bridging human and veterinary applications through adaptation of saliva extraction technologies. Sarstedt AG & Co. KG anchors the specialized device manufacturing segment with German-engineered collection geometries. These three entities represent distinct competitive vectors: workflow integration, species crossover, and precision manufacturing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Neogen Corporation |
| Abbott Laboratories |
| Sarstedt AG & Co. KG |
| Autogen, Inc. |
| Oasis Diagnostics Corporation |
| Porex Technologies Corp. |
| Salimetrics, LLC |
| OraSure Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at German and Austrian medical-grade polypropylene compounders anchors cost structures across the collection device tier, with scale-driven procurement contracts establishing price floors that smaller kit manufacturers struggle to undercut. This concentration of polymer supply translates directly into margin compression for device developers lacking long-term offtake agreements or backward integration into resin sourcing.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate procurement between collection tube manufacturers and European polymer suppliers, insulating compounders from feedstock volatility while passing margin risk downstream. Pricing stratifies across FDA-cleared premium tiers, CE-IVDR standard tiers, and unregistered economy tiers for research-use-only applications. Cost compression in the economy tier is intensifying because Brazilian and Mexican distributors are sourcing unvalidated alternatives from Asian manufacturers. Reference laboratories exhibit lowest price sensitivity due to reimbursement pass-through mechanisms, while direct-to-consumer genetic testing platforms face acute margin pressure from customer acquisition costs.
Supply Chain Analysis
Rhine-Ruhr industrial corridor transit underwrites polymer supply security for European collection device manufacturers, with alternative routing through Rotterdam adding logistics cost layers during peak demand periods. Manufacturing concentration in Germany, Austria, and China feeds global kit assembly operations, with specialized medical-grade polypropylene, antimicrobial preservatives, and silica membrane extraction matrices constituting critical input dependencies. Single-source vulnerability in notified body certification capacity creates bottleneck risk for CE-IVDR market entry. Distribution runs through health system GPO contracts in the United States, direct laboratory procurement in Germany and the Netherlands, and veterinary channel distributors in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat structure anchored in regulatory entrenchment, where FDA premarket notification and CE-IVDR certification timelines create switching costs that lock institutional buyers into validated supplier relationships.
For Market Incumbents: Secure exclusive supply agreements with Rhine-Ruhr polymer compounders to defend against propylene price volatility and emerging Asian resin competitors. Deepen backward integration into stabilization chemistry manufacturing to capture margin pools currently flowing to specialty reagent suppliers, while accelerating IVDR certification for next-generation collection geometries before notified body capacity constraints ease. For New Entrants and Emerging Players: API-integrated reporting layers for employer wellness programs represent a service gap where incumbents under-serve, creating white-space for cloud-native platforms with population health dashboards. Veterinary diagnostics crossover applications in Brazil and Mexico offer the most penetrable geography, with companion animal cortisol testing protocols adapting human device geometries. A direct-to-employer go-to-market angle bypasses reference laboratory channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors microfluidics-PCR convergence specialists with emergency department pilot traction and sub-thirty-minute sample-to-answer validation. Long-term viability hinges on CLIA-waived assay proliferation sustaining point-of-care migration. Acquisition targets should display stabilization chemistry IP and regulatory filing momentum across multiple jurisdictions. The signal to watch is CMS reimbursement decisions for remote specimen collection codes in preventive screening applications.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Pathway | Notified body capacity bottlenecks in Europe extend conformity assessment timelines beyond capital reserves of smaller manufacturers. |
| Microfluidics Platform Integration | Lab-on-chip systems reduce sample-to-answer intervals below thirty minutes for emergency department respiratory panel deployment. |
| Stabilization Chemistry Backward Integration | In-house production of room-temperature nucleic acid preservatives eliminates cold-chain dependency for direct-to-consumer channels. |
| Hospital System Partnership | Large health system GPO contracts in the United States standardize single-vendor workflows and reduce preanalytical variability. |
| Veterinary Diagnostics Crossover | Companion animal saliva testing protocols in Brazil and Mexico adapt human collection device geometries for dual-species positioning. |
Research Methodology
Desk research of FDA 510(k) filings, EMA IVDR technical documentation, and hospital procurement database records preceded structured interviews with diagnostic laboratory directors, regulatory affairs leads at kit manufacturers, GPO contracts managers, and point-of-care platform engineers. Primary fieldwork captured preanalytical workflow standardization practices, stabilization chemistry validation protocols, and reimbursement negotiation dynamics across United States, German, Dutch, Brazilian, and Chinese market participants. Secondary validation drew from ISO 13485 audit reports, CAP laboratory accreditation records, and customs trade data for medical-grade polymer imports. Bottom-up demand modeling triangulated against top-down health system expenditure tracking.
Variance decomposition across product type, application, end user, technology, and regional regulatory cluster dimensions shaped analytical framework construction throughout the projection horizon. CAGRs derived from segment-level volume build-ups incorporating CLIA-waiver expansion trajectories, pharmacogenomic reimbursement authorization patterns, and microfluidics adoption curves in emergency care settings. Industry-specific forecast inputs included propylene feedstock price indices, notified body certification queue lengths, and CMS remote collection code reconsideration timelines.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EMA IVDR implementation; material policy shifts in liquid biopsy guidance or REACH chemical restrictions would require re-modeling. Practitioners should keep alternative scenarios live as decentralized testing authorization frameworks and at-home collection reimbursement policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Johne's Disease Diagnostics Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Global Urinalysis Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Acute Ischemic Stroke Diagnosis Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market