
 Australia in-Vitro Diagnostics Market | 2026-2036
Australia in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia in-Vitro Diagnostics Market Outlook
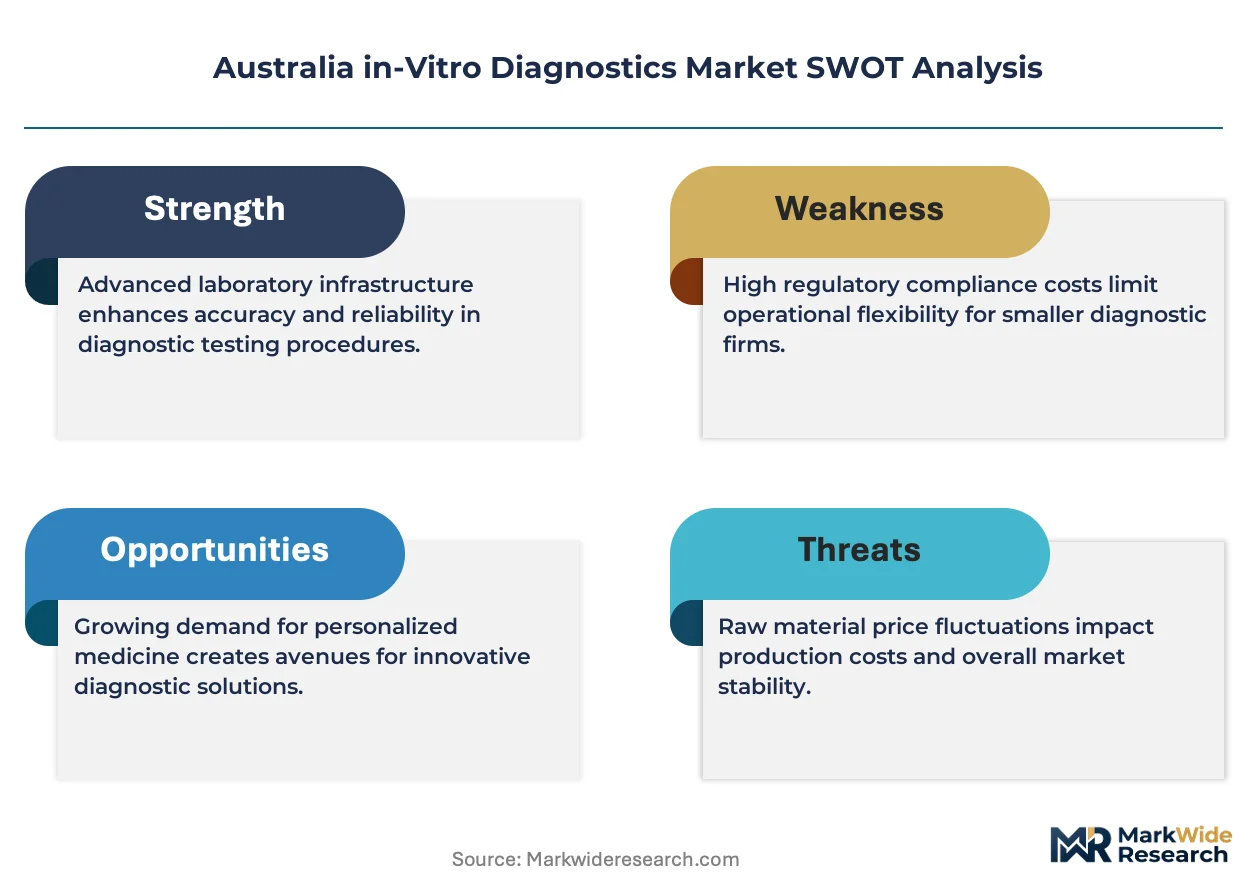
Modular assay panel bundling is repositioning procurement decisions across Australian health networks. Abbott Laboratories leverages its integrated diagnostic platform to anchor long-term supply contracts with public hospital systems. Sonic Healthcare Limited sustains its dominance through extensive geographic coverage of collection centers and reference laboratories nationwide.
In-vitro diagnostics encompasses medical tests performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions with detection sensitivity thresholds typically reaching picomolar concentrations to identify pathogens, biomarkers, or genetic variations. These systems serve clinical decision-making by enabling disease screening, treatment monitoring, and therapeutic selection across acute and ambulatory settings. Reagents capture the largest margin pool given their consumable nature and recurring purchase cycles tied to instrument install bases. Point-of-Care delivery mode exhibits the fastest structural expansion as decentralized testing protocols reduce turnaround times for emergency and rural settings.
TGA medical device frameworks, ISO 13485 quality management standards, and the Therapeutic Goods Act shape product registration pathways and post-market surveillance obligations for IVD sponsors operating in Australia. Compliance with these regimes determines market access timelines and influences R&D allocation toward software-enabled diagnostic platforms. Stakeholders must monitor evolving TGA guidance on artificial intelligence-based IVD algorithms to anticipate classification shifts that could reshape competitive positioning.
Market Dynamics
Modular assay panel bundling is repositioning procurement decisions across Australian health networks, forcing sponsors to anchor long-term supply contracts through integrated diagnostic platforms rather than standalone reagent sales.
Growth Catalysts
- TGA software classification updates:Accelerated compliance investments among device sponsors are expanding the addressable market for AI-enabled diagnostic platforms. Sponsors redirect R&D budgets toward algorithm-based IVD systems to capture premium reimbursement tiers.
- Chronic disease monitoring volumes:Diagnostic laboratories expand test menus to capture recurring revenue from diabetes, cardiovascular, and oncology patient cohorts. Public hospital networks centralize high-throughput pathology services in New South Wales and Victoria.
- Point-of-Care decentralization:Rural and emergency settings adopt portable molecular testing to reduce turnaround times. Regional health districts procure cartridge-based systems for remote clinic networks.
Market Restraints
- Reagent import dependency:Concentrated global supply of enzyme-linked immunosorbent assay substrates creates vulnerability to shipping disruptions and currency fluctuation.
- TGA conformity assessment timelines:Extended evaluation periods for novel IVD algorithms delay product launches and compress commercialization windows.
- Capital intensity of automation:High-throughput analyzers require substantial upfront investment, limiting adoption among smaller private pathology groups.
Strategic Opportunities
- Western Australia and Queensland expansion:Underpenetrated regional markets outside Sydney-Melbourne corridors present whitespace for collection center networks.
- ISO 13485 convergence with TGA requirements:Streamlined quality management pathways reduce dual-certification burdens for multinational sponsors entering Australia.
- Telepathology integration:Remote diagnostic interpretation platforms enable specialist workforce extension into rural territories without physical relocation.
Industry Challenges
- Clinical bioinformatics talent scarcity:Shortage of personnel trained in both laboratory medicine and computational biology constrains AI-IVD development pipelines.
- Legacy LIS integration complexity:Hospital information system fragmentation impedes seamless data flow from Point-of-Care devices to central electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia in-Vitro Diagnostics Market |
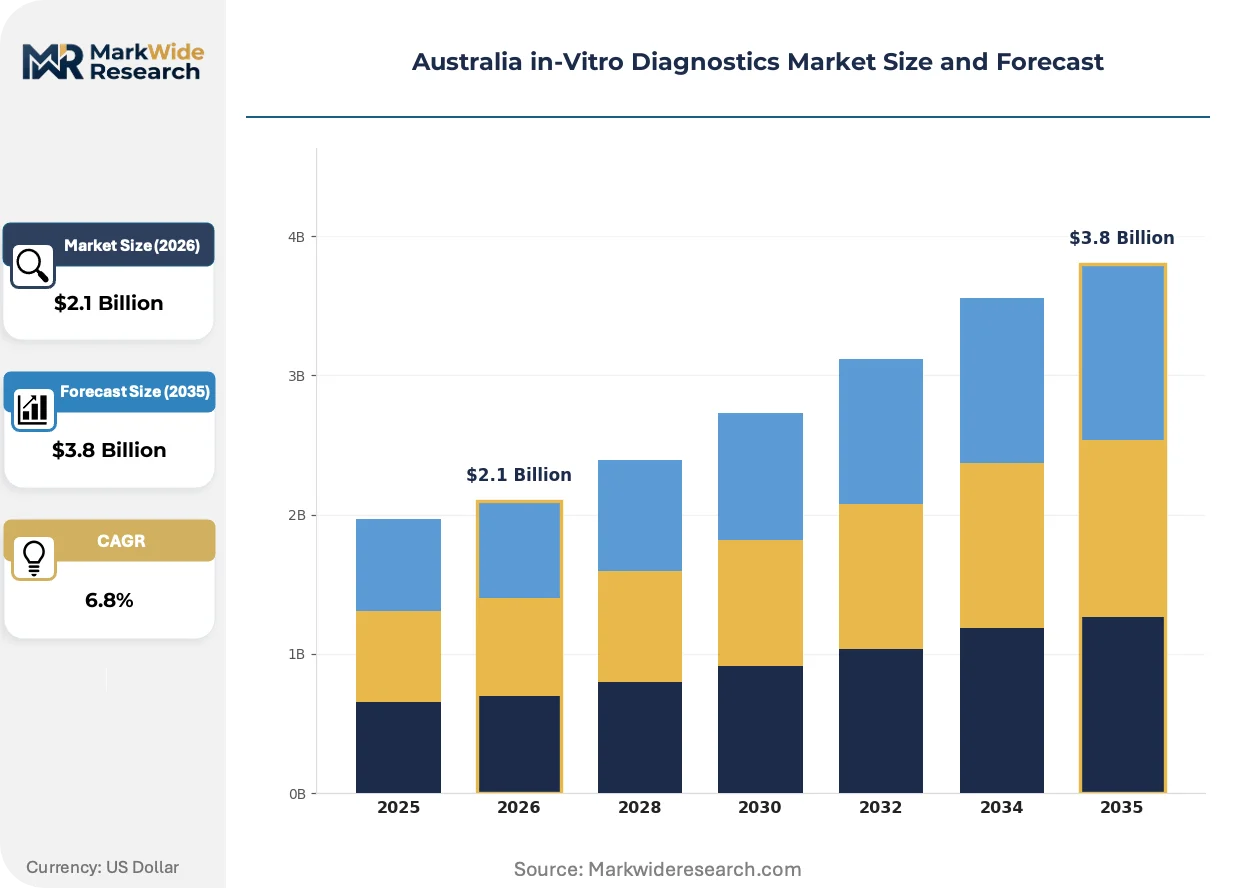
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Quality Control Products End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Immunohistochemistry, Next Generation Sequencing Delivery Mode: Point-of-Care, Centralized Lab Testing, Home Testing, Mobile Testing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche AG, Siemens Healthineers AG, Thermo Fisher Scientific Inc., bioMerieux SA, Sonic Healthcare Limited, Healius Ltd, Australian Clinical Labs, Sysmex Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia in-Vitro Diagnostics Market Strategic Shifts
Digital pathology and artificial intelligence are converging to compress diagnostic workflows, while regulatory frameworks race to keep pace with algorithm-based decision support tools.
Multiplexed molecular panels are rewriting how infectious disease diagnostics are ordered and reimbursed. Public hospital microbiology departments consolidate previously separate PCR tests into syndromic respiratory and gastrointestinal panels. This compression reduces per-test costs while expanding the clinical information captured from single specimens.
TGA guidance on artificial intelligence-based IVD algorithms is reshaping product registration pathways. Sponsors face classification uncertainty as software intended for diagnostic decision support straddles medical device and clinical decision support tool boundaries. The regulatory response is forcing developers toward prospective clinical validation studies that extend time-to-market.
Consolidated procurement through state-based health purchasing authorities is concentrating vendor selection power. Queensland and Victoria health departments now negotiate enterprise-wide reagent supply agreements that span multiple hospital networks. This aggregation favors sponsors with integrated instrument-reagent platforms capable of anchoring multi-site contracts.
Australia in-Vitro Diagnostics Market Segmentation
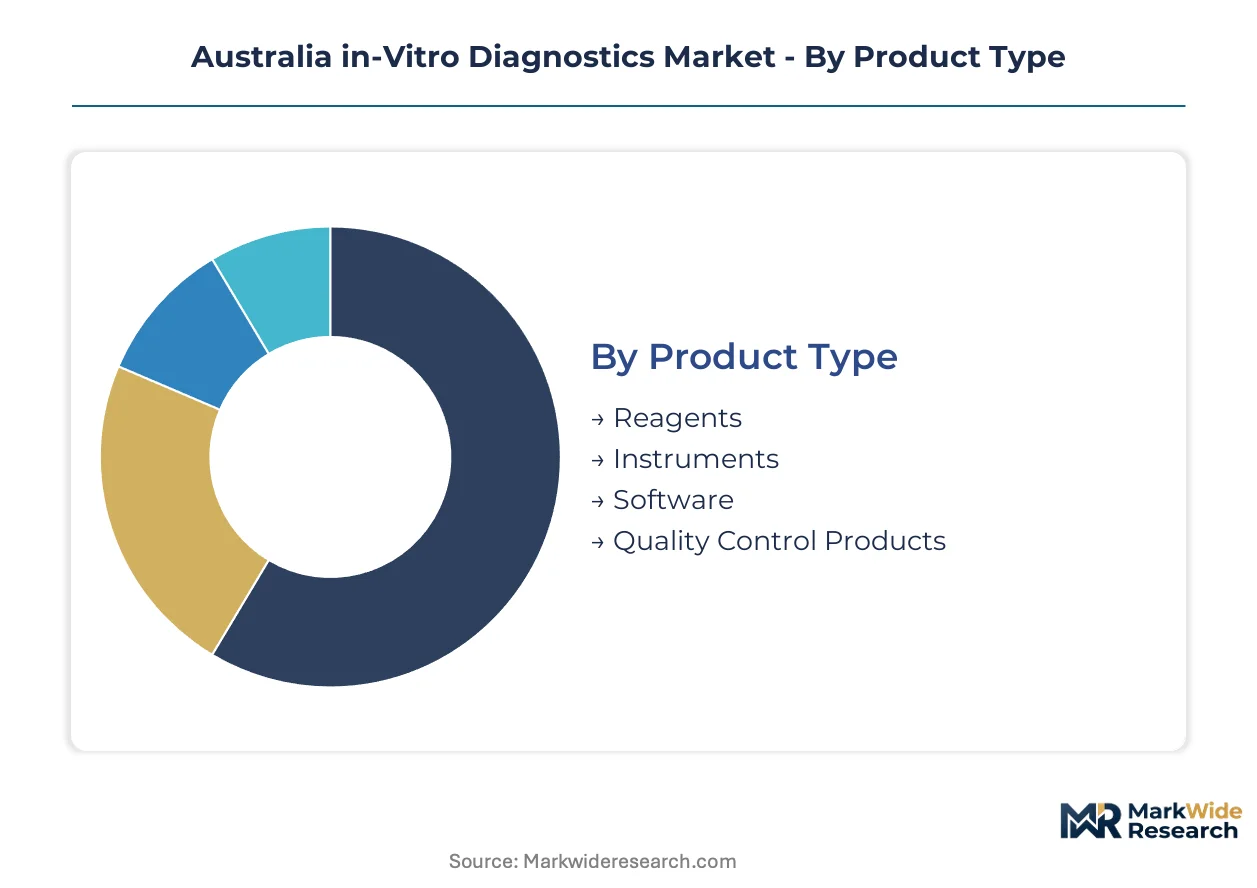
Segmentation reveals how procurement patterns diverge across Australian health networks. Reagent bundling strategies, instrument replacement cycles, and technology adoption curves reshape vendor positioning in each category.
Product Type:
Upgrade and replacement cycles vary dramatically by product economics—consumables lock in recurring revenue while instruments demand capital commitment cycles spanning 5-7 years.
- Reagents:Chemical substrates and assay kits with picomolar detection sensitivity drive recurring purchase obligations tied to installed instrument bases. Public hospital networks in New South Wales and Victoria concentrate procurement volumes through centralized pathology tenders, with TGA batch release requirements adding compliance overhead.
- Instruments:Automated analyzers and molecular diagnostic platforms require substantial upfront capital and extended validation timelines. Sonic Healthcare's nationwide laboratory network anchors the largest installed base, creating captive demand for manufacturer-specific consumables.
- Software:Laboratory information systems and AI-enabled diagnostic algorithms face evolving TGA classification uncertainty. Algorithm-based decision support tools straddle medical device and clinical software boundaries, complicating registration pathways.
- Quality Control Products:Calibrators and proficiency testing materials ensure analytical accuracy across accredited laboratories. ISO 13485 quality management standards govern manufacturing, with TGA conformity assessment required for local distribution.
Volume placements concentrate in Reagents; the faster expansion belongs to Software.
End User:
Customer concentration patterns reflect Australia's hospital network consolidation and the geographic spread of pathology collection infrastructure.
- Hospitals:Acute care facilities drive demand for rapid turnaround testing in emergency and intensive care settings. Queensland Health's enterprise-wide procurement authority negotiates multi-site reagent agreements favoring integrated platform vendors.
- Diagnostic Laboratories:Reference laboratories and pathology networks process high-throughput volumes for chronic disease monitoring. Sonic Healthcare's collection center footprint spans metropolitan and regional Australia, capturing outpatient test referrals.
- Research Institutions:Academic medical centers and biotechnology firms utilize specialized assays for translational research. Next Generation Sequencing adoption concentrates in Melbourne and Sydney research clusters.
- Clinics:General practice and specialist clinics adopt Point-of-Care testing for immediate clinical decision-making. Rural health districts in Western Australia procure cartridge-based systems to reduce specimen transport delays.
Procurement authority aggregates at Diagnostic Laboratories; Clinics are climbing the fastest as decentralization accelerates.
Technology:
Technical capabilities determine sensitivity thresholds, throughput economics, and the regulatory validation burden for each platform.
- Polymerase Chain Reaction:Nucleic acid amplification enables pathogen detection with high analytical specificity. Public hospital microbiology departments consolidate individual PCR tests into syndromic respiratory and gastrointestinal panels, compressing per-test costs while expanding clinical information yield.
- Enzyme-Linked Immunosorbent Assay:Antibody-antigen binding reactions support quantitative biomarker measurement for chronic disease management. Global substrate supply concentration creates import dependency vulnerability for Australian sponsors.
- Immunohistochemistry:Tissue-based protein detection guides oncology diagnostic and therapeutic selection. Specialized histopathology services concentrate in major metropolitan reference laboratories.
- Next Generation Sequencing:Massively parallel DNA sequencing enables comprehensive genomic profiling for precision medicine applications. Clinical bioinformatics talent scarcity constrains pipeline development for algorithm-based interpretation tools.
Installed base dominance sits with Polymerase Chain Reaction; Next Generation Sequencing shows the steepest expansion trajectory.
Delivery Mode:
Distribution economics and turnaround requirements segment the market by care setting and geographic access constraints.
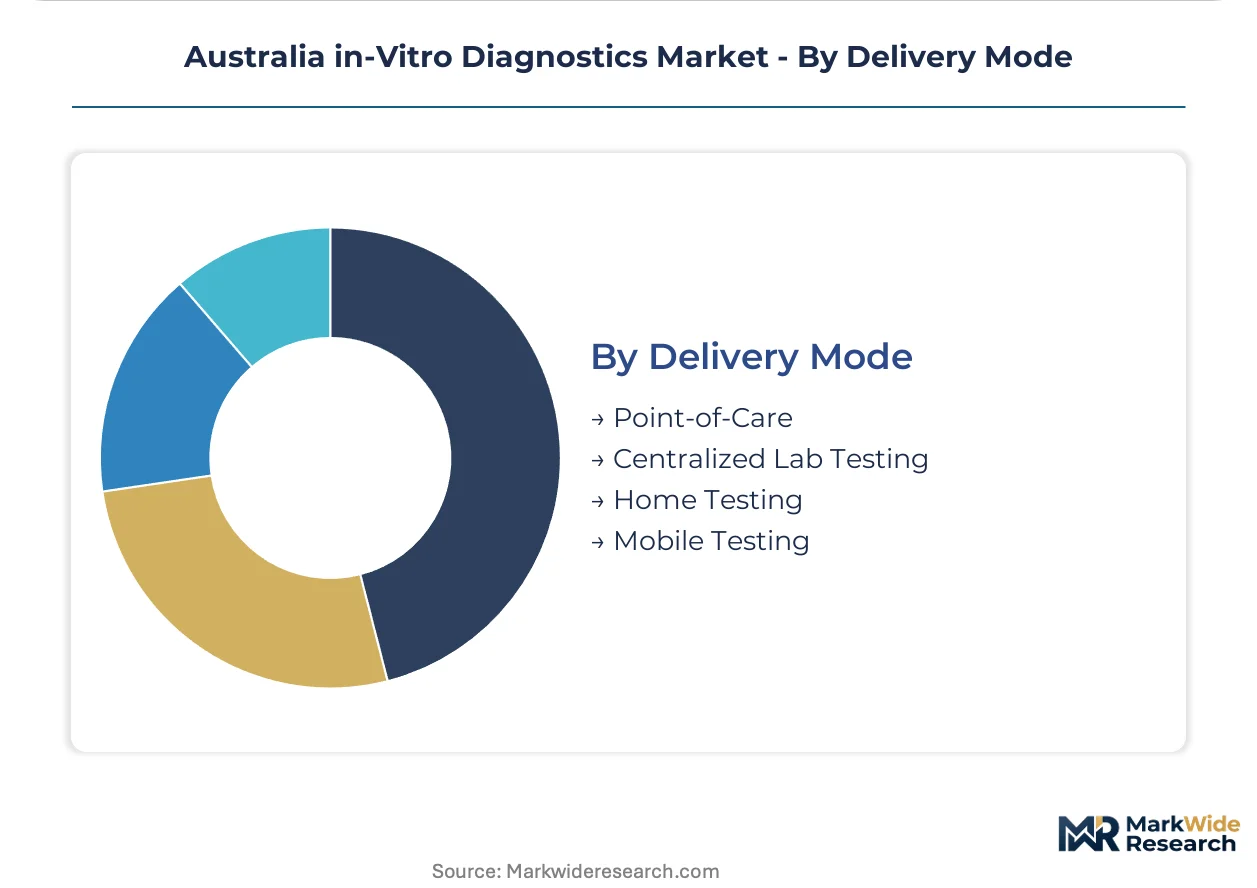
- Point-of-Care:Portable testing devices deliver results at the site of patient care without laboratory infrastructure. Regional health districts deploy cartridge-based molecular systems across remote clinic networks in Queensland and Western Australia.
- Centralized Lab Testing:High-throughput analyzers achieve economies of scale through specimen consolidation and automation. New South Wales and Victoria hospital networks centralize pathology services in metropolitan reference hubs.
- Home Testing:Self-collection kits enable patient-directed screening for chronic conditions and infectious disease. TGA oversight of in-vitro diagnostic software extends to algorithm-based result interpretation applications.
- Mobile Testing:Deployable laboratory units provide surge capacity for outbreak response and rural outreach. Australian Defence Force health services utilize field-deployable PCR platforms for expeditionary medical support.
Revenue concentration remains in Centralized Lab Testing; Point-of-Care is gaining share fastest through rural network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic production concentrates in Victoria and New South Wales manufacturing hubs, while testing demand spreads across all states with pronounced rural-urban access divides. This geographic mismatch shapes procurement patterns and infrastructure investment priorities.
New South Wales
Sydney anchors the largest pathology services concentration with high-throughput hospital networks driving centralized testing volumes. TGA medical device frameworks govern product registration timelines for sponsors supplying the state's public health system. The Westmead Health Precinct clusters specialized molecular diagnostics capability alongside major research institutions.
Victoria
Melbourne's hospital networks and research institutions generate substantial demand for precision medicine and genomic testing applications. ISO 13485 quality management standards align with TGA requirements to streamline certification pathways for multinational sponsors entering this market. The Parkville biomedical precinct concentrates next-generation sequencing expertise and clinical bioinformatics talent development.
Queensland
Regional health districts outside Brisbane drive point-of-care adoption to address specimen transport delays across vast distances. Enterprise-wide procurement authorities negotiate multi-site reagent agreements spanning hospital networks from Cairns to the Gold Coast. The Sunshine Coast and Townsville anchor regional laboratory hubs serving dispersed populations.
Western Australia
Remote clinic networks in the Kimberley and Pilbara regions deploy cartridge-based molecular systems to reduce diagnostic turnaround times. The state's resource sector generates occupational health screening demand alongside conventional clinical applications. Perth's QEII Medical Centre concentrates specialized pathology services for the state's two-million-plus population.
Australia in-Vitro Diagnostics Market Competitive Environment
The competitive structure tilts toward integrated platform providers anchoring long-term supply contracts through instrument-reagent bundling. Multinational sponsors with established TGA registrations hold procurement advantages in public hospital tenders, while domestic laboratory networks leverage geographic coverage for outpatient market capture. Two strategic archetypes dominate: global diagnostics conglomerates with full-stack platforms, and national pathology chains with collection center density. Competitive moves concentrate on contract consolidation through state-level purchasing authorities and point-of-care portfolio expansion into regional territories.
Among multinational sponsors, Abbott Laboratories and F. Hoffmann-La Roche AG exemplify the integrated platform archetype with instrument-reagent ecosystems designed for high-throughput hospital environments. Sonic Healthcare Limited occupies a distinct position as the dominant domestic operator, its nationwide collection center footprint creating captive specimen flows that reinforce reference laboratory economics. Siemens Healthineers AG and Thermo Fisher Scientific Inc. sit within the premium-tier instrumentation segment, supplying automation infrastructure to centralized pathology hubs. These four entities represent the competitive poles around which procurement decisions and market structure organize.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche AG |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| bioMerieux SA |
| Sonic Healthcare Limited |
| Healius Ltd |
| Australian Clinical Labs |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Enzyme-linked immunosorbent assay substrates flow from concentrated global manufacturers through tiered pricing structures that stratify Australian hospital procurement decisions. These biochemical inputs anchor consumable costs for diagnostic platforms, with currency fluctuation and shipping disruption risk transmitting downstream to public health network budgets.
Pricing Analysis
Margin tightening in the reagent tier reflects consolidated procurement authority wielded by Queensland and Victoria health departments negotiating enterprise-wide supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates TGA-registered multinational sponsors from ISO 13485-certified regional distributors and unbundled import channels. Price differentiation hinges on instrument-reagent platform integration depth and after-sales calibration service inclusion. Smaller private pathology groups exhibit highest price sensitivity due to capital constraints on automation infrastructure, while Sonic Healthcare's captive specimen volumes insulate it from spot market volatility.
Supply Chain Analysis
Regional distribution centers in Sydney and Melbourne operate hub-and-spoke patterns reaching remote Western Australia and Queensland clinic networks within 48-72 hour windows. Manufacturing concentration in the United States, Germany, and Japan supplies automated analyzers and molecular diagnostic platforms, while China and South Korea dominate substrate and cartridge component production. Raw material dependencies include fluorophore-labeled antibodies, polymerase enzymes, and specialized microfluidic plastics. Single-source vulnerability concentrates in enzyme-linked immunosorbent assay substrate supply. Distribution runs through TGA-authorized sponsors maintaining local batch release and quality control capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia in-Vitro Diagnostics Market rewards sponsors controlling upstream reagent manufacturing and downstream collection center access. Players securing both levers capture recurring revenue streams that resist price erosion from procurement consolidation.
For Market Incumbents: Anticipate TGA software classification uncertainty by accelerating prospective clinical validation studies for AI-enabled diagnostic algorithms before regulatory thresholds harden. Anchor long-term supply contracts through instrument-reagent platform bundling to defend against emerging point-of-care specialists. Deepen backward integration into reagent manufacturing to offset import dependency exposure and capture margin pool compression from state-level purchasing authority aggregation. For New Entrants and Emerging Players: The price-point gap between premium integrated platforms and economy unbundled reagents creates entry space for cartridge-based molecular systems targeting Western Australia and Queensland regional health districts. Western Australia's underpenetrated remote clinic networks present the most penetrable geography, with specimen transport delays generating urgent demand for decentralized testing. Pursue telepathology partnership models that extend specialist interpretation capability without physical infrastructure investment. For Investors and Strategic Acquirers: TGA guidance publication on artificial intelligence-based IVD algorithms is the leading indicator that classification clarity will trigger consolidation among software-enabled diagnostic developers. Acquisition targets should demonstrate ISO 13485 quality management certification plus established distribution relationships with public hospital networks. Long-term viability favors sponsors with captive manufacturing of consumable inputs rather than pure instrument or software plays exposed to supply chain disruption.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software Classification Compliance Investment | Prospective clinical validation studies for AI-IVD algorithms secure premium reimbursement tiers before regulatory thresholds harden. |
| Instrument-Reagent Platform Integration | Integrated diagnostic ecosystems anchor multi-site supply contracts with Queensland and Victoria enterprise procurement authorities. |
| Regional Collection Center Network Expansion | Geographic coverage in Western Australia and Queensland captures outpatient specimen flows that reinforce reference laboratory economics. |
| Telepathology Platform Development | Remote diagnostic interpretation extends specialist workforce into rural territories without physical relocation or infrastructure deployment. |
| ISO 13485 Quality Management Certification | Streamlined certification pathways reduce dual-certification burdens for multinational sponsors entering the Australian market. |
Study Parameters
Multi-period observation of TGA registration timelines, state procurement contract awards, and point-of-care deployment rates anchored the trend analysis, supplemented by interviews with pathology laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from TGA medical device databases, Queensland Health enterprise procurement disclosures, hospital pathology service annual reports, and ISO 13485 certification registries. Bottom-up instrument installation tracking and top-down health expenditure analysis were triangulated to cross-verify market sizing.
Input-output matrices modeled reagent consumption rates against installed instrument bases, segmenting projections by product type, end user, technology platform, and delivery mode across the analysis window. CAGRs were derived from regression analysis of historical procurement volumes and elasticity estimates for automation capital investment. Industry-specific forecast inputs included chronic disease prevalence trajectories and TGA regulatory pathway evolution assumptions.
Inputs from TGA registration databases and state health procurement portals were available through the study window; gaps in private pathology group financial disclosures introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding regulatory timeline stability and currency fluctuation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Vision Screeners Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Febrile Antigen Kits Market
Diagnostics
Global Liver Cancer Diagnostics Market
Diagnostics
Global Companion Animal Diagnostics Market
Diagnostics
Global STD Diagnostics Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
South Korea in Vitro Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market