
 India Electric Vehicle Battery Manufacturing Market | 2026-2036
India Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Battery Manufacturing Market Insights
Cell-to-pack architecture is reshaping how Indian OEMs design battery systems, eliminating redundant module housings and reducing pack weight. Exide Industries Limited leverages its century-old distribution network to anchor aftermarket service reach across tier-two cities. Grinntech Motors & Services Pvt. Ltd. specializes in indigenous lithium-ion cell design for commercial vehicle duty cycles. Amara Raja Batteries competes through backward integration into lead-acid recycling infrastructure that now feeds cathode precursor streams.
India electric vehicle battery manufacturing encompasses the domestic production of electrochemical energy storage systems, typically employing lithium iron phosphate or nickel-manganese-cobalt cathode formulations with energy densities ranging from 150 to 300 watt-hours per kilogram, assembled through electrode coating, cell formation, and pack integration processes to power traction motors in electrified road transport. Lithium-ion chemistry dominates current installed capacity while solid-state prototypes occupy advanced R&D pipelines at pilot scale. Among end users, fleet operators represent the fastest-expanding demand pool as state transport undertakings tender for electric bus deployments. Passenger vehicles carry the largest revenue share due to higher per-unit battery capacity and premium pricing on SUV platforms.
BIS certification mandates for cell safety and performance create compliance thresholds that filter import-dependent assemblers from domestic producers. The PLI scheme administered by the Ministry of Heavy Industries channels production-linked incentives toward ACC manufacturing, while CEA grid integration standards govern how stationary battery assets connect to charging infrastructure. Stakeholders must track how BIS evolves its testing protocols for sodium-ion and solid-state variants before committing to next-generation capacity investments.
Market Dynamics
Cell-to-pack architecture is compressing manufacturing margins for module-tier suppliers while redirecting capital toward electrode coating and formation equipment. The PLI scheme's production-linked incentive structure is accelerating domestic gigafactory commitments across Tamil Nadu and Gujarat.
Growth Catalysts
- ACC PLI Incentives:The Ministry of Heavy Industries channels capital toward advanced chemistry cell manufacturing through output-linked subsidies tied to domestic value addition thresholds.
- Fleet Electrification:State transport undertakings are tendering electric bus deployments at scale, creating anchor demand for high-cycle-life lithium iron phosphate systems.
- Tamil Nadu Corridor:Concentrated port infrastructure and automotive supplier density around Chennai is attracting cathode precursor and cell formation investments.
Market Restraints
- Lithium Import Dependency:Spodumene concentrate and lithium carbonate supply chains concentrate in Australian and Chilean extraction operations, exposing margin volatility to currency and shipping cost swings.
- BIS Certification Lag:Bureau of Indian Standards safety testing protocols for sodium-ion and solid-state variants remain under draft consultation, freezing next-generation product launch timelines.
- Lead-Acid Substitution:Two-wheeler and three-wheeler price-sensitive segments retain lead-acid batteries for sub-₹100,000 vehicle categories, capping lithium-ion penetration in volume segments.
Strategic Opportunities
- Gujarat Manufacturing Belt:Mundra and Hazira port zones offer duty-free import zones for cathode active material processing with direct rail links to Delhi-Mumbai industrial corridor off-takers.
- Second-Life Stationary Storage:Retired electric bus batteries with 70-80% residual capacity are repurposing into CEA-compliant grid stabilization assets for renewable energy integration.
- Recycling Integration:Amara Raja's lead-acid recycling infrastructure is feeding black mass processing streams that recover lithium, cobalt, and nickel for cathode precursor resynthesis.
Industry Challenges
- Electrolyte Formulation Talent:Domestic expertise in non-flammable electrolyte salts and solid-state ceramic separators remains concentrated in IISc and IIT-Madras research labs, constraining commercial scale-up.
- Formation Equipment Capex:Cell aging and electrochemical formation lines require 18-24 month commissioning cycles with 85% utilization thresholds to achieve PLI incentive eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Battery Manufacturing Market |
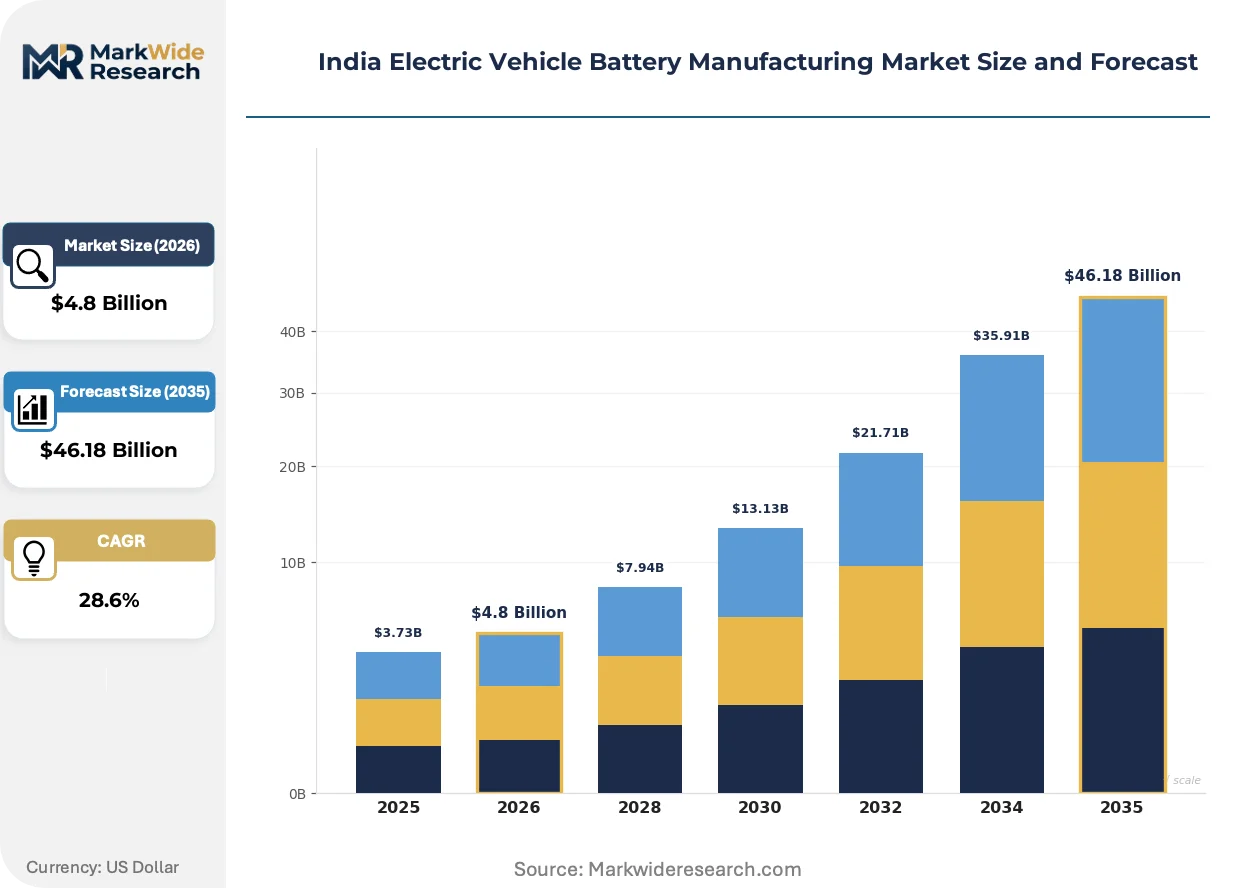
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Nickel-Cobalt, Lead-Acid, Solid-State End User: Automakers, Fleet Operators, Energy Storage Systems, Government Agencies Technology: Fast Charging, Battery Management Systems, Thermal Management, Recycling Technologies Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Public Transport |
| Companies Covered | Batteryinc, Bharatcell, Exide Industries Limited, Grinntech Motors & Services Pvt. Ltd., Exicom Energy Systems Pvt. Ltd, Amara Raja Batteries, Battrixx, Ipower Batteries, Aqueouss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Battery Manufacturing Market Trends and Innovations
Digital twin platforms are compressing cell design iteration cycles while sodium-ion prototypes challenge lithium iron phosphate cost structures in stationary applications. These shifts are reshaping how Indian OEMs specify battery management systems and thermal runaway mitigation.
Cell-to-pack architecture is virtualizing the module assembly tier by eliminating redundant aluminum housings and busbar interconnects. Electric bus OEMs at state transport undertakings are specifying direct cell-to-chassis bonding to maximize volumetric energy density. This compression is forcing traditional module suppliers to pivot toward battery management system firmware or exit the traction battery value chain entirely.
BIS is expanding certification mandates beyond cylindrical and prismatic lithium-ion formats to encompass sodium-ion and solid-state cell geometries. The draft protocols under consultation at the Bureau of Indian Standards are requiring nail penetration and thermal abuse testing at cell level rather than pack level. Commercial vehicle OEMs are responding by pre-qualifying suppliers against anticipated 2025-2026 enforcement timelines, front-loading compliance engineering spend.
Fleet operators are consolidating procurement through tender aggregators rather than direct OEM negotiations. State transport undertakings in Maharashtra and Karnataka are channeling electric bus battery orders through centralized tender platforms that unbundle vehicle chassis from battery pack supply. This disintermediation is compressing supplier margins while favoring cell manufacturers with direct BIS certification and aftermarket service networks across tier-two depot locations.
India Electric Vehicle Battery Manufacturing Market Segmentation
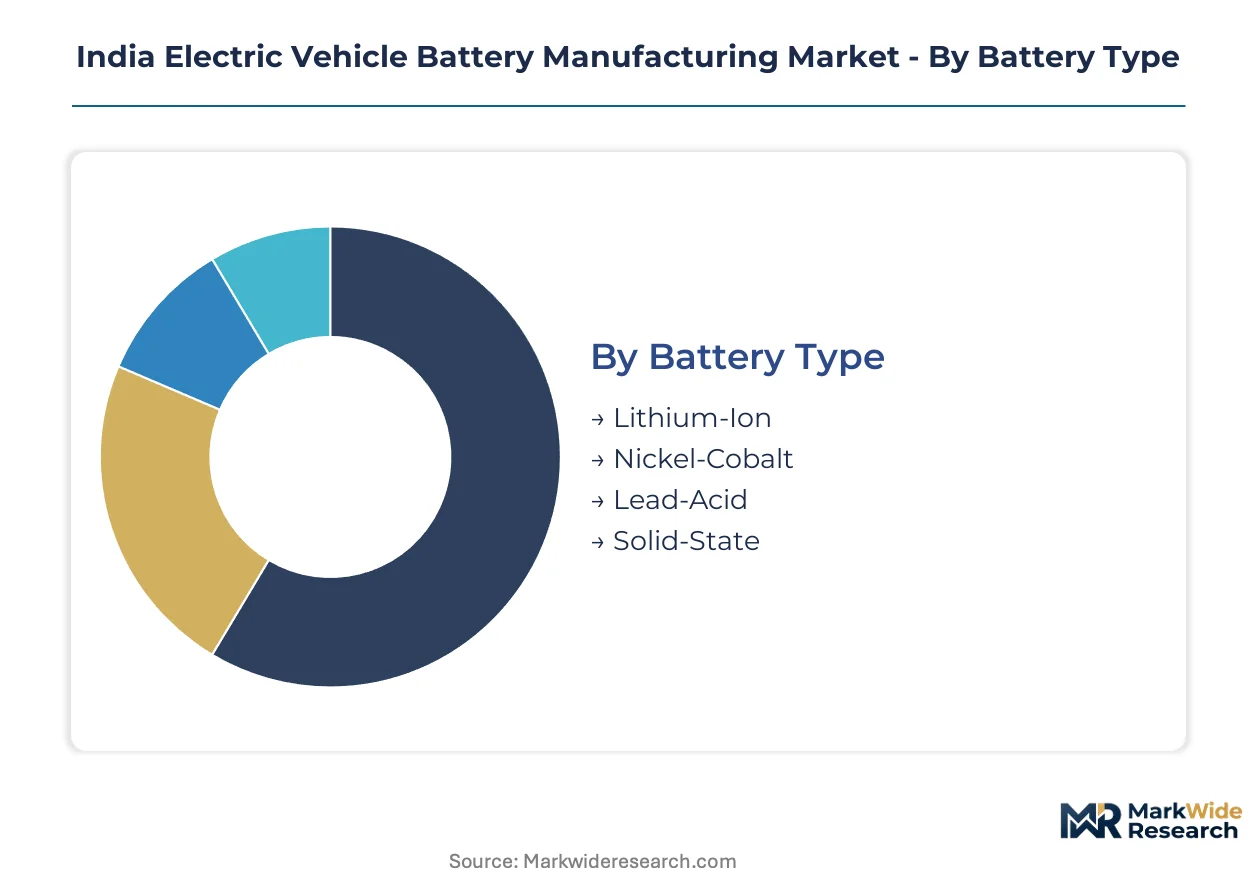
Segmentation reveals how cell chemistry, thermal architecture, and procurement authority reshape margin structures across India's battery manufacturing base. Fleet tenders and state transport contracts concentrate demand in distinct patterns that reward localized formation capacity.
Battery Type:
Use-case spectrum spans price-sensitive two-wheeler electrification through premium SUV platforms demanding 300 Wh/kg energy density.
- Lithium-Ion:Nickel-manganese-cobalt and lithium iron phosphate formulations dominate current gigafactory output. Tamil Nadu corridor investments anchor cathode precursor supply for Mahindra and Tata Motors passenger vehicle programs.
- Solid-State:Ceramic electrolyte prototypes at IISc and IIT-Madras pilot lines target 400 Wh/kg targets. BIS draft protocols for sulfide-based cell geometries remain under consultation, freezing commercial timelines until certification clarity emerges.
- Nickel-Cobalt:High-nickel cathode variants serve premium SUV platforms requiring 600-kilometer range certification.
- Lead-Acid:Sub-₹100,000 two-wheeler and three-wheeler categories retain flooded-cell designs for cost containment.
The dominant share belongs to Lithium-Ion, while Solid-State is closing the gap fastest on R&D intensity.
End User:
Procurement authority concentrates differently across private OEM integration contracts versus state-backed fleet aggregation.
- Fleet Operators:State transport undertakings in Maharashtra and Karnataka tender electric bus deployments through centralized platforms that unbundle chassis from battery supply. These contracts specify 4,000-cycle life warranties and depot-level service networks across tier-two cities.
- Automakers:Passenger vehicle OEMs negotiate direct cell-to-pack integration partnerships with BIS-certified manufacturers. SUV platforms command 70-80 kWh pack capacities with cell-to-chassis bonding for volumetric efficiency.
- Energy Storage Systems:CEA grid integration standards govern stationary assets repurposed from retired electric bus batteries.
- Government Agencies:Defense and postal fleet electrification programs specify indigenous cell design mandates under PLI localization thresholds.
Fleet Operators command the steepest expansion trajectory, though Automakers retain the largest revenue per-unit concentration.
Technology:
Cost tier differentiation separates premium thermal runaway mitigation from commodity battery management firmware.
- Battery Management Systems:Cell balancing algorithms and state-of-charge estimation firmware differentiate supplier competitiveness. Grinntech and Exide Industries anchor tier-two service reach through diagnostic tool deployment at state transport depots.
- Thermal Management:Liquid cooling plates and phase-change material integration address fast-charging heat rejection in commercial vehicle duty cycles. Gujarat manufacturing belt suppliers concentrate on aluminum stamping capacity for cold plate fabrication.
- Fast Charging:350-kilowatt charging protocols stress cell aging characteristics and formation quality.
- Recycling Technologies:Amara Raja's lead-acid infrastructure feeds black mass recovery streams for lithium and cobalt resynthesis.
Battery Management Systems capture the widest installed base, while Thermal Management is gaining share fastest on commercial vehicle penetration.
Application:
Volume concentration diverges between mass-market two-wheeler units and high-capacity public transport platforms.
- Passenger Vehicles:SUV and sedan platforms specify 60-80 kWh packs with nickel-rich cathode formulations. Tamil Nadu automotive supplier density enables just-in-time electrode coating and module assembly.
- Public Transport:Electric bus deployments at state transport undertakings specify lithium iron phosphate chemistry for cycle life and thermal stability. Tender aggregators in Maharashtra unbundle battery supply from chassis procurement, compressing supplier margins.
- Commercial Vehicles:Logistics fleet operators specify swap-compatible battery configurations for 24-hour utilization.
- Two-Wheelers:Price-sensitive segments retain lead-acid substitution below ₹100,000 vehicle price points.
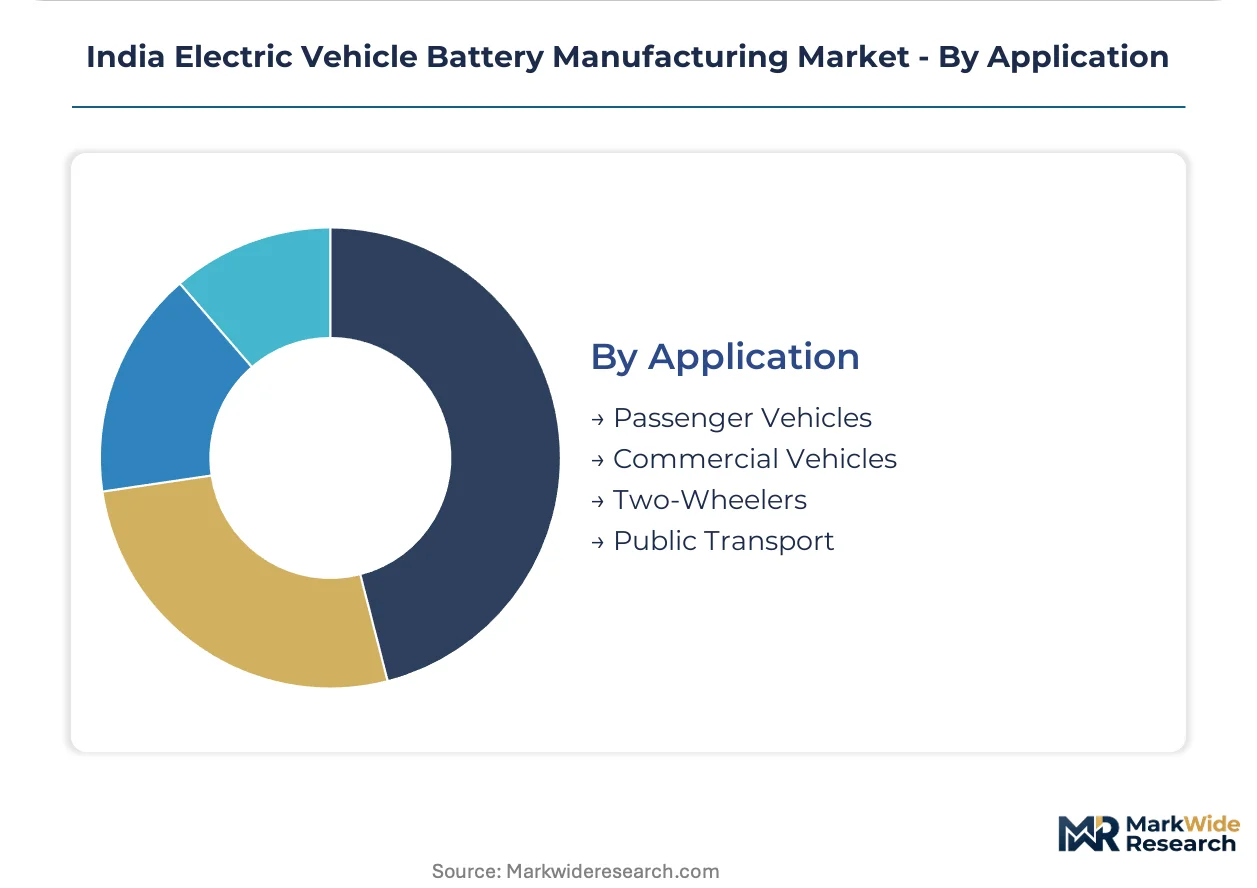
Passenger Vehicles retain the dominant revenue share, while Public Transport is expanding most quickly on state tender acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's battery manufacturing geography reflects a persistent import dependency on lithium feedstock from Australia and Chile, while domestic formation capacity clusters around coastal states with port access and automotive supplier density. Tamil Nadu and Gujarat anchor the export-oriented production base, with Maharashtra and Karnataka driving fleet procurement demand.
Tamil Nadu
State transport undertakings tender electric bus deployments at scale, creating anchor demand for lithium iron phosphate systems. The PLI scheme administered by the Ministry of Heavy Industries channels production-linked incentives toward cathode precursor investments near Chennai. Sriperumbudur and Oragadam automotive corridors concentrate electrode coating and cell formation capacity for Mahindra and Tata Motors passenger vehicle programs.
Gujarat
Mundra and Hazira port zones offer duty-free import zones for cathode active material processing with direct rail links to Delhi-Mumbai industrial corridor off-takers. CEA grid integration standards govern how stationary battery assets connect to charging infrastructure across the state's renewable energy zones. Sanand and Halol manufacturing belts attract aluminum stamping capacity for thermal management cold plate fabrication.
Maharashtra
Fleet operators consolidate procurement through tender aggregators that unbundle vehicle chassis from battery pack supply. BIS certification mandates for cell safety and performance create compliance thresholds that filter import-dependent assemblers from domestic producers. Chakan and Talegaon automotive clusters host depot-level service networks for state transport undertaking electric bus programs.
Karnataka
State transport undertakings tender electric bus deployments through centralized platforms specifying 4,000-cycle life warranties. The Bureau of Indian Standards draft protocols for sodium-ion and solid-state cell geometries remain under consultation, freezing next-generation product launch timelines. Bengaluru electronics manufacturing corridors concentrate battery management system firmware development and diagnostic tool deployment.
India Electric Vehicle Battery Manufacturing Market Competitive Landscape
On the supply side, the industry is consolidating around domestic gigafactory commitments while module-tier suppliers face margin compression from cell-to-pack architecture shifts. Three archetypes dominate: legacy battery manufacturers with recycling infrastructure, indigenous cell design specialists serving commercial vehicle duty cycles, and electronics fabricators pivoting into battery management systems. Competitive moves center on backward integration into cathode precursor processing and strategic partnerships with state transport undertakings through tender aggregation platforms.
Within the legacy manufacturer tier, Exide Industries Limited and Amara Raja Batteries occupy positions anchored by century-old distribution networks and lead-acid recycling infrastructure feeding cathode precursor streams. Grinntech Motors & Services Pvt. Ltd. exemplifies the indigenous specialist archetype, focusing on lithium-ion cell design for commercial vehicle applications. These three represent distinct competitive vectors: aftermarket service reach, recycling integration, and indigenous R&D capability.
| Leading Market Players |
|---|
| Batteryinc |
| Bharatcell |
| Exide Industries Limited |
| Grinntech Motors & Services Pvt. Ltd. |
| Exicom Energy Systems Pvt. Ltd |
| Amara Raja Batteries |
| Battrixx |
| Ipower Batteries |
| Aqueouss |
| Others |
Pricing and Supply Chain Analysis
Lithium import dependency from Australian and Chilean extraction operations determines both the spread between premium and economy battery tiers and the geographic clustering of domestic formation capacity around Tamil Nadu and Gujarat port zones.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with pricing stratification across premium, standard, and economy tiers tied to BIS certification grade and cathode chemistry composition. Cost compression in the standard tier is intensifying because fleet tender aggregators unbundle battery supply from chassis procurement, forcing suppliers to absorb logistics and depot-service costs. Two-wheeler OEMs exhibit the highest price sensitivity, while premium SUV platforms demonstrate the lowest due to cell-to-pack integration premiums.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculations for cathode active material and formation equipment imports. Domestic cell manufacturing draws from spodumene concentrate sourced from Australia, lithium carbonate from Chile, and separator membranes from South Korea and Japan. Single-source vulnerability concentrates in electrolyte salt formulations where domestic expertise remains tethered to IISc and IIT-Madras research labs. Distribution runs through state transport undertaking tender platforms and direct OEM integration contracts anchored by BIS certification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's electric vehicle battery manufacturing sector represents an early-cycle expansion story justified by the PLI scheme's production-linked incentive structure redirecting capital toward domestic gigafactory construction at scale.
For Market Incumbents: Insulate margin position through backward integration into cathode precursor processing and captive recycling infrastructure feeding black mass recovery streams. Sodium-ion chemistry substitution threatens lithium iron phosphate dominance in stationary applications, making electrolyte formulation R&D partnerships with IIT-Madras and IISc a critical capability lock-in.
For New Entrants and Emerging Players: Build out depot-level service networks across tier-two cities in Maharashtra and Karnataka where state transport undertakings tender electric bus deployments through unbundled procurement platforms. Second-life stationary storage applications for retired electric bus batteries offer the most penetrable white-space segment, with go-to-market traction through CEA-compliant grid integration partnerships.
For Investors and Strategic Acquirers: BIS certification expansion to sodium-ion and solid-state variants reshapes the acquisition landscape toward cell manufacturers with pilot-scale ceramic electrolyte capabilities and anticipated protocol compliance engineering. Long-term viability centers on five-to-ten year localization thresholds under PLI scheme domestic value addition requirements. The signal to monitor is draft protocol finalization timelines at the Bureau of Indian Standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Processing | Captures margin from Australian spodumene concentrate through Tamil Nadu corridor electrode coating capacity. |
| BIS Certification Pre-Qualification for Next-Generation Chemistries | Front-loads compliance engineering spend ahead of anticipated sodium-ion and solid-state protocol enforcement. |
| Depot-Level Service Network Expansion | Secures fleet operator loyalty through tier-two city aftermarket reach required by Maharashtra tender aggregators. |
| Second-Life Stationary Storage Partnerships | Repurposes retired electric bus batteries into CEA-compliant grid stabilization assets for renewable integration. |
| Recycling Infrastructure Scale-Up | Feeds black mass processing streams from lead-acid recovery into lithium and cobalt resynthesis for cathode production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and industry association disclosures across the battery manufacturing value chain. Primary interviews engaged cell formation engineers, state transport undertaking procurement officers, cathode precursor plant managers, and PLI scheme administrative officials at the Ministry of Heavy Industries. Secondary validation drew from BIS certification records, CEA grid integration standards, customs import data for lithium carbonate and spodumene concentrate, and automotive production databases. Bottom-up capacity installation tallies triangulated against top-down PLI incentive allocation trajectories.
Forecast inputs span cell chemistry segmentation, thermal architecture tiers, and procurement authority concentration across fleet tender versus direct OEM channels over the projection horizon. The analytical framework models vehicle class, propulsion architecture, and regional production cluster dimensions. CAGRs were derived from installed capacity buildout curves against tender aggregation velocity and BIS certification throughput rates. Industry-specific forecast inputs include PLI incentive eligibility thresholds and formation equipment commissioning cycles.
Stress conditions across lithium carbonate price volatility, rupee-dollar exchange rate swings, and BIS protocol implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PLI scheme continuity and port infrastructure expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
Traction Battery Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
EV Batteries Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
EV Battery Cells Market
EV Batteries
France EV Battery Pack Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
South America Electric Vehicle Battery Anode Market