
 EV Batteries Market | 2026-2036
EV Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
EV Batteries Market Intelligence
The divergence between premium high-nickel chemistries and commodity lithium-iron-phosphate (LFP) chemistries is consolidating the supply base for critical raw materials. Contemporary Amperex Technology Co., Limited (CATL) dominates the market through its immense manufacturing scale and diverse chemistry portfolio. LG Energy Solution competes by focusing on high-performance nickel-manganese-cobalt (NMC) cells for long-range vehicles. Meanwhile, BYD Company Limited leverages its deep vertical integration, controlling production from raw material processing to final vehicle assembly.
An EV battery is a rechargeable energy storage system designed specifically to power the electric motor of a vehicle. These systems are composed of individual cells grouped into modules, which are then assembled into a pack with a battery management system (BMS) to monitor and control performance. The primary commercial purpose is to provide a dense, reliable, and safe power source for electric mobility. Lithium-ion remains the dominant battery type due to its energy density. The application in passenger electric vehicles accounts for the largest market volume, while prismatic cells are a leading form factor.
Regulatory frameworks are fundamentally shaping market structure and technology roadmaps. The European Union's Battery Passport requirements under its Green Deal mandate lifecycle transparency and recycling. In China, GB standards dictate stringent safety and performance criteria for all batteries sold. The US Inflation Reduction Act (IRA) directly influences supply chain decisions by incentivizing domestic production and sourcing from specific trade partners. Strategic decisions for battery manufacturers now hinge on navigating these divergent regional policies while planning for next-generation chemistries.
Market Dynamics
The EV battery market is defined by a fundamental tension between globalized supply chains concentrated in China and increasingly divergent regional industrial policies. Regulations like the US IRA and EU Green Deal are compelling a geographic realignment of manufacturing and material sourcing, creating friction and opportunity simultaneously.
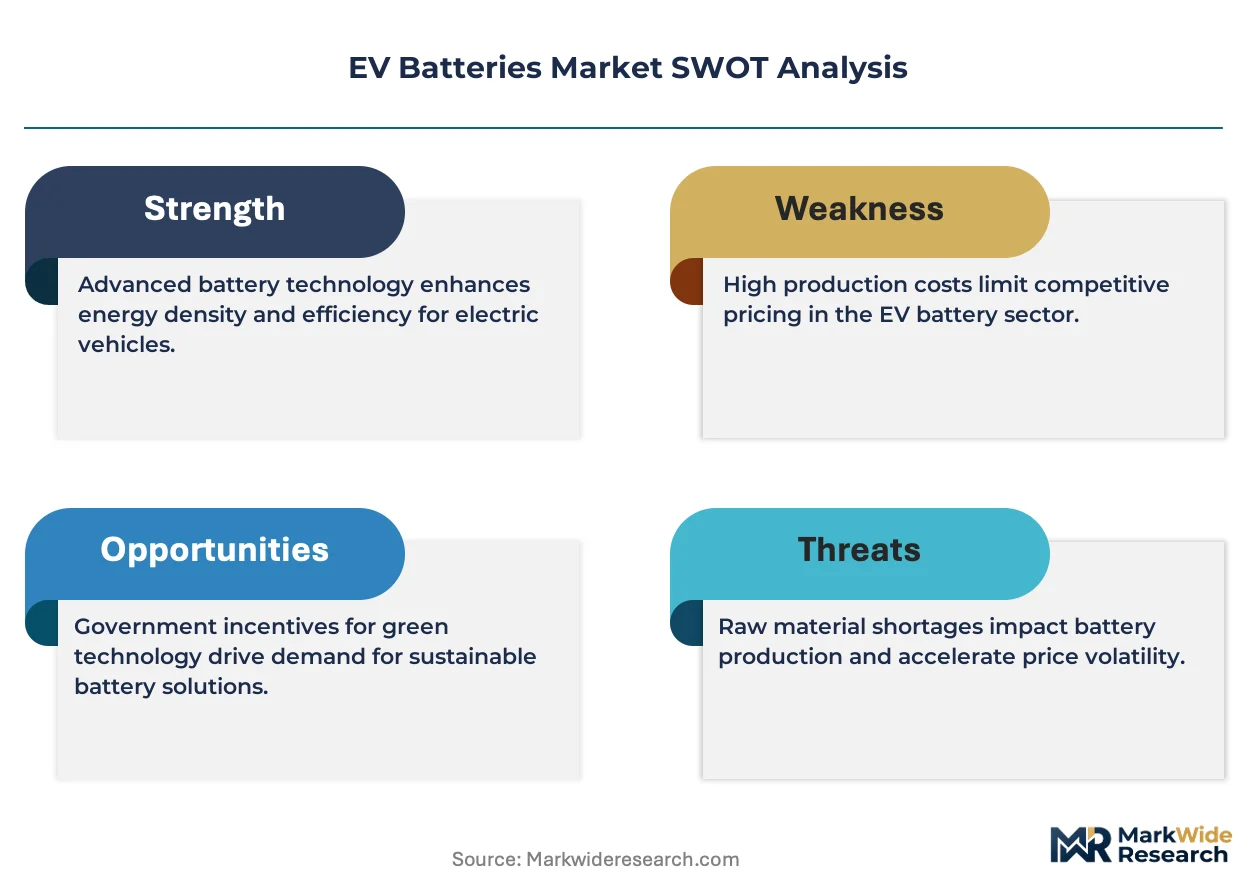
Growth Catalysts
- EV Adoption Mandates:Government policies in the European Union and China mandating the phase-out of internal combustion engines create guaranteed long-term demand for EV batteries.
- Chemistry Advancements:Improvements in energy density for NMC and LFP chemistries are expanding the viability of EVs for a wider range of passenger and commercial vehicle applications.
- Charging Infrastructure Growth:Public and private investment in fast-charging networks reduces range anxiety, a primary barrier to consumer adoption, thus stimulating demand for passenger EVs.
Market Restraints
- Raw Material Volatility:Price instability for critical minerals like lithium and cobalt creates cost-management challenges for cell manufacturers, impacting final battery pack prices.
- Supply Chain Concentration:Heavy concentration of cell manufacturing and material processing in China exposes automakers in Europe and North America to geopolitical and logistical risks.
- Technical Performance Gaps:Battery degradation over a vehicle's lifespan and long charging times compared to refueling conventional cars remain barriers to mass-market consumer acceptance.
Strategic Opportunities
- Emerging Market Electrification:EV incentives and infrastructure development in India and Southeast Asia offer new growth frontiers, particularly for two-wheeler and affordable car batteries.
- Adjacent Market Expansion:High-power battery systems for electric aviation, marine vessels, and heavy-duty mining equipment present opportunities for technology diversification beyond passenger cars.
- Circular Economy Services:Developing battery recycling and second-life stationary storage applications creates new revenue streams and meets regulatory mandates like the EU Battery Passport.
Industry Challenges
- Manufacturing Scalability:The immense capital expenditure and long lead times to build and ramp up gigafactories to meet automotive demand pose a significant execution risk.
- Fragmented Compliance Burden:Navigating divergent requirements from the US IRA, EU Battery Passport, and China's GB standards complicates global product design and supply chain management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Batteries Market |
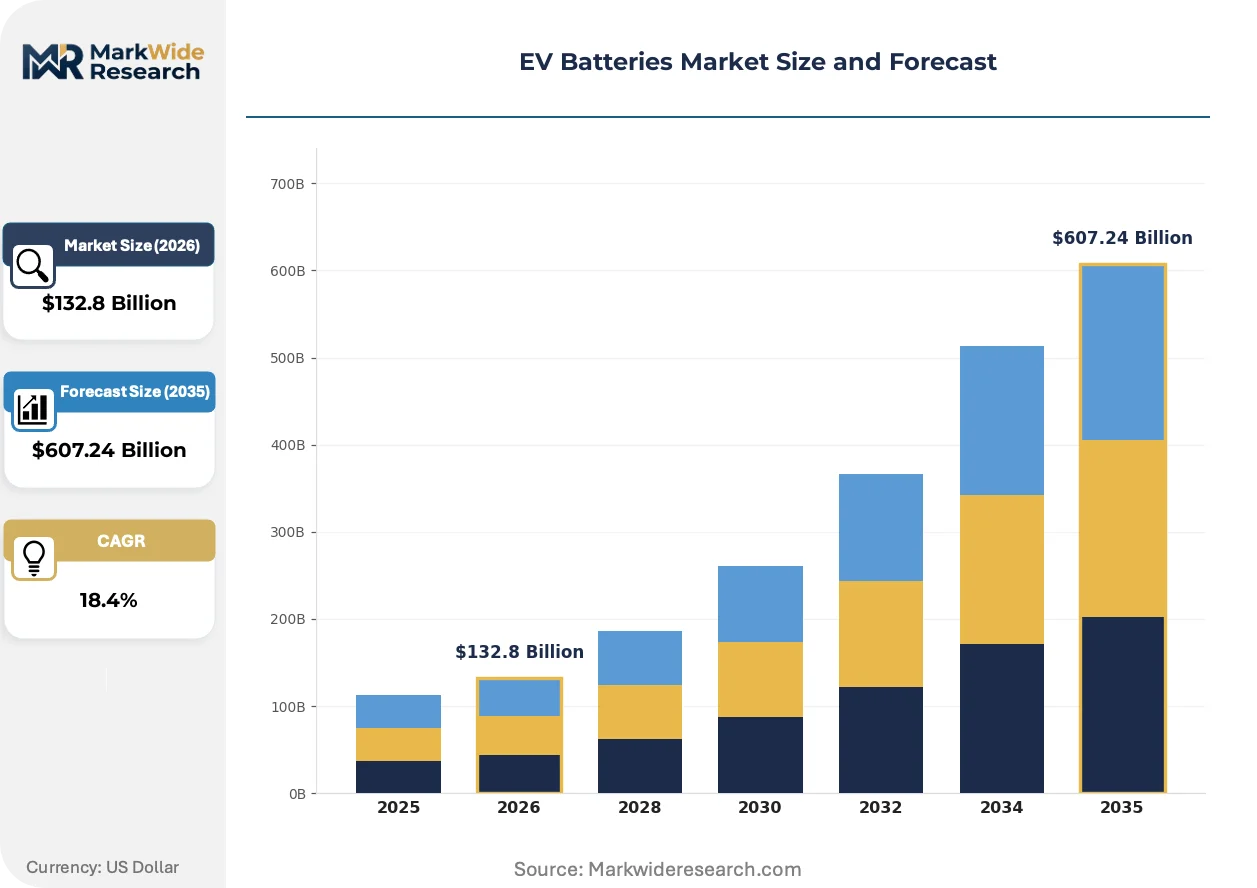
| Market Size in 2026 | $132.8 Billion |
| Market Size in 2035 | $607.24 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Solid-State, Lead-Acid, Sodium-Ion Application: Passenger Electric Vehicles, Commercial Electric Vehicles, Electric Two-Wheelers, Electric Buses, Electric Trucks Form Factor: Cylindrical, Prismatic, Pouch, Polymer, Button Cell End User: OEMs, Battery Manufacturers, Vehicle Assemblers, Aftermarket Suppliers, Fleet Operators |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), BYD Company Limited, LG Energy Solution, Panasonic Energy, Samsung SDI, SK Innovation, CALB, Sunwoda, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Batteries Market Strategic Shifts & Innovations
Pursuit of supply chain resilience is altering technology roadmaps and competitive strategies in the EV battery sector. A dual focus on advanced material science and regionalized production defines the next phase of market evolution.
Sodium-ion battery chemistry provides an alternative to lithium-ion, utilizing abundant and lower-cost materials. Automakers focused on entry-level urban vehicles and stationary storage providers are the initial adopters. This technology is decentralizing raw material dependencies away from the concentrated lithium supply chain, offering a path to lower-cost energy storage.
Legislation like the US Inflation Reduction Act (IRA) provides tax credits for EVs and batteries meeting domestic content requirements. This policy incentivizes onshoring of battery facilities to North America, reshaping investment flows. Automakers targeting the US market are localizing supply networks to ensure their vehicles qualify for consumer credits.
Automakers are moving beyond traditional supplier relationships to engage in direct sourcing and joint ventures with cell manufacturers. This gives OEMs greater control over battery design, chemistry, and supply assurance. The trend is most pronounced among automakers in Europe and North America competing with EV-native companies.
EV Batteries Market Segmentation
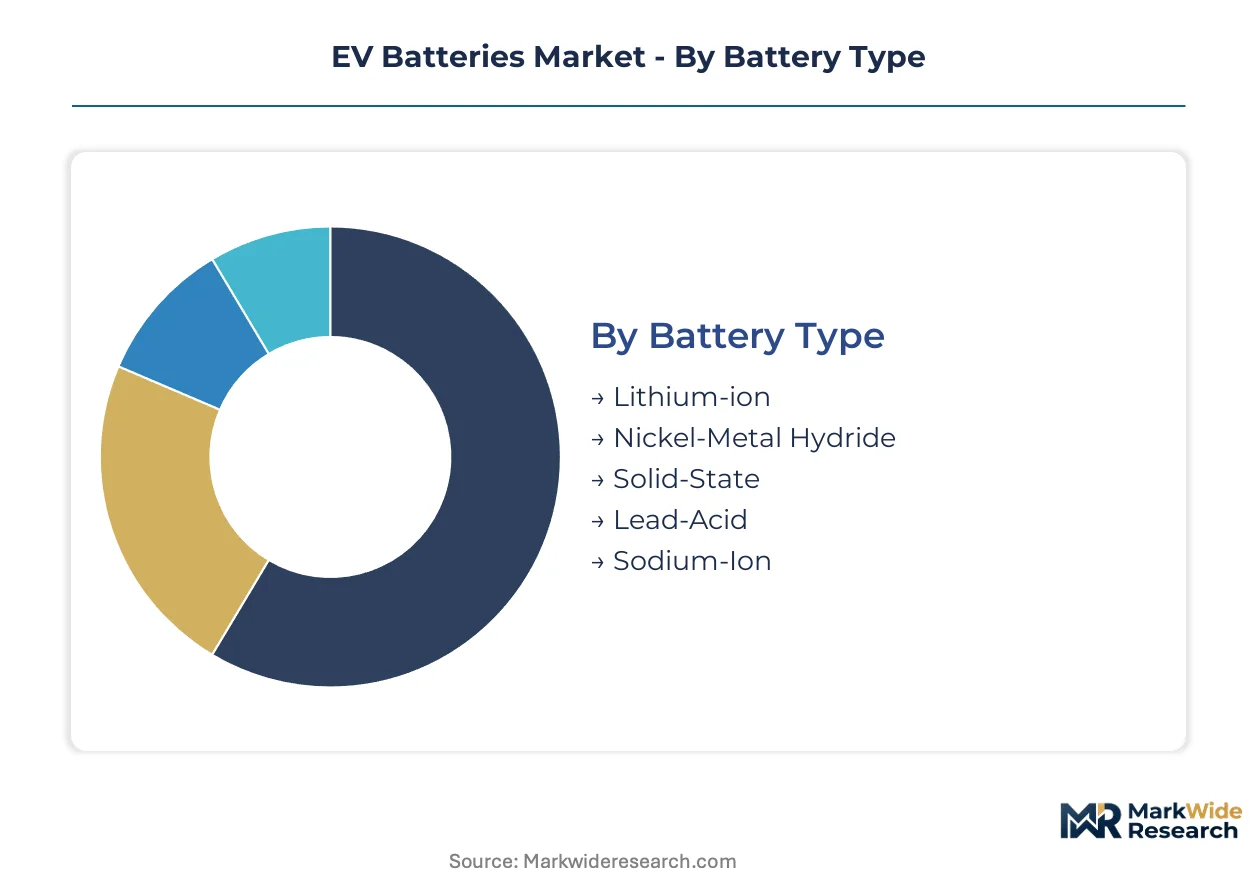
Understanding the EV battery market structure requires a detailed segmentation across critical dimensions. This analysis dissects the market by battery chemistry, vehicle application, physical design, and key end-users. Each segment reflects distinct technological requirements and supply chain dynamics, influencing competitive strategies.
Battery Type:
Supply concentration for EV battery chemistries remains a critical determinant of market dynamics, influencing material sourcing and production hubs.
- Lithium-ion:These rechargeable batteries offer high energy density and long cycle life, making them ideal for electric vehicles. Demand concentrates heavily in passenger electric vehicles across China and Europe, driven by stringent range requirements and performance expectations.
- Nickel-Metal Hydride:These batteries feature moderate energy density and good safety characteristics, often found in hybrid electric vehicles. Toyota and other Japanese automakers utilize this technology for specific models, prioritizing reliability over maximum range.
- Solid-State:This emerging technology replaces liquid electrolytes with solid materials, promising higher energy density, faster charging, and improved safety. Significant demand is anticipated from premium electric vehicle segments in Germany and the US, seeking performance breakthroughs and enhanced safety.
- Lead-Acid:Primarily used for auxiliary power in electric vehicles and for low-speed electric applications due to their cost-effectiveness.
- Sodium-Ion:This chemistry uses abundant and lower-cost sodium, providing an alternative to lithium-ion for entry-level urban vehicles and stationary storage.
Today's leader: Lithium-ion. Tomorrow's challenger: Solid-State.
Application:
Cost-tier differentiation significantly influences battery specifications, with premium applications prioritizing performance and economy segments focusing on affordability.
- Passenger Electric Vehicles:This segment requires batteries with high energy density for extended range and fast-charging capabilities to meet consumer expectations. Demand is strong in Europe and the United States, propelled by consumer incentives and emissions regulations.
- Commercial Electric Vehicles:These applications demand robust batteries capable of high power output and durability for frequent heavy-duty cycles. Urban logistics fleets in China and package delivery services in the US are rapidly electrifying, driven by fleet electrification mandates.
- Electric Two-Wheelers:This segment utilizes lighter, often swappable batteries, with a strong market presence in India and Southeast Asia for urban mobility.
- Electric Buses:These vehicles require large-capacity battery packs to support daily routes and fast charging infrastructure, prominent in municipal fleets in China.
- Electric Trucks:Heavy-duty applications demand extremely high energy storage and power delivery for long-haul transport and demanding operational profiles.
Passenger Electric Vehicles commands the largest volume, while Commercial Electric Vehicles are expanding most quickly.
Form Factor:
Application requirements largely dictate the preferred battery form factor, balancing space utilization, thermal management, and manufacturing efficiency.
- Cylindrical:These batteries, known for their standardized size and robust casing, are favored by some US-based automakers for their high energy density and thermal stability.
- Prismatic:Featuring a rigid rectangular casing, prismatic cells offer efficient packing into battery packs and simplified thermal management. These are widely adopted by China-based EV manufacturers, facilitating streamlined battery pack assembly and manufacturing processes.
- Pouch:Comprising flexible laminated foil, pouch cells allow for highly customizable shapes and optimized space utilization within vehicle designs. European premium vehicle brands frequently use pouch cells, leveraging their design freedom and high energy density.
- Polymer:This form factor often refers to batteries using solid polymer electrolytes, offering enhanced safety and flexibility for niche applications.
- Button Cell:Small, coin-shaped cells primarily used in auxiliary automotive functions or very small electric devices, not for primary propulsion.
Prismatic dominates current market share, with Pouch showing significant innovation.
End User:
Volume requirements significantly differentiate end-user demands, from large-scale automotive production to specialized aftermarket solutions.
- OEMs:Original Equipment Manufacturers integrate battery packs into their vehicle platforms, influencing design and performance specifications. Global automotive brands in Germany, Japan, and the US are major purchasers, seeking direct control over battery technology and supply assurance.
- Battery Manufacturers:These entities produce the individual cells and modules, managing raw material procurement and scaling production. Companies in China and South Korea lead this segment, benefiting from scale economies for cost-efficient cell production.
- Vehicle Assemblers:These companies integrate various components, including battery packs, into final vehicles, often working on a contract manufacturing basis.
- Aftermarket Suppliers:Providers of replacement battery packs or upgraded performance solutions for vehicles already in operation.
- Fleet Operators:Businesses and governmental entities that purchase electric vehicles for operational use, prioritizing total cost of ownership and reliability.
OEMs are the primary revenue generator, while Battery Manufacturers are crucial for supply chain integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering and manufacturing workforces in key Asian countries anchor the global EV battery market. These talent pools drive both innovation and massive production scale. Regional policies and local demand dynamics further shape investment and supply chain decisions across continents.
China
China's extensive manufacturing expertise propels its market leadership, driven by robust domestic EV adoption mandates. The nation's GB standards dictate stringent safety and performance criteria for all batteries sold. Major production hubs in the Yangtze River Delta and Shenzhen concentrate significant cell manufacturing capacity and R&D, serving global and local automakers.
United States
Consumer demand for passenger electric vehicles and fleet electrification drives battery demand in the United States. The US Inflation Reduction Act (IRA) directly incentivizes domestic production and sourcing from specific trade partners. Gigafactories in states like Michigan and Georgia are rapidly expanding, creating a localized supply chain for North American vehicle production.
Germany
Germany's focus on premium electric vehicles and expanding commercial truck electrification fuels its battery market. The European Union's Battery Passport requirements under the Green Deal mandate lifecycle transparency and recycling. Automotive clusters in Bavaria and Baden-Württemberg are centers for advanced battery pack assembly and integration into high-performance vehicles.
South Korea
South Korea's technological prowess in advanced battery chemistries supports its strong export-oriented EV battery industry. Government initiatives support domestic R&D into next-generation battery technologies and materials. Major battery manufacturers in the Seoul Capital Area and Gyeonggi Province lead in nickel-manganese-cobalt (NMC) cell production for global markets.
Japan
Japan's long-standing automotive industry is transitioning towards electric vehicles, with a focus on hybrid and future solid-state technologies. The Ministry of Economy, Trade and Industry (METI) supports domestic battery production and material innovation. Industrial zones around Nagoya and Kansai remain critical for battery component manufacturing and advanced R&D partnerships.
EV Batteries Market Key Industry Players
Top-tier vendors anchor the global EV battery market, while a diverse ecosystem of specialized material suppliers and emerging technology developers occupies lower tiers. The market structure is highly concentrated at the cell manufacturing level. Strategic archetypes include vertically integrated automotive giants, dedicated battery specialists, and advanced materials innovators. Key competitive moves involve massive capacity expansion and direct sourcing partnerships with automakers.
At the scale-driven end, Contemporary Amperex Technology Co., Limited (CATL) exemplifies a dominant Chinese battery manufacturer with a broad chemistry portfolio. LG Energy Solution, a South Korean entity, occupies a position as a high-performance cell supplier for long-range vehicles. BYD Company Limited, another Chinese firm, represents the vertically integrated model, controlling production from raw materials to final vehicle assembly.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| BYD Company Limited |
| LG Energy Solution |
| Panasonic Energy |
| Samsung SDI |
| SK Innovation |
| CALB |
| Sunwoda |
| EVE Energy |
| Others |
Cost & Logistics Intelligence
EU Green Deal's Battery Passport requirements gate qualified battery supply and influence premium-tier pricing access. Compliance costs for lifecycle transparency impact market entry and product differentiation.
Pricing Analysis
Bundled battery packs for OEMs often feature long-term contract pricing, while aftermarket solutions may adopt a per-unit transactional model. Price differentiation stems from energy density, such as high-nickel NMC cells, and the level of after-sales service including warranty and recycling programs. Pricing softness stems from raw material volatility and intense competition among cell manufacturers. Passenger EV OEMs are highly price-sensitive, balancing performance with vehicle affordability, while premium segments tolerate higher costs.
Supply Chain Analysis
Lithium-ion battery production relies heavily on critical minerals sourced from Australia, Chile, and the Democratic Republic of Congo. Cell manufacturing capacity concentrates in China, South Korea, and Japan, creating a significant geographic dependency. Supply chain risk arises from geopolitical tensions and commodity price volatility for lithium and cobalt. Distribution runs through direct OEM partnerships and specialized battery integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV battery market is positioned for significant margin expansion. This expansion is driven by ongoing advancements in cell chemistry, particularly solid-state technology, which commands premium pricing and higher performance.
For Market Incumbents: Extend existing manufacturing footprints into new geographies like North America and Europe to mitigate geopolitical risks and comply with local content regulations such as the US IRA. Diversify chemistry portfolios beyond lithium-ion to include sodium-ion for entry-level segments, countering potential raw material supply constraints. Invest in advanced R&D for solid-state batteries to maintain a performance edge against emerging battery technologies. Capacity expansion in strategic regions ensures supply assurance for major automotive partners.
For New Entrants and Emerging Players: Online procurement platforms for specialized industrial components offer a pathway to target adjacent markets like electric aviation and marine vessels. Focus on niche applications requiring high-power battery systems, such as heavy-duty mining equipment, which presents a less saturated market segment. Emphasize modular battery designs and adaptable form factors to cater to diverse vehicle platforms and emerging electrification needs. Develop advanced battery management systems as a core go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized material suppliers because of the fragmented nature of upstream mining and processing. The long-term viability of the EV battery sector remains strong, supported by global electrification mandates. Target mid-sized cell manufacturers with proprietary chemistry intellectual property or significant regional production capacity. A critical signal to watch is the commercialization timeline for solid-state battery technology, indicating a major market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in North America | Addresses US IRA requirements and localizes supply for American automakers. |
| Joint Venture for Raw Material Processing | Secures upstream supply of critical minerals and stabilizes input costs. |
| Advanced Solid-State Battery R&D | Positions for next-generation performance breakthroughs and premium market segments. |
| Circular Economy Service Development | Creates new revenue streams through recycling and meets EU Battery Passport mandates. |
| Partnership with Commercial Vehicle OEM | Expands market presence beyond passenger cars into heavy-duty applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a robust market perspective. Primary data collection involved discussions with battery cell engineers, automotive procurement leads, regulatory affairs specialists, and material science researchers. Secondary validation drew from public company filings, government energy reports, and industry association publications. A bottom-up approach for market sizing was triangulated with top-down validation.
Segment weighting across battery chemistry, vehicle application, and regional manufacturing capacity formed the core of the analytical framework. The model also incorporated the impact of regulatory frameworks and material availability over the projection horizon. Compound annual growth rates were derived from historical trends and projected adoption rates for electric vehicles. Key forecast inputs included EV sales projections and battery cost reduction curves.
The model assumes a particular technology adoption path; alternative pathways for sodium-ion or solid-state batteries would alter the outlook. Forecasts reflect assumptions regarding raw material availability and geopolitical stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
US EV Battery Pack Market
EV Batteries
Germany EV Battery Pack Market
EV Batteries
European EV Battery Systems Market
EV Batteries
India EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Auto Storage Battery Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market