
 Middle East and Africa Electric Vehicle Battery Manufacturing Market | 2026-2036
Middle East and Africa Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Vehicle Battery Manufacturing Market Insights
Aftermarket service revenue is tilting toward cell diagnostics and residual value recovery as battery leasing expands across commercial fleets. Gotion High-Tech leverages its electrode production know-how to anchor greenfield capacity near Moroccan automotive clusters. First National Battery Pty Ltd sustains its southern African footprint through deep distribution into mining and bus fleet retrofits. Exide Industries Ltd competes on lead-acid replacement cycles while navigating lithium-ion transitions in select segments.
The Middle East and Africa Electric Vehicle Battery Manufacturing sector encompasses the design, cell fabrication, module integration, and pack assembly of electrochemical energy storage systems for propulsion, with lithium-ion cells typically achieving energy densities of 250-300 Wh/kg at pack level and operating voltages spanning 400-800V architectures. Its primary purpose is to supply localized, cost-competitive power sources that reduce import dependency for electric mobility platforms. Lithium-ion chemistry dominates current capacity investments due to established supply chains and OEM qualification protocols, while solid-state architectures represent the fastest-growing technology node as regional labs pilot sulfide and oxide electrolyte formulations. Manufacturing process segmentation reveals electrode production as the margin-intensive stage where coating precision and dry-room infrastructure create entry barriers, whereas recycling is gaining structural attention from regulators and raw material strategists alike.
South Africa's National Regulator for Compulsory Specifications enforces UN ECE R100-aligned cell safety standards that dictate thermal runaway propagation test protocols for local market access. Morocco's investment codes and free-zone status under the country's automotive development framework shape where electrode and assembly lines locate, with CE marking equivalence easing export pathways into European OEM supply chains. Stakeholders must monitor how Saudi Arabia's dual carbon goals and industrial localization mandates redirect procurement toward domestic battery pack formation rather than fully built unit imports.
Market Dynamics
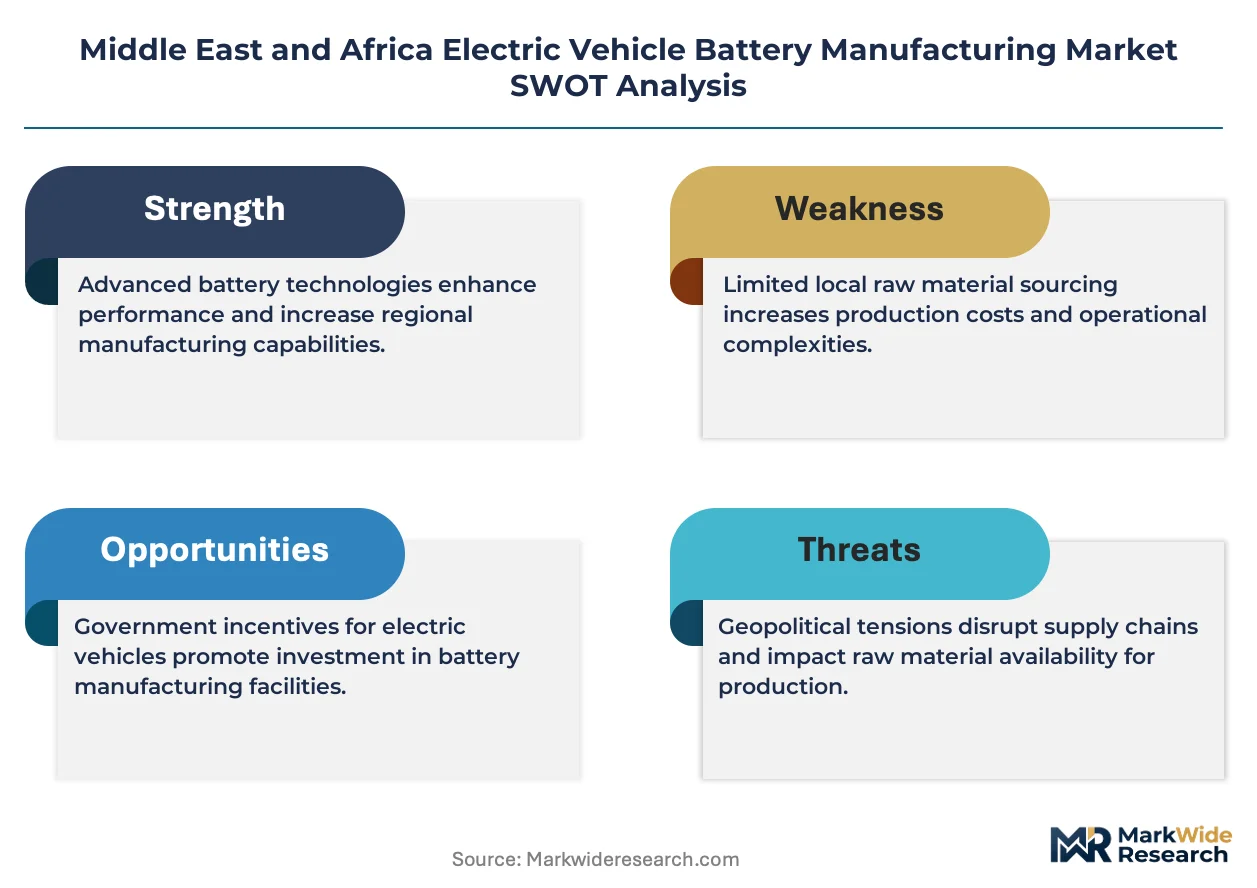
UN ECE R100-aligned thermal runaway propagation testing is collapsing the window for uncertified cell imports into South Africa and Morocco, forcing pack assemblers to localize electrode coating and dry-room infrastructure or exit fleet supply contracts.
Growth Catalysts
- Morocco's Automotive Free-Zone Incentives:The country's investment codes under its automotive development framework draw electrode production lines from Asian specialists, creating captive supply for Renault and Stellantis anchor plants.
- Fleet Electrification Mandates:Urban logistics operators across Johannesburg and Cairo are expanding procurement of locally assembled battery packs to meet municipal zero-emission delivery zones.
- Lithium-Ion Supply Chain Maturation:Established qualification protocols with European OEMs are accelerating cell certification timelines for North African pack integrators.
Market Restraints
- Lithium Carbonate Price Volatility:Raw material input costs swing with spot-market lithium contracts, compressing margin visibility for electrode coaters without offtake guarantees.
- Concentrated Cathode Precursor Supply:Refining capacity for nickel-cobalt-manganese hydroxide concentrates in China and Indonesia creates single-source dependency for MENA pack assemblers.
- UN ECE R100 Certification Friction:South Africa's National Regulator for Compulsory Specifications enforces cell-level safety protocols that extend qualification timelines by 12-18 months for new market entrants.
Strategic Opportunities
- Saudi Arabia's Industrial Localization Mandates:The kingdom's dual carbon goals redirect procurement toward domestic battery pack formation, creating demand for greenfield electrode and module assembly capacity.
- Second-Life Stationary Storage:Retired commercial EV packs from mining and bus fleets in Zambia and Botswana are repurposing into off-grid solar storage, opening residual value recovery channels.
- Solid-State Electrolyte Convergence:Regional research labs piloting sulfide and oxide formulations position North African manufacturing for next-generation cell architectures.
Industry Challenges
- Dry-Room Technician Scarcity:Electrode coating operations require humidity-controlled environments below 1% RH, but regional vocational pipelines lack specialized HVAC and contamination-control training.
- Capex Intensity of Formation Cycling:Pack-level aging and capacity grading equipment demands significant upfront investment, straining balance sheets of mid-scale assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Vehicle Battery Manufacturing Market |
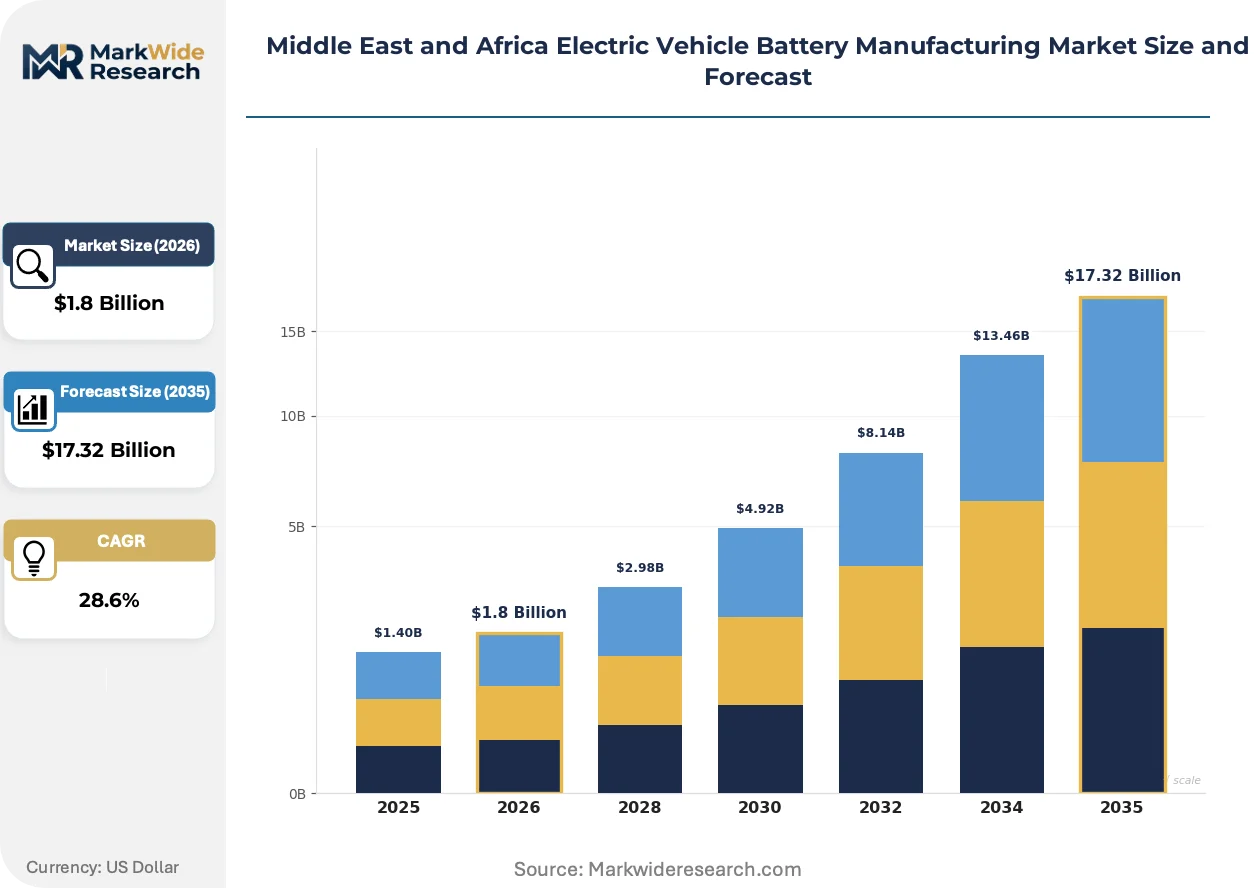
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Manufacturing Process: Cell Assembly, Electrode Production, Battery Pack Formation, Recycling End User: OEMs, Aftermarket Suppliers, Fleet Operators, Battery Leasing Companies Technology: Fast Charging, Energy Density, Battery Management Systems, Thermal Management |
| Companies Covered | East Penn Manufacturing Co. Inc, Exide Industries Ltd, Gotion High-Tech, GS Yuasa Corporation, First National Battery Pty Ltd, Afrivolt, C&D Technologies Inc., Saft Groupe S.A, Middle East Battery Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell chemistry evolution and procurement model restructuring are compressing traditional supply hierarchies across the Middle East and Africa, with regulatory alignment emerging as the primary gating mechanism for market access.
Dry electrode coating is collapsing the capital barrier for electrode production by eliminating solvent recovery systems and reducing dry-room footprint requirements. Moroccan pack assemblers near Tangier-Med automotive clusters are piloting this process to supply Stellantis and Renault plants with localized cells. The technology is collapsing the cost premium between imported Asian electrodes and regional production, enabling first-mover pack integrators to capture fleet service contracts.
South Africa's National Regulator for Compulsory Specifications is enforcing UN ECE R100 thermal runaway propagation protocols that mandate cell-level abuse testing for local market access. This regulatory stringency is disqualifying uncertified imports and redirecting procurement toward compliant regional assemblers. Fleet operators in Johannesburg and Cape Town are now requiring pack-level certification documentation in tender specifications, filtering supplier pools.
Leasing structures are displacing outright purchase for commercial EV batteries across mining and urban logistics fleets. First National Battery and regional financiers are structuring residual value guarantees that transfer degradation risk from fleet operators to battery owners. This model is most visible in South Africa's platinum belt and Morocco's phosphate transport corridors, where uptime guarantees outweigh capital ownership preferences.
Middle East and Africa Electric Vehicle Battery Manufacturing Market Segmentation
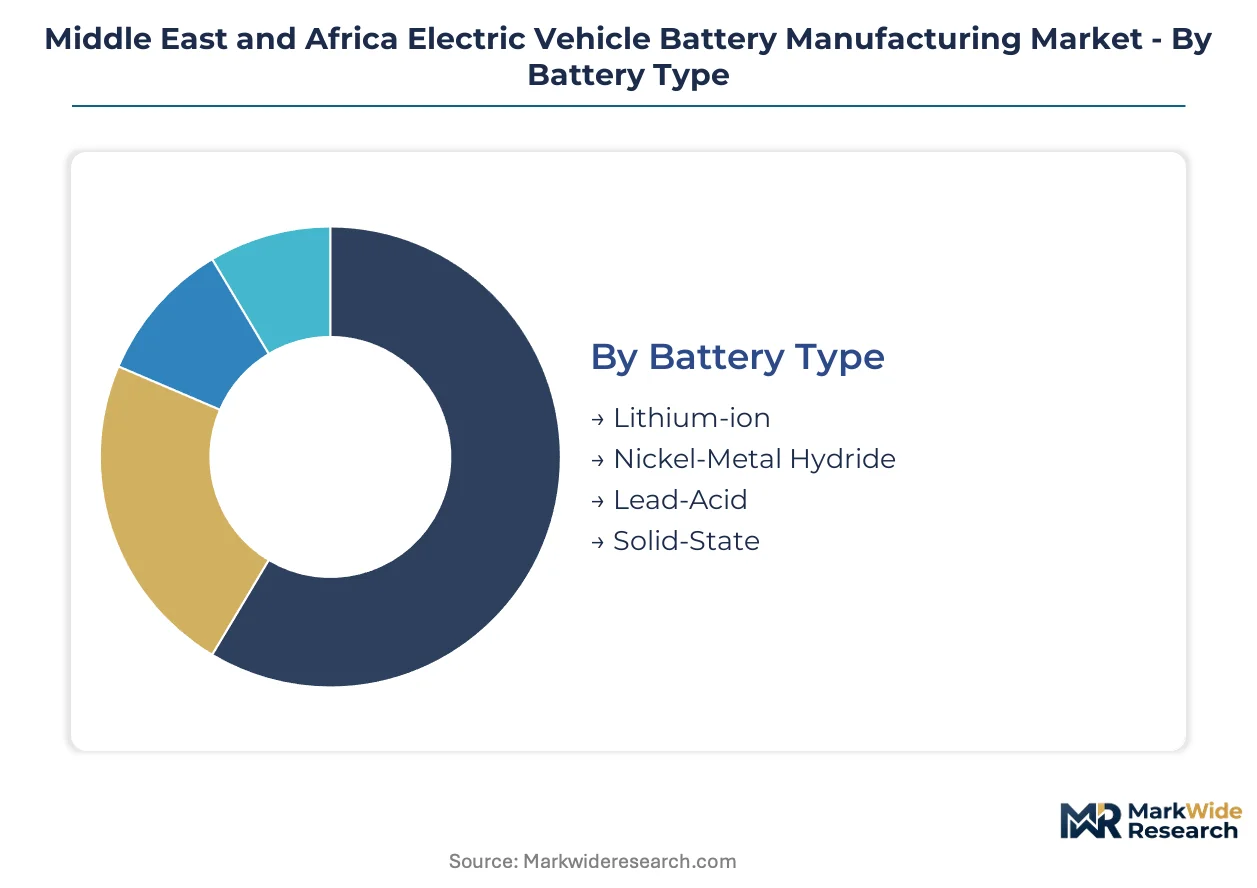
Segmentation reveals how cell chemistry, production stage, and procurement model concentrate margin capture across Middle East and Africa battery manufacturing. Each dimension exposes distinct entry barriers and customer anchoring strategies for regional assemblers.
Battery Type:
Use cases span from cost-sensitive fleet retrofits to next-generation automotive platforms, with chemistry selection dictating dry-room investment and certification pathways.
- Lithium-ion:NMC and LFP formulations achieve 250-300 Wh/kg pack densities and dominate electrode coating investments near Moroccan automotive clusters. Fleet tenders in Johannesburg and Cairo mandate UN ECE R100-certified lithium-ion packs for municipal zero-emission zones.
- Solid-State:Sulfide and oxide electrolyte architectures eliminate flammable liquid components and enable 400-800V architectures. Regional research labs in North Africa pilot these formulations to position for next-generation OEM qualification.
- Nickel-Metal Hydride:Mature chemistry serving hybrid retrofits and price-sensitive bus fleets in southern African mining corridors.
- Lead-Acid:Replacement cycles persist in low-voltage auxiliary systems and entry-level commercial vehicles across distributed aftermarket channels.
Established volume favors lithium-ion; emerging adoption favors solid-state.
Manufacturing Process:
Margin distribution concentrates where contamination control and precision coating create defendable positions.
- Electrode Production:Anode and cathode coating operations require sub-1% RH dry-room environments and precision slurry deposition. Moroccan free-zone incentives are drawing Asian specialists to localize this stage near Renault and Stellantis anchor plants.
- Cell Assembly:Stacking, winding, and electrolyte filling operations translate electrode output into cylindrical or prismatic formats. South African pack integrators are expanding cell-level capacity to satisfy National Regulator for Compulsory Specifications certification timelines.
- Battery Pack Formation:Aging and capacity grading equipment demands significant capex, straining mid-scale assemblers seeking fleet service contracts.
- Recycling:Hydrometallurgical recovery of lithium, cobalt, and nickel from retired commercial packs is gaining regulatory attention across the region's raw material strategists.
Electrode production commands margin premiums; recycling is climbing the fastest.
End User:
Procurement authority is shifting from capital ownership toward service-based models across commercial mobility.
- Fleet Operators:Urban logistics and mining fleet managers in South Africa's platinum belt and Morocco's phosphate corridors are expanding procurement of locally assembled packs. These operators prioritize uptime guarantees and residual value recovery over outright ownership.
- OEMs:Renault and Stellantis anchor plants in Morocco's automotive free zones are qualifying regional cell suppliers for platform integration. UN ECE R100-aligned thermal runaway propagation testing is collapsing the window for uncertified imports.
- Aftermarket Suppliers:Distribution networks serve replacement demand from aging commercial vehicle populations across Egypt and Nigeria.
- Battery Leasing Companies:Financiers structure residual value guarantees that transfer degradation risk from operators to owners, accelerating adoption in capital-constrained segments.
Fleet operators drive volume concentration; leasing companies are gaining share fastest.
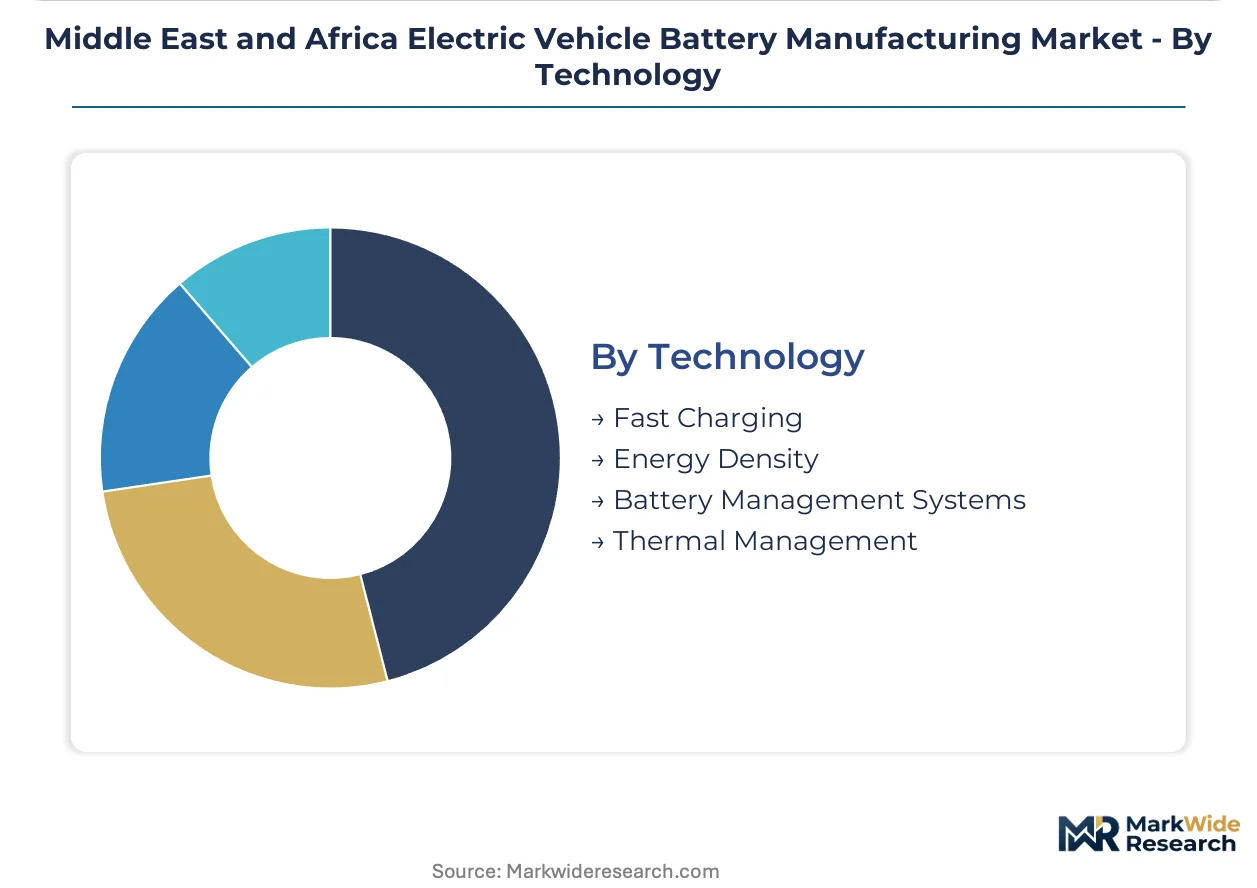
Technology:
Performance differentiation hinges on thermal control intelligence and charge-rate engineering.
- Thermal Management:Liquid cooling plates and phase-change materials prevent thermal runaway propagation in high-C-rate applications. South Africa's National Regulator for Compulsory Specifications mandates abuse testing protocols that elevate thermal system design priority.
- Fast Charging:800V architectures and silicon-anode formulations enable 10-80% charge cycles under 20 minutes for commercial logistics. Demand concentrates in Johannesburg and Cairo municipal delivery networks.
- Energy Density:Pack-level Wh/kg optimization determines vehicle range and payload capacity for regional OEM platforms.
- Battery Management Systems:Cell balancing and state-of-charge algorithms protect asset value under leasing structures where financiers retain degradation risk.
Thermal management anchors safety certification; fast charging is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement elasticity varies sharply across the region. South African mining operators absorb premium pricing for certified packs, while Nigerian logistics buyers remain highly price-sensitive and favor refurbished lead-acid systems.
Morocco
Renault and Stellantis anchor plants in Tangier-Med automotive clusters drive electrode production investments. The country's investment codes and free-zone status under its automotive development framework draw Gotion High-Tech and regional specialists to localize coating operations. Tangier-Med port infrastructure enables CE-marked export pathways into European OEM supply chains.
South Africa
Platinum belt mining fleets and Johannesburg municipal delivery operators expand procurement of locally assembled battery packs. The National Regulator for Compulsory Specifications enforces UN ECE R100-aligned thermal runaway propagation protocols that extend qualification timelines. Cape Town and Gauteng province concentrate pack integration capacity serving bus retrofits and commercial logistics.
Saudi Arabia
Industrial localization mandates under the kingdom's dual carbon goals redirect procurement toward domestic battery pack formation rather than fully built unit imports. The country's national industrial development program incentivizes greenfield electrode and module assembly investments. Riyadh and the Eastern Province are emerging as concentration points for formation cycling and pack integration facilities.
Egypt
Cairo municipal zero-emission delivery zones and Suez Canal logistics corridors generate fleet electrification demand for locally assembled packs. The country's automotive development strategy prioritizes import substitution for battery components. Alexandria and the Greater Cairo region host emerging pack assembly operations serving urban logistics and aftermarket replacement channels.
UAE
Dubai's logistics free zones and Abu Dhabi's industrial diversification programs create demand for high-voltage pack integration serving premium commercial segments. MOHAP and the country's standards body align product safety frameworks with international certification protocols. Jebel Ali industrial clusters concentrate module assembly and battery management system integration for regional export.
Middle East and Africa Electric Vehicle Battery Manufacturing Market Competitive Landscape
Asian electrode specialists and regional pack integrators split the market into technology-licensing and assembly-service archetypes. The structure remains fluid as certification requirements harden. Three archetypes dominate: Asian cell and electrode producers licensing technology to local partners; regional pack integrators investing in dry-room infrastructure and UN ECE R100 compliance; and diversified battery manufacturers pivoting from lead-acid legacy portfolios. Capacity expansion and strategic partnerships with automotive OEMs constitute the dominant competitive moves.
Within the regional pack integrator tier, First National Battery Pty Ltd and Afrivolt occupy positions shaped by fleet service relationships and mining corridor proximity. Gotion High-Tech anchors the Asian specialist archetype through electrode production know-how transferred to Moroccan free-zone operations. Exide Industries Ltd exemplifies the diversified manufacturer pivoting from lead-acid replacement cycles toward lithium-ion qualification in select commercial segments.
| Leading Market Players |
|---|
| East Penn Manufacturing Co. Inc |
| Exide Industries Ltd |
| Gotion High-Tech |
| GS Yuasa Corporation |
| First National Battery Pty Ltd |
| Afrivolt |
| C&D Technologies Inc. |
| Saft Groupe S.A |
| Middle East Battery Company |
| Others |
Pricing and Supply Chain Analysis
Tangier-Med port freight corridors channel electrode imports from Asian coaters into Moroccan automotive free zones, concentrating supply-side leverage among cell-certified assemblers and compressing margins for uncertified pack integrators serving price-sensitive mining fleets across southern Africa.
Pricing Analysis
Aftermarket service revenue from cell diagnostics and residual value guarantees now drives lifetime value capture across commercial EV battery deployments. Three-tier pricing structure across premium UN ECE R100-certified, standard locally assembled, and economy refurbished tiers separates fleet operators by risk tolerance and uptime requirements. Cost compression in standard-tier electrode coating is intensifying because dry-room technician scarcity extends lead times for compliant production. Mining fleet buyers in South Africa's platinum belt absorb premium pricing for certified packs, while Nigerian logistics operators remain the most price-sensitive segment, favoring lead-acid auxiliary systems.
Supply Chain Analysis
Lithium carbonate and nickel-cobalt-manganese hydroxide precursor feedstocks draw from concentrated refining capacity in China and Indonesia, tethering MENA pack assemblers to single-source cathode material dependencies. Electrode coating equipment and precision slurry deposition systems rest on specialized machinery imports from South Korea and Japan. Single-source vulnerability in cathode precursor supply creates structural exposure to spot-market lithium contract volatility. Distribution runs through automotive OEM anchor plants in Moroccan free zones, fleet service contracts with regional integrators, and aftermarket channels serving distributed commercial vehicle populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Electric Vehicle Battery Manufacturing market rewards players who control scarce dry-room infrastructure and UN ECE R100 certification timelines, with technician training pipelines and electrode coating precision representing the critical capability gaps separating viable assemblers from stranded capacity.
For Market Incumbents: Pre-empt emerging Asian electrode specialists by locking long-term offtake agreements with Renault and Stellantis anchor plants in Tangier-Med clusters. Accelerate in-house production of formation cycling capacity to capture residual value guarantees under expanding battery leasing structures, defending against financiers who threaten to disintermediate pack integrators from fleet service relationships.
For New Entrants and Emerging Players: Build out dry electrode coating pilot lines near Johannesburg or Cairo municipal logistics corridors, where fleet electrification mandates create certified demand without requiring full cell fabrication capability. Target second-life stationary storage repurposing from retired mining and bus packs in Zambia and Botswana, using residual value recovery as the go-to-market angle to bypass upfront cell certification barriers.
For Investors and Strategic Acquirers: Regional pack integrators with established UN ECE R100 compliance and fleet service contracts in South Africa's mining corridors represent the most defensible acquisition archetype for long-term viability. Monitor Saudi Arabia's industrial localization mandate implementation as the primary inflection signal, with domestic pack formation procurement redirection indicating sufficient demand scale to justify greenfield electrode investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry-Room Infrastructure Investment | UN ECE R100 certification timelines collapse without sub-1% RH coating capacity, disqualifying uncertified imports from South African mining fleet tenders. |
| Electrode Production Localization | Moroccan free-zone incentives enable Gotion High-Tech to supply Stellantis and Renault plants with CE-marked cells, bypassing Asian import dependencies. |
| Battery Leasing Structure Development | Residual value guarantees transfer degradation risk from Johannesburg logistics operators to financiers, accelerating capital-constrained fleet electrification. |
| Solid-State Electrolyte R&D Partnership | Regional research labs piloting sulfide formulations position North African manufacturing for next-generation cell architectures beyond lithium-ion dominance. |
| Second-Life Storage Repurposing | Retired commercial EV packs from Botswana mining fleets convert into off-grid solar storage, opening circular revenue streams for regional integrators. |
Research Methodology
Initial hypotheses were tested against primary input from dry-room operations managers, fleet procurement directors at mining and logistics operators, automotive OEM platform engineers, and electrode coating equipment specialists, and refined through secondary validation across UN ECE regulatory filings, South African National Regulator for Compulsory Specifications documentation, Moroccan automotive free-zone investment codes, and customs trade data for lithium carbonate and precursor material flows. Bottom-up cell and pack production capacity estimates were triangulated against top-down fleet electrification procurement forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning cell chemistry, manufacturing process stage, end-user procurement model, and thermal management technology tier. CAGRs were derived from installed base growth rates and replacement cycle dynamics rather than extrapolated from historical price trends. Industry-specific forecast inputs incorporated UN ECE R100 certification timeline assumptions and dry-room technician pipeline constraints.
Sensitivities concentrate around lithium carbonate spot price volatility, UN ECE regulatory alignment timing, and Saudi industrial localization mandate implementation pace. Forecasts reflect documented assumptions regarding fleet electrification policy continuity and automotive OEM supplier qualification protocols. Cross-checking against IEA critical mineral supply projections and regional automotive production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
UK EV Battery Pack Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Batteries Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Heating System Market