
 North America Electric Vehicle VRLA Batteries Market | 2026-2036
North America Electric Vehicle VRLA Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle VRLA Batteries Market Insights
The split between premium AGM configurations and commodity flooded designs is realigning as electric vehicle auxiliary power demands intensify. EnerSys leverages its North American manufacturing footprint to dominate high-reliability AGM supply for commercial vehicle electrification. Clarios sustains broad aftermarket coverage through extensive distribution networks across US and Canadian service channels. East Penn Manufacturing anchors its position with deep vertical integration into lead recycling and domestic raw material processing.
North America Electric Vehicle VRLA Batteries are rechargeable lead-acid cells utilizing valve-regulated gas recombination technology, typically constructed with absorbed glass mat separators or gelled electrolyte to prevent spillage and enable maintenance-free operation; these units deliver cold cranking amperage and deep-cycle resilience for auxiliary electrical systems in hybrid and full-electric vehicle architectures. AGM variants command the premium tier due to superior vibration tolerance and faster recharge rates demanded by regenerative braking integration in passenger electric vehicles. Flooded products retain volume leadership in commercial bus and industrial equipment segments where cost sensitivity outweighs cycle-life requirements. Aftermarket Providers represent a structurally distinct channel from OEMs, capturing margin pools through warranty replacement cycles and fleet refurbishment programs.
The US EPA and NHTSA jointly shape product standards through emissions compliance pathways and vehicle safety certification requirements that indirectly govern auxiliary battery specifications. Canada's PMRA and Transport Canada administer parallel chemical handling and transportation regulations affecting cross-border battery logistics. Mexico's environmental Secretariat enforces NOM standards for lead-acid manufacturing facilities operating within integrated North American supply chains. Stakeholders must monitor evolving domestic content thresholds under US IRA provisions to determine sourcing strategies and capital deployment timing.
Market Dynamics
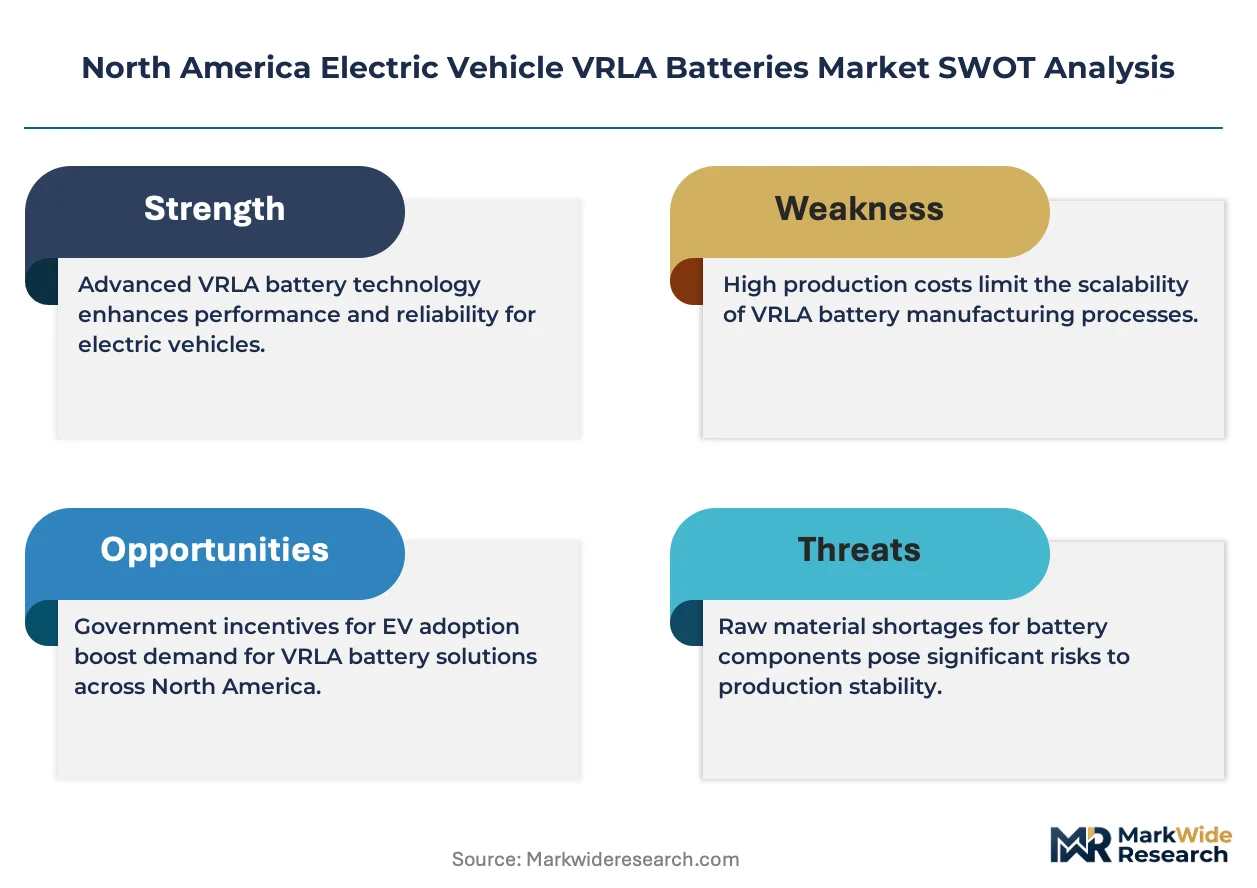
The US Inflation Reduction Act's domestic content thresholds are forcing battery manufacturers to reconfigure North American supply chains around qualifying raw material sourcing and assembly locations. This regulatory pressure is concentrating investment flows toward the Midwest automotive corridor while compressing lead times for auxiliary power system qualification.
Growth Catalysts
- IRA Domestic Content Incentives:The US Inflation Reduction Act's battery component credits are redirecting capital toward North American VRLA manufacturing facilities, accelerating localized production capacity expansion for electric vehicle auxiliary systems.
- Fleet Electrification Mandates:Commercial logistics operators across US and Canadian freight corridors are expanding VRLA procurement for auxiliary power in medium-duty electric trucks, creating sustained demand pull through 2035.
- Absorbed Glass Mat Innovation:AGM separator technology is achieving faster recharge rates compatible with regenerative braking architectures, opening premium positioning in passenger electric vehicle segments.
Market Restraints
- Lead Price Volatility:Raw lead concentrate costs fluctuate with global mining output and smelter capacity constraints, compressing margin stability for North American battery assemblers.
- Single-Geography Concentration:Primary lead smelting capacity concentrates in Missouri and Canada, creating supply vulnerability for US Midwest manufacturing clusters dependent on just-in-time material flows.
- Lithium-Ion Substitution:Declining lithium-ion pack costs for auxiliary power applications threaten VRLA volume in premium passenger electric vehicles where space and weight optimization dominate specification.
Strategic Opportunities
- Mexican Manufacturing Expansion:NOM-compliant lead-acid facilities in northern Mexico offer tariff-advantaged export platforms to US OEMs seeking IRA qualification through USMCA-integrated supply chains.
- Aftermarket Channel Digitization:Direct-to-fleet e-commerce platforms are bypassing traditional distribution tiers, capturing margin pools in warranty replacement and refurbishment procurement cycles.
- AGM-Flooded Convergence:Hybrid separator designs blending AGM performance with flooded cost structures are opening mid-tier positioning in commercial bus and industrial equipment segments.
Industry Challenges
- EPA RCRA Compliance Timeline:Hazardous waste handling certifications for lead recycling operations face extended approval windows, constraining capacity expansion velocity for vertically integrated manufacturers.
- Regenerative Braking Integration:Auxiliary battery systems must synchronize with high-voltage power electronics, requiring electrochemical engineering capabilities scarce in traditional VRLA engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle VRLA Batteries Market |
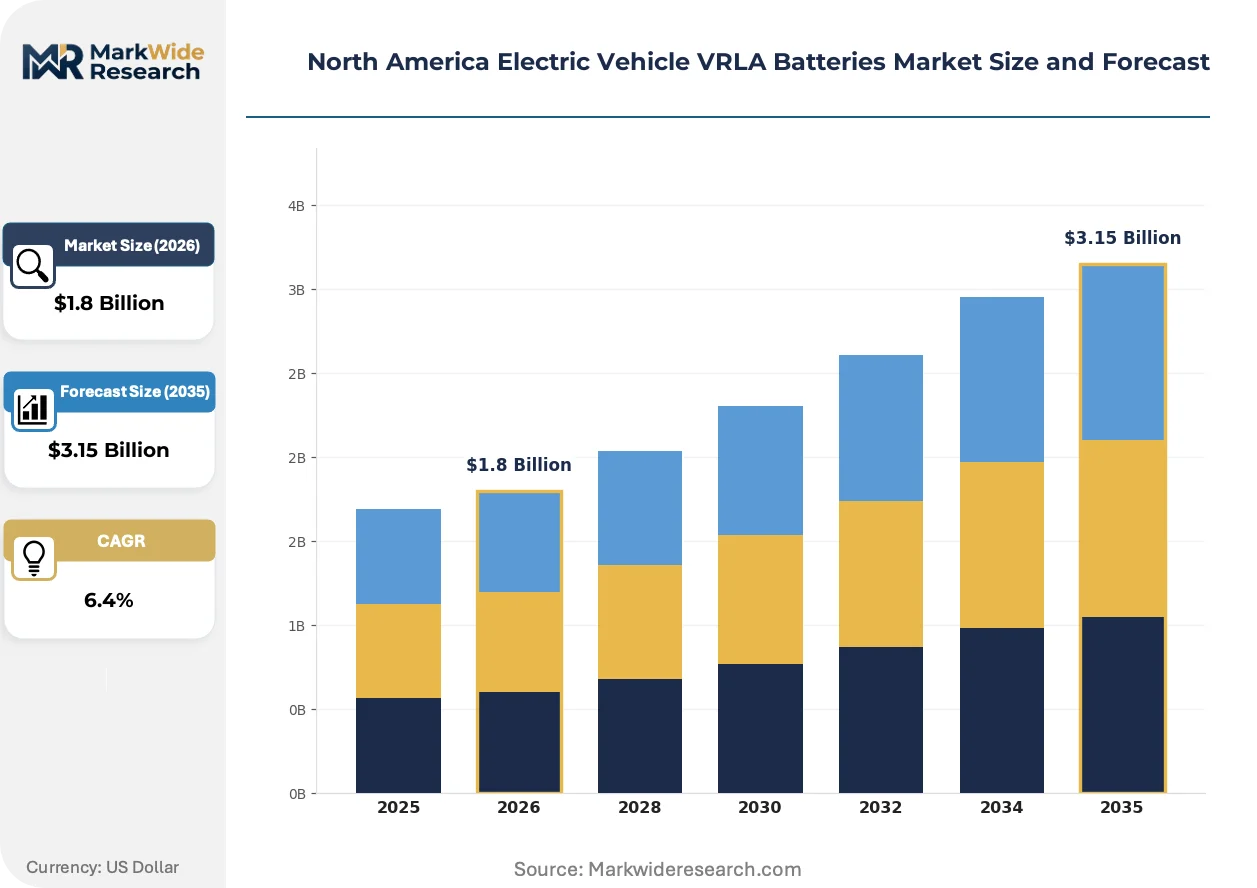
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
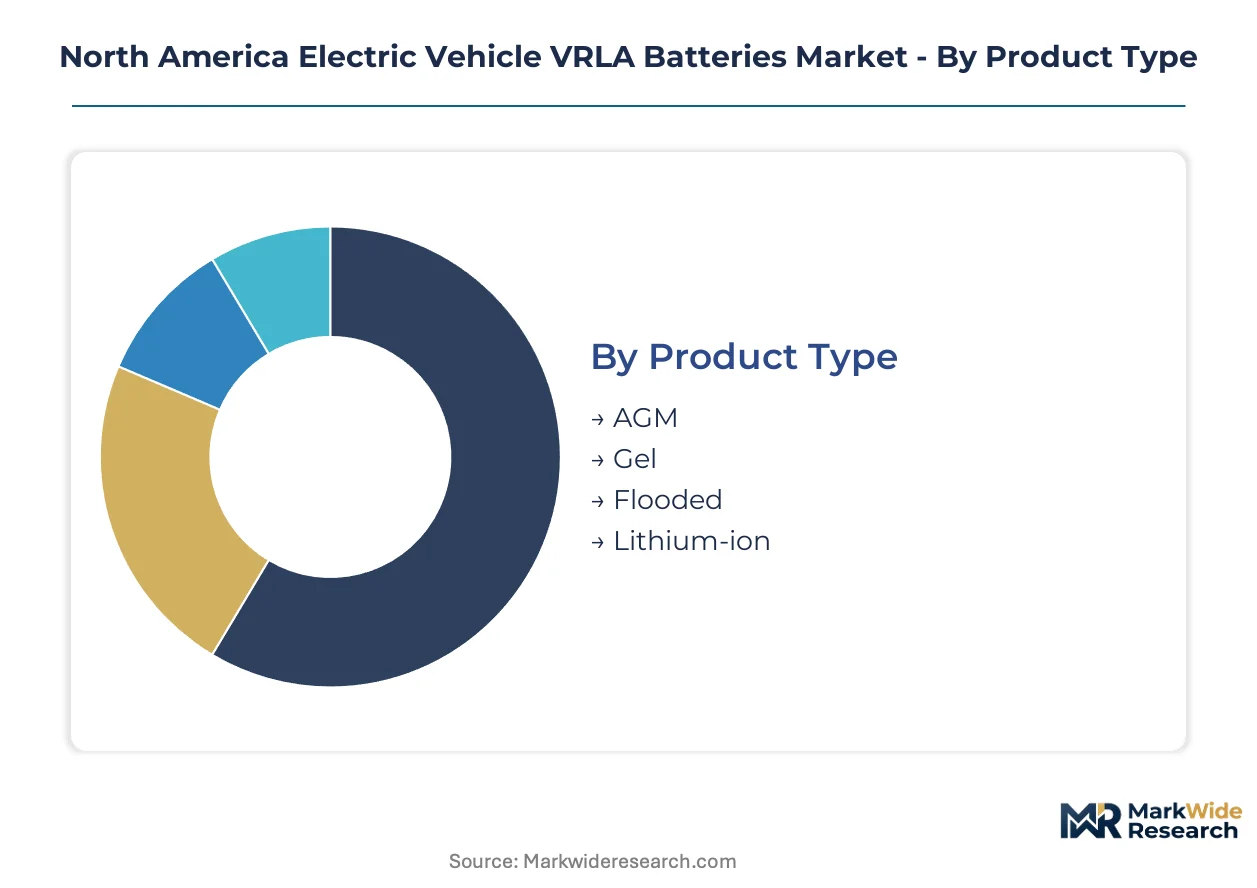
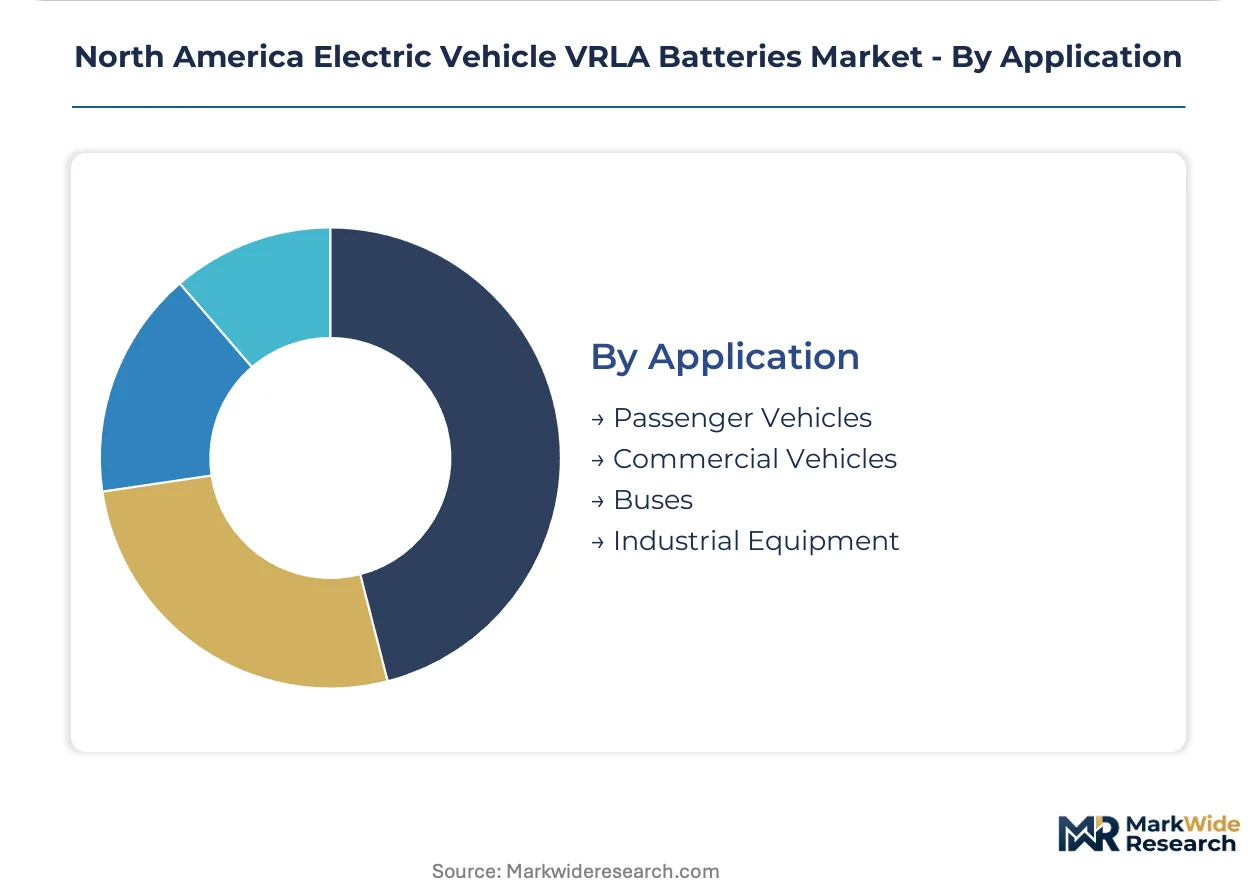
| Segmentation | Product Type: AGM, Gel, Flooded, Lithium-ion End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Capacity: Small, Medium, Large, Extra Large Application: Passenger Vehicles, Commercial Vehicles, Buses, Industrial Equipment |
| Companies Covered | EnerSys, East Penn Manufacturing, Exide Technologies, Clarios, C&D Technologies, GS Yuasa International, Leoch International Technology, Panasonic Holdings Corporation, Champion Power Tech, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle VRLA Batteries Market Trends and Innovations
Active materials science and regulatory compliance engineering are converging to redefine auxiliary power system specifications across North American electric vehicle platforms. Three developments are compressing product lifecycles and reshaping competitive positioning.
Thin-plate pure lead (TPPL) technology is absorbing vibration stress and deep-cycle demands from start-stop and regenerative braking architectures. Commercial fleet operators in the US Midwest automotive corridor are specifying TPPL for auxiliary systems in electric delivery vans. This chemistry is absorbing market share from conventional calcium-alloy designs by enabling maintenance-free operation under severe duty cycles.
The US EPA and NHTSA are tightening emissions compliance pathways that indirectly govern auxiliary battery specifications through vehicle-level certification requirements. Manufacturers must document lifecycle environmental impacts and recycling recoverability rates to maintain OEM supply qualifications. Passenger electric vehicle segments are responding by accelerating AGM adoption to meet extended warranty and reliability thresholds.
Fleet procurement teams are consolidating supplier relationships around vertically integrated manufacturers with captive lead recycling and domestic raw material processing. Traditional distribution tiers are compressing as large logistics operators negotiate direct volume agreements. This concentration is most visible in Michigan, Ohio, and Indiana, where automotive corridor proximity reduces freight costs and enables just-in-time delivery synchronization with vehicle assembly schedules.
North America Electric Vehicle VRLA Batteries Market Segmentation
Auxiliary power architecture in electric vehicles demands precise battery matching across chemistry, scale, and channel. Segment boundaries in North America reflect divergent performance requirements between regenerative braking integration and cost-optimized fleet refurbishment.
Product Type:
Integration depth separates standalone auxiliary units from embedded systems within unified power electronics architectures.
- AGM:Absorbed glass mat separators deliver vibration tolerance and rapid recharge rates demanded by regenerative braking synchronization in passenger electric vehicles. Michigan-based OEMs specify AGM for start-stop and auxiliary power modules requiring maintenance-free operation under severe duty cycles.
- Flooded:Conventional liquid electrolyte designs retain cost leadership in commercial bus and industrial equipment segments where capital constraints outweigh cycle-life optimization. Ohio fleet operators specify flooded units for medium-duty electric truck auxiliary systems with predictable replacement schedules.
- Gel:Immobilized electrolyte chemistry provides spill-proof operation for off-road industrial equipment and specialty vehicle applications requiring orientation flexibility.
- Lithium-ion:Solid-state and lithium iron phosphate chemistries penetrate premium passenger segments where weight reduction and energy density justify unit cost premiums over lead-acid alternatives.
Volume placements concentrate in Flooded; the faster expansion belongs to AGM.
End User:
Channel structure follows warranty lifecycle positioning and procurement centralization intensity.
- OEMs:Original equipment manufacturers integrate auxiliary batteries during vehicle assembly, qualifying suppliers through extended validation protocols tied to NHTSA safety certification requirements.
- Tier-1 Suppliers:System integrators package VRLA units with power electronics, managing thermal management and voltage regulation for delivery to final assembly plants.
- Aftermarket Providers:Independent distributors capture replacement demand through warranty cycles and fleet refurbishment programs across US and Canadian service networks.
- Vehicle Assemblers:Contract manufacturers without captive battery engineering capabilities rely on specified supplier relationships for auxiliary power module integration.
Procurement volume clusters with OEMs; margin capture tilts toward Aftermarket Providers.
Capacity:
Physical scale correlates with vehicle class and auxiliary load profile rather than propulsion system voltage tier.
- Small:Compact form factors serve passenger electric vehicle subsystems including infotainment retention and emergency lighting circuits.
- Medium:Intermediate capacity units dominate light commercial van and delivery vehicle auxiliary power requirements across the US Midwest automotive corridor.
- Large:Heavy-duty specifications support electric bus HVAC and liftgate operations in municipal transit fleets.
- Extra Large:Maximum capacity configurations address industrial equipment and specialty commercial applications with sustained high-current demands.
Shipment volumes peak in Medium; specification migration favors Large for commercial electrification.
Application:
Use-case differentiation reflects duty cycle severity and regulatory compliance pathway intensity.
- Passenger Vehicles:Start-stop and regenerative braking architectures drive AGM specification for rapid recharge acceptance and vibration resilience.
- Commercial Vehicles:Medium-duty electric truck fleets in Indiana and Ohio specify VRLA auxiliary systems for logistics refrigeration and liftgate power.
- Buses:Transit authority procurement favors flooded designs for HVAC and accessibility equipment where total cost of ownership dominates reliability premiums.
- Industrial Equipment:Forklift and material handling applications specify gel or AGM configurations depending on spill containment and orientation requirements.
Unit economics favor Commercial Vehicles; technology upgrade intensity runs highest in Passenger Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Midwest automotive corridor spanning Michigan, Ohio, and Indiana concentrates North American VRLA battery demand for electric vehicle auxiliary systems. Fleet electrification mandates and domestic content incentives under the US Inflation Reduction Act are reshaping procurement patterns across the region's manufacturing clusters.
United States
Michigan-based OEMs specify AGM configurations for start-stop and regenerative braking architectures in passenger electric vehicles. The US EPA and NHTSA jointly administer emissions compliance pathways that indirectly govern auxiliary battery specifications through vehicle-level certification requirements. Ohio fleet operators in the Midwest automotive corridor procure flooded VRLA units for medium-duty electric truck auxiliary systems serving logistics refrigeration and liftgate power demands.
Canada
Ontario's automotive assembly plants integrate VRLA auxiliary systems into electric vehicle platforms destined for US and Canadian markets. Health Canada and PMRA administer parallel chemical handling and transportation regulations affecting cross-border battery logistics between Windsor and Detroit manufacturing zones. Quebec's industrial battery distributors capture aftermarket replacement cycles for commercial fleet refurbishment programs across the Great Lakes freight corridor.
Mexico
Nuevo León's northern Mexico manufacturing zone hosts NOM-compliant lead-acid facilities offering tariff-advantaged export platforms to US OEMs. The country's environmental Secretariat enforces manufacturing standards for facilities operating within integrated North American supply chains seeking USMCA-integrated IRA qualification. Mexico City Metro-based logistics operators specify VRLA auxiliary systems for electric delivery van fleets serving central Mexico distribution networks.
North America Electric Vehicle VRLA Batteries Market Competitive Landscape
Premium-margin players sit above commodity-margin players across separator technology and cycle-life performance dimensions in the North American VRLA battery market. The competitive structure consolidates around vertically integrated manufacturers with captive lead recycling capabilities and specialized AGM engineering teams. Two strategic archetypes dominate: integrated producers controlling upstream material flows, and aftermarket specialists leveraging distribution density for warranty replacement capture. Capacity expansion and direct-to-fleet channel digitization represent the dominant competitive moves compressing traditional distribution tiers.
Within the integrated manufacturing tier, EnerSys and East Penn Manufacturing exemplify producers with North American production footprints and captive recycling operations. Clarios occupies a position representing aftermarket channel specialists with extensive US and Canadian service network coverage. These three anchors illustrate how competitive positioning stratifies between upstream-integrated and distribution-dominant business models.
| Leading Market Players |
|---|
| EnerSys |
| East Penn Manufacturing |
| Exide Technologies |
| Clarios |
| C&D Technologies |
| GS Yuasa International |
| Leoch International Technology |
| Panasonic Holdings Corporation |
| Champion Power Tech |
| Others |
Pricing and Supply Chain Analysis
Captive lead recycling operations in Missouri and Canada anchor supply positions for North American VRLA manufacturers while simultaneously insulating premium-tier pricing power against raw material volatility. This backward integration into smelting and secondary refining creates margin buffers that commodity assemblers lack when London Metal Exchange lead prices fluctuate.
Pricing Analysis
Value-based pricing tied to cycle-life guarantees and regenerative braking compatibility anchors premium AGM configurations. Price differentiation separates UL-certified auxiliary systems for passenger electric vehicles from economy flooded units serving commercial bus fleets. Cost compression in the flooded tier is intensifying because Ohio and Indiana fleet operators are consolidating volume procurement around vertically integrated suppliers. Aftermarket channels exhibit the highest price sensitivity due to warranty replacement commoditization, while OEM qualification programs demonstrate lowest sensitivity given NHTSA safety certification barriers.
Supply Chain Analysis
The US Inflation Reduction Act's domestic content thresholds are reshaping sourcing patterns toward USMCA-integrated supply chains spanning Michigan, Ohio, and northern Mexico. Primary lead concentrate draws from Missouri smelters and Canadian mining operations, with separator materials and electrolyte additives sourcing from specialized chemical processors. Single-geography concentration in Midwest smelting capacity creates vulnerability for just-in-time material flows to Indiana manufacturing clusters. Distribution runs through direct-to-fleet e-commerce platforms that are compressing traditional aftermarket tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where US EPA RCRA hazardous waste certifications create barrier-to-entry moats for lead recycling operators. The IRA's domestic content rules compound this dynamic by favoring capital-intensive players with established North American footprints.
For Market Incumbents: Hedge lithium-ion substitution risk by accelerating TPPL chemistry R&D for regenerative braking synchronization. Reinforce Midwest manufacturing corridor positions through captive recycling capacity additions in Missouri or Ontario. Secure long-term offtake agreements with Michigan-based OEMs before IRA qualification windows tighten.
For New Entrants and Emerging Players: Launch via direct-to-fleet e-commerce platforms targeting medium-duty electric truck refurbishment cycles in the Ohio-Indiana logistics corridor. Exploit white space in NOM-compliant Mexican manufacturing for tariff-advantaged USMCA export positioning. Prioritize aftermarket channel digitization over OEM qualification given extended NHTSA validation timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated battery conglomerates seeking North American IRA qualification. Long-term viability favors vertically integrated manufacturers with captive lead recycling and AGM engineering capabilities. Monitor EPA RCRA permit approval velocity as the critical inflection signal for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Recycling | Captive smelting operations in Missouri secure IRA domestic content qualification for Michigan OEM supply. |
| AGM-Flooded Hybrid Separator Development | Mid-tier chemistry captures commercial bus procurement migrating from pure flooded designs. |
| Direct-to-Fleet E-Commerce Platform Launch | Bypassing traditional distribution tiers captures warranty replacement margin pools in Ohio-Indiana corridors. |
| NOM-Compliant Mexican Manufacturing Expansion | Nuevo León facilities enable tariff-advantaged USMCA export positioning for US OEM qualification. |
| TPPL Chemistry R&D Investment | Thin-plate pure lead technology addresses regenerative braking duty cycles in passenger electric vehicles. |
Research Methodology
Independent corroboration across regulatory filings, trade customs data, and OEM procurement disclosures underwrites the qualitative findings in this study. Primary interviews with VRLA product engineering directors, Tier 1 supplier procurement managers, aftermarket distribution channel heads, and fleet maintenance supervisors were cross-referenced against secondary validation from US EPA RCRA permit databases, NHTSA vehicle certification records, USMCA trade flow statistics, and SEC filings from publicly traded battery manufacturers. Bottom-up unit shipment estimates and top-down value aggregation were reconciled across the analysis window.
Comparable historical periods anchored the projection horizon to observed IRA incentive uptake rates and fleet electrification mandate implementation timelines. The analytical framework modeled segmentation dimensions spanning product type chemistry, end-user channel structure, vehicle class application, and regional production cluster. CAGRs were derived from regression analysis of historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific inputs included lead price volatility indices and EPA permit approval velocity metrics.
Lead price volatility, IRA domestic content rule modifications, and lithium-ion auxiliary system cost curves are the dominant revision risks to the forecast framework. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Traction Battery Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Market
EV Batteries
EV Battery Cells Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market