
 Electric Vehicle Battery Conditioners Market | 2026-2036
Electric Vehicle Battery Conditioners Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Conditioners Market Foresight
The gap between silicon-based power electronics and next-generation silicon carbide inverter designs is narrowing, forcing battery conditioner architectures to accommodate higher switching frequencies and tighter thermal envelopes. CATL leverages its vertical cell-to-pack integration to embed conditioning logic directly into module housings, reducing external wiring complexity. LG Energy Solution anchors its competitive stance through proprietary active balancing algorithms that extend cycle life in cold climates. Samsung SDI differentiates by controlling the full semiconductor stack, from gate drivers to firmware, for its European OEM customers.
Electric vehicle battery conditioners are electrochemical support systems that regulate cell temperature, equalize charge distribution, and monitor state-of-health through integrated sensors and power electronics, typically operating within voltage ranges from 400V to 800V and thermal windows between minus 30°C and 60°C. Their primary commercial purpose is to prevent capacity fade, thermal runaway, and impedance growth that otherwise degrade range and safety over a vehicle's service life. Battery Management Systems now capture the deepest margin pools because firmware licensing and predictive analytics subscriptions recur across multiple vehicle generations. Active Balancing technology leads unit economics for premium passenger applications where cell replacement costs dominate lifetime ownership calculations, while Thermal Management hardware sustains volume leadership across commercial vehicle fleets where duty cycles stress passive architectures beyond their design limits.
NHTSA's proposed battery safety standards in the United States, China's GB/T 38031 cell-level thermal propagation requirements, and the EU Battery Regulation's mandatory state-of-health disclosure are collectively elevating conditioner performance thresholds and compliance documentation burdens. These frameworks shape demand by mandating traceable degradation data and fail-safe thermal controls as preconditions for type approval and market access. Stakeholders must decide whether to build conditioning intelligence in-house or source from specialized suppliers before semiconductor allocation constraints harden procurement timelines for next-generation 800V platforms.
Market Dynamics
The transition to 800V architectures is compressing thermal management tolerances and forcing battery conditioner suppliers to redesign power electronics for higher switching frequencies and tighter thermal envelopes.
Growth Catalysts
- NHTSA Thermal Runaway Mandates:Proposed battery safety standards in the United States require fail-safe thermal propagation barriers, compelling OEMs to upgrade conditioning hardware ahead of type approval deadlines.
- Silicon Carbide Inverter Adoption:Wide-bandgap semiconductors operating at 100+ kHz switching frequencies generate localized heat spikes that passive conditioning systems cannot manage, driving demand for active thermal regulation.
- Fleet Electrification:Commercial vehicle operators in Germany operate battery conditioning test facilities at scale to extend pack life across high-duty-cycle applications where replacement costs dominate total ownership economics.
Market Restraints
- Semiconductor Allocation Constraints:Gate driver ICs and power MOSFETs for 800V platforms face 26-32 week lead times, hardening procurement timelines for next-generation conditioner designs.
- GB/T 38031 Certification Burden:China's cell-level thermal propagation requirements impose extensive documentation and testing protocols that extend product development cycles by 8-14 months for non-domestic suppliers.
- Passive Architecture Persistence:Low-cost commercial vehicle segments in price-sensitive markets continue specifying air-cooled systems that limit addressable premium for intelligent conditioning modules.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for advanced chemistry cell manufacturing create captive demand for integrated conditioning logic within domestic battery assembly plants.
- Predictive Analytics Subscriptions:Firmware licensing models that monetize state-of-health data across multiple vehicle generations capture recurring revenue streams detached from hardware shipment cycles.
- Second-Life Stationary Storage:Retired EV packs require refurbished conditioning systems to meet IEC 62619 safety standards for grid-scale battery installations, opening aftermarket service corridors.
Industry Challenges
- Embedded Software Talent Scarcity:Active balancing algorithm development requires electrochemical modeling expertise combined with automotive functional safety competency under ISO 26262, a skill intersection with limited labor pool depth.
- Legacy 400V Platform Integration:Conditioner architectures must maintain backward compatibility with existing vehicle fleets while accommodating 800V forward designs, doubling validation matrices and testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Conditioners Market |
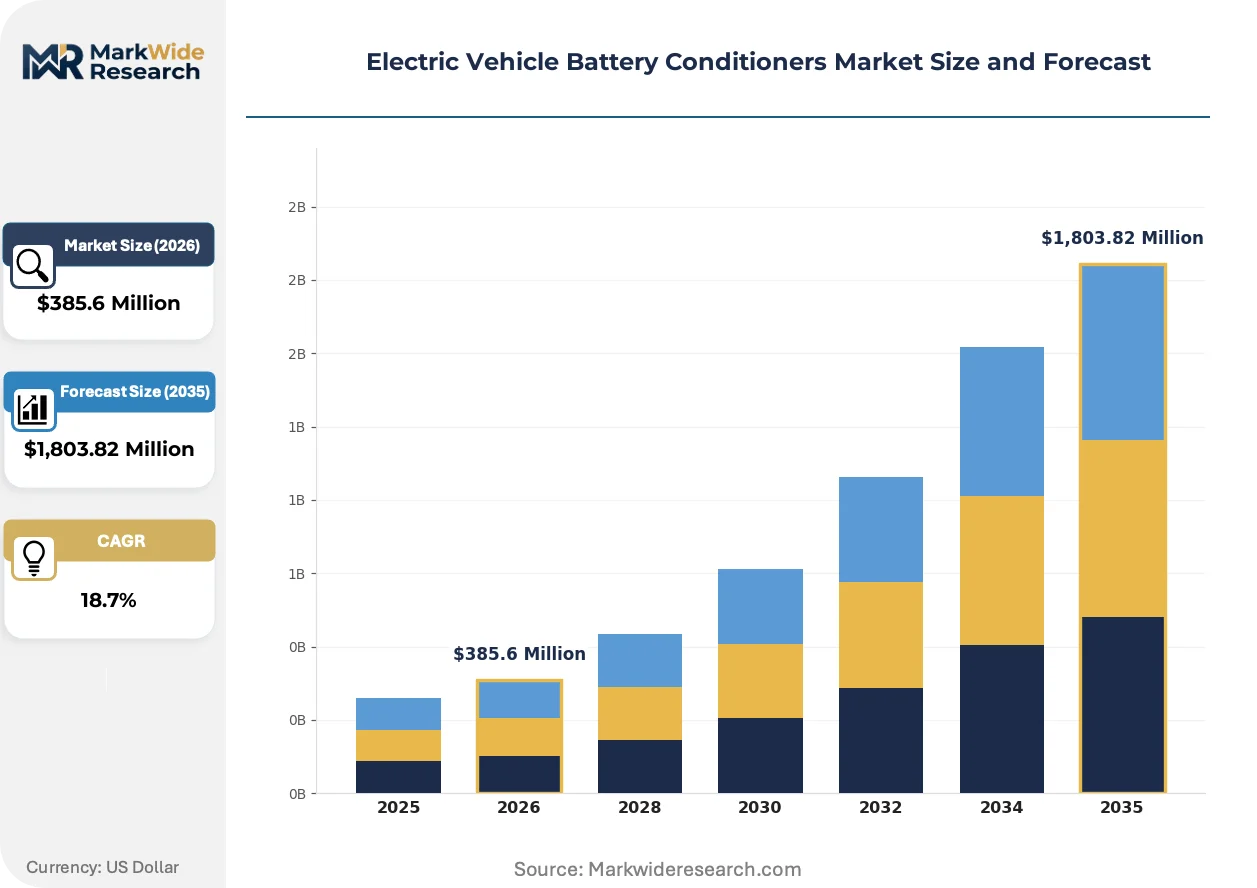
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Chargers, Stationary Conditioners, Fast Charging Units, Battery Management Systems Technology: Active Balancing, Passive Balancing, Thermal Management, State of Charge Estimation End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Utility Vehicles |
| Companies Covered | CATL, LG Energy Solution, BYD Company, Panasonic Corporation, SK On, Samsung SDI, CALB, GS Yuasa Corporation, Automotive Energy Supply Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Conditioners Market Shifts & Advancements
Silicon carbide power electronics are collapsing thermal management margins and forcing a fundamental redesign of how conditioning intelligence integrates with cell-to-pack architectures.
Cell-to-pack integration eliminates module-level housing and external wiring harnesses by embedding temperature sensors and balancing circuitry directly into pack enclosures. CATL and BYD are shipping 800V platforms with this architecture at volume in China. The approach is rendering obsolete discrete conditioner boxes that previously sat adjacent to battery packs.
The EU Battery Regulation mandates traceable state-of-health disclosure and recycled content thresholds for batteries placed on the European market. Industrial consequence includes mandatory battery passports and third-party verification of degradation data. Premium passenger OEMs are responding by specifying conditioners with embedded blockchain-logging capabilities to automate compliance documentation.
Fleet procurement teams now specify performance-based service agreements where suppliers guarantee minimum cycle life rather than selling hardware outright. This unbundles capital expenditure from operational risk and shifts conditioner vendors toward predictive maintenance subscriptions. The model is most visible in German commercial vehicle leasing where total cost of ownership guarantees dominate contract structures.
Electric Vehicle Battery Conditioners Market Segmentation
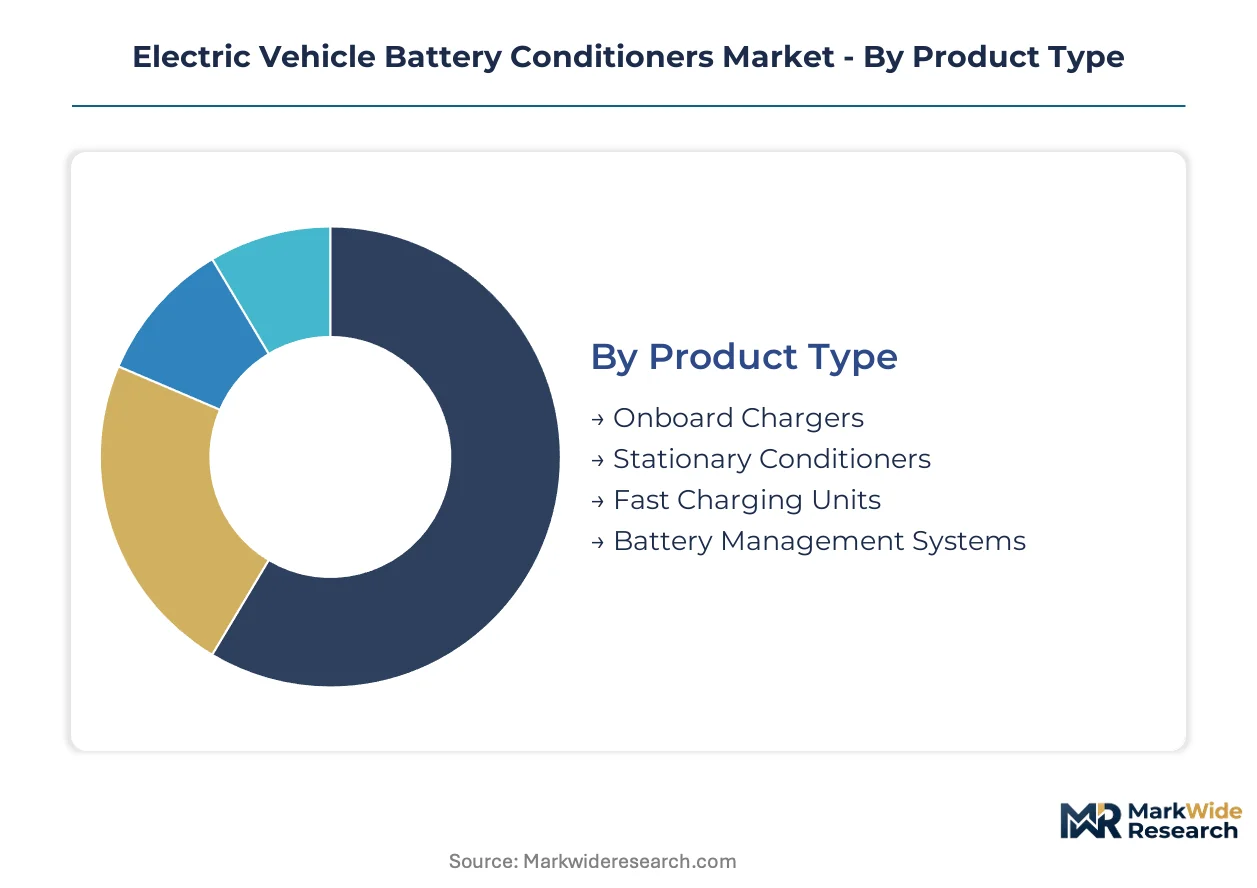
Battery conditioner architectures diverge sharply across vehicle electrification pathways. Product configurations must reconcile 800V platform thermal tolerances with legacy fleet compatibility, while end-user procurement models reshape margin capture mechanisms across hardware and software layers.
Product Type:
Onboard integration versus external infrastructure defines the use-case spectrum from vehicle-embedded intelligence to grid-side conditioning assets.
- Onboard Chargers:Integrated AC-to-DC conversion with embedded cell conditioning logic operates at 11-22kW for residential and workplace charging. German OEMs specify these units with predictive thermal algorithms to precondition packs before DC fast charging sessions, reducing lithium plating risks in cold climates.
- Battery Management Systems:Centralized firmware architectures govern cell-level voltage monitoring, balancing command distribution, and state-of-health analytics through CAN bus integration. CATL and LG Energy Solution license predictive degradation models as recurring revenue streams detached from hardware cycles, capturing margin pools across multiple vehicle generations.
- Stationary Conditioners:Rack-mounted systems for depot charging infrastructure manage thermal envelopes during overnight fleet charging cycles.
- Fast Charging Units:DC dispensers incorporate active cooling interfaces to stabilize cell temperatures during 350kW peak power delivery.
Established volume favors Battery Management Systems; emerging adoption favors Stationary Conditioners.
Technology:
Cost tier differentiation separates electrochemical intervention methods by hardware complexity and software dependency.
- Thermal Management:Liquid-cooled cold plates and refrigerant loops maintain cell temperatures within minus 30°C to 60°C operational windows through active heat exchange. Commercial vehicle fleets in Germany deploy these systems at scale because high-duty cycling degrades passive air-cooled architectures beyond design limits within 18-24 months.
- Active Balancing:Inductive or capacitive charge transfer circuits redistribute energy from high-voltage to low-voltage cells during operation, extending cycle life by 15-20% in premium passenger applications where replacement costs dominate ownership economics.
- Passive Balancing:Resistive bleed-off circuits dissipate excess cell energy as heat, sacrificing efficiency for hardware simplicity and cost minimization.
- State of Charge Estimation:Kalman filter and neural network algorithms predict remaining capacity through impedance tracking and voltage-temperature mapping.
Thermal Management commands current procurement volumes; Active Balancing climbs the fastest in premium segments.
End User:
Customer type determines contract structure, from capital equipment sales to performance-guaranteed service agreements.
- Fleet Operators:Commercial vehicle leasing companies specify outcome-based contracts where suppliers guarantee minimum cycle life rather than selling hardware outright. Total cost of ownership guarantees dominate German contract structures, unbundling capex from operational risk and shifting vendors toward predictive maintenance subscriptions.
- OEMs:Vehicle manufacturers integrate conditioning intelligence at pack design phase, with NHTSA thermal runaway mandates and China's GB/T 38031 standards compelling hardware upgrades ahead of type approval deadlines.
- Aftermarket Providers:Independent service networks refurbish retired EV packs for second-life stationary storage applications under IEC 62619 safety standards.
- Individual Consumers:Retail purchasers access conditioning primarily through bundled vehicle sales, with limited direct procurement of replacement or upgrade hardware.
Fleet Operators drive recurring revenue innovation; OEMs anchor platform-scale volume commitments.
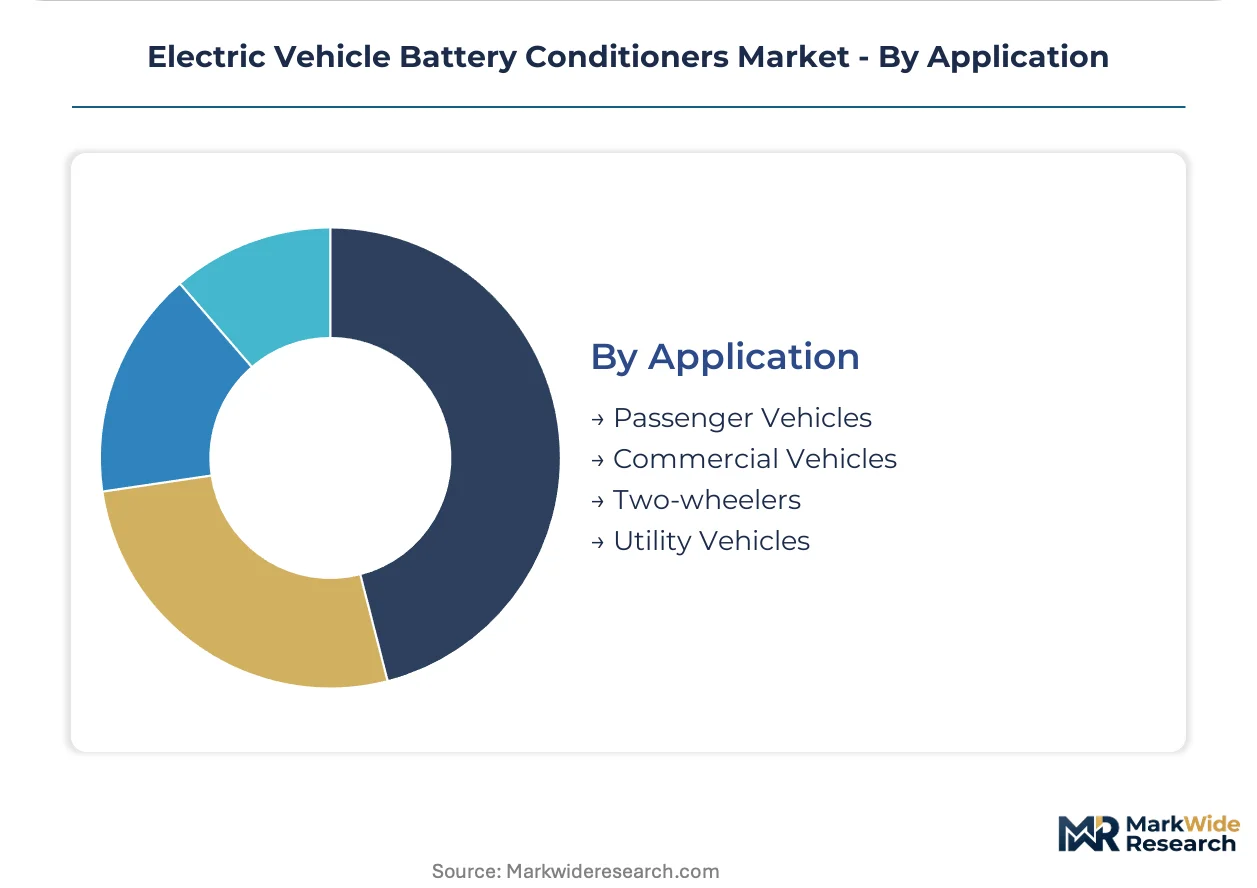
Application:
Vehicle duty cycle intensity shapes thermal stress profiles and conditioning hardware specification tiers.
- Commercial Vehicles:Heavy-duty trucks and buses operate 16-20 hour daily cycles with rapid-charging intervals that generate localized heat spikes. Silicon carbide inverters at 100+ kHz switching frequencies demand active thermal regulation that passive systems cannot manage, compelling fleet procurement of liquid-cooled conditioning architectures.
- Passenger Vehicles:Private automobiles with intermittent usage patterns accommodate simpler thermal management, though 800V platform adoption is compressing tolerances and forcing redesigns for higher switching frequencies.
- Two-wheelers:Low-voltage battery packs in electric scooters and motorcycles rely on air-cooled passive conditioning due to cost constraints and moderate thermal loads.
- Utility Vehicles:Off-road equipment and industrial machinery require ruggedized conditioning enclosures resistant to vibration and contamination exposure.
Commercial Vehicles impose the most demanding performance specifications; Passenger Vehicles deliver the deepest production volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports battery conditioning hardware to fleet operators across Scandinavia and Eastern Europe, with logistics corridors through Hamburg and Rotterdam handling the majority of cross-border shipments for commercial vehicle retrofits.
Germany
BMW and Volkswagen Group operate large-scale conditioning test facilities near Munich and Wolfsburg to validate thermal management systems for 800V platforms. KBA enforces stringent type approval protocols for thermal runaway prevention systems entering the domestic market. Bavaria's automotive cluster concentrates development activity around cell-to-pack integration architectures.
China
CATL and BYD ship cell-to-pack platforms with embedded conditioning logic at volume, capturing domestic fleet electrification contracts. MIIT administers GB/T 38031 certification requirements that extend product development cycles for foreign suppliers. The Yangtze River Delta hosts concentrated manufacturing capacity for silicon carbide power electronics feeding conditioner assembly lines.
United States
Commercial vehicle operators in Michigan and California deploy battery conditioning systems to extend pack life across high-duty-cycle logistics applications. NHTSA proposed thermal runaway mandates compel OEMs to upgrade hardware ahead of 2026 type approval deadlines. Detroit's automotive engineering base anchors validation partnerships between domestic fleet managers and semiconductor suppliers.
South Korea
LG Energy Solution and Samsung SDI leverage proprietary active balancing algorithms to secure European OEM supply contracts for cold-climate applications. METI coordinates domestic standards alignment with international IEC frameworks for second-life stationary storage applications. The Seoul Capital Area concentrates firmware development talent for predictive state-of-health analytics.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing create captive demand for integrated conditioning logic within domestic battery assembly plants. BIS certification requirements for thermal management hardware are tightening as local cell production scales. Tamil Nadu and Gujarat host emerging electrode manufacturing corridors where conditioning system suppliers co-locate with cell fabricators.
Electric Vehicle Battery Conditioners Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidation pressure concentrates among battery cell manufacturers extending downstream into conditioning firmware, while discrete electronics suppliers defend niche positions in power semiconductor integration. Strategic archetypes span integrated cell-to-pack architects, standalone battery management system licensors, and power electronics component specialists. Capacity expansion and technology licensing dominate competitive moves as semiconductor allocation constraints harden procurement timelines for 800V platform qualification.
Within the integrated cell-to-pack tier, CATL and BYD exemplify vertical control over conditioning logic embedding, while LG Energy Solution occupies a position emphasizing algorithmic differentiation for cold-climate cycle life extension. Samsung SDI anchors the full-stack semiconductor control archetype for European OEM customers requiring gate-driver-to-firmware integration. These three players represent divergent strategic postures on hardware-software bundling and geographic market prioritization.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| BYD Company |
| Panasonic Corporation |
| SK On |
| Samsung SDI |
| CALB |
| GS Yuasa Corporation |
| Automotive Energy Supply Corporation |
| Others |
Supply & Pricing Matrix
Hamburg-Rotterdam logistics corridors carry the majority of cross-border battery conditioning hardware shipments, with freight cost volatility feeding directly into supplier pricing power and downstream tier differentiation across fleet procurement contracts.
Pricing Analysis
Cost-plus contracts indexed to silicon carbide wafer spot markets dominate procurement between German OEMs and power electronics suppliers. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-certified thermal runaway systems from GB/T 38031-compliant units and uncertified aftermarket alternatives. Pricing pressure stems from semiconductor allocation constraints tightening gate driver IC availability. Fleet operators exhibit highest price sensitivity, while premium passenger OEMs absorb certification premiums for embedded firmware licensing.
Supply Chain Analysis
Supplier-financing facilities extending payment terms to 180 days have become standard for Yangtze River Delta semiconductor fabricators serving European conditioner assemblers. Manufacturing concentrates in China, South Korea, and Germany, with silicon carbide substrates, gate driver ICs, and electrochemical sensors as critical inputs. Single-source vulnerability runs through Taiwan-based SiC wafer production. Distribution runs through Tier 1 battery system integrators co-located with OEM pack assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active balancing algorithm development combined with ISO 26262 functional safety competency represents the critical skill intersection where talent scarcity constrains expansion timelines for conditioning system vendors.
For Market Incumbents: Harden firmware licensing architectures against unbundling by semiconductor suppliers seeking direct OEM relationships. Deepen backward integration into gate driver IC design to secure allocation priority for 800V platform qualification. Capacity expansion in Bavaria's automotive cluster reinforces proximity to BMW and Volkswagen Group validation pipelines. For New Entrants and Emerging Players: Build out aftermarket service corridors for second-life stationary storage refurbishment under IEC 62619 standards, where incumbent cell manufacturers have not deployed conditioning expertise. India's PLI-linked battery assembly plants offer the most penetrable geography for integrated logic suppliers. Partnership models with Tamil Nadu electrode fabricators bypass direct OEM certification burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-integrated conditioning architects over standalone battery management system licensors. Long-term viability rests on controlling firmware update channels across multiple vehicle generations. Acquisition targets should demonstrate embedded predictive analytics capabilities. The signal to watch is NHTSA thermal runaway mandate enforcement timing as volume inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Vertical Integration | Captive wafer supply secures gate driver allocation for 800V platform ramp. |
| Predictive Analytics Licensing | Recurring firmware revenue detaches margin capture from hardware shipment cycles. |
| Cell-to-Pack Architecture Partnership | Embedded conditioning logic eliminates discrete module housing cost structures. |
| Second-Life Refurbishment Service | IEC 62619-compliant systems open aftermarket revenue from retired EV packs. |
| India PLI Manufacturing Co-location | Tamil Nadu and Gujarat electrode corridors create captive domestic demand anchors. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and semiconductor supplier production data anchors the qualitative findings in this study. Primary interviews with battery system architects, thermal management specialists, Tier 1 procurement directors, and fleet operations managers combine with secondary validation from NHTSA regulatory filings, MIIT GB standard documentation, EU Battery Regulation impact assessments, and IHS Markit vehicle production databases. Bottom-up unit shipment estimates and top-down OEM platform content analysis provide triangulation.
Calibration against historical adoption curves for 400V-to-800V architecture transitions informs the projection framework across the analysis window. Segmentation dimensions include product integration tier, balancing technology type, end-user contract structure, vehicle duty cycle intensity, and regional regulatory cluster. CAGRs derive from fitted diffusion models incorporating silicon carbide penetration rates and thermal mandate compliance deadlines. Forecast inputs include fleet electrification procurement schedules and cell-to-pack platform shipment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration by battery cell manufacturers into semiconductor fabrication would shift outcomes. Forecasts reflect documented assumptions about certification timeline adherence and semiconductor allocation continuity. Macroeconomic contraction, tariff escalation on power electronics, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Auto Storage Battery Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
France Electric Vehicle Battery Manufacturing Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
South Korea Electric Vehicle Battery Market