
 Europe Electric Vehicle Battery Manufacturing Market | 2026-2036
Europe Electric Vehicle Battery Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Battery Manufacturing Market Insights
A shift from Asian single-source dependency toward multi-source regional supply is decoupling procurement risk from production scale. Northvolt anchors its strategy on vertical integration into raw material refining and recycling within the Nordic region. Volkswagen PowerCo leverages captive demand from the Volkswagen Group's EV ramp-up to sustain capacity commitments across its Salzgitter and Valencia sites. Samsung SDI competes through specialized high-nickel prismatic cell designs tailored to German premium OEM specifications.
Europe Electric Vehicle Battery Manufacturing encompasses the industrial production of electrochemical energy storage systems, typically lithium-ion cells with nickel-cobalt-manganese or lithium-iron-phosphate cathode formulations, assembled into modules and packs for traction applications in road vehicles. Cell production requires precision coating, drying, calendering, and formation cycling to achieve energy densities exceeding 250 Wh/kg and cycle lives above 1,000 charge events. Lithium-ion chemistry dominates installed capacity due to mature supply chains and continuous cost reduction, while solid-state technology occupies the premium development pipeline where higher energy density and intrinsic safety justify pre-commercial investment. Pack assembly concentrates margin pools through thermal management integration and vehicle-platform-specific form factors, particularly for passenger vehicles where OEMs demand customized housing and battery management system calibration.
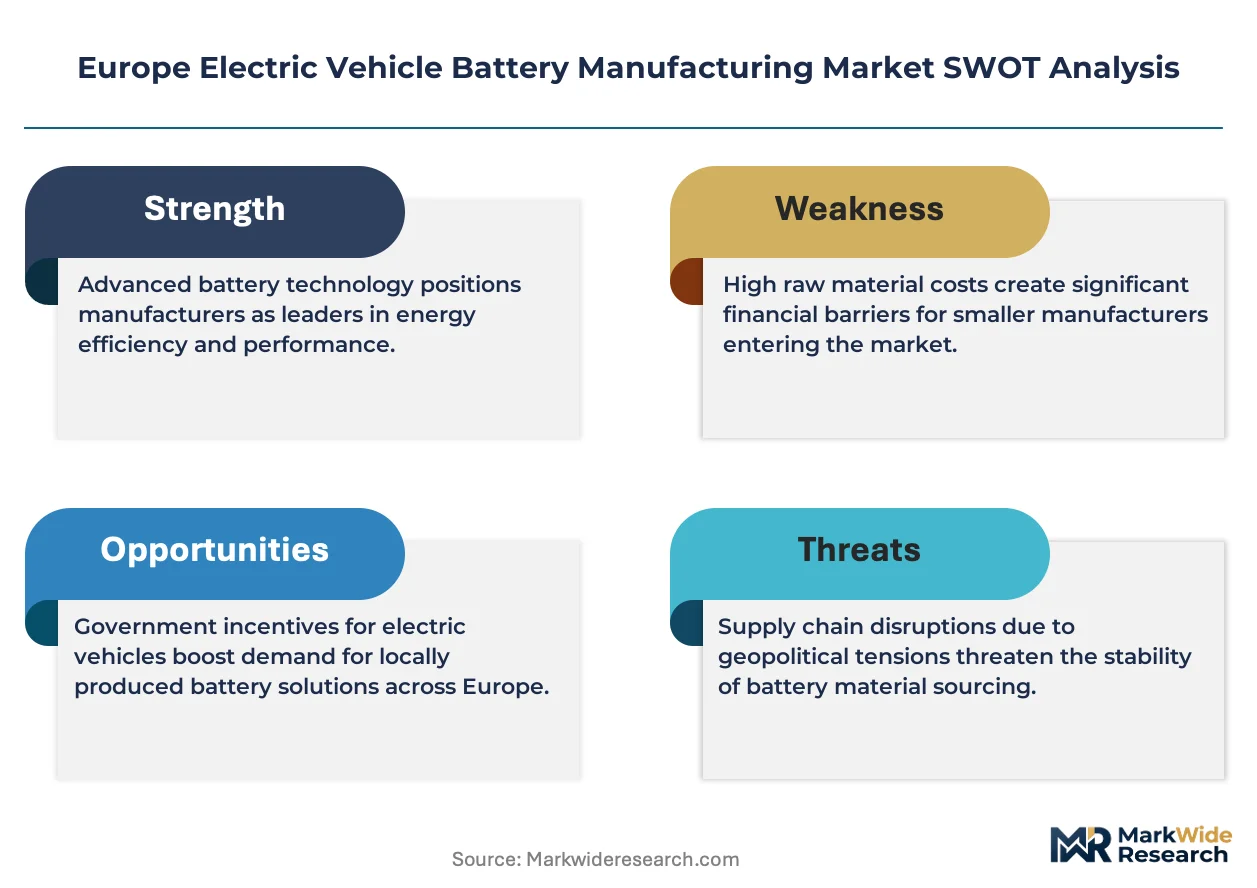
The EU Battery Regulation and ECHA REACH compliance framework are reshaping material sourcing by imposing due diligence on cobalt, lithium, and graphite supply chains alongside mandatory recycling efficiency targets. CE marking under the EU Green Deal's industrial policy umbrella restricts market access for imports failing carbon footprint thresholds at the cell level. The F-Gas Regulation indirectly influences thermal management system design by phasing down hydrofluorocarbon refrigerants used in battery cooling loops. Stakeholders must monitor how delegated acts under the Battery Regulation define performance classes and second-life criteria, as these will determine which manufacturing investments qualify for EU-level funding and offtake guarantees.
Market Dynamics
The EU Battery Regulation's carbon footprint declaration mandates are forcing cell manufacturers to reconfigure supply chains around verified low-carbon material sourcing before market access thresholds tighten. This structural pressure compounds with OEM platform standardization timelines, compressing the window for factory qualification.
Growth Catalysts
- EU Green Deal industrial policy:CE marking requirements under the Green Deal's sustainable battery framework are channeling public finance toward gigafactory construction in Germany, Sweden, and Hungary. National governments are matching EU-level funding to secure anchor manufacturing investments.
- Passenger EV platform ramp-ups:Dedicated battery-electric vehicle architectures from German and French OEMs are generating multi-year offtake commitments that de-risk capital deployment for cell producers. Platform-specific form factors lock in supplier relationships through design-in cycles.
- Lithium-iron-phosphate chemistry expansion:LFP cathode formulations are capturing share in entry-level and fleet vehicle segments where cost-per-kilowatt-hour dominates range requirements. Chinese process technology licensing is accelerating European LFP qualification timelines.
Market Restraints
- Refined lithium supply concentration:Battery-grade lithium hydroxide processing remains concentrated in Chinese state-linked refiners, exposing European cell producers to input cost volatility and geopolitical supply interruptions. Alternative refining capacity in Portugal and Germany will not reach scale before 2027.
- Skilled electrochemical engineering scarcity:Formation cycling and dry-room operations require specialized technicians whose training pipelines lag factory construction schedules. German technical universities are expanding battery-specific curricula but graduate throughput remains insufficient.
- High-nickel cathode technical limitations:Nickel-rich NMC811 and beyond formulations face thermal runaway risks that demand more complex battery management systems and thermal management hardware, adding cost and mass to pack designs.
Strategic Opportunities
- Poland and Hungary manufacturing corridors:Central European locations offer lower labor costs than Germany while maintaining EU regulatory alignment and proximity to German OEM assembly plants. Government incentive packages in these markets are attracting module and pack assembly investments.
- Second-life stationary storage applications:Retired automotive battery packs with degraded capacity retain value for grid-scale energy storage, creating circular revenue streams. The EU Battery Regulation's second-life criteria delegated acts will define which manufacturing designs qualify for extended producer responsibility credits.
- Solid-state electrolyte convergence:Sulfide and oxide solid-state technologies are converging with silicon-anode architectures to enable energy densities above 400 Wh/kg. Pre-commercial investments by German premium OEMs are funding pilot lines for 2028-2030 production windows.
Industry Challenges
- Formation cycling capex intensity:Cell formation and aging equipment represents 15-20% of factory capital expenditure, with European equipment vendors unable to match Asian suppliers on delivery timelines or cost. This bottleneck extends commissioning schedules for new production lines.
- ECHA REACH compliance timeline compression:Registration, evaluation, and authorization of novel electrolyte additives and binders requires 18-24 month dossier preparation, delaying new chemistry introductions. The authorization process for substituted substances creates uncertainty in formulation roadmaps.
- Pack-to-platform integration complexity:Cell-to-pack architectures eliminate module housings but require simultaneous engineering with vehicle structural elements, compressing development cycles and amplifying warranty exposure for thermal management failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Battery Manufacturing Market |
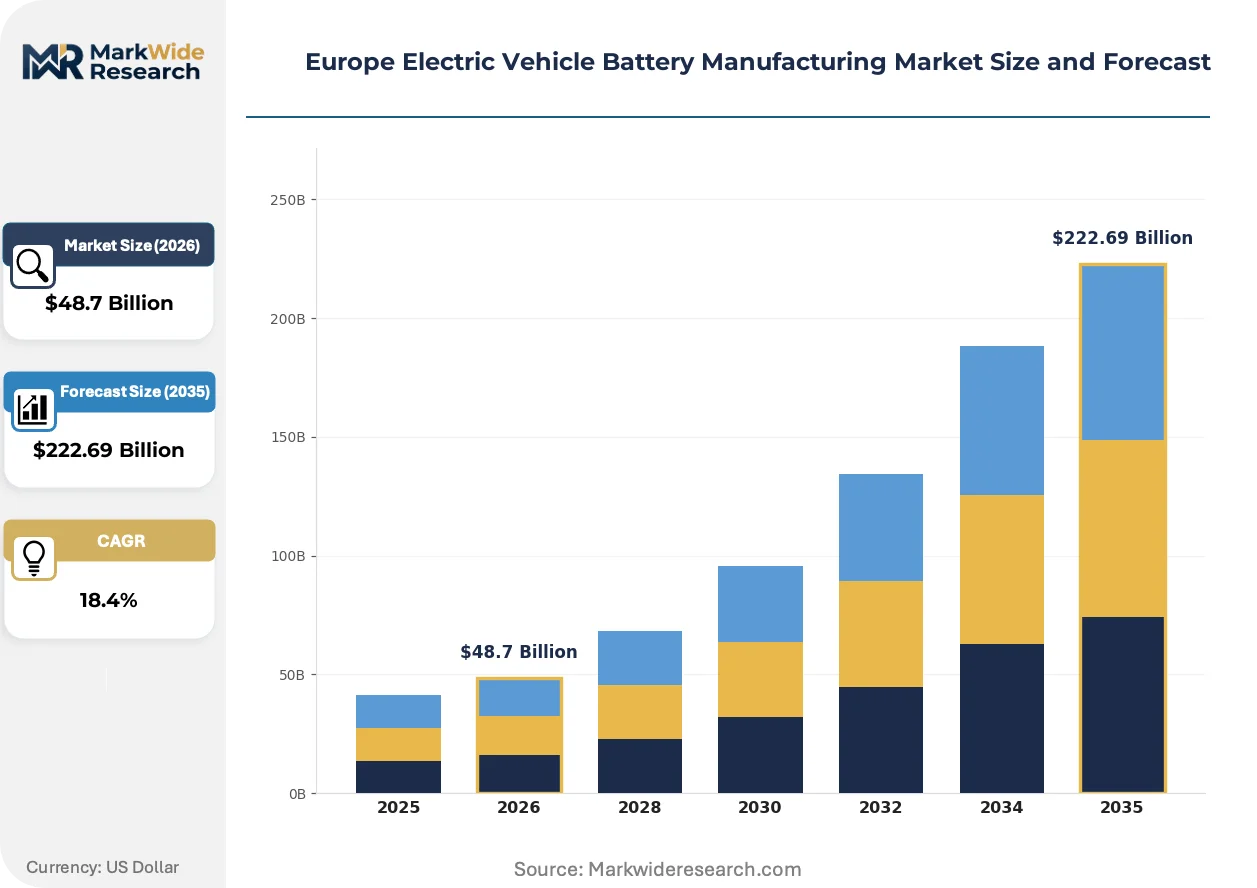
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $222.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Solid State, Lead-acid Manufacturing Technology: Cell Production, Pack Assembly, Recycling, Quality Testing End Use: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Industrial Applications Component: Electrodes, Electrolyte, Separators, BMS |
| Companies Covered | Volkswagen PowerCo GmbH, Northvolt, LG Energy Solution Ltd., Contemporary Amperex Technology Co., Ltd. (CATL), Samsung SDI Co., Ltd., SK On Co., Ltd., BYD Company Ltd., Saft Groupe SA, ACC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Battery Manufacturing Market Trends and Innovations
Cell manufacturing process innovation is accelerating as producers compete to reduce energy consumption per kilowatt-hour while scaling output. Equipment suppliers and chemical process engineers are converging on dry electrode coating and advanced formation protocols.
Dry electrode coating technology is integrating solvent-free binder application into European pilot lines, eliminating energy-intensive drying ovens and toxic NMP solvent recovery systems. BMW and Northvolt are qualifying dry-coated anodes for 2026 production start. The process is integrating into cost roadmaps by reducing factory footprint and utility consumption by 30% versus conventional wet coating.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is forcing thermal management system redesigns toward CO2-based cooling loops and immersion cooling architectures. Pack assemblers are reconfiguring housing designs to accommodate higher-pressure refrigerant circuits. German OEMs are most affected, with 2025 model-year platforms requiring full thermal system revalidation.
Fleet operators and energy utilities are consolidating procurement through long-term service contracts that bundle battery provision, charging infrastructure, and residual value guarantees. This model is displacing unit-based cell purchasing in commercial vehicle segments. The shift is most visible in Nordic markets where municipal bus electrification programs demand total-cost-of-ownership contracting.
Europe Electric Vehicle Battery Manufacturing Market Segmentation
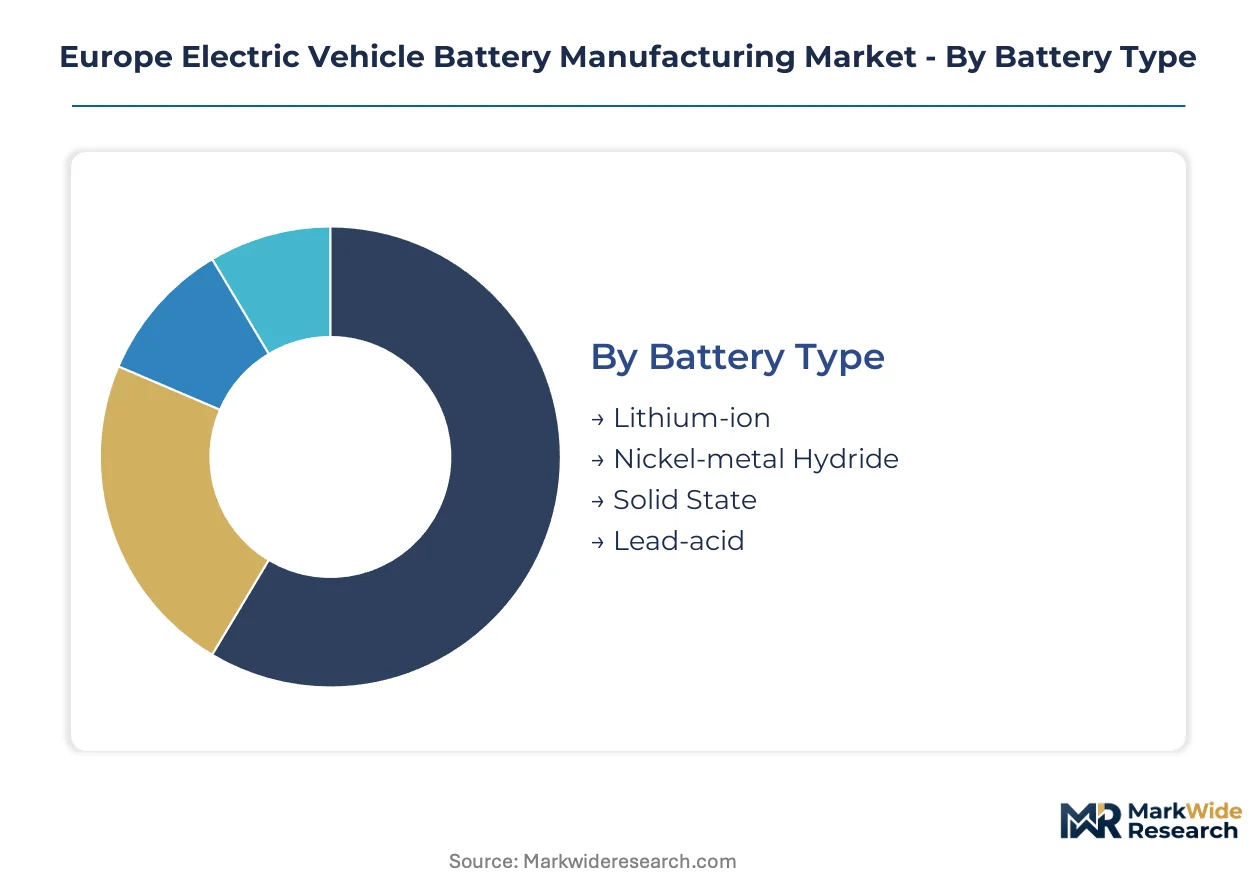
Segmentation in European EV battery manufacturing reveals how chemistry choices, production stages, and end-use requirements allocate capital across incompatible equipment sets and regulatory compliance pathways. Each dimension carries distinct margin structures and qualification timelines that determine supplier positioning.
Battery Type:
Lithium-ion dominates installed capacity while solid-state commands development premiums, creating a volume-versus-performance split across European factory investments.
- Lithium-ion:Nickel-cobalt-manganese and lithium-iron-phosphate cathode formulations constitute the overwhelming share of European cell output. German OEM platform ramp-ups are concentrating procurement of NMC cells for premium passenger vehicles, while LFP chemistry captures fleet vehicle tenders where cost-per-kilowatt-hour outweighs energy density requirements.
- Solid State:Sulfide and oxide electrolyte architectures promise energy densities exceeding 400 Wh/kg with intrinsic thermal stability. German premium OEM pilot lines are funding pre-commercial investments targeting production windows toward the end of this decade, constrained by manufacturing scalability challenges.
- Nickel-metal Hydride:Legacy hybrid electric vehicle applications retain niche demand from Toyota and Honda European assembly plants transitioning production.
- Lead-acid:Auxiliary power units and low-speed electric vehicles in Southern and Eastern European markets sustain residual manufacturing.
Mature deployment sits with lithium-ion across German and Swedish gigafactories. Newer deployment is concentrated in solid-state pilot investments.
Manufacturing Technology:
Capital allocation skews heavily toward cell production equipment, though pack assembly captures margin through thermal management integration and platform-specific engineering.
- Cell Production:Precision coating, drying, calendering, and formation cycling equipment constitutes the core capital intensity of European battery manufacturing. Formation cycling alone represents 15-20% of factory expenditure, with Asian equipment vendors currently outpacing European alternatives on delivery timelines.
- Pack Assembly:Module and pack integration concentrates margin pools through battery management system calibration, thermal management hardware, and vehicle-platform-specific form factors. German OEMs are driving cell-to-pack architectures that eliminate module housings while demanding simultaneous structural engineering.
- Recycling:Hydrometallurgical and pyrometallurgical recovery operations are scaling in response to EU Battery Regulation mandates for recycled content quotas.
- Quality Testing:Electrochemical impedance spectroscopy and thermal runaway verification protocols extend commissioning schedules but reduce warranty exposure.
Capital deployment concentrates in cell production. Margin expansion is climbing the fastest in pack assembly.
End Use:
Passenger vehicle platforms generate volume commitments that de-risk factory investments, while commercial vehicle segments are shifting toward service-based procurement models.
- Passenger Vehicles:Dedicated battery-electric architectures from Volkswagen, BMW, Mercedes-Benz, and Stellantis are generating multi-year offtake agreements that anchor capacity decisions at Northvolt and Volkswagen PowerCo sites. Platform-specific form factors lock suppliers through design-in cycles.
- Commercial Vehicles:Municipal bus electrification programs across Nordic markets and German cities are consolidating procurement through total-cost-of-ownership contracts bundling battery provision, charging infrastructure, and residual value guarantees.
- Two-wheelers:Last-mile delivery electrification in Paris, Amsterdam, and Milan is driving demand for standardized swappable battery formats.
- Industrial Applications:Forklift and material handling equipment manufacturers in Germany and France are converting lithium-ion from niche to standard configuration.
Volume concentration sits with passenger vehicles. Contracting innovation is expanding most quickly in commercial vehicles.
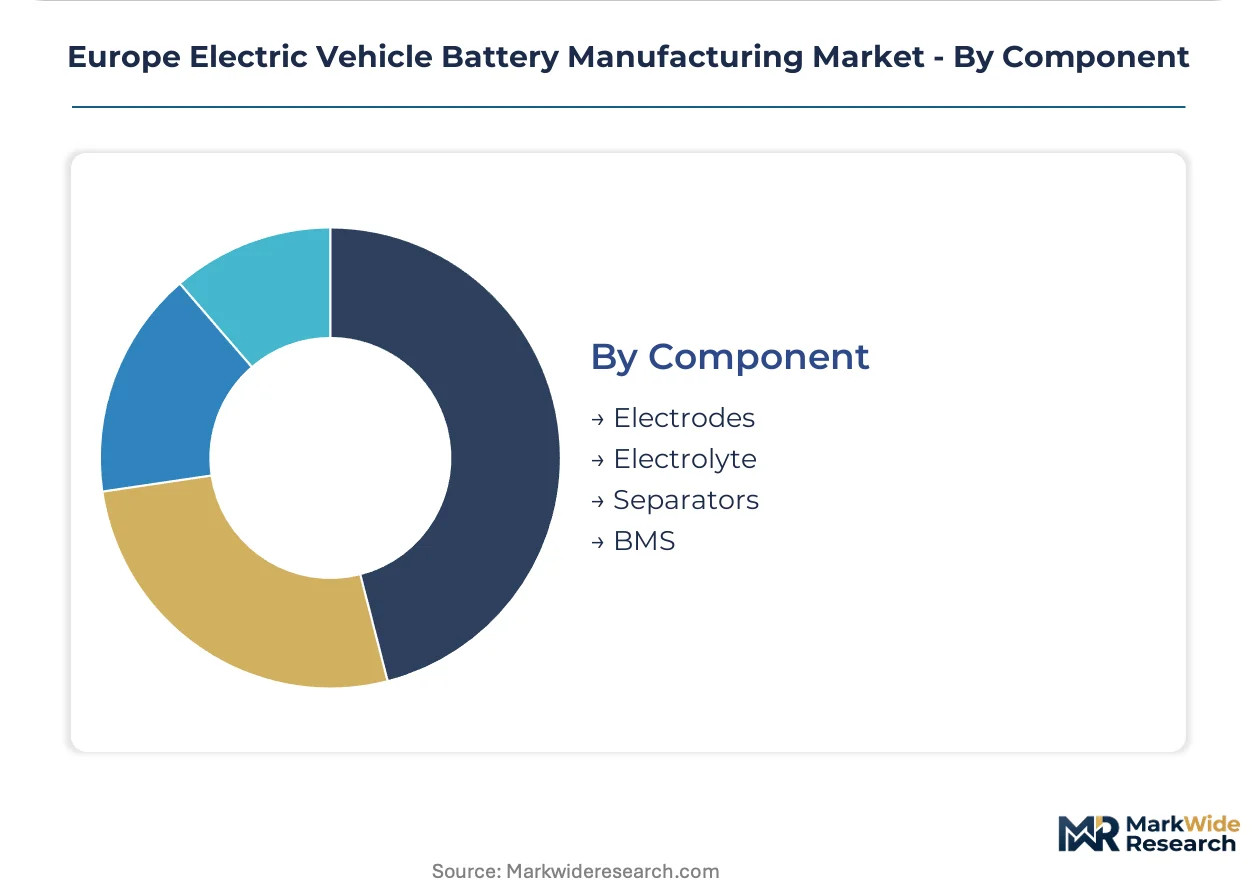
Component:
Electrode manufacturing determines cell performance while battery management systems differentiate pack-level value capture.
- Electrodes:Cathode active material coating and anode graphite or silicon composite fabrication define energy density and cycle life. Dry electrode coating pilot lines at BMW and Northvolt are eliminating NMP solvent recovery systems.
- BMS:Battery management system hardware and software calibration for thermal runaway prevention and state-of-charge estimation commands premium pricing in German premium OEM supply chains.
- Electrolyte:Lithium salt and solvent formulations face ECHA REACH authorization timelines that delay novel additive introductions.
- Separators:Ceramic-coated polyolefin membranes are standardizing across European cell producers to meet safety requirements.
Process maturity sits with electrodes. Technology differentiation is gaining share fastest in BMS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Portugal's northern belt anchor feedstock security for Iberian cell production, while Nordic graphite reserves and Polish copper infrastructure shape electrode supply chains across the continent.
Germany
Volkswagen Group's dedicated EV architectures and Mercedes-Benz platform ramp-ups concentrate demand in Lower Saxony and Baden-Württemberg. The EU Battery Regulation's carbon footprint mandates drive Salzgitter and Valencia site qualifications. North Rhine-Westphalia hosts chemical industry clusters supplying electrolyte precursors to adjacent cell factories.
Sweden
Nordic renewable energy pricing and timber industry byproducts attract energy-intensive cathode active material processing. Skellefteå anchors Europe's first vertically integrated gigafactory with on-site recycling and refining operations. Västerbotten County's mining heritage supplies skilled electrochemical technicians for formation cycling operations.
Hungary
Proximity to German OEM assembly plants in Bavaria and Lower Saxony positions Debrecen and Göd as module and pack assembly corridors. Government incentive packages under the EU Green Deal's industrial policy match national funding for gigafactory construction. The Central European location offers labor cost advantages while maintaining CE marking regulatory alignment.
Poland
Copper smelting infrastructure in Lower Silesia feeds current collector foil production for regional cell manufacturers. Wrocław and Poznań manufacturing corridors attract pack assembly investments serving Czech and Slovak automotive clusters. Polish technical universities are expanding battery-specific curricula to address skilled technician shortages.
France
Stellantis platform standardization and Renault's EV ramp-up generate offtake commitments for northern French cell production sites. The EU Battery Regulation's recycled content quotas drive Dunkirk hydrometallurgical recycling investments. Auvergne-Rhône-Alpes hosts materials science research clusters supporting solid-state electrolyte development.
Europe Electric Vehicle Battery Manufacturing Market Competitive Landscape
Global majors compete with regional champions across chemistry specialization and supply chain integration depth. The vendor base concentrates around three tiers: Asian scale leaders with European module assembly, European vertically integrated challengers with captive recycling, and automotive OEM captive producers with guaranteed offtake. Strategic moves center on backward integration into raw material refining and technology licensing partnerships for LFP process transfer.
Within the European challenger tier, Volkswagen PowerCo GmbH and Northvolt exemplify divergent integration strategies. Volkswagen PowerCo leverages captive demand from the Volkswagen Group's platform ramp-ups to sustain capacity commitments across German and Iberian sites. Northvolt anchors its positioning on upstream control over Nordic raw material refining and closed-loop recycling infrastructure. LG Energy Solution Ltd. and Samsung SDI Co., Ltd. represent the Asian scale leader archetype, competing through specialized high-nickel prismatic designs and established European module assembly footprints.
| Leading Market Players |
|---|
| Volkswagen PowerCo GmbH |
| Northvolt |
| LG Energy Solution Ltd. |
| Contemporary Amperex Technology Co., Ltd. (CATL) |
| Samsung SDI Co., Ltd. |
| SK On Co., Ltd. |
| BYD Company Ltd. |
| Saft Groupe SA |
| ACC |
| Others |
Pricing and Supply Chain Analysis
OEM platform standardization timelines are compressing supplier qualification windows and forcing cell manufacturers to absorb upfront certification costs that feed into long-term contract pricing structures. This demand-side pressure concentrates pricing power with German and French automakers while squeezing margins for producers lacking captive offtake agreements.
Pricing Analysis
Warranty bundling separates premium cell suppliers from commodity competitors, with German OEMs demanding 8-year performance guarantees that inflate upfront unit costs but reduce lifetime ownership risk. Three-tier pricing structure across premium NMC811, standard NMC622, and economy LFP chemistries reflects energy density and thermal management complexity differentials. Cost compression in entry-level LFP segments is intensifying because Chinese process licensors are flooding European qualification pipelines. Fleet operators exhibit highest price sensitivity through total-cost-of-ownership procurement, while premium passenger vehicle OEMs prioritize energy density over per-kilowatt-hour economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese state-linked refiners controlling battery-grade lithium hydroxide processing, exposing European cell producers to input cost volatility and geopolitical interruption. Raw material dependencies rest on Chilean lithium brine, Indonesian nickel laterite, and Chinese graphite spheroidization capacity. Supply chain risk centers on tariff exposure from pending EU carbon border adjustments on imported cathode active materials. Distribution runs through just-in-time module delivery contracts from Hungarian and Polish assembly corridors to German OEM plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Battery Regulation compliance deadlines are forcing a consolidation play as capital-intensive carbon footprint verification eliminates sub-gigawatt scale competitors. The window for weaker players to achieve factory qualification is narrowing against OEM platform ramp-up timelines.
For Market Incumbents: To counter Asian equipment vendor delivery advantages, accelerate in-house formation cycling capability through Portuguese and German refining partnerships. Prioritize CE marking pre-certification for Salzgitter and Skellefteå sites to lock in Green Deal funding eligibility before delegated acts tighten thresholds. For New Entrants and Emerging Players: Launch via Polish and Hungarian module assembly corridors serving Czech and Slovak automotive clusters where labor costs undercut German sites. Target second-life stationary storage applications in Nordic markets where EU Battery Regulation credits reduce effective manufacturing cost bases. White-space exists in dry electrode coating equipment supply where European vendors lag Asian competitors on delivery timelines. For Investors and Strategic Acquirers: The window for entry favors vertically integrated challengers with captive recycling infrastructure and Nordic renewable energy access. Long-term viability hinges on upstream lithium refining positions in Portugal and Germany that decouple from Chinese hydroxide concentration. Watch for EU delegated acts defining second-life criteria as the inflection signal determining which manufacturing designs qualify for extended producer responsibility credits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Portuguese and German refining capacity reduces dependency on Chinese state-linked hydroxide processors. |
| Dry Electrode Coating Adoption | BMW and Northvolt pilot lines eliminate NMP solvent recovery systems and reduce factory utility consumption. |
| Second-Life Criteria Qualification | EU Battery Regulation delegated acts will determine manufacturing designs eligible for circular revenue streams. |
| CO2-Based Thermal System Redesign | F-Gas Regulation phase-down forces German OEMs to revalidate 2025 model-year platforms with higher-pressure refrigerant circuits. |
| Central European Pack Assembly Expansion | Polish and Hungarian corridors capture margin pools through proximity to Czech and Slovak automotive clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with cell production engineers, OEM platform procurement leads, ECHA regulatory affairs specialists, and Nordic recycling facility operators combined with secondary validation from EU Battery Regulation delegated act drafts, REACH authorization dossiers, and national gigafactory incentive disclosures. Bottom-up capacity build-up by site and top-down OEM offtake commitment triangulation verified volume estimates.
Production volume, chemistry mix, and end-use segmentation reconciliation across German, Swedish, Hungarian, Polish, and French manufacturing clusters shaped the analytical framework over the projection horizon. Vehicle class, propulsion architecture, and cathode chemistry tier dimensions were modeled with CAGRs derived from OEM platform ramp-up schedules and Green Deal funding allocation trajectories. Lithium-iron-phosphate process licensing velocity and solid-state pilot line conversion rates served as chemistry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for sulfide solid-state electrolyte commercialization would alter the outlook. Forecasts reflect assumptions on EU delegated act timing, Chinese export license continuity, and Nordic renewable energy pricing stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
European EV Battery Systems Market
EV Batteries
North America Electric Vehicle Battery Materials Market