
 South America Hybrid Electric Vehicle Battery Market | 2026-2036
South America Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South America Hybrid Electric Vehicle Battery Market Insights
Dealer and direct-to-OEM supply channels for South America Hybrid Electric Vehicle Battery systems is fragmenting as regional assemblers diversify procurement beyond legacy distributors. Panasonic Holdings Corporation anchors Japanese technology transfer into Brazilian manufacturing complexes. BYD Company Ltd dominates lithium-iron-phosphate supply relationships with Latin American bus builders. LG Chem Ltd navigates localized cell assembly partnerships to bypass import tariff layers.
South America Hybrid Electric Vehicle Battery systems store electrical energy in electrochemical cells with nominal voltages typically ranging from 200 to 400 volts, combining lithium-ion or nickel metal hydride chemistries with battery management systems that monitor state-of-charge and thermal equilibrium to enable torque assist and regenerative braking in hybrid drivetrains. Lithium-ion chemistry occupies the dominant margin pool due to energy density advantages in passenger vehicle applications, while nickel metal hydride sustains cost-competitive positioning in commercial bus and fleet segments where cycle life outweighs gravimetric efficiency. Battery management system technology leads R&D allocation as OEMs demand predictive diagnostics and cell-balancing algorithms that extend pack longevity across high-temperature South American operating environments.
Brazil's Proconve P8 standards and ANFAVEA certification protocols shape product entry requirements, while Argentina's IRAM safety markings and INMETRO efficiency labels govern cross-border component acceptance. Chile's Ministry of Energy electrification mandates and Peru's SENCICO technical standards further fragment compliance obligations across Andean trade corridors. Stakeholders must monitor regulatory divergence between Mercosur harmonization talks and unilateral national efficiency programs that alter local content thresholds.
Market Dynamics
Brazil's Proconve P8 emission standards are compressing OEM development cycles and forcing powertrain electrification decisions before full EV infrastructure maturity, creating hybrid-specific battery demand acceleration distinct from global EV trajectories.
Growth Catalysts
- Municipal Bus Fleet Electrification:Transit authorities in São Paulo, Rio de Janeiro, and Belo Horizonte are mandating hybrid bus procurement quotas in public tenders, creating concentrated demand pull for nickel metal hydride and lithium-iron-phosphate systems.
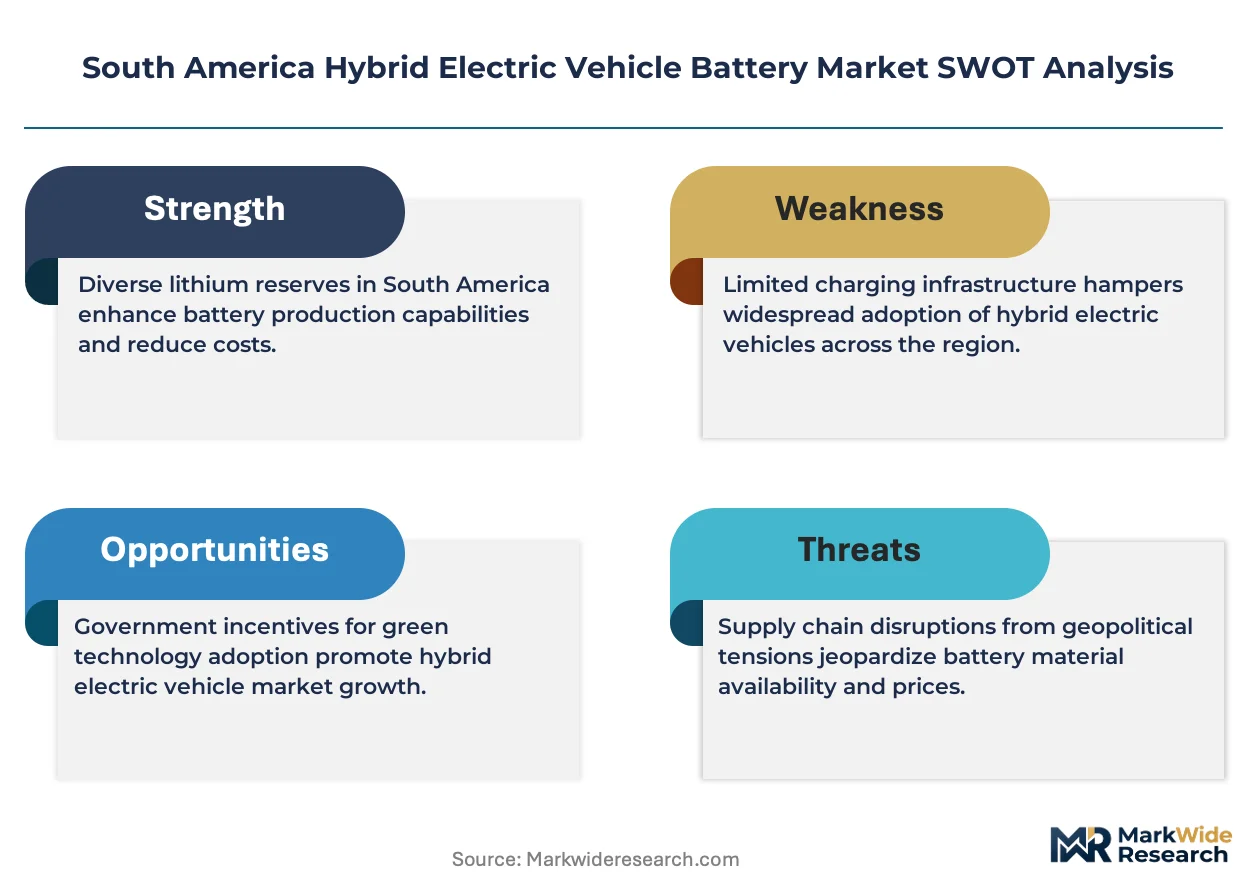
- Proconve P8 CO2 Limits:Brazil's tightened emission standards force OEMs to deploy electrified powertrains across passenger and commercial segments, expanding addressable battery system volumes beyond pure-electric mandates.
- São Paulo State Incentives:Congestion charging exemptions and state-level tax abatements for hybrid vehicles concentrate consumer adoption in Brazil's wealthiest automotive market, generating procurement scale for localized battery assembly.
Market Restraints
- Lithium Carbonate Price Volatility:Input cost fluctuations for cathode materials compress margin pools for pack assemblers unable to pass through pricing to municipal procurement contracts with fixed-term structures.
- Import Tariff Layering:Mercosur's external tariff walls on finished cells force manufacturers to absorb localization costs or cede price competitiveness to regional trading bloc suppliers with established Brazilian assembly presence.
- Nickel Metal Hydride Energy Density Ceiling:Gravimetric efficiency limitations constrain hybrid range extension in passenger applications, restricting the technology to commercial bus segments where cycle life economics dominate.
Strategic Opportunities
- Argentina's Untapped Fleet Segment:Buenos Aires and Córdoba municipal transit authorities lack established hybrid bus suppliers, creating first-mover positioning for Brazilian pack assemblers with cross-border certification capabilities.
- Chilean Mining Electrification Mandates:The Ministry of Energy's underground vehicle electrification requirements open hybrid powertrain applications for heavy-duty mining trucks operating at high-altitude thermal stress conditions.
- Battery Management System Software Licensing:Predictive diagnostics and cell-balancing algorithm exports to Andean assemblers represent recurring revenue streams decoupled from hardware margin compression.
Industry Challenges
- Thermal Engineering Talent Scarcity:Pack design engineers with high-temperature operating environment experience remain concentrated in São Paulo's automotive corridor, constraining assembly expansion to secondary Brazilian states.
- INMETRO Certification Timelines:Efficiency label approval processes for new chemistries extend product launch windows, allowing uncertified competitors to capture municipal tender awards during validation gaps.
- Legacy Bus Fleet Integration Complexity:Retrofit hybrid powertrain compatibility with existing chassis architectures from Marcopolo and Caio Induscar requires bespoke battery form factors that resist platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Hybrid Electric Vehicle Battery Market |
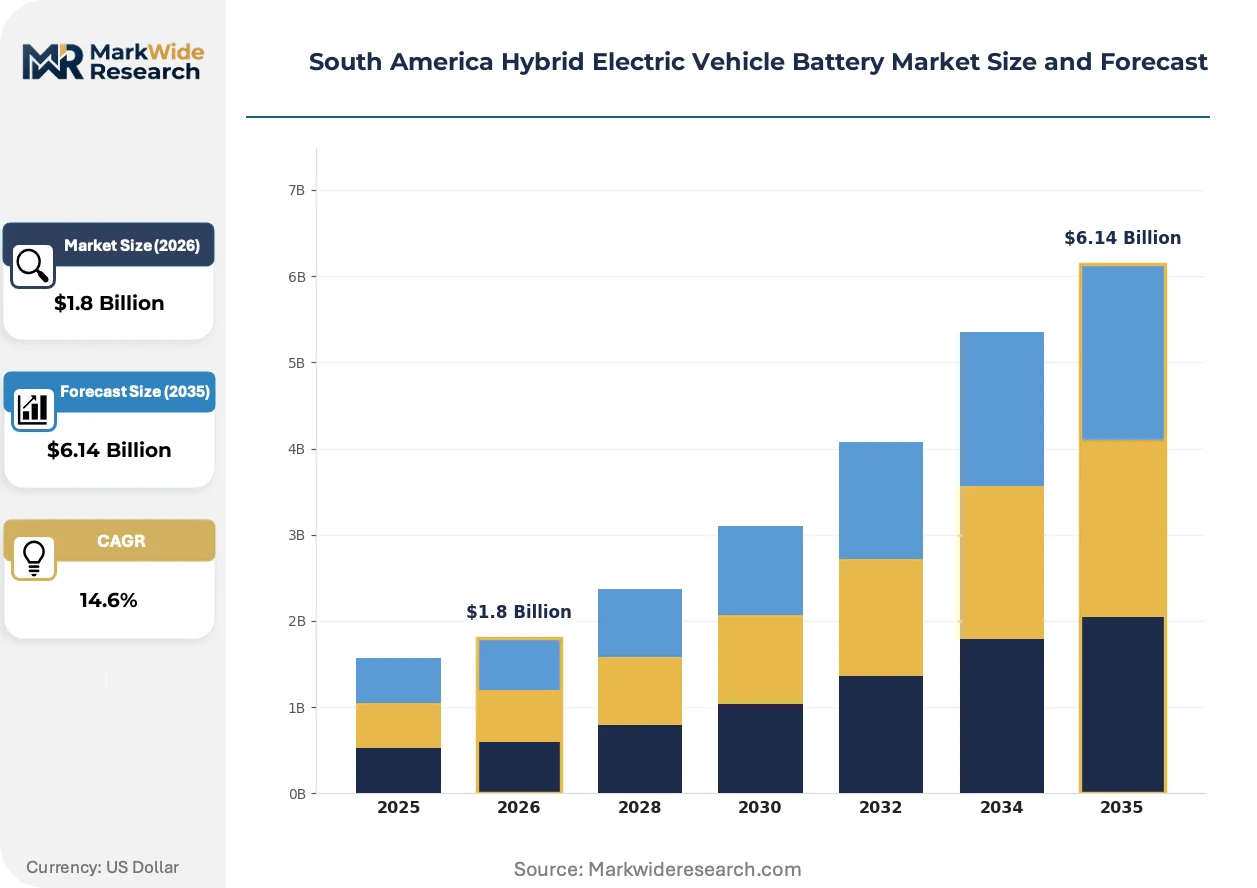
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel Metal Hydride, Lead Acid, Solid-State End User: OEMs, Aftermarket Providers, Fleet Operators, Government Agencies Technology: Battery Management System, Thermal Management, Regenerative Braking, Charging Solutions Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Buses |
| Companies Covered | Panasonic Holdings Corporation, Clarios, Contemporary Amperex Technology Co. Limited, BYD Company Ltd, VARTA AG, LG Chem Ltd, SK Innovation Co. Ltd, EnerSys, Exide Industries, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell chemistry evolution and thermal management software are converging to redefine pack architecture decisions, with Brazilian operating conditions accelerating adoption trajectories distinct from temperate-climate markets.
Solid-state electrolyte research programs at Brazilian federal technology institutes are rendering obsolete conventional liquid-electrolyte thermal runaway mitigation hardware, compressing pack volume and cooling system mass. OEM pilot programs with São Paulo-based engineering consortiums target 2027 validation for tropical-climate solid-state prototypes, with bus fleet operators prioritizing the elimination of fire-suppression system maintenance costs.
ANFAVEA certification protocols now mandate predictive battery health monitoring as a condition for Proconve P8 compliance, forcing pack suppliers to deploy cloud-connected battery management systems. The regulation compresses aftermarket service revenue for independent repair networks while concentrating diagnostic data flows within OEM-controlled platforms, with passenger vehicle segments adapting fastest due to telematics integration requirements.
Fleet procurement committees are unbundling battery pack purchases from complete bus contracts, establishing direct supply relationships with cell assemblers that bypass legacy distributor markups. São Paulo municipal transit authorities pioneered this model in 2024, with Rio de Janeiro and Belo Horizonte tender documents now explicitly permitting dual-source contracting for powertrain and energy storage subsystems.
South America Hybrid Electric Vehicle Battery Market Segmentation
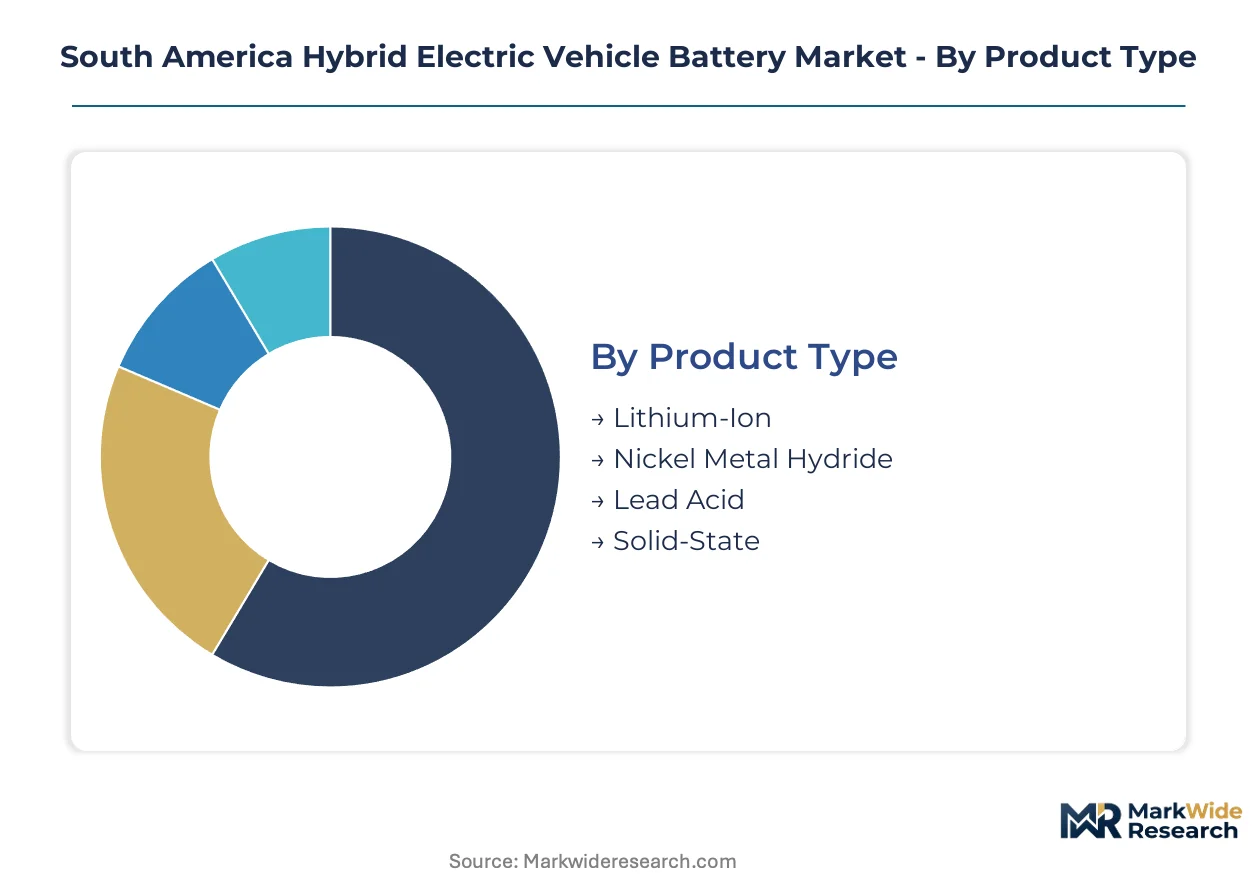
Segmentation of the South America Hybrid Electric Vehicle Battery Market reveals how after-sales-service intensity varies dramatically across chemistry types and customer channels. Service attachment rates for battery management system diagnostics and thermal recalibration differ by segment, reshaping margin structures for pack assemblers.
Product Type:
After-sales-service intensity escalates with energy density and thermal sensitivity, creating divergent service revenue profiles across electrochemical platforms.
- Lithium-Ion:Lithium-ion cells utilize layered oxide cathodes and graphite anodes with nominal voltages between 300-400V, delivering superior gravimetric efficiency for passenger hybrid applications. São Paulo state fleet procurement concentrates demand here, though Proconve P8 validation timelines compress aftermarket service windows before warranty expiration.
- Nickel Metal Hydride:Nickel metal hydride chemistry employs rare-earth alloy hydrides with aqueous potassium hydroxide electrolyte, prioritizing cycle life over energy density. Brazilian municipal bus tenders in Rio de Janeiro and Belo Horizonte favor this technology for its tolerance of high-temperature operating environments without active liquid cooling systems.
- Lead Acid:Lead acid systems serve auxiliary power unit functions in commercial truck mild-hybrid architectures across Mercosur trade corridors.
- Solid-State:Solid-state prototypes target elimination of thermal runaway mitigation hardware for tropical-climate validation by São Paulo engineering consortiums.
By volume, Nickel Metal Hydride leads. By growth pace, Solid-State is ahead.
End User:
Customer concentration shapes procurement contract structures, with municipal tender specifications dictating divergent warranty and service terms.
- OEMs:Original equipment manufacturers integrate battery packs at assembly plants in São Paulo's ABC automotive corridor, demanding predictive diagnostics integration and cloud-connected telematics platforms. ANFAVEA certification protocols mandate embedded battery health monitoring as a condition for Proconve P8 compliance, forcing pack suppliers to embed diagnostic hardware during manufacturing.
- Fleet Operators:Fleet procurement committees in São Paulo, Rio de Janeiro, and Belo Horizonte unbundle battery purchases from complete bus contracts, establishing direct supply relationships that bypass legacy distributor markups and capture service revenue internally.
- Aftermarket Providers:Independent repair networks face compressed revenue as OEM-controlled diagnostic data flows concentrate predictive maintenance within manufacturer platforms.
- Government Agencies:Municipal transit authorities issue hybrid bus procurement quotas with fixed-term pricing structures that resist lithium carbonate cost pass-through.
By contract value, OEMs dominate. By procurement innovation, Fleet Operators are expanding most quickly.
Technology:
Margin pools concentrate in software-defined functions that extend pack longevity across high-temperature South American operating environments.
- Battery Management System:Battery management systems monitor state-of-charge and cell balancing through predictive algorithms, with ANFAVEA protocols now mandating cloud-connected health monitoring for Proconve P8 compliance. São Paulo-based engineering talent scarcity constrains algorithm development for Andean assemblers.
- Thermal Management:Active liquid cooling and phase-change material systems address ambient temperature extremes in Brazil's interior states and high-altitude Chilean mining operations.
- Regenerative Braking:Kinetic energy recovery systems integrate with friction brake blending algorithms for bus stop-and-go duty cycles.
- Charging Solutions:Opportunity charging infrastructure for hybrid bus depots requires compatibility with existing electrical distribution networks in Argentine municipal transit authorities.
By R&D allocation, Battery Management System leads. By operational criticality, Thermal Management is climbing the fastest.
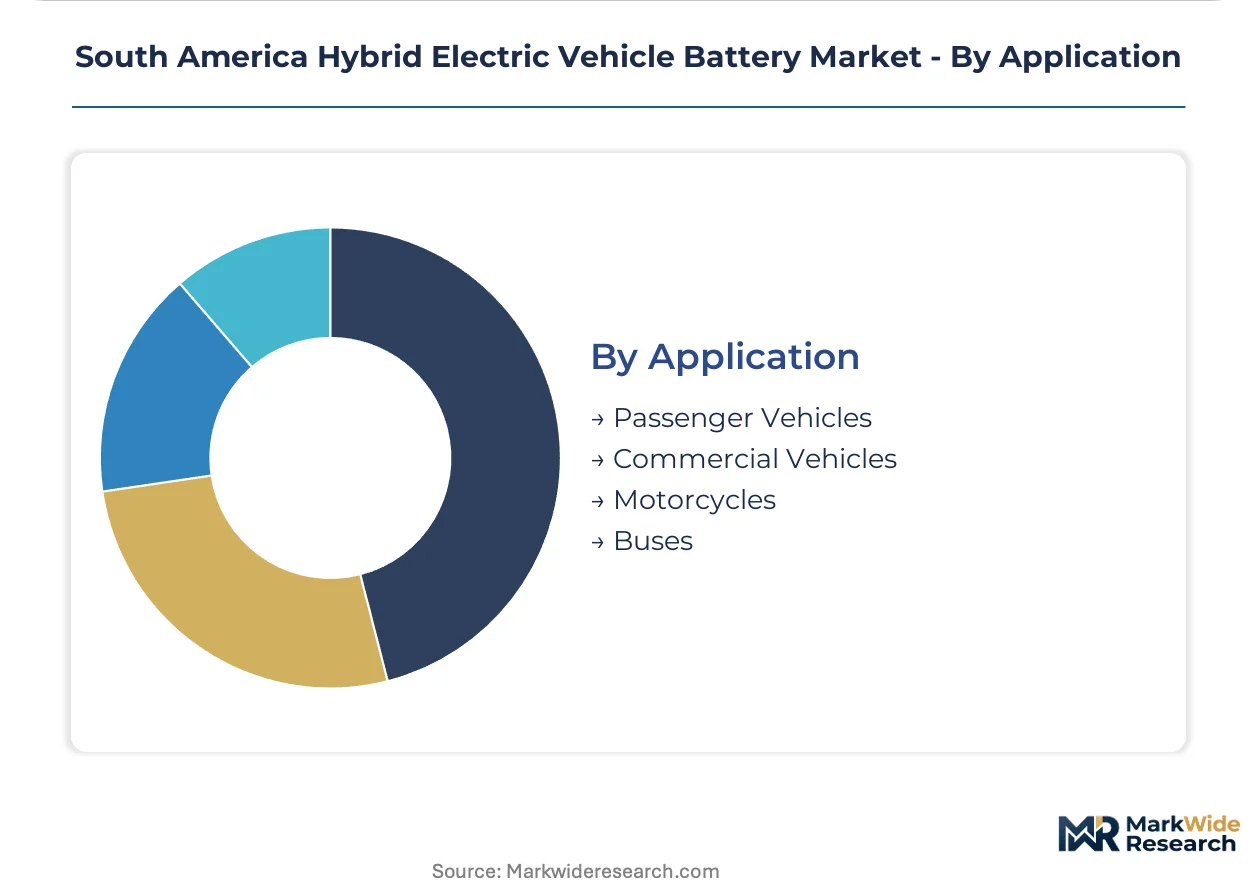
Application:
Vehicle architecture dictates pack form factor standardization potential, with legacy chassis integration complexity resisting platform consolidation.
- Passenger Vehicles:Passenger hybrid applications demand compact pack volumes with 200-400V nominal architectures, prioritizing gravimetric efficiency for consumer adoption in São Paulo's congestion-charging exemption zones. Telematics integration requirements accelerate battery management system software deployment fastest in this segment.
- Buses:Municipal bus fleets operate nickel metal hydride and lithium-iron-phosphate systems with 10-15 year cycle life requirements, where INMETRO certification timelines extend product launch windows and allow uncertified competitors to capture tender awards.
- Commercial Vehicles:Heavy-duty truck mild-hybrid systems serve mining electrification mandates from Chile's Ministry of Energy at high-altitude thermal stress conditions.
- Motorcycles:Two-wheeler hybrid applications remain nascent, constrained by pack volume limitations and cost thresholds for mass-market penetration.
By installed base, Buses lead. By technology transfer velocity, Passenger Vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands pricing power through São Paulo's concentrated procurement scale, while Argentine and Chilean markets absorb premium localization costs without equivalent volume leverage. This asymmetry shapes cross-border investment flows and certification sequencing strategies.
Brazil
São Paulo state's congestion charging exemptions and tax abatements concentrate hybrid vehicle adoption in Brazil's wealthiest automotive corridor. Proconve P8 emission standards from the national environmental council force OEMs toward electrified powertrains before full EV infrastructure maturity. The ABC automotive manufacturing belt around São Paulo anchors localized battery assembly partnerships that bypass Mercosur's external tariff walls on finished cells.
Argentina
Buenos Aires and Córdoba municipal transit authorities lack established hybrid bus suppliers, creating first-mover positioning for Brazilian pack assemblers with cross-border certification capabilities. The country's national industrial regulator mandates IRAM safety markings that extend product validation timelines for foreign entrants. Argentine fleet procurement committees increasingly unbundle battery purchases from complete bus contracts, mirroring São Paulo's 2024 tender restructuring.
Chile
The Ministry of Energy's underground vehicle electrification requirements open hybrid powertrain applications for heavy-duty mining trucks operating at high-altitude thermal stress conditions. SENCICO technical standards govern construction and mining equipment certification, fragmenting compliance obligations across Andean trade corridors. Antofagasta and Santiago engineering clusters concentrate thermal management talent for extreme ambient temperature pack design.
Peru
Lima's municipal transit authority issued preliminary hybrid bus procurement guidelines in 2024, though fixed-term pricing structures resist lithium carbonate cost pass-through. SENCICO technical standards align with Chilean requirements, enabling cross-border certification reuse for pack assemblers. The Callao port complex handles cell import logistics for Andean assemblers lacking Brazilian-scale localization economics.
Colombia
Bogotá's TransMilenio bus rapid transit system evaluates hybrid powertrain pilots as diesel import costs fluctuate. The national planning department's electrification roadmap lacks binding procurement mandates, leaving adoption timing to municipal discretion. Medellín's automotive engineering institutes partner with Brazilian federal technology programs on tropical-climate solid-state validation research.
South America Hybrid Electric Vehicle Battery Market Competitive Landscape
Japanese technology-transfer specialists and Chinese chemistry-integrated fabricators split the market along supply-chain control vectors. Panasonic Holdings Corporation anchors the former archetype through Brazilian manufacturing complex partnerships, while BYD Company Ltd exemplifies the latter via direct lithium-iron-phosphate supply relationships with Latin American bus builders. Three strategic archetypes now dominate: chemistry-integrated Asian conglomerates, component-specialized Korean chaebols, and regional assembly partners leveraging Mercosur tariff preferences. Competitive moves concentrate on localized cell assembly partnerships and predictive diagnostics software licensing to bypass hardware margin compression.
Within the chemistry-integrated tier, BYD Company Ltd and Contemporary Amperex Technology Co. Limited occupy positions shaped by direct cathode material supply control and scale-driven cost structures. Panasonic Holdings Corporation and LG Chem Ltd sit within the technology-transfer archetype, exemplifying partnerships that navigate INMETRO certification timelines through established Brazilian automotive relationships. Korean and Japanese players represent the premium-tier vector where battery management system software exports generate recurring revenue decoupled from pack hardware margins.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Clarios |
| Contemporary Amperex Technology Co. Limited |
| BYD Company Ltd |
| VARTA AG |
| LG Chem Ltd |
| SK Innovation Co. Ltd |
| EnerSys |
| Exide Industries |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Brazilian cell assembly facilities is compressing supplier margins while forcing buyers toward longer-term offtake commitments that lock in price stability against lithium carbonate volatility. São Paulo's concentrated procurement scale amplifies this dynamic, as municipal fleet operators exploit volume leverage to resist cost pass-through while pack assemblers absorb localization expenses to maintain Mercosur market access.
Pricing Analysis
Configured-to-order pricing for bespoke bus battery form factors commands premiums of 15-25% above standard passenger vehicle pack architectures due to legacy chassis integration complexity. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with INMETRO-validated systems capturing margin premiums. Cost compression in nickel metal hydride segments is intensifying because fixed-term municipal contracts resist cathode material inflation. Fleet procurement committees demonstrate highest price sensitivity, while OEM integration partners accept premium positioning for predictive diagnostics integration.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates supply chain risk calculations, forcing Korean and Japanese cell producers toward localized assembly partnerships that bypass Mercosur's external tariff walls. Cathode active material production concentrates in China, South Korea, and Japan, while lithium carbonate extraction feeds from Chile and Argentina. The supply chain rests on rare-earth alloy hydride sourcing for nickel metal hydride chemistry and layered oxide procurement for lithium-ion systems. Single-source vulnerability in Brazilian thermal engineering talent constrains pack design expansion. Distribution runs through São Paulo-based OEM integration hubs and direct fleet operator relationships that displace legacy distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full battery electric vehicle penetration represents the primary substitution threat that hybrid battery incumbents must navigate, as charging infrastructure maturity and falling cell costs erode the hybrid bridge-technology value proposition.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into cathode material supply and embedding software-defined battery management systems that generate recurring diagnostic licensing fees. Panasonic Holdings Corporation's technology-transfer model demonstrates how established Brazilian automotive relationships compress INMETRO certification timelines against emerging chemistry-integrated competitors. For New Entrants and Emerging Players: Establish a beachhead in Argentina's untapped municipal bus fleet segment, where Buenos Aires and Córdoba procurement authorities lack established hybrid suppliers and increasingly unbundle battery purchases from complete vehicle contracts. BYD Company Ltd's direct lithium-iron-phosphate supply relationships with Latin American bus builders illustrate the go-to-market angle of bypassing legacy distributor networks through direct fleet operator engagement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among battery management system software licensors, where predictive diagnostics and cell-balancing algorithm exports to Andean assemblers generate subscription-like cash flows decoupled from hardware margin compression. Acquisition targets should prioritize Brazilian pack assemblers with cross-border certification capabilities and established OEM integration relationships. The signal to monitor is municipal tender unbundling velocity, as Rio de Janeiro and Belo Horizonte replication of São Paulo's 2024 procurement restructuring indicates accelerating direct supply relationship formation.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Cell Assembly Partnership | Bypasses Mercosur tariff exposure while securing Proconve P8 compliance positioning. |
| Battery Management System Licensing | Generates recurring software revenue insulated from lithium carbonate price volatility. |
| Cross-Border Certification Investment | Enables Argentine and Chilean market penetration through IRAM and SENCICO alignment. |
| Thermal Engineering Talent Acquisition | Addresses São Paulo corridor concentration constraints for high-temperature pack design. |
| Direct Fleet Operator Relationship | Captures unbundled procurement revenue streams bypassing legacy distributor markups. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, municipal fleet procurement managers, Tier 1 supplier business development leads, and thermal pack design specialists. Secondary validation drew from ANFAVEA certification protocol documentation, INMETRO efficiency label registries, Mercosur customs trade data, and São Paulo state transit authority tender archives. Bottom-up cell shipment estimates were triangulated against top-down vehicle production forecasts across the analysis window.
Calibration against historical lithium-ion and nickel metal hydride penetration patterns anchored the projection framework, with segmentation modeling across chemistry type, end-user channel, application architecture, and regional regulatory cluster. CAGRs were derived from slope-consistent trajectory fitting rather than endpoint anchoring. Key forecast inputs included Proconve P8 compliance timeline assumptions and municipal electrification mandate adoption curves.
Sensitivities concentrate around lithium carbonate price volatility, INMETRO certification timeline extensions, and full EV substitution acceleration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure buildout pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market
EV Batteries
Traction Battery Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Auto Storage Battery Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market