
 EV Battery Cells Market | 2026-2036
EV Battery Cells Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Cells Market Analysis
Battery electrochemist shortages across Asia and Europe are reorganizing how manufacturers staff gigafactories and R&D centers. CATL leverages its captive lithium refining and cathode production to lock in cost advantages across the value chain. LG Energy Solution anchors its position through aggressive North American factory buildouts tied to IRA domestic content rules. Samsung SDI differentiates via high-nickel prismatic cells aimed at premium European automotive OEMs.
An EV battery cell is an electrochemical device comprising cathode, anode, separator, and electrolyte that stores and releases electrical energy through reversible lithium-ion intercalation, with energy density typically measured in watt-hours per kilogram and cycle life defining commercial viability. These cells power traction motors in battery electric vehicles, grid-scale storage installations, and industrial mobility platforms. Lithium-ion chemistry dominates current production, though solid-state architectures are attracting capital as manufacturers chase higher energy density and improved thermal stability. Fast charging technology commands premium positioning as OEMs compete on refueling parity with internal combustion engines. Automotive application absorbs the majority of cell output, while energy storage systems represent the fastest-expanding demand pool as utilities deploy grid buffers.
China's MIIT enforces GB standards for cell safety and recycling traceability, while the EU's Battery Regulation mandates carbon footprint declarations and recycled content minimums that reshape import competitiveness. The US IRA and EPA tailpipe rules together accelerate North American cell factory commitments by conditioning subsidies on domestic assembly and upstream mineral sourcing. Stakeholders must track how regional compliance divergences alter landing costs and factory location calculus.
Market Dynamics
The EV Battery Cells Market is being fundamentally restructured by the collision between China's GB safety mandates and the EU's carbon-footprint thresholds, which together force manufacturers to rebuild supply chains around certified low-carbon feedstock and transparent material provenance.
Growth Catalysts
- China's NEV mandate:The MIIT-enforced minimum new energy vehicle sales ratio compels domestic OEMs to secure long-term cell supply contracts, locking in manufacturing capacity commitments through 2030.
- Lithium iron phosphate chemistry:LFP cells are capturing share in mass-market passenger vehicles due to lower cobalt dependency and improved thermal stability under fast-charging protocols.
- Jiangsu-Fujian production corridor:Integrated cathode-to-cell facilities in these provinces achieve 40% logistics cost reduction versus dispersed supply chains, anchoring global cost benchmarks.
Market Restraints
- Spodumene concentrate volatility:Australian hard-rock lithium feedstock prices swing 30-50% annually, compressing cathode producer margins and destabilizing long-term contract pricing.
- Single-source separator dependency:Polypropylene and polyethylene membrane production concentrates in Japanese and Korean chemical conglomerates, creating chokepoint vulnerability for European and North American cell builders.
- EU Battery Regulation friction:The recycled content minimums and carbon footprint declarations impose compliance costs that disadvantage import-dependent assemblers versus vertically integrated producers.
Strategic Opportunities
- US IRA domestic content rules:The tax credit thresholds for North American assembly and upstream mineral sourcing are accelerating greenfield factory commitments across the battery belt states.
- Grid-scale storage integration:Utility-scale buffer installations represent the fastest-expanding demand pool as FERC interconnection reforms ease deployment timelines for battery energy storage systems.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic architectures promise 400+ Wh/kg energy density, enabling aviation and heavy-duty trucking applications currently unreachable with liquid electrolyte designs.
Industry Challenges
- Battery electrochemist scarcity:Gigafactory commissioning across Asia and Europe has exhausted the specialist labor pool, forcing manufacturers to train process engineers in electrochemistry fundamentals or poach from rival R&D centers.
- Cell passport certification timelines:The EU's digital battery passport requirements demand 18-24 month compliance preparation, delaying product launches for mid-tier producers lacking dedicated regulatory teams.
- Legacy thermal management integration:OEM vehicle platforms designed around cylindrical cell formats face costly redesign to accommodate prismatic or pouch architectures with superior pack-level energy density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Cells Market |
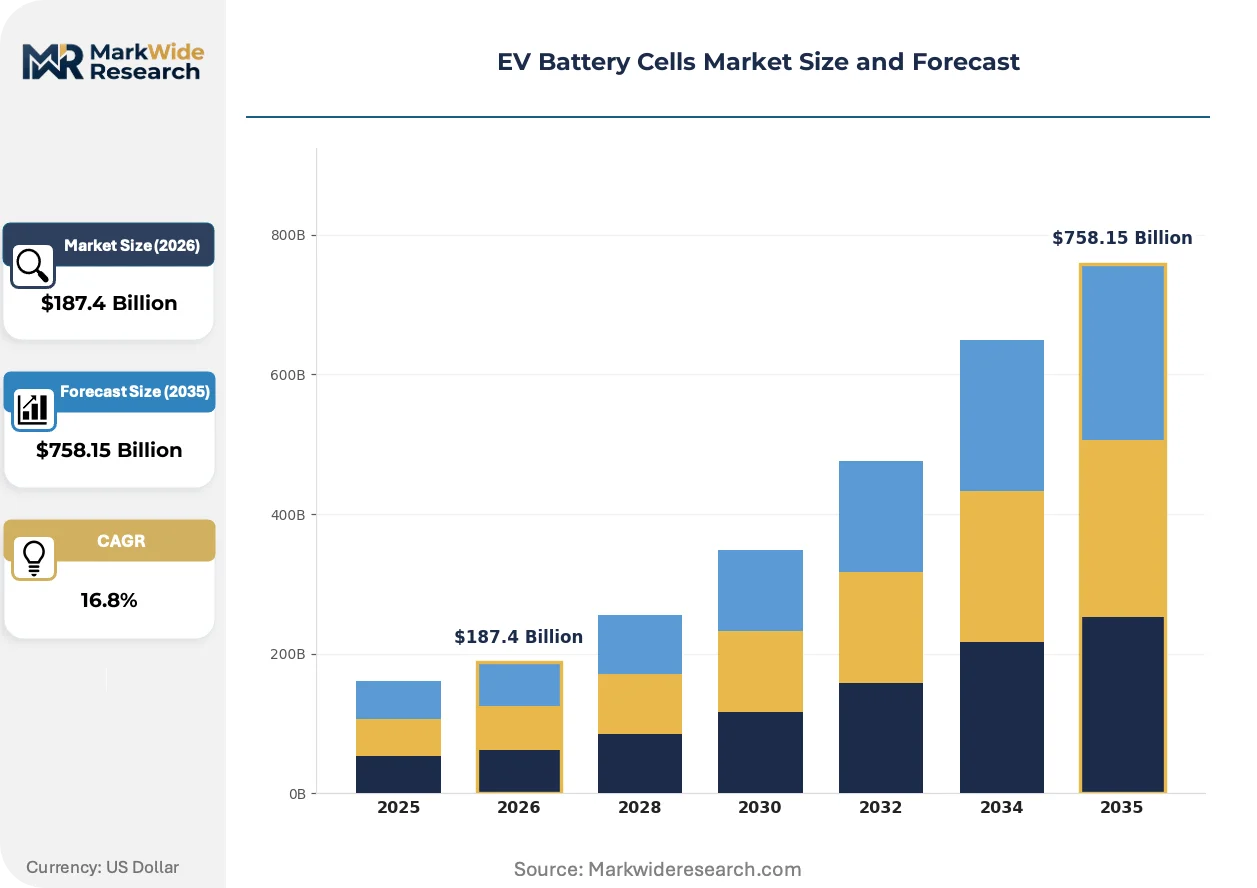
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lithium Polymer Technology: Fast Charging, Wireless Charging, Thermal Management, Energy Density Improvement Application: Automotive, Energy Storage Systems, Portable Electronics, Public Transport End User: OEMs, Aftermarket, Fleets, Private Consumers |
| Companies Covered | CATL, BYD, LG Energy Solution, Panasonic Energy, SK On, Samsung SDI, CALB, Gotion High-tech, EVE Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Cells Market Emerging Trajectories
Silicon-anode formulations and dry electrode coating processes are converging to break the 300 Wh/kg commercial threshold, while regulatory pressure on supply chain transparency accelerates blockchain-traceability adoption.
Dry electrode manufacturing is displacing traditional solvent-based slurry coating in pilot production lines. European premium automotive OEMs are qualifying these cells for 2027 platform launches. The elimination of N-methyl-2-pyrrolidone solvent reduces drying energy by 50% and enables thicker cathode loading, compressing manufacturing cost structures for nickel-manganese-cobalt chemistries.
The EU Battery Regulation's carbon footprint declaration mandate is forcing cathode active material suppliers to source hydroxide and sulfate from certified low-carbon refiners. This industrial consequence is reshaping offtake agreements toward long-term contracts with Australian and Chilean operations using renewable power. High-nickel cathode producers serving German automotive OEMs are most affected, with several establishing European precursor facilities to shorten transport emissions.
Fleet operators and energy utilities are consolidating procurement through direct long-term offtake contracts with cell manufacturers, bypassing traditional tiered distributor networks. This channel disintermediation concentrates volume commitments among buyers with balance-sheet capacity to absorb multi-gigawatt-hour commitments. The shift is most visible in North American utility-scale storage deployments, where independent power developers now negotiate directly with Korean and Chinese cell producers for decade-long supply agreements.
EV Battery Cells Market Segmentation
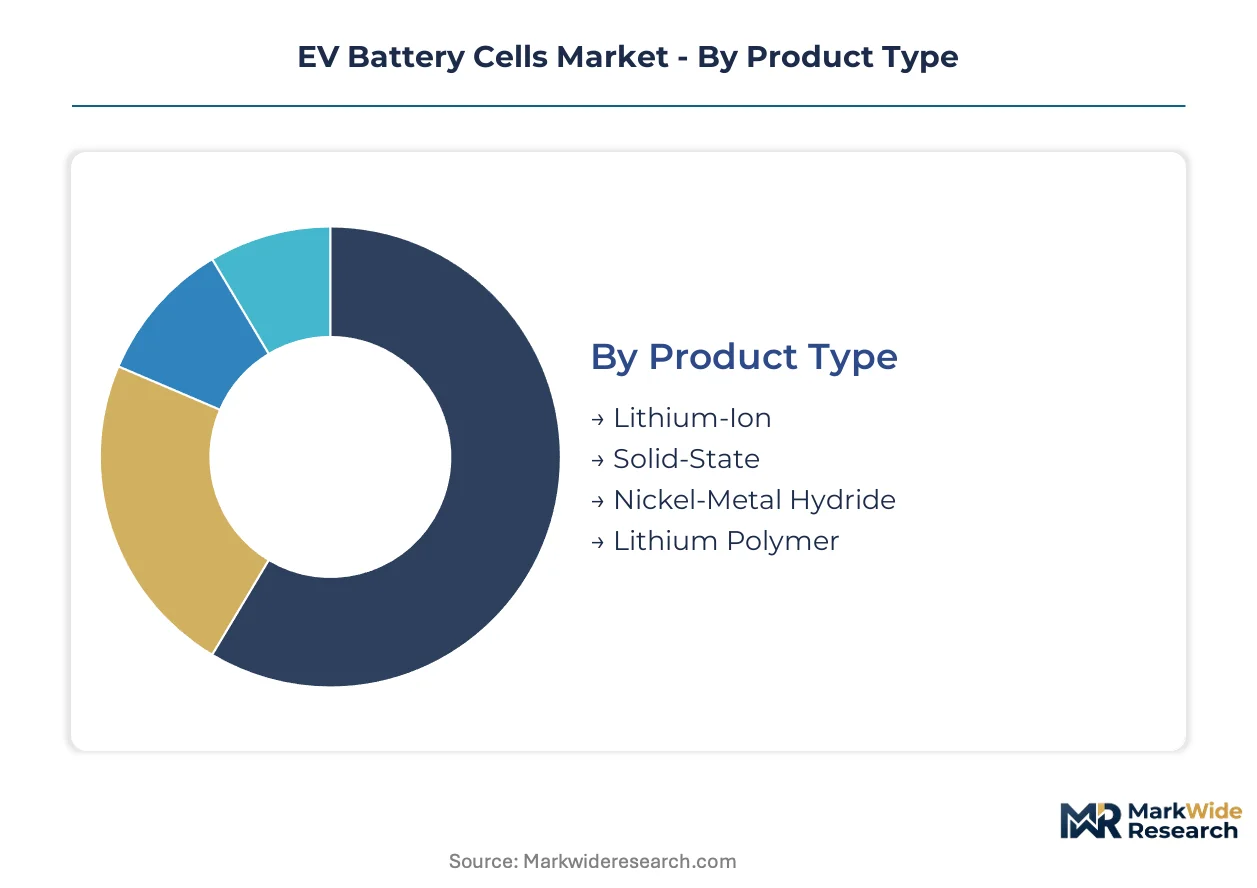
EV battery cell procurement channels diverge sharply by segment. Automotive OEMs negotiate direct offtake contracts for cylindrical and prismatic formats, while energy storage developers source pouch cells through integrator intermediaries. Understanding these channel dynamics reveals where pricing power concentrates and where margin compression threatens.
Product Type:
Lithium-ion formats dominate direct OEM procurement channels, while solid-state architectures flow through premium tier supplier relationships and joint development agreements.
- Lithium-Ion:NMC and LFP chemistries constitute the commercial backbone, with cylindrical 2170 and prismatic formats absorbing the majority of automotive contract volumes. CATL and LG Energy Solution have locked in supply agreements with German and Korean OEMs through 2030, anchoring this segment's channel stability.
- Solid-State:Sulfide and oxide electrolyte designs remain pre-commercial, with pilot production lines serving aviation and premium automotive qualification programs. Toyota and Samsung SDI are accelerating factory commitments in Japan and South Korea, betting on thermal runaway elimination to justify manufacturing cost premiums.
- Nickel-Metal Hydride:Toyota's hybrid vehicle programs in Japan and Kentucky sustain residual demand for this mature chemistry, though new platform development has ceased.
- Lithium Polymer:Pouch architectures serve portable electronics and limited automotive applications where form factor flexibility outweighs energy density requirements.
By volume, Lithium-Ion leads. By growth pace, Solid-State is ahead.
Technology:
Technology segments stratify by customer procurement sophistication, with fast charging commanding premium pricing from fleet operators while thermal management solutions penetrate through OEM platform integration mandates.
- Fast Charging:Silicon-anode and advanced electrolyte additives enable 10-80% state-of-charge cycles under 20 minutes. Chinese cell producers are qualifying these cells for European premium OEM platforms, where refueling parity with combustion engines drives specification requirements.
- Energy Density Improvement:High-nickel cathode loading and dry electrode coating processes push commercial cells toward 300 Wh/kg thresholds. Korean manufacturers are securing patents on thick-film cathode architectures that reduce cobalt dependency while maintaining cycle stability.
- Thermal Management:Cell-level cooling plates and phase-change materials integrate into pack designs, with Chinese and German OEMs mandating these specifications for warranty compliance in high-temperature climates.
- Wireless Charging:Inductive pad systems remain niche, deployed primarily in autonomous shuttle pilots in Singapore and Dubai where connector elimination reduces maintenance liability.
Fast Charging captures the highest price premiums. Energy Density Improvement shows the steepest expansion trajectory.
Application:
Application segments map to fundamentally different sales motions: automotive demands multi-year platform commitments, while energy storage tolerates shorter contract horizons and spot market flexibility.
- Automotive:Passenger and commercial vehicle platforms absorb the majority of cell output, with German and Chinese OEMs specifying cell-to-pack architectures that eliminate module housings. MIIT's NEV mandate in China and EPA tailpipe rules in the US are accelerating platform electrification timelines.
- Energy Storage Systems:Utility-scale buffer installations represent the most rapidly expanding demand pool, with FERC interconnection reforms in the US easing deployment timelines. Independent power developers in Texas and California now negotiate decade-long supply agreements directly with Korean cell producers.
- Portable Electronics:Cylindrical 18650 and 2170 formats serve power tool and laptop markets, with procurement concentrated through distributor networks rather than direct manufacturer relationships.
- Public Transport:Bus and rail electrification programs in Shenzhen, London, and Santiago drive demand for high-cycle-life LFP cells with standardized form factors for fleet maintenance simplicity.
Automotive commands absolute volume leadership. Energy Storage Systems are climbing the fastest.
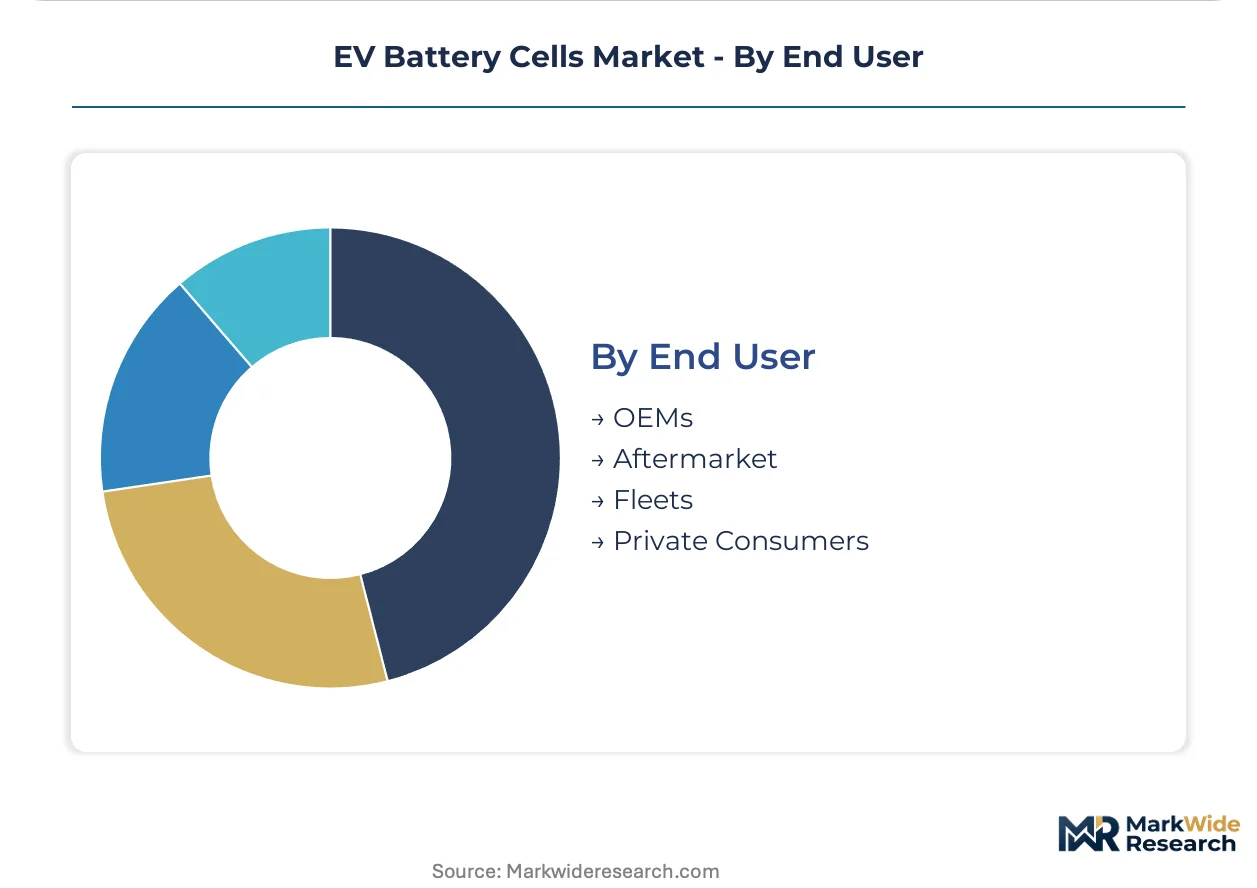
End User:
End user categories reflect divergent balance sheet capacities and contract risk tolerances, with OEMs and fleets absorbing multi-gigawatt-hour commitments that private consumers and aftermarket channels cannot match.
- OEMs:Volkswagen, BYD, and Stellantis are consolidating procurement through equity partnerships and long-term offtake contracts with cell manufacturers, securing capacity allocation through 2030. These arrangements increasingly specify carbon footprint thresholds compliant with EU Battery Regulation mandates.
- Fleets:Amazon, DHL, and Schneider Electric are bypassing tiered distribution to negotiate direct supply agreements, using balance sheet capacity to absorb volume commitments and capture price transparency unavailable through intermediaries.
- Aftermarket:Replacement cell demand concentrates in independent repair networks and refurbishment specialists, with procurement fragmented across regional distributors lacking manufacturer authorization.
- Private Consumers:Individual buyers access cells exclusively through finished pack purchases, with no direct procurement channel to cell manufacturers.
OEMs dominate contract value. Fleets are gaining share fastest through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers command pricing power through integrated cathode-to-cell facilities in Jiangsu and Fujian, while European and North American producers absorb cost premiums from carbon-footprint compliance and domestic content mandates.
China
CATL and BYD anchor massive production corridors in Jiangsu and Fujian provinces, achieving logistics cost advantages through backward integration into lithium refining and cathode manufacturing. MIIT enforces GB standards for cell safety and recycling traceability, tightening compliance for export-bound production. The Yangtze River Delta cluster concentrates the world's largest cell fabrication capacity, with local governments competing to attract gigafactory investments through subsidized land and power.
United States
The battery belt states stretching from Michigan to Georgia host accelerated greenfield commitments from Korean and domestic producers seeking IRA tax credit eligibility. FERC interconnection reforms ease utility-scale storage deployment timelines, expanding demand for LFP cells. EPA tailpipe rules and domestic content thresholds reshape factory location calculus, with producers locating cathode precursor facilities near Appalachian lithium processing sites.
Germany
Premium automotive OEMs in Bavaria and Baden-Württemberg specify high-nickel prismatic cells with carbon footprint declarations compliant with EU Battery Regulation mandates. The KBA enforces type approval standards that delay product launches for non-compliant imports. The Erfurt-Dresden corridor hosts European precursor facilities established to shorten transport emissions and satisfy recycled content minimums.
South Korea
LG Energy Solution and Samsung SDI leverage aggressive North American factory buildouts to capture IRA-compliant market share, while domestic R&D centers advance solid-state electrolyte architectures. The MFDS coordinates with METI-aligned standards for aviation battery qualification. The Gyeonggi-Seoul cluster concentrates high-nickel cathode research and pilot production lines for premium European offtake.
Japan
Toyota sustains hybrid vehicle demand through Kentucky and Aichi production of nickel-metal hydride cells, while Panasonic Energy qualifies cylindrical formats for North American EV platforms. METI funding accelerates sulfide-based solid-state pilot lines in Nagoya. The Kansai region hosts ceramic electrolyte research consortia targeting aviation applications with 400+ Wh/kg density targets.
EV Battery Cells Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Chinese producers dominate volume through integrated supply chains and LFP chemistry scale, while Korean and Japanese manufacturers anchor premium positioning through high-nickel and solid-state development. Three archetypes define the field: vertically integrated raw-material players, technology-specialist premium suppliers, and scale-driven mass-market fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers racing to secure offtake agreements before platform lock-in solidifies.
Among the cost-integrated tier, CATL and BYD represent the archetype of captive supply chain control, while LG Energy Solution occupies a position bridging premium technology and geographic diversification. Samsung SDI exemplifies the high-nickel specialist path, targeting qualification programs where thermal stability commands price premiums. These three anchors illustrate how competitive positioning diverges between mass-market volume capture and premium-tier technology differentiation.
| Leading Market Players |
|---|
| CATL |
| BYD |
| LG Energy Solution |
| Panasonic Energy |
| SK On |
| Samsung SDI |
| CALB |
| Gotion High-tech |
| EVE Energy |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between automotive OEMs and cell manufacturers lock in supply access and price visibility, with German and Chinese buyers securing decade-long agreements that insulate against Australian spodumene concentrate volatility while exposing them to EU Battery Regulation carbon-footprint compliance costs.
Pricing Analysis
The customization-premium spread in EV battery cells separates standard LFP cylindrical formats from configured-to-order high-nickel prismatic designs with cell-to-pack architectures. Contract-based long-term offtake dominates automotive procurement, while spot market flexibility persists in energy storage segments. Price differentiation rests on certification grade—EU Battery Regulation carbon declarations command premiums—and volume scale, with fleet operators capturing transparency unavailable through tiered distribution. Cost compression in mass-market LFP cells is intensifying because Chinese integrated producers leverage captive lithium refining, while premium high-nickel segments show pricing resilience. Fleet operators demonstrate highest price sensitivity due to direct procurement exposure, whereas premium European OEMs prioritize thermal stability over unit economics.
Supply Chain Analysis
Port congestion across Shanghai-Ningbo and Busan trade lanes elevates inbound logistics costs for European and North American cell assemblers sourcing cathode precursors from Jiangsu and Fujian provinces. Supply concentrates in China, South Korea, and Japan, with Chinese producers commanding 40% logistics cost advantages through backward integration. The chain draws from Australian hard-rock lithium, Chilean brine operations, and Indonesian nickel processing. Single-source separator dependency on Japanese and Korean chemical conglomerates creates chokepoint vulnerability. Distribution runs through direct manufacturer relationships for automotive OEMs and integrator intermediaries for energy storage developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV battery cells market is entering a cyclical recovery phase as lithium feedstock prices stabilize from spodumene concentrate volatility and OEM platform electrification timelines accelerate under EPA tailpipe mandates.
For Market Incumbents: Consolidate capacity allocation through equity partnerships with German and Chinese OEMs, securing platform lock-in before solid-state architectures mature. Prioritize backward integration into cathode precursor production near Appalachian lithium processing sites to satisfy IRA domestic content thresholds. Defend against Korean and Japanese high-nickel specialists by accelerating LFP scale in the Jiangsu-Fujian corridor. For New Entrants and Emerging Players: EU Battery Regulation certification fast-tracks offer penetration pathways for mid-tier producers lacking dedicated regulatory teams. Target North American utility-scale storage deployments where FERC interconnection reforms ease deployment timelines and independent power developers negotiate directly with cell manufacturers. Pursue solid-state electrolyte joint development agreements with aviation qualification programs as the most penetrable premium segment. For Investors and Strategic Acquirers: Solid-state pilot-line specialists with sulfide ceramic architectures represent the highest-conviction acquisition target archetype for long-term viability across the analysis window. These assets command premiums as Toyota and Samsung SDI accelerate factory commitments betting on thermal runaway elimination. Watch for inflection when aviation battery qualification programs shift from pre-commercial to volume procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captures IRA tax credit eligibility by locating facilities near Appalachian lithium processing sites. |
| EU Battery Regulation Certification Investment | Enables market access for German automotive OEM procurement with carbon footprint declaration mandates. |
| Direct Offtake Contract with Fleet Operators | Bypasses tiered distribution to capture price transparency through Amazon and DHL balance sheet capacity. |
| Solid-State Electrolyte Joint Development | Qualifies cells for aviation applications with 400+ Wh/kg density targets unreachable with liquid designs. |
| Grid-Scale Storage Supply Agreement | Secures decade-long commitments with Texas and California independent power developers under FERC reforms. |
Methodological Framework
The analysis maps lithium-ion format chemistries, solid-state architectures, and thermal management technologies, each validated through electrochemist interviews, OEM platform engineering directors, cathode procurement leads, and utility-scale storage developers. Primary fieldwork combined with secondary validation from MIIT GB standard filings, EU Battery Regulation implementation guidance, SEC 10-K supply chain disclosures, and FERC interconnection queue data. Bottom-up cell production capacity modeling triangulates against top-down automotive platform electrification forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation by chemistry type, form factor, application, and end-user procurement sophistication. CAGRs were derived from production capacity buildout timelines and OEM platform launch schedules. Industry-specific forecast inputs include spodumene concentrate price trajectories and solid-state pilot-line commissioning milestones.
Decision-makers should treat outputs as directional under assumptions of continued IRA domestic content enforcement and EU Battery Regulation carbon threshold tightening; material deviation would warrant model refresh. Forecasts reflect assumptions of lithium feedstock price stabilization and OEM platform electrification adherence to EPA mandates. Spodumene concentrate volatility, separator supply disruption, or solid-state technology acceleration could revise trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
US EV Battery Pack Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Traction Battery Market
EV Batteries
EV Batteries Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Thermal Interface Material for EV Battery Market
EV Batteries
United States Electric Vehicle Battery Anode Market