
 India Battery Energy Storage Systems Market | 2026-2036
India Battery Energy Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
India Battery Energy Storage Systems Market Foresight
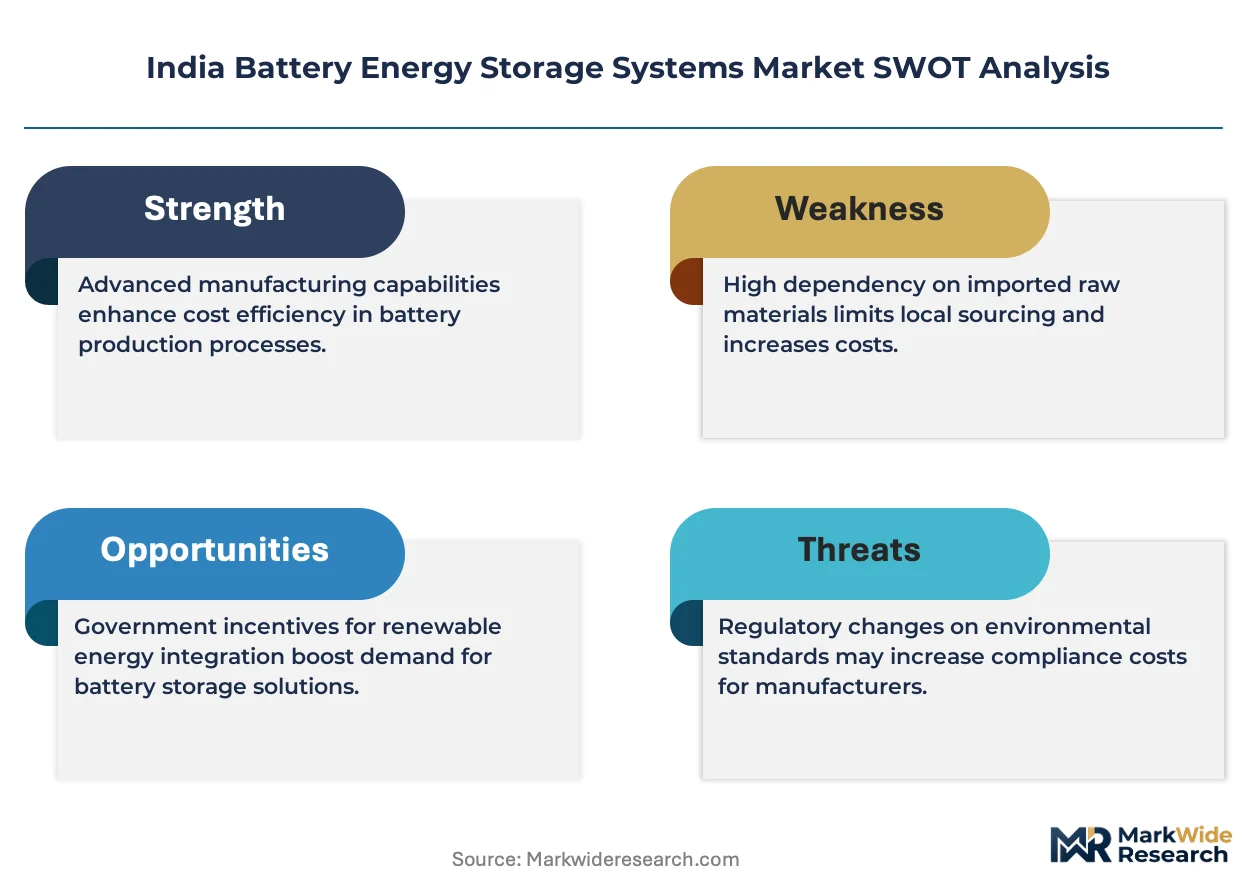
BIS certification for electrochemical energy storage systems is rotating the competitive landscape by disqualifying uncertified imports and favoring domestic manufacturers with testing infrastructure. Exide Industries leverages its established lead-acid manufacturing footprint to anchor early grid-scale deployments. Tata Power Renewable Energy Ltd competes through integrated renewable-plus-storage project development across western India. Reliance New Energy Ltd differentiates via captive cell manufacturing ambitions and backward integration into lithium processing.
Battery energy storage systems comprise electrochemical cells arranged in modular racks with power conversion systems and battery management units, typically operating at voltage ranges from 480V to 1500V DC for grid interconnection. These systems buffer intermittency from solar and wind assets while providing frequency regulation and peak shaving services to electricity networks. Lithium-ion batteries dominate utility procurement due to superior energy density and declining cell costs, while flow batteries occupy niche long-duration applications requiring eight-plus hours of discharge. Grid storage applications attract the deepest capital pools, though off-grid storage for rural electrification sustains faster volume growth in absolute unit terms.
CEA mandates and BIS standards govern safety and performance benchmarks for grid-connected installations, while the PLI scheme directs capital toward domestic cell manufacturing capacity. India's central electricity regulator shapes tariff structures that determine storage project returns and utility willingness to procure. Stakeholders must monitor how state-level renewable purchase obligations incorporate storage mandates and which states move first on standalone battery procurement auctions.
Market Dynamics
India's PLI scheme for advanced chemistry cell manufacturing is compressing import dependence while CEA mandates on grid-connected storage are forcing procurement model reinvention across state distribution companies.
Growth Catalysts
- CEA storage mandates:Central Electricity Authority regulations now require renewable energy projects above specified capacities to install co-located battery systems, creating guaranteed demand pools for developers in Rajasthan and Gujarat.
- Industrial microgrids:Manufacturing clusters in Maharashtra and Tamil Nadu are deploying captive storage to manage peak demand charges and power quality issues from erratic grid supply.
- Lithium-ion cost curves:Declining cell prices are narrowing the levelized cost gap against diesel backup generators for commercial and industrial offtakers.
Market Restraints
- Lithium supply concentration:Raw material processing dominance by Chinese refiners exposes Indian pack assemblers to input cost volatility and currency fluctuation risks.
- BIS certification timelines:Electrochemical energy storage testing infrastructure bottlenecks are extending product approval cycles by six to twelve months for imported cell configurations.
- Flow battery economics:Vanadium redox systems remain uncompetitive for four-hour applications despite superior cycle life, limiting technology diversification.
Strategic Opportunities
- Rural electrification:Off-grid solar-plus-storage mini-grids in Bihar and Uttar Pradesh offer faster deployment timelines than centralized transmission extension.
- Frequency regulation markets:Ancillary service tariff reforms by central electricity regulators could unlock new revenue streams for standalone battery assets.
- Sodium-ion convergence:Emerging chemistry alternatives paired with domestic hard rock graphite reserves may reduce import intensity for stationary applications.
Industry Challenges
- Thermal runaway mitigation:Grid-scale lithium-ion installations require specialized fire suppression engineering and ventilation design capabilities that remain scarce in domestic EPC markets.
- Integration complexity:Retrofitting battery management systems with existing SCADA infrastructure at state utility substations demands custom protocol translation and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Battery Energy Storage Systems Market |
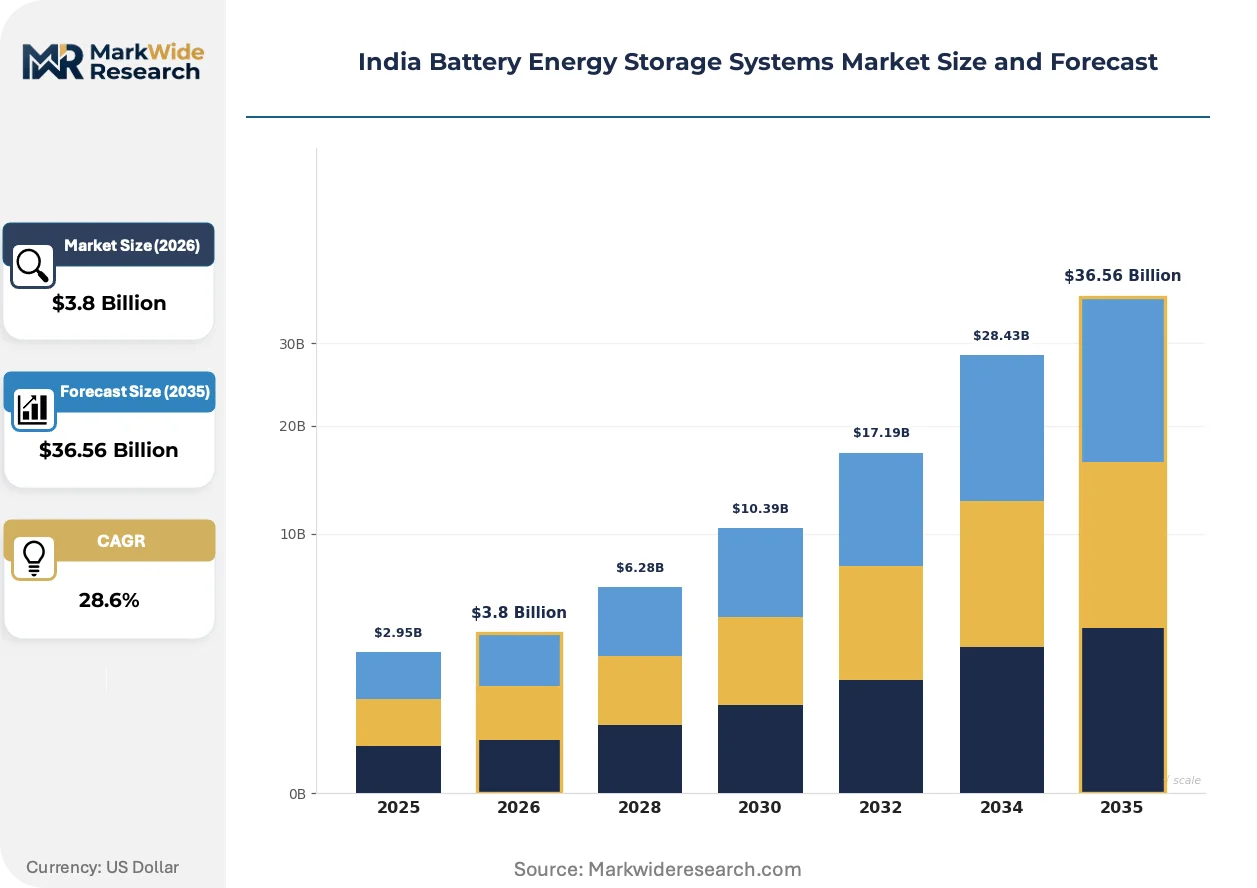
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid Batteries, Lithium-Ion Batteries, Flow Batteries, Nickel-Cadmium Batteries Application: Grid Storage, Off-Grid Storage, Renewable Integration, Backup Power End User: Residential, Commercial, Industrial, Utility Technology: Chemical Storage, Mechanical Storage, Thermal Storage, Electrochemical Storage |
| Companies Covered | AES Corporation, Delta Electronics Inc, Exide Industries Ltd, Panasonic Corporation, Adani Energy Solutions, Amara Raja Group, Reliance New Energy Ltd, Invergy Power Supply, Tata Power Renewable Energy Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Battery Energy Storage Systems Market Shifts & Advancements
Technology trajectories and procurement models across India's battery storage sector are diverging sharply between utility-scale and distributed applications, with regulatory pressure accelerating chemistry and system architecture experimentation.
Lithium iron phosphate chemistry is bifurcating the utility procurement landscape. The technology offers superior thermal stability and extended cycle life compared to nickel-manganese-cobalt alternatives. State distribution companies in western India are specifying LFP-dominant configurations for solar-wind hybrid tenders. This chemistry preference is compressing cobalt-linked supply chain exposure while elongating asset depreciation schedules for project financiers.
CEA technical standards for grid-connected battery energy storage systems are mandating granular telemetry and remote monitoring capabilities. The regulation requires real-time state-of-health reporting and automated disconnect protocols. Utility-scale developers are responding by embedding edge computing modules within power conversion systems, while smaller integrators struggle with compliance cost absorption.
Aggregated procurement through state nodal agencies is displacing bilateral developer-utility negotiations for grid-scale storage. Tamil Nadu and Maharashtra distribution companies are consolidating demand into centralized tenders with standardized technical specifications. This buyer concentration is compressing margin structures for system integrators while favoring manufacturers with certified manufacturing lines and established testing partnerships.
India Battery Energy Storage Systems Market Segmentation
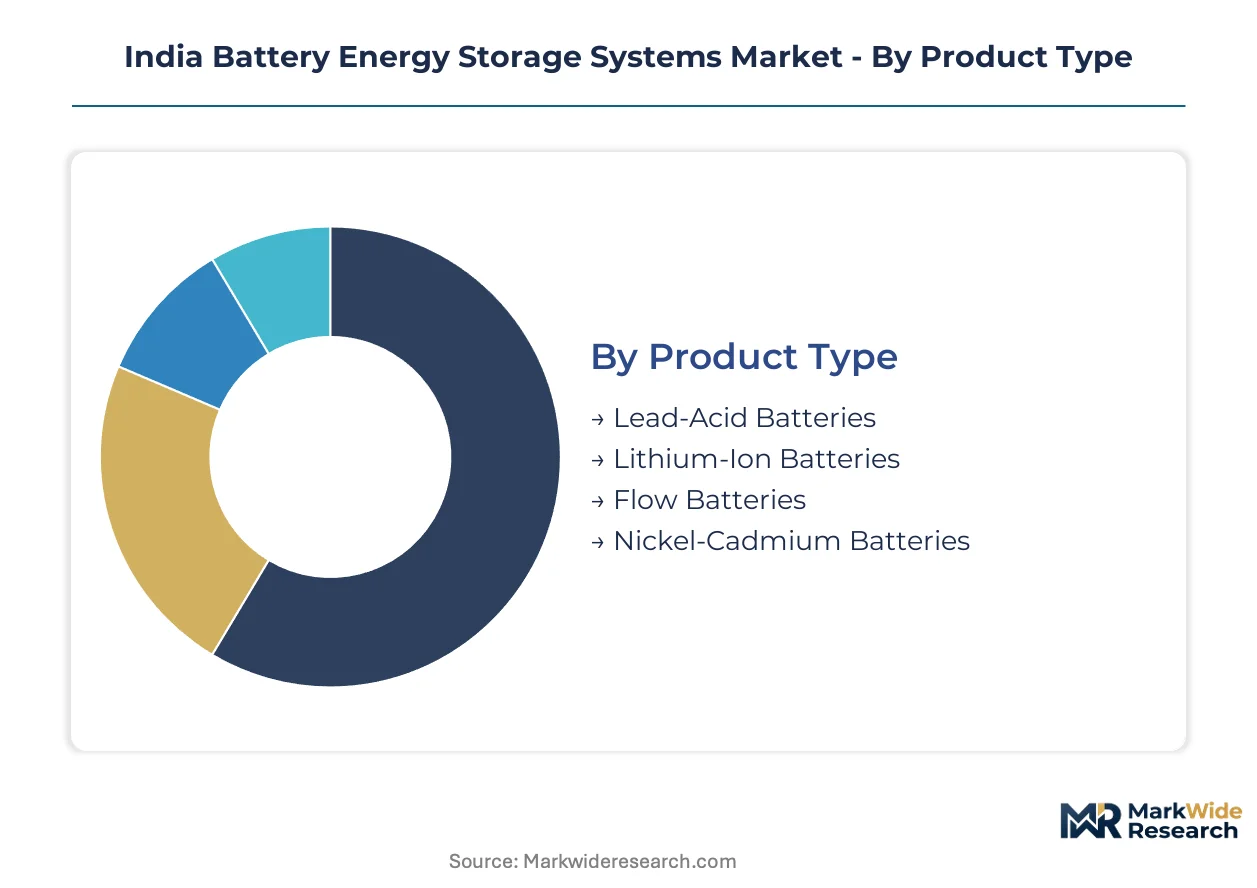
Segmentation reveals how procurement patterns diverge between grid-scale tenders and distributed installations across Indian states. Technology choices and end-user economics determine margin capture for domestic integrators navigating CEA mandates and BIS certification requirements.
Product Type:
Margin pools concentrate in lithium-ion configurations where PLI scheme incentives and declining cell costs reshape competitive economics against legacy chemistries.
- Lithium-Ion Batteries:Lithium iron phosphate and nickel-manganese-cobalt cells dominate utility procurement due to superior energy density and cycle life specifications. Demand clusters in Rajasthan and Gujarat solar-wind hybrid projects where CEA mandates guarantee procurement volumes for certified configurations.
- Flow Batteries:Vanadium redox systems deliver eight-plus hour discharge duration for long-duration applications. Installations remain niche due to capital cost premiums, though pilot deployments in Tamil Nadu industrial microgrids test viability for extended backup scenarios.
- Lead-Acid Batteries:Established recycling infrastructure and lower upfront capital sustain relevance in rural electrification mini-grids across Bihar and Uttar Pradesh.
- Nickel-Cadmium Batteries:Temperature tolerance advantages retain limited adoption in extreme climate zones despite cadmium handling regulations.
The dominant share belongs to lithium-ion configurations, while flow battery installations are gaining share fastest among duration-extended applications.
Application:
Application segmentation tracks how revenue models bifurcate between regulated utility procurement and risk-bearing commercial deployments.
- Grid Storage:Standalone and co-located battery assets provide frequency regulation and peak shaving services to state distribution companies. Procurement concentrates through Tamil Nadu and Maharashtra nodal agency tenders with standardized technical specifications compressing integrator margins.
- Renewable Integration:Solar-plus-storage and wind-plus-storage configurations satisfy CEA mandates for renewable projects above specified capacities. Rajasthan and Gujarat host the deepest project pipelines where land availability and irradiation levels optimize combined asset economics.
- Backup Power:Diesel generator replacement drives commercial and industrial adoption in Maharashtra manufacturing clusters managing peak demand charges.
- Off-Grid Storage:Mini-grid architectures deploy faster than centralized transmission extension in Bihar and Uttar Pradesh rural electrification programs.
Grid storage commands the largest revenue pool, though off-grid applications are expanding most quickly in absolute unit terms.
End User:
End-user segmentation exposes how tariff structures and regulatory obligations create divergent willingness-to-pay across customer categories.
- Utility:State distribution companies procure through centralized tenders shaped by renewable purchase obligations and CEA storage mandates. Aggregated demand pools in western India favor integrators with certified manufacturing lines and established BIS testing partnerships.
- Industrial:Manufacturing clusters in Maharashtra and Tamil Nadu deploy captive storage to manage power quality issues and peak demand charges from erratic grid supply. Microgrid configurations integrate with existing SCADA infrastructure demanding custom protocol translation.
- Commercial:Office complexes and retail chains evaluate battery economics against diesel backup generators as lithium-ion cost curves narrow levelized cost differentials.
- Residential:Rooftop solar-plus-storage adoption remains constrained by upfront capital requirements and limited net metering compensation frameworks.
Utility procurement absorbs the deepest capital deployment, while industrial microgrids are climbing the fastest as manufacturing clusters electrify.
Technology:
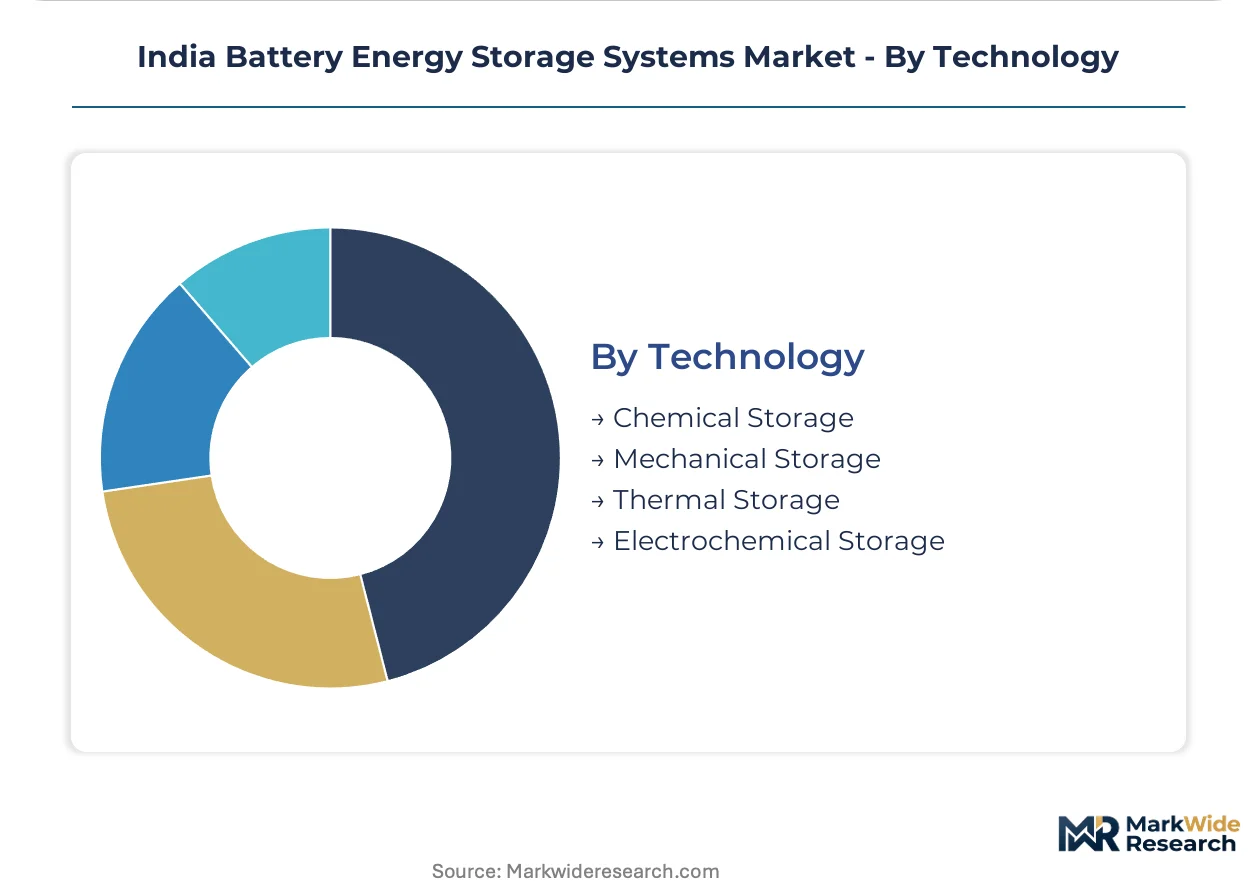
Technology segmentation distinguishes between electrochemical dominance and emerging mechanical and thermal alternatives seeking cost competitiveness.
- Electrochemical Storage:Battery systems comprising modular cell racks with power conversion systems and battery management units operate at 480V to 1500V DC for grid interconnection. BIS certification requirements for electrochemical energy storage systems favor domestic manufacturers with testing infrastructure.
- Chemical Storage:Hydrogen and synthetic fuel pathways remain pre-commercial for grid applications though pilot projects test long-duration viability.
- Mechanical Storage:Pumped hydro and compressed air systems leverage existing civil engineering capabilities in select Himalayan and Deccan topography.
- Thermal Storage:Molten salt configurations pair with concentrated solar power plants in Gujarat where direct normal irradiation supports trough and tower architectures.
Electrochemical systems hold the dominant position, while thermal storage is closing the gap fastest in solar-thermal hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement concentrates in western solar corridors while industrial microgrids cluster in southern manufacturing belts. State-level renewable purchase obligations and CEA storage mandates are redistributing deployment geography across Indian states.
Rajasthan
Solar-wind hybrid zones in Jaisalmer and Barmer districts are absorbing grid-scale battery deployments under CEA co-location requirements. The state's land availability and irradiation levels attract standalone storage tenders from central nodal agencies. Bhadla Solar Park anchors the deepest project pipeline where developers integrate lithium-ion racks with existing transmission infrastructure.
Gujarat
Charanka Solar Park and Kutch renewable energy zones drive procurement volumes for four-hour duration systems. The state's distribution company consolidates demand through centralized tenders with standardized LFP specifications. Gandhinagar-based project offices coordinate with BIS-certified integrators for compliance with CEA telemetry mandates.
Maharashtra
Industrial clusters in Pune and Aurangabad deploy captive storage to manage peak demand charges and power quality fluctuations. The state's microgrid regulations enable behind-the-meter configurations for manufacturing facilities. Mumbai's financial institutions are structuring project finance for distributed assets with shorter commissioning timelines than utility-scale counterparts.
Tamil Nadu
Wind-solar hybrid sites in Tirunelveli and Coimbatore districts require storage for grid stabilization and renewable firming. The state's nodal agency aggregates procurement through technology-specific tenders favoring certified domestic integrators. Chennai's industrial estates are piloting vanadium redox systems for extended backup scenarios in textile and automotive manufacturing.
Karnataka
Pavagada Solar Park and surrounding renewable zones are retrofitting battery systems to meet revised CEA storage obligations. The state's open access regulations enable commercial and industrial offtakers to procure renewable-plus-storage directly from developers. Bengaluru's technology corridor is testing sodium-ion alternatives for stationary applications with domestic hard rock graphite integration.
India Battery Energy Storage Systems Market Competitive Landscape
Player mix skews toward integrated energy conglomerates with captive manufacturing ambitions and established industrial battery fabricators pivoting toward grid-scale systems. Tier concentration is moderate with four to six entities controlling tender participation in western solar corridors. Strategic archetypes include renewable-plus-storage developers, legacy battery manufacturers with testing infrastructure, and new entrants with PLI-linked cell production plans. Capacity expansion and BIS certification partnerships represent the dominant competitive moves as qualification requirements tighten.
Among legacy industrial battery specialists, Exide Industries leverages established lead-acid manufacturing footprints and testing partnerships to anchor early grid-scale deployments. Tata Power Renewable Energy Ltd exemplifies the integrated developer archetype through renewable-plus-storage project origination across western India. Reliance New Energy Ltd occupies a position within the captive manufacturing tier with backward integration ambitions into lithium processing and cell production.
| Leading Market Players |
|---|
| AES Corporation |
| Delta Electronics Inc |
| Exide Industries Ltd |
| Panasonic Corporation |
| Adani Energy Solutions |
| Amara Raja Group |
| Reliance New Energy Ltd |
| Invergy Power Supply |
| Tata Power Renewable Energy Ltd |
| Others |
Supply & Pricing Matrix
Cell manufacturing scale economies in China and South Korea compress module pricing floors for Indian integrators while simultaneously concentrating supply risk. This dual dynamic forces domestic pack assemblers to absorb currency volatility through inventory buffers or long-term offtake commitments with lithium refiners.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate utility-scale procurement, tying final system prices to London Metal Exchange benchmarks and Shanghai Futures Exchange movements. Price differentiation separates BIS-certified domestic integrators from uncertified imports through testing infrastructure premiums and warranty extension bundling. Cost compression in four-hour lithium-ion configurations intensifies as PLI-linked cell capacity ramps and state nodal agencies consolidate tender volumes. Industrial microgrid buyers exhibit highest price sensitivity due to diesel backup parity calculations, while utility offtakers prioritize telemetry compliance over marginal cost reductions.
Supply Chain Analysis
Malacca Strait transit underwrites lithium hydroxide delivery schedules from Australian spodumene concentrators to Chinese refiners serving Indian pack assemblers. Raw material flows draw from Chilean and Argentine brine operations for carbonate, Indonesian nickel laterite for cathode precursors, and Chinese graphite for anode production. Single-source vulnerability concentrates in cathode active material processing, where Chinese refiners control conversion capacity. Distribution runs through Gujarat and Tamil Nadu port infrastructure to Rajasthan and Maharashtra project clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India battery storage market exhibits cyclical recovery characteristics anchored to CEA mandate enforcement waves and PLI scheme disbursement cycles. State distribution company procurement acceleration following regulatory deadlines provides predictable demand troughs and peaks.
For Market Incumbents: Secure BIS certification partnerships before testing infrastructure bottlenecks extend approval timelines for imported cell configurations. Deepen captive lithium processing capabilities to offset raw material cost volatility from Chinese refiner concentration. Anchor grid-scale tender participation through established relationships with Rajasthan and Gujarat nodal agencies.
For New Entrants and Emerging Players: Differentiate on sodium-ion chemistry integration with domestic hard rock graphite reserves for stationary applications outside utility procurement. Target Bihar and Uttar Pradesh rural electrification mini-grids where deployment timelines compress competitive qualification requirements. Pursue EPC partnerships with state utilities lacking in-house commissioning capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrators with certified manufacturing lines and backward lithium processing control over pure project developers. Long-term viability rests on chemistry diversification capability and regulatory compliance infrastructure rather than single-technology scale. Watch for PLI scheme disbursement acceleration as inflection signal for domestic cell capacity utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Testing infrastructure partnerships disqualify uncertified imports from CEA-mandated tenders in western states. |
| Backward Lithium Integration | Captive processing capabilities insulate margin structures from Shanghai Futures Exchange volatility. |
| State Nodal Agency Partnership | Aggregated procurement channels in Tamil Nadu and Maharashtra compress customer acquisition costs. |
| Sodium-Ion Chemistry Development | Domestic hard rock graphite pairing reduces import intensity for duration-extended rural electrification. |
| Telemetry Compliance Engineering | CEA-mandated real-time state-of-health reporting embeds switching costs for utility-scale deployments. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and grid operators and refined through secondary validation against CEA technical standards, BIS certification databases, state nodal agency tender documents, and PLI scheme disbursement records. Bottom-up project pipeline aggregation across Rajasthan, Gujarat, Maharashtra, and Tamil Nadu converged with top-down addressable market sizing from renewable capacity forecasts and CEA mandate coverage ratios.
Variance decomposition across technology chemistry, application duration, and end-user tariff structure shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, application use case, end-user category, and regional regulatory cluster. CAGRs derived from installed capacity buildout trajectories and system cost decline curves, with specific inputs from lithium-ion cell price forecasts and state-level renewable purchase obligation enforcement timelines.
Material uncertainties — raw material processing concentration, BIS certification timeline variability, and state-level storage mandate adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding PLI scheme continuity and CEA technical standard stability. Revision becomes warranted when Chinese refinery utilization rates or Indian state distribution company liquidity indicators cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Battery Monitoring Unit Market
Battery Management System
Electric Bus Lithium-Ion Battery Management System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
US Energy Storage Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Energy Storage System (ESS) Battery Market
Battery Management System
Battery Energy Management System Market
Battery Management System
DC Coupled Solar Battery System Market
Battery Management System
North America Energy Storage Market
Battery Management System
Global Power Management System Market