
 Electric Bus Lithium-Ion Battery Management System Market | 2026-2036
Electric Bus Lithium-Ion Battery Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Bus Lithium-Ion Battery Management System Market Analysis
China's manufacturing corridor is reconfiguring supply dynamics for electric bus battery management systems. LG Chem Ltd. leverages its cathode material dominance to secure upstream cost positions in cell-BMS integration. Samsung SDI Co., Ltd. anchors high-nickel chemistry supply through dedicated Korean production lines. ABB Ltd. competes on charging infrastructure-BMS interoperability, extending its power electronics footprint into bus OEM specification sheets.
An electric bus lithium-ion battery management system comprises embedded controllers, sensing arrays, and switching circuitry that monitor cell voltage, current, and temperature to prevent thermal runaway and optimize cycle life across 3,000-plus charge events. The system performs state-of-charge estimation, cell balancing, and fault isolation to protect 300-600 kWh battery packs operating under variable load profiles. Distributed architectures lead in high-capacity transit deployments where wiring weight reduction offsets per-module controller costs. Active balancing technology captures margin pools as operators prioritize range recovery over passive dissipation schemes. Fleet operators represent the fastest-growing end-user category, consolidating procurement across multi-depot electrification programs.
China's MIIT enforces GB/T standards for battery system safety testing, including nail penetration and overcharge tolerance protocols that shape BMS firmware requirements. The EU F-Gas Regulation and REACH chemical restrictions constrain thermal management fluid selections for European bus deployments. India's CEA battery storage directives and PLI scheme localization rules are creating dual certification paths for suppliers serving Asia-Pacific transit tenders. Stakeholders must monitor how cell-to-pack structural designs eliminate module-level BMS nodes, compressing hardware content per vehicle.
Market Dynamics
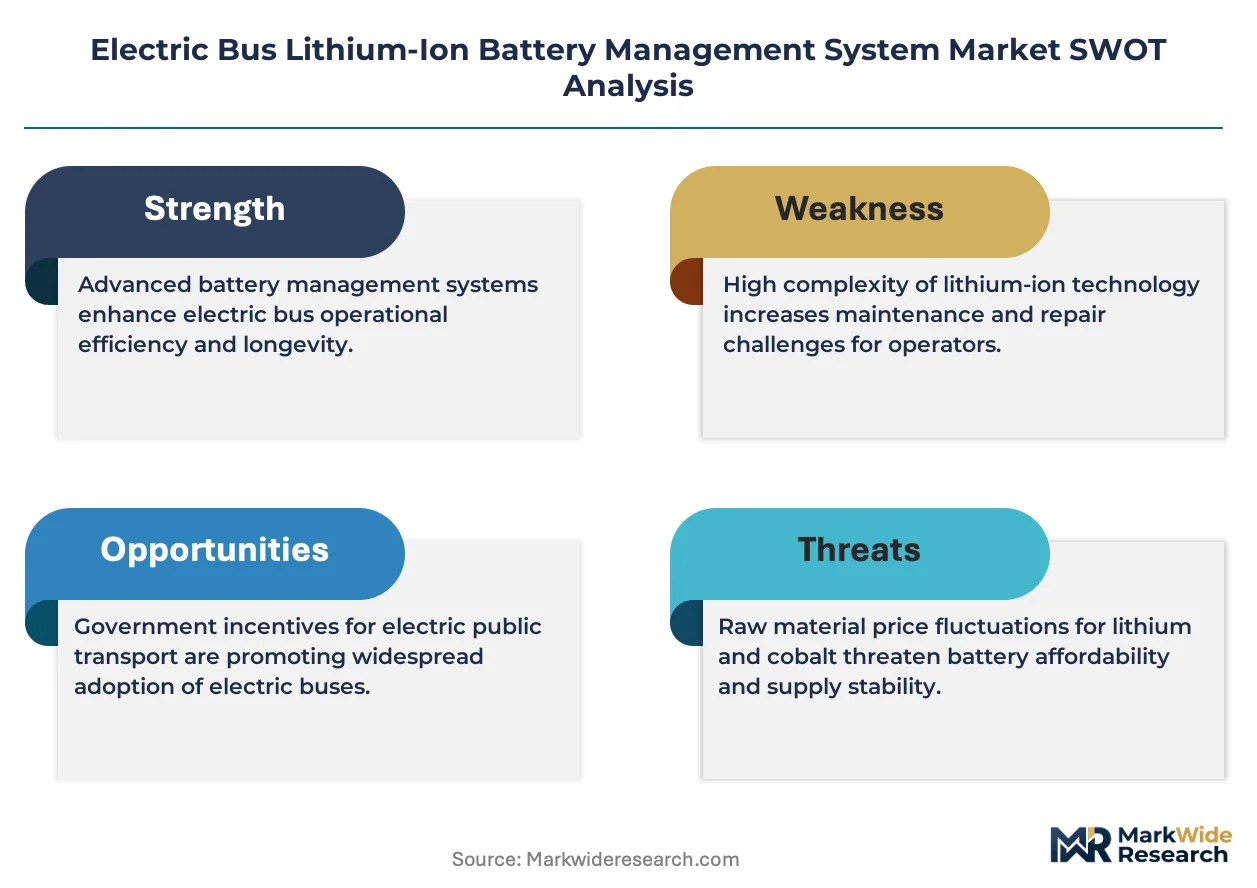
Cell-to-pack architectures are compressing module-level hardware requirements across electric bus battery management systems, forcing suppliers to recalibrate controller density and firmware complexity per vehicle platform.
Growth Catalysts
- China's GB/T 31485 safety protocols:Nail penetration and overcharge tolerance mandates are accelerating firmware investment in thermal runaway detection algorithms. Transit OEMs must certify to these standards for fleet procurement eligibility.
- Fleet operator consolidation:Multi-depot electrification programs are aggregating procurement volumes, creating specification leverage that favors integrated BMS-battery pack suppliers over standalone controller vendors.
- Active balancing circuits:Operators recovering 8-12% additional range per charge cycle are specifying inductive and capacitive transfer topologies over passive dissipation schemes in tender documents.
Market Restraints
- Cobalt and nickel price volatility:High-nickel cathode chemistries expose BMS voltage monitoring precision to raw material cost swings that compress pack-level margins.
- Korean cathode supply concentration:LG Chem and Samsung SDI control upstream NCM precursor output, creating single-source vulnerability for European and North American integrators.
- Functional safety certification timelines:ISO 26262 ASIL-D compliance for automotive-derived BMS architectures extends product validation cycles by 14-18 months.
Strategic Opportunities
- India's PLI scheme localization:Battery cell manufacturing incentives are creating captive demand for domestically assembled BMS controllers in Gujarat and Tamil Nadu production corridors.
- Wireless cell monitoring:Elimination of wiring harnesses between modules is enabling 12-15% weight reduction in double-decker and articulated bus platforms.
- EU F-Gas Regulation phase-down:Thermal management fluid restrictions are opening specification windows for dielectric immersion cooling systems that integrate directly with BMS thermal logic.
Industry Challenges
- Embedded systems firmware talent scarcity:State-estimation algorithm development for lithium-ion state-of-charge prediction requires specialized electrochemical modeling expertise concentrated in automotive hubs.
- Legacy depot charging infrastructure retrofit:Existing pantograph and plug-in systems lack CAN bus protocol compatibility with next-generation BMS communication stacks, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Bus Lithium-Ion Battery Management System Market |
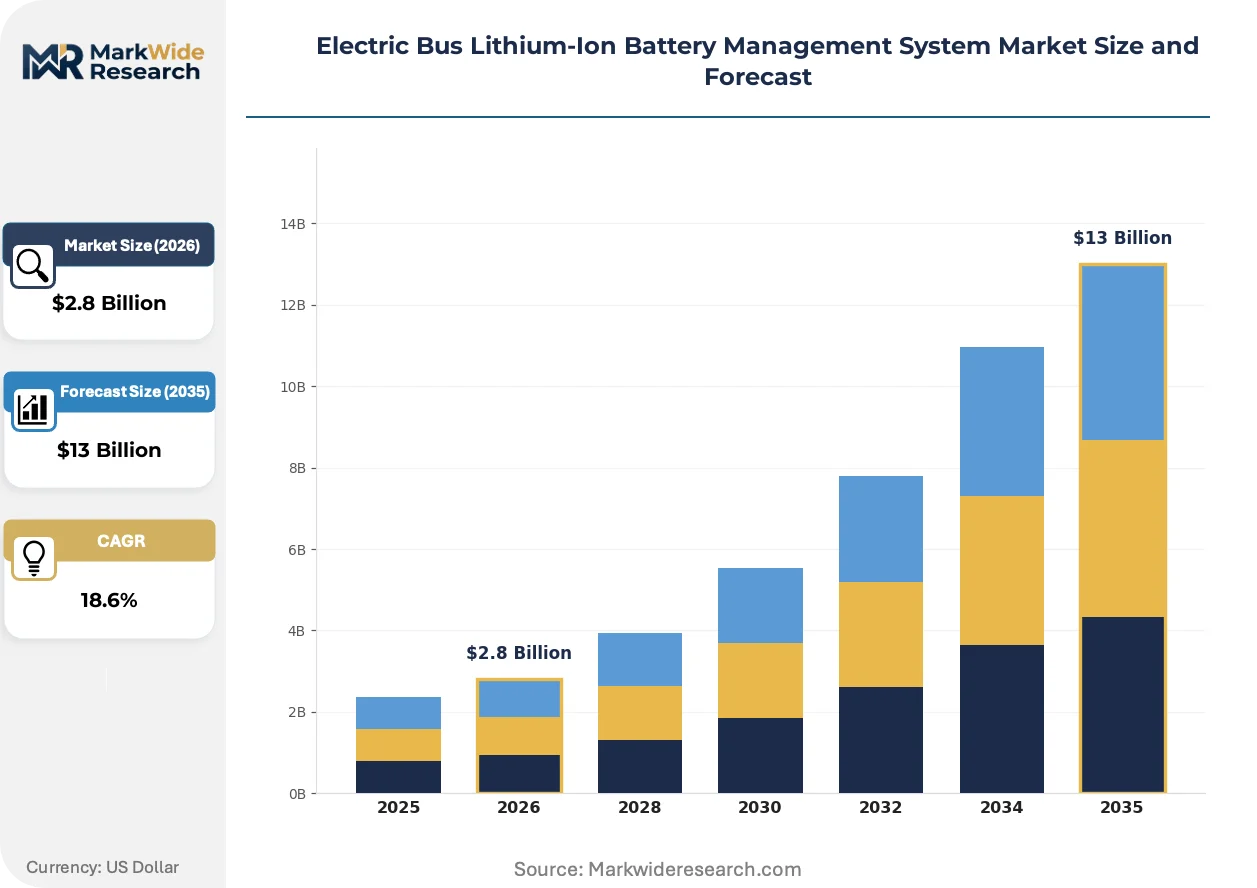
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized, Distributed, Modular, Hybrid Application: Public Transport, School Buses, Shuttle Services, Freight Transport End User: Municipalities, Logistics Companies, Fleet Operators, Private Transport Services Technology: Active Balancing, Passive Balancing, Thermal Management, Voltage Monitoring |
| Companies Covered | AVL List GmbH, Johnson Matthey PLC, Samsung SDI Co., Ltd., Eberspaecher Vecture Inc., Nuvation Energy Ltd., LG Chem Ltd., Lithium Balance A/S, Renesas Electronics Corporation, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Bus Lithium-Ion Battery Management System Market Emerging Trajectories
Distributed computing architectures are displacing centralized battery management topologies as bus OEMs prioritize wiring weight reduction and fault isolation granularity in high-capacity transit platforms.
Digital twin technology is virtualizing cell degradation prediction by creating real-time electrochemical models that mirror physical battery state. Fleet operators in Shenzhen and Guangzhou are deploying these systems across 300-plus vehicle deployments to optimize charging schedules and predict maintenance windows. This capability is compressing warranty reserve requirements and enabling usage-based service contracts that transfer residual value risk from operators to suppliers.
Europe's F-Gas Regulation is banning hydrofluorocarbon-based thermal management fluids above specified global warming potential thresholds by 2030. Bus OEMs serving German and French transit authorities are accelerating qualification of dielectric mineral oils and engineered fluorinated ketones that require recalibrated BMS temperature mapping algorithms. The regulation is forcing simultaneous redesign of cooling loop sensors and firmware compensation tables.
Consolidated procurement desks at municipal transit agencies are displacing decentralized depot-level purchasing for battery management systems. Aggregated tender specifications in California and New York are mandating 15-year cycle life guarantees and unified telematics platforms that lock out smaller BMS vendors lacking balance sheet capacity for long-term warranty obligations. This concentration is visible most acutely in zero-emission bus programs where federal funding eligibility requires standardized reporting protocols.
Electric Bus Lithium-Ion Battery Management System Market Segmentation
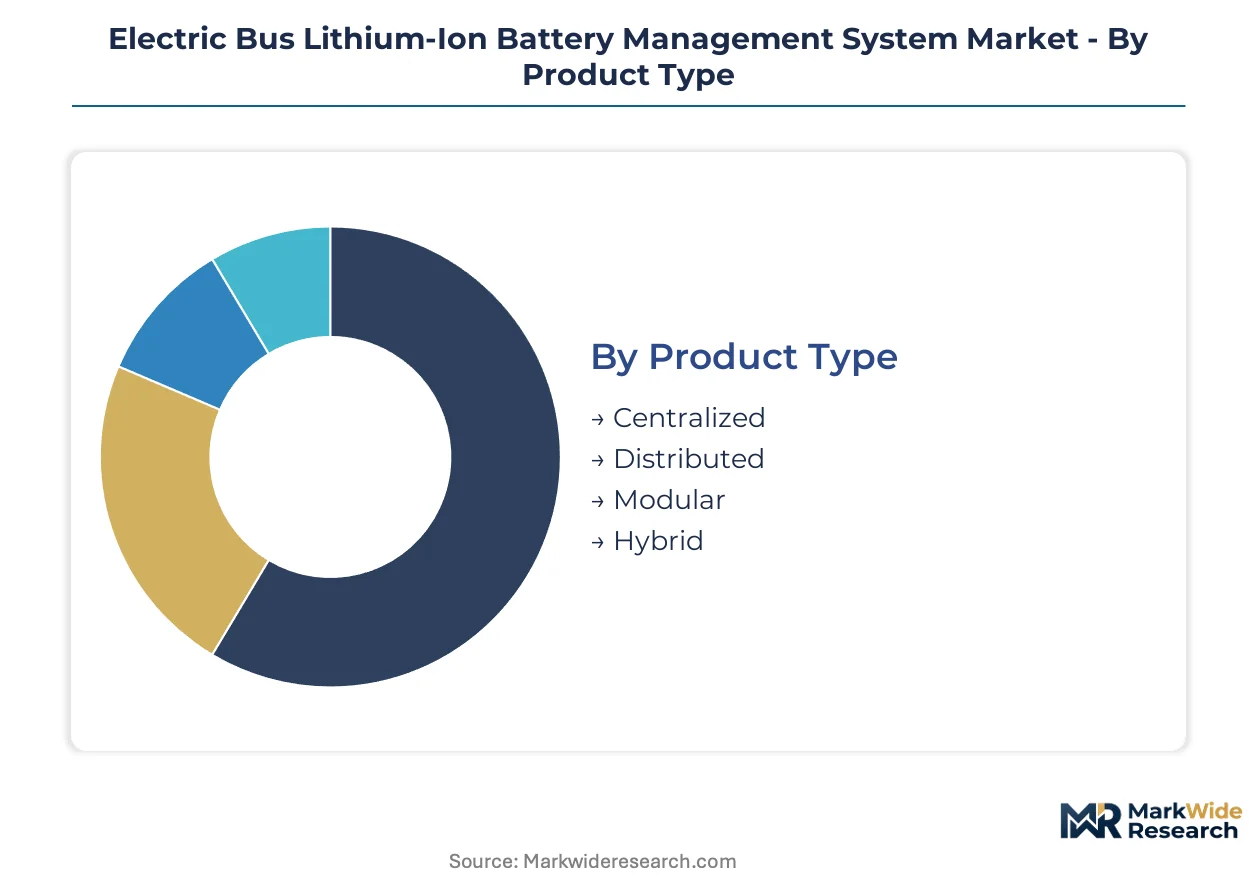
Bus electrification programs impose divergent technical requirements across duty cycles and fleet ownership models. Segmentation reveals where controller architectures, balancing technologies, and procurement channels concentrate investment and margin capture.
Product Type:
Mature centralized designs coexist with emerging distributed architectures as wiring weight and fault isolation priorities reshape platform engineering.
- Distributed:Per-module controllers with isolated CAN bus communication reduce harness mass by 8-12 kg in double-decker configurations. Shenzhen's full-electric fleet procurement specifications favor this topology for 600 kWh-plus packs operating in subtropical thermal conditions.
- Centralized:Single master controller with cell monitoring unit daisy chains dominates retrofit deployments and cost-constrained municipal tenders. European integrators specify this architecture for mid-life depot upgrades where wiring replacement is prohibitive.
- Modular:Swappable controller nodes enable pack-level repair without full system replacement. Demand concentrates in Indian PLI scheme corridors where Gujarat-based assemblers prioritize serviceability.
- Hybrid:Master-slave configurations with zone-based intelligence balance cost and granularity. Korean cell-BMS integrators deploy this for articulated bus platforms requiring asymmetric load management.
Distributed architectures handle the majority of new platform throughput; modular designs are climbing the fastest on share as serviceability clauses tighten in Asian tenders.
Application:
Volume concentration follows fleet electrification mandates with divergent duty cycle severity and charging infrastructure access.
- Public Transport:High-frequency urban routes with 18-22 hour daily utilization demand predictive thermal algorithms and 15-year cycle life guarantees. Guangdong Province procurement benchmarks set firmware requirements for adjacent Chinese provinces.
- School Buses:Predictable morning-afternoon duty cycles with extended midday dwell periods suit simplified passive balancing and depot charging. California's zero-emission school bus program aggregates specification leverage through unified telematics mandates.
- Shuttle Services:Airport and corporate campus loops with moderate range requirements prioritize cost-optimized voltage monitoring over active balancing.
- Freight Transport:Heavy-duty depot-to-depot routes with opportunity charging stress cell chemistry uniformity and require enhanced state-of-charge estimation precision.
Public transport absorbs dominant procurement volumes; school buses are expanding most quickly as US federal funding eligibility accelerates fleet conversion timelines.
End User:
Customer concentration shifts from fragmented depot purchasing toward consolidated procurement desks with unified specification authority.
- Fleet Operators:Multi-depot electrification programs aggregate volumes across 50-200 vehicle deployments, creating leverage for integrated BMS-battery pack sourcing. New York MTA and Los Angeles Metro tender structures lock out standalone controller vendors lacking long-term warranty capacity.
- Municipalities:City-owned transit agencies with federal funding eligibility requirements standardize on GB/T 31485 or ISO 26262 ASIL-D certified systems. Chinese MIIT enforcement of nail penetration protocols shapes firmware investment priorities.
- Logistics Companies:Private depot operators with captive maintenance capabilities favor modular architectures enabling in-house cell replacement.
- Private Transport Services:Charter and tour operators with variable route profiles specify adaptive thermal management over fixed-coefficient cooling designs.
Fleet operators command the steepest expansion trajectory; municipalities retain dominant installed base share through legacy procurement frameworks.
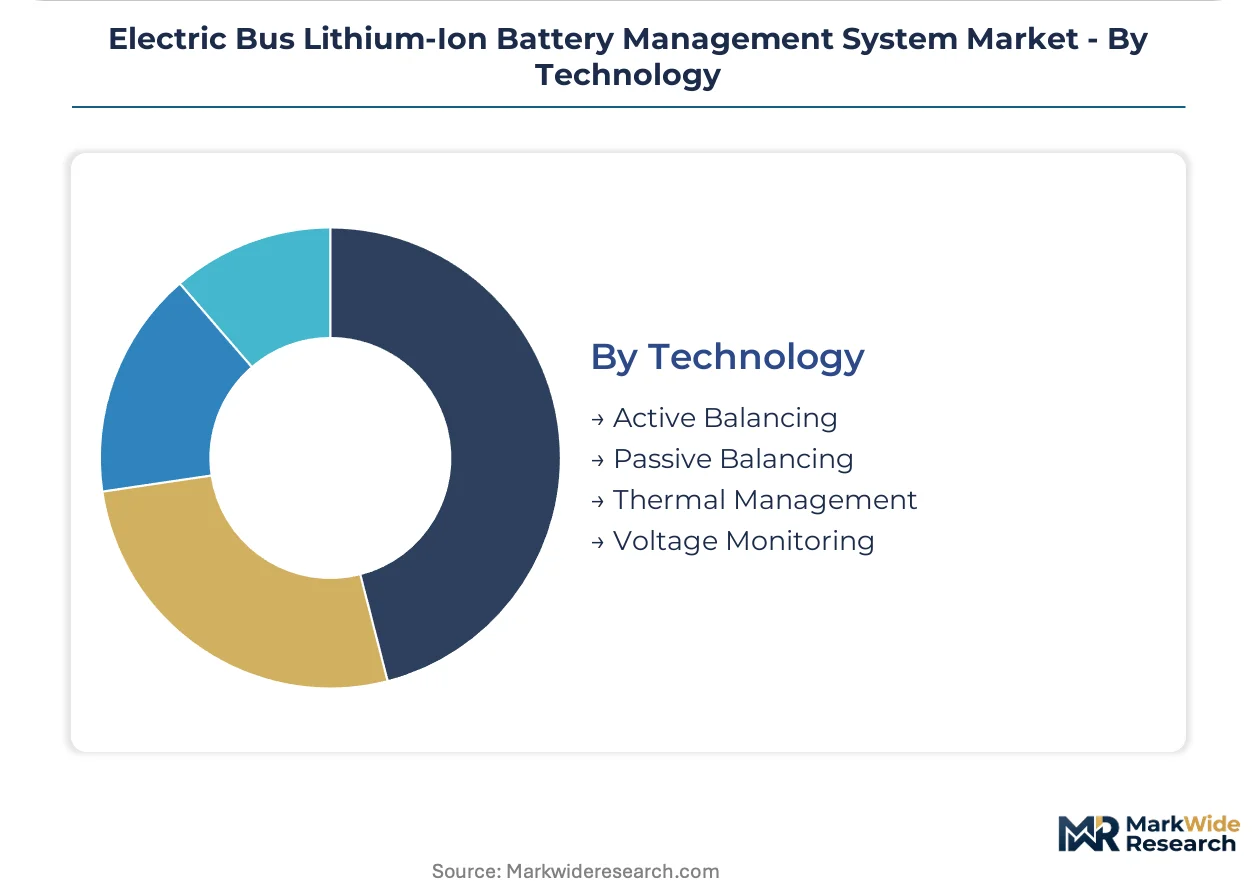
Technology:
Margin pools concentrate where operators prioritize range recovery and thermal precision over baseline monitoring functionality.
- Active Balancing:Inductive and capacitive charge transfer circuits recover 8-12% additional range per cycle versus passive dissipation. Specifications in Guangzhou and Shenzhen tenders explicitly favor inductive topologies for high-utilization routes.
- Thermal Management:Dielectric immersion cooling and engineered fluid loops integrate directly with BMS logic under EU F-Gas Regulation phase-down requirements. German and French transit authorities mandate recalibrated temperature mapping algorithms for alternative coolants.
- Passive Balancing:Resistor-based cell equalization dominates cost-optimized school bus and shuttle deployments with lower cycle frequency.
- Voltage Monitoring:Precision sensing arrays with <5 mV accuracy underpin all BMS architectures but generate thinner margins as commoditization advances.
Active balancing captures premium pricing tiers; thermal management is gaining share fastest as fluid regulation redesigns cooling system specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream cathode precursor output concentrates in Korean industrial corridors, while BMS controller assembly clusters in Chinese coastal manufacturing zones. European thermal management qualification requirements and Indian localization mandates are redistributing downstream value capture across three continents.
China
Shenzhen's full-electric bus fleet exceeds 16,000 vehicles, establishing procurement benchmarks that Guangdong Province transit agencies replicate. MIIT enforces GB/T 31485 nail penetration protocols that shape firmware development priorities for domestic suppliers. The Yangtze River Delta corridor hosts cell-BMS integration facilities serving BYD and CATL contract manufacturing networks.
Germany
Transit operators in Berlin and Hamburg aggregate electrification tenders requiring 15-year cycle life guarantees and ISO 26262 ASIL-D certification. The KBA enforces UNECE R100 battery safety standards that constrain BMS fault isolation architecture designs. Bavaria-based automotive electronics suppliers are repurposing passenger vehicle BMS platforms for MAN and Mercedes-Benz bus divisions.
United States
California's zero-emission bus program consolidates procurement through unified telematics mandates that lock out standalone controller vendors. The EPA's Clean School Bus Program allocates $5 billion toward electrification, accelerating active balancing specifications in New York and Los Angeles Metro tenders. The Pacific Northwest corridor hosts charging infrastructure-BMS interoperability development for Proterra and New Flyer platforms.
India
Gujarat and Tamil Nadu production corridors attract PLI scheme incentives for cell manufacturing, creating captive demand for domestically assembled BMS controllers. The CEA battery storage directives mandate dual certification paths for suppliers serving state transport corporation tenders. Delhi-NCR operators specify modular BMS architectures enabling in-house pack repair to reduce lifecycle costs.
South Korea
LG Chem and Samsung SDI anchor high-nickel cathode supply through dedicated domestic production lines, controlling upstream NCM precursor pricing. The MFDS enforces battery safety testing protocols that extend product validation timelines for export-bound systems. The Seoul Capital Area hosts R&D facilities developing wireless cell monitoring for next-generation articulated bus platforms.
Electric Bus Lithium-Ion Battery Management System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in voltage sensing and balancing circuit supply. The vendor base stratifies across three tiers: captive cell-BMS integrators, independent controller developers, and charging infrastructure specialists extending into power electronics. Korean conglomerates and European automotive suppliers represent distinct strategic archetypes. Competitive moves concentrate on backward integration into cathode materials and firmware talent acquisition through automotive hub relocation.
Among Korean-based conglomerates, Samsung SDI Co., Ltd. and LG Chem Ltd. exemplify captive integration archetypes controlling upstream chemistry supply. ABB Ltd. occupies a position bridging power electronics and charging infrastructure interoperability. Johnson Matthey PLC represents the materials-science pathway into BMS-adjacent thermal and electrochemical systems. These anchors illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| AVL List GmbH |
| Johnson Matthey PLC |
| Samsung SDI Co., Ltd. |
| Eberspaecher Vecture Inc. |
| Nuvation Energy Ltd. |
| LG Chem Ltd. |
| Lithium Balance A/S |
| Renesas Electronics Corporation |
| ABB Ltd. |
| Others |
Supply Flow & Price Mechanics
Cobalt and nickel price volatility determines both pricing tier spreads and supply chain shape across electric bus lithium-ion battery management systems, compressing pack-level margins for European and North American integrators while Korean cathode suppliers capture upstream pricing power through NCM precursor concentration.
Pricing Analysis
China's GB/T 31485 nail penetration protocols dictate the pricing tier structure across controller architectures, separating ASIL-D certified systems with predictive thermal algorithms from baseline voltage monitoring units. Premium-mid-economy pricing differentiation tracks firmware complexity and active balancing circuit inclusion, with fleet operators in Guangdong Province least sensitive to unit cost given 15-year total cost of ownership frameworks. Cost compression in centralized architectures intensifies as Indian PLI scheme localization mandates force price repositioning for modular serviceable designs. Municipal transit agencies with federal funding eligibility exhibit highest price sensitivity, prioritizing standardized telematics platforms over feature depth.
Supply Chain Analysis
High-nickel cathode precursor output concentrates in South Korea, China, and Japan, with LG Chem and Samsung SDI controlling upstream NCM pricing that feeds into cell-BMS integration facilities. Controller assembly draws from Yangtze River Delta manufacturing corridors for sensing arrays and switching circuitry, while dielectric immersion cooling fluids hinge on EU F-Gas Regulation phase-down timelines. Single-source vulnerability runs through Korean cathode supply concentration for European integrators lacking captive chemistry positions. Distribution runs through integrated battery pack suppliers serving consolidated fleet operator procurement desks, displacing standalone controller vendors from multi-depot electrification tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric bus lithium-ion battery management system procurement is recovering from certification backlog delays, with China's MIIT enforcement of GB/T standards and India's PLI scheme localization creating cyclical demand inflection points across Asia-Pacific production corridors.
For Market Incumbents: Pre-empt firmware talent scarcity by relocating state-estimation algorithm development to automotive electronics hubs in Bavaria and Seoul, while securing captive cathode supply positions through joint ventures with Korean NCM precursor producers. Cell-to-pack architectural shifts threaten module-level controller vendors with hardware content compression, requiring investment in zone-based intelligence and wireless cell monitoring to defend specification relevance.
For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu PLI scheme corridors by assembling domestically certified controllers for state transport corporation tenders, leveraging modular serviceability requirements that incumbent integrated suppliers underserve. California's zero-emission school bus program offers the most penetrable segment, with simplified passive balancing specifications and unified telematics mandates that lower firmware complexity barriers for new suppliers.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward thermal management specialists with dielectric immersion cooling capabilities and recalibrated BMS temperature mapping algorithms. Long-term viability centers on suppliers capable of bridging 15-year cycle life guarantees with usage-based service contract structures. The signal to watch is wireless cell monitoring adoption rates in double-decker and articulated bus platforms, indicating architectural transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Korean NCM precursor control secures upstream cost positions for cell-BMS integrators serving Guangdong fleet tenders. |
| Firmware Talent Acquisition in Automotive Hubs | Relocation to Bavaria and Seoul addresses electrochemical modeling expertise scarcity for state-of-charge prediction algorithms. |
| Dielectric Immersion Cooling Qualification | EU F-Gas Regulation compliance opens specification windows with German and French transit authorities requiring recalibrated thermal logic. |
| Wireless Cell Monitoring Development | 12-15% wiring weight reduction enables penetration of double-decker platforms in Shenzhen and London electrification programs. |
| Modular Controller Assembly in India | PLI scheme localization in Gujarat and Tamil Nadu captures captive demand from state transport corporation serviceability mandates. |
Methodological Framework
A standing panel of BMS platform engineers, fleet procurement directors at municipal transit agencies, cathode materials procurement leads, and thermal management system designers provided ongoing calibration across primary interview cycles. Secondary validation incorporated MIIT GB/T standard filings, CEA battery storage directive publications, EU F-Gas Regulation implementation timelines, and PLI scheme beneficiary disclosures from India's Ministry of Heavy Industries. Bottom-up unit economics from controller bill-of-materials analysis triangulated against top-down fleet electrification procurement forecasts across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, application duty cycle, end-user procurement consolidation stage, and balancing technology architecture throughout the forecast period. CAGRs derived from installed base replacement curves and new platform penetration rates, with cell-to-pack adoption elasticity and active balancing specification intensity serving as key demand-side inputs alongside charging infrastructure deployment schedules.
Sensitivities concentrate around Korean cathode supply disruption, GB/T certification timeline extensions, and F-Gas Regulation phase-down acceleration. Forecasts reflect assumptions regarding fleet operator consolidation velocity and wireless monitoring technology maturation. Cross-checking against Shenzhen and Guangzhou municipal tender award data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Global Power Management System Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
North America Battery Energy Storage System Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Distributed Energy Storage System Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Electric Two-Wheeler Lithium-Ion Battery Management System Market
Battery Management System
North America Battery Management System Market
Battery Management System
Energy Storage Systems Market
Battery Management System
DC Coupled Solar Battery System Market