
 Global Pharmacogenetics Testing in Psychiatry/Depression Market | 2026-2036
Global Pharmacogenetics Testing in Psychiatry/Depression Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacogenetics Testing in Psychiatry/Depression Market Foresight
North American reference laboratory networks is repositioning toward psychiatric pharmacogenetics as a standardized care protocol. Myriad Genetics leverages its hereditary cancer infrastructure to anchor psychiatric testing workflows. GeneSight competes through proprietary combinatorial pharmacogenomic algorithms that integrate multiple gene variants.
Pharmacogenetics testing in psychiatry evaluates patient-specific genetic variations affecting drug metabolism, receptor binding, and therapeutic response to antidepressants and mood stabilizers; assays typically analyze CYP2D6, CYP2C19, SLC6A4, and HTR2A polymorphisms using PCR-based genotyping or next-generation sequencing platforms to guide clinician selection of psychiatric medications and dosing regimens. Genotyping and targeted gene panels dominate current test volumes due to lower cost and faster turnaround, while whole genome sequencing occupies emerging niches where complex polygenic interactions require deeper interrogation. Hospital-based services and in-lab testing capture the majority of revenue, though mobile health platforms represent the fastest-growing delivery format as telepsychiatry expands access.
The FDA pharmacogenomic biomarker table and EMA's pharmacogenomic guideline framework shape product development priorities and clinical claim substantiation for test developers seeking market access. ISO 15189 accreditation requirements for clinical laboratories performing psychiatric pharmacogenetics ensure quality standards that influence provider trust and payer reimbursement decisions. Stakeholders must monitor evolving CMS coverage determinations and state-level genetic counselor scope-of-practice laws that will determine whether testing scales through specialist psychiatrists or decentralizes to primary care.
Market Dynamics
The FDA's pharmacogenomic biomarker table expansion is compressing development timelines for test developers while simultaneously raising the evidentiary bar for clinical claims substantiation.
Growth Catalysts
- Medicare coverage expansion:CMS reimbursement decisions for pharmacogenetic testing in depression management have broadened payer access across outpatient psychiatric services in the United States.
- EMA pharmacogenomic guideline framework:European harmonization of biomarker validation standards accelerates cross-border test commercialization and mutual recognition procedures.
- Telepsychiatry platform integration:Mobile health delivery formats connect rural and underserved patient populations to pharmacogenetics-enabled prescribing workflows.
Market Restraints
- Reagent supply concentration:PCR master mix and NGS library preparation kits depend on a limited supplier base concentrated in North American and European manufacturing clusters.
- State-level genetic counselor scope restrictions:Variability in licensure laws across US jurisdictions limits test ordering authority and creates compliance fragmentation.
- Alternative biomarker modalities:Proteomic and metabolomic companion diagnostics for antidepressant selection compete for limited payer budget allocation.
Strategic Opportunities
- Primary care penetration:Underpenetrated US family medicine and internal medicine practices represent expansion targets for decentralized pharmacogenetics ordering.
- Polygenic risk score integration:Convergence of combinatorial pharmacogenomic algorithms with whole-genome background risk stratification enables next-generation test panels.
- Japan's PMDA biomarker qualification pathway:Streamlined regulatory routes for psychiatric pharmacogenetic claims create first-mover advantages in East Asian markets.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories face recruitment gaps for variant interpretation specialists capable of navigating CYP450 allele nomenclature complexity.
- ISO 15189 accreditation timelines:Quality management system implementation for psychiatric pharmacogenetics extends 12-18 months before operational launch.
- EHR integration complexity:Discrete genetic result reporting into electronic health records requires custom interface development with legacy psychiatric practice management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacogenetics Testing in Psychiatry/Depression Market |
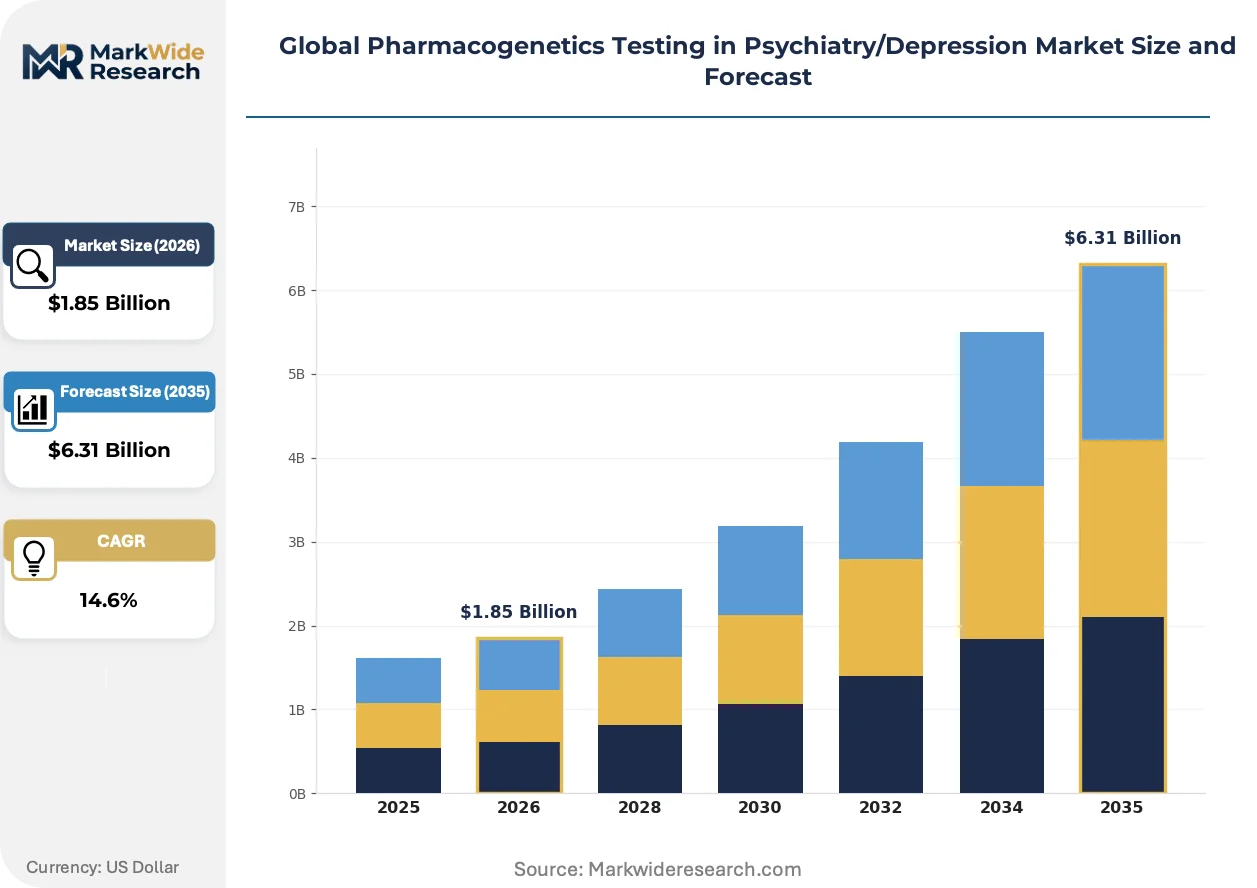
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Genotyping, Phenotyping, Whole Genome Sequencing, Targeted Gene Panels Application Area: Major Depressive Disorder, Bipolar Disorder, Anxiety Disorders, Drug Response Prediction End User: Psychiatrists, Clinical Laboratories, Research Institutes, Genetic Counselors Delivery Format: In-Lab Testing, Direct-to-Consumer Kits, Hospital-Based Services, Mobile Health Platforms |
| Companies Covered | Genomind, GeneSight, CNSDose, Myriad Genetics, Invitae Corporation, QIAGEN, Thermo Fisher Scientific, Illumina, GeneDx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacogenetics Testing in Psychiatry/Depression Market Shifts & Advancements
Next-generation sequencing platforms are compressing per-sample costs while expanding the variant spectrum interrogated beyond core CYP450 genes, fundamentally altering competitive positioning among test developers.
Combinatorial pharmacogenomic algorithms that integrate CYP2D6, CYP2C19, SLC6A4, and HTR2A polymorphisms into single interpretive scores is rewriting how psychiatrists prioritize antidepressant selection. Hospital-based clinical laboratories in the United States are adopting these integrated platforms at accelerating pace. The technology is compressing the competitive moat previously held by proprietary single-gene test developers.
REACH regulation evolution in Europe is tightening requirements for in vitro diagnostic material sourcing and clinical evidence documentation. Test developers must now demonstrate supply chain transparency for reagent components and maintain post-market surveillance registries. Psychiatric pharmacogenetics manufacturers with EU notified body relationships are restructuring quality management systems to accommodate expanded technical documentation obligations.
Telepsychiatry-enabled test ordering is displacing traditional referral pathways through hospital-based genetic counselors. Direct-to-clinician digital platforms now capture specimen logistics and result delivery for outpatient psychiatric practices. This channel shift concentrates most visibly in United States markets where payer coverage for remote psychiatric services has expanded through parity legislation implementation.
Global Pharmacogenetics Testing in Psychiatry/Depression Market Segmentation
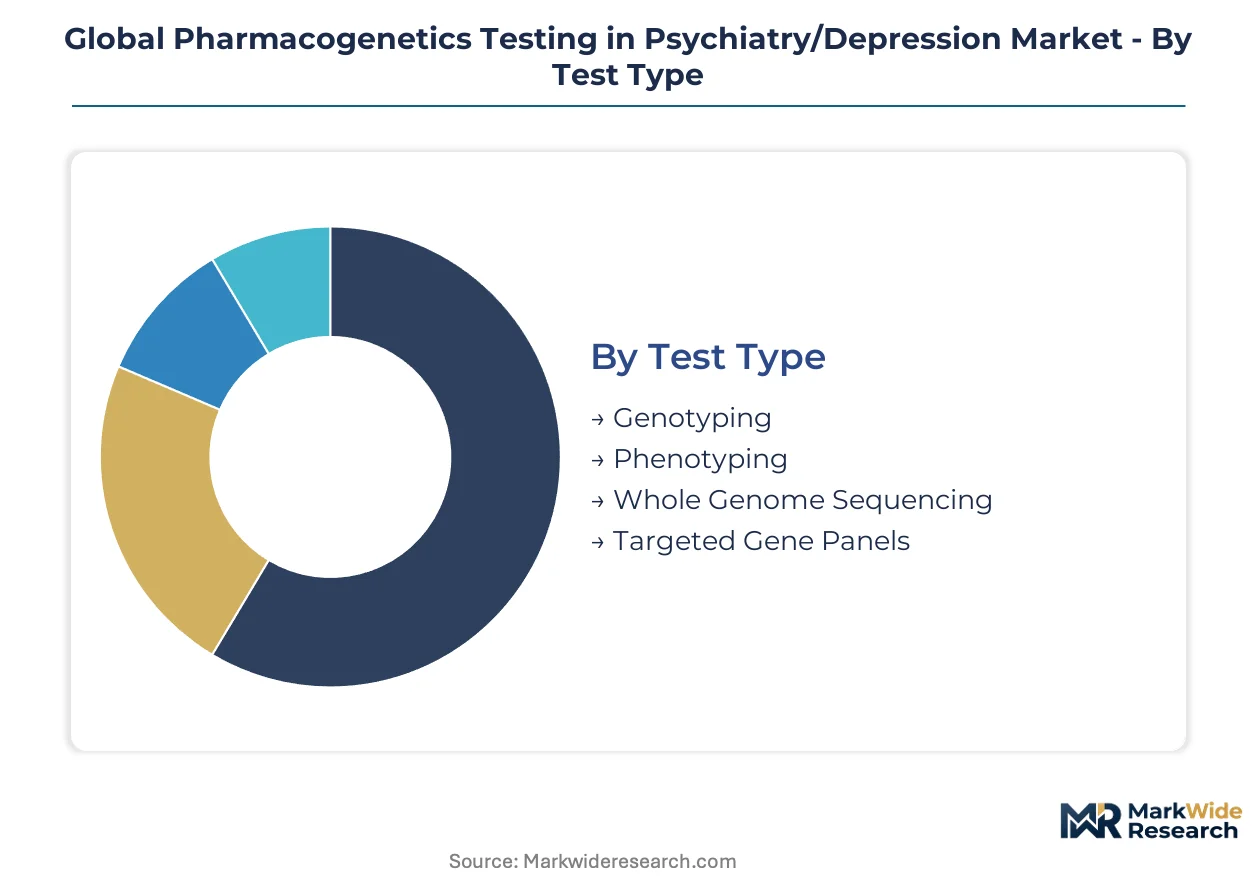
Pharmacogenetics testing in psychiatry fragments across technical methodologies, clinical indications, and delivery channels that each carry distinct regulatory burdens and reimbursement pathways. Test developers must align product architectures with specific certification requirements from FDA, EMA, and ISO frameworks to secure market access.
Test Type:
FDA pharmacogenomic biomarker table alignment and ISO 15189 accreditation requirements vary sharply across technical approaches, with PCR-based methods facing lower evidentiary hurdles than NGS platforms.
- Genotyping:PCR-based assays analyzing CYP2D6, CYP2C19, SLC6A4, and HTR2A polymorphisms dominate current test volumes through lower per-sample costs and 24-48 hour turnaround times. Clinical laboratories in the United States concentrate demand here as Medicare coverage decisions favor established single-gene indications over exploratory panels.
- Targeted Gene Panels:Combinatorial platforms integrating multiple pharmacogenomic variants into unified interpretive scores command premium pricing through proprietary algorithmic outputs. Hospital-based psychiatric services in the United States drive adoption as EHR integration capabilities improve prescriber workflow efficiency.
- Phenotyping:Functional metabolic characterization through probe drug administration provides direct enzyme activity measurement beyond genetic inference alone.
- Whole Genome Sequencing:Comprehensive variant interrogation occupies emerging niches requiring complex polygenic risk stratification beyond core CYP450 genes.
Leading the category by volume: Genotyping. Growing fastest: Targeted Gene Panels.
Application Area:
Diagnostic code specificity and payer coverage policies create tiered reimbursement landscapes across psychiatric indications, with depression management commanding the most mature evidence base.
- Major Depressive Disorder:The most validated application with extensive randomized trial evidence supporting pharmacogenetic-guided antidepressant selection. United States outpatient psychiatric practices generate concentrated demand as commercial insurers and Medicare expand coverage determinations for treatment-resistant depression protocols.
- Drug Response Prediction:Emerging applications predicting adverse event liability and therapeutic window optimization across multiple medication classes. Research institutes and academic medical centers in the United States and Europe drive early adoption through investigator-initiated studies.
- Bipolar Disorder:Mood stabilizer pharmacogenetics requires navigation of complex polypharmacy interactions and narrower therapeutic indices.
- Anxiety Disorders:SSRI and SNRI response prediction applications face sparser clinical evidence requirements for widespread payer acceptance.
Highest reimbursement certainty: Major Depressive Disorder. Steepest expansion trajectory: Drug Response Prediction.
End User:
Professional scope-of-practice regulations and ordering authority laws fragment market access across prescriber types, with state-level variability creating compliance complexity for test developers.
- Clinical Laboratories:Reference laboratory networks and hospital-based services capture the majority of revenue through centralized testing infrastructure and established payer contracts. North American laboratory networks are repositioning toward psychiatric pharmacogenetics as standardized care protocols.
- Psychiatrists:Specialty prescribers represent the core ordering constituency with direct patient management authority and established therapeutic relationships. United States psychiatrists drive volume through integrated EHR ordering workflows and telepsychiatry platform adoption.
- Genetic Counselors:State-level licensure restrictions limit test ordering authority across United States jurisdictions, creating access fragmentation.
- Research Institutes:Academic and commercial research applications support biomarker discovery and algorithm validation outside reimbursed clinical care.
Dominant revenue concentration: Clinical Laboratories. Gaining share fastest: Psychiatrists through direct digital platform access.
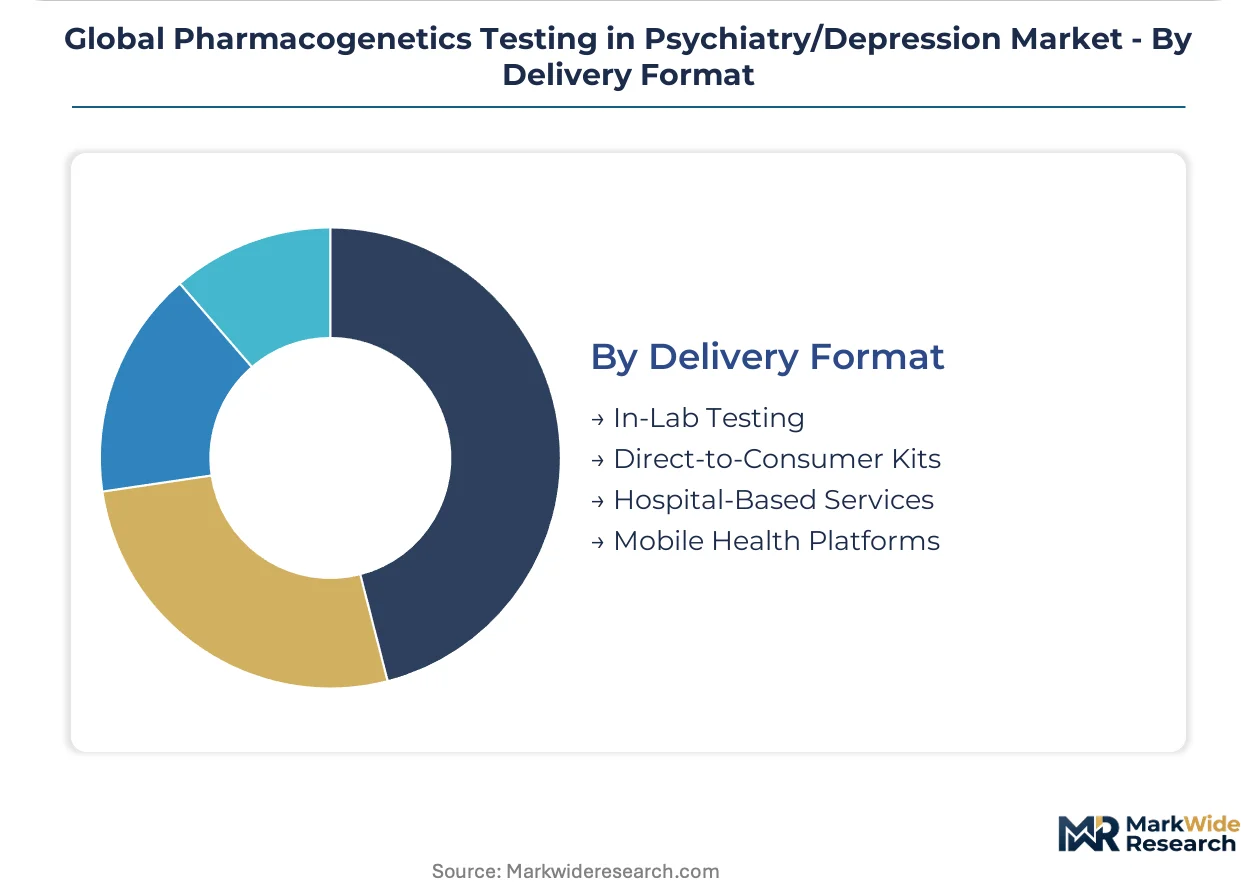
Delivery Format:
Channel economics and patient access requirements are compressing traditional hospital-based models toward decentralized and remote-enabled formats.
- Hospital-Based Services:Integrated clinical laboratory infrastructure within psychiatric inpatient and outpatient settings maintains quality control advantages and established referral relationships. United States health systems concentrate investment here as value-based care contracts incentivize standardized prescribing protocols.
- Mobile Health Platforms:Telepsychiatry-enabled test ordering and result delivery connects rural and underserved populations to pharmacogenetics-enabled prescribing. United States markets show fastest expansion through parity legislation implementation and remote service reimbursement expansion.
- In-Lab Testing:Centralized reference laboratory processing maintains cost efficiencies through volume consolidation and automated workflow integration.
- Direct-to-Consumer Kits:Patient-initiated testing faces regulatory constraints from FDA oversight and limited prescriber integration pathways.
Current revenue anchor: Hospital-Based Services. Expanding most quickly: Mobile Health Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Genetic reagent manufacturing clusters in Massachusetts and California anchor North American supply chains for psychiatric pharmacogenetics, while precision medicine hubs in Basel-Tokyo-Boston corridors concentrate test development expertise.
United States
Medicare coverage expansion and commercial insurer reimbursement policies drive outpatient psychiatric adoption of pharmacogenetic testing. FDA pharmacogenomic biomarker table updates validate gene-drug interactions for antidepressant selection. The Greater Boston corridor hosts concentrated clinical laboratory networks repositioning toward standardized psychiatric care protocols.
Germany
EMA pharmacogenomic guideline harmonization accelerates cross-border test commercialization through mutual recognition procedures. REACH regulation evolution tightens in vitro diagnostic material sourcing requirements for reagent components. The Rhine-Main biotech cluster in Frankfurt-Heidelberg anchors quality management system implementation for EU market access.
Japan
PMDA biomarker qualification pathways create streamlined regulatory routes for psychiatric pharmacogenetic claims in East Asian markets. METI precision medicine initiatives fund pharmacogenomics integration into national health technology assessment frameworks. The Kanto region around Tokyo concentrates hospital-based clinical laboratory adoption of combinatorial pharmacogenomic platforms.
United Kingdom
NHS England genomic medicine service expansion incorporates pharmacogenetics into mental health treatment pathways with defined commissioning frameworks. MHRA recognition of FDA pharmacogenomic biomarkers accelerates parallel market authorization timelines. The Cambridge-London corridor anchors academic medical center research validating polygenic risk score applications for antidepressant response prediction.
Australia
TGA pharmacogenetic test regulation through in vitro diagnostic medical device frameworks shapes commercialization requirements for depression management applications. Medicare Benefits Schedule review processes determine reimbursement eligibility for psychiatrist-ordered testing. The Melbourne-Sydney biomedical corridor concentrates telepsychiatry platform development connecting rural populations to pharmacogenetics-enabled prescribing workflows.
Global Pharmacogenetics Testing in Psychiatry/Depression Market Competitive Landscape
Global majors compete with regional champions across algorithm development and laboratory infrastructure deployment. The vendor base stratifies into three tiers: integrated reference laboratory networks, specialized pharmacogenetic test developers, and platform technology suppliers. Two strategic archetypes dominate—proprietary algorithm specialists leveraging combinatorial pharmacogenomic scoring, and diversified genomic service providers extending hereditary cancer infrastructure into psychiatric applications. Competitive moves concentrate on EHR integration partnerships and telepsychiatry platform alliances.
Among specialized pharmacogenetic developers, GeneSight and Genomind exemplify the proprietary algorithm tier, while Myriad Genetics occupies a position representing diversified genomic service providers extending infrastructure across therapeutic areas. Thermo Fisher Scientific and QIAGEN anchor the platform technology supplier segment, supplying PCR master mixes and NGS library preparation kits that underpin test workflows.
| Leading Market Players |
|---|
| Genomind |
| GeneSight |
| CNSDose |
| Myriad Genetics |
| Invitae Corporation |
| QIAGEN |
| Thermo Fisher Scientific |
| Illumina |
| GeneDx |
| Others |
Supply & Pricing Matrix
Bioinformatics variant interpretation specialists concentrated in the Greater Boston and San Francisco Bay Area corridors command wage premiums that compress pricing-tier spreads between economy genotyping assays and premium combinatorial algorithm platforms. Labor-cost differentials between these talent clusters and secondary metropolitan markets directly shape how test developers structure service bundling and warranty terms across product tiers.
Pricing Analysis
Warranty and interpretive report bundling separates premium-priced combinatorial pharmacogenomic algorithms from unbundled economy genotyping services. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade—ISO 15189-accredited laboratories command 15-25% premiums over non-accredited competitors. Cost compression in economy PCR-based assays is intensifying because Medicare coverage decisions favor established single-gene indications over exploratory panels. Hospital-based psychiatric services show least price sensitivity due to value-based care contract incentives, while independent clinical laboratories face acute margin pressure from reference laboratory network consolidation.
Supply Chain Analysis
Dual-sourcing requirements for PCR master mixes and NGS library preparation kits mandate multi-supplier qualification across Thermo Fisher Scientific and QIAGEN manufacturing footprints. Reagent manufacturing concentrates in Massachusetts, California, and the Basel-Tokyo corridor. Raw material dependencies span oligonucleotide synthesis reagents, fluorescent probes, and polymerase enzymes. Single-source vulnerability in semiconductor-dependent sequencing instrumentation creates supply chain risk. Distribution runs through centralized reference laboratory networks with specimen logistics partnerships extending to outpatient psychiatric practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over proprietary combinatorial algorithms and EHR integration layers determines pricing power. Players are pursuing downstream leverage through direct-to-clinician digital platforms that displace traditional genetic counselor referral pathways.
For Market Incumbents: Hedge against algorithm commoditization by deepening in-house production of interpretive software and securing exclusive EHR integration partnerships with major psychiatric practice management system vendors. Capacity addition in telepsychiatry-enabled mobile health platforms defends against emerging entrants leveraging remote service reimbursement expansion. Certification investment in Japan's PMDA biomarker qualification pathway creates geographic optionality. For New Entrants and Emerging Players: The price-point gap between GeneSight's premium combinatorial platforms and economy genotyping services creates white-space opportunity in mid-market targeted gene panels. Primary care penetration in underpenetrated US family medicine practices offers the most penetrable segment given state-level scope-of-practice variability limits genetic counselor ordering authority. Go-to-market through telepsychiatry platform alliances bypasses traditional hospital-based laboratory contracting barriers. For Investors and Strategic Acquirers: Re-rating potential sits with diversified genomic service providers extending hereditary cancer infrastructure into psychiatric applications given Medicare coverage expansion catalysts. Long-term viability hinges on consolidation of algorithm development capabilities with clinical laboratory networks possessing ISO 15189 accreditation and established payer contracts. The signal to watch is CMS coverage determinations for polygenic risk score applications as inflection indicator for next-generation test panel adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Patent Portfolio Expansion | Combinatorial pharmacogenomic scoring IP creates defensible moats against PCR-based commoditization. |
| EHR Integration Partnership | Direct result reporting into Epic and Cerner psychiatric modules streamlines prescriber workflow adoption. |
| Telepsychiatry Platform Alliance | Mobile health delivery formats capture rural patient access through parity legislation implementation. |
| ISO 15189 Accreditation Investment | Quality management certification unlocks Medicare reimbursement and hospital system contracting eligibility. |
| PMDA Biomarker Qualification Filing | Japan's streamlined regulatory route creates first-mover positioning in East Asian psychiatric pharmacogenetics. |
Research Methodology
Multi-period observation of FDA pharmacogenomic biomarker table expansions, CMS coverage determination timelines, and EMA guideline framework evolutions anchored the trend analysis, supplemented by interviews with laboratory directors at North American reference networks, psychiatric prescribers in hospital-based and telemedicine settings, genetic counselors navigating state licensure variability, and payer medical policy leads at major commercial insurers. Secondary validation drew from FDA 510(k) filings, Clinical Laboratory Improvement Amendments certification databases, CMS National Coverage Determination records, and ISO 15189 accreditation registries. Bottom-up test volume modeling and top-down market sizing triangulated demand estimates.
Segment-weighting across test type, application area, end user, and delivery format dimensions structured the analytical framework. CYP450 genotyping volumes, combinatorial algorithm adoption rates, and telepsychiatry platform penetration curves were modeled across the projection horizon. CAGRs derived from logistic diffusion curves calibrated to historical biomarker adoption patterns in companion diagnostics. Pricing trajectories incorporated Medicare fee schedule evolution and commercial insurer medical policy update frequencies.
Inputs from FDA, CMS, and EMA regulatory filings were available through the study window; gaps in real-time telepsychiatry platform transaction data introduce uncertainty bands around mobile health delivery format projections. Forecasts reflect assumptions regarding payer coverage expansion continuity and state-level genetic counselor scope-of-practice liberalization. Deviation in CMS National Coverage Determination timelines for polygenic risk score applications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Microarray Analysis Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Reproductive Genetics Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
DNA Sequencing Services Market
Genomics
Genomics Personalized Health Market
Genomics
DNA Diagnostics Market
Genomics
United States Cancer Biomarkers Market
Genomics
Spatial OMICS Market
Genomics
Plant Genomics Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Latin America Gene Expression Market
Genomics
Genetic Testing Market
Genomics
North America DNA Sequencing Products Market
Genomics
Genetic Material Market