
 In-Vehicle AI Robot Market | 2026-2036
In-Vehicle AI Robot Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vehicle AI Robot Market Intelligence
The EU Green Deal's embedded carbon tracking mandate is recalibrating how automakers specify in-vehicle compute hardware. NVIDIA sustains technology leadership through its DRIVE platform architecture and silicon design for automotive AI workloads. Tesla dominates consumer-facing deployment with its Full Self-Driving neural networks and over-the-air update infrastructure. BMW differentiates through premium cabin experience integration, leveraging gesture recognition and natural language interfaces across its vehicle lineup.
An in-vehicle AI robot is an electromechanical or software-agent system installed within automotive architectures to perceive cabin environments, process occupant inputs through multimodal sensors, and execute physical or digital responses. These systems typically integrate LiDAR or camera arrays, edge-computing processors, and servo-actuated components to enable autonomous interaction with passengers. Machine Learning and Computer Vision segments lead current revenue generation, with Natural Language Processing exhibiting the fastest trajectory as conversational interfaces penetrate mid-range vehicle tiers. Embedded Systems command the largest integration-level share, though Cloud-Connected architectures are capturing margin pools through subscription-based feature monetization.
NHTSA in the United States, EMA and EU AI Act frameworks in Europe, and MIIT standards in China collectively govern safety validation, data privacy, and algorithmic transparency for automotive AI systems. These bodies mandate crashworthiness testing for robotic components, restrict biometric data retention, and require explainability in autonomous decision pathways. Stakeholders must monitor diverging certification timelines across jurisdictions to avoid platform fragmentation and redundant engineering cycles.
Market Dynamics
Passenger vehicle OEMs face intensifying pressure from the EU AI Act's algorithmic transparency mandates and NHTSA's evolving autonomous system guidance, forcing simultaneous redesign of hardware architectures and software validation pipelines.
Growth Catalysts
- EU AI Act Certification Requirements:Mandatory explainability standards for autonomous decision pathways are accelerating investment in interpretable machine learning frameworks across European vehicle programs.
- Edge Computing Hardware Maturation:Automotive-grade SoCs now deliver sufficient TOPS for real-time multimodal inference without cloud dependency, enabling latency-critical cabin interaction.
- China MIIT Standards Harmonization:Unified national protocols for in-vehicle AI safety validation are reducing regional fragmentation and streamlining OEM platform deployment.
Market Restraints
- LiDAR Sensor Cost Volatility:Automotive-grade solid-state LiDAR modules remain supply-constrained from specialized foundry capacity in Taiwan and South Korea.
- Biometric Data Retention Limits:GDPR and emerging state-level US privacy statutes restrict longitudinal occupant behavior datasets, constraining training data accumulation.
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance for robotic actuators extends development cycles by 18-24 months versus non-safety-critical cabin electronics.
Strategic Opportunities
- Commercial Fleet Retrofit Segment:Last-mile delivery operators in Germany and the United States represent unserved demand for aftermarket AI cabin monitoring without full vehicle replacement.
- EU Green Deal Embedded Carbon Tracking:Mandated supply chain disclosure creates competitive differentiation for OEMs deploying low-carbon compute substrates in robot hardware.
- Natural Language Processing Convergence:Integration of large language models with edge-constrained automotive processors opens premium-tier feature democratization.
Industry Challenges
- Multimodal Sensor Fusion Expertise Gap:Shortage of engineers proficient in synchronizing LiDAR, camera, and radar inputs with real-time actuator control limits team scaling.
- Legacy Vehicle Bus Architecture Integration:CAN-FD and Ethernet backbone incompatibility with 15-year-old vehicle fleets complicates aftermarket deployment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vehicle AI Robot Market |
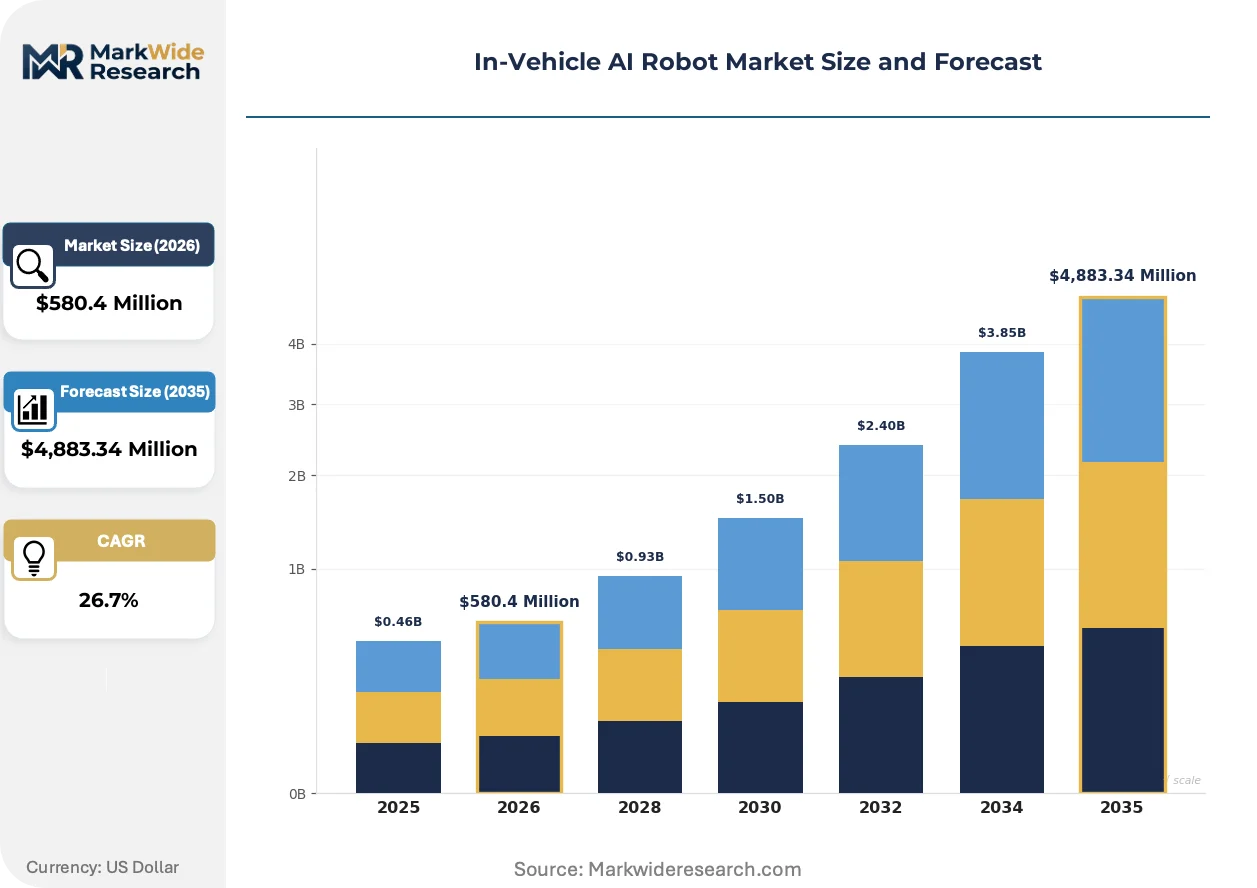
| Market Size in 2026 | $580.4 Million |
| Market Size in 2035 | $4,883.34 Million |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Product Type: Adaptive Cruise Control, Voice Assistants, Autonomous Navigation, Gesture Recognition End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Integration Level: Embedded Systems, Cloud-Connected, Standalone Units, Modular Solutions |
| Companies Covered | Tesla, Waymo, General Motors, NVIDIA, BMW, Baidu, Motional Inc., AutoX Inc., Zoox Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vehicle AI Robot Market Strategic Shifts & Innovations
Automotive AI architecture is bifurcating between centralized domain controllers and distributed edge nodes, with implications for hardware sourcing, software update cadence, and subscription revenue capture.
Generative AI inference at the edge is electrifying cabin interaction design. Transformer-based language models running on automotive SoCs enable contextual dialogue without cloud round-trips. Luxury OEMs in Germany and the United States are piloting these systems for 2026 model year deployment. The technology is electrifying competitive differentiation in premium segments while compressing feature parity timelines across mid-range tiers.
The EU AI Act's risk-based classification system is recalibrating validation protocols. High-risk in-robotic systems now require conformity assessment by notified bodies before market placement. European OEMs are restructuring quality assurance organizations to embed algorithmic auditing capabilities. This regulatory architecture most acutely affects computer vision-based occupant monitoring systems, where explainability requirements conflict with black-box neural network architectures.
Fleet operators are consolidating procurement around vertically integrated platform providers. Large commercial buyers in the United States now specify AI cabin systems as part of total cost of ownership calculations rather than discrete option packages. This behavior concentrates vendor selection power with three to four national fleet management companies. The shift is most visible in long-haul trucking, where driver monitoring mandates from the Department of Transportation accelerate standardization.
In-Vehicle AI Robot Market Segmentation
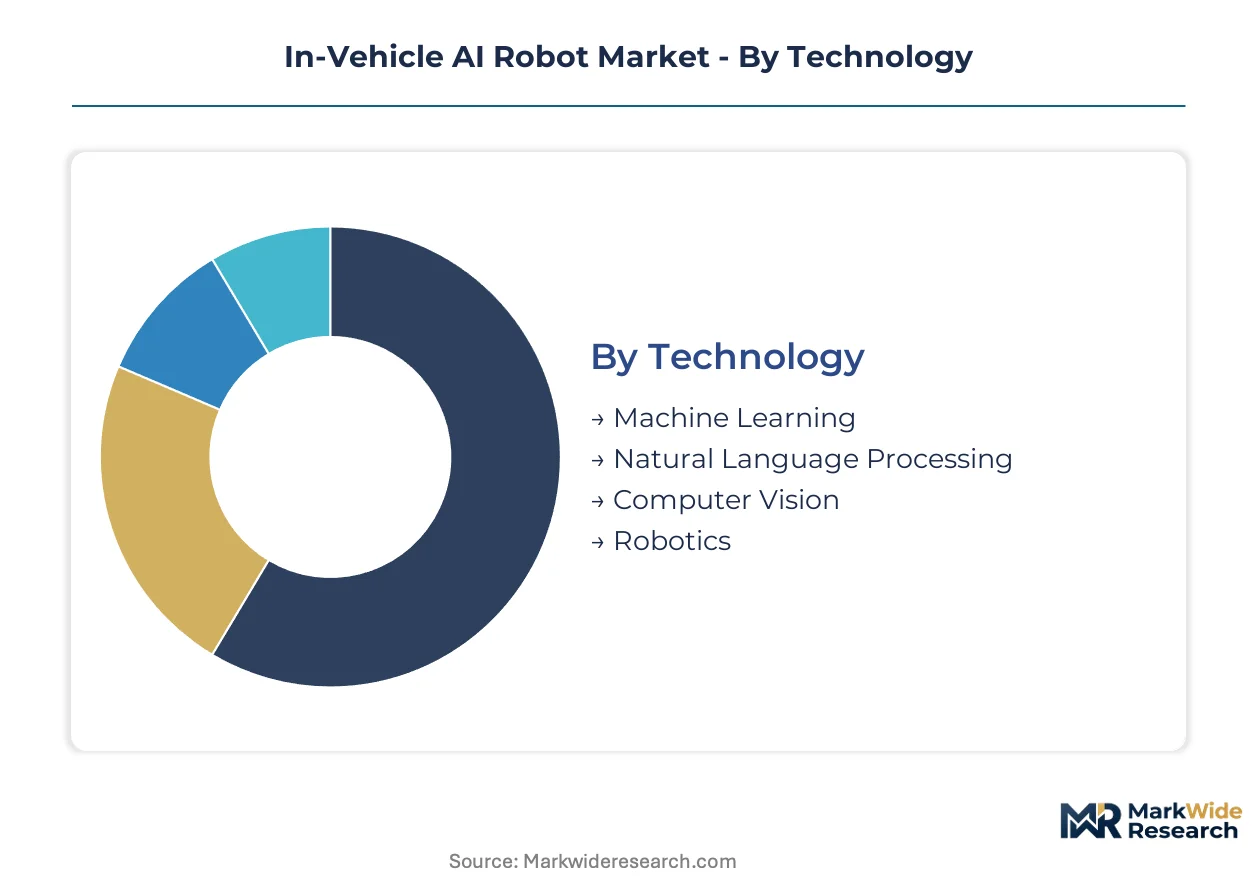
Segmentation in the In-Vehicle AI Robot Market reveals distinct certification pathways and margin profiles across technology tiers. Each category demands tailored regulatory navigation and supply chain configuration.
Technology:
ISO 26262 ASIL-D certification burdens vary sharply across technology segments, with computer vision systems facing the most intensive validation cycles due to real-time safety-critical outputs.
- Machine Learning:Neural network inference engines process multimodal sensor fusion for predictive cabin behavior modeling. Demand concentrates in German premium OEM programs where EU AI Act explainability mandates drive interpretable architecture investments.
- Natural Language Processing:Transformer-based dialogue systems enable occupant-command interpretation without cloud dependency. United States passenger vehicle deployments lead volume as NHTSA distraction-reduction guidelines favor voice-first interfaces.
- Computer Vision:Occupant monitoring and gesture recognition via camera-LiDAR fusion.
- Robotics:Servo-actuated physical agents for cabin manipulation tasks.
Leading the category by volume: Machine Learning. Growing fastest: Natural Language Processing.
Product Type:
Cost tier stratification separates premium integrated systems from economy-grade retrofit modules, with pricing spreads reflecting compute substrate grades and sensor array densities.
- Adaptive Cruise Control:Longitudinal vehicle control with AI-enhanced predictive braking. Aftermarket providers in the United States capture margin through fleet retrofit contracts where Department of Transportation safety mandates accelerate replacement cycles.
- Voice Assistants:Natural language cabin control with edge-constrained inference. OEMs in China dominate procurement volumes as MIIT standards harmonization reduces platform fragmentation across domestic vehicle programs.
- Autonomous Navigation:Path planning and obstacle avoidance for self-driving architectures.
- Gesture Recognition:Non-contact HMI via computer vision interpretation.
Highest average selling prices attach to Autonomous Navigation. Steepest expansion trajectory: Voice Assistants.
End User:
Customer type determines procurement cadence and specification authority, with fleet operators consolidating purchasing power around total-cost-of-ownership metrics.
- OEMs:Vehicle manufacturers specifying factory-integrated AI systems. Germany's KBA certification requirements for algorithmic transparency extend development timelines but lock in long-term platform control.
- Tier-1 Suppliers:Component integrators delivering subsystem modules to multiple OEMs. China's MIIT unified safety protocols enable these suppliers to serve domestic brands with reduced customization overhead.
- Aftermarket Providers:Retrofit specialists targeting installed base vehicles.
- Fleet Operators:Commercial buyers specifying cabin monitoring across vehicle pools.
Dominant procurement volume: OEMs. Gaining share fastest: Fleet Operators.
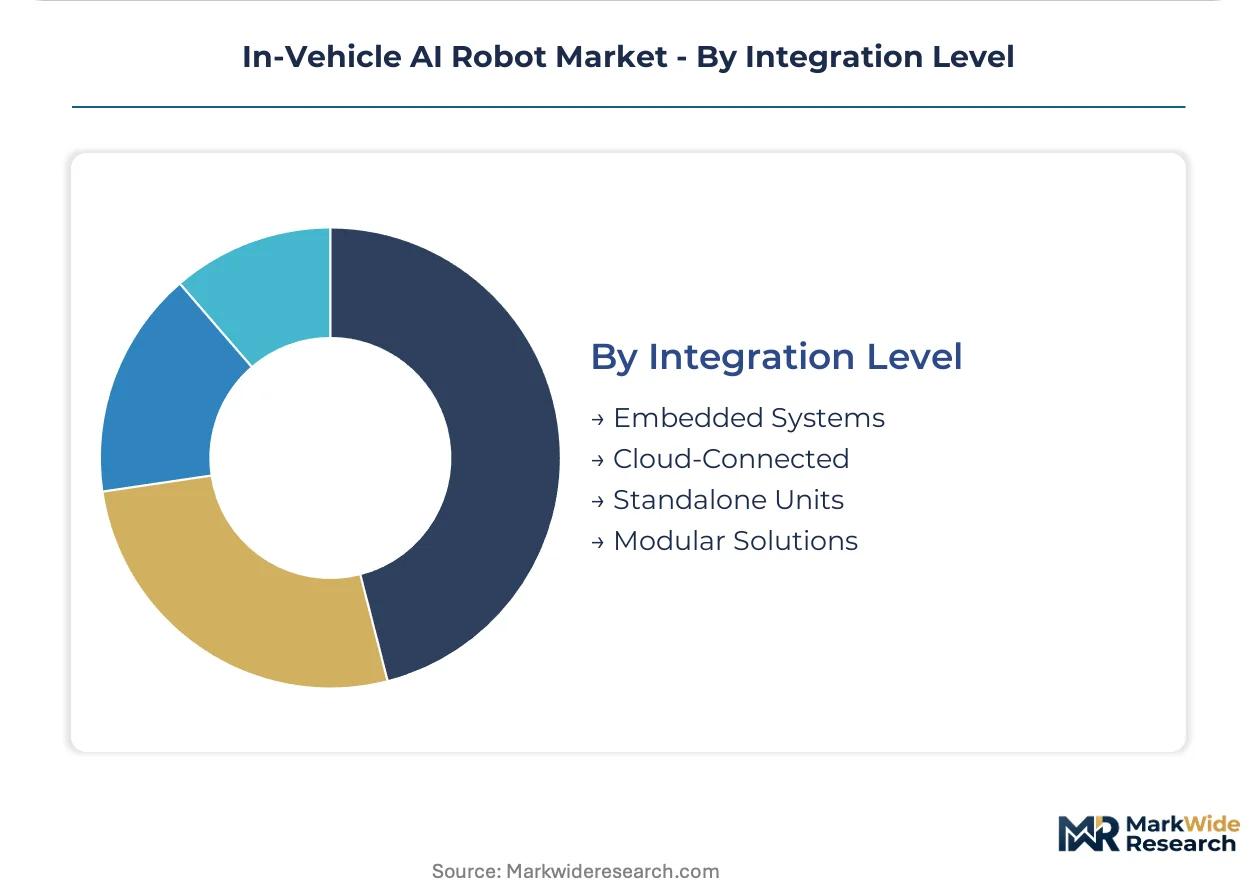
Integration Level:
Supply concentration for automotive-grade SoCs and edge processors determines which integration architectures achieve cost viability at scale.
- Embedded Systems:Dedicated onboard compute without external connectivity. United States long-haul trucking fleets specify these for driver monitoring where cellular dead zones preclude cloud dependency.
- Cloud-Connected:Hybrid architectures with over-the-air update capability. German luxury OEMs monetize subscription features through these systems, though GDPR biometric retention limits constrain data harvesting.
- Standalone Units:Self-contained retrofit devices for legacy vehicle compatibility.
- Modular Solutions:Upgradeable component architectures for flexible deployment.
Largest revenue pool: Embedded Systems. Climbing the fastest: Cloud-Connected.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor anchors North American in-vehicle AI robot deployment, with OEM engineering centers driving validation protocols for cabin-integrated systems. The concentration of Tier-1 supplier headquarters and NHTSA regulatory proximity shapes platform development timelines.
United States
Long-haul trucking fleets and luxury passenger OEMs drive demand for edge-constrained cabin monitoring systems. NHTSA's evolving autonomous system guidance forces simultaneous hardware and software validation redesigns. Michigan's Detroit-Warren corridor concentrates engineering talent for multimodal sensor fusion development.
Germany
Premium OEM programs prioritize EU AI Act-compliant explainable architectures for occupant-facing robotics. KBA certification requirements extend development timelines but lock in platform control for domestic manufacturers. Stuttgart and Munich anchor computer vision and natural language processing R&D clusters.
China
Domestic OEMs and fleet operators scale voice-first cabin assistants across mid-range vehicle tiers. MIIT unified safety protocols reduce platform fragmentation for Tier-1 suppliers serving multiple brands. Shanghai and Shenzhen house edge-computing processor design centers for automotive SoCs.
Japan
Keiretsu-affiliated suppliers integrate gesture recognition and driver monitoring for export-focused vehicle programs. METI standards harmonization with international frameworks accelerates dual-market certification strategies. Nagoya's Chubu region concentrates robotics actuator manufacturing for cabin deployment.
South Korea
Domestic OEMs and battery-electric vehicle specialists specify AI cabin systems as standard equipment. MFDS-aligned safety validation protocols streamline export preparation for European and North American markets. Seoul Capital Area hosts machine learning inference optimization labs for automotive edge processors.
In-Vehicle AI Robot Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and compute-performance dimensions. The vendor base stratifies between vertically integrated OEM captive units, automotive-focused semiconductor specialists, and autonomous system pure-plays. Three archetypes dominate: full-stack OEMs controlling hardware-software integration, silicon vendors licensing platform architectures, and robotics specialists supplying servo-actuated components. Competitive moves concentrate on strategic partnerships for sensor fusion IP and geographic expansion into harmonized regulatory zones.
Within the full-stack OEM tier, Tesla and BMW exemplify divergent approaches to cabin-integrated AI deployment. NVIDIA occupies a position as the dominant automotive-grade silicon platform licensor, with its DRIVE architecture serving multiple OEM validation pipelines. Baidu represents the autonomous system pure-play archetype, anchoring Chinese market development through MIIT-aligned safety protocols. These three companies collectively illustrate how geographic regulatory proximity and integration depth determine competitive positioning across premium and volume vehicle segments.
| Leading Market Players |
|---|
| Tesla |
| Waymo |
| General Motors |
| NVIDIA |
| BMW |
| Baidu |
| Motional Inc. |
| AutoX Inc. |
| Zoox Inc. |
| Others |
Cost & Logistics Intelligence
OEM captive units and sovereign-backed semiconductor foundries dominate ownership structures across the in-vehicle AI robot supply base, concentrating pricing power with vertically integrated platform licensors while forcing Tier-2 component specialists into cost-absorbing contract terms. This ownership pattern tightens margin capture at the silicon layer and propagates pricing discipline downward through sensor and actuator tiers.
Pricing Analysis
Value-based pricing anchored to functional safety certification grade dominates procurement negotiations, with ASIL-D validated modules commanding substantial premiums over ASIL-B equivalents. Price differentiation separates premium integrated systems with edge-AI inference capabilities from economy-grade retrofit units constrained by legacy vehicle bus architectures. Pricing pressure stems from automotive-grade LiDAR module supply constraints in Taiwan and South Korea foundries. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement frameworks, while German luxury OEMs absorb premium positioning for EU AI Act compliance.
Supply Chain Analysis
China's MIIT local-content mandates and the EU Green Deal's embedded carbon disclosure rules are reshaping sourcing patterns for automotive-grade compute substrates and sensor arrays. Supply concentrates in Taiwan for SoC foundry capacity, South Korea for memory and advanced packaging, and Germany for robotics actuator precision manufacturing. Raw material dependencies span high-purity silicon wafers, rare-earth magnets for servo motors, and specialized optical glass for LiDAR lenses. Single-source vulnerability in Taiwan's leading-edge foundry capacity constitutes the dominant structural risk. Distribution runs through Tier-1 supplier consolidation hubs serving multiple OEM validation pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The in-vehicle AI robot market is consolidating around platform-standardization imperatives, with EU AI Act certification timelines and NHTSA validation complexity forcing sub-scale component vendors toward exit or acquisition.
For Market Incumbents: To counter margin compression from cloud-connected architecture commoditization, incumbents should deepen backward integration into automotive-grade SoC design and secure exclusive sensor fusion IP through targeted specialist acquisition. Priority investment in interpretable machine learning frameworks addresses EU AI Act explainability mandates while locking in European OEM platform control. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels offer the most penetrable entry vector, specifically targeting last-mile delivery operators in Germany and the United States with aftermarket cabin monitoring solutions bypassing traditional Tier-1 procurement. White-space concentration sits in commercial vehicle retrofit segments where legacy fleet depreciation cycles delay full vehicle replacement. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated robotics specialists with existing ISO 26262 certification infrastructure in South Korea and Japan, where keiretsu-affiliated suppliers face margin pressure from Chinese OEM vertical integration. Long-term viability hinges on 5-10 year regulatory harmonization trajectories across NHTSA, EU AI Act, and MIIT frameworks. The signal to watch is fleet operator consolidation around national procurement consortia, which will concentrate vendor selection power and accelerate platform winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces fragmentation across NHTSA, EU AI Act, and MIIT validation pipelines for OEMs. |
| Edge Computing Hardware Investment | Enables real-time multimodal inference without cloud dependency for latency-critical cabin interaction. |
| Natural Language Processing Integration | Democratizes premium-tier conversational interfaces across mid-range vehicle tiers. |
| Strategic Partnership for Sensor Fusion IP | Addresses multimodal synchronization expertise gaps limiting team scaling velocity. |
| Geographic Manufacturing Footprint Expansion | Aligns production with EU Green Deal embedded carbon tracking mandates for competitive differentiation. |
Research Approach
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and fleet management company technology officers underwrites the qualitative findings. Primary interviews with these stakeholders were cross-referenced against NHTSA guidance documents, EU AI Act regulatory filings, MIIT standardization protocols, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing and top-down market envelope triangulation were applied throughout.
Comparable-period anchoring to historical technology adoption curves in automotive electronics informed the projection horizon. The analytical framework modeled segmentation across technology type, product category, end-user archetype, and integration level, with vehicle class and regional regulatory cluster as additional dimensions. CAGRs were derived from installed base penetration rates and content-per-vehicle scaling assumptions, incorporating edge processor TOPS advancement trajectories and LiDAR cost decline curves as industry-specific inputs.
Inputs from OEM engineering centers and Tier-1 supplier headquarters were available through the study window; gaps in aftermarket provider financial disclosure and private fleet operator procurement data introduce uncertainty bands around commercial segment sizing. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and sensor fusion technology maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market