
 North America ADAS Market | 2026-2036
North America ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
North America ADAS Market Analytics
Market Context
The divergence between premium and commodity tiers is hardening in North America ADAS procurement. OEMs specify 8-megapixel camera arrays and 4D imaging radar for luxury nameplates while entry-level personal vehicles retain single-sensor configurations. Bosch leverages its cross-continental manufacturing footprint to supply both tiers. Nvidia sustains dominance in AI compute platforms for higher-automation stacks. Aptiv anchors the Tier-1 supplier channel with integrated sensor modules.
Technical Definition and Segment Structure
Advanced Driver Assistance Systems encompass electronic control units, environmental sensors, and software algorithms that automate, warn, or assist vehicle control functions without full autonomy; these systems typically operate on 12V or 48V architectures and process inputs at latency thresholds below 100 milliseconds to enable real-time intervention. Camera systems lead installed base volume across personal vehicles, while lidar systems command concentrated investment in commercial vehicle pilot programs across Arizona and Texas freight corridors. OEMs represent the dominant end-user category, though fleet operators are emerging as the fastest-growing procurement segment due to insurance cost reduction mandates.
Regulatory Framework and Outlook
NHTSA automatic emergency braking requirements and FMVSS 127 standards compel OEMs to embed collision-avoidance technology across light-duty lineups, while Transport Canada CMVSS alignment pressures suppliers to maintain dual-certification capability. EPA fuel-economy regulations indirectly stimulate ADAS adoption by enabling predictive powertrain management. Stakeholders must monitor NHTSA rulemaking on higher-automation pathways and state-level liability frameworks governing commercial deployment.
Market Dynamics
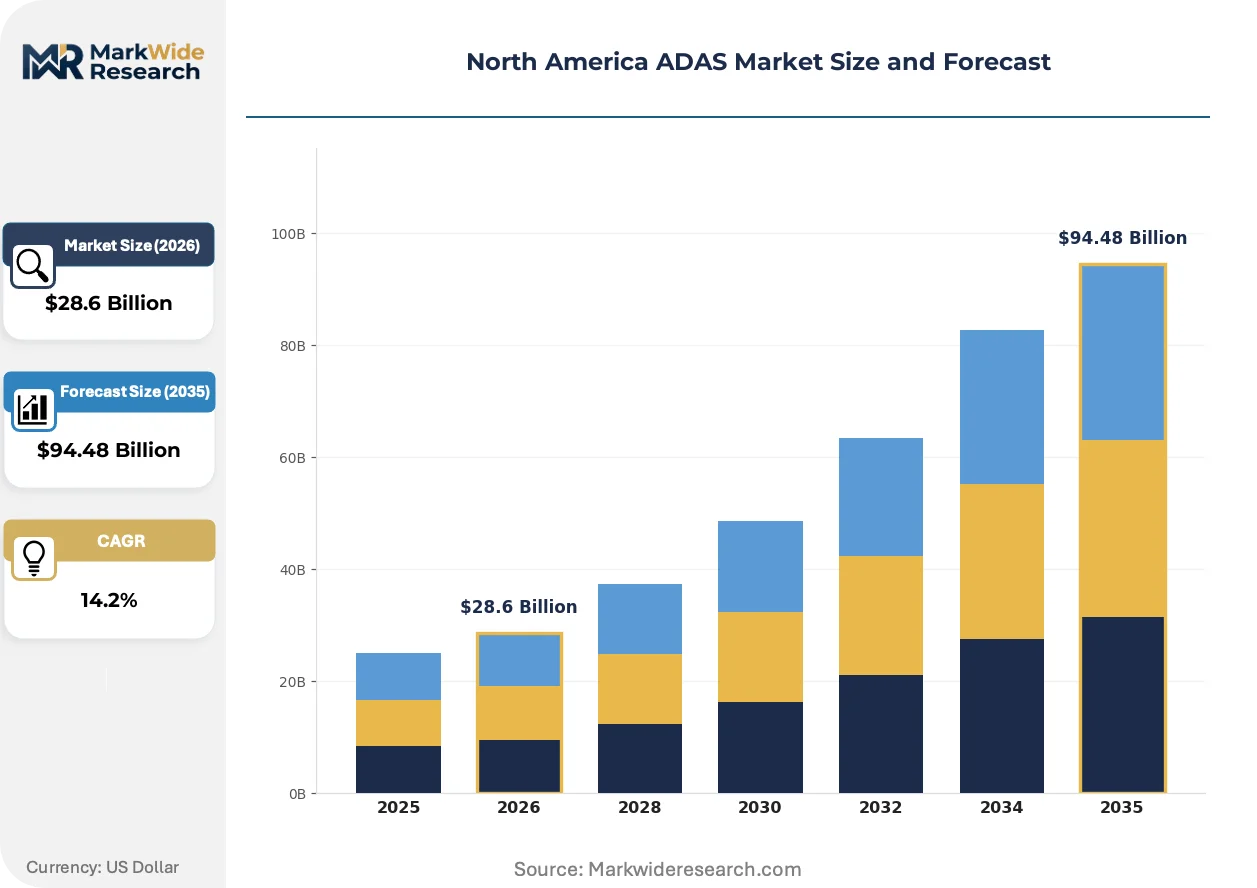
The North America ADAS market is undergoing a fundamental restructuring as NHTSA mandates force collision-avoidance hardware into 100% of light-duty production, compressing supplier lead times and concentrating procurement power among OEMs with dual-certification capability across US and Canadian assembly corridors.
Growth Catalysts
- NHTSA FMVSS 127:Automatic emergency braking requirements now cover all passenger vehicles under 10,000 pounds, compelling Tier-1 suppliers to scale sensor fusion modules for high-volume deployment across Detroit and Ontario production lines.
- Fleet insurance mandates:Commercial operators in Texas and California face premium reductions contingent on ADAS installation, accelerating procurement of camera-radar bundles for Class 8 tractors and last-mile delivery vans.
- 48V electrical architectures:Powertrain electrification enables higher-compute sensor processing without 12V system overload, allowing mid-tier nameplates to adopt features previously restricted to luxury segments.
Market Restraints
- Silicon carbide substrate shortages:Power electronics for high-resolution LiDAR and thermal cameras face allocation constraints from concentrated Asian wafer fabrication, extending OEM qualification timelines by 8-14 months.
- Canadian CMVSS misalignment:Transport Canada testing protocols for pedestrian automatic emergency braking diverge from NHTSA procedures, forcing suppliers to maintain parallel validation tracks and duplicate homologation costs.
- Software-defined vehicle complexity:Over-the-air update architectures require cybersecurity certifications under ISO/SAE 21434 that most legacy Tier-2 firmware vendors cannot satisfy without substantial engineering investment.
Strategic Opportunities
- Mexico assembly expansion:OEMs are relocating ADAS module integration to Guanajuato and Nuevo León facilities to exploit USMCA tariff advantages, creating demand for localized sensor calibration and testing infrastructure.
- EPA fuel-economy credits:Predictive adaptive cruise control that optimizes powertrain load cycles generates compliance value beyond safety functionality, opening procurement conversations with sustainability officers previously excluded from ADAS specification.
- Camera-LiDAR fusion:The convergence of solid-state LiDAR cost curves with 8-megapixel camera arrays enables Level 3 highway automation at price points accessible to mass-market crossovers, expanding addressable volume beyond premium sedans.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification expertise concentrates among a handful of suppliers and consultancies, constraining validation bandwidth for new entrants attempting to displace established sensor module vendors.
- Legacy CAN bus integration:Mixed-voltage architectures in refreshed nameplates require protocol translation gateways that introduce latency, complicating real-time sensor fusion and forcing expensive electrical system redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America ADAS Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Radar Systems, Lidar Systems, Ultrasonic Sensors Technology: Adaptive Cruise Control, Lane Departure Warning, Automatic Emergency Braking, Collision Avoidance End User: OEMs, Tier-1 Suppliers, Repair Shops, Fleet Operators Application: Personal Vehicles, Commercial Vehicles, Public Transport, Heavy Machinery |
| Companies Covered | Aptiv, Valeo, Bosch, Nvidia, Magna, Continental AG, Denso, Qualcomm, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America ADAS Market Evolving Landscape
Sensor fusion architectures are displacing discrete component sourcing as OEMs consolidate procurement responsibility, while regulatory pressure on pedestrian safety and commercial fleet liability accelerates hardware refresh cycles beyond traditional model-year cadences.
4D imaging radar is converging with neural-network-based object classification to enable single-sensor redundancy for highway automation, reducing bill-of-materials complexity for Level 2+ systems. GM and Ford are qualifying Continental and Aptiv units for 2026 nameplates, compressing the traditional radar-camera-LiDAR trinity into dual-sensor configurations for mid-tier trims. This convergence is forcing pure-play LiDAR vendors to defend position in commercial vehicle applications where range requirements exceed radar capability.
Transport Canada CMVSS amendments aligning with UN Regulation 152 on advanced emergency braking create dual-certification pathways that reduce supplier engineering burden, though NHTSA has not signaled equivalent harmonization. The regulatory divergence most affects pedestrian detection algorithms, where Canadian winter testing protocols demand thermal camera supplementation that US-market vehicles omit. Suppliers serving both markets are standardizing on fused thermal-visible architectures to minimize variant proliferation.
Fleet procurement departments are consolidating ADAS specification authority from decentralized maintenance divisions, centralizing vendor negotiations and demanding outcome-based performance guarantees rather than component warranties. Ryder and Penske are piloting this model in California freight corridors, replacing per-unit hardware pricing with per-mile safety metrics. This shift is visible most acutely in Class 6-8 vehicle segments where insurance carriers now mandate third-party ADAS performance verification.
North America ADAS Market Segmentation
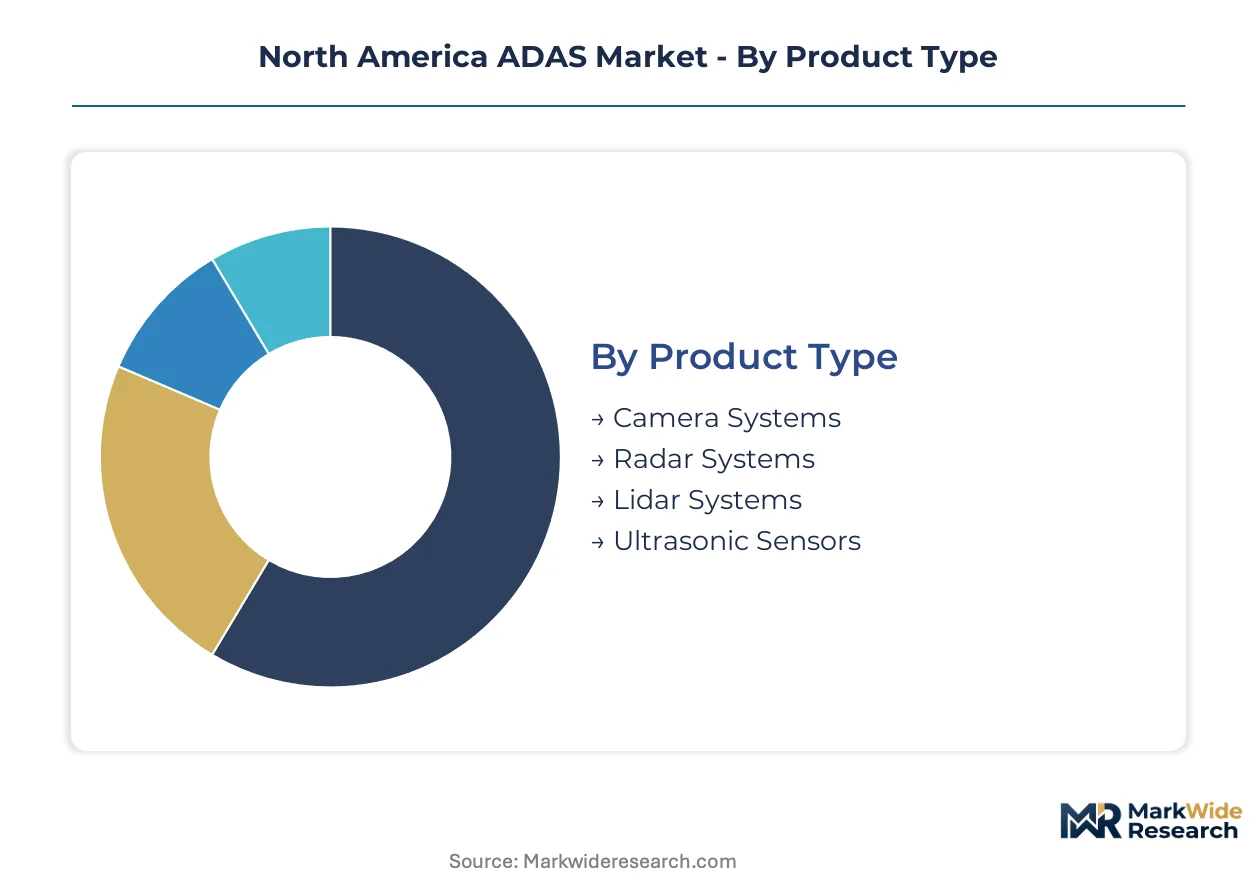
North American OEM procurement patterns reveal a split between integrated safety suites and discrete component sourcing. Tier-1 suppliers configure sensor bundles differently depending on whether the end customer operates assembly lines in Detroit, Ontario, or Guanajuato.
Product Type:
Standalone camera and radar modules dominate current installation volumes, while fused architectures embedding multiple sensing modalities are displacing discrete procurement in premium nameplates.
- Camera Systems:8-megapixel arrays with neural-network image processing handle lane-keeping, traffic-sign recognition, and pedestrian detection. Michigan and Ontario assembly lines specify these for Level 2+ highway automation, though thermal-visible fusion adds cost for Canadian winter certification.
- Radar Systems:4D imaging units with elevation measurement and Doppler velocity capture enable single-sensor redundancy for adaptive cruise control. Texas and California fleet operators procure these in camera-radar bundles for Class 8 tractor collision mitigation.
- Lidar Systems:Solid-state units with silicon photonics backends concentrate in Arizona and Texas commercial vehicle pilot programs where 300-meter range requirements exceed radar capability.
- Ultrasonic Sensors:Short-range parking assistance modules retain 12V architecture compatibility for entry-level nameplates.
Volume placements concentrate in Camera Systems; the faster expansion belongs to Radar Systems.
Technology:
Cost tier differentiation separates mandated safety functions from discretionary convenience features across OEM trim strategies.
- Adaptive Cruise Control:Predictive powertrain integration generates EPA fuel-economy credits beyond safety value, opening procurement conversations with sustainability officers at Ford and GM.
- Lane Departure Warning:Camera-based trajectory monitoring with haptic steering feedback commands minimal hardware cost and achieves near-ubiquitous penetration.
- Automatic Emergency Braking:NHTSA FMVSS 127 mandates this function across all light-duty vehicles under 10,000 pounds, compressing supplier margins through high-volume commoditization.
- Collision Avoidance:Multi-sensor fusion architectures with sub-100-millisecond latency thresholds concentrate in commercial vehicle specifications where insurance carriers mandate third-party performance verification.
Procurement volume clusters around Automatic Emergency Braking; steepest expansion trajectory sits with Adaptive Cruise Control.
End User:
Customer type determines specification authority, warranty terms, and whether procurement centers on hardware cost or outcome-based safety metrics.
- OEMs:Detroit Three and transplant manufacturers in Tennessee and South Carolina consolidate Tier-1 negotiations, demanding dual US-Canada certification capability from sensor module vendors.
- Tier-1 Suppliers:Bosch, Aptiv, and Continental integrate discrete components into calibrated assemblies, managing ISO 26262 ASIL-D validation liability.
- Repair Shops:Aftermarket replacement demand concentrates in collision-repair networks requiring OE-equivalent calibration tooling.
- Fleet Operators:Ryder and Penske centralize ADAS specification from decentralized maintenance divisions, piloting per-mile safety guarantees in California freight corridors.
Revenue concentration remains with OEMs; fleet operators are climbing the fastest as insurance mandates reshape procurement authority.
Application:
Geography and duty cycle differentiate sensor durability requirements, calibration protocols, and regulatory compliance pathways.
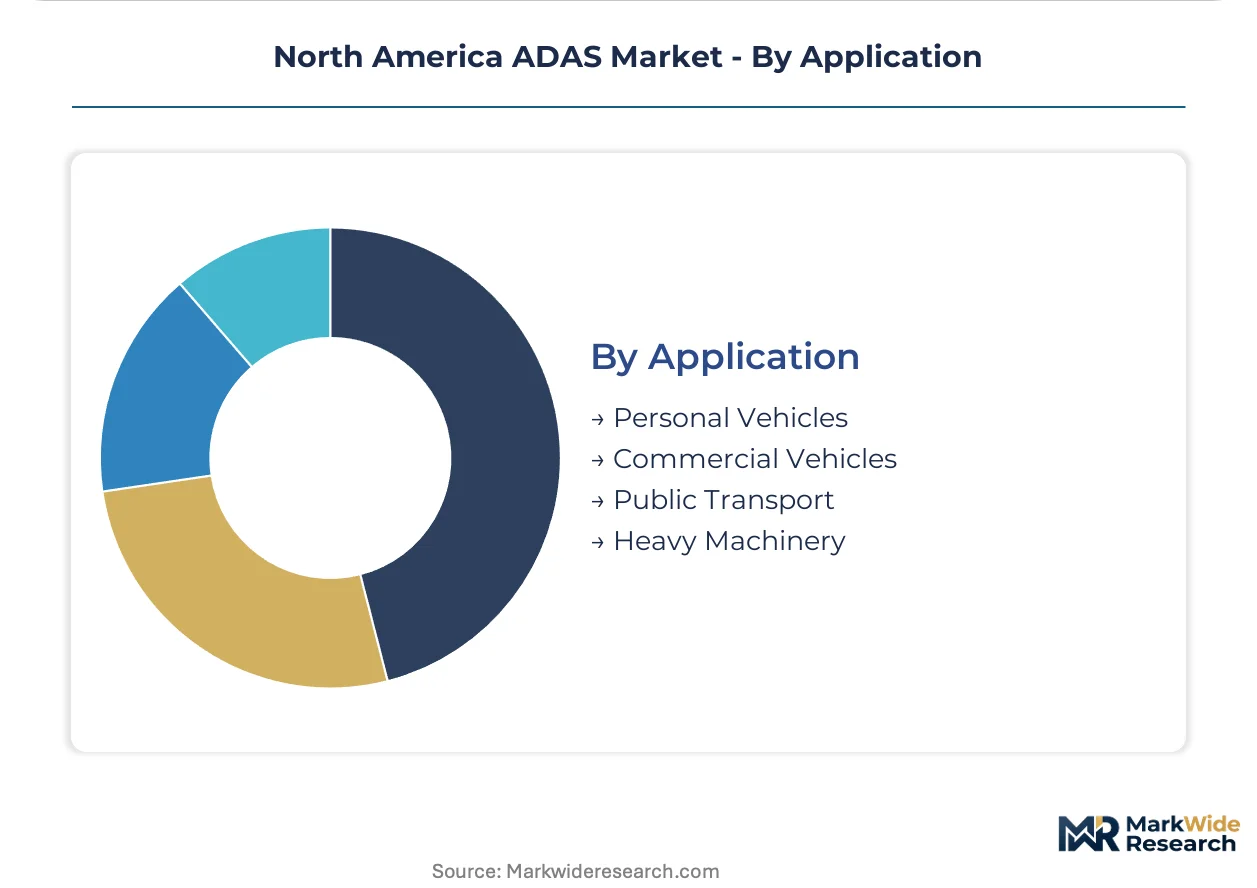
- Personal Vehicles:Light-duty nameplates in Michigan and Ontario integrate camera-radar fusion for NHTSA and Transport Canada dual certification.
- Commercial Vehicles:Class 6-8 tractors and last-mile delivery vans in Texas and California face premium reductions contingent on ADAS installation, accelerating camera-LiDAR bundle adoption.
- Public Transport:Municipal bus operators in Toronto and Vancouver specify pedestrian automatic emergency braking with thermal camera supplementation for winter protocols.
- Heavy Machinery:Construction and mining equipment in Alberta oil sands and Arizona copper corridors demand ruggedized sensor housings with vibration isolation beyond automotive specifications.
Installation base tilts toward Personal Vehicles; gaining share fastest are Commercial Vehicles as fleet insurance mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors North American ADAS manufacturing concentration, with Michigan and Ontario assembly corridors processing the majority of sensor module procurement for Detroit Three and transplant OEMs.
United States
Texas and California freight corridors drive commercial vehicle ADAS adoption as fleet operators face insurance premium reductions contingent on camera-radar bundle installation. NHTSA FMVSS 127 mandates automatic emergency braking across all light-duty vehicles under 10,000 pounds, compelling Tier-1 suppliers to scale production for high-volume deployment. Arizona hosts concentrated LiDAR pilot programs where 300-meter range requirements exceed radar capability for Class 8 tractor automation.
Canada
Ontario assembly lines in Windsor and Oshawa specify thermal-visible camera fusion for Transport Canada CMVSS winter certification protocols diverging from NHTSA testing procedures. Municipal bus operators in Toronto and Vancouver procure pedestrian automatic emergency braking with thermal camera supplementation. Suppliers maintain parallel validation tracks to satisfy dual US-Canada homologation requirements, elevating engineering costs for cross-border production.
Mexico
Guanajuato and Nuevo León facilities attract ADAS module integration relocation to exploit USMCA tariff advantages, creating localized demand for sensor calibration infrastructure. OEMs consolidate Tier-1 negotiations for mid-tier nameplate production serving both US and Canadian markets. The Bajío Region emerges as a testing ground for 48V electrical architecture adoption in entry-level vehicles previously restricted to 12V sensor configurations.
North America ADAS Market Competitive Landscape
Capital-heavy semiconductor foundries compete with asset-light algorithm designers for margin capture in sensor fusion architectures. The supplier base concentrates among Tier-1 integrators capable of managing ISO 26262 ASIL-D validation liability across dual-certification markets. Three archetypes dominate: diversified automotive conglomerates with cross-continental manufacturing footprints, pure-play AI compute platform vendors, and specialized sensor module fabricators. Competitive moves center on strategic partnerships for software-defined vehicle architectures and geographic expansion into Mexican assembly zones.
Within the Tier-1 integrator tier, Aptiv and Continental AG exemplify suppliers managing calibrated sensor assembly liability across Detroit and Ontario production lines. Bosch anchors the diversified conglomerate archetype with manufacturing presence spanning both premium and commodity ADAS tiers. Nvidia occupies a distinctive position among AI compute platform vendors, sustaining dominance in higher-automation processing stacks without direct sensor fabrication exposure.
| Leading Market Players |
|---|
| Aptiv |
| Valeo |
| Bosch |
| Nvidia |
| Magna |
| Continental AG |
| Denso |
| Qualcomm |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
ISO 26262 ASIL-D functional safety engineer concentration in Michigan and Ontario widens pricing spreads between certified Tier-1 integrators and commodity sensor vendors, compressing margins for suppliers lacking dual-certification capability across US and Canadian assembly corridors.
Pricing Analysis
Value-based pricing tied to collision-avoidance outcome guarantees anchors commercial fleet procurement in Texas and California, while transactional per-unit pricing persists for personal vehicle OEMs. Price differentiation separates NHTSA FMVSS 127-compliant sensor fusion modules from single-sensor configurations lacking Transport Canada winter certification. Cost compression in entry-level camera-radar bundles intensifies as Bosch and Aptiv scale high-volume production for Detroit Three nameplates. Fleet operators exhibit lowest price sensitivity due to insurance premium reduction mandates, whereas aftermarket repair shops face severe margin pressure from OE-equivalent calibration tooling requirements.
Supply Chain Analysis
Reverse-logistics flows for LiDAR refurbishment and radar recalibration concentrate in Guanajuato and Nuevo León facilities serving USMCA tariff-advantaged assembly zones. Silicon carbide substrate supply draws from Taiwan, Japan, and South Korea, creating single-source vulnerability for 4D imaging radar power electronics. German and Japanese precision optics feed camera module production for 8-megapixel arrays. Distribution runs through Tier-1 integrator hubs in Michigan and Ontario before final OEM line-fit, with sensor calibration equipment following separate aftermarket channels to collision-repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA FMVSS 127 mandates erect a cost-of-compliance barrier that rewards incumbent Tier-1 suppliers with pre-existing dual-certification infrastructure while straining new entrants lacking ISO 26262 ASIL-D validation bandwidth.
For Market Incumbents: Lock in procurement consolidation advantages by deepening captive supply of silicon carbide power electronics and expanding Guanajuato calibration infrastructure ahead of Mexico assembly relocation. Defend against pure-play LiDAR vendors by accelerating 4D imaging radar performance to satisfy 300-meter commercial vehicle range requirements without LiDAR supplementation. For New Entrants and Emerging Players: Solid-state LiDAR cost curve convergence presents a technology-first wedge for Arizona and Texas freight corridor pilots where incumbent radar-camera bundles fail on range specifications. Target municipal bus operators in Toronto and Vancouver requiring thermal-visible camera fusion for winter pedestrian detection protocols underserved by US-market suppliers. Pursue outcome-based per-mile safety guarantees to bypass incumbent component pricing structures. For Investors and Strategic Acquirers: Re-rating potential sits with Tier-1 integrators possessing dual US-Canada certification capability given Transport Canada CMVSS alignment pressure with UN Regulation 152. Long-term viability favors suppliers with backward integration into neural-network training data and sensor fusion software stacks. Monitor NHTSA rulemaking on higher-automation liability frameworks as inflection indicator for Level 3 highway automation procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Reduces variant proliferation for OEMs sourcing across Michigan, Ontario, and Guanajuato assembly lines. |
| 48V Electrical Architecture Adoption | Enables mid-tier nameplate access to compute-intensive features previously restricted to luxury segments. |
| Mexico Manufacturing Footprint Expansion | Captures USMCA tariff advantages for ADAS module integration serving cross-border production. |
| Software-Defined Vehicle Investment | Positions suppliers for ISO/SAE 21434 cybersecurity certification requirements in over-the-air update architectures. |
| Fleet Outcome-Based Partnership | Aligns supplier incentives with Ryder and Penske per-mile safety metrics replacing hardware warranties. |
Research Methodology
Multi-period observation of NHTSA rulemaking trajectories, EPA fuel-economy credit valuations, and fleet insurance mandate diffusion anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket calibration equipment distributors, and commercial fleet safety managers. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC supplier filings, and Transport Canada CMVSS amendment dockets. Bottom-up sensor unit shipment estimates triangulated against top-down OEM platform content analysis.
Input-output matrices mapped sensor modality penetration across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGR derivation rested on regression-adjusted technology adoption curves and regulatory mandate phase-in schedules. Industry-specific forecast inputs included silicon carbide wafer supply allocation forecasts and dual-certification engineering cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NHTSA acceleration of higher-automation rulemaking or prolonged silicon carbide substrate allocation constraints. Practitioners should monitor Transport Canada CMVSS harmonization signals, fleet insurance mandate state-level expansion, and Tier-1 supplier qualification timeline extensions for early indicators of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Autonomous Electric Bus Market