
 AI in Transportation Market | 2026-2036
AI in Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Transportation Market Analysis
The capital-intensity divergence between sensor-hardware manufacturers and pure-software stack developers is reorganizing competitive hierarchies across autonomous mobility. Waymo leverages its vertically integrated LiDAR production to sustain testing scale in multiple urban zones. NVIDIA Corporation anchors the upstream compute layer with its Drive platform, while Mobileye competes through tightly bundled vision-processor and mapping contracts with established OEMs.
AI in Transportation denotes the application of machine-learning inference, computer-vision perception, and predictive analytics to vehicular control, traffic orchestration, and logistics coordination, typically operating on edge-GPU architectures with sub-100-millisecond latency requirements for safety-critical decisions. Its primary purpose is to reduce human-operator burden while improving throughput and collision avoidance across road, rail, and maritime networks. Machine learning and computer vision together constitute the dominant technology pairing, with computer vision commanding disproportionate R&D allocation due to the computational cost of real-time object detection at highway speeds. Autonomous vehicles absorb the largest share of application-level investment, though fleet management is gaining traction among logistics providers seeking fuel-efficiency gains from dynamic routing algorithms.
The National Highway Traffic Safety Administration in the United States, the EU AI Act framework, and China's Ministry of Industry and Information Technology GB standards collectively shape homologation timelines, data-governance obligations, and cross-border deployment permissions for self-driving systems. NHTSA's evolving crash-reporting mandates force developers to document disengagement patterns, while the EU AI Act's risk-classification scheme imposes conformity-assessment burdens on autonomous-vehicle algorithms entering European roads. Stakeholders must monitor regulatory divergence between Washington and Brussels, as divergent liability frameworks will determine which technology architectures achieve scalable commercial deployment without jurisdiction-specific retrofit costs.
Market Dynamics
Freight operators are consolidating predictive maintenance deployments across North American and European corridors, creating concentrated demand pull for edge-computing hardware suppliers serving long-haul logistics networks.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic disclosure requirements for autonomous vehicle deployments are accelerating third-party validation services and compliance-tooling procurement across European testbeds.
- Edge-GPU latency thresholds:Sub-100-millisecond safety-critical inference standards are forcing hardware upgrades across existing ADAS fleets, generating replacement-cycle demand for automotive compute modules.
- German automotive clustering:Stuttgart and Munich corridor concentration is concentrating R&D spillover effects, drawing specialized perception-software vendors into proximity with OEM engineering centers.
Market Restraints
- LiDAR sensor cost structures:Solid-state unit economics remain prohibitive for mass-market passenger vehicle integration, constraining deployment to premium segments and commercial freight applications with clearer ROI pathways.
- Training data governance:Cross-border transfer restrictions under GDPR and emerging national data-localization frameworks are fragmenting dataset assembly for perception-model development.
- Homologation timeline divergence:NHTSA crash-reporting mandates and EU AI Act conformity-assessment burdens are creating jurisdiction-specific retrofit requirements that compress margin structures for multi-market developers.
Strategic Opportunities
- Maritime autonomous navigation:Port automation and coastal freight corridors present underpenetrated demand for collision-avoidance and route-optimization systems outside road-dominated investment flows.
- Rail predictive maintenance:Track-inspection computer vision and bearing-failure prediction models represent emerging application white space with established infrastructure owner-operators and clearer procurement authority.
- India PLI scheme incentives:Production-linked incentive structures for automotive electronics and semiconductor packaging are drawing component assembly capacity toward subcontinent supply bases.
Industry Challenges
- Edge-AI talent scarcity:Embedded systems engineers with safety-critical software certification experience command premium compensation, constraining development velocity for mid-tier stack vendors.
- Retrofit integration complexity:Legacy fleet management systems in commercial trucking lack standardized CAN bus architectures, forcing costly custom engineering for AI-enabled telematics overlay deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Transportation Market |
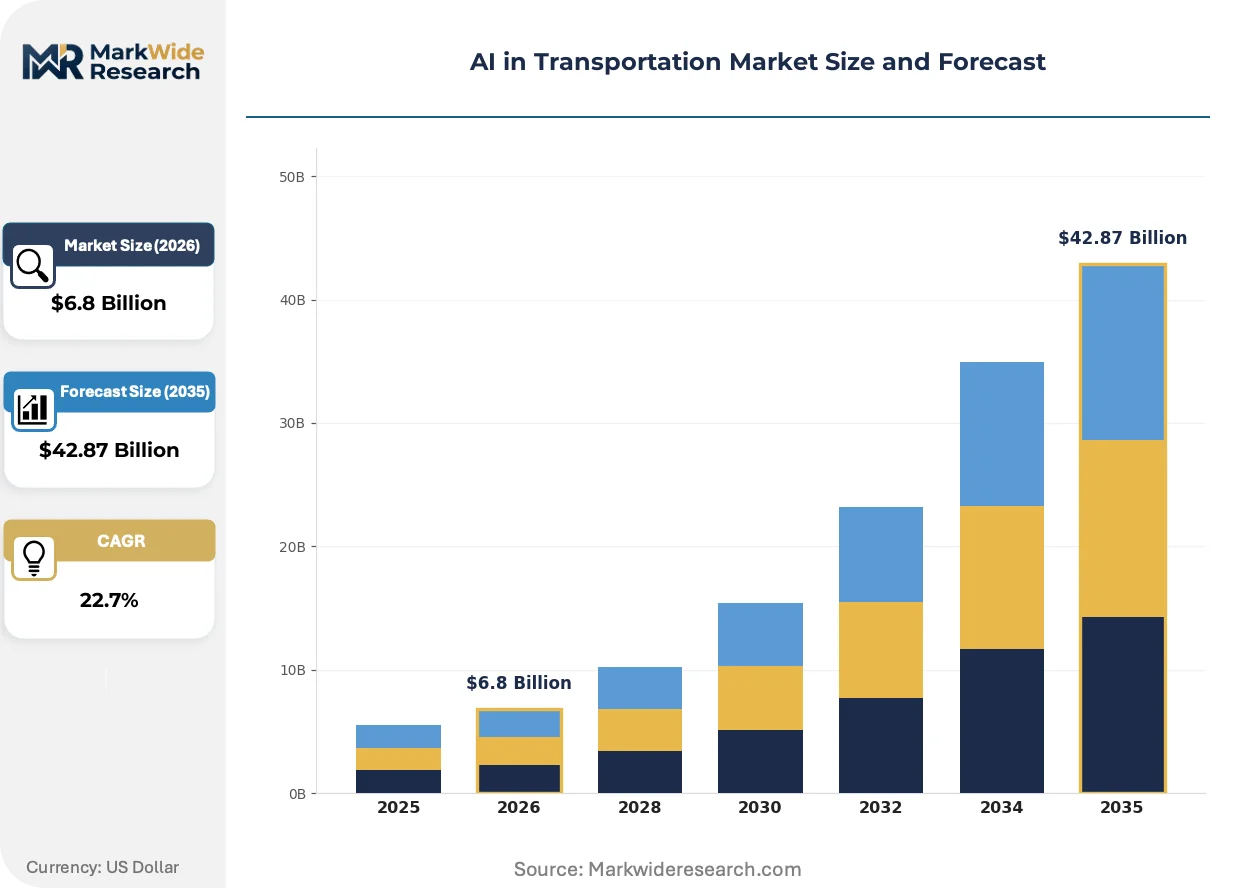
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $42.87 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Computer Vision, Natural Language Processing, Robotics Application: Autonomous Vehicles, Traffic Management, Route Optimization, Fleet Management End User: Logistics Providers, Public Transit Authorities, Ride-sharing Companies, Freight Operators Functionality: Predictive Maintenance, Driver Assistance, Demand Forecasting, Safety Monitoring |
| Companies Covered | Waymo, Tesla, Mobileye, NVIDIA Corporation, Intel Corporation, Robert Bosch GmbH, Continental AG, Volvo Group, Baidu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Transportation Market Emerging Trajectories
Foundation-model architectures trained on synthetic driving scenarios are compressing development timelines for perception systems while raising new questions about simulation-to-reality transfer reliability.
Transformer-based neural architectures for multi-object tracking are displacing recurrent and convolutional legacy approaches in production ADAS stacks. Tier-1 suppliers serving German and Japanese OEMs are adopting these models for highway-pilot features launching in 2024-2025 vehicle generations. The shift is compressing competitive differentiation timelines as open-source implementations erode proprietary algorithm moats.
The EU AI Act's risk-classification framework for autonomous vehicle algorithms is imposing conformity-assessment burdens on European deployments. Developers must document training-data provenance and model-performance boundaries under third-party audit protocols. Mid-tier stack vendors are responding by narrowing geographic scope to avoid multi-jurisdiction compliance costs.
Fleet procurement of AI-enabled telematics is consolidating around outcome-based fuel-efficiency guarantees rather than hardware-centric capital expenditure models. Logistics providers with dense route networks are demanding vendor accountability for MPG improvements. This shift is most visible in North American long-haul trucking where fuel represents the largest variable cost line item.
AI in Transportation Market Segmentation
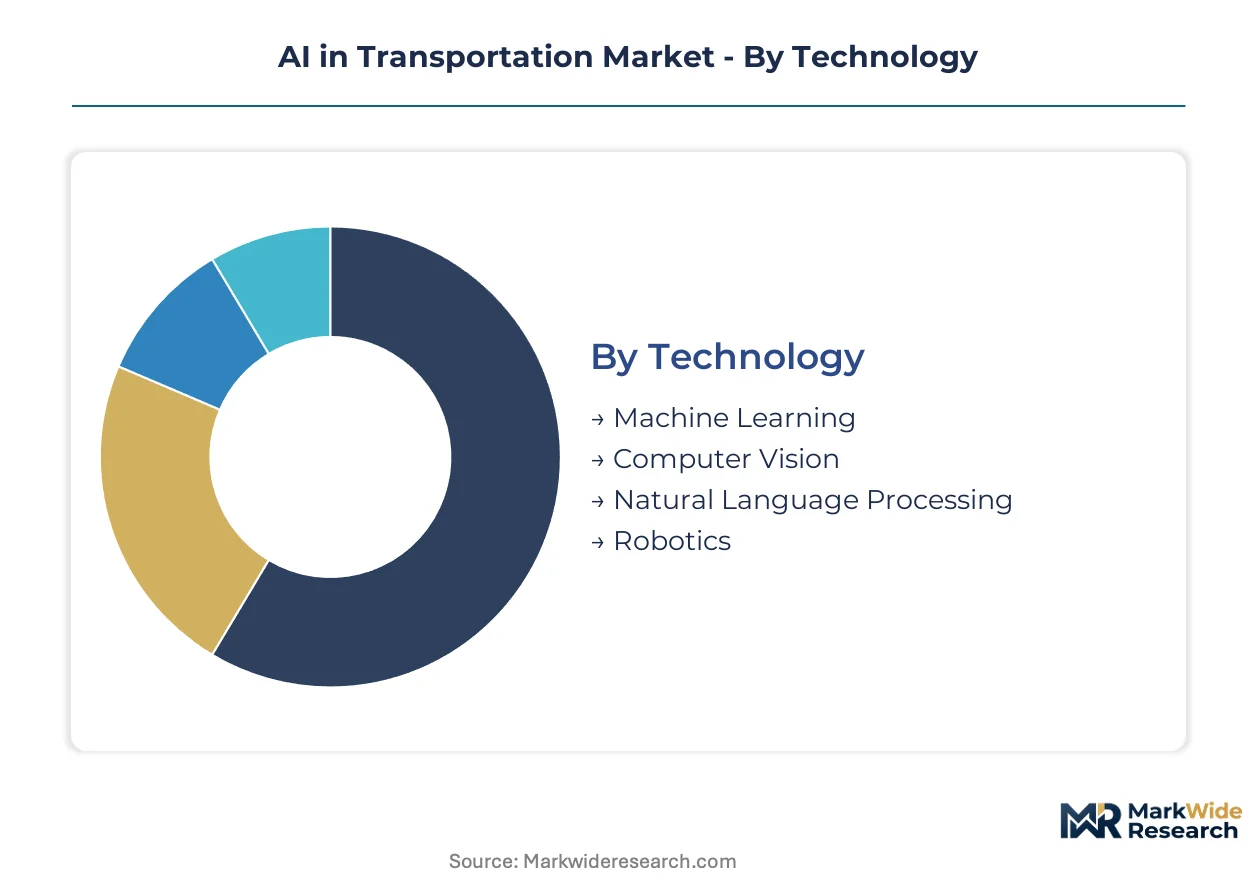
Technology architecture choices determine deployment feasibility across regulatory environments. Application-level segmentation reveals divergent ROI timelines between passenger mobility and freight logistics. End-user procurement authority shapes vendor contracting structures and pilot-to-scale conversion rates.
Technology:
Machine Learning and Computer Vision concentrate R&D investment domestically within German and US engineering centers, while Natural Language Processing and Robotics draw more export-oriented demand from Asian manufacturing hubs.
- Machine Learning:Inference engines process sensor fusion data for trajectory prediction and collision avoidance. Demand clusters around Stuttgart and Munich where automotive OEMs operate dedicated AI research campuses. The EU AI Act's risk-classification requirements accelerate third-party model-validation procurement.
- Computer Vision:Real-time object detection systems operate on edge-GPU architectures with sub-100-millisecond latency thresholds. Long-haul freight corridors across the US Interstate system and German autobahn network absorb the majority of highway-pilot deployment volumes. Solid-state LiDAR integration costs constrain mass-market passenger applications.
- Natural Language Processing:Voice-controlled cabin interfaces and dispatcher communication systems. Japanese and South Korean OEMs lead integration for premium vehicle segments.
- Robotics:Automated cargo handling and last-mile delivery mechanisms. Port automation projects in Rotterdam and Singapore drive specialized hardware procurement.
Computer Vision holds the largest share; momentum sits with Machine Learning as foundation-model architectures compress development timelines.
Application:
Cost tier stratification separates capital-intensive autonomous vehicle platforms from software-only traffic orchestration tools with minimal hardware dependencies.
- Autonomous Vehicles:Full self-driving stacks integrating perception, planning, and control modules. Waymo's vertically integrated LiDAR production and NVIDIA's Drive platform anchor competing technical approaches. NHTSA crash-reporting mandates and EU AI Act conformity assessments create jurisdiction-specific retrofit burdens.
- Traffic Management:Signal optimization and congestion prediction algorithms deployed by municipal authorities. Singapore's Land Transport Authority and the Netherlands' Rijkswaterstaat operate reference implementations with open data APIs.
- Route Optimization:Dynamic fuel-efficiency algorithms for commercial fleets. North American logistics providers demand outcome-based MPG guarantees rather than capital expenditure procurement models.
- Fleet Management:Telematics integration for predictive maintenance and driver behavior monitoring. European freight operators consolidate deployments across Rhine-Alpine and North Sea-Baltic corridors.
Autonomous Vehicles command the highest absolute investment; Route Optimization gains share fastest as fuel costs pressure logistics margins.
End User:
Customer type determines contract structure complexity, with public sector procurement cycles running 18-24 months longer than commercial fleet operator decisions.
- Logistics Providers:DHL Supply Chain and Kuehne+Nagel operate dedicated AI innovation labs for warehouse-to-vehicle coordination. Dynamic routing algorithms reduce empty-mileage across European distribution networks.
- Public Transit Authorities:Transport for London and RATP deploy demand-forecasting models for bus frequency optimization. GDPR-compliant passenger data handling adds implementation overhead.
- Ride-sharing Companies:Uber and Lyft suspended proprietary autonomous vehicle programs, shifting to OEM partnership models for driver-assistance features.
- Freight Operators:J.B. Hunt and Schneider National consolidate predictive maintenance deployments across North American long-haul corridors. Edge-computing hardware suppliers serve concentrated demand pull from this segment.
Freight Operators hold the largest share; momentum sits with Logistics Providers as outcome-based contracting spreads.
Functionality:
Supply concentration clusters around predictive maintenance and driver assistance, where established Tier-1 suppliers possess embedded systems certification experience.
- Predictive Maintenance:Bearing-failure prediction and track-inspection computer vision for rail networks. Deutsche Bahn and SNCF operate procurement programs with clearer technical specifications than road-dominated applications.
- Driver Assistance:Lane-keeping and adaptive cruise control systems. Mobileye's bundled vision-processor and mapping contracts with German and Japanese OEMs sustain market position.
- Demand Forecasting:Passenger volume prediction for transit frequency adjustment. Urban authorities in Barcelona and Copenhagen deploy open-source implementations eroding proprietary algorithm differentiation.
- Safety Monitoring:Driver fatigue detection and collision-warning systems. EU General Safety Regulation mandates accelerate fleet retrofit requirements.
Driver Assistance holds the largest share; Predictive Maintenance climbs fastest as rail infrastructure operators clarify procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in AI-enabled transportation hardware favor Germany and the United States as net exporters of perception software and automotive compute modules, while China and Japan import specialized edge-GPU components for domestic autonomous vehicle testbeds. Trade flows concentrate around Stuttgart-Munich, Silicon Valley, and Shenzhen corridor exchanges.
United States
Freight operators across the Interstate highway system drive edge-computing procurement for predictive maintenance and dynamic routing systems. NHTSA crash-reporting mandates force developers to document disengagement patterns and algorithmic performance boundaries. Waymo anchors autonomous vehicle testing in Phoenix, Arizona and San Francisco, California, generating concentrated demand for LiDAR and simulation software vendors.
Germany
Automotive OEMs cluster around Stuttgart and Munich engineering campuses, drawing specialized perception-software vendors into proximity with established Tier-1 suppliers. The EU AI Act's risk-classification framework imposes conformity-assessment burdens on autonomous-vehicle algorithms entering European roads. Robert Bosch GmbH and Continental AG anchor the Baden-Württemberg supplier ecosystem, sustaining R&D spillover effects across the Rhine-Alpine freight corridor.
China
MIIT GB standards govern homologation timelines for self-driving systems deployed across coastal manufacturing zones and inland logistics networks. Baidu operates autonomous vehicle pilots in Beijing and Wuhan under national data-localization frameworks that fragment cross-border dataset assembly. Production-linked incentive structures for automotive electronics draw component assembly capacity toward Yangtze River Delta supply bases.
Japan
METI safety-certification protocols shape deployment permissions for highway-pilot features targeting premium vehicle segments. Japanese OEMs lead integration of voice-controlled cabin interfaces using natural language processing for dispatcher coordination. Toyota and Honda engineering centers in Nagoya and Tokyo sustain demand for vision-processor and mapping contract specialists serving domestic and export markets.
India
PLI scheme incentives for automotive electronics and semiconductor packaging draw component assembly capacity toward subcontinent supply bases. The country's national automotive regulator enforces localization requirements for safety-critical software modules deployed in commercial fleet management. Maharashtra and Tamil Nadu manufacturing corridors concentrate telematics hardware production for domestic logistics providers and export markets.
AI in Transportation Market Vendor Landscape
Concentration sits with vertically integrated technology conglomerates and specialized automotive Tier-1 suppliers rather than pure-software startups. The vendor base organizes around three strategic archetypes: captive technology divisions of automotive OEMs, independent perception-stack developers, and upstream compute-platform providers. Competitive moves center on strategic partnerships for data-sharing corridors and technology licensing agreements that reduce jurisdiction-specific retrofit costs.
Within the technology conglomerate tier, NVIDIA Corporation and Intel Corporation anchor upstream compute and semiconductor supply positions, while Waymo exemplifies the vertically integrated autonomous-system developer archetype with in-house LiDAR production capabilities. Mobileye occupies a specialist position bundling vision-processor and mapping contracts with established German and Japanese OEMs. Robert Bosch GmbH and Continental AG represent the traditional Tier-1 supplier archetype adapting embedded systems certification experience toward AI-enabled driver assistance modules.
| Leading Market Players |
|---|
| Waymo |
| Tesla |
| Mobileye |
| NVIDIA Corporation |
| Intel Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Volvo Group |
| Baidu |
| Others |
Supply Flow & Price Mechanics
Outcome-based fuel-efficiency guarantees lock in multi-year vendor commitments across North American freight corridors, binding logistics providers to predictable per-mile costs while securing edge-computing hardware suppliers against demand volatility.
Pricing Analysis
Industrial OEM buyers anchor tiered pricing structures across premium, standard, and economy compute-module tiers. Certification grade under EU AI Act conformity-assessment protocols and volume scale across fleet-deployment contracts drive price differentiation. Cost compression in standard-tier edge-GPU modules is intensifying because open-source perception architectures erode proprietary algorithm premiums. Small fleet operators exhibit highest price sensitivity; premium German OEMs demonstrate lowest.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for automotive-grade GPUs and vision processors, while Germany concentrates LiDAR sensor assembly and embedded systems integration. Raw material dependencies span rare-earth elements for magnet assemblies, silicon carbide substrates for power electronics, and specialized optical glass for camera modules. Single-source vulnerability in advanced-node chip fabrication threatens tiered supplier commitments. Distribution runs through captive Tier-1 supplier networks into OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems engineers with safety-critical software certification experience command compensation premiums that constrain development velocity, creating a talent-access bottleneck that determines which stack vendors achieve scalable deployment.
For Market Incumbents: Shield proprietary LiDAR production advantages through backward integration into optical component supply. Deepen embedded systems certification capabilities to satisfy EU AI Act third-party audit protocols. Consolidate data-sharing corridor partnerships with freight operators to lock out emerging perception-stack competitors.
For New Entrants and Emerging Players: Lead with maritime autonomous navigation and rail predictive maintenance applications where procurement authority is clearer and incumbent concentration is lowest. Target port automation projects in Rotterdam and Singapore with collision-avoidance modules priced on outcome-based guarantees rather than hardware capital expenditure.
For Investors and Strategic Acquirers: Perception-software vendors with established Tier-1 supplier integration pathways present acquisition profiles with defensible OEM channel access. Long-term viability hinges on jurisdictional scope discipline to avoid multi-market compliance cost burdens. Watch for EU AI Act enforcement patterns as inflection indicator for geographic expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Third-party model-validation procurement accelerates across Stuttgart and Munich engineering clusters. |
| Edge-GPU Hardware Upgrade Cycle | Sub-100-millisecond inference standards force replacement demand across existing ADAS fleets. |
| Maritime Navigation Partnership | Port automation projects in Rotterdam create reference implementations for coastal freight corridors. |
| Rail Predictive Maintenance Deployment | Deutsche Bahn procurement programs clarify technical specifications for track-inspection computer vision. |
| India PLI Scheme Localization | Production-linked incentives draw automotive electronics assembly toward Maharashtra manufacturing corridors. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, freight operator fleet managers, and edge-computing hardware vendors converged on the working assumptions. Primary interviews combined with secondary validation against NHTSA crash-reporting databases, EU AI Act implementation guidance, vehicle production registries, and customs trade records. Bottom-up deployment estimates and top-down technology-spending allocations were triangulated to establish market boundaries.
Segmentation dimensions modeled span technology architecture, application type, end-user procurement authority, and functionality across the analysis window. CAGRs derive from installed-base penetration curves and replacement-cycle timing for automotive compute modules. Forecast inputs incorporate homologation timeline divergence between Washington and Brussels, plus fuel-cost volatility effects on logistics-provider procurement urgency.
Forecasts assume regulatory continuity in NHTSA reporting mandates and EU AI Act risk-classification enforcement; material policy shifts would require re-modeling deployment permissions and cross-border dataset assembly feasibility. Specific risks include GDPR training-data fragmentation, solid-state LiDAR cost-structure breakthroughs, and talent-scarcity constraints on development velocity. Recalibration cycles align with material shifts in homologation timelines and fuel-efficiency guarantee contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
US Autonomous Car Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market