
 Norway Autonomous Navigation Market | 2026-2036
Norway Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Autonomous Navigation Market Insights
The Norwegian Maritime Authority's coastal route autonomy framework is hardening certification requirements for vessel operators seeking limited-crew permits. Kongsberg leverages its Kongsberg Maritime division to dominate integrated bridge systems for Norwegian ferry operators. NAVTOR sustains a specialized position in digital chart distribution and voyage optimization software for coastal fleets. Saab anchors defense-linked autonomous surface vessel development through its Swedish-Norwegian maritime technology partnerships.
Autonomous navigation encompasses sensor-guided vessel and vehicle positioning systems that fuse LiDAR, radar, and GPS inputs to execute course corrections without continuous human intervention, typically operating within sub-meter accuracy thresholds in maritime environments where GNSS degradation occurs. The primary commercial purpose centers on reducing crew exposure in hazardous waters while optimizing fuel consumption through algorithmic route planning. Maritime end users currently lead solution adoption as Norwegian fjord routes present repeatable, high-frequency corridors where remote monitoring and fleet management solutions generate measurable operational savings. Vision systems within the technology segment are gaining traction as supplement to radar in low-visibility North Sea conditions, though GPS-dependent architectures remain the baseline for open-water segments.
The Norwegian Maritime Authority, the Norwegian Coastal Administration, and ISO 19848 ship data standards collectively shape product development timelines and market access conditions for autonomy system vendors. Vessel operators must demonstrate compliance with route-specific risk assessments before receiving operational exemptions, creating a two-tier market between certified and uncertified solution providers. Stakeholders should monitor how forthcoming amendments to the Norwegian Ship Safety Act integrate IMO's Maritime Autonomous Surface Ship code provisions into domestic enforcement frameworks.
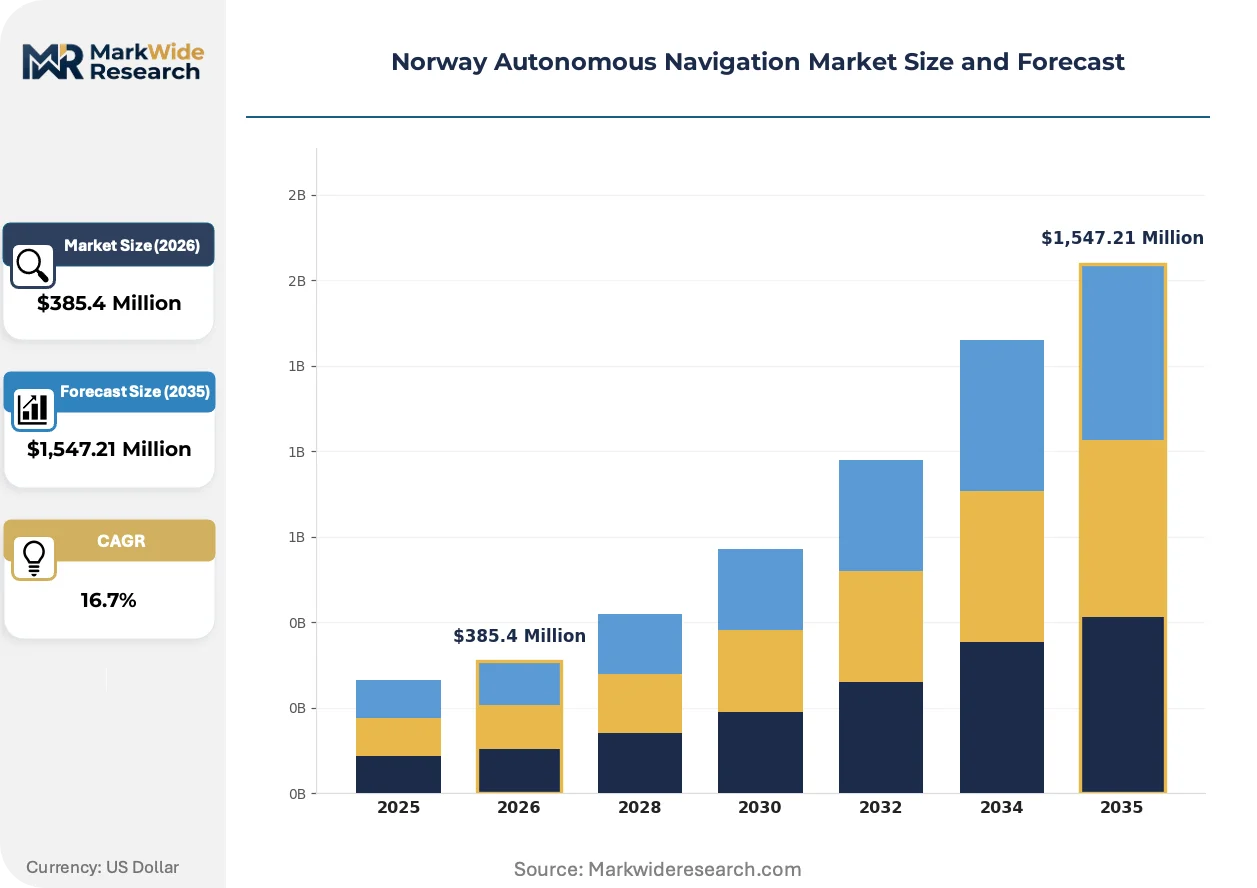
Market Dynamics
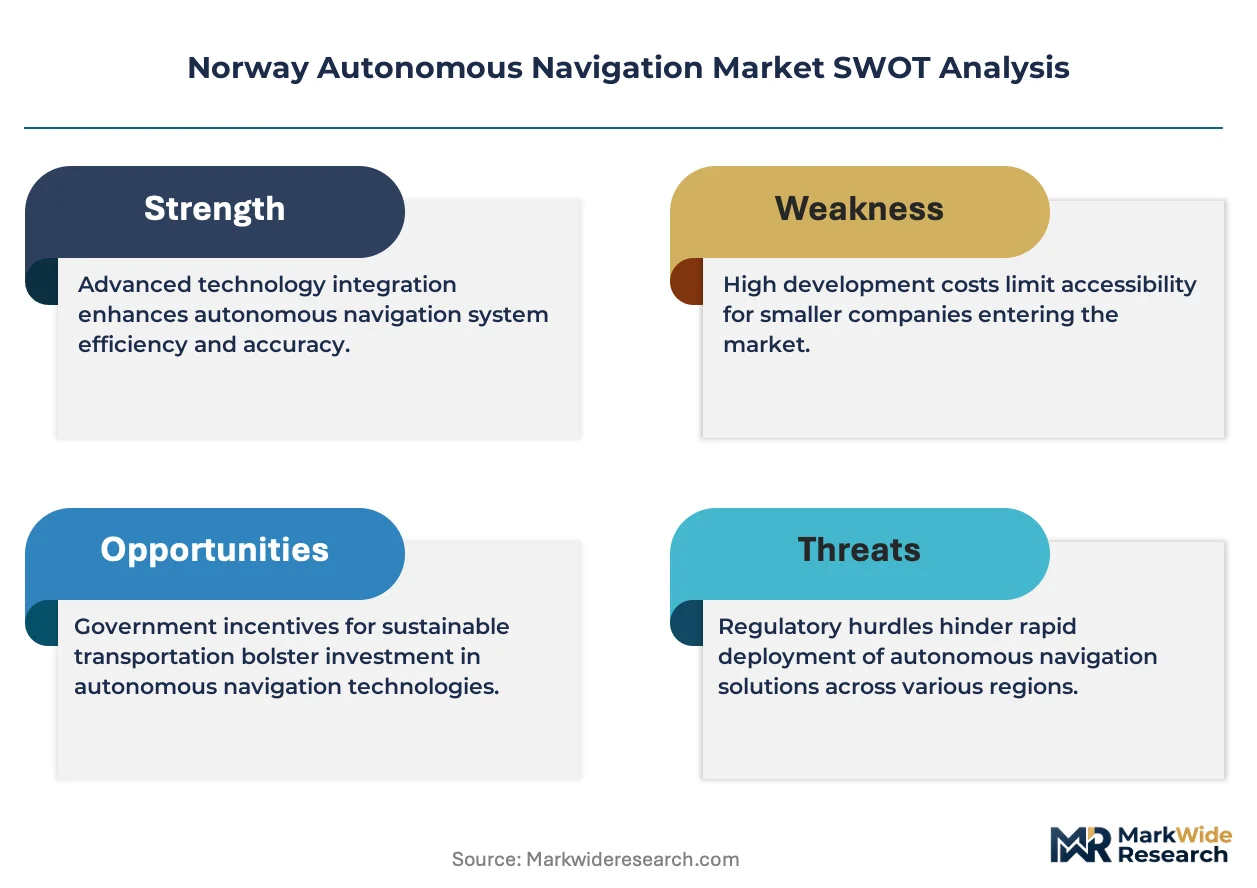
The Norwegian Maritime Authority's route-specific autonomy framework is compressing certification timelines while hardening technical requirements, creating a bifurcation between certified system integrators and uncertified component vendors.
Growth Catalysts
- Fjord corridor density:Norway's 1,190 fjords generate repeatable, high-frequency vessel routes where remote monitoring infrastructure generates immediate fuel and crew-cost savings for ferry operators.
- ISO 19848 compliance pathway:Standardized ship data protocols reduce integration costs for sensor fusion architectures, accelerating vendor onboarding for coastal fleets.
- Offshore energy R&D clusters:Bergen and Stavanger-based research consortia fund harsh-weather navigation algorithms, transferring defense-grade positioning technology to commercial maritime applications.
Market Restraints
- LiDAR supply concentration:Maritime-grade solid-state LiDAR production concentrates among three Asian component manufacturers, exposing Norwegian system integrators to 14-18 week lead times.
- GNSS degradation zones:North Sea geomagnetic interference creates sub-meter accuracy failures in GPS-dependent architectures, forcing redundant sensor overlays that inflate unit costs.
- Crew certification friction:The Norwegian Ship Safety Act mandates dual-licensed bridge officers for limited-crew permits, constricting eligible operator pools.
Strategic Opportunities
- Tromsø Arctic testing corridor:Northern Norway's extended winter darkness and ice-edge conditions offer validation environments for vision-radar fusion systems targeting polar route markets.
- IMO MASS code alignment:Upcoming amendments to the Norwegian Ship Safety Act incorporating international autonomous vessel standards will pre-approve export-ready system architectures.
- Electrification convergence:Battery-electric ferry retrofits create bundled procurement opportunities where autonomy systems integrate with energy management platforms.
Industry Challenges
- Multisensor calibration expertise:Maritime autonomy engineering requires rare cross-training in naval architecture, machine vision, and maritime law, with Norwegian technical universities producing fewer than forty qualified graduates annually.
- Route-specific risk assessment delays:Each operational exemption demands 8-14 months of documented trial data, freezing commercial deployment for second-tier vendors lacking established track records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Autonomous Navigation Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,547.21 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Vision Systems, GPS End User: Public Transport, Maritime, Agriculture, Mining Application: Autonomous Vehicles, Drone Delivery, Smart Shipping, Remote Monitoring Solution: Navigation Software, Fleet Management, Sensor Fusion, Mapping Services |
| Companies Covered | Kongsberg, NAVTOR, Saab, StormGeo, ZeroNorth, OneOcean, Danelec, Wärtsila, Vissim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Autonomous Navigation Market Trends and Innovations
Sensor fusion architectures are displacing single-modality navigation systems as North Sea operators confront GNSS degradation in fjord shadow zones and low-visibility conditions.
Millimeter-wave radar is integrating thermal imaging inputs to maintain sub-meter positioning accuracy during North Sea fog events. Offshore supply vessel operators in Stavanger are retrofitting hybrid sensor stacks at twice the pace of open-water fleets. The technology is compressing the performance gap between certified and uncertified autonomy vendors by democratizing harsh-weather capability.
Amendments to the Norwegian Ship Safety Act will incorporate IMO Maritime Autonomous Surface Ship code provisions into domestic enforcement frameworks. Vessel operators must demonstrate compliance with route-specific risk assessments before receiving limited-crew operational exemptions. Coastal ferry routes between Bergen and Stavanger are most affected, with operators accelerating trial documentation to secure grandfathered permits.
Fleet procurement is consolidating around integrated bridge system vendors capable of delivering bundled sensor, software, and certification support. Single-component suppliers without regulatory liaison capabilities are losing position to full-stack providers. The shift is most visible among Hurtigruten coastal cruise operators, who now require turnkey autonomy packages with pre-approved Norwegian Maritime Authority documentation.
Norway Autonomous Navigation Market Segmentation
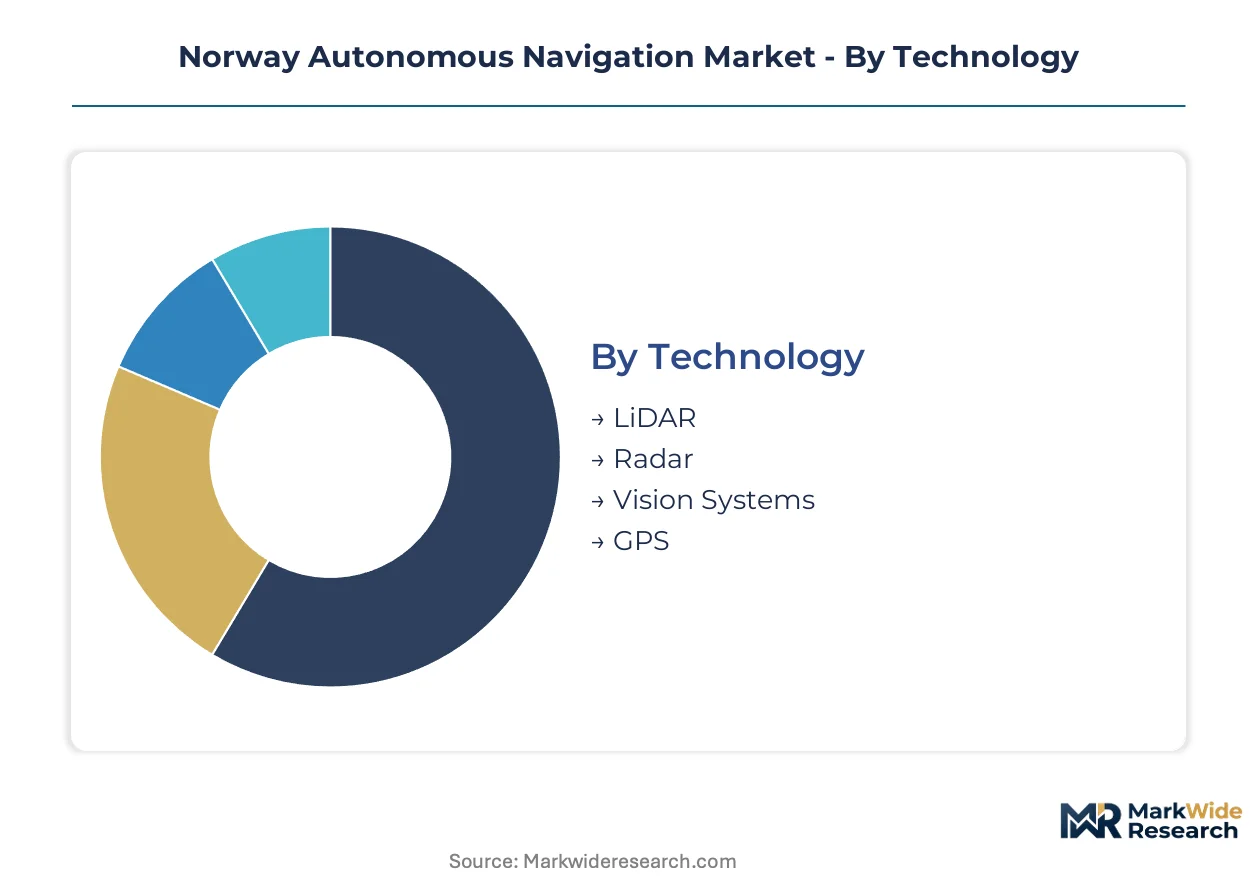
Segmentation reveals how Norwegian autonomy vendors align technical capabilities with distinct operational environments. The fjord-intensive coastline and offshore energy clusters create divergent requirements across sensor modalities and end-use applications.
Technology:
Integration depth varies sharply: LiDAR and radar function as standalone perception layers in certified maritime systems, while vision systems and GPS typically embed within multi-sensor fusion architectures.
- LiDAR:Maritime-grade solid-state units emit pulsed laser arrays for sub-meter range mapping in narrow fjord corridors. Demand clusters around Bergen-Stavanger ferry retrofits where Norwegian Maritime Authority certification mandates redundant obstacle detection.
- Radar:Millimeter-wave systems penetrate North Sea fog and precipitation that blind optical sensors. Offshore supply vessel operators in Stavanger prioritize radar-first stacks for 24-hour positioning continuity during winter darkness.
- Vision Systems:Camera arrays with thermal overlay supplement radar in low-visibility zones.
- GPS:GNSS cores remain baseline for open-water segments despite geomagnetic degradation near fjord walls.
Volume placements concentrate in Radar; the faster expansion belongs to Vision Systems.
End User:
Cost tier stratification separates capital-intensive maritime deployments from pilot-phase land-based applications.
- Maritime:Coastal ferry and offshore vessel operators fund integrated bridge system overhauls with autonomy bundles. Norwegian Coastal Administration route permits accelerate procurement for Hurtigruten and energy service fleets.
- Public Transport:Autonomous bus trials in Oslo and Trondheim operate under limited operational design domains. Ruter and AtB transit authorities evaluate sensor costs against labor savings on low-frequency rural routes.
- Agriculture:Tractor guidance systems deploy in Østfold grain districts with centimeter-accuracy GPS correction.
- Mining:Underground vehicle autonomy progresses at Svalbard and continental tunnel operations.
Procurement volumes favor Maritime; steepest expansion trajectory sits with Public Transport.
Application:
Maturity gradients separate proven maritime use cases from emerging aerial and terrestrial modalities.
- Smart Shipping:Coastal route autonomy with remote monitoring centers dominates current deployment. Norwegian Maritime Authority exemptions cover 14 operational corridors between Bergen and Kirkenes.
- Remote Monitoring:Shore-based fleet oversight reduces crew complements on repetitive fjord transits. Operators achieve 30-40 percent labor cost reductions with Norwegian Coastal Administration-approved control room architectures.
- Autonomous Vehicles:Road trials remain constrained by Norwegian Public Roads Administration permitting timelines.
- Drone Delivery:Medical and logistics UAVs operate in northern Norway beyond road networks.
Revenue concentration rests with Smart Shipping; share gains flow fastest to Remote Monitoring.
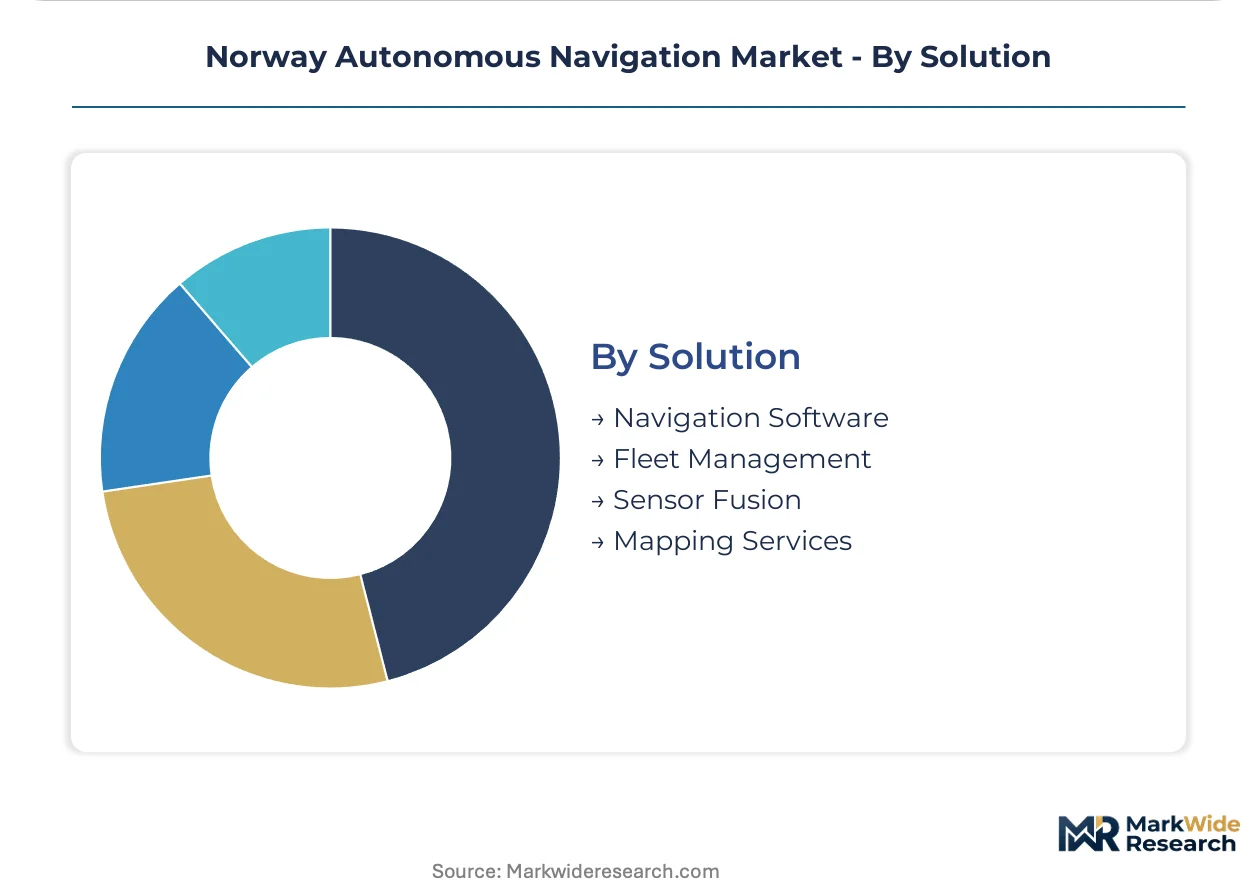
Solution:
Supply concentration favors full-stack providers over component specialists as certification requirements harden.
- Sensor Fusion:Integrated LiDAR-radar-vision processing units command premium positioning in Norwegian Maritime Authority pre-approved vendor lists. Kongsberg Maritime and NAVTOR dominate coastal fleet procurement with bundled hardware-software-certification packages.
- Navigation Software:Digital chart distribution and voyage optimization modules embed within broader bridge system contracts. NAVTOR maintains specialized position with ENCs tailored to fjord bathymetry.
- Fleet Management:Remote monitoring platforms aggregate vessel telemetry for shore-side operators.
- Mapping Services:High-resolution fjord bathymetry and coastal chart updates support autonomy route planning.
Deployment volumes cluster in Sensor Fusion; the climbing trajectory belongs to Fleet Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norwegian Innovation Clusters program concentrates autonomous navigation R&D through tax-advantaged zones along the western coastline. Bergen and Stavanger anchor offshore energy technology transfer, while Tromsø hosts Arctic validation corridors. Government-backed maritime testbeds accelerate commercial deployment timelines.
Vestland
Ferry operators along the Bergen-Stavanger corridor fund integrated bridge retrofits with bundled autonomy packages. The Norwegian Maritime Authority's route-specific permits cover 14 operational corridors in this region. Bergen's offshore supply cluster transfers defense-grade sensor fusion algorithms to commercial maritime applications.
Rogaland
Stavanger-based energy service vessels prioritize radar-first sensor stacks for 24-hour positioning continuity during North Sea winter darkness. The Norwegian Coastal Administration accelerates exemption timelines for documented trial data from established operators. Local research consortia develop millimeter-wave radar integration with thermal imaging overlays.
Troms og Finnmark
Arctic testing corridors offer extended winter darkness and ice-edge conditions for vision-radar fusion validation. The Norwegian Ship Safety Act amendments will incorporate IMO MASS code provisions for polar route system architectures. Tromsø's university-industry partnerships produce cross-trained autonomy engineers bridging naval architecture and machine vision.
Oslo and Viken
Autonomous bus trials operate under limited operational design domains with Ruter and AtB transit authorities evaluating sensor costs against rural route labor savings. The Norwegian Public Roads Administration maintains permitting timelines that constrain road deployment relative to maritime corridors. Oslo's software developers supply fleet management platforms aggregating vessel telemetry for shore-side operators.
Møre og Romsdal
Hurtigruten coastal cruise operators require turnkey autonomy packages with pre-approved Norwegian Maritime Authority documentation. The Norwegian Coastal Administration route permits accelerate procurement for grandfathered operational exemptions. Ålesund's maritime equipment suppliers integrate with Kongsberg Maritime's certified vendor ecosystem.
Norway Autonomous Navigation Market Competitive Landscape
Norwegian producers anchor the integrated systems tier; Nordic and European specialists hold component and software positions. The market consolidates around full-stack providers capable of delivering bundled hardware-software-certification packages. Three archetypes dominate: defense-technology transfer houses, maritime electronics integrators, and voyage optimization software specialists. Competitive moves center on regulatory pre-approval acquisition and sensor fusion architecture standardization.
Within the integrated systems tier, Kongsberg occupies a position exemplifying defense-to-commercial technology transfer, while NAVTOR represents specialized digital chart distribution and voyage optimization software. Saab anchors Swedish-Norwegian maritime technology partnerships for defense-linked autonomous surface vessel development. These three entities sit within distinct competitive vectors—hardware integration, software specialization, and dual-use technology—rather than direct substitution relationships.
| Leading Market Players |
|---|
| Kongsberg |
| NAVTOR |
| Saab |
| StormGeo |
| ZeroNorth |
| OneOcean |
| Danelec |
| Wärtsila |
| Vissim |
| Others |
Pricing and Supply Chain Analysis
Cross-trained autonomy engineering talent concentration in Vestland and Rogaland compresses labor-cost differentials between premium certified-system integrators and uncertified component vendors, widening pricing-tier spreads for bundled bridge-system packages versus standalone sensor modules.
Pricing Analysis
Short-lead-time premiums for maritime-grade solid-state LiDAR units command substantial markups over spot-inventory discounts for standard radar components. Three-tier pricing structure across certified-integration, pre-certified-software, and economy-component levels separates Kongsberg Maritime bundles from NAVTOR software licenses from Asian-sourced standalone sensors. Price differentiation hinges on Norwegian Maritime Authority pre-approval status and volume-scale procurement by Hurtigruten-scale ferry operators. Pricing pressure stems from 14-18 week LiDAR lead times forcing operators toward premium expedited sourcing. Public transport pilot programs exhibit highest price sensitivity due to municipal budget constraints, while offshore energy fleets show lowest sensitivity given operational savings from reduced crew exposure.
Supply Chain Analysis
Regional distribution centers in Bergen and Stavanger operate hub-and-spoke patterns feeding fjord-corridor ferry terminals and offshore supply bases. Geographic supply concentration centers on Japan, South Korea, and China for solid-state LiDAR emitters, millimeter-wave radar chipsets, and thermal imaging sensors. Raw material dependencies include indium phosphide substrates, gallium arsenide wafers, and specialized maritime-grade optical coatings. Single-source vulnerability concentrates in three Asian LiDAR manufacturers, exposing Norwegian integrators to geopolitical logistics disruption. Distribution runs through Kongsberg Maritime's certified vendor ecosystem and NAVTOR's direct coastal-fleet digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in cross-trained naval architecture-machine vision engineering talent prop pricing power for certified system integrators capable of delivering bundled hardware-software-certification packages.
For Market Incumbents: Extend certification-first bundling strategies to preempt emerging pure-software entrants lacking Norwegian Maritime Authority liaison capabilities. Deepen backward integration into sensor fusion processing units to reduce Asian component dependency exposure. Prioritize Tromsø Arctic testing corridor capacity to validate polar-route architectures before IMO MASS code alignment hardens export-ready system requirements. For New Entrants and Emerging Players: Launch via direct-to-fleet software licensing models targeting second-tier ferry operators priced out of Kongsberg Maritime integrated bridge contracts. White-space concentration sits with remote monitoring platform modules for shore-side control room architectures. Penetrate through Oslo and Viken public transport pilot programs where Ruter and AtB authorities evaluate sensor costs against rural route labor savings. For Investors and Strategic Acquirers: Re-rating potential sits with voyage optimization software specialists given IMO MASS code alignment catalyst accelerating export-ready certification demand. Long-term viability favors firms with demonstrated Norwegian Maritime Authority pre-approval track records and established Bergen-Stavanger customer density. Watch for Norwegian Ship Safety Act amendment passage as inflection signal for grandfathered permit valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Standardization | Kongsberg Maritime and NAVTOR consolidate procurement around pre-certified integrated stacks. |
| Arctic Testing Corridor Investment | Tromsø validation environments accelerate vision-radar fusion certification for polar routes. |
| IMO MASS Code Alignment Preparation | Norwegian Maritime Authority amendment timeline creates first-mover export advantage. |
| Electrification Convergence Bundling | Battery-electric ferry retrofits create captive autonomy-energy management platform demand. |
| Remote Monitoring Platform Development | Shore-side fleet oversight modules capture 30-40 percent labor cost reduction value. |
Research Methodology
Document review covered Norwegian Maritime Authority exemption filings, Norwegian Coastal Administration route permits, ISO 19848 ship data standards, and IMO MASS code drafts, complemented by interviews with ferry fleet operations directors, offshore supply vessel procurement managers, maritime autonomy system engineers, and Norwegian technical university research faculty. Secondary validation drew from Kongsberg Maritime and NAVTOR public disclosures, Bergen and Stavanger cluster program documentation, and customs records for maritime sensor imports. Bottom-up vessel-operator demand estimates and top-down market sizing triangulated across primary stakeholder input and secondary data benchmarks.
Historical deployment trajectories across certified and uncertified system tiers were cross-referenced against panel input from maritime electronics procurement leads. Segmentation dimensions modeled include technology modality, end-user vertical, application maturity, and solution integration depth, alongside regional corridor-specific regulatory approval status. CAGRs were derived from fitted growth curves anchored to documented exemption timelines and fleet retrofit procurement patterns. Forecast inputs incorporated LiDAR supply lead time volatility and Norwegian Ship Safety Act amendment probability assessments.
Regulatory amendment delays, Asian component supply disruptions, and geomagnetic interference mitigation cost overruns are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding certification timeline compression and cluster program funding continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market