
 Automotive Brake Actuator Market | 2026-2036
Automotive Brake Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Actuator Market Analytics
Aftermarket distribution networks are rewriting procurement patterns for replacement brake actuators across mature vehicle parcs. Continental AG leverages captive manufacturing of pneumatic actuators to sustain fleet service contracts in European commercial corridors. Robert Bosch GmbH competes through integrated sensor-actuator modules that anchor its position in ESC-equipped platforms. ZF Friedrichshafen AG specializes in electromechanical braking architectures that differentiate its portfolio from conventional hydraulic suppliers.
An automotive brake actuator is a powered transducer that converts control signals into mechanical force to apply friction at wheel-end braking elements, typically achieving response latencies under 100 milliseconds in modern electronic systems. Its primary industrial purpose is to enable automated braking intervention for advanced driver assistance and autonomous vehicle platforms. Electric actuators now lead product type growth as automakers phase vacuum-dependent designs from passenger car architectures, while pneumatic systems retain margin pools in heavy-duty commercial truck applications where air-brake infrastructure dominates. Installation type segmentation shows OEM integration capturing value through brake-by-wire consolidation, though aftermarket channels serve aging ABS-equipped vehicle populations requiring actuator replacement.
NHTSA mandates on commercial vehicle stopping distances shape product specifications for US-market pneumatic and hydraulic actuators, while ECE R13 regulations in Europe enforce comparable performance thresholds for cross-border truck and bus certification. REACH restrictions on friction material constituents compel suppliers to reformulate actuator interface components for EU market access. Stakeholders must monitor the convergence of brake-by-wire standards with autonomous emergency braking requirements as regulatory bodies on both sides of the Atlantic finalize interoperability protocols for mixed-traffic environments.
Market Dynamics
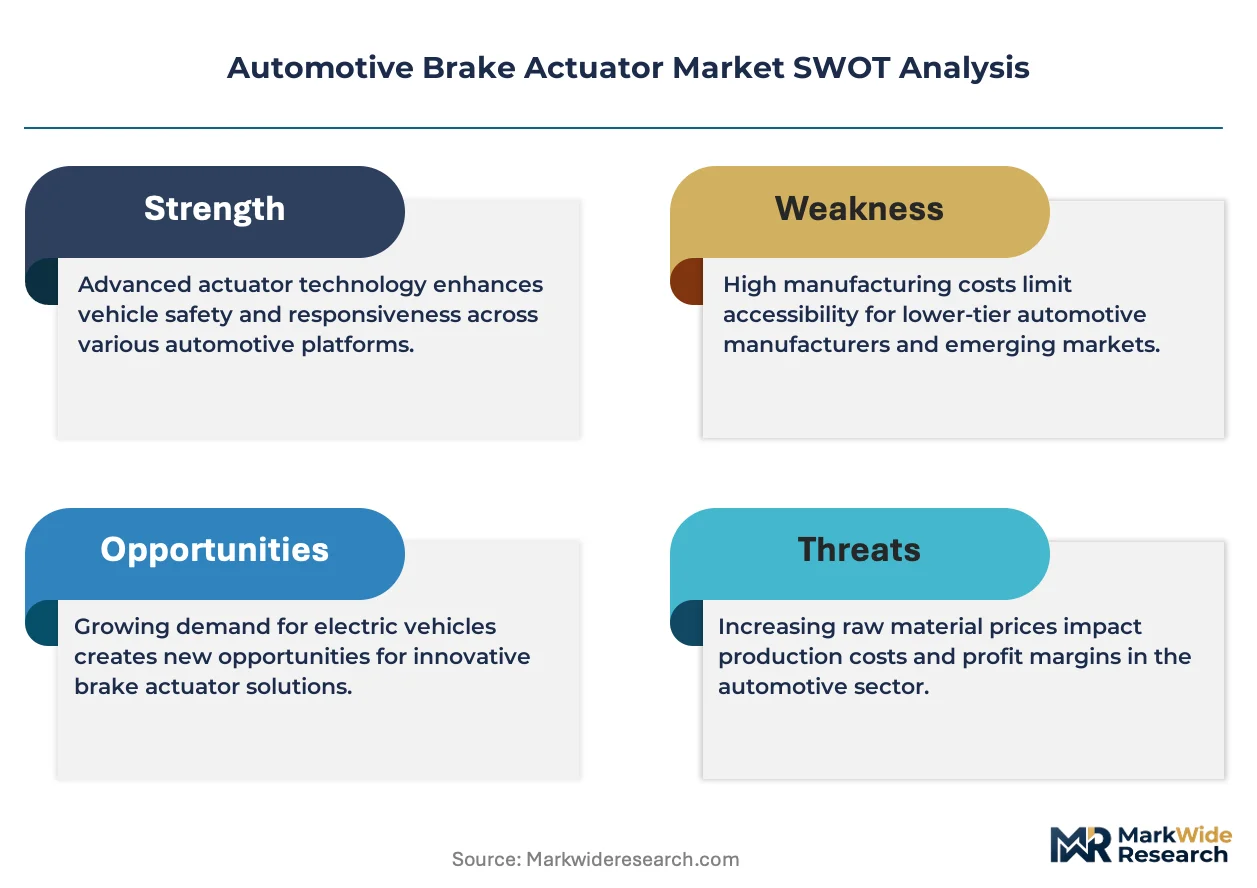
Electric brake actuator architectures are displacing vacuum-dependent designs across passenger vehicle platforms, forcing suppliers to reconfigure manufacturing footprints and R&D priorities toward electromechanical integration.
Growth Catalysts
- NHTSA stopping-distance mandates:US commercial vehicle regulations compel heavy-duty truck fleets to upgrade pneumatic actuator specifications, sustaining replacement demand across North American corridors.
- Brake-by-wire consolidation:Premium passenger car platforms in Germany and Japan integrate sensor-actuator modules that enable autonomous emergency braking functionality.
- Aftermarket channel expansion:Aging ABS-equipped vehicle populations across mature European parcs generate recurring revenue streams for replacement actuator procurement.
Market Restraints
- Rare earth magnet cost volatility:Electromechanical actuator production depends on neodymium supply concentrated in Chinese processing facilities, exposing margins to input price swings.
- REACH friction material restrictions:ECHA compliance requirements force reformulation of actuator interface components, extending EU market access timelines for non-European suppliers.
- Hydraulic system path dependency:Established commercial truck air-brake infrastructure limits electromechanical substitution rates in heavy-duty segments despite technical feasibility.
Strategic Opportunities
- India commercial vehicle electrification:BIS certification pathways for electric actuators align with domestic truck fleet modernization initiatives under national automotive mission plans.
- Autonomous vehicle platform integration:Convergence of brake-by-wire architectures with ISO 26262 functional safety standards creates specification windows for qualified actuator suppliers.
- Direct fleet procurement channels:Large-scale logistics operators bypass traditional distribution tiers to negotiate volume contracts for predictive maintenance programs.
Industry Challenges
- Embedded software certification bottlenecks:ISO 26262 ASIL-D compliance for safety-critical actuator control algorithms extends development cycles by 18-24 months.
- Legacy hydraulic integration complexity:Electromechanical retrofits into existing vehicle architectures require custom mounting solutions that fragment production scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Actuator Market |
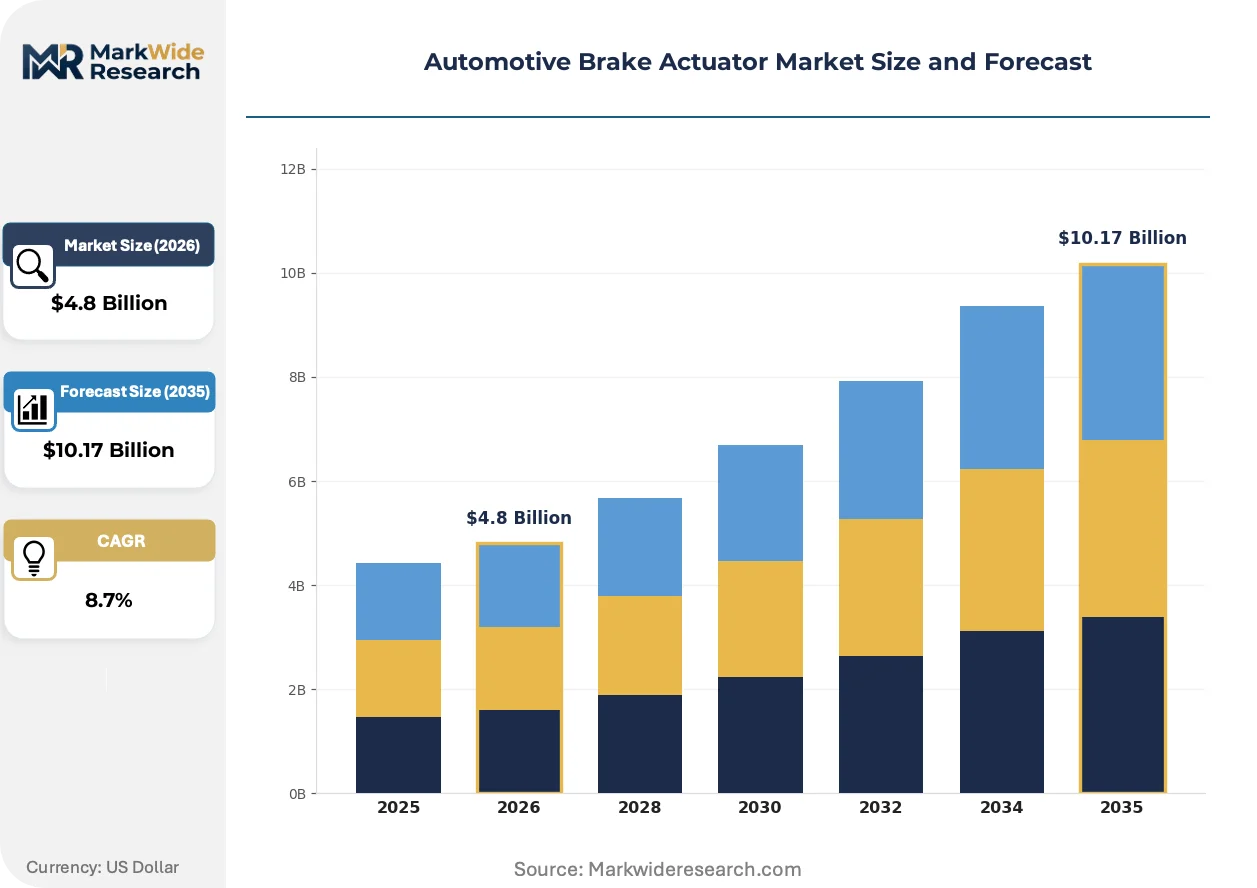
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Hydraulic, Vacuum Installation Type: OEM, Aftermarket, Retrofit, Integrated Vehicle Type: Passenger Cars, Commercial Trucks, Motorcycles, Buses Control Technology: ABS, ESC, EBD, ASR |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Nissin Kogyo, Denso Corporation, Hyundai Mobis, Aisin Corporation, Magna International, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Actuator Market Evolving Landscape
Digital twin methodologies and predictive maintenance protocols are compressing development cycles and reshaping how brake actuator performance is validated before physical prototyping.
Electromechanical braking architectures are virtualizing the traditional separation between hydraulic power transmission and electronic control modules. Tier-1 suppliers in Germany and Japan embed motor-inverter-ECU combinations within wheel-end assemblies, eliminating fluid lines. Premium OEM platforms adopt these integrated units to achieve sub-100-millisecond response latencies required for autonomous emergency braking. The technology is virtualizing conventional tiering between brake system suppliers and semiconductor vendors.
ECE R13 harmonization efforts across European commercial vehicle certification are mandating uniform actuator performance thresholds for cross-border truck and bus operations. The regulation compresses national variance in type-approval testing, forcing suppliers to design for the strictest common denominator. Heavy-duty pneumatic actuator manufacturers serving Germany, France, and Poland must consolidate previously divergent product lines to maintain margin structures.
Fleet operators are unbundling actuator replacement decisions from traditional dealership service networks. Large logistics companies in the United States negotiate direct sourcing agreements with Tier-1 manufacturers, bypassing aftermarket distributors. This procurement compression is most visible in long-haul trucking corridors where predictive maintenance data enables just-in-time component replacement rather than scheduled interval service.
Automotive Brake Actuator Market Segmentation
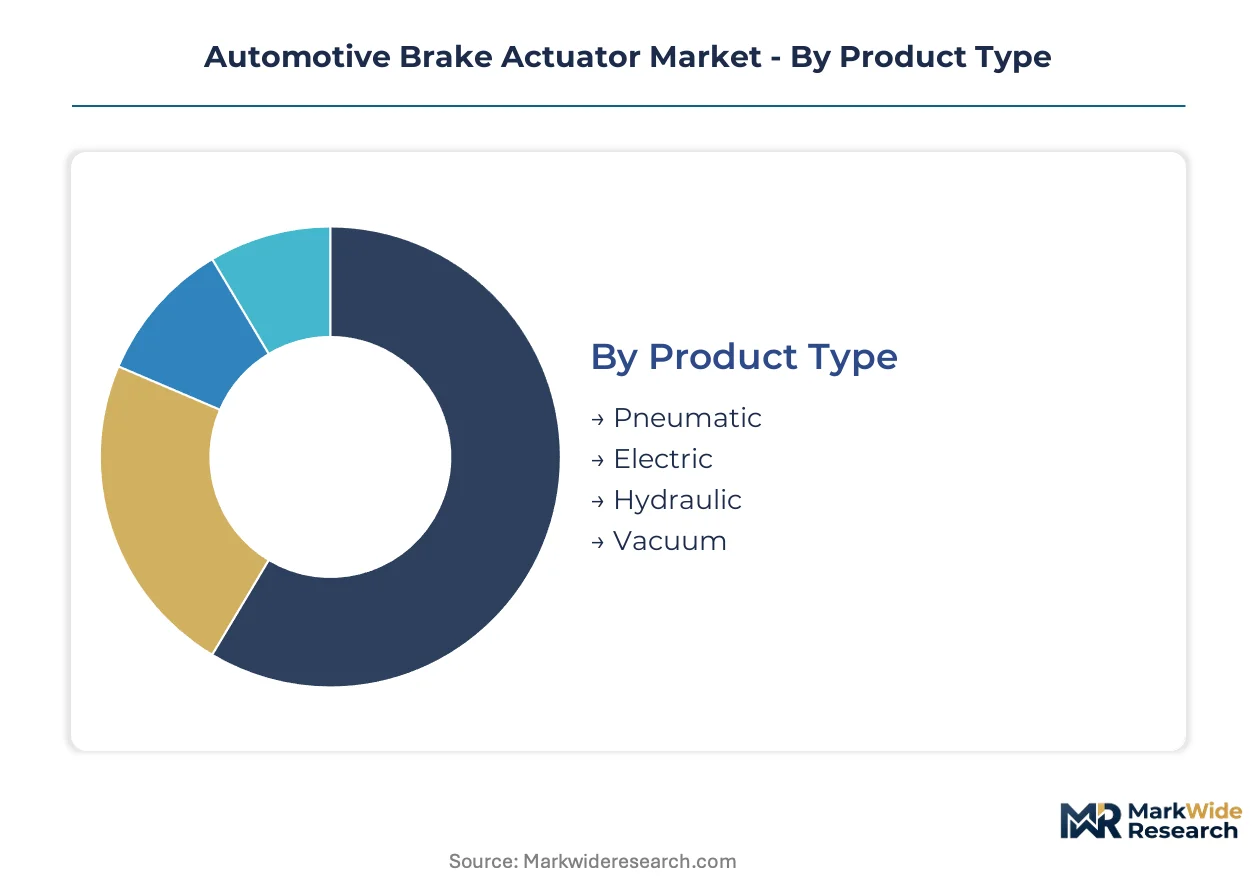
Brake actuator segmentation reveals divergent technology trajectories between passenger vehicle electrification and commercial vehicle infrastructure lock-in. Product architecture choices cascade through installation channels, vehicle applications, and control system integration requirements.
Product Type:
Cost tier differentiation separates mature pneumatic infrastructure from emerging electromechanical platforms demanding premium component sourcing.
- Electric:Motor-inverter-ECU combinations eliminate fluid lines entirely. German and Japanese premium passenger car platforms absorb these units to achieve sub-100-millisecond response latencies for autonomous emergency braking. Rare earth magnet cost volatility constrains margin expansion.
- Pneumatic:Compressed air systems dominate heavy-duty commercial truck applications where established service infrastructure and technician familiarity sustain installed base economics. North American long-haul fleets maintain replacement schedules aligned with NHTSA stopping-distance compliance cycles.
- Hydraulic:Conventional fluid-power architectures persist in mid-market passenger vehicles and legacy commercial platforms where brake-by-wire conversion costs outweigh performance benefits.
- Vacuum:Vacuum-dependent designs face phase-out across passenger car segments as automakers eliminate engine-driven vacuum sources in downsized and electrified powertrain architectures.
Pneumatic systems command the established base. The steepest expansion runs through Electric architectures.
Installation Type:
Application timing separates factory-integrated brake-by-wire consolidation from post-production service interventions.
- OEM:Factory installation captures value through sensor-actuator module consolidation and ISO 26262 functional safety certification bundled at vehicle assembly. Tier-1 suppliers anchor long-term platform supply agreements with German and Japanese automakers.
- Aftermarket:Replacement demand concentrates in aging ABS-equipped vehicle populations across mature European parcs where dealership service networks compete with independent distributors for actuator procurement.
- Retrofit:Electromechanical conversions into existing hydraulic architectures require custom mounting solutions that fragment production scale economies and extend engineering validation timelines.
- Integrated:Wheel-end assemblies combining motor, inverter, and ECU eliminate tiering between brake system suppliers and semiconductor vendors, compressing traditional supply chain margins.
OEM channels anchor volume concentration. Aftermarket pathways climb fastest as vehicle parcs age across Western Europe and North America.
Vehicle Type:
Customer type segmentation maps actuator specifications to duty-cycle intensity and regulatory compliance thresholds.
- Commercial Trucks:Heavy-duty pneumatic specifications face NHTSA stopping-distance mandates in the United States and ECE R13 harmonization across Germany, France, and Poland. Fleet operators negotiate direct sourcing agreements bypassing traditional distribution tiers.
- Passenger Cars:Premium platforms in Germany and Japan integrate electric brake-by-wire modules enabling autonomous emergency braking functionality. Volume manufacturers phase vacuum-dependent designs from electrified architectures.
- Buses:Urban transit and intercity coach applications combine high-cycle braking demands with regulatory mandates for anti-lock and stability control systems across European cross-border operations.
- Motorcycles:Two-wheeler applications concentrate ABS and combined braking system requirements in Indian and Southeast Asian markets where two-wheeler volumes dominate vehicle production.
Commercial Trucks retain the largest installed base. Passenger Cars gain share fastest through brake-by-wire consolidation.
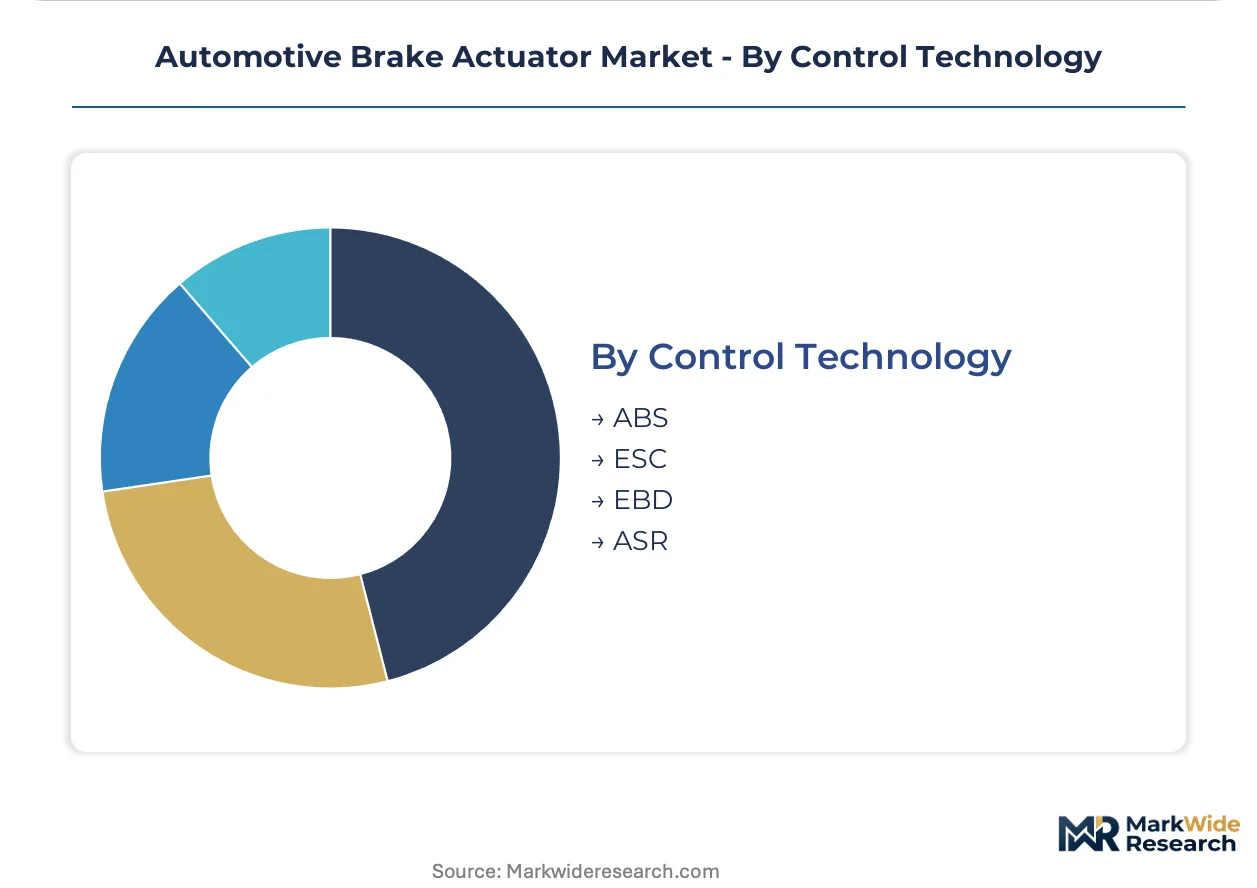
Control Technology:
Technology maturity stratifies actuator integration requirements across foundational stability systems and advanced intervention protocols.
- ABS:Anti-lock braking systems represent the baseline control layer, generating replacement actuator demand across aging vehicle populations in European and North American aftermarket channels.
- ESC:Electronic stability control mandates in the United States and European Union drive sensor-actuator module integration, with Robert Bosch GmbH and Continental AG competing through integrated hardware-software platforms.
- EBD:Electronic brake-force distribution optimizes axle-specific pressure allocation, requiring actuator response precision that favors electromechanical architectures over pneumatic alternatives.
- ASR:Anti-slip regulation extends actuator intervention into traction control scenarios, demanding faster response latencies than conventional ABS implementations.
ABS retains the broadest installed footprint. ESC integration expands most quickly through regulatory mandate convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Windsor automotive corridor anchors North American brake actuator demand through integrated OEM supply chains serving transnational vehicle assembly. German autobahns and Japanese expressway networks concentrate premium brake-by-wire adoption in parallel development clusters.
United States
NHTSA stopping-distance mandates drive heavy-duty truck fleet upgrades across interstate corridors from Texas to Michigan. The Department of Transportation enforces compliance timelines that synchronize with carrier maintenance cycles. Detroit-based Tier-1 suppliers coordinate pneumatic actuator specifications directly with long-haul logistics operators bypassing traditional distribution tiers.
Germany
Premium passenger car platforms in Stuttgart and Munich integrate electromechanical brake-by-wire modules for autonomous emergency braking functionality. ECE R13 harmonization compresses national variance in type-approval testing across cross-border commercial operations. Continental AG anchors captive manufacturing in Hanover to sustain fleet service contracts throughout European commercial corridors.
Japan
Tokyo and Nagoya automotive clusters concentrate sensor-actuator module development for ESC-equipped platforms. METI industrial standards guide functional safety certification pathways for electromechanical architectures. Denso Corporation and Aisin Corporation occupy positions within the supplier ecosystem serving domestic OEM brake-by-wire consolidation.
China
Yangtze River Delta vehicle production clusters absorb electric actuator volumes as domestic automakers phase vacuum-dependent designs from electrified architectures. MIIT technical standards govern brake system certification for new energy vehicle platforms. Shanghai and Jiangsu Province manufacturing bases supply both domestic OEM integration and export-oriented aftermarket channels.
India
Maharashtra and Tamil Nadu commercial vehicle assembly plants generate demand for pneumatic and hydraulic actuator specifications under BIS certification pathways. The national automotive mission plan aligns domestic truck fleet modernization with electric actuator adoption timelines. Pune-based suppliers serve both indigenous OEM requirements and export markets across Southeast Asian corridors.
Automotive Brake Actuator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying electromechanical sub-assemblies and pneumatic hardware. The market structure concentrates around diversified automotive suppliers with brake system heritage, while semiconductor vendors encroach on traditional tier boundaries through motor-inverter-ECU consolidation. Three archetypes dominate: diversified Tier-1 system houses, captive in-house production units of major OEMs, and focused electromechanical component specialists. Competitive moves center on brake-by-wire technology licensing agreements and backward integration into rare earth magnet supply chains.
Among German diversified suppliers, Continental AG and ZF Friedrichshafen AG exemplify platform integrators competing through consolidated sensor-actuator modules. Robert Bosch GmbH anchors the integrated hardware-software tier with ESC-equipped system architectures. These three entities represent divergent strategic postures: captive manufacturing for fleet service contracts, electromechanical specialization, and sensor-actuator module integration respectively.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Nissin Kogyo |
| Denso Corporation |
| Hyundai Mobis |
| Aisin Corporation |
| Magna International |
| HELLA GmbH & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese rare earth processing facilities compresses neodymium magnet margins for electromechanical actuator suppliers, forcing tier-1 manufacturers to renegotiate long-term offtake terms or absorb input volatility through captive inventory positions.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from aftermarket spot purchases across North American commercial corridors. Three-tier pricing stratification across ISO 26262 ASIL-D certified premium modules, standard ESC-integrated units, and economy-grade ABS replacements reflects certification investment recovery timelines. Cost compression in the economy tier intensifies as Chinese manufacturers expand electric actuator exports under MIIT technical standards. Fleet operators exhibit lowest price sensitivity due to predictive maintenance value capture, while independent repair shops face acute margin pressure from consolidated distribution.
Supply Chain Analysis
Export-control regimes limiting semiconductor fabrication equipment flows to Chinese wafer fabs concentrate motor-inverter-ECU production in Taiwan, South Korea, and Japan. Actuator assembly draws from German precision machining for housing components, Malaysian semiconductor packaging for power electronics, and Chinese rare earth magnet processing for rotor assemblies. Single-source vulnerability in neodymium separation exposes margin structures to supply quota fluctuations. Distribution runs through captive OEM supply agreements for brake-by-wire platforms and independent aftermarket distributors for replacement pneumatic units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across electric, pneumatic, and hydraulic architectures creates specialist opportunities as OEM platform diversification outpaces consolidated supplier adaptation.
For Market Incumbents: Entrench brake-by-wire platform supply agreements through backward integration into rare earth magnet sourcing and ISO 26262 ASIL-D certification investment. Capture fleet service contracts via predictive maintenance data integration. Defend against Chinese electric actuator exporters by anchoring European commercial corridor relationships through ECE R13 harmonization compliance. For New Entrants and Emerging Players: Pursue India commercial vehicle electrification pathways where BIS certification creates specification windows ahead of incumbent consolidation. Target aftermarket retrofit demand for aging ABS-equipped parcs in Western Europe through direct e-commerce distribution. Differentiate via electromechanical architecture specialization for motorcycle ABS applications in Southeast Asian volume markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical brake-by-wire sub-segments as motor-inverter-ECU consolidation demands semiconductor fabrication exposure. Long-term viability favors suppliers with functional safety certification heritage and rare earth supply hedging. Acquisition targets should demonstrate embedded software competency aligned with autonomous emergency braking convergence. Monitor NHTSA rulemaking timelines as inflection indicators for commercial vehicle replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Brake-by-Wire Platform Standardization | Reduces engineering validation costs for German and Japanese OEM consortiums. |
| Rare Earth Magnet Supply Agreement | Secures neodymium processing capacity against Chinese export quota volatility. |
| ISO 26262 ASIL-D Certification Investment | Unlocks premium pricing tiers for autonomous emergency braking integration. |
| Fleet Predictive Maintenance Partnership | Bypasses traditional aftermarket distribution through direct procurement channels. |
| India Manufacturing Footprint Expansion | Aligns with national automotive mission plan commercial vehicle modernization. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet maintenance directors; and secondary validation against vehicle production databases, IHS Markit registration data, NHTSA compliance filings, and ECE R13 type-approval records. Bottom-up actuator volume estimates triangulated against top-down automotive production forecasts across the analysis window.
Forecast inputs incorporated propulsion architecture segmentation by vehicle class, content-per-vehicle trajectories for brake-by-wire adoption, and regional production cluster capacity utilization. CAGRs derived from modeled unit shipments and average selling price evolution throughout the projection horizon. Rare earth magnet cost curves and ISO 26262 certification penetration rates served as automotive-specific demand shapers.
Sensitivities concentrate around NHTSA mandate enforcement timelines, Chinese rare earth export policy shifts, and brake-by-wire standard convergence pace. Cross-checking against vehicle parc age distributions and fleet replacement cycle data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Tappet Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Germany Automotive Pneumatic Actuators Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Engine Oils Market
Automotive Parts
North America Gear Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Automotive Seat Track Market