
 Automotive Autonomous Emergency Braking System Market | 2026-2036
Automotive Autonomous Emergency Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Autonomous Emergency Braking System Market Analysis
Market Context with Strategic Players
Capital-intensity divergence between integrated sensor developers and modular system assemblers is bifurcating competitive returns in the Automotive Autonomous Emergency Braking System space. Robert Bosch GmbH leverages in-house radar fabrication and software stacks to sustain margin capture across European OEM programs. Denso Corporation anchors its position through tight Toyota keiretsu relationships and thermal-management integration in sensor housings. Continental AG competes on fused camera-radar architectures that dominate premium German vehicle platforms.
Technical Definition and Structural Segments
An Automotive Autonomous Emergency Braking System is an active safety assembly that uses forward-facing sensors to detect imminent collision risks and autonomously applies braking force without driver intervention, typically operating at closing speeds up to 80 km/h for pedestrian scenarios and 130 km/h for vehicle-to-vehicle events. The system serves the primary commercial purpose of reducing rear-end and pedestrian collision frequency, thereby lowering insurance loss costs and regulatory compliance exposure for vehicle manufacturers. Camera-Integrated product configurations currently lead volume deployment due to lower unit costs, while Lidar-Controlled variants represent the fastest-growing sub-area as solid-state designs approach automotive price points. Machine Learning technology segments command the deepest margin pools because algorithm training datasets create defensive intellectual property moats against second-tier entrants.
Regulatory Frame and Forward-Looking Close
UN R152 mandates AEB performance for new passenger cars across UNECE member states, while NHTSA's automatic emergency braking commitment from twenty automakers covers the US market, and Euro NCAP scoring protocols effectively require AEB for five-star ratings in Europe. These frameworks shape demand by removing optional fitment discretion and standardizing minimum sensor performance thresholds that favor Tier-1 suppliers with established homologation track records. Stakeholders must monitor whether China's MIIT adopts equivalent mandatory AEB standards, as such a move would redirect sensor procurement volumes toward domestic supply chains and reshape competitive access.
Market Dynamics
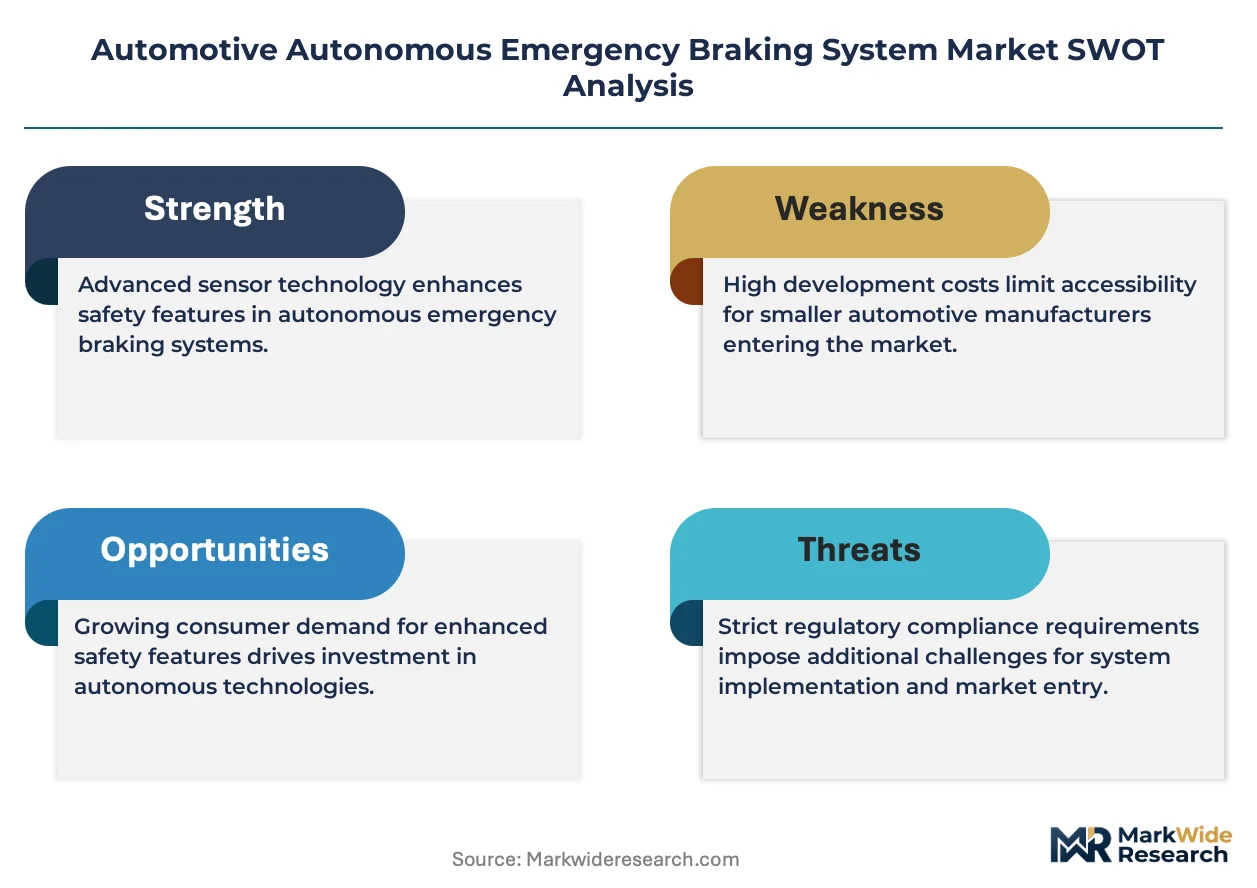
Regulatory mandates across Germany, Japan, and the United States are eliminating optional AEB fitment and forcing sensor procurement volumes toward Tier-1 suppliers with established homologation track records.
Growth Catalysts
- UN R152 Mandate:UNECE member states now require AEB performance certification for all new passenger cars, removing OEM discretion and standardizing minimum sensor thresholds.
- Euro NCAP Scoring Protocols:Five-star safety ratings in Europe are unattainable without functional AEB systems, compelling mid-range vehicle line upgrades.
- Solid-State Lidar Maturation:Automotive-grade solid-state designs are approaching cost parity with radar-camera fusion, opening premium vehicle segments to enhanced perception stacks.
Market Restraints
- Sensor Cost Volatility:Semiconductor shortages and rare-earth magnet dependencies in radar modules create input cost instability for system assemblers.
- Homologation Concentration:Established Tier-1 suppliers in Germany and Japan control regulatory testing infrastructure, raising barriers for new entrants.
- Technical Edge-Case Limitations:Adverse weather performance degradation in camera-dominant systems restricts operational envelopes in Nordic and monsoon climates.
Strategic Opportunities
- India Commercial Vehicle Segment:Underpenetrated truck and bus fleets present volume expansion potential as the country's Ministry of Road Transport considers mandate adoption.
- V2X Convergence:Integration of cellular vehicle-to-everything modules with AEB stacks enables cooperative perception beyond sensor line-of-sight.
- Insurance Channel Partnerships:Direct-to-fleet sales through telematics-linked underwriting programs bypass traditional OEM supply chains.
Industry Challenges
- Functional Safety Engineering Scarcity:ISO 26262-certified systems architects command premium compensation, constraining development velocity at mid-tier suppliers.
- Legacy Platform Integration Complexity:Retrofitting AEB onto older electrical architectures requires gateway controller redesigns that extend program timelines.
- Dataset Licensing Friction:Training-data ownership disputes between OEMs and algorithm developers complicate machine-learning model deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Autonomous Emergency Braking System Market |
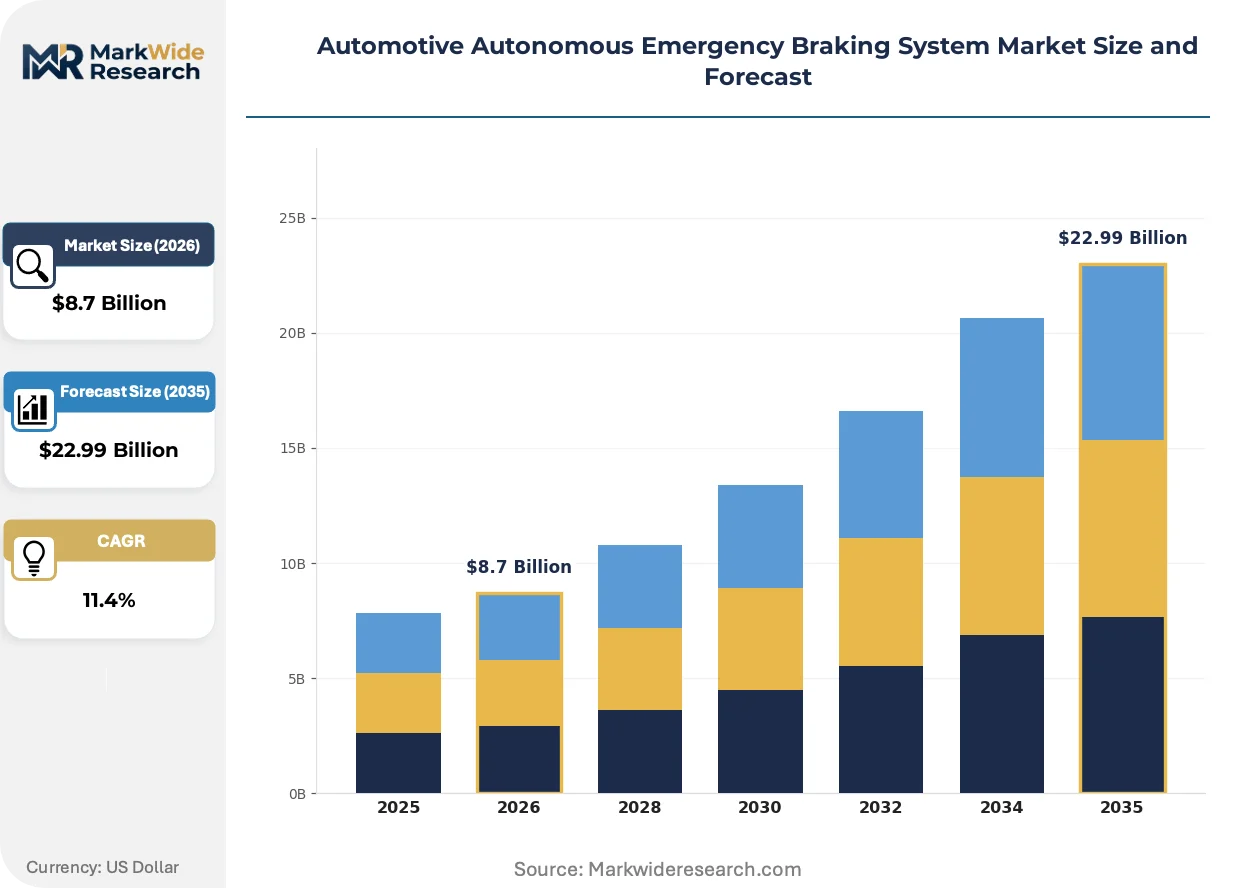
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor-Based, Lidar-Controlled, Camera-Integrated, Radar-Aided Technology: Machine Learning, Computer Vision, Ultrasonic Sensing, AI Algorithms End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Original Equipment, Retrofit Kits, Service Center, Dealer Installed |
| Companies Covered | Hyundai Mobis, Denso Corporation, Robert Bosch GmbH, Aisin Seiki Co Ltd, Autoliv Inc, Continental AG, Valeo, Mando Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Autonomous Emergency Braking System Market Emerging Trajectories
Sensor fusion architectures and regulatory scoring evolution are compressing single-modality system viability while opening margin pools for perception software specialists.
4D imaging radar is supplanting conventional 3D radar in premium German vehicle platforms by delivering elevation data without lidar cost structures. BMW and Mercedes-Benz procurement teams have accelerated 4D radar adoption for 2026 model year programs. This modality shift is supplanting camera-radar fusion as the baseline perception stack in vehicles above €50,000 price points.
NHTSA's automatic emergency braking commitment from twenty automakers is binding US market participants to standardized performance timelines regardless of federal rulemaking delays. The agreement's 2029 full-fleet coverage deadline is compressing development cycles for domestic Tier-2 suppliers. Light-truck and SUV segments face the steepest compliance ramps as these vehicle categories previously lagged passenger car fitment rates.
Fleet operators are consolidating sensor procurement decisions at the holding-company level rather than delegating to individual OEM relationships. This buying-pattern compression is forcing Tier-1 suppliers to establish direct commercial vehicle service networks parallel to OEM supply chains. North American long-haul trucking corridors exhibit the most pronounced procurement centralization, with megafleets negotiating multi-year AEB maintenance contracts independent of vehicle purchase agreements.
Automotive Autonomous Emergency Braking System Market Segmentation
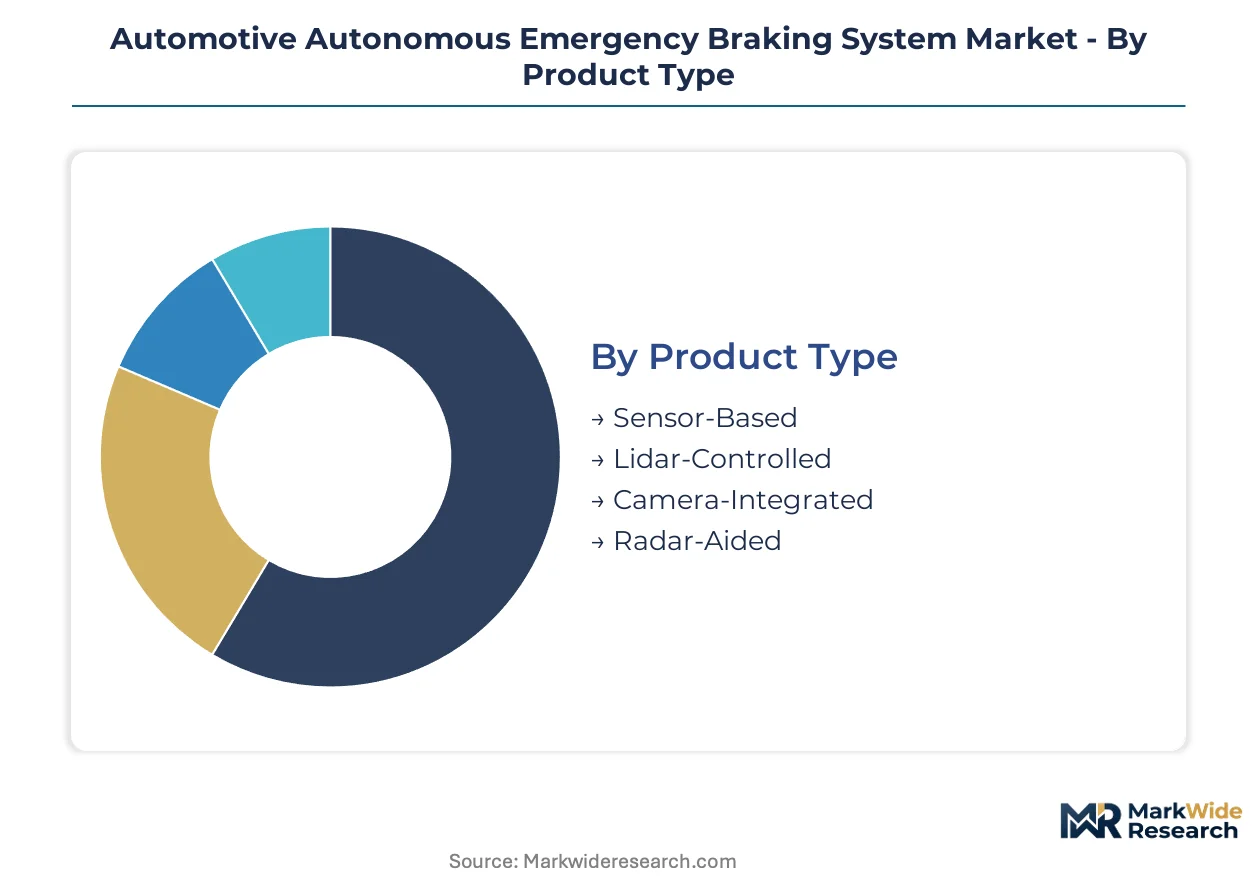
Segmentation in the Automotive Autonomous Emergency Braking System market reveals how procurement decisions concentrate around regulatory compliance thresholds and sensor modality trade-offs. Understanding these divisions exposes where margin pools form and which technical architectures command pricing power across vehicle price tiers.
Product Type:
Camera-Integrated configurations dominate domestic European and Japanese OEM programs where Euro NCAP scoring drives volume, while Lidar-Controlled variants concentrate in export-bound premium platforms targeting North American and Gulf state markets.
- Camera-Integrated:Combines forward-facing CMOS sensors with embedded image processors to detect vehicles and pedestrians through pattern recognition algorithms. Demand concentrates in Germany and Japan where Bosch and Denso supply mid-range passenger car lines facing Euro NCAP five-star mandates. Cost advantages over radar-lidar fusion sustain volume leadership despite weather-performance trade-offs.
- Lidar-Controlled:Employs solid-state or mechanical lidar emitters to generate dense 3D point clouds for object classification at extended ranges. Export-led demand from California and UAE-based premium EV manufacturers drives procurement, with solid-state designs approaching cost parity for vehicles above €50,000. Solid-state maturation is compressing unit economics fastest in this segment.
- Sensor-Based:Generic multi-modality architectures without dominant sensor primacy.
- Radar-Aided:77GHz and 4D imaging radar modules providing velocity and elevation data independent of optical conditions.
Camera-Integrated commands the established base. The steepest expansion runs through Lidar-Controlled.
Technology:
Cost tier separation is pronounced: Machine Learning and AI Algorithms occupy premium development budgets with dedicated training infrastructure, while Computer Vision and Ultrasonic Sensing serve standard and economy system tiers through licensed IP blocks.
- Machine Learning:Deep neural networks trained on proprietary collision datasets to predict trajectory intersections and false-positive rejection. Tier-1 suppliers with captive data lakes—Continental, Bosch, Denso—defend margin pools through dataset scale advantages that mid-tier entrants cannot replicate without OEM partnership.
- AI Algorithms:Deterministic rule-based systems augmented with lightweight inference engines for real-time decision optimization. Japanese and German OEMs specify these for next-generation platforms where functional safety certification (ISO 26262) intersects with adaptive behavior requirements. Regulatory pressure for explainable braking decisions favors this architecture.
- Computer Vision:Classical edge-detection and optical-flow methods deployed in cost-constrained retrofit applications.
- Ultrasonic Sensing:Short-range parking-adjacent systems with limited AEB functionality at low speeds.
Machine Learning holds the revenue concentration. AI Algorithms are climbing the fastest as homologation frameworks mandate traceable decision logic.
End User:
Volume concentration tilts toward OEM direct procurement in Germany and Japan, while aftermarket channel development lags except in North American commercial fleet segments where holding-company-level procurement bypasses traditional supply chains.
- OEMs:Volkswagen, Toyota, and Stellantis specify AEB as standard fitment across model lines to secure regulatory compliance and insurance premium reductions. Their purchasing power compresses Tier-1 margins while guaranteeing volume commitments that amortize sensor platform development costs across multi-year programs.
- Tier-1 Suppliers:Bosch, Continental, and Denso integrate sensor fabrication with software stacks to supply complete AEB modules to vehicle manufacturers. Their control of homologation testing infrastructure in Germany and Japan creates structural barriers for new entrants seeking regulatory certification.
- Aftermarket Providers:Independent installers serving retrofit demand where legacy fleet operators seek insurance-linked telematics integration.
- Vehicle Assemblers:Contract manufacturers without full OEM status purchasing pre-certified AEB subsystems.
OEMs anchor procurement volume. Aftermarket Providers are expanding most quickly through telematics-linked fleet underwriting programs.
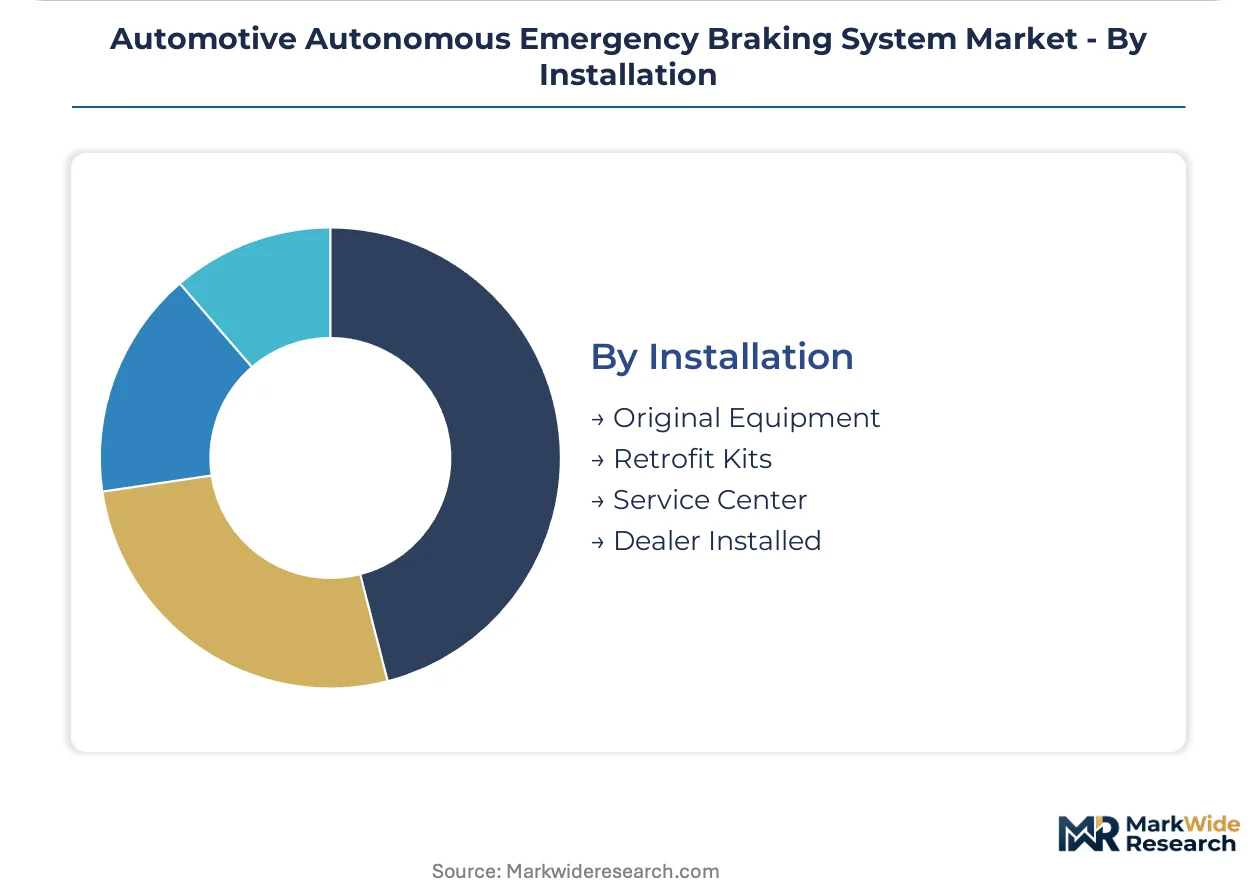
Installation:
Original Equipment captures regulatory-mandated new vehicle fitment in Europe and Japan, while Retrofit Kits concentrate in North American commercial trucking corridors where megafleets negotiate maintenance contracts independent of OEM relationships.
- Original Equipment:Factory-integrated AEB systems engineered into vehicle electrical architectures from program inception. UN R152 and Euro NCAP timelines force this installation mode for all new passenger cars in UNECE member states, with sensor calibration performed on assembly lines in Wolfsburg, Toyota City, and Stuttgart.
- Retrofit Kits:Aftermarket packages requiring gateway controller installation and CAN bus integration with legacy braking systems. North American long-haul trucking fleets in Texas and California corridors deploy these to satisfy insurer requirements without waiting for full fleet turnover, though technical complexity limits viable vehicle age to platforms with compatible electrical architectures.
- Service Center:Authorized third-party installation through branded maintenance networks.
- Dealer Installed:OEM-affiliated retrofit programs for certified pre-owned vehicle certification.
Original Equipment dominates current fitment. Retrofit Kits show the steepest expansion trajectory as commercial fleet operators accelerate compliance outside OEM purchase cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where Tier-1 suppliers command sensor procurement premiums, while cost-sensitive markets in India and Brazil compress margins through localized sourcing mandates.
United States
NHTSA's automatic emergency braking commitment from twenty automakers binds domestic OEMs to 2029 full-fleet coverage timelines. Light-truck and SUV segments face the steepest compliance ramps. Texas and California corridors exhibit pronounced procurement centralization among megafleets negotiating maintenance contracts.
Germany
UN R152 homologation requirements and Euro NCAP five-star scoring protocols compel technology upgrades across Volkswagen, BMW, and Mercedes-Benz model lines. Stuttgart and Wolfsburg assembly plants integrate sensor calibration into production sequences. Bosch and Continental leverage in-house radar fabrication to sustain margin capture.
Japan
Toyota keiretsu relationships anchor Denso Corporation's position through thermal-management integration in sensor housings. METI standards alignment with UNECE frameworks accelerates domestic platform refreshes. Toyota City and Nagoya clusters concentrate AEB module production for export-bound vehicles.
China
MIIT consideration of mandatory AEB standards would redirect sensor procurement toward domestic supply chains. BYD and NIO expansion in premium EV segments drives solid-state lidar adoption. Yangtze River Delta manufacturing bases approach automotive-grade solid-state cost parity.
India
Ministry of Road Transport evaluation of commercial vehicle mandate adoption presents volume expansion potential for underpenetrated truck and bus fleets. Tamil Nadu and Maharashtra automotive corridors attract Tier-1 suppliers establishing localized assembly. Retrofit kit demand concentrates in long-haul corridors linking Delhi to Mumbai.
Automotive Autonomous Emergency Braking System Market Vendor Landscape
Concentration sits with diversified automotive Tier-1 suppliers possessing captive sensor fabrication and established homologation track records. Three archetypes dominate: integrated sensor developers controlling radar and camera module production, modular system assemblers purchasing components from upstream specialists, and perception software houses licensing algorithm IP to hardware partners. Dominant competitive moves include backward integration into semiconductor packaging and strategic partnerships with solid-state lidar startups to secure next-generation perception stacks.
Within the integrated sensor developer tier, Robert Bosch GmbH and Denso Corporation exemplify the archetype through geographic anchoring in Germany and Japan respectively. Continental AG occupies a position bridging hardware fabrication with fused perception architectures. These three entities represent the concentration of regulatory testing infrastructure control that raises barriers for new entrants seeking UN R152 or NHTSA certification.
| Leading Market Players |
|---|
| Hyundai Mobis |
| Denso Corporation |
| Robert Bosch GmbH |
| Aisin Seiki Co Ltd |
| Autoliv Inc |
| Continental AG |
| Valeo |
| Mando Corporation |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Solid-state lidar substitution for radar-camera fusion is simultaneously shifting sensor procurement toward Yangtze River Delta manufacturing bases and compressing unit economics for premium vehicle platforms above €50,000. This substitution dynamic concentrates margin capture with integrated developers possessing captive semiconductor packaging capabilities while forcing modular assemblers toward cost-competitive geographies.
Pricing Analysis
The customization-premium spread separates configured-to-order AEB stacks with fused perception architectures from standard camera-integrated systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from Volkswagen-scale OEMs. Cost compression in standard-tier camera systems is intensifying because Bosch and Denso amortize platform development across multi-year programs. Fleet procurement managers exhibit highest price sensitivity, while German premium OEMs prioritize performance thresholds over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for semiconductor packaging materials and rare-earth magnet inputs. Sensor module fabrication concentrates in Germany, Japan, and China's Yangtze River Delta, drawing from silicon wafer supplies in Taiwan and South Korea and specialized optical components from Japan. Single-source vulnerability in automotive-grade radar chipsets creates supply chain risk. Distribution runs through Tier-1 supplier direct channels to OEM assembly plants with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where telematics-linked maintenance contracts and over-the-air calibration updates expand faster than hardware shipments. Recurring revenue layers from fleet monitoring subscriptions now outpace one-time sensor sales in North American commercial corridors.
For Market Incumbents: Fortify backward integration into semiconductor packaging to defend margin pools against modular assemblers sourcing from upstream specialists. Deepen captive production of 4D imaging radar modules in Stuttgart and Nagoya clusters. Expand direct service networks for megafleet maintenance contracts bypassing traditional OEM supply chains. For New Entrants and Emerging Players: Differentiate on retrofit kit compatibility for legacy commercial vehicle electrical architectures in Indian long-haul corridors linking Delhi to Mumbai. Target underpenetrated truck and bus fleets where Ministry of Road Transport mandate adoption remains pending. Pursue insurance channel partnerships offering telematics-linked underwriting programs as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed perception software houses possessing ISO 26262-certified algorithm stacks but lacking homologation infrastructure control. Long-term viability in this market hinges on regulatory certification track records spanning multiple geographies. Acquisition targets should show established UN R152 testing relationships. Monitor China's MIIT for mandatory AEB standard adoption as inflection signal redirecting procurement volumes toward domestic supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Standardization | Bosch and Continental leverage unified radar-camera architectures to reduce OEM integration costs across Volkswagen programs. |
| Solid-State Lidar Supply Agreement | Premium German OEMs secure next-generation perception stacks for 2026 model year vehicles above €50,000 price points. |
| Software-Defined Vehicle Investment | Over-the-air calibration capabilities enable recurring revenue from fleet monitoring subscriptions independent of hardware replacement cycles. |
| Geographic Manufacturing Footprint | Yangtze River Delta bases approach cost parity for automotive-grade solid-state designs serving BYD and NIO expansion. |
| Telematics Infrastructure Partnership | North American megafleets negotiate multi-year maintenance contracts linking AEB performance data to insurance underwriting terms. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filing databases, vehicle production registries, and Tier-1 supplier technical disclosures. Primary interviews engaged OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and fleet telematics operators across Germany, Japan, and the United States. Secondary sources included UN R152 homologation records, Euro NCAP test protocols, NHTSA commitment documentation, and IHS Markit vehicle registration data. Bottom-up sensor shipment estimates triangulate against top-down OEM production forecasts.
Segmentation dimensions modeled span product type, technology architecture, end-user category, and installation mode across vehicle class, propulsion architecture, and regional production cluster. CAGRs derive from regression analysis of historical fitment rates projected against regulatory mandate timelines. Industry-specific inputs incorporate Euro NCAP scoring evolution, UN R152 implementation schedules, and solid-state lidar cost curves.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or semiconductor supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding mandate adoption schedules and sensor modality substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market