
 Global Semi Autonomous and Autonomous Truck Market | 2026-2036
Global Semi Autonomous and Autonomous Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semi Autonomous and Autonomous Truck Market Outlook
SAE J3016 automation-level classification is redrawing competitive boundaries for commercial vehicle autonomy. Daimler Truck AG leverages integrated powertrain and chassis control systems to anchor its position in hub-to-hub automation. Aurora Innovation Inc. competes through its FirstLight LiDAR platform and carrier partnerships across the southwestern United States. Waymo LLC sustains its advantage via billions of accumulated real-world autonomous miles and relationships with freight networks.
Semi autonomous and autonomous trucks integrate multi-modal sensor arrays—LiDAR point clouds, radar velocity maps, camera visual feeds, and ultrasonic proximity data—processed through redundant compute stacks to execute longitudinal and lateral vehicle control without continuous human intervention. These systems serve commercial freight operations by reducing per-mile labor costs and enabling continuous fleet utilization beyond human driving-hour limits. Heavy-duty trucks dominate current deployment as long-haul routes offer the simplest operational design domains, while electric trucks represent the fastest-growing product type as battery energy density improvements align with autonomous energy management. Highway deployment captures the deepest margin pools today due to predictable road geometry and limited pedestrian interaction, though urban last-mile segments attract accelerating investment from logistics providers seeking full network automation.
FAA regulations for autonomous ground vehicle coordination near air cargo hubs, NHTSA Federal Motor Vehicle Safety Standards for automated driving system equipment, and EPA emissions frameworks for heavy-duty powertrains collectively shape product certification pathways and market access timelines in the United States. EMA and EU AI Act compliance requirements in Europe impose parallel validation standards that fragment development resources across regulatory jurisdictions. Stakeholders must monitor which geography first harmonizes insurance liability frameworks with operational permits, as that alignment will determine where scaled commercial deployment becomes economically viable before competing regions.
Market Dynamics
The convergence of SAE Level 4 automation standards with hub-to-highway freight corridors is compressing development timelines and redrawing competitive boundaries across commercial vehicle autonomy.
Growth Catalysts
- FAA Ground Vehicle Coordination:Regulations enabling autonomous truck access near air cargo hubs in the United States are opening dedicated freight corridors for time-sensitive logistics operations.
- LiDAR-Radar Sensor Fusion:Multi-modal perception architectures are reducing system redundancy costs while maintaining safety-critical performance thresholds for highway deployment.
- Long-Haul Labor Economics:Per-mile driver cost structures in North American freight are accelerating carrier willingness to pilot autonomous alternatives on predictable interstate routes.
Market Restraints
- Lithium-Ion Battery Supply:Concentration of cathode material processing in China creates input cost volatility and geopolitical exposure for electric autonomous truck programs.
- EU AI Act Compliance:Parallel validation requirements for automated driving systems in Europe fragment engineering resources and extend certification timelines.
- Insurance Liability Fragmentation:Misaligned state-level fault determination rules in the United States prevent standardized commercial deployment at scale.
Strategic Opportunities
- Platooning Corridors:Dedicated I-10 and I-40 freight lanes connecting California, Arizona, and Texas offer controlled operational design domains for early revenue generation.
- Last-Mile Electrification:Battery energy density improvements converging with autonomous energy management systems are opening urban delivery applications previously reserved for human drivers.
- Japan METI Standards:Early harmonization of automated vehicle insurance frameworks in Asian markets may attract deployment investment ahead of Western regulatory alignment.
Industry Challenges
- Redundant Compute Architectures:Dual-stack verification requirements demand specialized embedded systems engineering talent that remains scarce across automotive and technology sectors.
- NHTSA FMVSS Certification:Automated driving system equipment approval timelines extend 18-24 months, compressing first-mover advantage windows for technology developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semi Autonomous and Autonomous Truck Market |
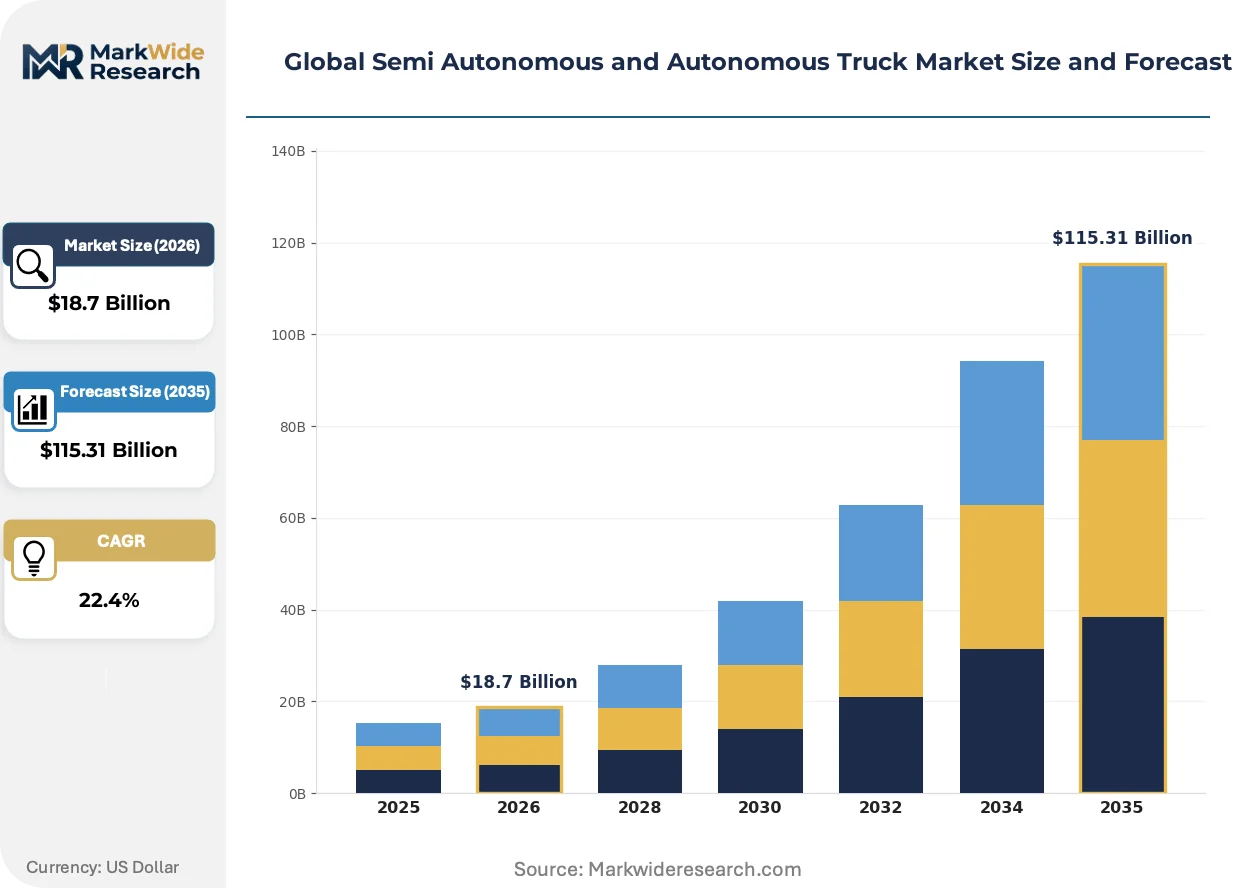
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Camera, Ultrasonic Sensors End User: Retailers, Logistics Providers, Fleet Operators, Manufacturers Product Type: Heavy-Duty Trucks, Light-Duty Trucks, Medium-Duty Trucks, Electric Trucks Deployment: On-Road, Off-Road, Urban, Highway |
| Companies Covered | Daimler Truck AG, AB Volvo, PACCAR Inc., Aurora Innovation Inc., Waymo LLC, TuSimple Inc., Plus.ai Inc., Kodiak Robotics Inc., IVECO S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semi Autonomous and Autonomous Truck Market Strategic Shifts
Sensor fusion architectures and regulatory harmonization efforts are actively reshaping how autonomous truck systems achieve commercial validation and fleet integration across freight networks.
Domain-specific compute platforms are decomposing the traditional centralized vehicle architecture into distributed processing nodes. Tier-1 suppliers and fleet operators are adopting zonal electronic control unit configurations to reduce wiring complexity and improve fault isolation. This decomposition is enabling faster over-the-air updates and reducing hardware refresh cycles from seven years to three.
REACH chemical safety assessments and EU AI Act conformity evaluations are imposing parallel technical documentation requirements on sensor manufacturers and system integrators. Industrial consequence includes extended supplier qualification timelines and accelerated vertical integration into component certification. European heavy-duty OEMs are responding by consolidating LiDAR and camera module sourcing under captive quality assurance protocols.
Freight procurement is compressing contract durations from annual to quarterly terms as carriers demand flexibility to integrate autonomous capacity without long-term fleet commitments. Asset-light logistics providers are displacing traditional dedicated contract carriage with dynamic routing platforms that mix human-driven and autonomous capacity. This behavioral shift is most visible in southwestern United States corridors where pilot programs concentrate.
Global Semi Autonomous and Autonomous Truck Market Segmentation
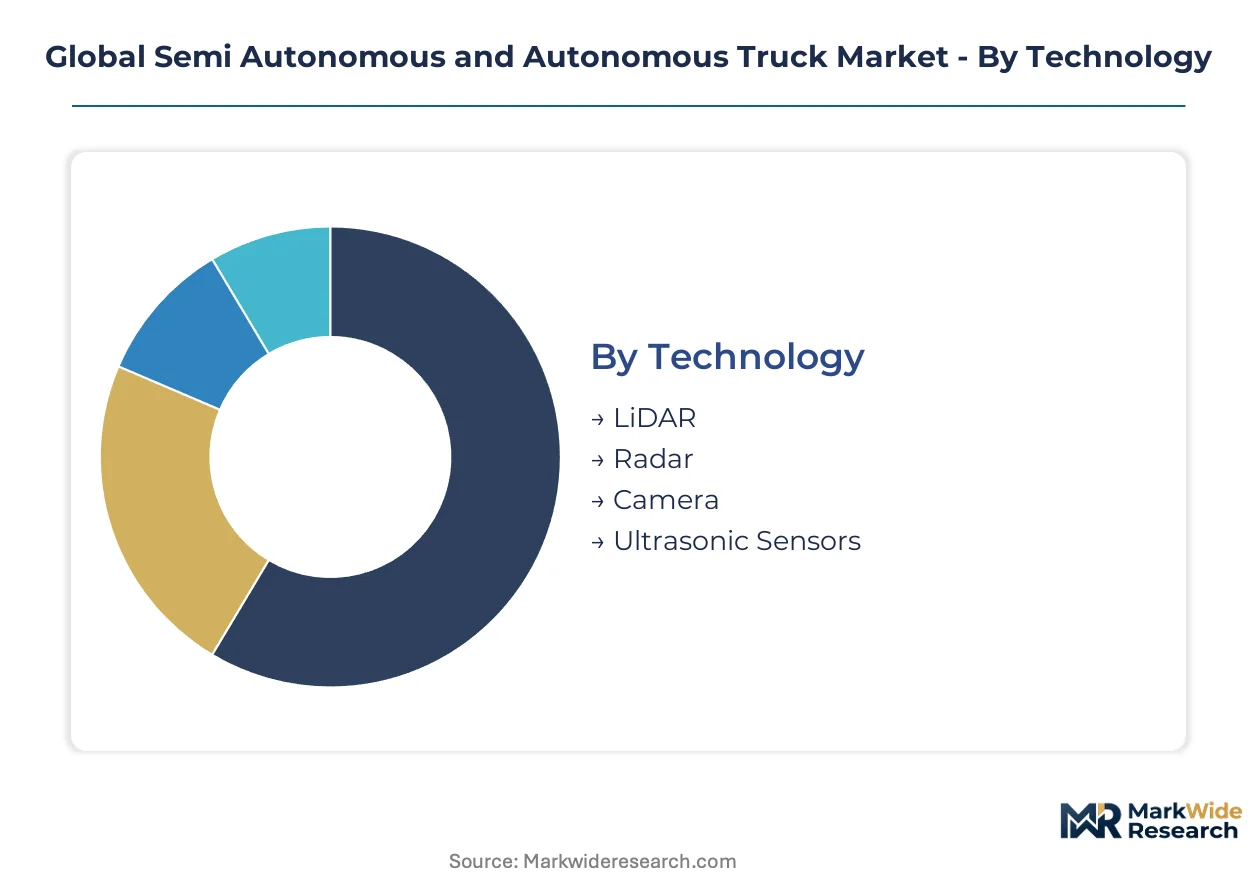
Technology choices determine regulatory compliance pathways and sensor fusion costs across freight corridors. End-user concentration shapes pilot program scale and revenue timing for autonomous truck deployments.
Technology:
LiDAR and radar systems anchor North American highway automation, while camera-dominant architectures gain traction in cost-sensitive European pilots. Ultrasonic arrays remain concentrated in low-speed yard operations.
- LiDAR:FirstLight and similar platforms generate 360-degree point clouds for SAE Level 4 decision-making. Demand concentrates along I-10 and I-40 corridors where dust and glare conditions stress optical alternatives. NHTSA FMVSS certification timelines favor established LiDAR suppliers with prior automotive validation.
- Radar:Velocity mapping and all-weather reliability make radar essential for redundant perception stacks. German freight operators on A2 and A9 autobahn corridors prioritize radar fusion to meet KBA type-approval requirements for mixed-traffic operation.
- Camera:Visual feed processing enables lane-keeping and traffic sign recognition at lowest hardware cost. Chinese port automation projects deploy camera-primary systems under MIIT GB standards for controlled environments.
- Ultrasonic Sensors:Proximity detection for parking and yard maneuvering operates at sub-10-meter ranges. Japanese METI guidelines encourage ultrasonic redundancy for last-meter safety near distribution centers.
LiDAR commands the established base. The steepest expansion runs through camera systems gaining algorithmic capability.
End User:
Fleet operators control deployment scale through hub-to-highway corridor access. Retailers and manufacturers lag in direct adoption, instead contracting logistics providers for autonomous capacity.
- Fleet Operators:Dedicated contract carriers with terminal infrastructure in Phoenix, Dallas, and Los Angeles anchor pilot program volume. These operators leverage existing maintenance networks to support autonomous truck uptime requirements.
- Logistics Providers:Asset-light platforms mix human-driven and autonomous capacity through dynamic routing software. Demand from 3PLs concentrates in southwestern United States corridors where freight density justifies automation capital expenditure.
- Retailers:E-commerce fulfillment networks seek autonomous middle-mile solutions between regional distribution centers. Walmart and Amazon-scale operators pilot hub-to-hub automation without direct fleet ownership.
- Manufacturers:Automotive and industrial producers evaluate autonomous inbound logistics for assembly plant supply chains. German OEMs test autonomous supplier milk runs under EU AI Act conformity frameworks.
Fleet operators capture the deepest automation investment. Logistics providers are climbing the fastest as asset-light models reduce deployment risk.
Product Type:
Heavy-duty configurations dominate long-haul economics, while electric powertrains reshape energy management architectures for autonomous operation.
- Heavy-Duty Trucks:Class 8 tractors with 80,000-pound gross vehicle weight ratings execute interstate freight automation. Battery-electric heavy-duty variants face payload tradeoffs that autonomous energy optimization partially offsets.
- Electric Trucks:Zero-emission powertrains align with California Air Resources Board mandates and autonomous fleet charging optimization. Energy density improvements enable 300-mile autonomous routes with mid-journey fast-charging infrastructure.
- Medium-Duty Trucks:Class 4-6 vehicles serve regional distribution and urban freight applications. These trucks bridge highway automation and last-mile manual operation in mixed fleets.
- Light-Duty Trucks:Class 1-3 configurations address final-mile delivery and small-freight logistics. Autonomous light-duty deployment concentrates in Arizona and Texas regulatory environments with streamlined testing permits.
Heavy-duty trucks command the established base. Electric trucks are gaining share fastest through emissions compliance and energy management convergence.
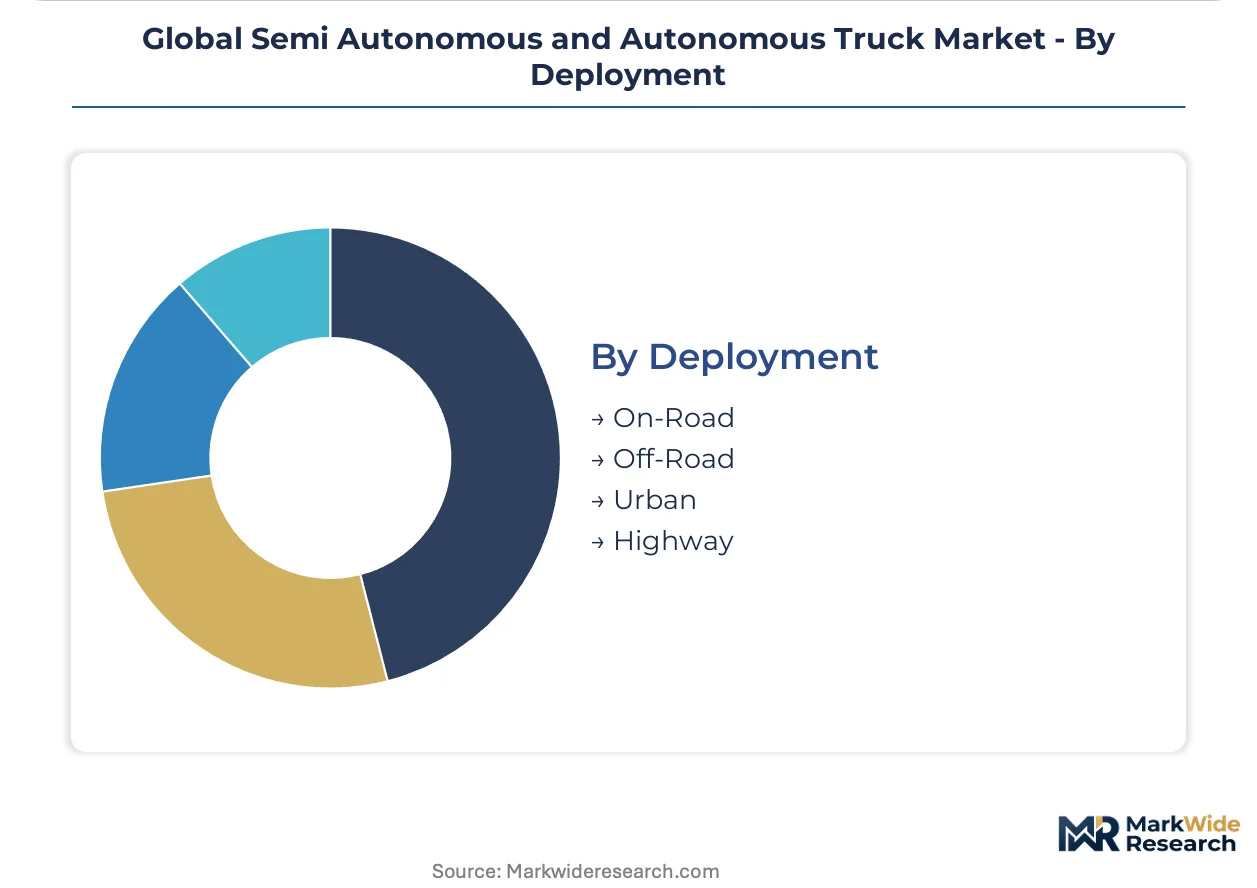
Deployment:
Highway environments offer simplest operational design domains, while urban deployment demands pedestrian interaction capabilities that extend development timelines.
- Highway:Predictable road geometry and limited intersection complexity enable SAE Level 4 commercial operation. I-10 and I-40 corridors provide controlled environments with minimal weather variability.
- Urban:Signalized intersections, cyclist presence, and construction zones demand higher computational redundancy. Waymo and Aurora concentrate urban testing in Phoenix and San Francisco Bay Area suburbs.
- On-Road:Public street operation encompasses both highway and urban domains under unified regulatory permits. NHTSA automated driving system equipment standards apply across on-road deployment categories.
- Off-Road:Mining, agriculture, and port terminal automation operate outside FMVSS jurisdiction. Australian iron ore mines and Rotterdam container terminals deploy off-road autonomous haulage at commercial scale.
Highway deployment commands the established base. Urban segments are climbing the fastest as last-mile electrification converges with automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-10 interstate corridor connecting Los Angeles to Phoenix underpins North American autonomous freight density, while Rotterdam's port automation infrastructure anchors European deployment timelines.
United States
Hub-to-highway freight corridors along I-10 and I-40 generate concentrated pilot demand from logistics providers seeking continuous fleet utilization. NHTSA Federal Motor Vehicle Safety Standards govern automated driving system equipment approval with 18-24 month certification timelines. Phoenix, Dallas, and Los Angeles terminal clusters host dedicated contract carriers leveraging existing maintenance networks for autonomous truck uptime.
Germany
A2 and A9 autobahn corridors attract freight operators prioritizing radar fusion for mixed-traffic type-approval under KBA standards. EU AI Act conformity evaluations impose parallel technical documentation requirements extending supplier qualification timelines. Stuttgart and Munich industrial zones concentrate OEM testing of autonomous supplier milk runs for assembly plant supply chains.
China
Port automation projects at Shanghai and Ningbo deploy camera-primary systems under MIIT GB standards for controlled container terminal environments. Dual carbon goals accelerate battery-electric autonomous truck alignment with emissions reduction mandates. Yangtze River Delta manufacturing clusters integrate autonomous inbound logistics for automotive production networks.
Japan
METI guidelines encourage ultrasonic redundancy for last-meter safety near distribution centers, shaping sensor architecture requirements. Early harmonization of automated vehicle insurance frameworks attracts deployment investment ahead of Western regulatory alignment. Chubu and Kansai logistics hubs test autonomous middle-mile solutions between regional distribution centers.
Australia
Iron ore mining operations in Western Australia deploy off-road autonomous haulage at commercial scale outside standard vehicle safety jurisdiction. TGA-equivalent mining safety protocols enable accelerated deployment timelines absent public road regulatory complexity. Pilbara region extraction sites demonstrate fully autonomous heavy-duty haulage in closed operational design domains.
Global Semi Autonomous and Autonomous Truck Market Competitive Environment
Listed leaders compete with private specialists across capital access and development velocity, producing a tiered structure where public OEMs anchor hardware integration while venture-backed autonomy developers concentrate perception software. Strategic archetypes separate integrated truck manufacturers, pure-play autonomy stack providers, and fleet-operator technology joint ventures. Dominant competitive moves include captive sensor module sourcing under quality assurance protocols and carrier partnership structures for corridor-specific deployment rights.
Within the integrated manufacturer tier, Daimler Truck AG and AB Volvo occupy positions combining powertrain control with chassis automation development. Aurora Innovation Inc. and Waymo LLC exemplify the autonomy-software archetype, accumulating real-world operational data through freight network relationships. TuSimple Inc. and Kodiak Robotics Inc. represent venture-backed specialists targeting hub-to-highway corridor commercialization.
| Leading Market Players |
|---|
| Daimler Truck AG |
| AB Volvo |
| PACCAR Inc. |
| Aurora Innovation Inc. |
| Waymo LLC |
| TuSimple Inc. |
| Plus.ai Inc. |
| Kodiak Robotics Inc. |
| IVECO S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month NHTSA FMVSS certification timelines concentrate pricing power among established LiDAR suppliers with prior automotive validation, while tiered volume discounts compress margins for late entrants seeking corridor deployment rights.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments autonomous truck systems by sensor fusion complexity and certification grade. Premium tiers command position through FirstLight-equivalent LiDAR platforms with redundant compute stacks, while standard tiers compete on radar-camera fusion for highway-only operation. Cost compression in economy tiers reflects camera-dominant architectures from Chinese suppliers under MIIT GB standards. Fleet operators with terminal infrastructure in Phoenix, Dallas, and Los Angeles exhibit lowest price sensitivity due to uptime guarantees, whereas asset-light logistics providers negotiating quarterly contract terms drive hardest bargain.
Supply Chain Analysis
China and South Korea anchor cathode material processing and battery cell manufacturing for electric autonomous truck programs, while Germany and Japan concentrate precision radar module production. Sensor fusion architectures draw from Taiwanese semiconductor foundries for compute stack components and Mexican assembly plants for chassis integration. Single-source vulnerability in lithium hydroxide refining creates tariff exposure through US-China trade policy friction. Distribution runs through captive supplier networks under OEM quality assurance protocols, bypassing traditional Tier-1 distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in urban last-mile automation where regulatory heterogeneity creates niche entry points for specialized sensor packagers.
For Market Incumbents: Compound defensive position through backward integration into LiDAR module certification and captive maintenance network expansion in southwestern corridor terminals. Aurora Innovation and Waymo partnerships threaten carrier relationship exclusivity; vertical integration into sensor manufacturing insulates margin structure from Chinese supply volatility. For New Entrants and Emerging Players: Lead with camera-primary architectures for Japanese METI-compliant yard automation, where ultrasonic redundancy requirements favor modular system designers over integrated OEMs. Last-meter safety applications near Chubu distribution centers represent most penetrable white space. Go-to-market through METI-registered insurance framework alignment accelerates permit acquisition ahead of Western regulatory harmonization. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier-1 suppliers with stranded LiDAR development programs following OEM vertical integration moves. Five-to-ten-year viability hinges on corridor-specific deployment rights rather than technology differentiation alone. Signal to watch: state-level insurance liability harmonization enabling standardized commercial permits at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Certification Investment | NHTSA FMVSS pre-validation compresses carrier procurement cycles for established suppliers. |
| Corridor-Specific Carrier Partnership | I-10 and I-40 deployment rights lock in freight density for pilot program scaling. |
| Backward Integration into LiDAR Manufacturing | Captive supply of FirstLight-equivalent platforms insulates margin from Chinese input volatility. |
| Urban Last-Mile Platform Development | Phoenix and San Francisco Bay Area testing accumulates pedestrian interaction datasets for regulatory submission. |
| EU AI Act Conformity Documentation | Parallel technical qualification enables German A2 and A9 autobahn corridor access ahead of fragmented competitors. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, autonomous vehicle program managers, NHTSA regulatory affairs leads, and Tier-1 supplier procurement heads; and secondary validation through NHTSA FMVSS docket filings, FAA autonomous ground vehicle coordination notices, SEC 10-K autonomy program disclosures, and EU AI Act conformity assessment databases. Bottom-up deployment projections across hub-to-highway corridors triangulated against top-down freight density models.
Across the analysis window, forecasts model technology adoption by sensor fusion architecture, end-user procurement model, vehicle powertrain configuration, and deployment environment complexity. CAGRs derive from corridor-specific pilot program scaling assumptions and carrier willingness-to-pay elasticity for autonomous capacity. Battery energy density improvement curves and charging infrastructure buildout schedules feed electric truck segment projections.
Forecasts assume regulatory continuity in NHTSA FMVSS certification timelines and EU AI Act conformity pathways; material policy shifts in insurance liability harmonization or lithium-ion battery sourcing restrictions would require re-modeling. Recalibration cycles align with material shifts in corridor deployment permit issuance and cathode material supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Automotive Adaptive Cruise Control Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Europe Autonomous Navigation Market