
 Robotaxi Market | 2026-2036
Robotaxi Market Size, Share, and Industry Trends Forecast 2026-2036
Robotaxi Market Analysis
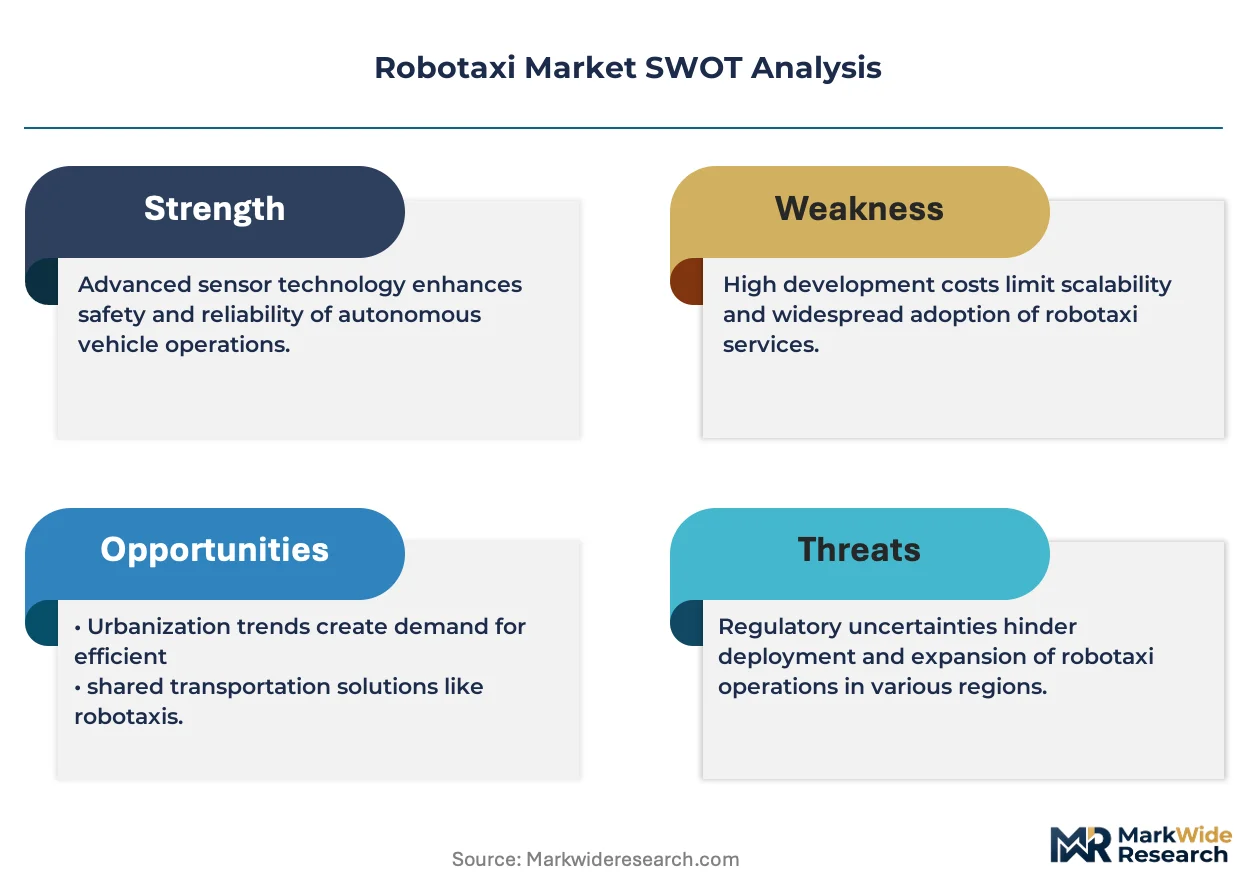
California's autonomous vehicle testing infrastructure is pivoting toward commercial robotaxi deployment at scale. Waymo leverages its LiDAR-heavy sensor stack to sustain operational coverage across Phoenix, San Francisco, and Los Angeles. Baidu anchors its position in Beijing and Wuhan through Apollo Go, where it competes with Didi Chuxing's autonomous division. Tesla differentiates through its computer-vision-only approach, positioning Full Self-Driving as a future robotaxi enabler without redundant hardware.
A robotaxi denotes a fully autonomous, self-driving vehicle configured for commercial passenger transport without a human safety operator. The system integrates LiDAR, radar, computer vision, and GPS fusion to achieve SAE Level 4 or 5 autonomy, with redundant braking, steering, and compute architectures ensuring fail-operational performance. Ride-hailing dominates service type revenue pools due to immediate addressable demand and per-mile economics, while shuttle services occupy structured environments such as airports and business parks where geofencing reduces complexity. Electric vehicles lead vehicle type adoption because battery platforms accommodate the high electrical loads of sensor suites and compute clusters, and because fleet operators prioritize total cost of ownership over upfront capital.
The NHTSA governs vehicle safety standards and crashworthiness for autonomous systems in the United States, while the FAA coordinates low-altitude airspace rules that indirectly shape ground-based mobility corridors in dense cities. China's MIIT and SAMR jointly administer GB standards for connected vehicles and data security, creating a dual-track compliance burden for multinationals. The EU AI Act and GDPR impose algorithmic transparency and biometric data restrictions that affect passenger monitoring systems. Stakeholders must monitor how regulator fragmentation across Washington, Beijing, and Brussels reshapes deployment timelines and data localization requirements.
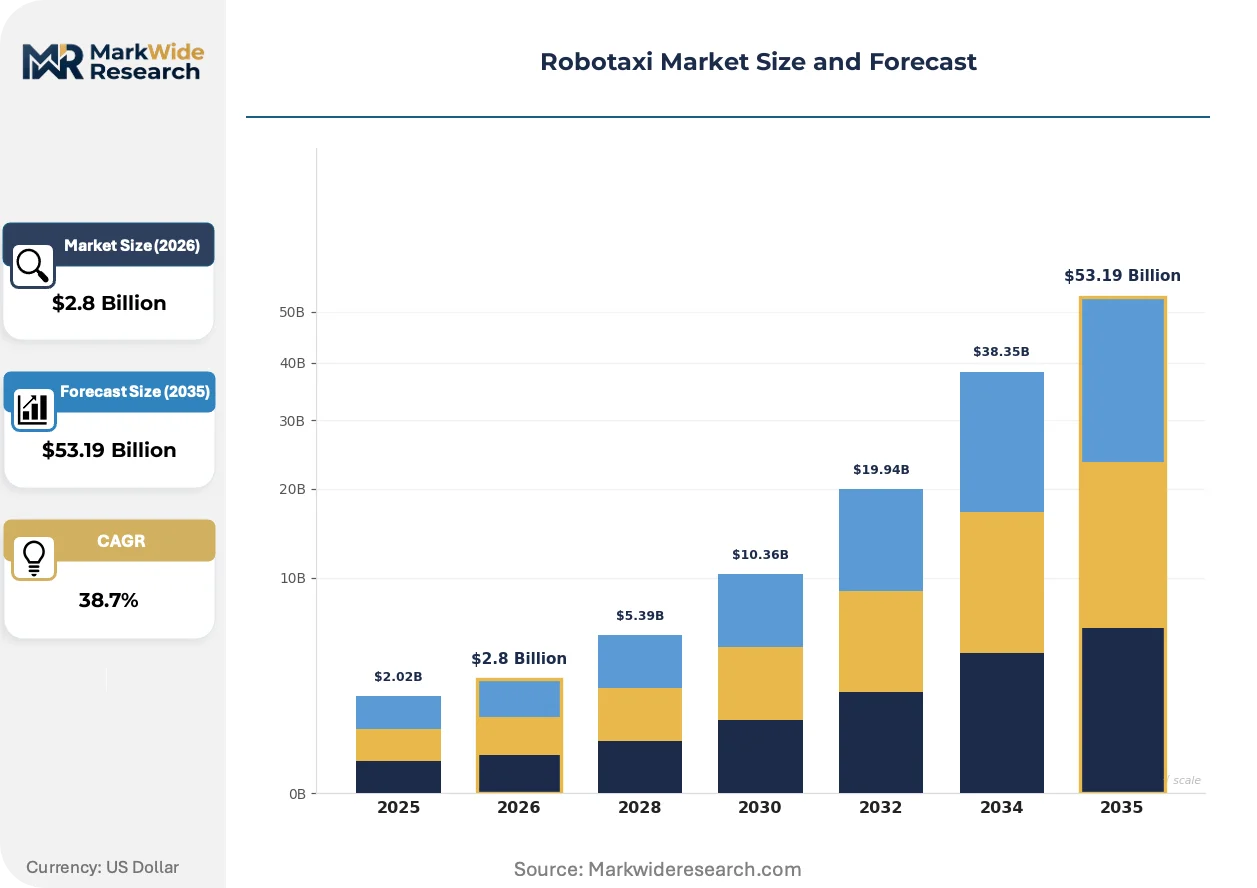
Market Dynamics
Fleet operators are consolidating around electric vehicle platforms to absorb the electrical loads of sensor suites and compute clusters, while NHTSA and China's MIIT compete to streamline commercial licensing pathways that determine deployment velocity.
Growth Catalysts
- Urban congestion pricing schemes:London, Singapore, and Stockholm impose fees on private vehicle entry, pushing commuters toward shared autonomous mobility services that bypass these charges entirely.
- SAE Level 4 validation protocols:Standardized testing frameworks from ISO and IEC reduce redundant certification cycles, cutting time-to-deployment for multi-city fleet expansions.
- LiDAR cost deflation:Solid-state sensor manufacturing at scale in Taiwan and South Korea collapses unit economics below the threshold for commercial viability in mass robotaxi operations.
Market Restraints
- Compute hardware supply concentration:NVIDIA's dominance in automotive-grade GPUs creates single-source vulnerability for inference workloads across perception stacks.
- High-definition mapping dependency:Centimeter-accurate road data requires continuous fleet telemetry and manual verification, locking operators into capital-intensive map maintenance cycles.
- EU AI Act algorithmic transparency mandates:Explainability requirements for neural network decision-making impose documentation burdens that extend compliance timelines for European deployments.
Strategic Opportunities
- Airport ground transport automation:Geofenced environments with predictable traffic patterns offer lower-complexity entry points for revenue service before general road deployment.
- India's PLI scheme for advanced automotive technology:Production-linked incentives for electric and connected vehicles attract component manufacturing that supports future robotaxi supply chains.
- V2X infrastructure convergence:Integration of cellular vehicle-to-everything protocols with 5G networks enables cooperative perception that extends operational design domains beyond onboard sensor range.
Industry Challenges
- Systems safety engineering talent scarcity:Functional safety expertise per ISO 26262 remains concentrated among automotive Tier-1 suppliers, constraining in-house hiring for technology-focused operators.
- Remote assistance center scaling:Edge-case disengagements require human teleoperators at ratios that explode labor costs during geographic expansion phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotaxi Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $53.19 Billion |
| CAGR (2026 – 2036) | 38.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Computer Vision, GPS Service Type: Ride-hailing, Shuttle Services, Delivery, Carpooling End User: Commuters, Tourists, Businesses, Students Vehicle Type: Electric Vehicles, Autonomous Cars, Vans, Compact Cars |
| Companies Covered | Toyota Motor Corporation, Mercedes-Benz Group AG, Waymo LLC, Didi Chuxing Technology Co. Ltd., Amazon.com Inc., Tesla Inc., Baidu Inc., BMW AG, Uber Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotaxi Market Emerging Trajectories
Sensor fusion architectures and regulatory sandboxes are compressing the gap between pilot programs and revenue service, while procurement patterns shift toward fleet-as-a-service models that transfer capital risk to infrastructure providers.
Silicon carbide power electronics is electrifying drivetrain efficiency in electric robotaxi platforms, cutting thermal losses during stop-and-go urban cycles. Fleet operators in Phoenix and San Francisco specify SiC inverters for their next-generation vehicle orders. This transition is electrifying total cost of ownership calculations that previously favored conventional silicon IGBTs.
China's MIIT GB standards for data security and connected vehicle certification impose dual-track compliance for multinationals seeking access alongside domestic Apollo Go deployments. The industrial consequence fragments software architectures into region-specific builds that cannot share update pipelines. European operators face parallel pressure from GDPR biometric restrictions that force redesign of passenger monitoring cameras.
Municipal procurement departments are bundling robotaxi concessions with public transit operating contracts, displacing pure technology vendors in favor of integrated mobility providers. Chicago and Dubai issued combined RFPs that tie autonomous vehicle permits to minimum service frequency guarantees on underserved routes. This pattern concentrates buyer power among transit authorities that previously lacked technical evaluation capacity.
Robotaxi Market Segmentation
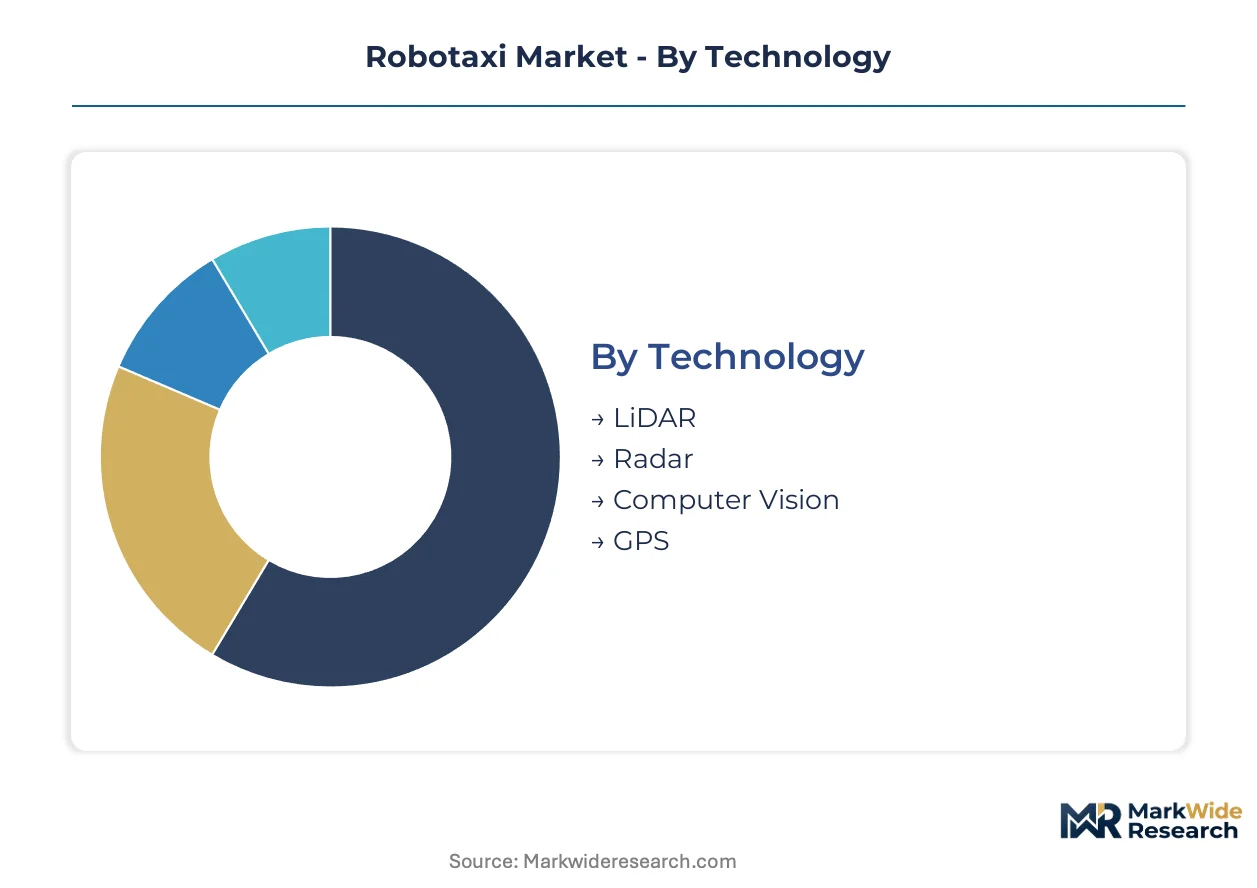
Robotaxi market segmentation reveals how deployment economics and passenger behavior reshape technology procurement. Fleet operators select sensor stacks and vehicle configurations based on operational design domains rather than universal specifications.
Technology:
Procurement teams differentiate vendors by environmental resilience and total cost of ownership across urban deployment scenarios.
- LiDAR:Solid-state units emit pulsed laser arrays to construct centimeter-accurate 3D point clouds. Phoenix and San Francisco operators specify redundant LiDAR configurations for nighttime and adverse weather reliability where camera-only perception degrades.
- Computer Vision:Camera arrays paired with neural network inference deliver object classification at fractional hardware cost. Tesla's Full Self-Driving stack demonstrates this approach in California, though edge-case handling requires more training data than LiDAR-hybrid alternatives.
- Radar:Frequency-modulated continuous-wave sensors penetrate fog and precipitation where optical systems fail. Most fleets deploy radar as secondary validation rather than primary perception.
- GPS:Real-time kinematic positioning corrects satellite signals to decimeter precision. Geofenced shuttle services in airport environments rely on GPS fusion for lane-level localization where map matching suffices.
LiDAR leads volumes today; computer vision is gaining share fastest.
Service Type:
Revenue model selection determines fleet utilization rates and capital recovery timelines for operators.
- Ride-hailing:On-demand point-to-point transport captures the largest addressable passenger base. Waymo and Baidu scale this model across Phoenix, San Francisco, Beijing, and Wuhan where regulatory permits allow unmanned commercial service.
- Shuttle Services:Fixed-route circulation within geofenced campuses and transit corridors reduces mapping burden. Airport ground transport automation in Dubai and Singapore deploys this model for predictable loop patterns.
- Delivery:Goods transport without passenger safety constraints expands operational design domains. Grocery and meal delivery pilots operate in Texas and Arizona suburbs where traffic complexity remains moderate.
- Carpooling:Shared-ride matching algorithms optimize vehicle occupancy during peak periods. This segment climbs fastest as congestion pricing in London and Stockholm pushes commuters toward shared autonomous alternatives.
Ride-hailing dominates revenue today; carpooling shows the steepest expansion trajectory.
End User:
Passenger cohorts exhibit divergent willingness-to-pay and trip frequency patterns that shape service tier design.
- Commuters:Daily work-trip regulars generate predictable demand density along corridor routes. Subscription pricing models target this segment in metropolitan areas with congestion charging schemes.
- Tourists:Episodic visitors prioritize convenience over cost, accepting premium pricing for unfamiliar destinations. Waymo and Cruise capture this demand at airports and hotel districts.
- Businesses:Corporate account contracts guarantee minimum trip volumes and priority dispatch. Fleet operators in Chicago negotiate these arrangements alongside municipal transit concessions.
- Students:Price-sensitive campus populations drive demand for pooled service tiers. University partnerships in Arizona and California anchor initial deployment phases before general road expansion.
Commuters anchor volume today; business accounts are expanding most quickly.
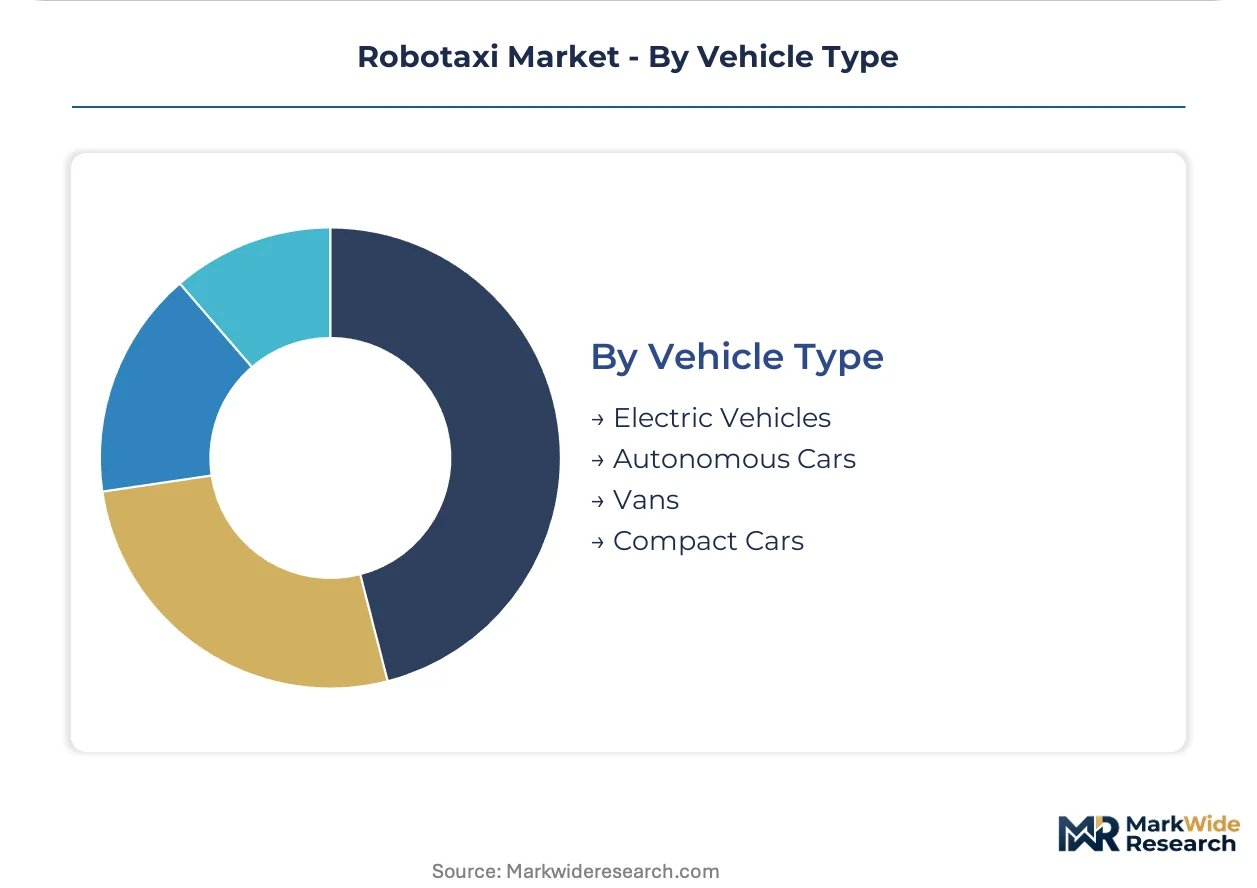
Vehicle Type:
Platform selection hinges on electrical architecture compatibility with sensor loads and total cost of ownership projections.
- Electric Vehicles:Battery platforms accommodate high-voltage sensor suites and compute clusters without alternator retrofit. Silicon carbide inverters from suppliers in Taiwan and South Korea cut thermal losses during urban stop-and-go cycles.
- Autonomous Cars:Purpose-built vehicles integrate redundant steering, braking, and compute from initial design rather than retrofit. Waymo's Jaguar I-PACE fleet exemplifies this configuration across Phoenix and Los Angeles.
- Vans:High-occupancy platforms serve airport shuttles and corporate campus loops. Geofenced environments in Dubai and Singapore favor this format for predictable passenger loads.
- Compact Cars:Smaller footprints navigate dense European and Asian street networks where full-size vehicles face maneuvering constraints. Baidu deploys modified compact platforms in Wuhan's narrower historic districts.
Electric vehicles lead deployment today; purpose-built autonomous cars are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting autonomous vehicle testing capital toward jurisdictions with streamlined permitting frameworks. Operators migrate deployments from restrictive compliance environments to markets offering accelerated commercial licensing pathways.
United States
Waymo and Cruise sustain unmanned revenue service across Phoenix, San Francisco, and Los Angeles. The NHTSA oversees federal safety standards while California's DMV administers operational permits through its Autonomous Vehicle Program. Silicon Valley and Arizona's Sun Corridor concentrate LiDAR sensor manufacturing and fleet maintenance infrastructure.
China
Baidu's Apollo Go scales passenger rides in Beijing and Wuhan ahead of international competitors. The MIIT and SAMR jointly enforce GB standards for data security and connected vehicle certification. The Yangtze River Delta and Pearl River Delta host domestic LiDAR production clusters serving Apollo Go and Didi Chuxing fleets.
Germany
Mercedes-Benz and BMW pursue Level 3 conditional automation approvals for highway passenger transport. The KBA regulates type approval under UN ECE frameworks with stricter liability provisions than US counterparts. Bavaria and Baden-Württemberg anchor automotive R&D campuses where OEMs test SAE Level 4 architectures.
Japan
Toyota Motor Corporation advances mobility-as-a-service pilots in Tokyo and Osaka metropolitan corridors. METI coordinates national standards for automated driving systems alongside prefectural traffic safety ordinances. The Kanto region concentrates Tier-1 supplier networks feeding sensor fusion development for domestic robotaxi platforms.
United Kingdom
Waymo explores London mapping and simulation work ahead of potential service launch. The Department for Transport consults on automated vehicle legislation while Transport for London manages congestion charging zones that favor shared autonomous alternatives. The Midlands and Greater Manchester host autonomous shuttle trials in geofenced business park environments.
Robotaxi Market Vendor Landscape
United States technology developers anchor one tier; German automotive incumbents and Chinese mobility platforms hold differentiated positions. The structure fragments across three non-overlapping capability domains rather than consolidating around unified stacks. Technology-first operators, established OEMs with manufacturing scale, and ride-hailing aggregators each pursue incompatible go-to-market models. Capacity expansion through fleet-as-a-service partnerships and geographic licensing agreements constitute the dominant competitive moves.
Within the technology-operator tier, Waymo LLC exemplifies the LiDAR-heavy sensor architecture approach, while Tesla Inc. represents the computer-vision-only alternative. Among automotive incumbents, Toyota Motor Corporation occupies a position emphasizing manufacturing integration and hybrid-electric platforms for future autonomous deployment.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Mercedes-Benz Group AG |
| Waymo LLC |
| Didi Chuxing Technology Co. Ltd. |
| Amazon.com Inc. |
| Tesla Inc. |
| Baidu Inc. |
| BMW AG |
| Uber Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Solid-state LiDAR manufacturing migration from mechanical to semiconductor-grade fabrication processes simultaneously collapses unit sensor costs below commercial viability thresholds and concentrates production capability among Taiwan and South Korean foundry specialists. This technological transition reshapes procurement economics for fleet operators scaling from pilot to revenue service.
Pricing Analysis
Fleet-as-a-service contracts transfer capital risk to infrastructure providers, compressing direct-to-OEM discounts for sensor and compute hardware. Pricing stratifies across premium redundant-sensor configurations, standard LiDAR-camera fusion stacks, and economy camera-only architectures differentiated by certification tier and after-sales telemetry support. Cost compression in solid-state perception hardware intensifies as Taiwanese foundries achieve automotive-grade yields. Price sensitivity concentrates among municipal transit authorities bundling robotaxi concessions with minimum service guarantees, while airport operators exhibit lowest sensitivity due to geofenced operational certainty.
Supply Chain Analysis
China's MIIT data-localization mandates and India's PLI scheme for advanced automotive technology are reshaping sourcing patterns for multinationals seeking market access alongside domestic Apollo Go deployments. Geographic concentration centers on Taiwan and South Korea for LiDAR foundry output, China for battery cell production, and Germany for automotive-grade silicon carbide inverters. Raw material dependencies span rare-earth elements for magnet manufacturing, lithium carbonate for battery chemistry, and high-purity silicon for compute substrates. Single-source vulnerability permeates NVIDIA's dominance in automotive-grade GPUs for inference workloads. Distribution runs through Tier-1 automotive suppliers integrating sensor fusion modules before OEM platform assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotaxi market reads as a late-cycle quality story where operator differentiation hinges on SAE Level 4 validation depth rather than hardware specification alone. Municipal procurement departments are shifting specifications toward premium redundancy standards and minimum service frequency guarantees that favor incumbents with proven multi-city deployment records.
For Market Incumbents: To counter Tesla's computer-vision-only cost structure and Baidu's domestic data-scale advantages in China, Waymo and Cruise must deepen backward integration into solid-state LiDAR manufacturing through captive supply agreements with Taiwan foundries. Certification investment in ISO 26262 functional safety expertise and channel control through exclusive fleet-as-a-service partnerships with municipal transit authorities constitute essential defensive positioning. For New Entrants and Emerging Players: Airport ground transport automation presents the most penetrable white-space target, offering geofenced environments with predictable traffic patterns and lower mapping burden than general road deployment. European shuttle services in business park corridors face reduced competitive intensity due to EU AI Act compliance timelines that delay established operators. A go-to-market angle anchored in V2X infrastructure convergence with 5G network operators enables cooperative perception capabilities without full sensor-stack capital burden. For Investors and Strategic Acquirers: Valuations sit cheapest among Tier-1 automotive suppliers with dormant autonomous vehicle engineering capabilities and existing OEM relationships but lacking fleet-operator revenue visibility. Long-term viability over the analysis window favors entities controlling both perception hardware manufacturing and municipal concession contracts rather than pure software licensors. The signal to watch is NHTSA commercial licensing velocity in secondary metropolitan areas, which would validate capital recovery timelines for hardware-heavy business models.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Standardization | Reduces redundant certification cycles across multi-city fleet expansions under NHTSA and MIIT frameworks. |
| Silicon Carbide Inverter Supply Agreement | Taiwan and South Korean suppliers cut thermal losses during urban stop-and-go cycles for electric platforms. |
| Municipal Transit Concession Partnership | Chicago and Dubai bundled RFPs concentrate buyer power among authorities seeking integrated mobility providers. |
| V2X Infrastructure Integration | Cellular vehicle-to-everything protocols with 5G networks extend operational design domains beyond onboard sensor range. |
| Functional Safety Certification Investment | ISO 26262 expertise scarcity among Tier-1 suppliers constrains in-house hiring for technology-focused operators. |
Methodological Framework
Multiple input streams — fleet operator deployment disclosures, regulatory filing documentation, and component supplier production records — were reconciled against municipal procurement databases and autonomous vehicle permit registries. Primary interviews with autonomous vehicle program directors, municipal transit authority procurement leads, LiDAR sensor engineering heads, and automotive Tier-1 supplier strategy officers were validated through secondary sources including NHTSA autonomous vehicle program filings, California DMV testing mileage reports, MIIT connected vehicle certification announcements, and SEC disclosures from publicly traded technology operators. Bottom-up unit economics modeling and top-down market sizing triangulation were applied across technology, service type, and regional segmentation dimensions.
Data-stream reconciliation anchored volume projections to fleet deployment timelines disclosed by Waymo, Cruise, Baidu Apollo Go, and Didi Chuxing, while value outputs incorporated sensor stack cost curves and fleet-as-a-service contract structures. Segmentation modeling spanned LiDAR, computer vision, radar, and GPS fusion technologies; ride-hailing, shuttle, delivery, and carpooling service types; and electric vehicle, purpose-built autonomous car, van, and compact car platforms. CAGRs were derived from deployment velocity assumptions tied to regulatory permit issuance rates and commercial licensing pathway clarity. Industry-specific forecast inputs included LiDAR cost deflation trajectories from Taiwanese foundry yield improvements and municipal congestion pricing scheme adoption patterns across London, Singapore, and Stockholm.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation across Washington, Beijing, and Brussels, NHTSA rulemaking velocity for unmanned commercial service, and compute hardware supply concentration risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Vehicle Intelligence System Market