
 Autopilot Systems Market | 2026-2036
Autopilot Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Autopilot Systems Market Intelligence
The fusion of artificial intelligence with multi-modal sensor data is reshaping the architecture of modern autopilot systems, enabling more complex, autonomous flight profiles. Honeywell International Inc. leverages its deep expertise in flight control systems to develop next-generation solutions for this shift. Collins Aerospace competes on the strength of its integrated avionics suites for large commercial airliners, while Garmin Ltd. specializes in systems for general aviation and unmanned vehicles.
Autopilot systems are flight control platforms that automate an aircraft's trajectory without constant human input. These systems process inputs from GPS, inertial navigation units, and air data computers to command flight control surfaces. Within applications, the commercial aviation segment remains the largest by value, but Unmanned Aerial Vehicles represent the fastest-growing opportunity. The adoption of artificial intelligence and computer vision technologies is a key differentiator, particularly in advanced guidance systems.
Regulatory frameworks from bodies like the US Federal Aviation Administration (FAA) dictate stringent certification requirements for both hardware and software. The forthcoming EU AI Act will introduce new compliance obligations for systems incorporating machine learning. System developers must therefore prioritize certifiability and transparent algorithm design to ensure market access and maintain safety standards.
Market Dynamics
The central force shaping the autopilot market is the drive toward certifiable autonomy, creating tension between rapid AI innovation and the stringent safety verification processes mandated by global aviation authorities.
Growth Catalysts
- Sensor Fusion Advancement:The integration of data from multiple sources like radar, LiDAR, and electro-optical cameras enables more robust and reliable autonomous navigation, particularly for Unmanned Aerial Vehicles operating in complex environments.
- Defense Modernization Programs:Government initiatives in the United States and allied nations to upgrade unmanned surveillance and combat aircraft fleets directly stimulate demand for next-generation, AI-enabled autopilot systems.
- Commercial Aviation Efficiency:Airlines are adopting advanced autopilot functions to optimize flight paths, reduce fuel consumption, and lower operational costs, creating a consistent upgrade cycle for commercial airliner fleets.
Market Restraints
- Extreme Certification Hurdles:The high cost and long timelines associated with achieving DO-178C and DO-254 compliance from regulators like the FAA and EASA for flight-critical software and hardware limit market entry.
- AI Algorithm Verifiability:Proving the safety and predictability of complex machine learning models used in autonomous navigation presents a fundamental technical barrier, slowing their adoption in certified, safety-critical applications.
- Component Supply Chain Constraints:A limited number of global suppliers for aerospace-grade, radiation-hardened microprocessors and inertial measurement units creates potential bottlenecks and increases system costs.
Strategic Opportunities
- Urban Air Mobility:The emerging market for electric vertical take-off and landing (eVTOL) aircraft for intra-city transport represents a greenfield opportunity for highly autonomous, fly-by-wire autopilot systems.
- Retrofit and Modernization Kits:Developing modular autopilot upgrades for the large existing fleet of general aviation and older commercial aircraft offers a significant revenue stream outside of new airframe production cycles.
- Expansion in Asia-Pacific:The growth of indigenous aerospace manufacturing in countries like China and India provides an opportunity to supply autopilot systems for new commercial and unmanned platforms.
Industry Challenges
- Specialized Talent Scarcity:A shortage of software engineers with dual expertise in flight control theory and certifiable AI development creates a significant human capital constraint for system developers.
- Legacy System Integration:Ensuring seamless interoperability between modern autopilot systems and the diverse array of legacy avionics on existing aircraft platforms is a major engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autopilot Systems Market |
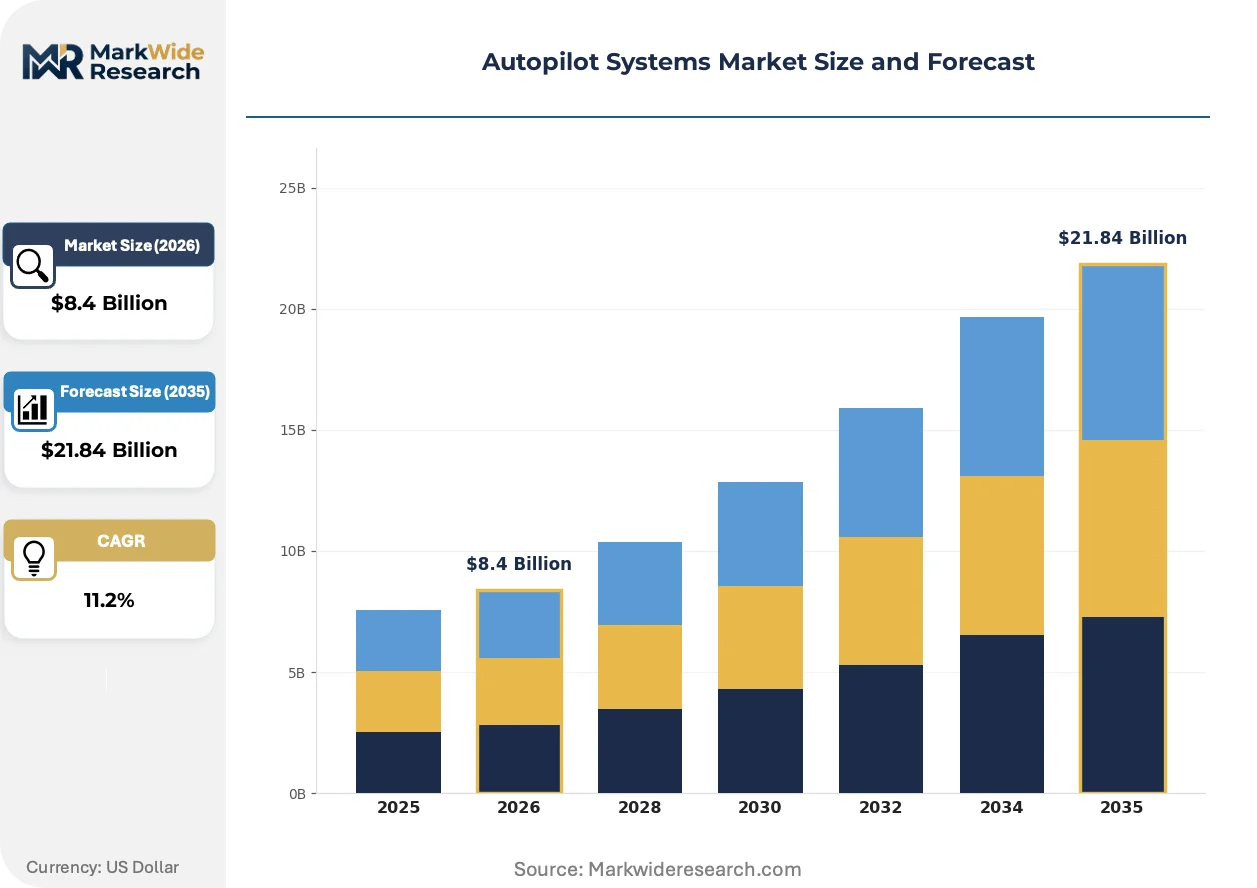
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $21.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Flight Control Systems, Navigation Systems, Sensor Fusion Systems, Guidance Systems Application: Commercial Aviation, Military Aviation, Unmanned Aerial Vehicles, Recreational Drones End User: Aerospace Manufacturers, Defense Contractors, Aerospace Service Providers, Private Pilots Technology: GPS Navigation, Inertial Navigation, Computer Vision, Artificial Intelligence |
| Companies Covered | Thales Group, Moog Inc., Honeywell International Inc., L3Harris Technologies, Inc., BAE Systems plc, Collins Aerospace, Safran SA, Lockheed Martin Corporation, Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autopilot Systems Market Strategic Shifts & Innovations
Market evolution is defined by a shift from deterministic, rule-based automation to adaptive, data-driven autonomy. This transition prioritizes software-defined capabilities and verifying complex intelligent systems for safety-critical operations.
Digital twin technology provides a high-fidelity virtual replica of an aircraft's flight dynamics and systems. Aerospace manufacturers and system integrators are rapidly adopting this for development and in-service support. This approach is virtualizing significant portions of the physical testing and certification process, compressing development timelines and reducing reliance on costly flight trials.
Forthcoming regulation like the EU AI Act introduces a risk-based framework for artificial intelligence systems placed on the European market. This policy mandates stringent transparency, data governance, and human oversight for high-risk applications like autonomous flight controls. System developers targeting the EU must now embed certifiability and algorithmic explainability into their core design process from the outset.
A notable demand-side evolution involves the move from purchasing standalone hardware components to licensing integrated, software-defined flight control platforms. This model challenges traditional avionics suppliers by emphasizing recurring revenue and feature updates delivered over the air. The shift is most pronounced within the unmanned systems and advanced air mobility segments, where platform agility is a key competitive differentiator.
Autopilot Systems Market Segmentation
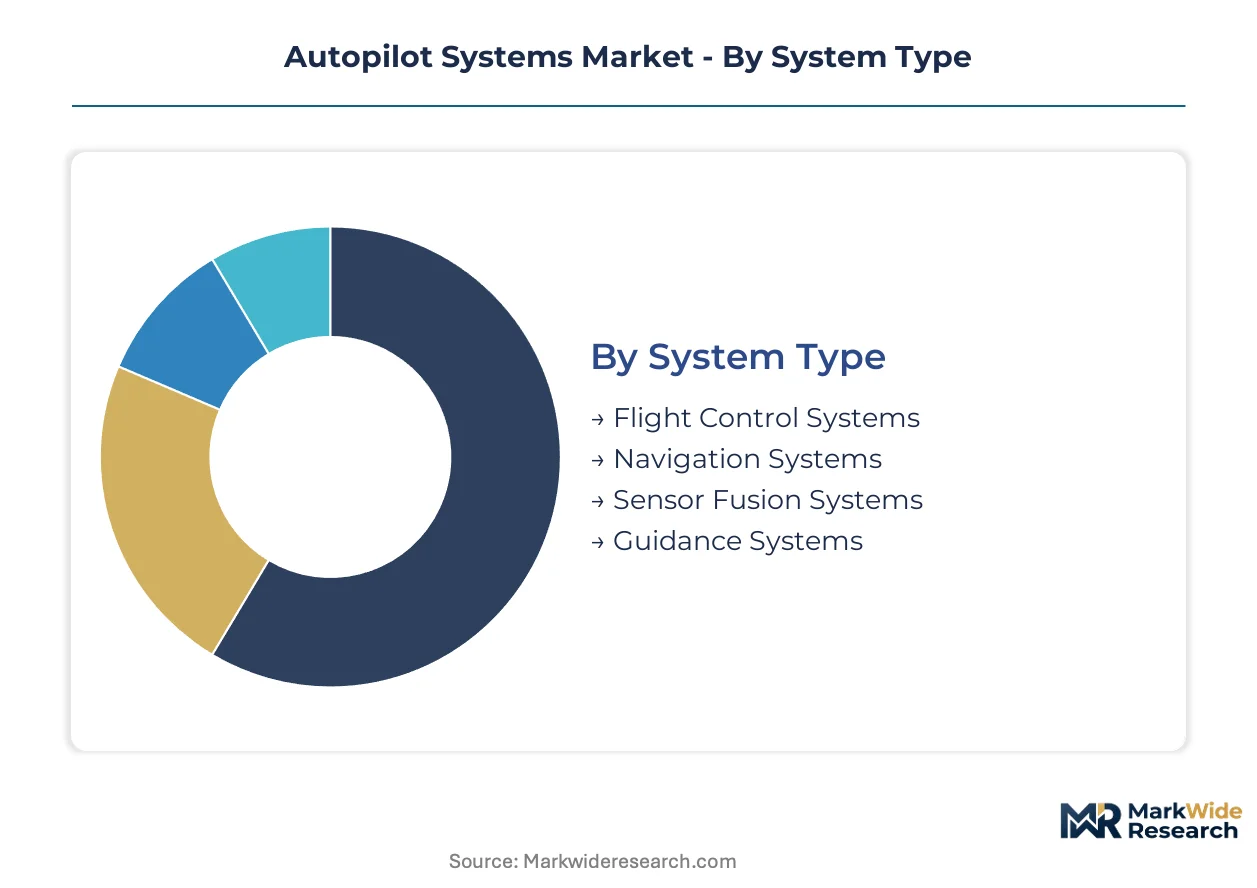
Understanding the varied segments within the autopilot systems market provides critical insights into demand drivers and technological specialization. Each category reveals distinct operational requirements and commercial value propositions, shaping strategic investment and product development pathways for industry participants.
System Type:
The intensity of after-sales service and maintenance requirements often dictates the long-term profitability within different system types.
- Flight Control Systems:These core platforms manage an aircraft's attitude, altitude, and heading through direct manipulation of control surfaces. Demand concentrates in both new aircraft production cycles and extensive modernization programs for existing commercial and military fleets, driven by safety and efficiency upgrades.
- Sensor Fusion Systems:Integrating data from multiple dissimilar sensors, such as radar, LiDAR, and electro-optical cameras, these systems provide a comprehensive environmental picture. Their adoption is accelerating within Unmanned Aerial Vehicles for complex autonomous operations and in advanced air mobility, where robust perception is paramount.
- Navigation Systems:These components determine an aircraft's position and velocity, primarily using GPS and inertial measurement units. Modern navigation systems incorporate advanced algorithms for enhanced accuracy and reliability.
- Guidance Systems:Guiding an aircraft along a predetermined flight path, these systems interpret navigation data to issue commands to flight control systems. They are essential for precision approaches and autonomous mission execution.
By volume, Flight Control Systems lead. By growth pace, Sensor Fusion Systems are ahead.
Application:
The volume of aircraft operations and the specific mission profiles significantly influence the design and deployment of autopilot solutions across various applications.
- Commercial Aviation:Autopilot systems in this segment automate routine flight phases, optimize fuel consumption, and reduce pilot workload on large passenger and cargo aircraft. Ongoing fleet upgrades and new aircraft deliveries sustain consistent demand.
- Unmanned Aerial Vehicles:These systems provide full autonomy for surveillance, reconnaissance, and logistics drones, enabling complex missions without direct human piloting. The defense sector and emerging commercial drone services are driving rapid expansion.
- Military Aviation:Autopilot technology supports advanced combat maneuvers, precision targeting, and autonomous operations for fighter jets and transport aircraft. Governments worldwide continuously invest in upgrading these capabilities.
- Recreational Drones:Simpler autopilot functions provide stability, GPS hold, and basic waypoint navigation for consumer-grade aerial platforms. These systems enhance ease of use for hobbyists and photographers.
Commercial Aviation commands the largest market share. Unmanned Aerial Vehicles are expanding most quickly.
End User:
The maturity of procurement processes and the scale of integration challenges vary significantly among different end-user groups, impacting market access for system developers.
- Aerospace Manufacturers:These companies integrate autopilot systems directly into new airframes during the production phase for commercial and general aviation aircraft. They represent the primary customer base for advanced system development.
- Defense Contractors:Specializing in military aircraft and weapon systems, these contractors procure highly customized and robust autopilot solutions for national defense programs. Their requirements often involve stringent security and performance specifications.
- Aerospace Service Providers:Offering maintenance, repair, and overhaul services, these providers facilitate the upgrade and modernization of existing aircraft fleets with new autopilot technologies. They cater to airlines and private operators.
- Private Pilots:Individuals operating general aviation aircraft often seek simpler, cost-effective autopilot solutions for enhanced safety and reduced fatigue during longer flights. This segment values ease of installation and intuitive interfaces.
Aerospace Manufacturers drive significant upfront purchases. Defense Contractors exhibit stable, long-term procurement cycles.
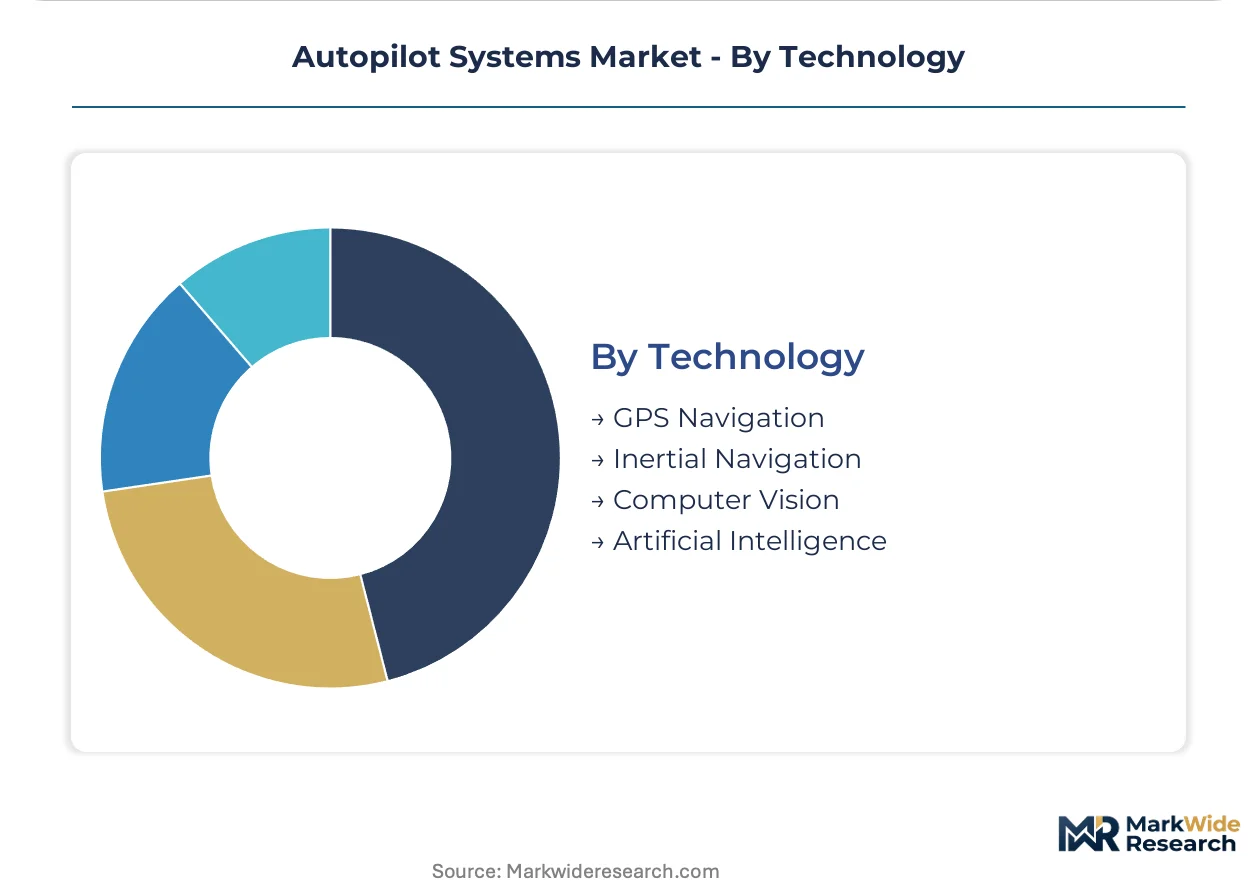
Technology:
The concentration of specialized component suppliers and intellectual property ownership dictates the competitive landscape within various technology segments.
- Artificial Intelligence:AI algorithms enable advanced decision-making, anomaly detection, and adaptive flight control, moving beyond traditional rule-based automation. This technology is a key differentiator in next-generation autonomous platforms.
- Computer Vision:Utilizing cameras and image processing, computer vision systems provide environmental awareness, obstacle avoidance, and precision landing capabilities. This technology is critical for autonomous operations in complex or GPS-denied environments.
- GPS Navigation:Global Positioning System technology provides precise location and velocity data, forming the backbone of modern aircraft navigation. Its widespread adoption ensures fundamental navigational capabilities.
- Inertial Navigation:Employing accelerometers and gyroscopes, inertial navigation systems provide continuous position, orientation, and velocity information independently of external signals. These systems offer redundancy and enhanced accuracy.
Artificial Intelligence commands high research and development investment. GPS Navigation forms a foundational technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global market for autopilot systems sees significant technology transfer from established aerospace manufacturing nations to emerging markets. This dynamic drives demand for advanced flight control solutions in various regions. Major aerospace players often supply systems across international borders, influencing regional market development.
United States
Defense modernization programs and commercial aviation fleet upgrades drive demand for autopilot systems in the United States. The US Federal Aviation Administration (FAA) sets stringent certification standards for all flight-critical software and hardware. Seattle, Washington, hosts major aerospace manufacturing, concentrating autopilot system integration and development.
France
France's strong commercial aviation sector, anchored by Airbus, and its military aircraft production sustain demand for sophisticated autopilot solutions. European Union Aviation Safety Agency (EASA) regulations and the forthcoming EU AI Act significantly influence system development. Toulouse, a prominent European aerospace hub, concentrates research and development for advanced avionics.
Germany
Germany's high-tech manufacturing base and significant research and development investment in aerospace and defense stimulate demand. EASA regulations and national defense procurement policies shape market requirements for autonomous flight controls. Munich and Hamburg are key centers for aerospace engineering and system integration.
Japan
Japan's indigenous defense sector development and growing interest in advanced air mobility applications fuel demand for autopilot systems. The Japan Civil Aviation Bureau (JCAB) oversees aviation safety and certification for both manned and unmanned aircraft. Nagoya and Tokyo feature aerospace component suppliers and advanced R&D facilities.
Autopilot Systems Market Key Industry Players
Channel-controlling players compete with product-specialist players across the autopilot systems market. The competitive landscape features a mix of large, integrated avionics suppliers and smaller, niche technology providers. Strategic archetypes include defense primes, commercial aviation system integrators, and specialized unmanned aerial vehicle (UAV) solution developers. Key competitive moves involve significant research and development investment into AI and sensor fusion, alongside strategic partnerships to broaden technological capabilities.
Within the integrated avionics segment, Honeywell International Inc. and Collins Aerospace exemplify established suppliers with broad portfolios. Garmin Ltd. occupies a position as a specialist in general aviation and unmanned systems, emphasizing user-friendly interfaces. These companies represent different tiers of the market, from comprehensive platform providers to targeted solution developers.
| Leading Market Players |
|---|
| Thales Group |
| Moog Inc. |
| Honeywell International Inc. |
| L3Harris Technologies, Inc. |
| BAE Systems plc |
| Collins Aerospace |
| Safran SA |
| Lockheed Martin Corporation |
| Garmin Ltd. |
| Others |
Cost & Logistics Intelligence
Radiation-hardened microprocessors and inertial measurement units from a limited number of global suppliers directly influence system costs and margin pools for autopilot system integrators. This upstream concentration dictates pricing flexibility and component availability across the market.
Pricing Analysis
Next-generation software-defined platforms command premium pricing due to advanced AI capabilities and certifiability, creating a significant gap with legacy hardware. The dominant pricing model is project-based for new airframe integration, complemented by software licensing for feature updates and per-unit transactional sales for retrofit kits. Price differentiation stems from the stringent DO-178C and DO-254 certification levels and the degree of system customization. Pricing softness affects older, less complex systems as modernization kits offer cost-effective upgrades. Private Pilots exhibit the highest price sensitivity for general aviation solutions.
Supply Chain Analysis
Specialized aerospace foundries and contract manufacturers in the United States, France, and Germany hold significant capacity for critical autopilot system components. The market draws from a limited pool of suppliers for aerospace-grade microprocessors, inertial measurement units, and advanced LiDAR and radar components. Single-source vulnerability for these highly specialized inputs presents a structural supply chain risk. Downstream distribution primarily involves direct sales and integration with Aerospace Manufacturers and Defense Contractors, alongside a network of Aerospace Service Providers for aftermarket upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autopilot systems market presents a service-attach opportunity, as licensing integrated, software-defined flight control platforms expands faster than new hardware sales. This shift emphasizes recurring revenue and feature updates delivered over the air.
For Market Incumbents: Build regulatory compliance moats through early engagement with bodies like the FAA and EASA on AI certification. This counters threats from agile software-focused entrants lacking deep aerospace certification expertise. Invest in certifiable AI development and secure long-term supply agreements for aerospace-grade components. Deepen R&D into transparent algorithm design for critical flight controls.
For New Entrants and Emerging Players: Pursue niche opportunities within Urban Air Mobility (UAM) and retrofit markets, where certification pathways are still evolving or less stringent. Target general aviation and older commercial aircraft for modular autopilot upgrades, leveraging software-defined capabilities. Focus on developing user-friendly interfaces and simplified installation for private pilots. A go-to-market angle involves strategic partnerships with eVTOL manufacturers for early integration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialist avionics component manufacturers and software development firms focusing on niche AI applications. Long-term viability depends on firms demonstrating clear pathways to certifiable autonomy for safety-critical applications. Identify acquisition targets with strong intellectual property in sensor fusion or explainable AI for aerospace. The signal to watch is the first successful certification of an AI-powered flight control system by a major regulator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Certifiable AI | Accelerates adoption of advanced autonomy in safety-critical systems. |
| Form Regulatory Partnerships | Shapes future compliance standards for AI-enabled flight controls. |
| Develop Modular Retrofit Kits | Unlocks new revenue streams from existing aircraft fleets. |
| Secure Component Supply | Mitigates bottlenecks for aerospace-grade microprocessors and sensors. |
| Target Urban Air Mobility | Captures greenfield demand for highly autonomous eVTOL platforms. |
Research Approach
Desk research of industry reports, regulatory filings, and academic publications preceded structured interviews with aerospace manufacturers, defense contractors, and avionics engineers. This primary data collection involved discussions with flight control systems architects and certification specialists. Bottom-up data from company disclosures was triangulated with top-down market sizing for comprehensive validation.
Forecast assumptions held regulatory frameworks and technological advancements as key variables across the analysis window. The quantitative model segmented the market by system type, application, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates were derived from historical data and projected market dynamics. Key forecast inputs included defense spending trends and commercial aircraft delivery schedules.
Sensitivities concentrate around unforeseen regulatory changes and advancements in AI verifiability for flight-critical applications. The analysis reflects current market conditions and known development pipelines. Quarterly review of certification milestones and defense budget allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market