
 Italy Autonomous Navigation Market | 2026-2036
Italy Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Autonomous Navigation Market Insights
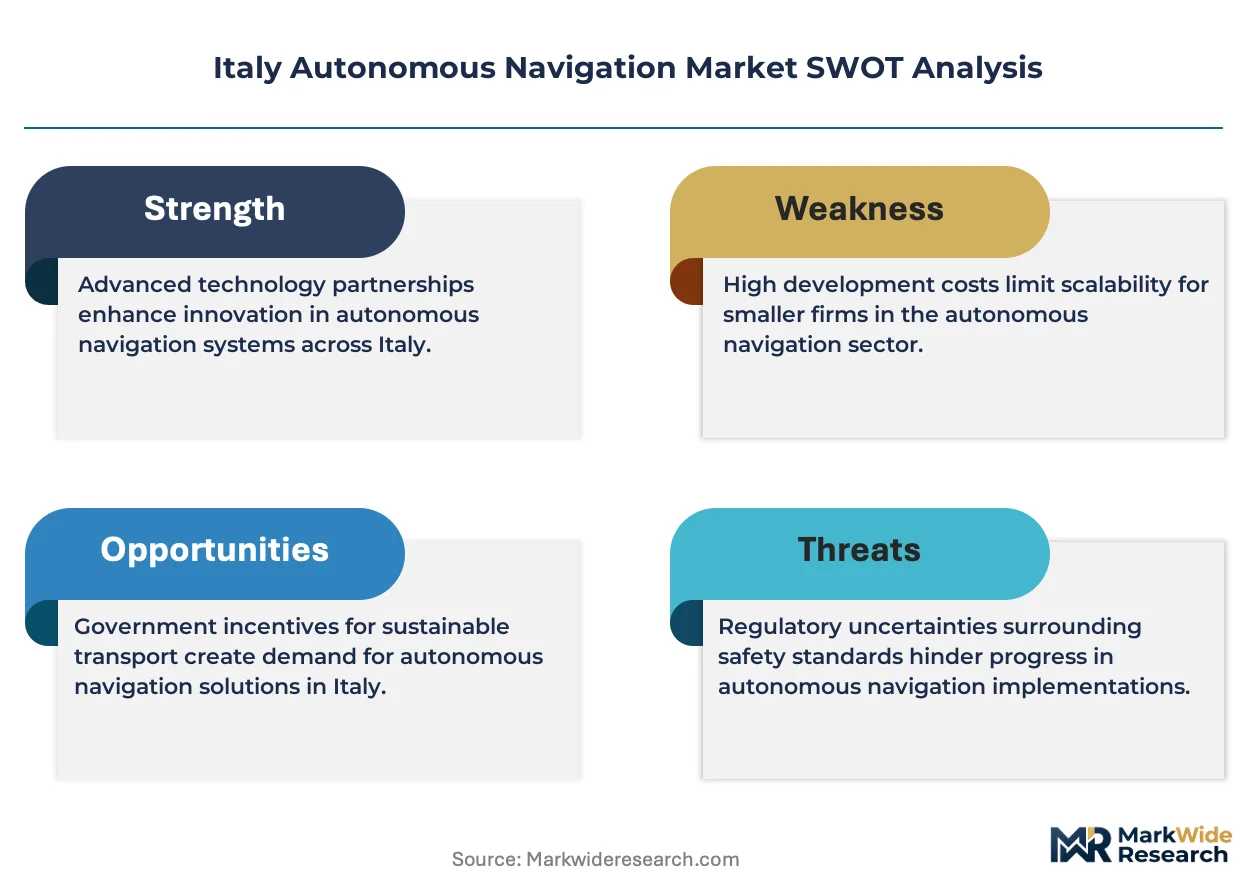
CE marking under the EU Machinery Directive is rotating vendor eligibility in Italy's autonomous navigation sector. Northrop Grumman Italia leverages its defense-aerospace heritage to anchor high-assurance navigation contracts. Comau specializes in industrial robotics applications, sustaining factory-floor autonomy demand. Datalogic competes through sensor fusion expertise for warehouse and port logistics environments.
Autonomous navigation encompasses self-directing systems that compute position, plan trajectories, and execute movement without human intervention using sensor arrays, localization algorithms, and real-time path planning operating within centimeter-level accuracy tolerances. These systems serve industrial automation, defense platforms, and commercial transport by replacing manual control with deterministic machine decision-making. Hardware components dominate installed value due to lidar and radar unit costs, while software and algorithms capture expanding margin pools through recurring update cycles. The automotive OEM end-user segment leads volume absorption, though logistics companies represent the fastest structural expansion as warehouse robotics and yard automation scale across Northern Italy.
Italy's National Recovery and Resilience Plan channels EU cohesion funds toward digital infrastructure, while ECHA REACH compliance governs sensor material composition and the EU AI Act imposes conformity assessment on algorithmic decision systems. These frameworks elevate compliance costs for non-integrated suppliers while privileging vendors with established certification pathways. Stakeholders must monitor how Italy's forthcoming smart mobility infrastructure tenders allocate risk between navigation technology providers and public concession holders.
Market Dynamics
EU AI Act conformity assessments are forcing Italian autonomous navigation vendors to restructure certification workflows before 2025 implementation deadlines, compressing time-to-market for algorithmic decision systems in commercial transport and industrial automation.
Growth Catalysts
- EU Cohesion Funding:Italy's National Recovery and Resilience Plan directs digital infrastructure investment toward smart mobility corridors in Turin and Milan, accelerating fleet automation procurement.
- CE Marking Acceleration:Machinery Directive compliance pathways for autonomous industrial vehicles reduce regulatory friction for factory-floor deployment in Emilia-Romagna's manufacturing belt.
- Logistics Robotics Demand:Northern Italian port operators and warehouse clusters are expanding yard automation to address labor availability constraints in container handling.
Market Restraints
- Sensor Input Concentration:Lidar and radar module supply depends on a limited base of German and Asian component suppliers, exposing Italian integrators to allocation risk.
- REACH Compliance Burden:ECHA material composition rules for sensor electronics elevate non-recurring engineering costs for smaller navigation system vendors.
- Technical Validation Gaps:Edge-case scenario testing for urban autonomous navigation lacks standardized protocols, prolonging safety certification timelines.
Strategic Opportunities
- Underpenetrated Southern Corridors:Naples-Porto Empedocle logistics routes show minimal autonomous yard tractor deployment, offering first-mover positioning for port terminal operators.
- Defense-Aerospace Crossover:Dual-use navigation algorithms developed for military unmanned platforms can migrate to commercial high-assurance applications.
- 5G-V2X Convergence:Integration of cellular vehicle-to-everything networks with onboard sensor fusion enables cooperative perception in dense urban environments.
Industry Challenges
- Embedded Systems Talent Scarcity:Real-time operating system programming and safety-critical software engineering skills concentrate in Turin's automotive cluster, leaving other regions underserved.
- Legacy Fleet Integration:Retrofit compatibility with existing commercial vehicle CAN bus architectures demands custom middleware development, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Autonomous Navigation Market |
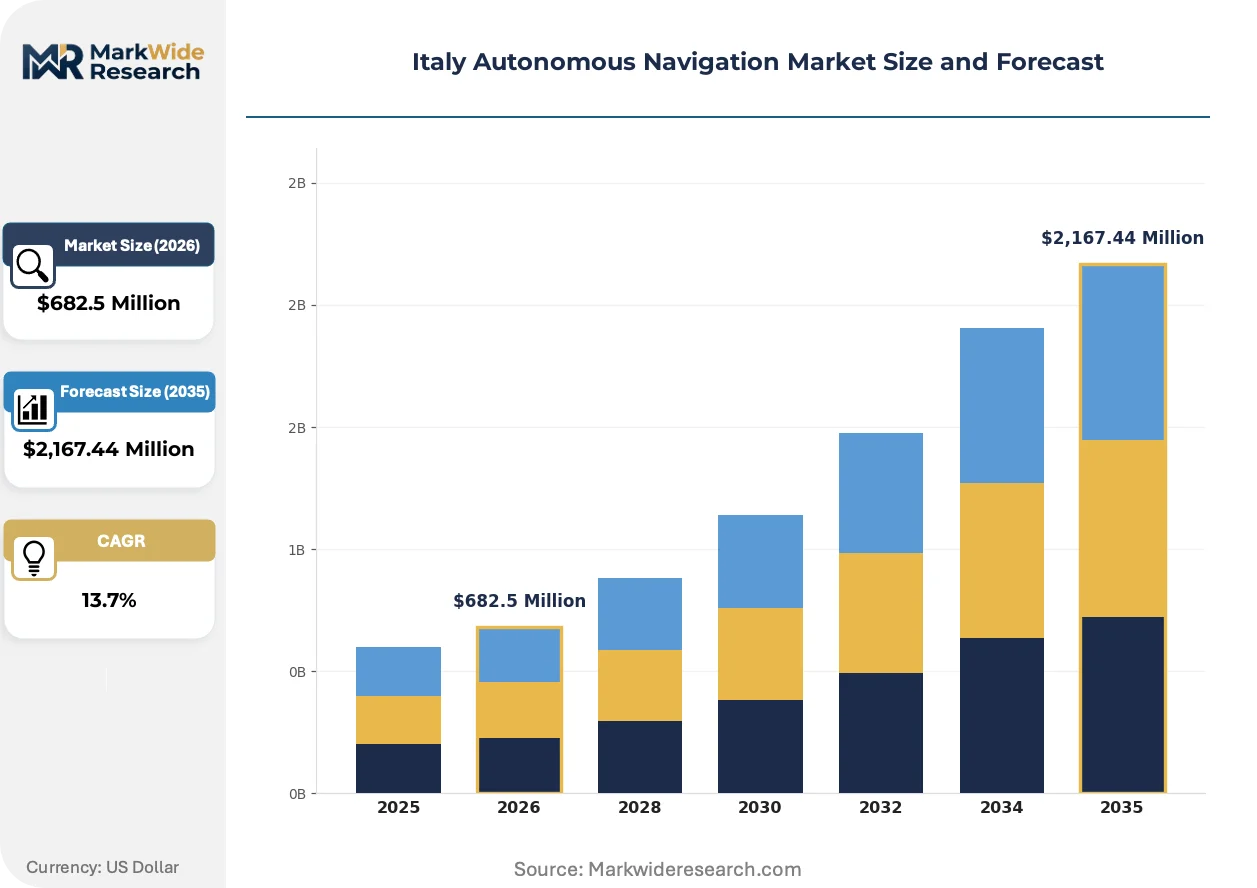
| Market Size in 2026 | $682.5 Million |
| Market Size in 2035 | $2,167.44 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Sensors, Algorithms End User: Consumer Electronics, Automotive OEMs, Logistics Companies, Public Transport Technology: Computer Vision, Lidar, Radar, GPS Application: Personal Vehicles, Drones, Maritime, Robotics |
| Companies Covered | Northrop Grumman Italia, Comau, Datalogic, BlueBotics, Mobileye, Waymo, BAE Systems, ABB, Safran, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Autonomous Navigation Market Trends and Innovations
Solid-state lidar architectures and edge AI inference engines are compressing unit economics for autonomous navigation hardware while elevating software differentiation as the primary competitive battleground.
Solid-state lidar eliminates mechanical scanning components, reducing failure rates and maintenance intervals for commercial vehicle applications. Fleet operators in Milan's logistics corridor are specifying solid-state units for new yard tractor procurements. This hardware transition is displacing traditional electromechanical sensor suites as the default configuration in mid-market automation projects.
The EU AI Act imposes conformity assessment obligations on algorithmic decision systems used in autonomous mobility, requiring documented risk management and human oversight protocols. Italian OEMs must restructure development workflows to capture training data provenance and model validation evidence. Commercial vehicle segments face the steepest compliance burden, with vendors accelerating internal audit capabilities ahead of enforcement timelines.
Terminal operators are unbundling navigation system procurement from full-stack automation contracts, preferring to source perception and path-planning modules separately from vehicle integration services. This disaggregation pressures traditional system integrators to demonstrate algorithmic performance independent of hardware packaging. The shift is most visible in Genoa and La Spezia port authorities, where tender structures now separate software licensing from mechanical platform supply.
Italy Autonomous Navigation Market Segmentation
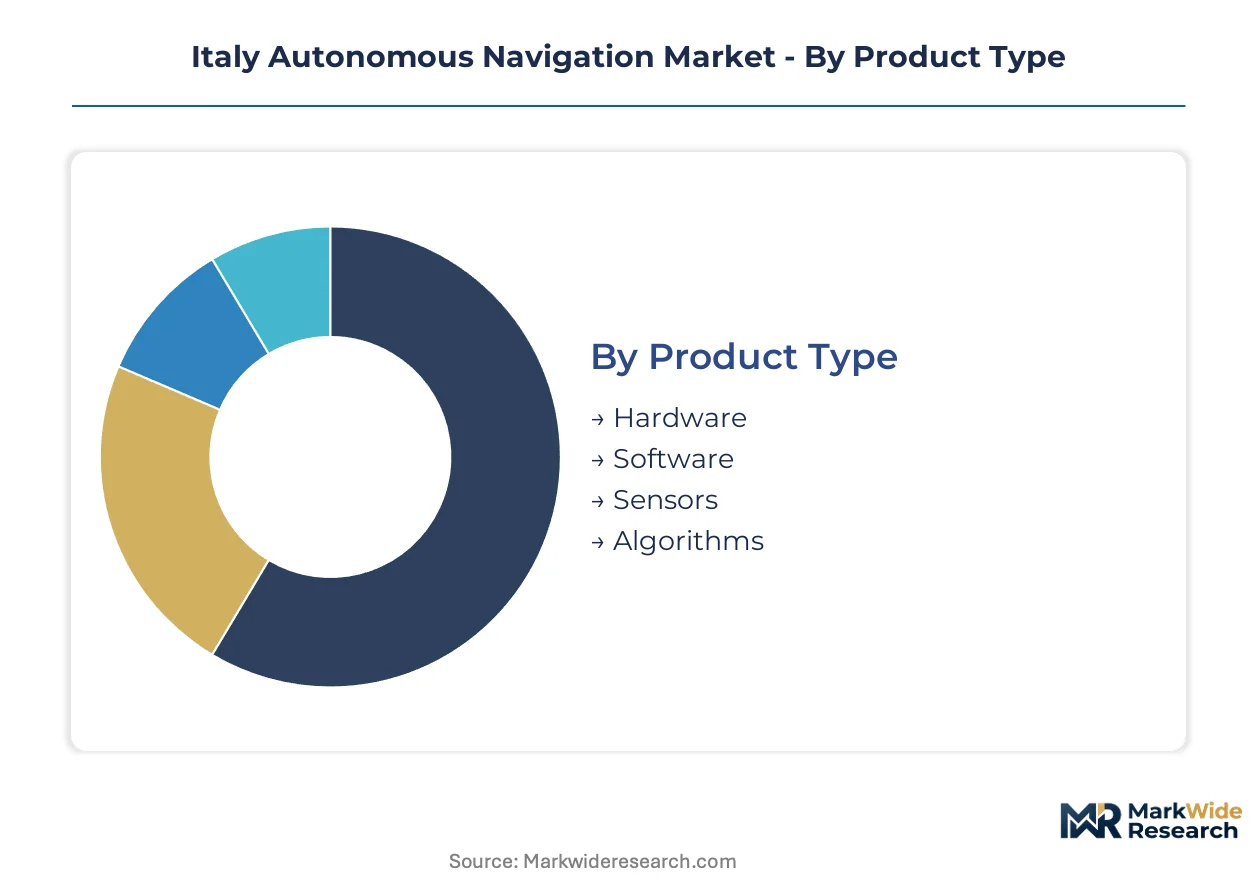
Segmentation reveals how autonomous navigation value flows through distinct procurement channels in Italy. Hardware and software components follow separate commercial pathways, while end-user concentration in Turin's automotive cluster and Milan's logistics corridor shapes demand patterns across all categories.
Product Type:
Hardware components move through direct OEM supply agreements, while software and algorithms increasingly route through subscription licensing channels to fleet operators and system integrators.
- Hardware:Encompasses computing platforms, control units, and mechanical actuation systems that execute navigation commands. Demand concentrates with automotive OEMs in Turin's manufacturing belt, where CE marking under the EU Machinery Directive governs factory-floor deployment eligibility.
- Software:Comprises real-time operating systems, middleware stacks, and fleet management platforms that orchestrate autonomous operations. Logistics companies in Milan's corridor are procuring software licenses separately from vehicle integration services, accelerating modular procurement trends.
- Sensors:Lidar, radar, and camera modules providing environmental perception data streams.
- Algorithms:Path-planning, localization, and decision-making code subject to EU AI Act conformity assessments.
By volume, Hardware leads. By growth pace, Software is ahead.
End User:
Customer concentration varies sharply by margin profile, with automotive OEMs capturing scale economies while logistics companies yield premium pricing for specialized yard automation.
- Automotive OEMs:Vehicle manufacturers integrating autonomous navigation into production models and commercial fleets. Turin's OEM cluster drives volume absorption, though procurement cycles extend due to legacy CAN bus retrofit requirements.
- Logistics Companies:Warehouse operators, port terminals, and yard fleet managers deploying robotics for container handling. Northern Italian port authorities in Genoa and La Spezia are expanding automation to address labor availability constraints.
- Consumer Electronics:Personal device and mobility product manufacturers.
- Public Transport:Municipal operators and regional transit authorities piloting autonomous shuttle services.
Automotive OEMs dominate installed base. Logistics Companies show the steepest expansion trajectory.
Technology:
Technology selection tracks application risk tolerance, with Lidar commanding premium positioning in high-assurance environments while Computer Vision penetrates cost-sensitive consumer segments.
- Lidar:Active ranging systems using laser pulses for centimeter-level spatial mapping. Solid-state architectures are displacing electromechanical units in Milan logistics procurements, reducing failure rates and maintenance intervals.
- Computer Vision:Camera-based perception systems employing deep learning for object recognition and scene understanding. Consumer-facing applications in personal mobility devices favor this technology for unit economics advantages.
- Radar:Radio-frequency sensing for velocity measurement and all-weather operation.
- GPS:Satellite-based positioning augmented with RTK corrections for outdoor navigation.
Lidar captures the highest per-unit value. Computer Vision is gaining share fastest in consumer-tier deployments.
Application:
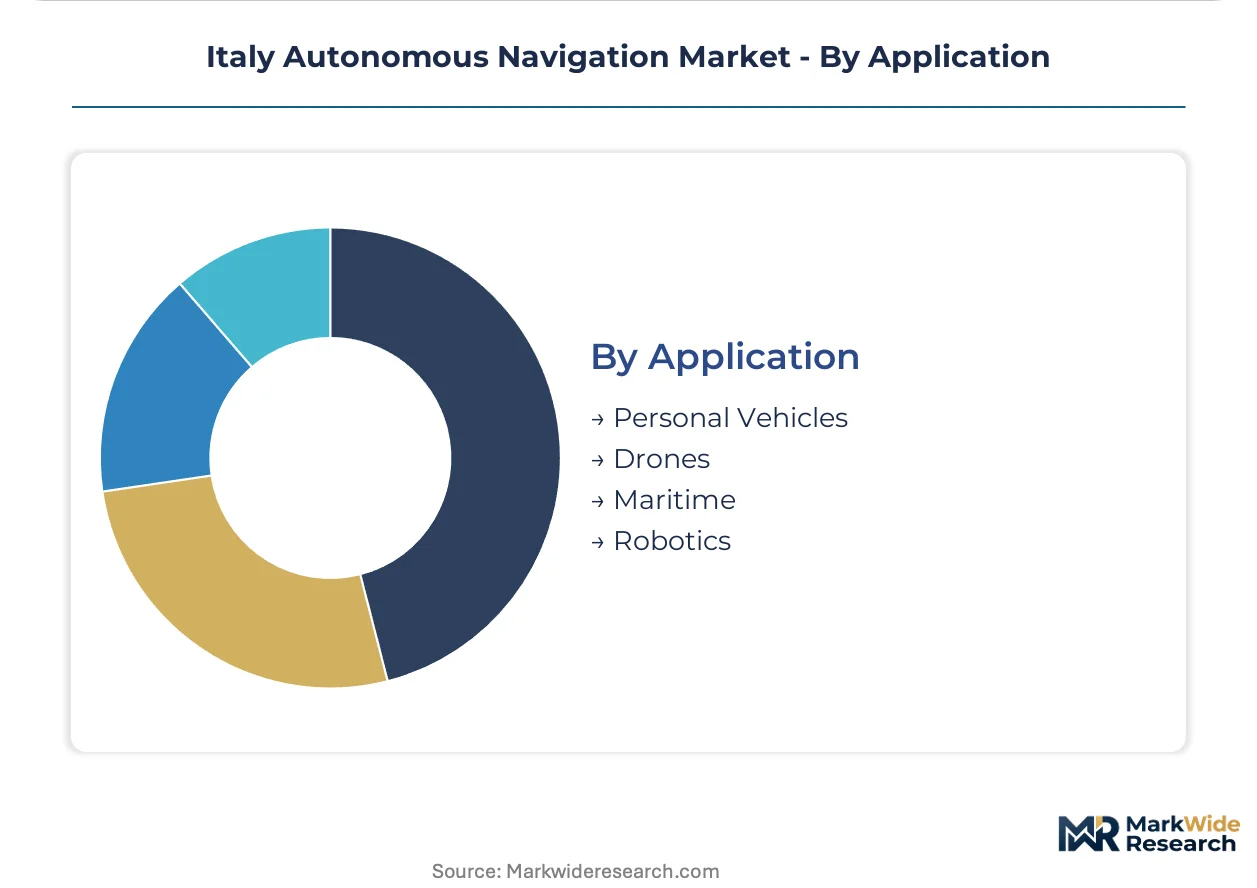
Application maturity correlates with operational environment predictability, with controlled industrial settings advancing ahead of unstructured urban deployments.
- Robotics:Industrial automation systems including warehouse AMRs and manufacturing floor AGVs. Emilia-Romagna's manufacturing belt sustains factory-floor demand, with CE marking pathways reducing deployment friction.
- Maritime:Port terminal automation and vessel navigation systems. Container handling yards in La Spezia and Genoa are specifying autonomous yard tractors, though Southern corridors like Naples-Porto Empedocle remain underpenetrated.
- Personal Vehicles:Passenger cars and light commercial vehicles with SAE Level 2+ capabilities.
- Drones:Aerial platforms for inspection, delivery, and defense applications.
Robotics leads in deployment volume. Maritime is climbing the fastest as port operators unbundle navigation procurement from full-stack automation contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure anchors continental Europe's autonomous yard automation demand, while Italy's Adriatic corridor and Germany's industrial belt compete for navigation technology deployment.
Piedmont
Turin's automotive manufacturing cluster drives volume absorption for factory-floor autonomous vehicles. CE marking under the EU Machinery Directive governs deployment eligibility for industrial robotics. Comau anchors production integration demand in this northwestern manufacturing belt.
Lombardy
Milan's logistics corridor sustains procurement of yard automation systems for warehouse and distribution operations. Italy's National Recovery and Resilience Plan channels EU cohesion funds toward smart mobility infrastructure in this region. Solid-state lidar specifications dominate new fleet procurements here.
Liguria
Genoa and La Spezia port authorities unbundle navigation procurement from full-stack automation contracts. The EU AI Act conformity assessments reshape tender structures for algorithmic decision systems. Terminal operators specify separate software licensing from mechanical platform supply.
Emilia-Romagna
Manufacturing automation demand concentrates in this industrial belt with reduced regulatory friction for CE-marked autonomous vehicles. ECHA REACH compliance governs sensor material composition for electronics suppliers. Factory-floor deployment accelerates across Bologna and Modena production hubs.
Campania
The Naples-Porto Empedocle logistics corridor shows minimal autonomous yard tractor deployment relative to Northern counterparts. EU cohesion funding allocations lag in Southern infrastructure tenders. First-mover positioning remains available for port terminal operators seeking automation scale.
Italy Autonomous Navigation Market Competitive Landscape
Listed leaders compete with private specialists across defense-aerospace and industrial automation verticals, producing a tiered structure where scale advantages concentrate in Turin and Milan corridor incumbents. Strategic archetypes include defense-heritage system integrators, industrial robotics specialists, and sensor fusion technology vendors. Competitive moves center on certification pathway acceleration and unbundled software licensing models.
Among defense-aerospace heritage anchors, Northrop Grumman Italia occupies a position exemplifying high-assurance navigation contract capture, while Comau represents the industrial robotics archetype sustaining factory-floor autonomy demand. Datalogic sits within the sensor fusion specialist tier competing for warehouse and port logistics environments. These three anchors illustrate how vendor eligibility rotates under CE marking and EU AI Act compliance pressures.
| Leading Market Players |
|---|
| Northrop Grumman Italia |
| Comau |
| Datalogic |
| BlueBotics |
| Mobileye |
| Waymo |
| BAE Systems |
| ABB |
| Safran |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with German and Asian sensor suppliers lock in lidar and radar module access while anchoring price visibility for Italian integrators navigating EU AI Act compliance timelines. These contracts insulate Turin OEMs and Milan logistics operators from spot-market volatility in critical perception hardware.
Pricing Analysis
Certification level under CE marking and EU AI Act conformity creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling algorithmic audit trails and human-in-the-loop protocols. Cost compression in mid-market sensor fusion modules is intensifying because solid-state lidar architectures are displacing electromechanical units. Logistics companies in Milan's corridor show highest price sensitivity due to thin yard-automation margins, while defense-aerospace buyers absorb premium pricing for high-assurance navigation stacks.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain component flow velocity for Italian integrators dependent on German and Taiwanese sensor module suppliers. Hardware value concentrates in Germany, Taiwan, and South Korea for lidar emitters, radar chipsets, and edge AI processors. Raw material dependencies span indium phosphide substrates, gallium arsenide wafers, and rare-earth magnets for precision actuation. Single-source vulnerability in solid-state lidar VCSEL arrays poses allocation risk. Distribution runs through direct OEM supply agreements for hardware and subscription licensing channels for algorithmic components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software update and algorithmic retraining services are expanding faster than hardware sales as EU AI Act compliance mandates recurring model validation cycles. This service-attach dynamic elevates recurring revenue multiples for vendors with embedded fleet relationships.
For Market Incumbents: Secure backward integration into sensor calibration and certification audit capabilities to defend against modular software competitors unbundling navigation stacks. Anchor exclusive supply relationships with German lidar suppliers before capacity reservation windows close. Deepen vertical control over safety-critical software engineering talent concentrated in Turin's automotive cluster. For New Entrants and Emerging Players: Post-deployment algorithmic monitoring and fleet optimization services represent a service-layer gap where incumbents under-serve mid-market logistics operators. Target Naples-Porto Empedocle port terminals with unbundled perception-module licensing to bypass entrenched Northern Italian integrators. Pursue cooperative perception pilots with 5G-V2X infrastructure providers as the go-to-market angle. For Investors and Strategic Acquirers: Dual-use navigation algorithm developers with military unmanned platform heritage and commercial CE marking pathways represent the acquisition target archetype with highest strategic optionality. Long-term viability hinges on regulatory capture through EU AI Act conformity assessment infrastructure. Monitor Italy's National Recovery and Resilience Plan smart mobility tender allocations as the inflection signal for fleet automation procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | CE marking and algorithmic audit capabilities unlock public-sector tender eligibility in Turin and Milan corridors. |
| Solid-State Lidar Supplier Partnership | Exclusive module allocation secures cost positioning for yard automation deployments in Genoa and La Spezia ports. |
| Software Licensing Unbundling | Separate algorithmic procurement from vehicle integration captures margin pools in logistics operator RFPs. |
| 5G-V2X Cooperative Perception Pilot | Cellular vehicle-to-everything integration enables dense urban navigation in Milan's smart mobility infrastructure. |
| Southern Corridor First-Mover Positioning | Naples-Porto Empedocle automation scale builds before EU cohesion funding allocations accelerate. |
Research Methodology
Initial hypotheses were tested against primary input from autonomous navigation engineering directors, fleet procurement managers at logistics operators, port terminal automation leads, and EU regulatory compliance officers, then refined through secondary validation. Primary interviews combined with customs trade data, SEC filings of listed sensor suppliers, EU tender documentation from Italy's National Recovery and Resilience Plan, and CE marking certification databases. Bottom-up fleet deployment estimates and top-down EU cohesion funding allocation analysis provided triangulation across the analysis window.
Variance decomposition across hardware, software, sensor, and algorithm segments drove the analytical framework, with technology maturity and regulatory compliance tier as cross-cutting dimensions. CAGRs were derived from installation base expansion rates and unit economics trajectories modeled through the projection horizon. Forecast inputs incorporated EU AI Act implementation timelines, solid-state lidar cost curves, and 5G-V2X infrastructure deployment schedules.
Underlying assumptions cover sustained EU cohesion funding flows, stable German-Asian sensor supply relationships, and linear EU AI Act enforcement progression, with deviation risk concentrated in tariff exposure on Taiwanese semiconductor inputs and delays in standardized urban navigation safety protocols. Recalibration cycles align with material shifts in EU AI Act delegated acts and Italy's smart mobility tender award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Middle East and Africa ADAS Market
Autonomous Vehicles
Autonomous Vehicle Sensor Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
North America Adaptive Steering Market