
 Immersion Cooling Market | 2026-2036
Immersion Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Immersion Cooling Market Intelligence
Software-defined thermal management is realigning the value proposition from simple hardware sales to integrated cooling-as-a-service models. Green Revolution Cooling leverages its long-standing expertise in single-phase systems for enterprise clients. LiquidStack specializes in two-phase solutions for high-density computing environments. Submer positions its offerings for both data center and edge computing applications, addressing a broad spectrum of deployment scales.
Immersion cooling is a thermal management technique where electronic components are submerged in a non-conductive dielectric liquid. This direct contact facilitates superior heat transfer compared to traditional air cooling, enabling higher-density server deployments. Within applications, data centers and high-performance computing represent the largest segments, driven by rising processor power densities. Two-phase cooling systems, while more complex, are gaining traction over single-phase options for their higher thermal efficiency in extreme-density racks.
Regulatory frameworks like the EU Green Deal and environmental regulations from the US EPA on specific fluorinated gases are shaping the choice of dielectric fluids. Concurrently, standards from organizations like the Open Compute Project and ISO influence system design and interoperability. Stakeholder decisions will hinge on balancing the total cost of ownership against evolving data center energy efficiency mandates.
Market Dynamics
The immersion cooling market's trajectory is defined by the escalating power density of modern processors clashing with stringent energy efficiency mandates. This dynamic forces data center operators to move beyond traditional air cooling, creating a structural shift toward direct liquid immersion as a necessary thermal management solution for high-performance and hyperscale computing.
Growth Catalysts
- High-Performance Computing:The proliferation of AI, machine learning, and scientific modeling workloads drives demand for processors with high thermal design power, making direct liquid cooling a necessity for stable operation and performance.
- Regulatory Mandates:The European Union's Corporate Sustainability Reporting Directive (CSRD) compels large data centers to disclose energy consumption and efficiency metrics, incentivizing the adoption of technologies like immersion cooling to meet sustainability targets.
- Data Center Concentration:The build-out of massive data center campuses in hubs like Northern Virginia and Central Texas creates concentrated pockets of demand where operators seek density and efficiency gains that immersion cooling provides.
Market Restraints
- High Initial Capex:Retrofitting existing air-cooled data centers for immersion cooling involves substantial upfront investment in tanks, dielectric fluids, and specialized infrastructure, posing a significant barrier for many operators.
- Fluid Selection Complexity:US EPA regulations on specific fluorinated gases and concerns over per- and polyfluoroalkyl substances (PFAS) complicate the selection of dielectric fluids, creating uncertainty and potential compliance risks.
- System Complexity:Two-phase immersion systems, despite their superior thermal efficiency, introduce complexities in fluid management and vapor recovery, leading to perceived operational risks and a preference for simpler single-phase solutions among some end-users.
Strategic Opportunities
- Edge Computing Deployments:The expansion of 5G and IoT applications creates an opportunity for compact, self-contained immersion cooling units at the network edge, where traditional cooling infrastructure is often unavailable.
- Cooling-as-a-Service Models:The convergence of immersion hardware with software-defined thermal management enables vendors to offer outcome-based service contracts, lowering the adoption barrier for customers hesitant about high initial capital costs.
- EU Green Deal Alignment:Broader policy frameworks like the EU Green Deal provide long-term tailwinds by promoting circular economy principles and energy efficiency, which supports investment in sustainable data center technologies.
Industry Challenges
- Standardization Gaps:A lack of universally accepted standards for tank design, fluid specifications, and server form factors, despite efforts by the Open Compute Project, slows widespread adoption and limits interoperability between vendor ecosystems.
- Legacy System Integration:Integrating immersion-cooled racks into facilities designed for air cooling presents significant operational challenges, requiring modifications to power distribution, facility monitoring systems, and maintenance protocols.
- Specialized Skill Scarcity:The market faces a shortage of technicians and engineers with the expertise to design, deploy, and maintain liquid immersion cooling systems, hindering implementation and long-term support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immersion Cooling Market |
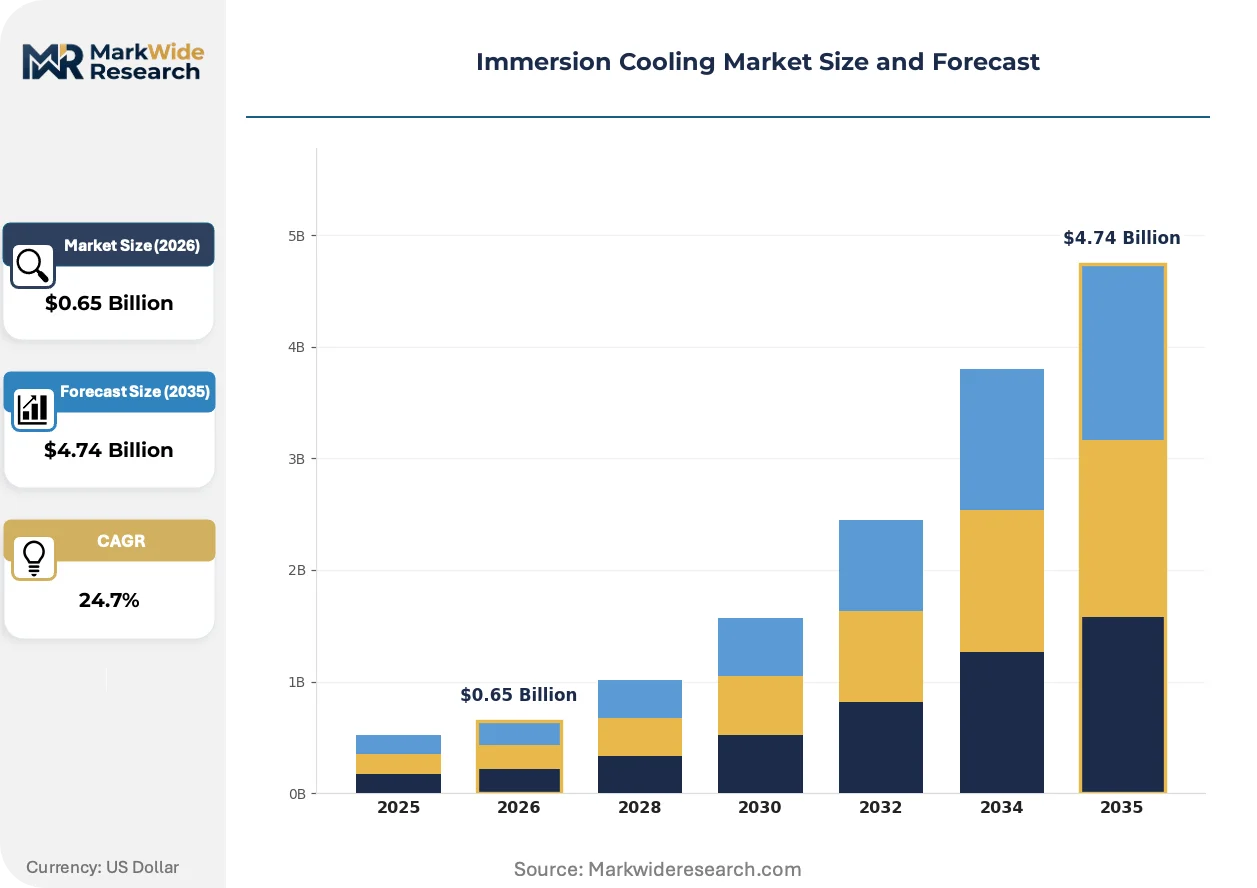
| Market Size in 2026 | $0.65 Billion |
| Market Size in 2035 | $4.74 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Two-Phase, Refrigerant-Based, Oil-Based Application: Data Centers, High-Performance Computing, Cryptocurrency Mining, Telecommunications End User: Enterprise, Cloud Providers, Academic Institutions, Research Facilities Installation Type: New, Retrofit, Modular, Integrated |
| Companies Covered | Submer, LiquidStack, Green Revolution Cooling, Iceotope, Asperitas, Midas Immersion Cooling, DUG Technology, Fujitsu, DCX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immersion Cooling Market Strategic Shifts & Innovations
A fundamental transition from component sales to integrated, software-driven thermal management is underway. This shift reflects a maturing market where performance and sustainability outcomes, governed by intelligent control systems, are becoming the primary value proposition over the hardware itself.
Software-defined thermal management provides real-time, granular control over cooling resources based on specific IT workloads. Hyperscale data centers and high-performance computing facilities are the primary adopters of this technology. This software layer is decentralizing thermal control from the general facility level down to individual server racks, enabling precise and efficient energy application.
United States EPA regulations under the AIM Act are accelerating the phase-down of certain fluorinated gases with high global warming potential. This action is forcing a rapid innovation cycle in the development of next-generation dielectric fluids. The chemical and materials segment is most affected, with research and development now centered on creating biodegradable or synthetic fluids that offer high performance without the associated environmental liabilities.
A clear pivot from one-time capital equipment sales to recurring revenue models based on performance is evident. This evolution disrupts traditional hardware distribution channels, favoring vendors who can deliver a complete service package including hardware, fluid lifecycle management, and operational support. The trend is most pronounced in the colocation and enterprise data center segments, where total cost of ownership and operational predictability are paramount.
Immersion Cooling Market Segmentation
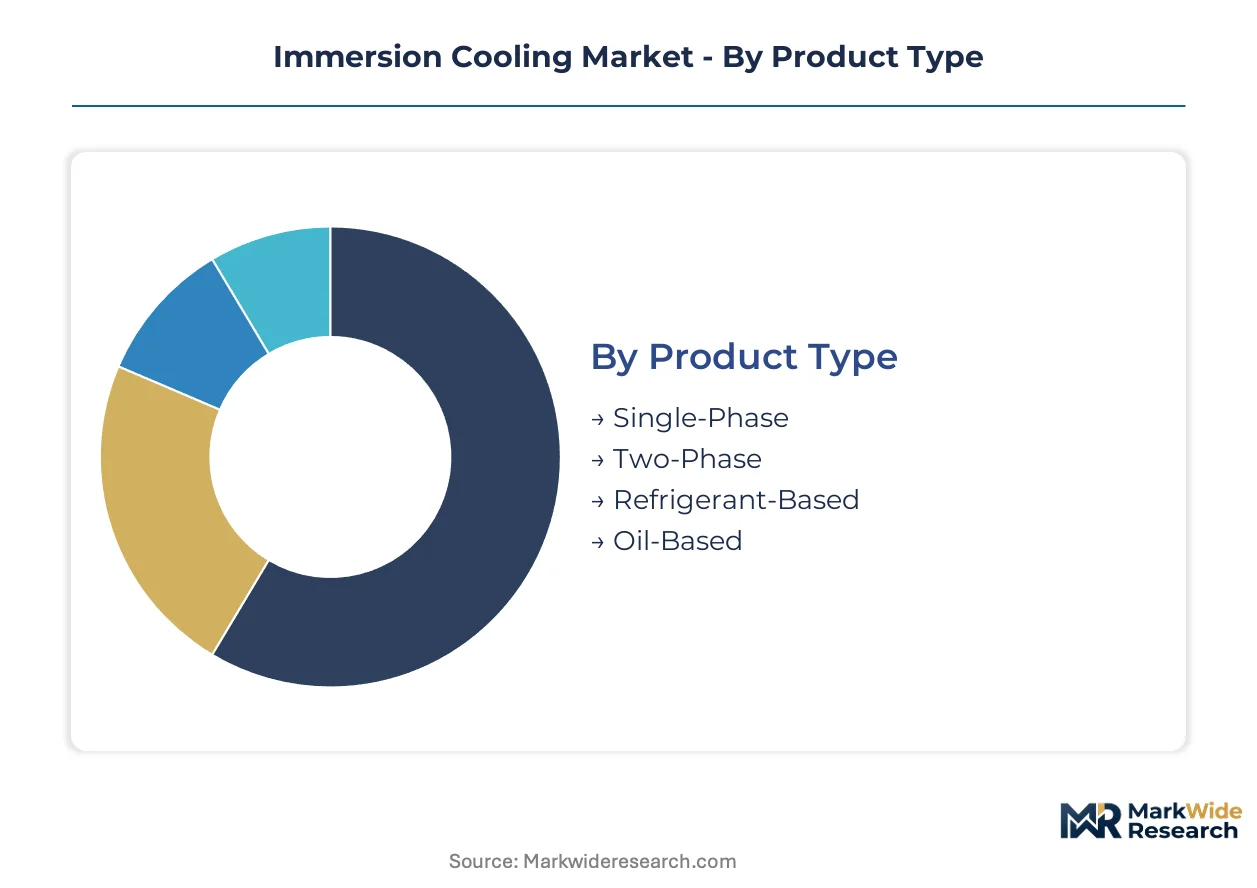
The immersion cooling market segmentation provides a granular understanding of diverse technological approaches and varied end-user requirements. Analyzing these segments helps stakeholders identify specific growth vectors and strategic entry points within the evolving thermal management landscape.
Product Type:
The product type segmentation highlights the customization versus standardization spectrum in dielectric fluid technologies.
- Two-Phase:Involves a dielectric fluid that boils off components, transferring heat through a phase change. Demand concentrates in hyperscale data centers in the United States, driven by extreme power densities and efficiency targets.
- Single-Phase:Submerges IT equipment in a non-conductive liquid that remains in a liquid state, transferring heat via circulation. Enterprise clients in Europe widely adopt this technology, valuing its operational simplicity and proven reliability.
- Refrigerant-Based:Utilizes engineered fluids designed for specific boiling points and thermal properties, often for specialized high-density applications.
- Oil-Based:Employs mineral or synthetic oils as dielectric coolants, offering a cost-effective solution for some data center environments.
Most installed capacity flows through Single-Phase systems. Expansion is steepest in Two-Phase solutions.
Application:
This application segmentation illustrates the varied demands placed on immersion cooling solutions across different computing environments.
- Data Centers:Covers hyperscale, colocation, and enterprise facilities seeking energy efficiency and higher server density. Operators in Northern Virginia prioritize immersion cooling for its potential to reduce operational expenditures and meet sustainability goals.
- High-Performance Computing:Involves supercomputers and clusters used for complex simulations and AI/ML workloads requiring precise thermal management. Research institutions in Germany deploy these systems to maintain peak processor performance and stability.
- Cryptocurrency Mining:Employs immersion cooling to manage the intense heat generated by specialized hardware, optimizing efficiency and extending equipment lifespan.
- Telecommunications:Utilizes compact immersion units for edge computing sites and 5G infrastructure, where space and traditional cooling are limited.
The largest segments by volume are Data Centers and High-Performance Computing. Emerging applications include Telecommunications and Cryptocurrency Mining.
End User:
The end-user segmentation reveals distinct operational priorities and infrastructure requirements across various customer types.
- Cloud Providers:Operate massive data center campuses, prioritizing scalability, power usage effectiveness, and total cost of ownership. Major cloud operators in Ireland invest in immersion cooling to support their expanding global infrastructure.
- Enterprise:Includes corporate data centers and private cloud deployments, focusing on reliability, ease of integration, and long-term asset protection. European enterprises adopt these solutions to comply with stringent energy efficiency mandates.
- Academic Institutions:Deploy immersion cooling for their high-performance computing clusters, supporting scientific research and educational programs.
- Research Facilities:Utilize advanced thermal management for experimental setups and specialized computing, ensuring stable conditions for critical scientific work.
Demand is primarily driven by Cloud Providers and Enterprise segments. Academic Institutions and Research Facilities present specialized needs for high-density computing.
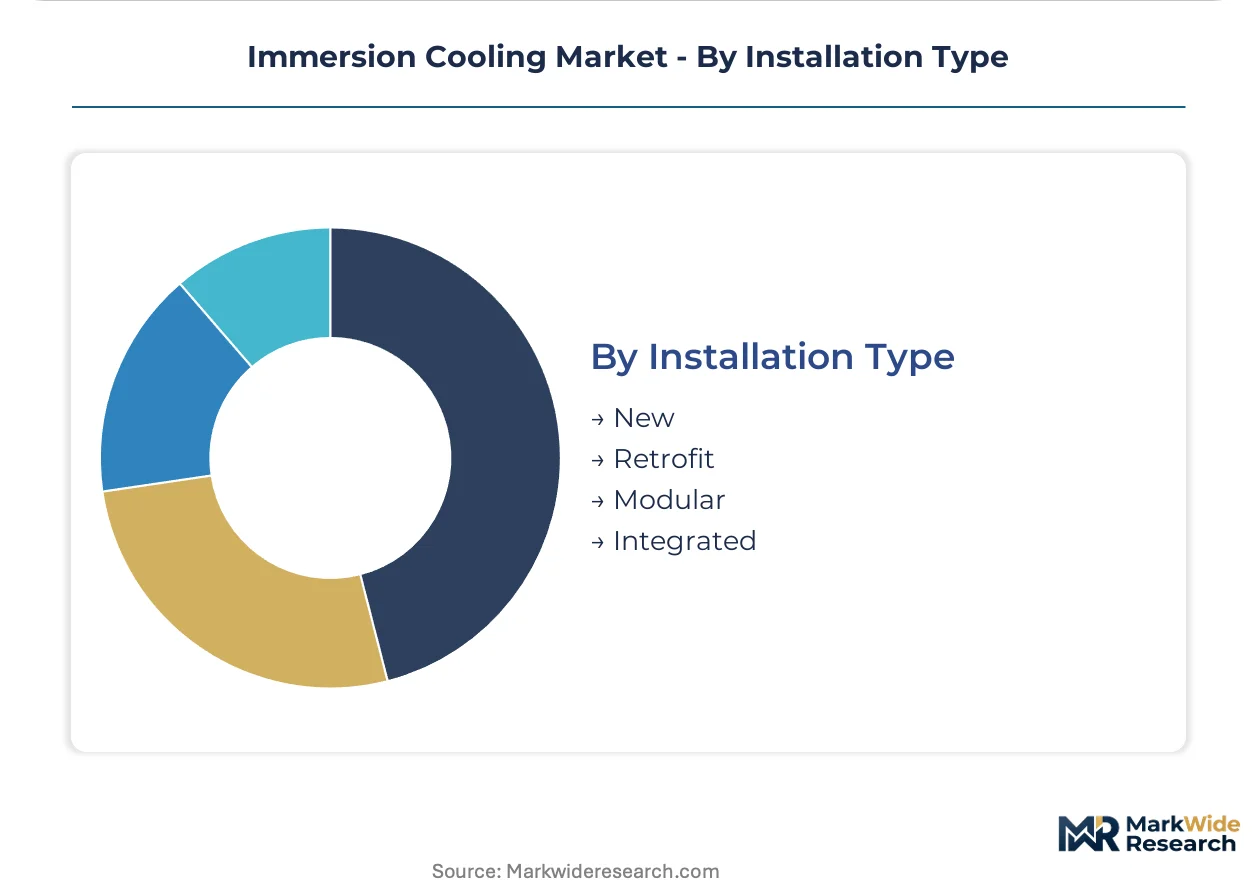
Installation Type:
This installation type segmentation highlights deployment flexibility and integration complexity for immersion cooling solutions.
- New:Involves designing and building facilities specifically for immersion cooling, optimizing infrastructure from the ground up. Hyperscale data center builds in Texas frequently incorporate new immersion cooling designs for maximum efficiency.
- Retrofit:Adapts existing air-cooled data centers to accommodate immersion cooling tanks and systems, often requiring significant infrastructure modifications. Operators in the United Kingdom consider retrofits to extend the life of older facilities while improving energy performance.
- Modular:Consists of pre-fabricated, self-contained immersion cooling units, ideal for rapid deployment and scalable expansion at the edge.
- Integrated:Refers to systems where immersion cooling is deeply embedded within the overall data center infrastructure, providing seamless operation and management.
The majority of current deployments are in New installations. Future growth is concentrated in Modular and Retrofit solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Immersion Cooling Market demonstrates varied adoption patterns, with the United States showing strong demand for hyperscale data centers, while European nations prioritize stringent energy efficiency mandates. This global landscape underscores distinct regional drivers for advanced thermal management solutions.
United States
Demand for immersion cooling in the United States stems from the rapid expansion of AI and high-performance computing workloads. US EPA regulations under the AIM Act accelerate the phase-down of certain fluorinated gases, influencing fluid selection. Major data center hubs in Northern Virginia and Central Texas are seeing significant investment in new immersion cooling designs.
Germany
Germany's market for immersion cooling is driven by research institutions and high-performance computing clusters requiring stable thermal environments. The EU Green Deal broadly promotes sustainable data center technologies across Germany. Research facilities in cities like Jülich and Dresden are deploying advanced immersion systems for critical scientific work.
United Kingdom
The United Kingdom sees demand for immersion cooling in retrofitting existing data centers to improve energy performance. Operators consider these solutions to extend the life of older facilities while meeting evolving sustainability goals. London's colocation data centers are exploring modular and retrofit immersion solutions for increased density and efficiency.
Ireland
Cloud providers in Ireland are expanding their data center campuses, necessitating scalable and energy-efficient cooling solutions. The Corporate Sustainability Reporting Directive (CSRD) influences operational decisions for large data centers in Ireland. Dublin and other key data center locations are attracting investment in immersion cooling to support hyperscale infrastructure.
Immersion Cooling Market Key Industry Players
Top-tier vendors anchor the immersion cooling market, while specialized solution providers offer niche capabilities for specific use cases. This tiered structure reflects varying levels of integration and global reach among market participants. Strategic archetypes include hardware manufacturers focusing on tanks and racks, fluid specialists developing advanced dielectric liquids, and integrated cooling-as-a-service providers. Dominant competitive moves involve strategic partnerships to expand solution portfolios and geographic expansion into new data center hubs, particularly in high-growth regions.
Specialists in different immersion cooling approaches include Submer, LiquidStack, and Green Revolution Cooling. Submer represents providers positioning offerings for both data center and edge computing applications, addressing a broad spectrum of deployment scales. LiquidStack exemplifies companies focused on two-phase solutions for high-density computing environments, emphasizing thermal efficiency. Green Revolution Cooling anchors the segment of vendors leveraging long-standing expertise in single-phase systems, particularly for enterprise clients. These companies collectively illustrate the diverse technological and strategic focuses within the immersion cooling market.
| Leading Market Players |
|---|
| Submer |
| LiquidStack |
| Green Revolution Cooling |
| Iceotope |
| Asperitas |
| Midas Immersion Cooling |
| DUG Technology |
| Fujitsu |
| DCX |
| Others |
Cost & Logistics Intelligence
Cloud providers' concentrated demand for energy efficiency and operational predictability drives the market towards outcome-based service contracts, influencing pricing models across the immersion cooling ecosystem.
Pricing Analysis
Capacity additions in US data center hubs are reshaping price floors for immersion cooling hardware. The dominant pricing model combines project-based hardware sales with recurring outcome-based service contracts for fluid management and operational support. Price differentiation stems from the customization level for specific IT workloads and the inclusion of after-sales fluid lifecycle management. Pricing pressure on hardware unit costs stems from increasing competition and the need to lower initial capital expenditure barriers for operators. Enterprise clients exhibit higher price sensitivity regarding initial Capex, while hyperscale cloud providers prioritize total cost of ownership and long-term energy efficiency.
Supply Chain Analysis
Dielectric fluid formulations rely on a specialized chemical supply chain. Geographic supply concentration includes specialty chemical producers in Europe for advanced fluids and Asia for basic mineral oils, alongside manufacturing of tanks and systems in North America and Europe. Raw material dependencies include specialized dielectric fluids, high-grade metals for tanks, pumps, and heat exchangers. Regulatory restrictions on specific fluorinated gases, such as those from the US EPA AIM Act, represent a structural risk, causing fluid reformulation delays and supply uncertainty. Distribution occurs primarily through direct sales to large data center operators and via specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a compelling margin-expansion story, driven by the strategic shift from hardware sales to software-defined thermal management and integrated service models.
For Market Incumbents:Anchor existing client relationships through integrated service offerings that span hardware, fluids, and software control. Invest in research and development for next-generation biodegradable fluids to mitigate regulatory risks and differentiate offerings. Consider acquiring specialized software-defined thermal management startups to enhance platform capabilities and expand recurring revenue streams. The emergence of new fluid chemistries from specialized chemical firms poses a potential threat. Certification investment in standards like those from the Open Compute Project serves as a critical lever for market acceptance.
For New Entrants and Emerging Players:Data center design and build firms represent a critical channel partner type for market entry. Target white-space opportunities in modular edge computing deployments and specialized high-performance computing clusters. The telecommunications sector, particularly for 5G infrastructure, offers the most penetrable segment due to space constraints and limited traditional cooling options. A compelling go-to-market angle involves offering compact, pre-integrated modular units with simplified deployment and maintenance protocols.
For Investors and Strategic Acquirers:Large industrial conglomerates with existing thermal management divisions are the most active acquirers in this space. The long-term viability for immersion cooling is strong, positioning it as an essential infrastructure technology with tailwinds from AI proliferation and sustainability mandates. Acquisition targets should include firms with patented fluid technologies or advanced software control platforms that offer distinct competitive advantages. The acceleration of large-scale retrofit projects across Europe serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Co-develop integrated solutions with major IT hardware vendors for hyperscale clients. |
| Fluid R&D Investment | Accelerate development of environmentally compliant dielectric fluids to meet evolving regulations from the US EPA. |
| Service Model Expansion | Offer Cooling-as-a-Service contracts with performance guarantees to lower customer adoption barriers. |
| Modular Unit Development | Design compact, self-contained systems for rapid deployment in edge computing environments. |
| Geographic Expansion | Establish local support and manufacturing capabilities in key data center hubs like Northern Virginia. |
Research Approach
Direct dialogue with data center architects, IT procurement managers, thermal engineers, and fluid chemists forms the qualitative grounding for this analysis. This primary research is validated against extensive secondary sources, including industry association reports from the Open Compute Project, government energy efficiency mandates like the EU Corporate Sustainability Reporting Directive, and academic research papers on advanced thermal management. A robust bottom-up and top-down triangulation approach ensures comprehensive market sizing and forecasting.
A bottom-up analytical lens, cross-referenced with top-down market validation, frames the forecast framework across the analysis window. Segmentation dimensions modeled include product type, application, end-user, installation type, and regional regulatory impact. Compound annual growth rates are derived by integrating historical adoption trends with projected technological advancements and policy shifts. Processor power density trends and data center build-out rates in key regions serve as critical industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rapid shifts in fluid regulations, unforeseen technological breakthroughs in alternative cooling, or significant changes in global data center investment patterns. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market