
 Ireland Data Center Cooling Market | 2026-2036
Ireland Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Cooling Market Insights
Refrigeration engineering talent is reorganizing around Ireland's data center corridor, with specialist contractors and commissioning engineers migrating from traditional HVAC sectors into precision cooling roles. Schneider Electric SE leverages its European manufacturing footprint to anchor supply chains serving Irish hyperscale builds. Vertiv Group Corp. competes through service density, maintaining rapid-response technician pools across Dublin and Cork. STULZ specializes in close-coupled cooling units calibrated for Ireland's temperate maritime climate, reducing chiller runtime hours.
Data center cooling encompasses the engineered systems that maintain thermal equilibrium for IT infrastructure, typically holding server inlet temperatures between 18°C and 27°C per ASHRAE guidelines while rejecting heat loads ranging from 5 kW to 50+ kW per rack. Liquid cooling solutions are capturing the fastest expansion trajectory as GPU-intensive AI workloads exceed air-cooling thresholds in Irish facilities. Chilled water systems still dominate installed base value, though retrofit projects face space constraints that favor modular installations with smaller footprints. Hyperscale providers command the largest procurement volumes, while colocation facilities represent higher-margin opportunities due to customized SLA requirements.
The Environmental Protection Agency enforces Ireland's industrial emissions licensing for data centers, while the Commission for Regulation of Utilities governs grid connection agreements that indirectly cap cooling power draw. SEAI building regulations and EU ETS carbon pricing are forcing operators to document refrigerant leakage rates and phase down high-GWP working fluids. Stakeholders must monitor planning board decisions on strategic data center zones, as local authority cooling load approvals will determine where infrastructure can scale.
Market Dynamics
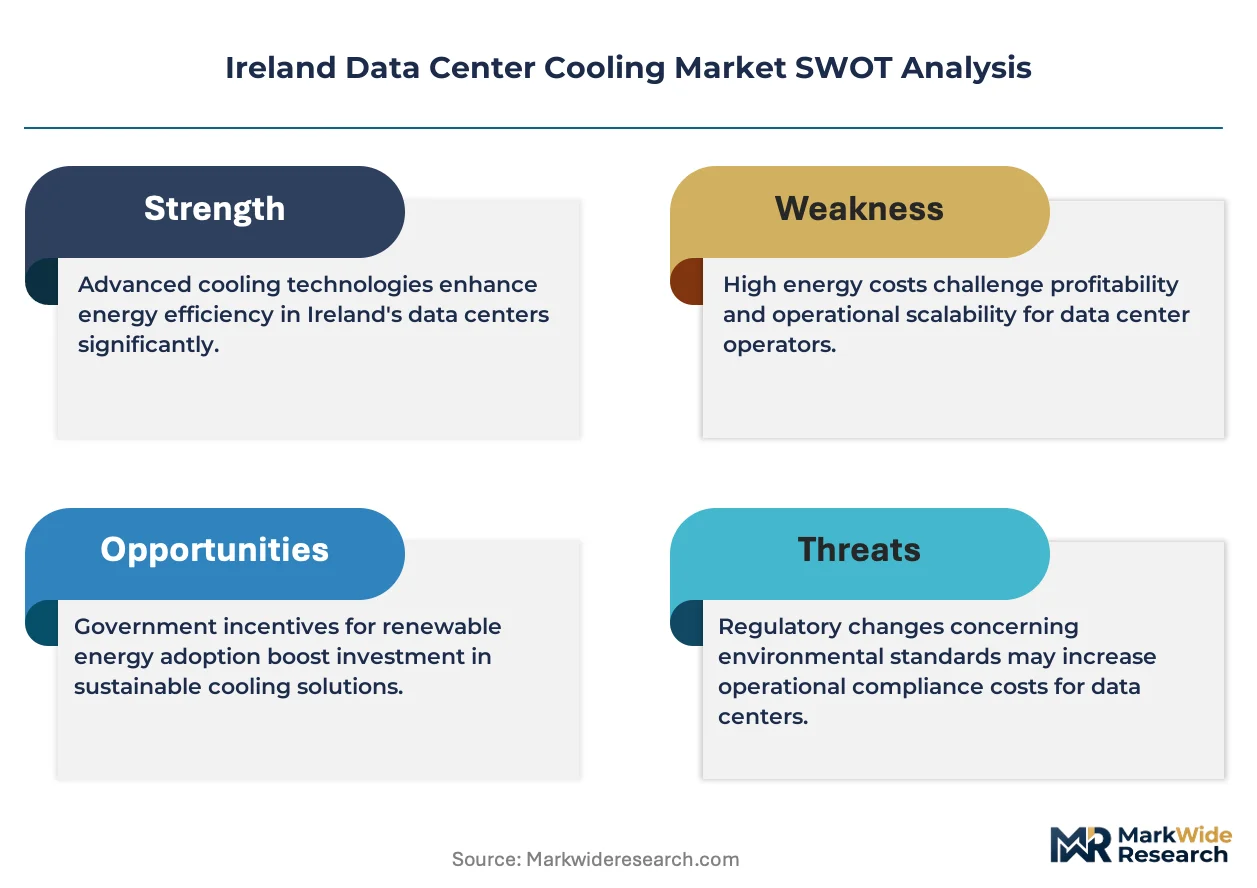
Power grid constraints across the Greater Dublin Area are compressing deployment timelines and forcing operators toward higher-density liquid cooling architectures that maximize compute per megawatt.
Growth Catalysts
- EU Energy Efficiency Directive:Mandates for data center power usage effectiveness are accelerating retrofit demand across existing facilities in Cork and Dublin.
- Hyperscale cloud expansion:Microsoft, Amazon, and Google are committing to multi-hundred-megawatt campuses that require advanced thermal management at scale.
- Maritime climate advantage:Ireland's temperate weather enables extended free cooling hours, reducing chiller energy consumption versus continental European locations.
Market Restraints
- Grid interconnection queues:EirGrid's connection approval delays are stretching project timelines to 36-48 months for large-scale facilities.
- Copper and aluminum price volatility:Liquid cooling manifold fabrication costs are fluctuating with commodity markets, squeezing contractor margins.
- Refrigerant phase-down requirements:EU F-Gas Regulation restrictions on high-GWP working fluids are complicating chiller fleet planning for legacy sites.
Strategic Opportunities
- SEAI grant programs:Capital incentives for energy efficiency retrofits are unlocking upgrade budgets at colocation facilities seeking competitive differentiation.
- Immersion cooling convergence:Dielectric fluid systems paired with waste heat recovery are creating circular economy propositions for district heating networks.
- Cork secondary market:Planning restrictions in Dublin are redirecting development toward the southern corridor with lower land costs and available grid capacity.
Industry Challenges
- Refrigeration engineer scarcity:Specialist talent is migrating from commercial HVAC into data center roles faster than training pipelines can replenish.
- Legacy air-cooled retrofit complexity:Space-constrained facilities face structural barriers to installing liquid cooling infrastructure without operational disruption.
- Commissioning timeline compression:Hyperscale deployment schedules are compressing acceptance testing windows for thermal performance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Cooling Market |
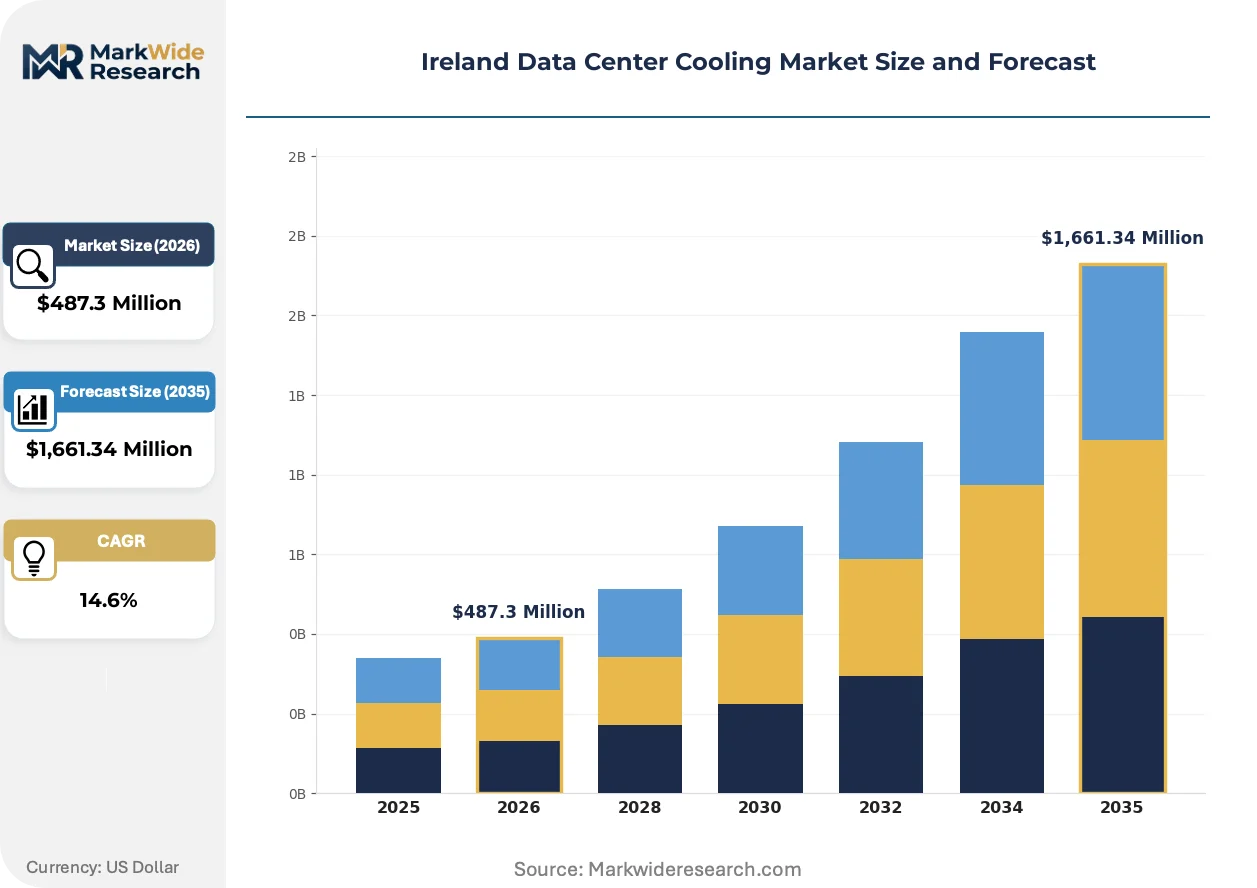
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled Water Systems, Air Conditioning Units, Liquid Cooling Solutions, Refrigerant-Based Cooling Cooling Technology: Air-Based, Water-Based, Evaporative Cooling, Immersion Cooling End User: Hyperscale Providers, Colocation Facilities, Enterprises, Managed Service Providers Installation Type: New Data Centers, Retrofit Projects, Modular Installations, On-Premise Solutions |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Rittal GMBH & Co. KG, Trane Technologies Company LLC, Daikin Applied (UK) Ltd, STULZ, Munters Corporation, FlaktGroup, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are fundamentally restructuring how Irish facilities manage thermal loads, with three converging developments reshaping equipment procurement and system design priorities.
Direct-to-chip liquid cooling is decomposing the traditional raised-floor air distribution model that has dominated Irish colocation facilities for two decades. Hyperscale operators are specifying cold plate manifolds as standard for GPU-intensive racks exceeding 30 kW density. This decomposition is collapsing the mechanical footprint per megawatt, enabling operators to extract more compute from constrained Dublin real estate.
The Environmental Protection Agency's industrial emissions licensing framework is tightening refrigerant leak detection and reporting obligations for data center cooling systems. Operators must now install continuous monitoring infrastructure and submit annual leakage rate documentation. Colocation providers are responding fastest, embedding compliance costs into service level agreements to transfer liability to tenants.
Heat reuse contracting is altering how Irish facilities monetize thermal output, with operators negotiating long-term supply agreements with district heating authorities. Traditional equipment vendors are restructuring service offerings to include heat network integration engineering. Cork's municipal heating scheme is emerging as the testbed for these arrangements, with several facilities pursuing combined heat and compute certifications.
Ireland Data Center Cooling Market Segmentation
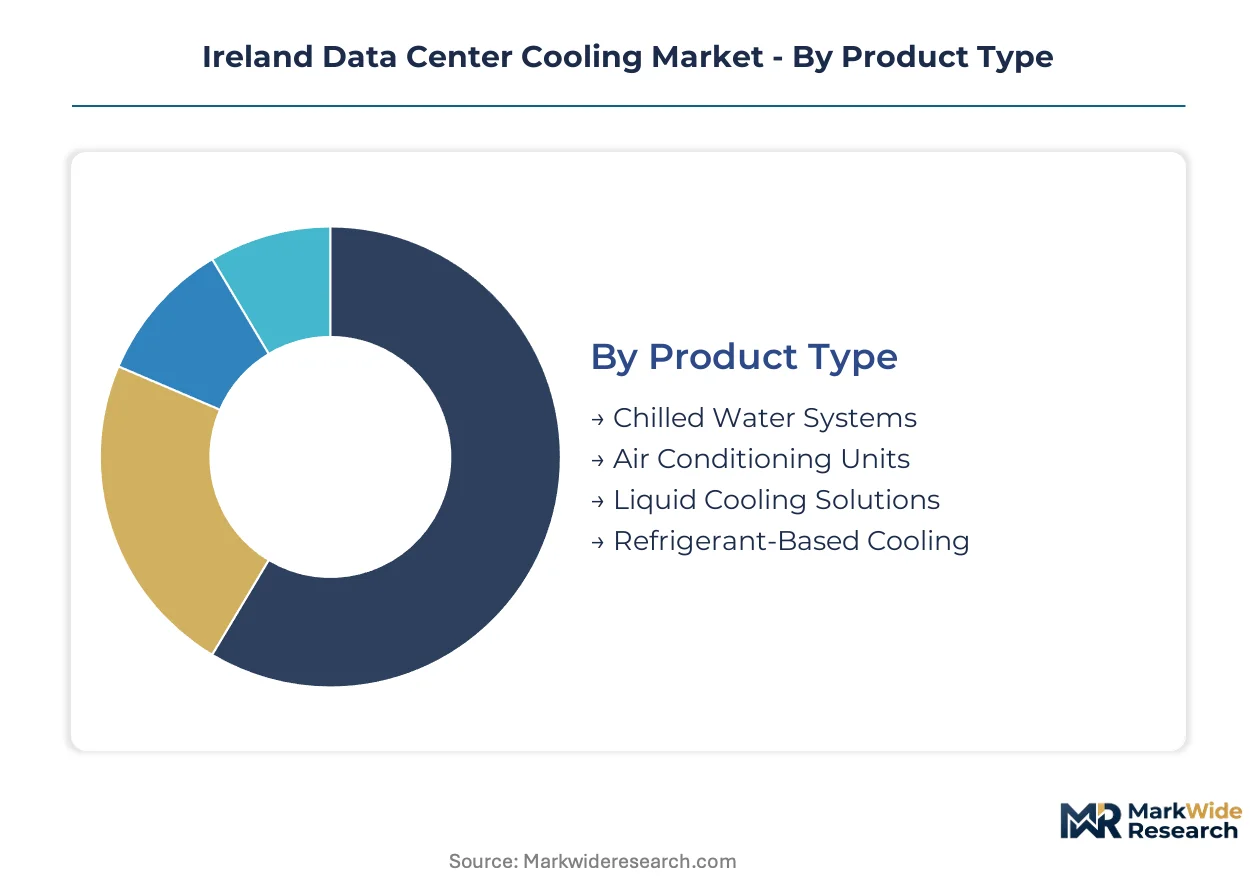
Segmentation reveals how procurement channels fragment across Irish data center operators. Channel strategy must align with hyperscale direct-buy patterns versus colocation integrator routes. Each dimension exposes distinct margin structures and technical specification requirements.
Product Type:
Channel flows diverge sharply: hyperscale operators source liquid cooling and chilled water systems through direct manufacturer relationships, while colocation and enterprise segments rely on mechanical contractors and system integrators for air conditioning and refrigerant-based units.
- Liquid Cooling Solutions:Cold plate and immersion systems circulate dielectric fluids or water-glycol mixtures directly to processor heat sinks. Demand concentrates in Greater Dublin Area hyperscale campuses where GPU densities exceed 30 kW per rack and EirGrid interconnection caps force compute-per-megawatt optimization. Direct procurement from specialized vendors dominates this segment.
- Chilled Water Systems:Central plant architectures distribute conditioned water through CRAH units or fan walls, maintaining ASHRAE-compliant supply temperatures. Retrofit demand in legacy Cork and Dublin facilities drives specification of compact chiller plants with magnetic bearing compressors to meet SEAI efficiency grant thresholds. Systems integrators and MEP contractors capture most procurement flow.
- Air Conditioning Units:CRAC and CRAH equipment for raised-floor distribution remains prevalent in enterprise and smaller colocation deployments. Specification favors close-coupled row-based units to minimize fan energy.
- Refrigerant-Based Cooling:DX split systems and packaged rooftop units serve edge and modular installations where water infrastructure is unavailable. Contractors source through HVAC distribution channels.
By volume, Chilled Water Systems leads. By growth pace, Liquid Cooling Solutions is ahead.
Cooling Technology:
Cost tier stratification separates premium immersion and advanced water-based systems from standard air and evaporative approaches. Capital expenditure per kilowatt of cooling capacity spans threefold between base air-cooled architectures and full immersion deployments.
- Immersion Cooling:Single-phase and two-phase dielectric fluid systems submerge entire server assemblies, eliminating fans and enabling heat recovery integration. Trials at Cork municipal heating network facilities are validating commercial viability for district heat supply contracts. Premium pricing reflects fluid costs and specialized infrastructure requirements.
- Water-Based:Direct-to-chip cold plates and rear-door heat exchangers capture waste heat at the rack level. Hyperscale Dublin campuses specify these as standard for AI training clusters above 40 kW density. Mid-tier capex positioning drives rapid share expansion.
- Air-Based:Traditional raised-floor and hot-aisle containment architectures dominate legacy installed base. Replacement cycles favor energy-efficient fan upgrades over full system replacement.
- Evaporative Cooling:Adiabatic and direct evaporative systems exploit Ireland's maritime climate for extended free cooling hours. Lower operating costs offset moderate water consumption concerns.
Air-Based technology retains the largest installed footprint. Immersion Cooling is climbing the fastest as heat reuse economics mature.
End User:
Customer type determines specification authority and procurement velocity. Hyperscale operators internalize engineering decisions and compress vendor selection cycles, while enterprise and managed service segments delegate technical specification to design consultants.
- Hyperscale Providers:Microsoft, Amazon, and Google operate captive engineering organizations that specify custom cooling architectures for multi-hundred-megawatt campuses. Direct vendor relationships eliminate distributor margins and enable co-development of next-generation thermal systems.
- Colocation Facilities:Equinix, Digital Realty, and indigenous operators balance standardized designs against tenant-specific SLA requirements. Multi-tenant environments demand flexible cooling zones supporting diverse density commitments.
- Enterprises:Financial services and pharmaceutical operators in Dublin maintain captive facilities with conservative technical specifications. Procurement flows through facilities management and corporate real estate functions.
- Managed Service Providers:Regional IT outsourcing firms operate smaller edge facilities with limited in-house engineering. Reliance on contractor recommendations produces price-sensitive equipment selection.
Hyperscale Providers command procurement volume leadership. Colocation Facilities are gaining share fastest as cloud repatriation and hybrid strategies expand.
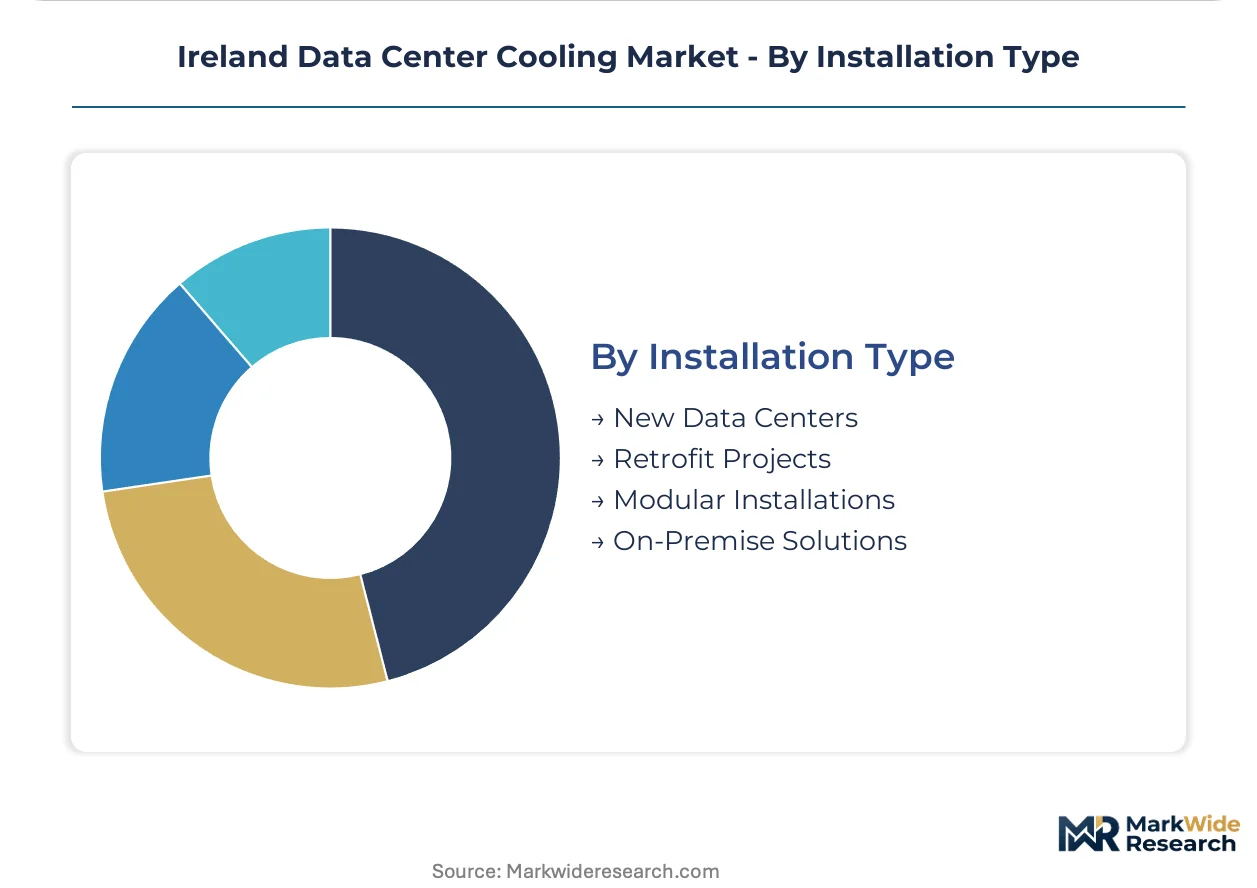
Installation Type:
Maturity differentiation separates greenfield new construction from complex retrofit environments. New data centers enable optimized thermal architectures, while retrofit projects confront space, structural, and operational constraints that favor modular and containerized approaches.
- New Data Centers:Greenfield construction in Cork and designated strategic zones permits integrated thermal design from foundation to roof. Liquid cooling infrastructure embeds during civil works, avoiding later disruption costs.
- Retrofit Projects:Legacy Dublin facilities confront slab loading limits, ceiling height constraints, and live-environment installation requirements. Phased cutover strategies prioritize modular equipment with minimal structural modification.
- Modular Installations:Prefabricated power and cooling modules accelerate deployment for grid-constrained sites awaiting permanent infrastructure. Factory acceptance testing reduces on-site commissioning risk.
- On-Premise Solutions:Enterprise server rooms and edge locations deploy packaged units with minimal engineering support. Standardized specifications enable rapid procurement cycles.
New Data Centers dominates current investment flow. Retrofit Projects are expanding most quickly as SEAI grant programs unlock upgrade budgets at existing facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland's data center cooling market diverges from continental European patterns through its hyperscale-dominated procurement structure and maritime climate dependency, whereas Germany and the Netherlands emphasize industrial colocation density and France prioritizes nuclear-powered grid stability for thermal loads.
Greater Dublin Area
Hyperscale cloud operators concentrate multi-hundred-megawatt campuses across Dublin and surrounding counties, driving specification of liquid cooling architectures that maximize compute per constrained megawatt. The Commission for Regulation of Utilities governs grid interconnection agreements that indirectly cap cooling power draw, forcing thermal innovation. Tallaght and Clondalkin industrial zones host the densest clustering of precision cooling infrastructure deployment.
Cork Metropolitan Region
Secondary market expansion redirects development from Dublin toward available grid capacity and lower land costs in Ireland's southern corridor. SEAI grant programs for energy efficiency retrofits unlock upgrade budgets at existing facilities seeking competitive differentiation. Little Island and Ringaskiddy industrial estates emerge as testbeds for immersion cooling convergence with district heating network integration.
Galway and Western Corridor
Edge computing and enterprise facilities populate smaller urban centers with modular cooling requirements and limited in-house engineering capacity. The Environmental Protection Agency enforces industrial emissions licensing that tightens refrigerant leak detection obligations across all facility scales. Oranmore business parks attract managed service providers deploying standardized air-cooled architectures.
Limerick-Shannon Economic Zone
Pharmaceutical and medical technology enterprises maintain captive data centers with conservative technical specifications and facilities management procurement flows. EirGrid's western network reinforcement programs ease interconnection timelines relative to Dublin queues. Shannon Free Zone hosts hybrid cloud deployments balancing on-premise thermal loads with colocation overflow capacity.
Ireland Data Center Cooling Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Ireland's data center cooling market, with full-system providers controlling hyperscale direct procurement channels while component specialists capture retrofit and colocation integrator flows. The structure concentrates around three strategic archetypes: European manufacturing anchors with captive supply chains, rapid-response service density operators maintaining technician pools across Dublin and Cork, and climate-calibrated specialists optimizing for maritime free cooling economics. Dominant competitive moves include geographic service network expansion to compress commissioning timelines and portfolio diversification into heat reuse engineering for district heating integration.
Among the integrated European tier, Schneider Electric SE anchors supply chain relationships serving Irish hyperscale builds through its continental manufacturing footprint. Vertiv Group Corp. occupies a position exemplifying service-density competition, with rapid-response technician pools positioned across Dublin and Cork metropolitan areas. STULZ represents the climate-specialist archetype, with close-coupled cooling units calibrated for Ireland's temperate maritime conditions to reduce chiller runtime hours.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Rittal GMBH & Co. KG |
| Trane Technologies Company LLC |
| Daikin Applied (UK) Ltd |
| STULZ |
| Munters Corporation |
| FlaktGroup |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance certification gates supplier qualification and simultaneously stratifies price tiers across Ireland's data center cooling procurement channels. Operators without documented refrigerant management systems face exclusion from hyperscale vendor pools, while certified contractors command premium positioning for SEAI retrofit grant projects.
Pricing Analysis
Long-term offtake contracts dominate hyperscale procurement, with Microsoft, Amazon, and Google negotiating multi-year supply agreements that lock capacity and compress distributor margins. Price differentiation hinges on SEAI energy efficiency certification tier and geographic service density—Vertiv's rapid-response technician pools in Dublin and Cork justify 15-20% premiums over standard contractor rates. Cost compression in air-cooled retrofits is intensifying because legacy facilities compete for scarce refrigeration engineering talent. Colocation providers show highest price sensitivity due to multi-tenant SLA cost allocation pressures, while hyperscale operators prioritize thermal performance over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standardized chiller components, but strategic stockpiling of copper and aluminum feedstock buffers commodity volatility for liquid cooling manifold fabrication. Manufacturing concentrates in Germany, the Netherlands, and China—Schneider Electric leverages its continental European footprint to anchor Irish hyperscale builds, while Asian suppliers feed modular equipment for edge deployments. Raw material dependencies center on copper tubing, aluminum heat exchangers, and synthetic dielectric fluids. Single-source vulnerability runs through specialized refrigeration compressor suppliers serving the Greater Dublin Area. Distribution runs through MEP contractors and systems integrators for colocation and enterprise segments, with direct manufacturer relationships capturing hyperscale volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the retrofit upgrade cycle as SEAI grant programs unlock capital at legacy facilities unable to source direct hyperscale procurement channels. Demand-side shift toward heat reuse contracting creates specialist niches for district heating integration engineering.
For Market Incumbents: Secure refrigerant recovery and reclamation capabilities ahead of EU F-Gas phase-down deadlines to defend service contract renewals at legacy Cork and Dublin facilities. Deepen backward integration into heat exchanger manufacturing to offset copper price volatility squeezing contractor margins. Capacity expansion in Cork's Ringaskiddy industrial estate captures development redirecting from grid-constrained Dublin.
For New Entrants and Emerging Players: Commissioning engineer scarcity at hyperscale deployment timelines represents the most penetrable service gap—target compressed acceptance testing windows with specialized thermal performance verification offerings. Little Island's emerging immersion cooling testbeds offer white-space entry for dielectric fluid system integrators unburdened by legacy air-cooled installed bases. Go-to-market through SEAI grant program advisory relationships unlocks colocation facility access.
For Investors and Strategic Acquirers: EU Energy Efficiency Directive enforcement reshapes the acquisition landscape toward energy performance contracting specialists with documented PUE improvement track records. Long-term viability favors climate-calibrated equipment providers optimizing for Ireland's maritime free cooling economics over generic HVAC manufacturers. Target acquisition archetype: regional commissioning engineering firms with EPA emissions licensing compliance infrastructure. Signal to watch is EirGrid interconnection queue clearance rates triggering hyperscale construction restarts.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat Reuse Engineering Capability Buildout | Enables Cork municipal heating network supply contracts and circular economy positioning. |
| Refrigerant Recovery Infrastructure Investment | Secures EPA compliance service contracts ahead of F-Gas phase-down enforcement. |
| Commissioning Engineer Training Pipeline | Addresses talent scarcity compressing hyperscale deployment acceptance timelines. |
| Modular Cooling Product Line Expansion | Captures retrofit demand from space-constrained legacy Dublin facilities. |
| District Heating Authority Partnership | Locks long-term thermal offtake agreements validating immersion cooling economics. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with data center operators, MEP contractors, and refrigeration engineering specialists, combined with secondary validation through EirGrid interconnection queue disclosures, EPA industrial emissions licensing records, and SEAI grant program documentation. Stakeholder interviews encompassed facilities directors at hyperscale campuses, commissioning engineers, colocation procurement leads, and district heating authority planners. Secondary sources included EU F-Gas Regulation implementation reports, customs data on cooling equipment imports, and utility grid constraint filings. Bottom-up equipment procurement flow analysis triangulated against top-down market sizing from construction pipeline tracking.
Across the analysis window, projections model liquid cooling adoption curves, SEAI grant program disbursement rates, and hyperscale capex commitment patterns. Segmentation dimensions span product type, cooling technology tier, end-user procurement authority, and installation maturity. CAGRs derive from equipment shipment volumes correlated with EirGrid connection approval timelines. Industry-specific inputs include maritime climate free cooling hour calculations and refrigerant phase-down compliance cost trajectories.
Forecasts assume regulatory continuity in EU Energy Efficiency Directive enforcement and EPA emissions licensing frameworks; material policy shifts would require re-modeling. Commodity price volatility in copper and aluminum, EirGrid interconnection queue delays beyond current 36-48 month baselines, and unexpected F-Gas Regulation acceleration represent primary revision triggers. Revision becomes warranted when hyperscale deployment cancellations cross thresholds that collapse equipment order backlogs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market