
 Adiabatic Dry Cooler Market | 2026-2036
Adiabatic Dry Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Adiabatic Dry Cooler Market Insights
ISO 5149 certification for refrigerating systems and heat pumps is rotating the competitive threshold for adiabatic dry cooler suppliers seeking European market access. Baltimore Aircoil Company leverages its extensive cooling tower heritage to anchor positions in hybrid adiabatic configurations. Guntner GmbH & Co. KG sustains engineering leadership through deep specialization in aluminum micro-channel heat exchangers for industrial refrigeration. Kelvion Holding GmbH competes on manufacturing scale across its European and Asian production footprints.
An adiabatic dry cooler is a heat rejection device that pre-cools ambient air through evaporative wetting of an external pad or spray system before passing it over finned coils, achieving fluid outlet temperatures below dry-bulb conditions without direct water contact with the process loop. Typical units operate with adiabatic saturation efficiencies of 80-95% and design pressures up to 40 bar for industrial refrigerant circuits, serving primarily to eliminate water consumption in cooling applications while maintaining thermal performance comparable to evaporative cooling towers. Air-cooled and hybrid product types dominate current shipment volumes, though dual-circuit architectures are capturing margin pools in data center applications where redundant thermal paths are mandatory. Micro-channel technology leads the technology dimension on coil compactness and refrigerant charge reduction, while indirect cooling configurations are expanding fastest among healthcare end users seeking to isolate process fluids from ambient air.
The EPA enforces refrigerant management requirements under Section 608 of the Clean Air Act, directly shaping product design rules for adiabatic dry coolers deployed in US commercial HVAC. Ecodesign regulations under the EU framework mandate minimum seasonal energy performance ratios that favor adiabatic pre-cooling stages in dry cooler selections across member states. India's BIS certification scheme for refrigeration and air-conditioning equipment is tightening test protocols that importers must satisfy for market entry. Stakeholders must monitor how fragmented national refrigerant-phaseout schedules reshape equipment replacement cycles and supplier qualification burdens across their installed bases.
Market Dynamics
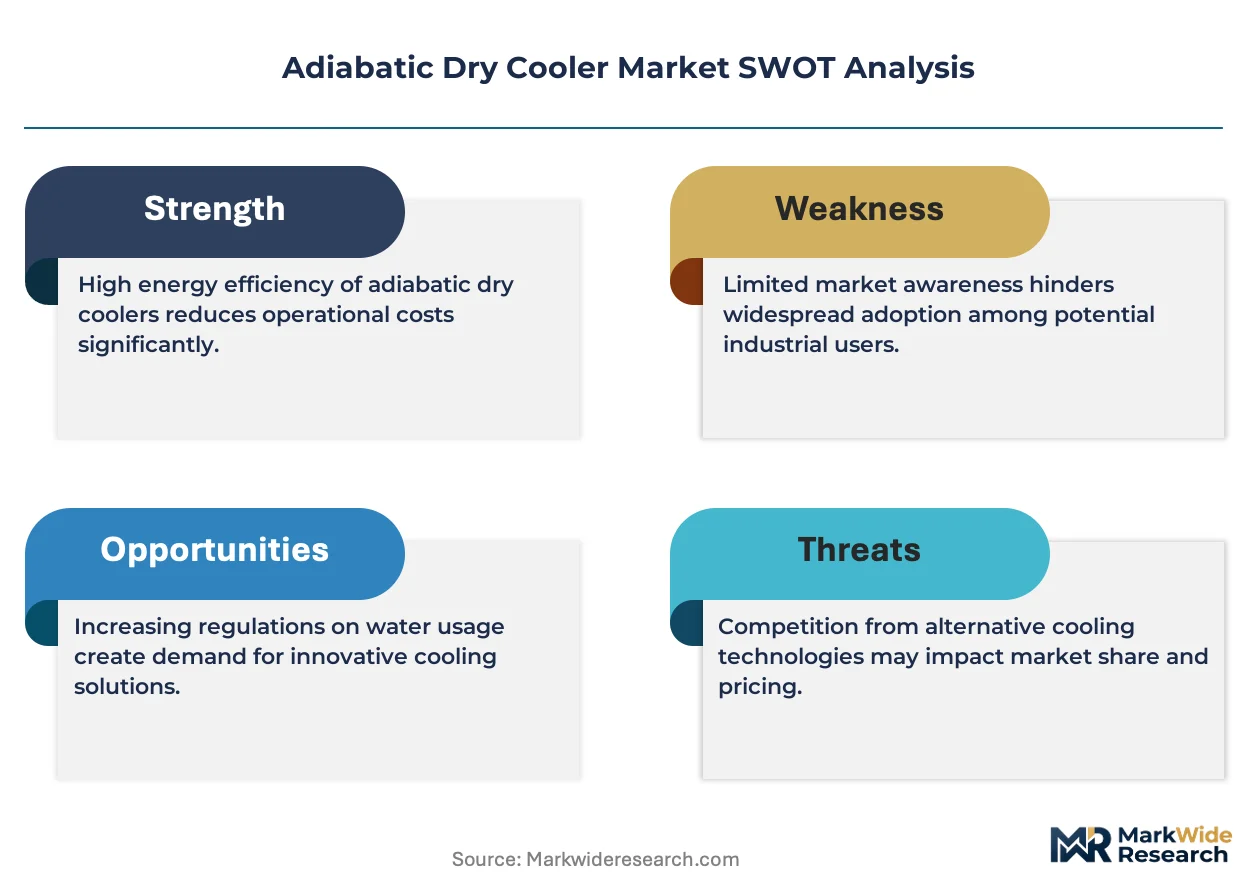
Water-use restrictions in drought-prone regions are compressing specification cycles for data center cooling infrastructure, forcing operators to abandon evaporative towers in favor of adiabatic dry architectures that eliminate direct water contact with process loops.
Growth Catalysts
- EU F-Gas Regulation:Accelerated refrigerant-phaseout timelines favor dry cooling systems that minimize synthetic refrigerant dependence, particularly in German industrial clusters where retrofit demand concentrates.
- Hyperscale data center expansion:Operators across Arizona, California, and Singapore face municipal water withdrawal limits that mandate adiabatic pre-cooling stages to maintain thermal rejection capacity.
- Aluminum micro-channel heat exchangers:Coil compactness and refrigerant charge reduction enable footprint-constrained installations in urban colocation facilities.
Market Restraints
- Aluminum price volatility:Micro-channel coil fabrication depends on aluminum alloy supply chains concentrated in Chinese smelting capacity, exposing margin structures to input cost swings.
- Adiabatic saturation efficiency ceilings:Physical limits of evaporative pre-cooling pad performance cap thermal rejection capacity in extreme wet-bulb conditions, constraining deployment in Gulf Coast and Southeast Asian climates.
- Dual-circuit certification burden:Redundant thermal path architectures for healthcare and nuclear applications require parallel compliance with ASME and ISO 5149 protocols, extending qualification timelines.
Strategic Opportunities
- India BIS certification tightening:Stricter test protocols for imported refrigeration equipment create first-mover advantage for suppliers establishing domestic assembly partnerships ahead of full enforcement.
- Hybrid adiabatic-chiller integration:Convergence of dry cooler pre-cooling with magnetic bearing compressor technology opens efficiency gains in pharmaceutical cleanroom applications.
- Healthcare isolation requirements:Indirect cooling configurations that separate process fluids from ambient air address infection control mandates in hospital central plant retrofits.
Industry Challenges
- Refrigerant handling certification gaps:EPA Section 608 technician qualification requirements lag deployment of low-GWP alternatives, creating field service bottlenecks for adiabatic systems using A2L-class refrigerants.
- Legacy chiller integration complexity:Retrofit projects must reconcile adiabatic dry cooler control logic with existing building automation protocols, particularly in 1990s-era industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adiabatic Dry Cooler Market |
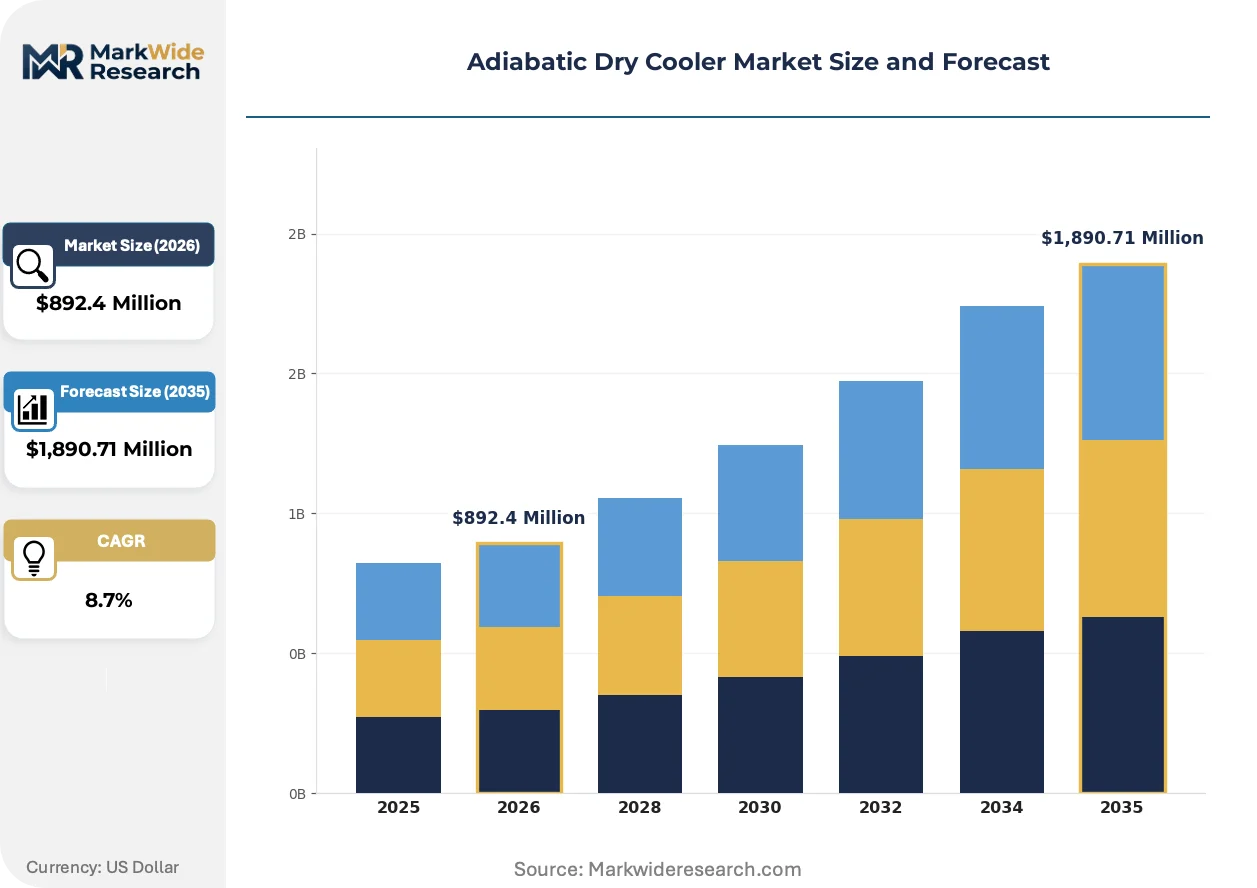
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Hybrid, Dual-Circuit Application: HVAC Systems, Industrial Processes, Data Centers, Refrigeration End User: Manufacturing, Commercial, Healthcare, Agriculture Technology: Micro-channel, Coaxial, Direct Expansion, Indirect Cooling |
| Companies Covered | Baltimore Aircoil Company, EVAPCO Inc., SPX Cooling Technologies, Guntner GmbH & Co. KG, Kelvion Holding GmbH, Thermax Limited, Alfa Laval, MITA Group, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adiabatic Dry Cooler Market Trends and Innovations
Adiabatic dry cooler architectures are bifurcating between compact micro-channel designs for space-constrained urban deployments and large-format hybrid systems for hyperscale campuses, with control intelligence becoming the primary differentiation vector.
Micro-channel aluminum coil technology is fragmenting supplier tiers as proprietary fin geometries and brazing processes lock in performance advantages. Data center operators in Frankfurt and Amsterdam specify these configurations to meet Ecodesign seasonal energy performance minimums while reducing refrigerant inventory. The technology is fragmenting procurement patterns, with premium-tier buyers demanding coil-specific warranties separate from unit-level coverage.
EPA enforcement of refrigerant management under Section 608 of the Clean Air Act is tightening leak detection and repair mandates for commercial HVAC systems. Equipment specifiers now prioritize adiabatic dry coolers with hermetically sealed circuits and minimal connection points to reduce compliance exposure. US supermarket chains and cold storage operators are responding by consolidating thermal infrastructure replacement cycles to align with phasedown schedules.
Specification authority is migrating from mechanical contractors to sustainability officers within enterprise end-users, compressing traditional distribution channels. Engineering-procurement-construction firms now bundle adiabatic dry cooler selection with water-neutral certification consulting for California and Singapore data center projects. This shift is most visible in hyperscale procurement, where direct OEM relationships displace wholesale HVAC distribution for campus-scale deployments.
Adiabatic Dry Cooler Market Segmentation
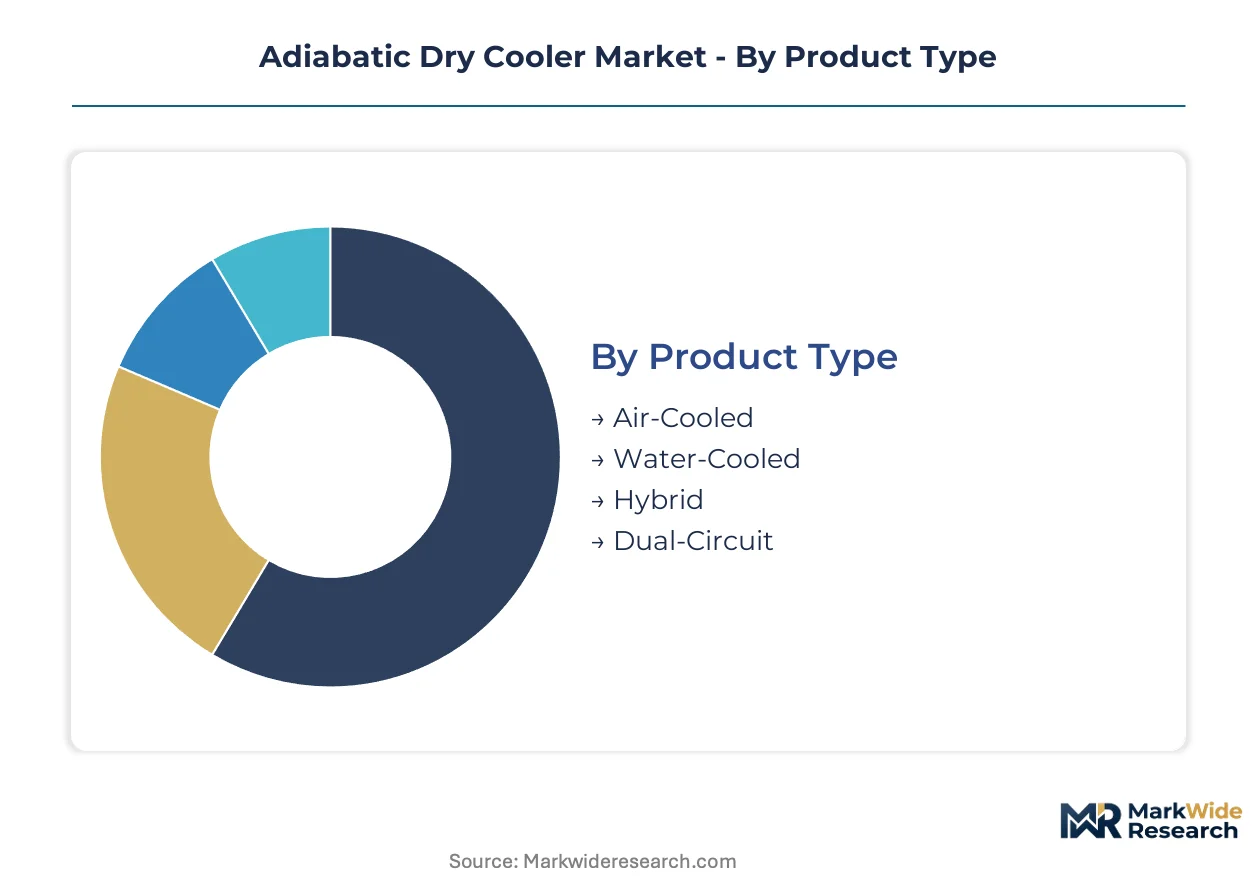
Adiabatic dry cooler procurement patterns diverge sharply across installation contexts, with regulatory pressure on refrigerant phaseout and water-use restrictions reshaping specification priorities. Manufacturers must align coil technologies and control architectures to distinct compliance burdens and thermal performance requirements.
Product Type:
EU F-Gas Regulation enforcement creates divergent qualification thresholds across product architectures, with refrigerant charge limits and leak-tightness standards favoring certain configurations over others.
- Air-Cooled:Conventional finned-coil designs operate without evaporative pre-cooling stages, serving legacy industrial refrigeration retrofits where water access remains unrestricted. Demand concentrates in Eastern European manufacturing clusters where Ecodesign compliance costs deter adiabatic upgrades.
- Hybrid:Integrated evaporative pre-cooling pads enable sub-dry-bulb fluid temperatures during peak ambient conditions. Data center operators in Arizona and Singapore specify these units to satisfy municipal water withdrawal limits while maintaining thermal rejection capacity.
- Water-Cooled:Closed-circuit designs retain minimal water inventory for indirect heat exchange, bridging regulatory gaps in jurisdictions with transitional water-use codes. These configurations see procurement from pharmaceutical cleanroom operators seeking redundant thermal paths.
- Dual-Circuit:Redundant refrigerant loops satisfy ASME and ISO 5149 parallel certification requirements for healthcare and nuclear applications. Extended qualification timelines constrain deployment velocity despite premium pricing tolerance.
Hybrid configurations handle the majority of new specification activity; dual-circuit architectures are expanding most quickly on share as critical facility standards tighten.
Application:
Cost tier differentiation separates commodity HVAC replacements from mission-critical infrastructure where thermal failure carries operational or regulatory penalties.
- Data Centers:Hyperscale and colocation operators face simultaneous pressure from EPA refrigerant management mandates and drought-driven water-use restrictions. Frankfurt and Amsterdam facilities specify micro-channel adiabatic systems to meet Ecodesign seasonal energy performance minimums.
- Industrial Processes:Chemical and petrochemical plants deploy large-format hybrid coolers for process heat rejection, with aluminum coil specifications driven by footprint constraints in brownfield expansions.
- HVAC Systems:Commercial building retrofits favor air-cooled architectures where existing chiller infrastructure limits integration complexity. US supermarket chains consolidate replacement cycles to align with AIM Act phasedown schedules.
- Refrigeration:Cold storage and food processing facilities prioritize hermetically sealed circuits with minimal connection points to reduce EPA Section 608 compliance exposure.
Data center applications command premium pricing tiers; industrial process installations represent the steepest expansion trajectory as German clusters accelerate retrofit timelines.
End User:
Customer type determines procurement authority migration patterns, with sustainability officers displacing mechanical contractors in enterprise specification decisions.
- Commercial:Office and retail portfolios balance first-cost sensitivity against escalating water tariffs in drought-prone municipalities. Engineering-procurement-construction firms bundle adiabatic selection with water-neutral certification consulting for California projects.
- Healthcare:Hospital central plants require indirect cooling configurations that isolate process fluids from ambient air to satisfy infection control mandates. Procurement cycles extend to accommodate parallel ASME and ISO 5149 protocol compliance.
- Manufacturing:Automotive and electronics production facilities specify compact micro-channel designs for space-constrained urban deployments where refrigerant charge reduction delivers regulatory advantage.
- Agriculture:Controlled-environment agriculture operators in water-stressed regions adopt adiabatic pre-cooling to maintain greenhouse climate control without evaporative tower water consumption.
Commercial end users generate the highest shipment volumes; healthcare specifications are climbing fastest as hospital retrofit mandates proliferate.
Technology:
Supply concentration in Chinese aluminum smelting capacity shapes margin structures across coil fabrication technologies, with proprietary fin geometries locking in performance differentiation.
- Micro-channel:Aluminum multi-port extrusions achieve coil compactness and refrigerant charge reduction through enhanced surface-area-to-volume ratios. Urban colocation facilities in Frankfurt specify these configurations to meet footprint constraints.
- Indirect Cooling:Heat exchanger architectures that separate process fluids from ambient air address healthcare isolation requirements and refrigerant containment priorities. These systems gain specification share in hospital central plant retrofits.
- Coaxial:Tube-in-tube designs persist in legacy industrial refrigeration where established service infrastructure and technician familiarity delay technology transition.
- Direct Expansion:Refrigerant-to-air heat exchange without intermediate fluid loops maintains deployment in cost-sensitive commercial HVAC where first-cost optimization outweighs efficiency premiums.
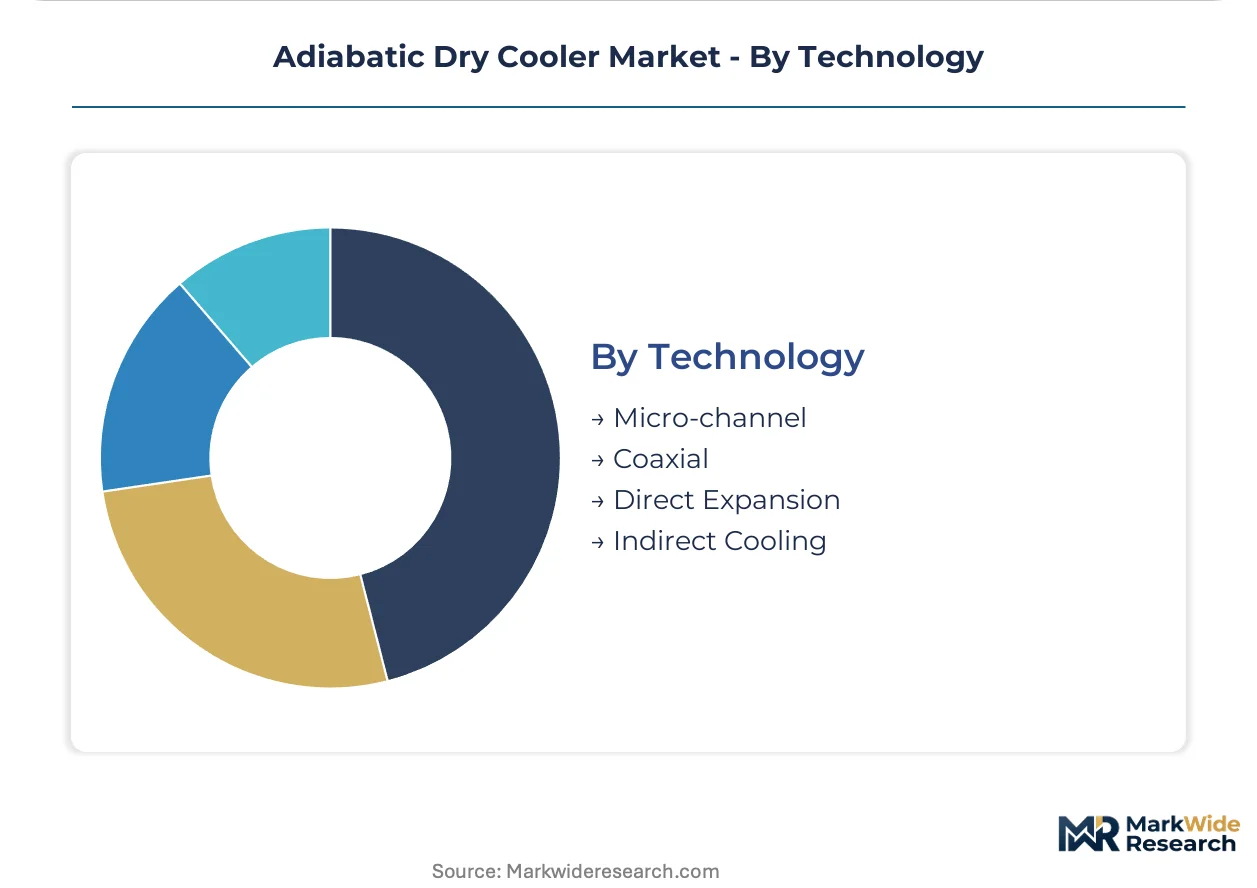
Micro-channel technology dominates current procurement volume; indirect cooling configurations are expanding most rapidly on specification share as healthcare and data center isolation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation enforcement and municipal water withdrawal limits are reshaping procurement patterns across industrial clusters and data center corridors. National refrigerant-phaseout schedules and building code stringency now determine specification authority in each market.
United States
Data center operators in Arizona and California face municipal water restrictions that mandate adiabatic pre-cooling stages for thermal rejection capacity. EPA Section 608 enforcement under the Clean Air Act tightens leak detection mandates for commercial HVAC systems. Phoenix and Las Vegas hyperscale campuses specify hybrid adiabatic configurations to satisfy drought-driven codes.
Germany
Industrial refrigeration retrofits concentrate in chemical and automotive clusters where Ecodesign seasonal energy performance minimums favor adiabatic upgrades. The EU F-Gas Regulation accelerates synthetic refrigerant phaseout timelines for dry cooling architectures. Frankfurt and Düsseldorf data center operators specify micro-channel systems to meet footprint and efficiency thresholds.
India
Commercial building portfolios in water-stressed metros drive specification of air-cooled adiabatic units to avoid evaporative tower consumption. BIS certification tightening for imported refrigeration equipment raises qualification barriers for market entry. Mumbai and Bangalore industrial zones see procurement consolidation as domestic assembly partnerships form ahead of full enforcement.
Singapore
Hyperscale and colocation facilities face strict water-neutrality mandates that eliminate traditional cooling tower architectures. The country's national water agency imposes withdrawal limits that compress specification cycles toward adiabatic dry coolers. Jurong and Changi data center clusters specify hybrid systems with redundant thermal paths to maintain rejection capacity under tropical wet-bulb conditions.
China
Dual carbon goals and provincial water-use quotas accelerate retrofit demand in eastern manufacturing belts. GB standards for refrigerating systems and heat pumps tighten test protocols that importers must satisfy. Yangtze River Delta electronics and pharmaceutical facilities specify compact micro-channel designs for space-constrained urban deployments.
Adiabatic Dry Cooler Market Competitive Landscape
Player mix skews toward diversified thermal infrastructure suppliers with cooling tower heritage and specialized aluminum heat exchanger fabricators. Market structure concentrates around engineering-led mid-cap specialists and scale-driven diversified industrials. Two strategic archetypes dominate: heritage cooling tower manufacturers extending into hybrid adiabatic configurations, and dedicated heat exchanger specialists commanding premium positioning through proprietary coil geometries. Competitive moves center on geographic expansion through domestic assembly partnerships and technology licensing for micro-channel fabrication processes.
Among German engineering specialists, Guntner GmbH & Co. KG and Kelvion Holding GmbH exemplify the heat exchanger-fabricator archetype with deep specialization in aluminum micro-channel systems. Baltimore Aircoil Company represents the heritage cooling tower manufacturer extending into hybrid adiabatic configurations. These three anchors demonstrate how coil technology ownership and cooling tower legacy respectively define competitive positioning in procurement cycles driven by Ecodesign compliance and water-use restrictions.
| Leading Market Players |
|---|
| Baltimore Aircoil Company |
| EVAPCO Inc. |
| SPX Cooling Technologies |
| Guntner GmbH & Co. KG |
| Kelvion Holding GmbH |
| Thermax Limited |
| Alfa Laval |
| MITA Group |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for aluminum micro-channel coils lock in supply access for European heat exchanger fabricators while capping price visibility against LME volatility. These arrangements tether procurement costs to Chinese smelting output, compressing margin buffers when alloy premiums spike.
Pricing Analysis
Certification level (ISO 5149/CE-grade) creates the primary spread between premium and standard tiers. Project-based pricing dominates large-format hybrid installations for hyperscale data centers, while per-unit transactional structures serve commercial HVAC retrofits. Pricing pressure stems from aluminum alloy cost volatility concentrated in Chinese smelting capacity. Commercial building portfolios exhibit highest price sensitivity; healthcare and nuclear applications tolerate premium tiers for dual-circuit ASME compliance.
Supply Chain Analysis
Strait of Malacca transit routes concentrate aluminum alloy feedstock movement from Chinese smelters to Southeast Asian coil fabrication facilities. Micro-channel coil production draws from aluminum extrusion inputs, brazing alloys, and proprietary fin geometries. Single-source vulnerability runs through Yangtze River Delta smelting complexes exposed to provincial emissions quotas. Distribution runs through engineering-procurement-construction firms bundling equipment with water-neutral certification consulting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adiabatic dry cooler market functions as a defensive-moat industry where regulatory entrenchment creates durable switching costs. EU F-Gas phaseout schedules and municipal water-use codes lock in specification authority for qualified suppliers.
For Market Incumbents: Compound engineering leadership through captive micro-channel coil fabrication and ISO 5149 certification depth. Aluminum price volatility threatens margin structures; backward integration into alloy sourcing or long-term offtake agreements with Yangtze River Delta smelters defends cost position. Channel control via direct OEM relationships with hyperscale operators displaces wholesale HVAC distribution. For New Entrants and Emerging Players: Differentiate on healthcare isolation configurations addressing hospital central plant retrofits. India's BIS certification tightening creates white-space for domestic assembly partnerships ahead of full enforcement. Target controlled-environment agriculture operators in water-stressed regions with compact air-cooled units. Go-to-market through engineering-procurement-construction bundling accelerates specification access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heat exchanger specialists with proprietary coil geometries and aftermarket service contracts. Long-term viability favors suppliers with regulatory entrenchment across multiple jurisdictions. Acquisition target archetype: mid-cap aluminum micro-channel fabricators with ISO 5149 depth and healthcare certification track records. Watch EPA Section 608 enforcement intensity as inflection indicator for US replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Coil Fabrication | Captive micro-channel production insulates margin structures from Chinese alloy volatility. |
| ISO 5149 Certification Investment | European market access requires rotating competitive threshold for refrigerating systems compliance. |
| Domestic Assembly Partnership Formation | India BIS tightening rewards first-mover localization ahead of import protocol enforcement. |
| Healthcare Isolation Configuration Development | Indirect cooling architectures address hospital infection control mandates in central plant retrofits. |
| Direct OEM Relationship Cultivation | Hyperscale data center procurement bypasses wholesale HVAC channels for campus-scale deployments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with thermal infrastructure procurement directors, data center sustainability officers, and hospital facility engineers; and secondary validation against EU Ecodesign compliance databases, EPA Section 608 enforcement records, and aluminum trade flow customs data. Bottom-up shipment triangulation across product architectures converged with top-down market sizing from refrigeration equipment production statistics.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, application vertical, end-user category, and coil technology dimension. CAGRs derived from regression analysis of historical replacement cycles, regulatory phaseout schedules, and water-use restriction intensity indices. Forecast inputs incorporated EU F-Gas quota allocation trajectories and hyperscale data center capex disclosure patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or aluminum supply stability would require recalibration. Forecasts reflect documented assumptions regarding refrigerant-phaseout adherence and municipal water code expansion. Practitioners should keep alternative scenarios live as drought-driven specification mandates and Chinese smelting capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market