
 Mexico Data Center Cooling Market | 2026-2036
Mexico Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Data Center Cooling Market Insights
Aftermarket service revenue is tilting toward thermal optimization contracts as operators extend equipment lifecycles. Schneider Electric SE leverages its integrated building management platform to anchor long-term service agreements across Mexican facilities. Vertiv Group Corp competes through localized manufacturing presence, while Stulz GmbH specializes in precision air conditioning for high-density compute environments.
Data center cooling encompasses mechanical and thermal management systems that maintain server inlet temperatures between 18°C and 27°C while rejecting heat to external sinks, primarily through vapor-compression cycles, chilled water loops, or dielectric fluid immersion. These systems prevent thermal throttling, extend semiconductor lifespan, and enable sustained power densities above 15 kW per rack. Air cooling still dominates installed base economics, though liquid cooling is capturing the fastest expansion as GPU clusters proliferate. Hyperscale data centers command the largest absolute spend, while retrofit projects represent a concentrated margin pool where existing facilities upgrade legacy infrastructure.
CRE's energy efficiency standards and PROFECO labeling requirements shape equipment procurement decisions, while NOM-001-SEDE electrical norms govern installation safety and thermal system integration. CFE's industrial tariff structures create operating expenditure pressure that favors high-efficiency chillers and free-cooling architectures. Stakeholders must weigh capital deployment timing against evolving carbon reporting obligations and the pace of direct-to-chip cooling adoption.
Market Dynamics
Direct-to-chip liquid cooling architectures are compressing traditional chilled water infrastructure economics as AI training clusters exceed 50 kW per rack across Querétaro and Mexico City facilities.
Growth Catalysts
- NOM-001-SEDE electrical norms:These safety mandates accelerate thermal system upgrades by requiring integrated arc-fault protection and redundant cooling circuits in new data center construction.
- Hyperscale cloud expansion:Microsoft, Google, and Amazon Web Services are commissioning dedicated AI training campuses in central Mexico, mandating precision cooling with sub-1°C temperature variance.
- CFE industrial tariff restructuring:Time-of-use electricity pricing creates operating expenditure pressure that rewards facilities deploying free-cooling economizers during temperate highland nights.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger fabrication costs swing with London Metal Exchange commodity indices, compressing chiller OEM margins on fixed-price municipal contracts.
- Single-source dependence for precision valves:Proportional refrigerant flow controls concentrate with German and Japanese suppliers, exposing Mexican integrators to 12-16 week lead time extensions.
- Dielectric fluid supply concentration:Immersion cooling deployments rely on fluorinated chemistries produced by three global chemical conglomerates, limiting price negotiation leverage for domestic operators.
Strategic Opportunities
- Monterrey industrial corridor penetration:Manufacturing-driven edge computing demand remains underserved by precision cooling specialists, creating first-mover advantage for localized service networks.
- PROFECO energy labeling alignment:Premium efficiency equipment certification opens preferential procurement channels with state-owned enterprises and federal data consolidation projects.
- Refrigerant-natural gas hybrid systems:Absorption chillers paired with stranded gas assets offer carbon accounting advantages for operators near Pemex pipeline infrastructure.
Industry Challenges
- Thermal-fluid engineering specialization:Mexican technical institutes produce fewer than 200 graduates annually with direct-to-chip cooling design competency, forcing employers to import talent from Spain and Argentina.
- Legacy air-cooled retrofit integration:Facilities built 2015-2019 face structural floor loading limits and piping corridor constraints that complicate liquid cooling infrastructure grafting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Data Center Cooling Market |
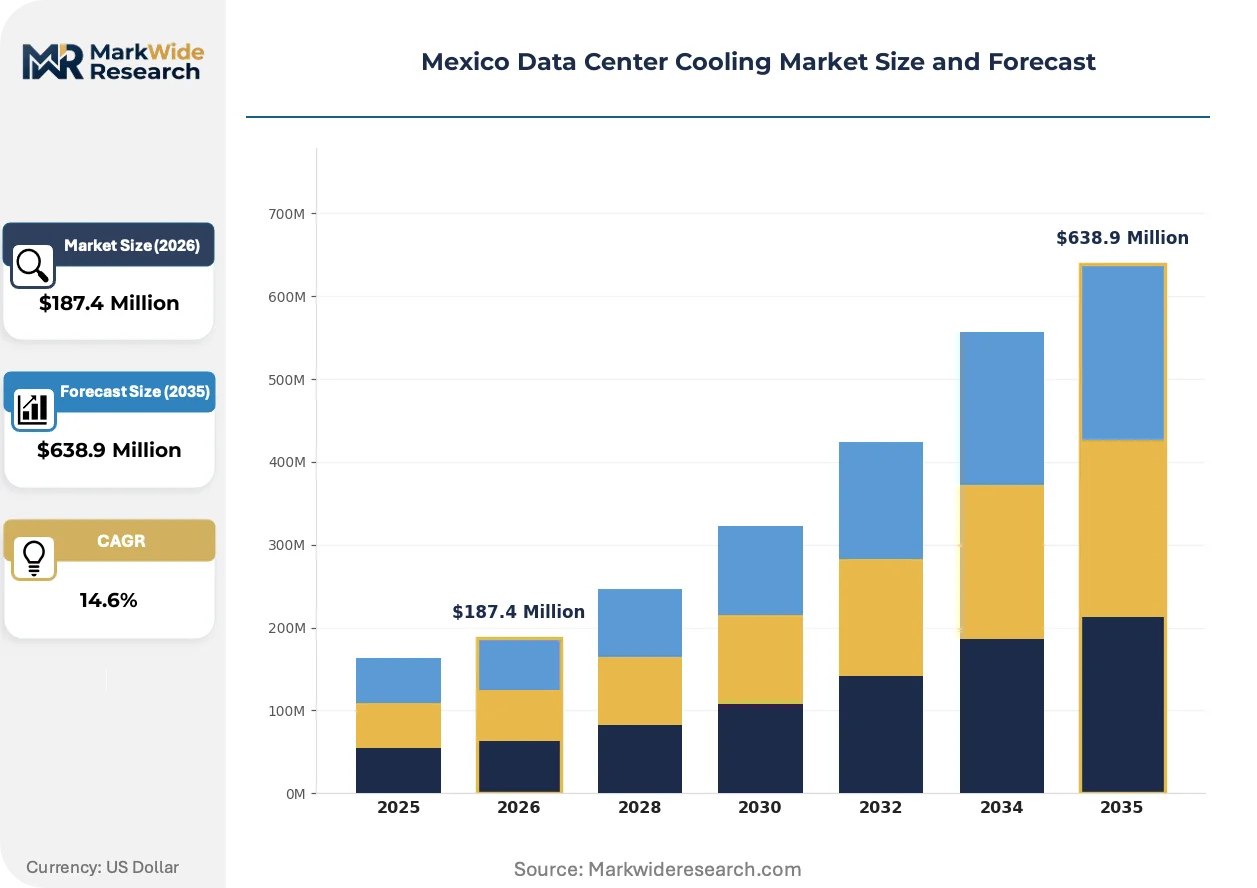
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Air Conditioners, Cooling Towers, In-Row Cooling Technology: Liquid Cooling, Air Cooling, Evaporative Cooling, Immersion Cooling End User: Colocation Providers, Enterprises, Cloud Service Providers, Hyperscale Data Centers Installation: New Installations, Retrofit Projects, Modular Installations, Expansion Projects |
| Companies Covered | Stulz GmbH, Rittal GMBH & Co. KG, Schneider Electric SE, Vertiv Group Corp, Mitsubishi Electric Corporation, Daikin Industries Limited, Johnson Controls International PLC, Munters, Airedale International Air Conditioning Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Data Center Cooling Market Trends and Innovations
Cooling technology trajectories in Mexican data centers center on heat rejection efficiency, refrigerant chemistry transitions, and procurement model compression that favors operational expenditure structures over capital-intensive ownership.
Single-phase immersion cooling using engineered fluorocarbon dielectrics is collapsing the distinction between facility infrastructure and IT equipment thermal management. Hyperscale operators in Querétaro are piloting tank-based systems at 100 kW-plus densities, eliminating mechanical refrigeration loops entirely. This collapse of traditional HVAC boundaries enables modular data hall construction with 40% reduced mechanical footprint.
CRE's updated energy efficiency standards for non-residential buildings now mandate real-time power usage effectiveness monitoring and annual thermal performance disclosure for facilities exceeding 500 kW connected load. The industrial consequence is accelerated replacement of fixed-speed compressors with variable-frequency drive chillers. Colocation providers in Mexico City's Tlalnepantla cluster are responding by consolidating cooling plant retrofits to meet 2027 compliance deadlines.
Aftermarket thermal optimization contracts are unbundling from traditional equipment maintenance agreements. Facility operators now procure continuous commissioning and predictive analytics as separate line items from cooling OEMs or third-party energy service companies. This unbundling is most visible among financial services data centers in Guadalajara, where Santander and BBVA facilities have shifted to performance-guaranteed thermal management with penalty clauses for temperature excursion events.
Mexico Data Center Cooling Market Segmentation
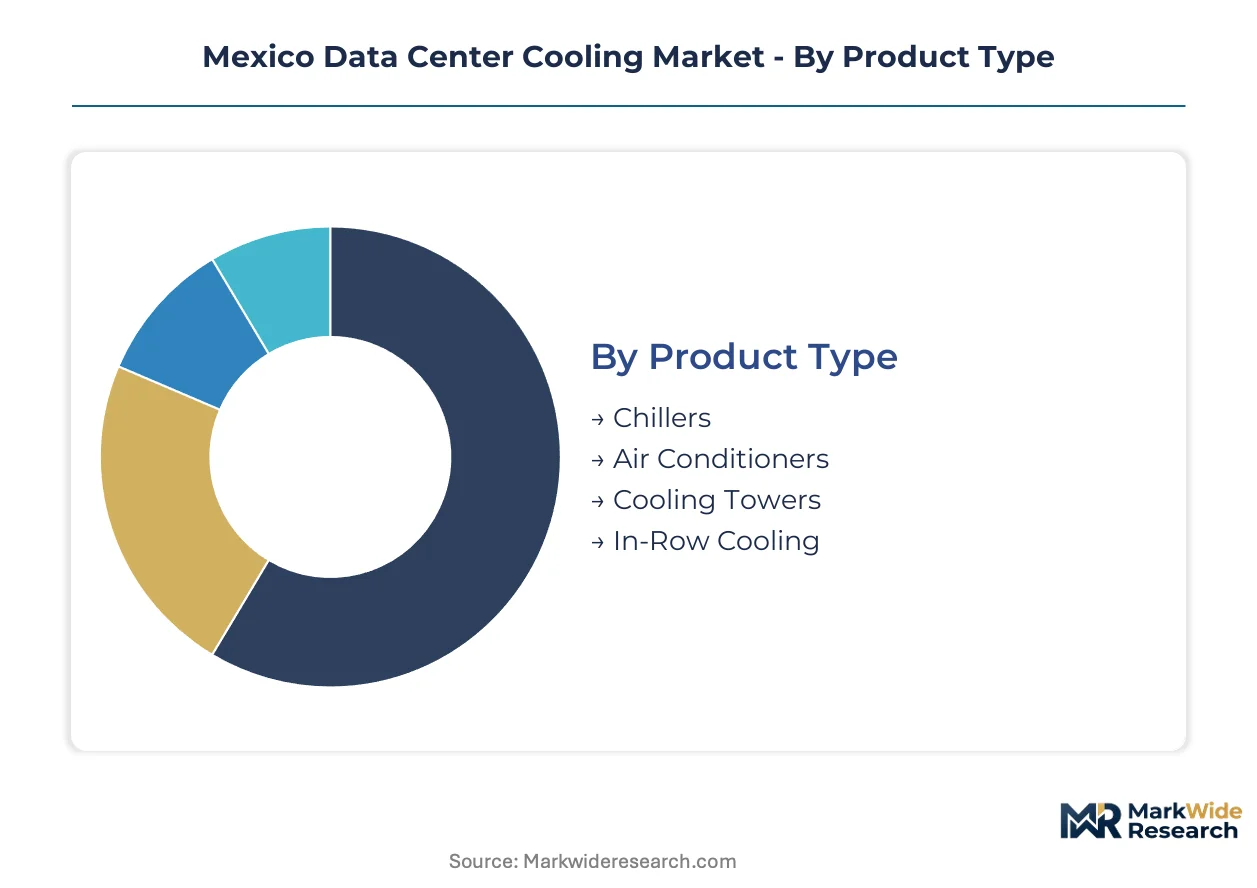
Segmentation reveals how cooling procurement diverges across infrastructure vintages and compute densities in Mexico. Each dimension exposes distinct margin pools, from legacy air-cooled retrofits in Mexico City to liquid-cooled greenfield campuses in Querétaro.
Product Type:
Cost tier stratification separates capital-intensive central plant equipment from distributed precision cooling at the rack level.
- Chillers:Centralized vapor-compression or absorption systems generating chilled water for secondary distribution loops. Demand concentrates in hyperscale campuses across Querétaro's digital corridor where CFE industrial tariffs reward high-efficiency centrifugal designs with variable-frequency drives.
- Air Conditioners:Direct-expansion or chilled-water units delivering conditioned air to raised-floor plenums. Legacy enterprise facilities in Mexico City's Tlalnepantla cluster drive replacement demand as CRE energy efficiency standards mandate real-time power usage effectiveness monitoring.
- Cooling Towers:Open-circuit or closed-circuit heat rejection devices exploiting central Mexico's highland diurnal temperature swings for free-cooling economization.
- In-Row Cooling:Close-coupled precision units mounted directly adjacent to server racks, eliminating air mixing losses. Edge computing deployments in Guadalajara's financial district favor this configuration for density without raised-floor infrastructure.
Chillers command the established base. The steepest expansion runs through In-Row Cooling.
Technology:
Application heat density determines thermal architecture selection, with compute intensity now the dominant selector.
- Liquid Cooling:Direct-to-chip cold plates or rear-door heat exchangers circulating water or dielectric fluid to capture processor heat at source. AI training clusters exceeding 50 kW per rack across Querétaro and Mexico City facilities are compressing traditional chilled water economics.
- Air Cooling:Conventional raised-floor distribution with computer room air handlers or air conditioning units. Enterprise colocation in Monterrey's emerging corridor maintains this architecture for sub-15 kW densities.
- Evaporative Cooling:Adiabatic or direct evaporative systems leveraging Mexico's arid highland climates for water-side economization during temperate seasons.
- Immersion Cooling:Single-phase or two-phase dielectric fluid baths submerging entire server assemblies. Hyperscale pilots at 100 kW-plus densities are collapsing the distinction between facility infrastructure and IT equipment thermal management.
Air Cooling retains the installed base majority. Liquid Cooling is climbing the fastest as GPU clusters proliferate.
End User:
Customer type segmentation exposes divergent procurement sophistication, from standardized colocation contracts to bespoke hyperscale engineering specifications.
- Colocation Providers:Multi-tenant facility operators selling space, power, and cooling by the rack or cage. Mexico City and Querétaro operators are consolidating cooling plant retrofits to meet CRE's 2027 compliance deadlines for facilities exceeding 500 kW connected load.
- Enterprises:Single-occupant corporate data centers in banking, telecommunications, and manufacturing. BBVA and Santander facilities in Guadalajara have shifted to performance-guaranteed thermal management with penalty clauses for temperature excursion events.
- Cloud Service Providers:Regional cloud infrastructure operators serving Latin American workloads. These entities prioritize modular cooling architectures enabling rapid capacity scaling.
- Hyperscale Data Centers:Microsoft, Google, and Amazon Web Services commissioning dedicated AI training campuses. These facilities mandate precision cooling with sub-1°C temperature variance and sub-1.2 design power usage effectiveness.
Enterprises represent the largest absolute retrofit opportunity. Hyperscale Data Centers are gaining share fastest through greenfield capacity additions.
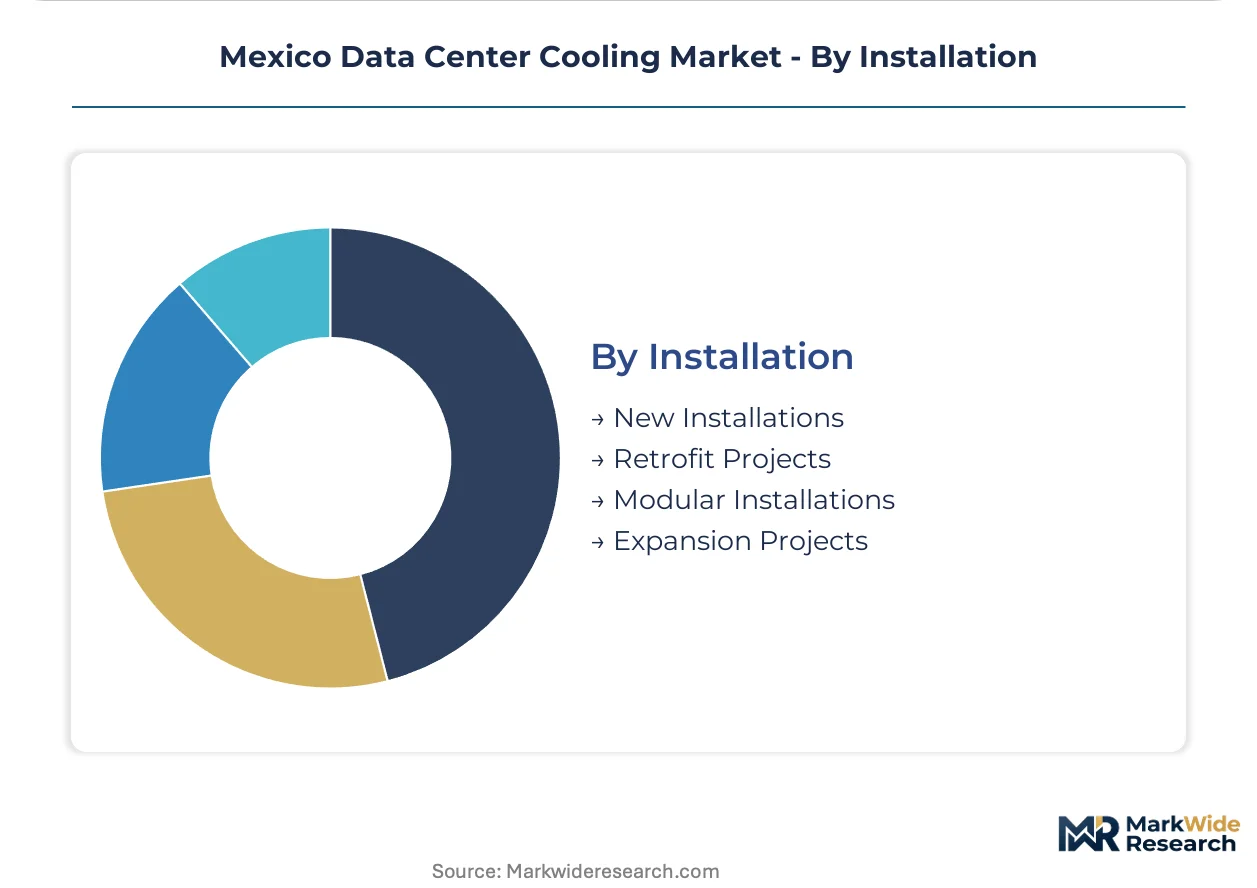
Installation:
Project maturity distinguishes greenfield engineering flexibility from the constraints of legacy infrastructure grafting.
- New Installations:Ground-up data center construction with integrated thermal design. Querétaro's digital corridor attracts these projects for fiber connectivity and CFE transmission capacity.
- Retrofit Projects:Cooling system replacement within operational facilities. Facilities built 2015-2019 face structural floor loading limits and piping corridor constraints complicating liquid cooling integration.
- Modular Installations:Prefabricated cooling plants or containment pods deployed as standardized building blocks. This approach accelerates deployment for cloud service providers with standardized specifications.
- Expansion Projects:Capacity additions to existing campuses requiring thermal infrastructure scaling. These engagements often unbundle aftermarket optimization from equipment procurement.
New Installations anchor vendor order books. Retrofit Projects concentrate margin through engineering complexity and continuous commissioning contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Mexican sub-regions. Querétaro hyperscale buyers absorb premium liquid cooling costs without procurement friction, while Monterrey industrial operators demand aggressive equipment financing to offset capital constraints.
Querétaro
Microsoft, Google, and Amazon Web Services anchor AI training campus construction with sub-1°C temperature variance specifications. CRE energy efficiency standards mandate real-time power usage effectiveness monitoring for facilities exceeding 500 kW connected load. The Santiago de Querétaro digital corridor concentrates liquid cooling deployment at 50-100 kW per rack densities.
Mexico City Metro
Colocation providers in Tlalnepantla and satellite municipalities drive retrofit demand for legacy air-cooled facilities built 2015-2019. NOM-001-SEDE electrical norms require integrated arc-fault protection and redundant cooling circuits in thermal system upgrades. CFE time-of-use industrial tariffs reward free-cooling economizer deployment during temperate highland nights.
Jalisco
Financial services data centers in Guadalajara unbundle aftermarket thermal optimization from traditional maintenance agreements. PROFECO energy labeling requirements shape equipment procurement for state-owned enterprise channels. Santander and BBVA facilities have shifted to performance-guaranteed thermal management with penalty clauses for temperature excursion events.
Nuevo León
Manufacturing-driven edge computing demand in Monterrey remains underserved by precision cooling specialists. CFE transmission capacity constraints create deployment bottlenecks for facilities requiring redundant substations. The Apodaca industrial corridor attracts first-mover localized service networks for modular cooling plant deployment.
Bajío Region
Automotive and aerospace supplier data consolidation projects generate mid-density cooling requirements between 15-30 kW per rack. PEMEX pipeline infrastructure proximity enables refrigerant-natural gas hybrid absorption chiller pilots. León and Irapuato municipalities host federal data center consolidation initiatives with preferential procurement for PROFECO-certified premium efficiency equipment.
Mexico Data Center Cooling Market Competitive Landscape
Integrated building management specialists and precision air conditioning fabricators split the market along project complexity lines. Market structure tilts toward consolidated vendor relationships in hyperscale greenfield projects, while fragmented local integrators capture retrofit margin pools. Two strategic archetypes dominate: European-headquartered multinationals with captive service networks, and Asia-Pacific equipment manufacturers competing through localized assembly partnerships. Competitive intensity centers on long-term thermal optimization contracts and refrigerant chemistry transition roadmaps.
Within the European-headquartered tier, Schneider Electric SE exemplifies integrated platform positioning through building management system anchoring, while Stulz GmbH occupies precision air conditioning specialization for high-density compute environments. Vertiv Group Corp represents manufacturing-integrated competitive positioning. These three entities collectively illustrate how vendor selection in Mexican data center cooling increasingly separates facility infrastructure procurement from continuous commissioning service relationships.
| Leading Market Players |
|---|
| Stulz GmbH |
| Rittal GMBH & Co. KG |
| Schneider Electric SE |
| Vertiv Group Corp |
| Mitsubishi Electric Corporation |
| Daikin Industries Limited |
| Johnson Controls International PLC |
| Munters |
| Airedale International Air Conditioning Ltd |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency for precision refrigerant valves from German and Japanese suppliers compresses both pricing tier spreads and supply chain resilience, forcing Mexican integrators to absorb extended lead times or pay expedite premiums while CFE tariff structures reshape total cost of ownership calculations across cooling architectures.
Pricing Analysis
Aftermarket thermal optimization contracts now drive lifetime value, with continuous commissioning and predictive analytics unbundled from traditional maintenance agreements. Pricing stratifies across premium efficiency certified equipment, standard variable-frequency drive configurations, and economy fixed-speed compressor replacements. Cost compression in chiller OEM margins intensifies because London Metal Exchange copper and aluminum volatility swings heat exchanger fabrication costs on fixed-price municipal contracts. Hyperscale operators in Querétaro exhibit lowest price sensitivity, absorbing premium liquid cooling costs without procurement friction, while Monterrey industrial edge computing buyers demand aggressive equipment financing.
Supply Chain Analysis
Tariff exposure between Mexico and Asian manufacturing hubs dominates supply chain risk assessment for precision cooling components. Heat exchanger fabrication draws from China, South Korea, and domestic Mexican assembly partnerships. Proportional refrigerant flow controls, dielectric fluid chemistries, and variable-frequency drive electronics rest on concentrated Asian supplier bases. Single-source vulnerability for fluorinated immersion cooling fluids produced by three global chemical conglomerates limits domestic operator negotiation leverage. Distribution runs through authorized integrator networks with captive service capabilities, bypassing traditional HVAC wholesale channels for hyperscale direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in retrofit engineering complexity, as legacy air-cooled facilities built 2015-2019 face structural constraints that resist standardized solutions and reward specialized integration capabilities.
For Market Incumbents: Harden service network density in Querétaro's digital corridor to anchor long-term thermal optimization contracts against emerging localized competitors. Deepen backward integration into precision valve inventory buffers to mitigate single-source dependency exposure from German and Japanese suppliers. Invest in direct-to-chip cooling design competency through technical institute partnerships, addressing the sub-200 annual graduate pipeline forcing talent import from Spain and Argentina. For New Entrants and Emerging Players: Establish a beachhead in Monterrey's underserved manufacturing-driven edge computing corridor, where precision cooling specialist presence remains thin and CFE transmission constraints create deployment bottlenecks for incumbent expansion. Target modular cooling plant deployment for cloud service providers with standardized specifications, leveraging prefabricated building blocks to bypass raised-floor infrastructure requirements. Lead with performance-guaranteed thermal management contracts featuring penalty clauses, mirroring the unbundled procurement shift visible among Guadalajara financial services facilities. For Investors and Strategic Acquirers: The market sits at an infrastructure transition phase that favors engineering-specialized integrators over equipment manufacturers. Long-term viability across the projection horizon hinges on continuous commissioning service relationships rather than capital equipment sales cycles. Acquisition target archetype: regional integrators with captive thermal-fluid engineering talent and established relationships with CFE planning officers. Monitor direct-to-chip cooling adoption velocity among AI training clusters as the inflection indicator for traditional chilled water infrastructure displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Manufacturing Partnership | Vertiv Group Corp's Mexican assembly presence reduces lead times for CFE tariff-sensitive hyperscale projects. |
| Refrigerant-Natural Gas Hybrid Deployment | Absorption chiller pilots near Pemex infrastructure offer carbon accounting advantages for federal consolidation initiatives. |
| PROFECO Certification Investment | Premium efficiency labeling opens preferential procurement channels with state-owned enterprises and federal data projects. |
| Direct-to-Chip Engineering Talent Acquisition | Spanish and Argentine thermal-fluid specialists address the sub-200 annual graduate output from Mexican technical institutes. |
| Continuous Commissioning Service Unbundling | Santander and BBVA facilities in Guadalajara have shifted to penalty-clause thermal management, validating the model. |
Research Methodology
Cross-validation between facility operator interviews and regulatory filing analysis anchors the qualitative findings for this study. Primary fieldwork engaged data center engineering directors, CFE industrial planning officers, thermal system procurement leads at colocation providers, and aftermarket service heads at cooling OEMs. Secondary validation drew from CRE energy efficiency standard disclosures, PROFECO certification databases, NOM-001-SEDE electrical norm filings, and CFE tariff restructuring announcements. Bottom-up equipment shipment analysis and top-down infrastructure investment tracking were reconciled through iterative triangulation.
Calibration against historical deployment patterns and announced hyperscale campus commitments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, cooling technology density class, end-user procurement sophistication, and installation project maturity. CAGRs were derived from slope analysis of announced capacity additions and efficiency-driven replacement cycles. Industry-specific forecast inputs incorporated GPU cluster power density trajectories and CRE compliance deadline clustering effects.
Stress conditions across copper and aluminum commodity bands, CFE tariff restructuring scenarios, and direct-to-chip cooling adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hyperscale commitment timelines and regulatory enforcement consistency. Macroeconomic deviation, regulatory postponement, or technological disruption in dielectric fluid chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
China Study of Data Center Water Consumption Market