
 India Data Center Cooling Market | 2026-2036
India Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Cooling Market Insights
Thermal engineering talent scarcity is bifurcating the competitive landscape between multinational specialists and domestic system integrators. Vertiv Holdings Co. leverages its global precision cooling portfolio to anchor hyperscale relationships in Navi Mumbai and Bengaluru. Voltas Ltd. competes through localized manufacturing scale and service density across tier-two cities. Schneider Electric SE differentiates via integrated microgrid-cooling architectures that sustain uptime in tropical climates.
Data center cooling encompasses engineered heat rejection systems—precision air conditioners, chillers, liquid cooling loops, and containment architectures—designed to maintain server inlet temperatures between 18°C and 27°C per ASHRAE guidelines while optimizing power usage effectiveness. Liquid cooling deployments are accelerating fastest among AI training clusters where rack densities exceed 30 kW, though air cooling retains dominant share in legacy enterprise facilities. Edge deployments represent the most fragmented configuration segment, with rack-mounted systems leading in telecom tower integration while standalone units prevail in remote industrial IoT sites.
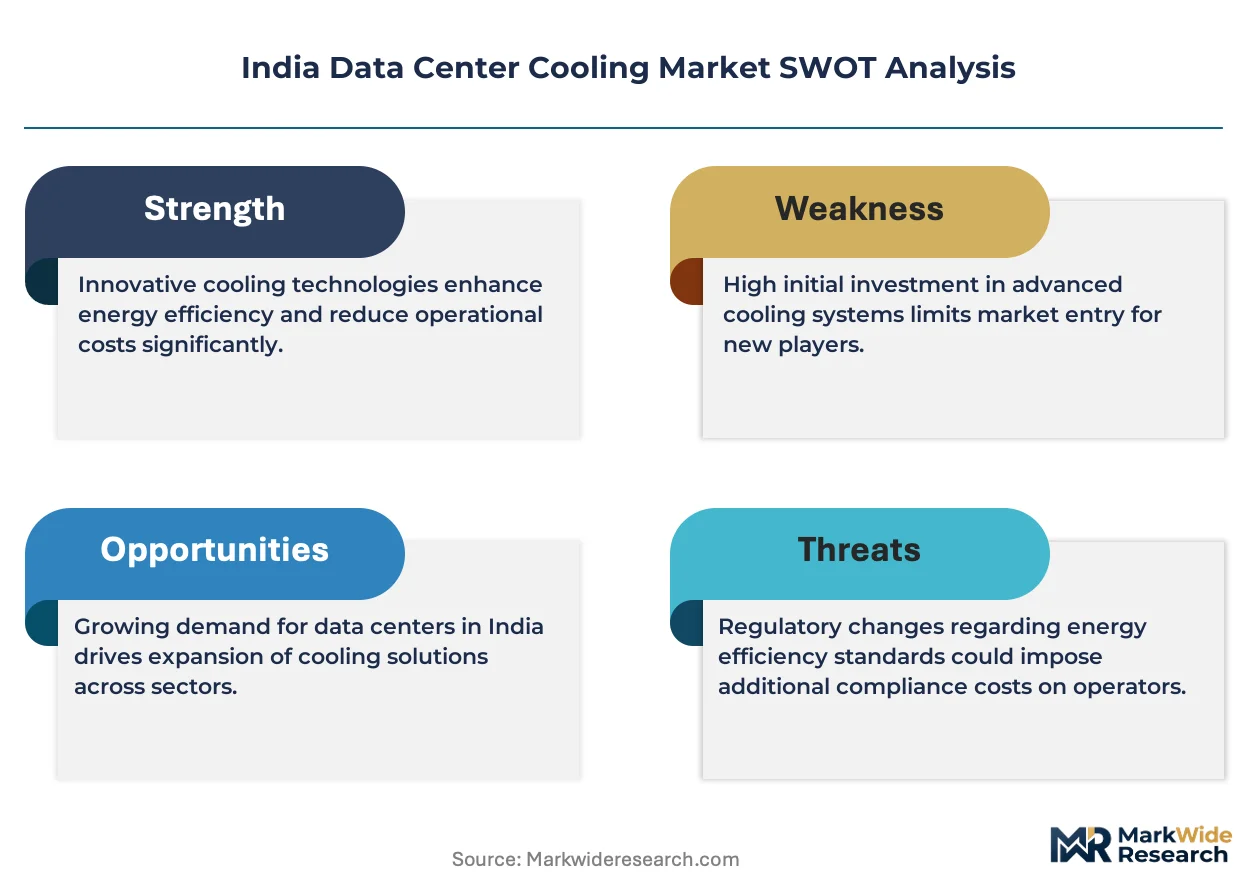
BIS mandates minimum energy performance standards for cooling equipment, while CEA regulations enforce power factor and harmonic distortion limits that shape system design. MEITY's green data center guidelines and state-level renewable purchase obligations are redirecting procurement toward heat recovery and free cooling architectures. Stakeholders must monitor evolving PLI scheme eligibility for domestic component manufacturing to recalibrate supply chain and pricing strategies.
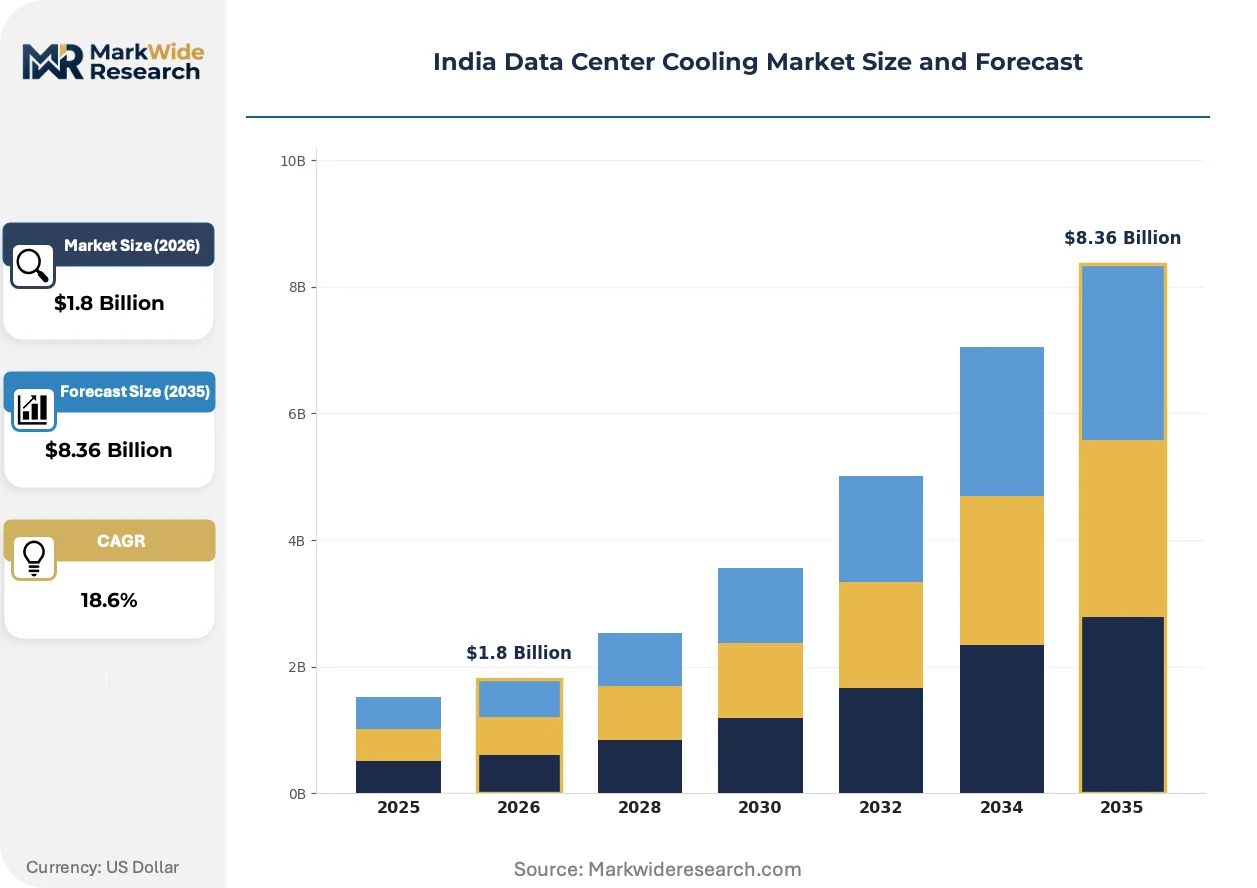
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and demanding liquid-ready infrastructure, forcing cooling vendors to reengineer product architectures before rack densities cross 50 kW thresholds.
Growth Catalysts
- MEITY Green Guidelines:Central government mandates for renewable energy integration and power usage effectiveness targets are accelerating free cooling and heat recovery retrofits in Mumbai and Hyderabad facilities.
- AI Training Clusters:Domestic generative AI deployments by cloud operators are pulling direct-to-chip liquid cooling systems into greenfield builds faster than legacy air-cooled designs can accommodate.
- State RPO Mandates:Renewable purchase obligations in Maharashtra, Telangana, and Tamil Nadu are redirecting capital toward cooling architectures that capture waste heat for district heating or industrial process integration.
Market Restraints
- Copper and Aluminum Volatility:Heat exchanger and piping raw material costs swing with commodity markets, compressing margins on fixed-price EPC contracts signed 12-18 months before deployment.
- Precision Component Import Dependence:Variable speed drives, advanced refrigerants, and high-efficiency compressors concentrate supply in German and Japanese manufacturing bases, exposing projects to currency and shipping risk.
- ASHRAE Thermal Range Limits:Tropical ambient conditions in Chennai and Kochi exceed free cooling viability hours, forcing mechanical refrigeration that degrades power usage effectiveness below certification thresholds.
Strategic Opportunities
- Tier-Two City Edge:Pune, Jaipur, and Bhubaneswar data center corridors remain underpenetrated for precision cooling, with local system integrators capturing service relationships before multinational vendors establish density.
- PLI Scheme Localization:Production-linked incentives for domestic manufacturing of cooling components and refrigerant handling equipment are creating captive supply advantages for vendors with in-house fabrication.
- Immersion-Adjacent Retrofits:Hybrid cooling architectures that bridge air-cooled legacy halls with liquid-cooled AI pods are enabling phased capital deployment without full facility shutdown.
Industry Challenges
- Thermal Engineering Talent Scarcity:Computational fluid dynamics modeling and refrigerant system design expertise concentrates in Bengaluru and Pune, leaving Navi Mumbai and Chennai projects dependent on fly-in specialists.
- BIS Certification Timelines:Energy performance standard testing queues at accredited laboratories extend equipment approval cycles, delaying hyperscale procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Cooling Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Hybrid Cooling, Refrigerant-Based Cooling End User: IT & Telecom, BFSI, Government, Healthcare Deployment Model: On-Premises, Colocation, Cloud, Edge System Configuration: Standalone Units, Rack-Mounted Systems, Chilled Water Systems, Integrated Solutions |
| Companies Covered | Johnson Controls International Plc, Mitsubishi Electric Corporation, Vertiv Holdings Co., Voltas Ltd., Blue Star Ltd., Schneider Electric SE, Trane Technologies Plc, Alfa Laval AB, Stulz GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Cooling Market Trends and Innovations
Cooling technology is fragmenting into specialized architectures as AI rack densities break legacy thermal assumptions, while regulatory pressure on energy performance accelerates equipment replacement cycles beyond historical norms.
Direct-to-chip liquid cooling is decomposing the traditional perimeter CRAC unit model by placing heat capture at the processor surface. Hyperscale operators in Navi Mumbai and Bengaluru are specifying this architecture for new 40-plus kW AI training racks. The shift is compressing the addressable market for precision air conditioners in high-density halls while expanding demand for coolant distribution units and leak detection systems.
BIS energy performance standards for cooling equipment are tightening minimum efficiency thresholds for units above 50 kW capacity. The regulation is disqualifying older chiller designs from new hyperscale procurement lists and redirecting R&D toward magnetic bearing compressors and adiabatic cooling augmentation. Domestic manufacturers in Pune and Chennai are accelerating testing programs to maintain eligibility under the revised schedule.
Hyperscale operators are unbundling cooling equipment procurement from mechanical EPC contracts and establishing direct relationships with precision cooling specialists. The pattern disrupts traditional general contractor markups and shifts commissioning risk to equipment vendors. Mumbai and Hyderabad corridors show the clearest evidence of this disintermediation, with cloud operators publishing technical specifications that bypass intermediary engineering firms.
India Data Center Cooling Market Segmentation
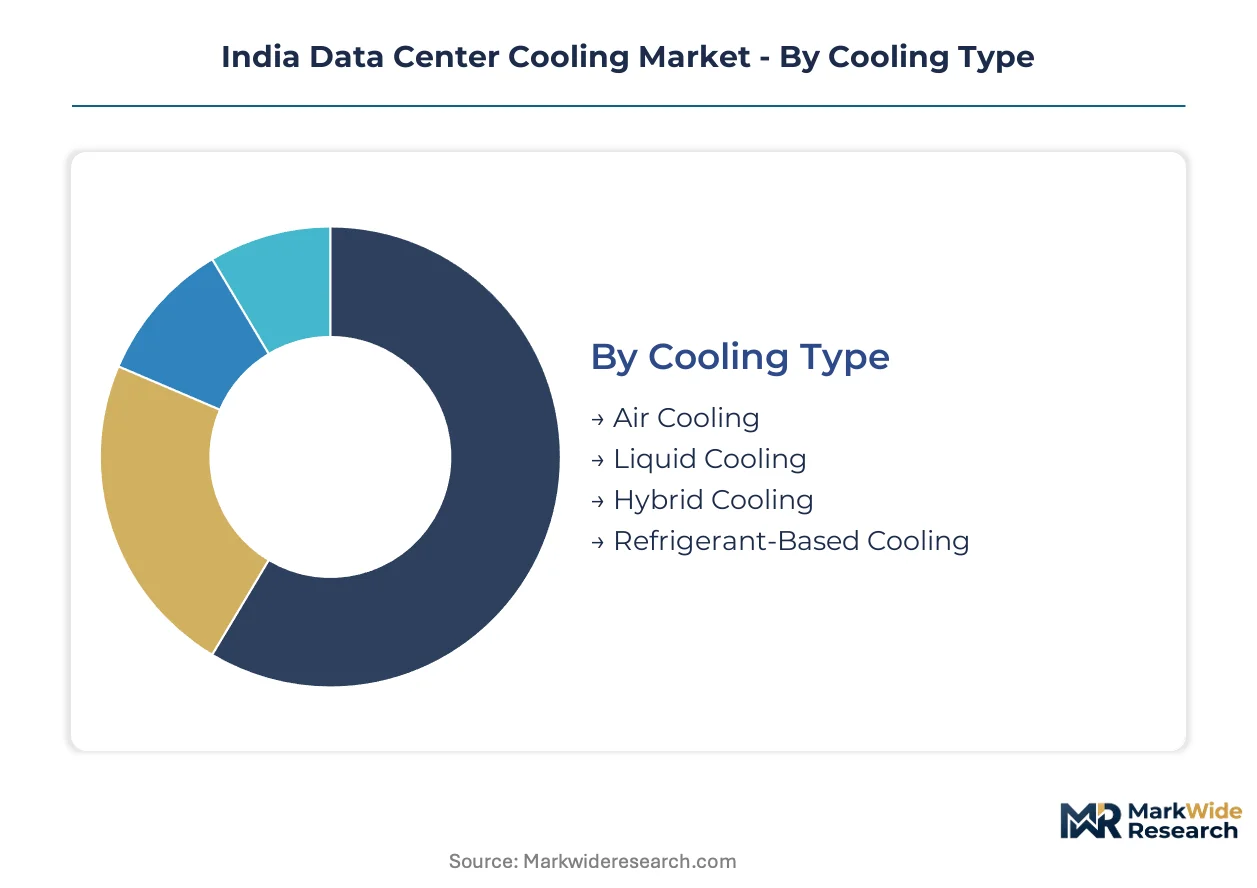
Cooling architecture selection in India hinges on rack density trajectories, regulatory compliance pathways, and the geographic distribution of hyperscale versus edge deployments. Procurement patterns bifurcate between legacy air-cooled retrofits in enterprise facilities and liquid-ready greenfield builds for AI clusters.
Cooling Type:
Domestic demand concentrates in air and hybrid architectures serving legacy enterprise facilities, while liquid cooling imports dominate AI training corridors in Navi Mumbai and Bengaluru.
- Air Cooling:Perimeter CRAC and CRAH units utilizing chilled water or direct expansion refrigerant cycles maintain dominance in legacy enterprise halls below 15 kW rack densities. Tamil Nadu and Maharashtra facilities favor these systems for BFSI compliance workloads where uptime certification outweighs efficiency gains.
- Liquid Cooling:Direct-to-chip and immersion architectures capture waste heat at processor surfaces for AI training racks exceeding 30 kW. Hyperscale operators in Hyderabad and Bengaluru specify these systems for generative AI deployments where ASHRAE thermal limits constrain air-cooled alternatives.
- Hybrid Cooling:Bridging architectures enable phased facility upgrades without full shutdowns. Telangana colocation providers deploy these for mixed-density halls serving both legacy enterprise and emerging AI workloads.
- Refrigerant-Based Cooling:Direct expansion systems with advanced refrigerants address edge deployments lacking chilled water infrastructure. Gujarat and Rajasthan industrial IoT sites specify these for standalone reliability.
Air cooling holds the largest share; momentum sits with liquid cooling.
End User:
Procurement scale and certification requirements vary sharply across customer categories, with hyperscale cloud operators compressing decision cycles relative to regulated industries.
- IT & Telecom:Hyperscale cloud operators and domestic telecom infrastructure deploy precision cooling at maximum scale. Jio and Airtel tower edge specifications drive rack-mounted system demand across Maharashtra and Gujarat corridors.
- BFSI:RBI data localization mandates force captive facility investment with stringent uptime requirements. Mumbai financial institutions prioritize redundant chilled water architectures over efficiency optimization.
- Government:MEITY green guidelines and state RPO obligations shape public sector procurement toward heat recovery integration. UP and Karnataka state data centers specify free cooling where ambient conditions permit.
- Healthcare:CDSCO medical device hosting regulations impose temperature stability requirements for diagnostic imaging archives. Tier-two city hospital networks represent fragmented demand for standalone precision units.
IT & Telecom commands volume leadership; Healthcare presents the steepest expansion trajectory as diagnostic digitization accelerates.
Deployment Model:
Capital deployment patterns distinguish between captive infrastructure, third-party colocation, and distributed edge architectures across India's urban hierarchy.
- On-Premises:Enterprise captive facilities in Delhi NCR and Chennai maintain legacy air-cooled halls with gradual efficiency retrofits. BFSI and manufacturing verticals dominate this category.
- Colocation:Third-party data center operators in Mumbai and Hyderabad offer multi-tenant precision cooling with PUE guarantees. Yotta and STT GDC specifications drive standardized chiller procurement.
- Cloud:Hyperscale self-builds by AWS, Azure, and GCP specify liquid-ready infrastructure for AI training zones. Navi Mumbai and Bengaluru corridors concentrate this demand.
- Edge:Distributed compute nodes for telecom and industrial IoT favor rack-mounted or standalone units. Rajasthan and Madhya Pradesh tower sites represent underserved configuration demand.
Colocation absorbs the dominant capital flow; Edge configurations are gaining share fastest as 5G rollout extends.
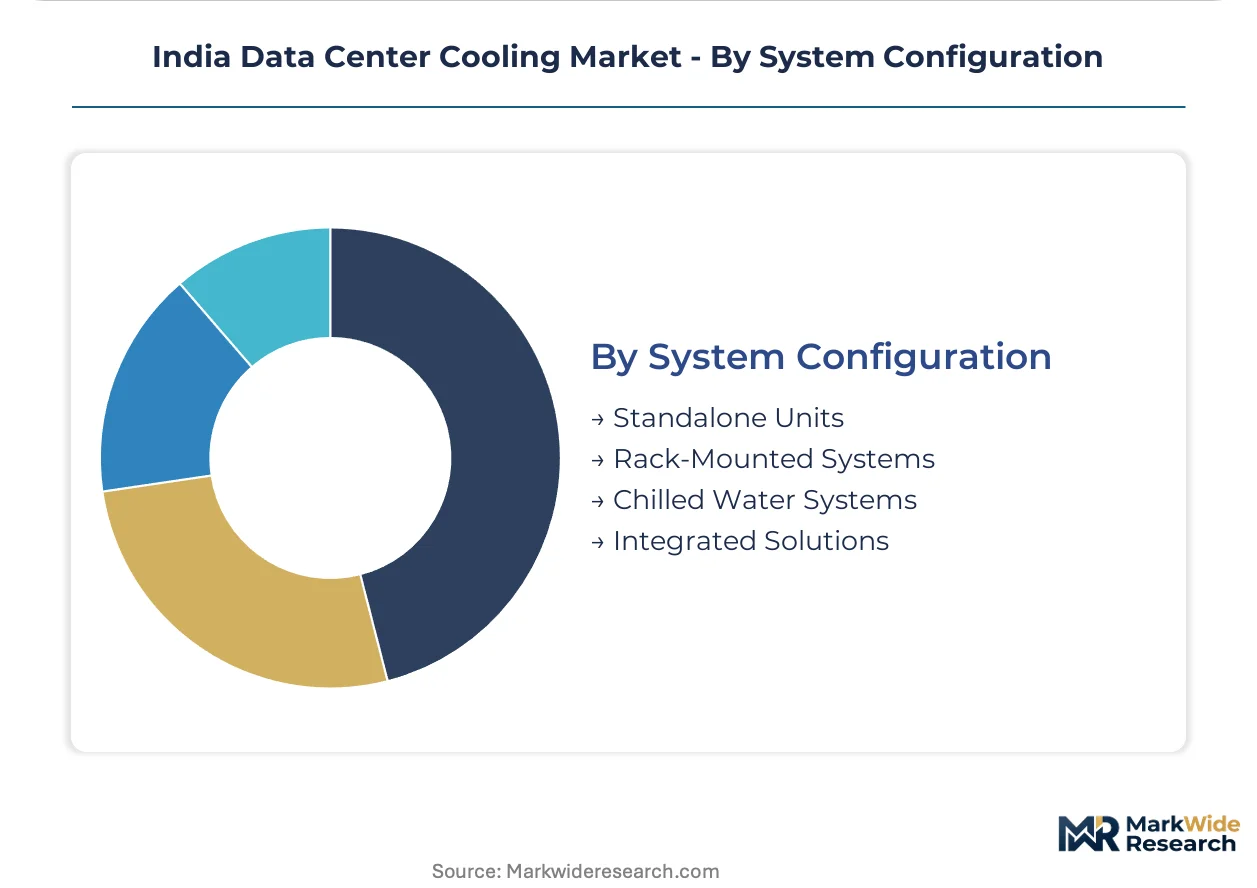
System Configuration:
Equipment form factor selection correlates with facility scale, existing mechanical infrastructure, and the availability of skilled commissioning resources.
- Standalone Units:Self-contained precision air conditioners serve remote edge sites and small enterprise server rooms. Pune and Jaipur industrial zones specify these for rapid deployment without chilled water infrastructure.
- Rack-Mounted Systems:In-row and rear-door heat exchangers address high-density zones within larger facilities. Bengaluru AI labs deploy these for targeted cooling of GPU clusters.
- Chilled Water Systems:Central plant architectures with CRAH units and cooling towers dominate hyperscale halls. Chennai and Mumbai operators favor these for operational flexibility across tenant mixes.
- Integrated Solutions:Factory-assembled mechanical and electrical modules compress construction timelines for greenfield builds. Hyderabad corridor projects specify these to accelerate commissioning.
Chilled water systems retain the largest installed base; integrated solutions are climbing the fastest as hyperscale timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai commands pricing premiums for liquid-ready infrastructure while Chennai operators absorb margin compression from tropical ambient conditions that degrade free cooling economics.
Maharashtra
Hyperscale cloud operators anchor procurement volume in Navi Mumbai and Thane corridors where land scarcity elevates rack density requirements. BIS energy performance standards disqualify legacy chiller designs from new builds. Yotta Infrastructure and STT GDC specifications drive standardized CDU procurement in the Mumbai-Pune belt.
Telangana
State renewable purchase obligations redirect capital toward heat recovery architectures in Hyderabad data center parks. CEA power factor regulations shape electrical-cooling system integration requirements. Microsoft and Amazon self-builds concentrate in the Fab City corridor with direct-to-chip liquid cooling specifications.
Tamil Nadu
Enterprise BFSI compliance workloads sustain demand for redundant chilled water systems despite efficiency penalties. MEITY green guidelines push public sector facilities toward free cooling where coastal humidity permits. Chennai's Sriperumbudur electronics cluster generates colocation demand with uptime certification priorities.
Karnataka
AI training cluster deployments by domestic cloud operators pull coolant distribution units into Bengaluru's Whitefield and Electronic City zones. TRAI telecom infrastructure mandates drive edge cooling specifications for tower sites across the state. Shell and Adani data center projects specify hybrid architectures for mixed-density halls.
Delhi-NCR
Government data center consolidation under the National Data Center Policy concentrates demand in Greater Noida and Manesar. RBI data localization enforcement sustains captive BFSI facility investment with stringent thermal redundancy. Haryana state incentives attract integrated solution deployments for rapid commissioning timelines.
India Data Center Cooling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision engineering specialists commanding premium positioning while domestic fabricators compete on localized service density. The market structure tiers into multinational precision cooling portfolios, integrated electrical-mechanical platforms, and regional system integrators with captive fabrication. Vertiv Holdings Co. and Schneider Electric SE anchor the technology-intensive segment through global precision portfolios. Competitive moves center on PLI scheme qualification for domestic component manufacturing and direct procurement relationships that bypass traditional EPC markups.
Among multinational specialists, Vertiv Holdings Co. and Schneider Electric SE occupy positions defined by integrated microgrid-cooling architectures and hyperscale specification influence. Voltas Ltd. exemplifies the domestic scale-driven archetype with localized manufacturing and service density across tier-two corridors. These three anchors represent the competitive tension between global technology access and indigenous cost structures that shapes procurement outcomes in Mumbai, Hyderabad, and Bengaluru corridors.
| Leading Market Players |
|---|
| Johnson Controls International Plc |
| Mitsubishi Electric Corporation |
| Vertiv Holdings Co. |
| Voltas Ltd. |
| Blue Star Ltd. |
| Schneider Electric SE |
| Trane Technologies Plc |
| Alfa Laval AB |
| Stulz GmbH |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month equipment lead times for variable speed drives and magnetic bearing compressors concentrate pricing power with German and Japanese component suppliers, compressing margins for Indian system integrators locked into fixed-price EPC contracts.
Pricing Analysis
Mumbai commands 15-25% premiums over Chennai for liquid-ready infrastructure due to land scarcity and hyperscale concentration. Three-tier pricing structure across liquid-cooled AI clusters, hybrid retrofits, and air-cooled legacy installations separates procurement tiers. Cost compression in air-cooled segments is intensifying because BIS efficiency standards disqualify older chiller designs. Colocation operators exhibit highest price sensitivity due to multi-tenant PUE guarantees, while captive BFSI facilities prioritize uptime certification over unit economics.
Supply Chain Analysis
Germany and Japan anchor precision component manufacturing for variable speed drives, advanced refrigerants, and high-efficiency compressors. India draws from these sources for critical cooling infrastructure while domestic fabrication concentrates in Pune and Chennai for sheet metal housings and piping assemblies. Single-source vulnerability runs through refrigerant supply chains subject to F-Gas Regulation equivalency pressures. Distribution runs through mechanical EPC contractors in legacy segments, though hyperscale operators increasingly disintermediate for direct equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center cooling is shifting toward platform-economics dynamics where coolant distribution unit interoperability and AI workload orchestration layers determine vendor stickiness beyond hardware specifications.
For Market Incumbents: Shield installed base relationships by accelerating PLI scheme qualification for domestic compressor and heat exchanger fabrication before tariff exposure on German and Japanese imports intensifies. Vertiv and Schneider must deepen backward integration into refrigerant handling equipment to defend margin position against Voltas' localized service density in tier-two corridors.
For New Entrants and Emerging Players: Lead with immersion-cooling adjacent retrofits for Telangana and Karnataka colocation providers serving mixed-density tenant mixes. Bhubaneswar and Jaipur edge corridors remain underpenetrated for rack-mounted precision units. Target telecom tower specifications through TRAI-mandated infrastructure partnerships with Jio and Airtel.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid cooling infrastructure as rack densities cross 30 kW thresholds and direct-to-chip architectures require specialized coolant distribution units. Acquisition targets should exhibit captive CFD modeling capabilities and BIS certification laboratory relationships. Monitor hyperscale procurement specification releases as inflection indicators for technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Localization | Domestic manufacturing of compressors and heat exchangers reduces import exposure to German and Japanese supply bases. |
| Liquid-Ready Infrastructure Specification | Hyperscale direct procurement relationships bypass EPC markups and shift commissioning risk to equipment vendors. |
| Heat Recovery Architecture Deployment | Maharashtra and Telangana RPO mandates redirect capital toward waste heat capture for district heating integration. |
| CFD Modeling Capability Acquisition | Thermal engineering talent scarcity in Navi Mumbai and Chennai elevates value of in-house simulation expertise. |
| Edge Cooling System Miniaturization | Rajasthan and Madhya Pradesh telecom tower sites generate underserved demand for rack-mounted precision units. |
Research Methodology
Cross-validation between hyperscale procurement officer interviews and BIS certification database analysis anchors the qualitative findings on technology transition timing. Primary fieldwork engaged data center engineering directors, mechanical EPC contractors, thermal system commissioning specialists, and PLI scheme administrators. Secondary sources include CEA power factor compliance filings, MEITY green data center guideline releases, state RPO mandate documents, and customs records for cooling equipment imports. Bottom-up facility-level capacity tracking triangulates against top-down hyperscale capex disclosures.
Sensitivity analysis on commodity price volatility and certification timeline delays shapes the analytical framework across the projection horizon. Segmentation dimensions span cooling architecture type, deployment model, end-user vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, greenfield build announcements, and efficiency retrofit penetration curves. Forecast inputs incorporate AI training cluster density trajectories and BIS energy performance standard phase-in schedules.
The analysis sits within stated boundaries; outcomes outside sustained hyperscale investment in Navi Mumbai and Bengaluru corridors would require recalibration. Forecasts reflect assumptions on copper and aluminum price stability, BIS laboratory testing queue durations, and MEITY guideline enforcement consistency. Recalibration cycles align with material shifts in hyperscale procurement specifications and PLI scheme eligibility revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market