
 Video Server Software Market | 2026-2036
Video Server Software Market Size, Share, and Industry Trends Forecast 2026-2036
Video Server Software Market Analytics
Enterprise buyers are redrawing procurement patterns away from legacy broadcast houses toward SaaS-native corporate and education departments. Brightcove Inc. leverages its specialization in monetization workflows for media publishers. Microsoft Corporation anchors enterprise video through Teams-integrated streaming and Azure Media Services architecture. Wowza Media Systems LLC differentiates through edge-optimized streaming protocols for low-latency use cases.
Video server software comprises applications that ingest, transcode, store, and distribute video streams across IP networks, typically supporting H.264/H.265 codecs and adaptive bitrate protocols such as HLS and DASH for device-agnostic playback. The primary purpose is to ensure reliable, scalable video delivery for live and on-demand content across enterprise, consumer, and surveillance environments. Cloud-based deployment is capturing the fastest expansion as organizations abandon capital-intensive on-premises infrastructure, while video management systems concentrate margin pools through recurring subscription attach rates. Encoding software retains volume leadership but faces compression from integrated platform bundles.
FCC guidelines shape content distribution standards for US broadcasters, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European video platforms. ISO and IEC frameworks underpin interoperability benchmarks that reduce vendor lock-in and accelerate procurement cycles. Stakeholders must monitor regulatory divergence between data sovereignty regimes and codec patent pools when selecting platform architecture.
Market Dynamics
Enterprise migration from capital-intensive broadcast infrastructure toward consumption-based cloud streaming is compressing traditional vendor margins while expanding addressable spend across corporate IT and education technology budgets.
Growth Catalysts
- GDPR and EU AI Act compliance mandates:European data residency requirements are forcing platform refreshes, creating replacement demand for sovereign-cloud video architectures that embed governance controls by design.
- Edge computing protocols:Low-latency streaming standards are unlocking interactive broadcast applications in sports wagering and live commerce, pulling investment toward distributed encoding nodes.
- Federal agency modernization:United States government departments are replacing legacy satellite distribution with IP-based video delivery stacks, concentrating procurement volume through GSA schedules.
Market Restraints
- Codec patent pool complexity:H.265 and emerging VVC licensing frameworks impose per-stream royalty uncertainty that deters long-term platform commitments from mid-market buyers.
- Cloud egress cost volatility:Bandwidth pricing from hyperscale providers introduces operational expenditure unpredictability that erodes the total-cost-of-ownership advantage over on-premises alternatives.
- Technical debt in broadcast incumbents:Legacy hardware-dependent vendors face compressed R&D cycles as recurring revenue from maintenance contracts declines faster than SaaS transition velocity.
Strategic Opportunities
- India's education technology expansion:Government digital learning mandates and low broadband penetration create demand for offline-capable video management systems with adaptive compression.
- AI-generated content governance:Synthetic media detection and provenance tracking represent unmet needs where video platforms can attach premium compliance modules.
- Convergence of video and access control:Physical security integrators are unifying surveillance and corporate communications streams, opening channel partnerships for unified video management platforms.
Industry Challenges
- Real-time streaming engineering scarcity:Specialized expertise in WebRTC optimization and edge node orchestration commands premium compensation that strains mid-tier vendor hiring.
- Multi-cloud interoperability certification:Buyers demand validated deployment across AWS, Azure, and Google Cloud simultaneously, extending quality assurance timelines and support matrix complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Server Software Market |
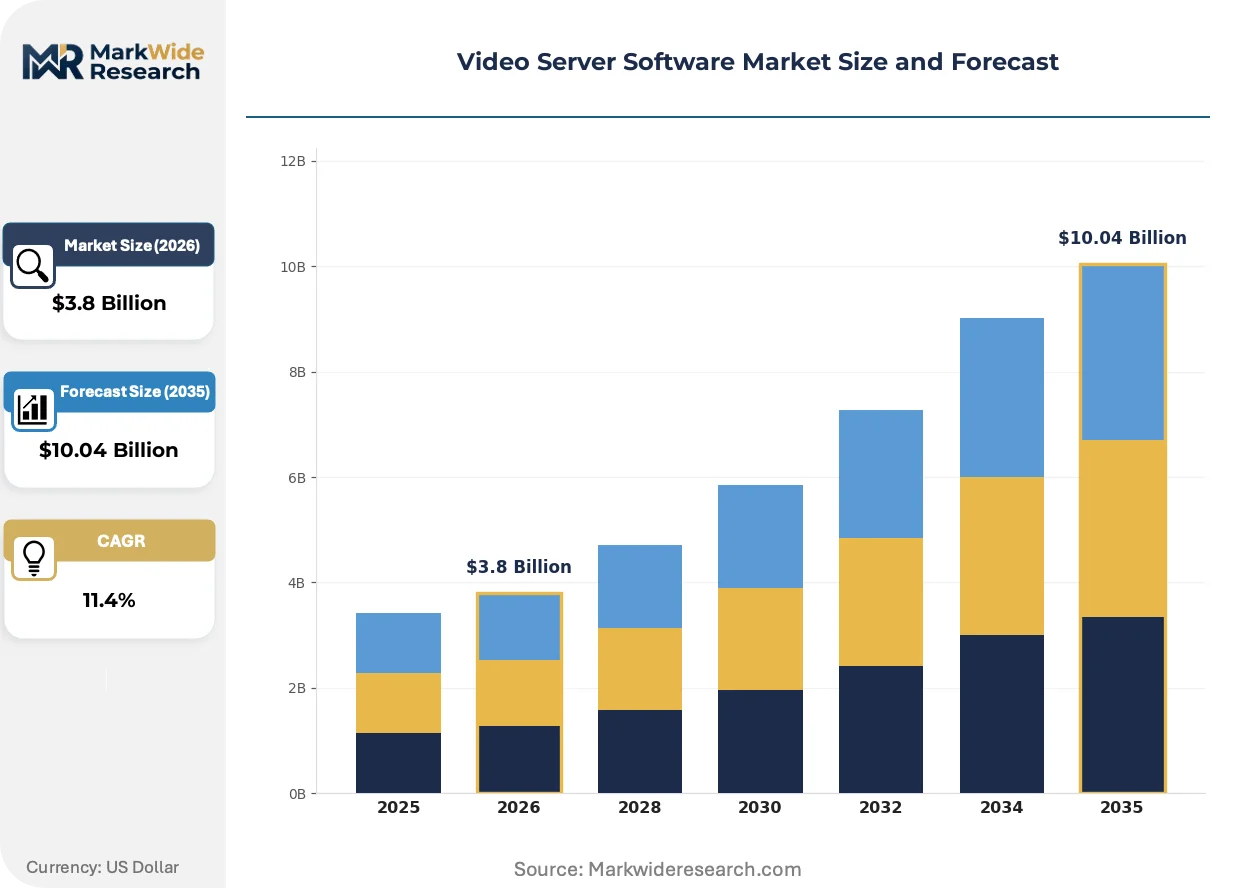
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Encoding Software, Streaming Server, Video Management System, API Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Media & Entertainment, Education, Corporate, Government Application: Live Streaming, Video Conferencing, Content Delivery, Video Surveillance |
| Companies Covered | IBM Corporation, Brightcove Inc., Kaltura Inc., Microsoft Corporation, Vimeo.com, Inc., Haivision Systems Inc., Wowza Media Systems LLC, Akamai Technologies Inc., Panopto Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Server Software Market Evolving Landscape
Codec diversification and regulatory fragmentation are forcing platform architectures toward modular, policy-embeddable designs that separate content processing from delivery infrastructure.
AV1 encoding is fragmenting competitive positioning in the streaming infrastructure layer. The royalty-free codec reduces bandwidth costs for high-resolution delivery by fifteen to thirty percent relative to H.265. Media publishers with direct-to-consumer applications are adopting AV1 transcode pipelines fastest, compressing margin pools for incumbent encoding software vendors who built around patent-encumbered standards.
GDPR enforcement actions against video platforms for biometric data processing are tightening consent architecture requirements. The European Data Protection Board's guidance on facial recognition in video analytics is forcing re-engineering of content moderation and audience measurement tools. Enterprise buyers in France and Germany are now demanding data protection impact assessments as standard procurement documentation, slowing sales cycles but favoring vendors with pre-certified compliance modules.
Subscription fatigue among corporate learning departments is compressing contract renewal rates for standalone video platforms. Buyers are unbundling video delivery from learning management systems, preferring API-first infrastructure that embeds into existing SaaS workflows. This pattern is most visible in United States healthcare systems, where HIPAA-compliant video consultation tools are being procured through electronic health record vendors rather than dedicated streaming providers.
Video Server Software Market Segmentation
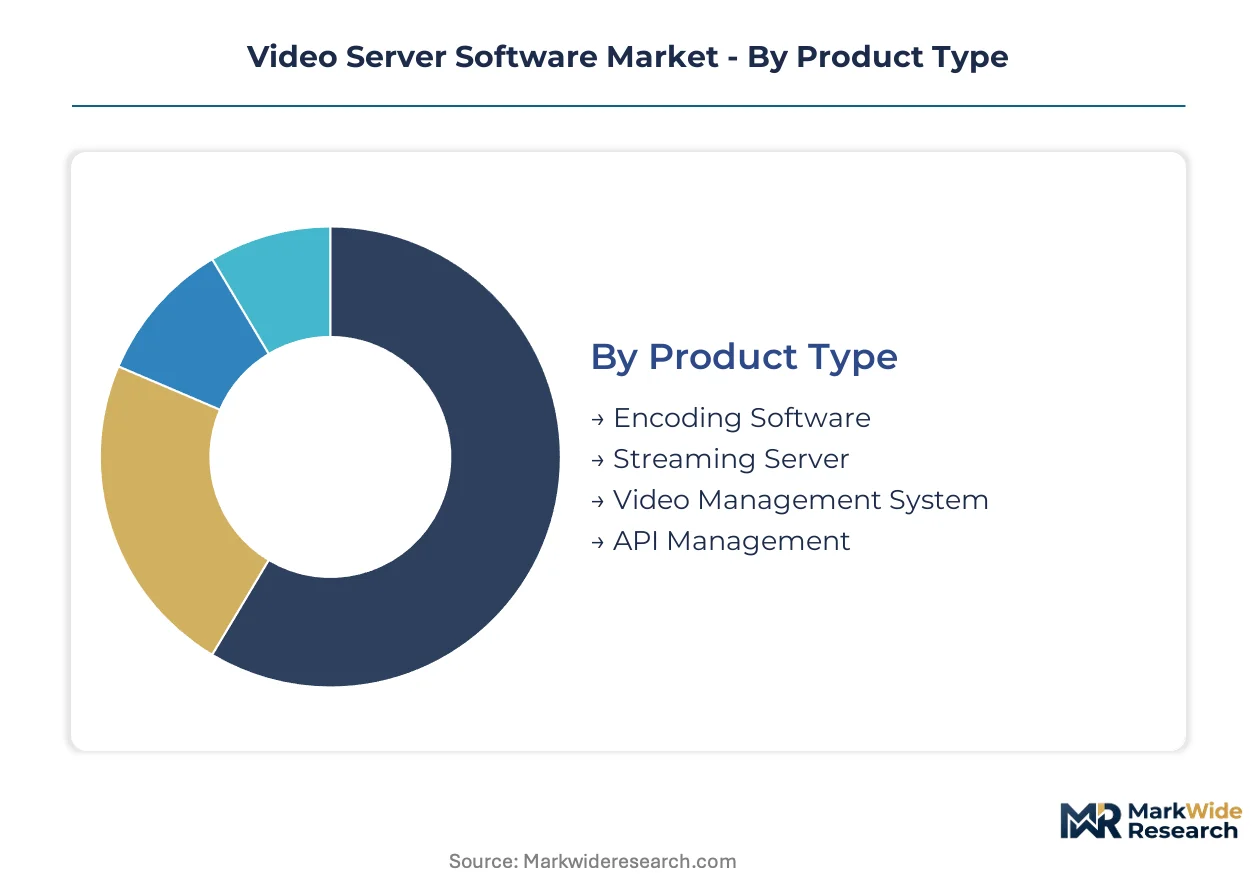
Segmentation in video server software reveals how procurement authority has shifted from broadcast engineers to IT infrastructure teams. Buyers now evaluate platforms through compliance, integration, and consumption economics rather than codec specifications alone.
Product Type:
GDPR and EU AI Act enforcement is fragmenting procurement across product tiers, with European buyers demanding embedded governance modules that legacy encoding tools lack.
- Encoding Software:Performs real-time transcoding across H.264, H.265, and AV1 formats with hardware acceleration support. Media publishers in the United States are consolidating vendor relationships around encoding vendors that bundle royalty clearance for patent pools, compressing standalone software margins.
- Video Management System:Centralizes metadata, access controls, and analytics for enterprise video libraries. Corporate learning departments in Germany now require data protection impact assessments as standard procurement documentation, slowing sales cycles but favoring pre-certified platforms.
- Streaming Server:Handles adaptive bitrate delivery via HLS and DASH protocols with CDN integration.
- API Management:Enables embedded video workflows within third-party SaaS applications through RESTful interfaces.
Encoding Software handles the majority of throughput; Video Management System is the fastest mover on share.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from consumption-metered cloud alternatives, with hybrid architectures capturing stranded asset scenarios.
- Cloud-Based:Delivers elastic compute and storage through hyperscale provider infrastructure with per-hour billing. Federal agencies in the United States are replacing satellite distribution with IP-based stacks procured through GSA schedules, concentrating volume in sovereign-cloud configurations.
- Edge Computing:Distributes encoding and cache nodes to regional points of presence for sub-second latency. Sports wagering platforms in Nevada and New Jersey are pulling investment toward distributed nodes that support real-time interactivity.
- On-Premises:Requires dedicated hardware ownership with perpetual licensing and maintenance contracts.
- Hybrid:Combines private infrastructure for sensitive content with cloud burst capacity for peak loads.
Cloud-Based deployments dominate new procurement; Edge Computing is expanding most quickly as interactive applications proliferate.
End User:
Customer type fragmentation reflects divergent compliance postures, with government and healthcare buyers imposing certification requirements that consumer-facing segments ignore.
- Corporate:Deploys video for internal communications, training, and executive broadcasting with SSO integration. HIPAA-compliant video consultation tools in United States healthcare systems are being procured through electronic health record vendors rather than dedicated streaming providers, unbundling delivery from learning management.
- Education:Supports lecture capture, virtual classrooms, and remote examination proctoring with accessibility compliance. Government digital learning mandates in India are creating demand for offline-capable systems with adaptive compression for low broadband penetration.
- Media & Entertainment:Monetizes direct-to-consumer and ad-supported streaming with DRM and dynamic ad insertion.
- Government:Requires FedRAMP or equivalent certification with air-gapped deployment options for classified content.
Corporate accounts generate the largest contract values; Education is climbing the fastest as institutional digitization accelerates.
Application:
Maturity gradients separate established live streaming workflows from emerging surveillance-to-communications convergence patterns.
- Live Streaming:Enables real-time broadcast with DVR, clipping, and multi-platform simulcast capabilities. Media conglomerates in the United States are modernizing delivery stacks around cloud-native infrastructure that reduces satellite dependency.
- Video Surveillance:Integrates physical security feeds with corporate communications for unified command centers. Physical security integrators are unifying surveillance and communications streams, opening channel partnerships for platforms that bridge both workflows.
- Video Conferencing:Supports multi-party collaboration with recording, transcription, and breakout room management.
- Content Delivery:Optimizes global distribution through CDN orchestration and geographic load balancing.
Live Streaming retains volume leadership; Video Surveillance is gaining share fastest through security-communications convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems landing at Virginia Beach and Bude anchor North American and European video traffic exchange, while submarine cables connecting Mumbai, Chennai, and Singapore underpin Asia-Pacific streaming infrastructure scale.
United States
Media conglomerates in New York and Los Angeles are modernizing delivery stacks around cloud-native infrastructure. FCC guidelines shape content distribution standards for broadcasters while federal agencies replace satellite distribution with IP-based stacks through GSA schedules. The Washington DC-to-Northern Virginia corridor concentrates sovereign-cloud procurement for classified video delivery.
Germany
Enterprise buyers in Frankfurt and Munich now demand data protection impact assessments as standard procurement documentation. GDPR enforcement by the CNIL's German counterpart and the EU AI Act impose algorithmic transparency obligations on video platforms. The Rhine-Ruhr industrial belt hosts automotive manufacturers deploying edge-optimized streaming for factory floor communications.
India
Government digital learning mandates and low broadband penetration create demand for offline-capable video management systems. TRAI regulations on data localization intersect with central education ministry procurement guidelines. Bangalore and Hyderabad clusters host education technology platforms building adaptive compression for rural connectivity constraints.
United Kingdom
Corporate learning departments in London are unbundling video delivery from learning management systems, preferring API-first infrastructure. Ofcom content standards and post-Brexit data adequacy arrangements create compliance complexity for cross-border streaming. The Manchester media corridor hosts broadcasters transitioning from legacy satellite to IP-based distribution.
Japan
Enterprise IT departments in Tokyo and Osaka are expanding procurement of cloud-native streaming infrastructure for hybrid workforce communications. METI guidelines on data sovereignty and JIS interoperability standards shape platform selection. The Nagoya manufacturing belt deploys low-latency streaming for supply chain coordination and quality assurance workflows.
Video Server Software Market Competitive Landscape
Concentration sits with hyperscale cloud providers and specialized streaming infrastructure vendors. The vendor base spans three tiers: cloud-native platforms with integrated encoding and delivery, point-solution specialists in low-latency or security verticals, and legacy broadcast hardware vendors attempting SaaS transition. Strategic moves center on M&A for codec patent clearance and geographic expansion through channel partnerships in regulated markets.
Within the enterprise SaaS tier, Microsoft Corporation and IBM Corporation occupy positions anchored to broader cloud productivity ecosystems. Brightcove Inc. exemplifies the media publisher specialization archetype, while Wowza Media Systems LLC represents edge-optimized protocol vendors serving interactive broadcast applications. These three companies illustrate the competitive divergence between platform breadth and vertical depth.
| Leading Market Players |
|---|
| IBM Corporation |
| Brightcove Inc. |
| Kaltura Inc. |
| Microsoft Corporation |
| Vimeo.com, Inc. |
| Haivision Systems Inc. |
| Wowza Media Systems LLC |
| Akamai Technologies Inc. |
| Panopto Inc. |
| Others |
Value Network & Pricing Analysis
FedRAMP certification gates both supplier qualification and price differentiation in the United States government segment, forcing vendors to absorb compliance engineering costs that compress margins at the standard tier while enabling premium pricing for air-gapped deployments. This regulatory barrier simultaneously restricts the vendor pool and stratifies contract values across civilian and classified use cases.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with annual committed use discounts reaching steeper thresholds for healthcare systems bundling video consultation tools through electronic health record vendors. Price differentiation rests on certification grade—FedRAMP High versus Moderate—and geographic delivery cost for edge node proximity. Pricing pressure stems from hyperscale cloud providers bundling video infrastructure into productivity suites, eroding standalone platform margins. Mid-market education buyers exhibit highest price sensitivity, while federal agencies with GSA schedule access show lowest.
Supply Chain Analysis
Submarine cable landings at Virginia Beach and Bude anchor transatlantic bandwidth chokepoints that constrain European data residency compliance for United States-based hyperscalers. Software development concentrates in the United States, India, and Ireland, with encoding hardware acceleration drawing from Taiwan and South Korea. Single-source vulnerability sits with patent-encumbered codec licensing pools for H.265 and emerging VVC standards. Distribution runs through hyperscale marketplaces and direct enterprise sales with professional services attach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment—certification backlogs and compliance engineering—creates sticky revenue streams that resist displacement by unqualified challengers.
For Market Incumbents: Compound switching cost advantages by deepening API-first integration with electronic health record and learning management system incumbents, while accelerating FedRAMP High certification pipelines to defend against sovereign-cloud challengers. Patent pool clearance for AV1 and VVC codecs represents the critical R&D lever to maintain encoding margin structures against royalty-free alternatives. For New Entrants and Emerging Players: AI-generated content provenance tracking represents a service-layer gap where incumbents under-serve media publishers facing EU AI Act synthetic media disclosure mandates. India's education technology procurement—offline-capable adaptive compression for low broadband penetration—offers the most penetrable geography. Go-to-market should anchor through state-level education ministry channel partnerships rather than direct institutional sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native streaming infrastructure as containerized deployment reduces hardware-dependent capex. Long-term viability favors platforms with recurring subscription attach rates above professional services dependency. Acquisition target archetype: edge-optimized protocol specialists with Nevada gaming commission certifications. The signal to watch is GSA schedule consolidation velocity as federal procurement centralizes around fewer approved vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Codec Patent Clearance Investment | AV1 and VVC licensing frameworks determine margin sustainability for encoding vendors competing against royalty-free alternatives. |
| Sovereign-Cloud Partnership | European data residency requirements force hyperscalers into joint ventures with local operators to maintain public sector access. |
| API-First Platform Integration | Healthcare systems now procure video through EHR vendors, unbundling standalone streaming from clinical workflow budgets. |
| Edge Node Geographic Expansion | Nevada and New Jersey sports wagering platforms demand sub-second latency that pulls encoding capacity toward distributed points of presence. |
| Compliance Module Premiumization | GDPR biometric consent architecture and EU AI Act synthetic media detection create attachable governance revenue streams. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with chief technology officers, IT procurement officers at healthcare systems, platform engineers at education technology providers, and federal GSA contract specialists. Secondary validation drew from FCC filing databases, hyperscaler capex disclosures, SEC 10-K infrastructure segment reporting, and EU regulatory guidance documents. Bottom-up deployment model sizing was triangulated against top-down enterprise software spending benchmarks.
Across the projection horizon, the analytical framework modeled segmentation across deployment model, organization size, vertical compliance posture, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific forecast inputs included federal modernization budget appropriations and education ministry procurement timelines in India.
Underlying assumptions cover sovereign-cloud certification velocity and hyperscale bundling intensity, with deviation risk concentrated in codec patent pool litigation and bandwidth pricing volatility. Practitioners should keep alternative scenarios live as EU AI Act enforcement interpretations and federal agency cloud migration deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Curriculum Mapping Software Market
Software & Services
Staffing Software Market
Software & Services
Application Server Market
Software & Services
Online Paint Editor App Market
Software & Services
Global Polling Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Tag Management Software Market
Software & Services
Global Automation Software Market
Software & Services
North America Equity Management Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Global Test Data Management Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Online Whiteboard Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Global Affiliate Software Market