
 Taiwan Data Center Cooling Market | 2026-2036
Taiwan Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Cooling Market Insights
Multi-sourced equipment procurement is expanding across Taiwanese data center operators as liquid cooling deployments scale beyond pilot phases. Delta Electronics Inc. anchors domestic manufacturing of precision cooling units for local hyperscale builds. Vertiv Group Corp. competes through thermal management integration services targeting AI training clusters. Schneider Electric SE extends its position via energy-efficient chiller systems aligned with Taiwan's green building certifications.
Taiwan data center cooling encompasses engineered thermal management systems—chillers, computer room air handlers, liquid cooling manifolds, and environmental controls—designed to maintain server inlet temperatures between 18°C and 27°C per ASHRAE guidelines while dissipating heat loads exceeding 50 kW per rack in AI-optimized facilities. Liquid cooling solutions are capturing margin pools as GPU densities render traditional air-based methods insufficient for HPC workloads. Chilled water systems still dominate legacy enterprise installations, though evaporative cooling gains traction in Taoyuan facilities exploiting Taiwan's subtropical humidity cycles for adiabatic efficiency.
Taiwan's Bureau of Energy enforces minimum energy performance standards for data center infrastructure, while the EPA administers greenhouse gas inventory requirements that pressure operators toward lower-PUE designs. The National Communications Commission imposes equipment safety certifications on imported cooling hardware, shaping vendor market access protocols. Stakeholders must weigh thermal design power trajectories against local grid constraints as AI deployment accelerates facility power densities beyond current substation capacities.
Market Dynamics
Liquid cooling infrastructure is modularizing across Taiwanese hyperscale facilities as GPU thermal design power exceeds 50 kW per rack, forcing operators to abandon legacy air-based architectures mid-deployment cycle.
Growth Catalysts
- AI Training Cluster Deployment:Hyperscalers in Hsinchu Science Park are commissioning dedicated liquid cooling loops for NVIDIA H100 and Blackwell architectures, creating immediate infrastructure pull-through.
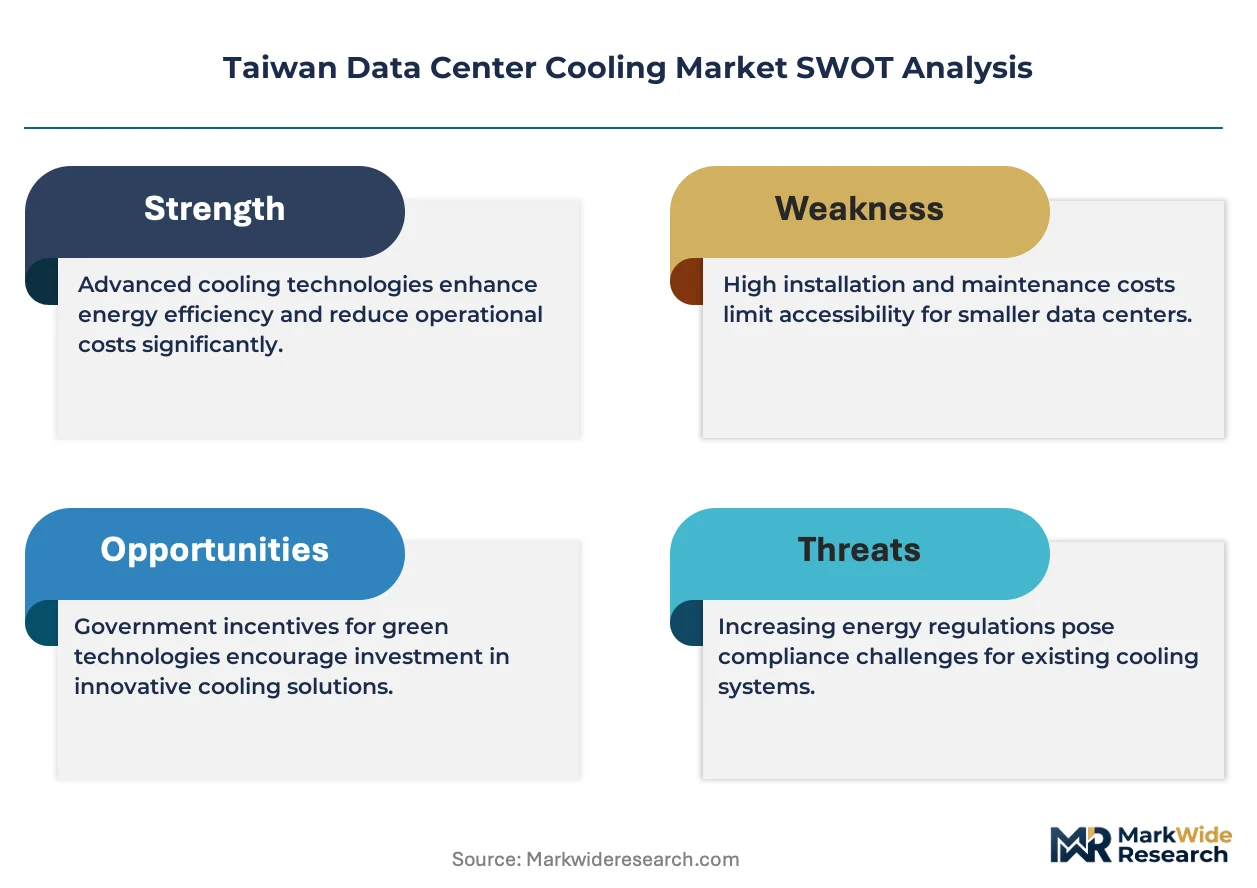
- Bureau of Energy Efficiency Mandates:Taiwan's minimum energy performance standards for data center infrastructure are compressing PUE targets below 1.3, disqualifying traditional chilled water systems from new builds.
- Semiconductor Co-location Density:Foundry expansion in Taichung and Tainan is concentrating compute demand within 20 kilometers of fab complexes, enabling shared district cooling economies.
Market Restraints
- Copper and Nickel Price Volatility:Liquid cooling manifolds and cold plates depend on refined copper and nickel alloys, with Taiwan's import exposure creating margin compression during commodity spikes.
- Substation Capacity Saturation:Taoyuan and Taipei grid infrastructure cannot support projected 2030 power densities without 18-24 month utility upgrade cycles, throttling facility commissioning.
- Dielectric Fluid Supply Concentration:Engineered coolants for single-phase immersion systems source primarily from US and Japanese chemical specialists, exposing operators to export control friction.
Strategic Opportunities
- Kaohsiung Port Zone Development:Underutilized industrial land near submarine cable landing stations offers 40% lower land costs than northern corridors for hyperscale greenfield builds.
- Heat Reuse Integration:District heating partnerships with nearby aquaculture and greenhouse operations monetize waste heat from liquid cooling loops, offsetting carbon intensity reporting.
- Modular Edge Deployment:Containerized liquid cooling units are penetrating 5G edge clusters across Taiwan's eastern counties where grid constraints prohibit traditional facility construction.
Industry Challenges
- Thermal-Fluid Engineering Talent Scarcity:Taiwan's universities produce fewer than 200 specialized engineers annually for two-phase flow and dielectric chemistry applications, forcing operators to recruit from overseas.
- Legacy Air-Handler Stranded Assets:Enterprise colocation facilities in Taipei face write-down pressure as existing CRAH infrastructure cannot retrofit to support liquid-cooled racks without complete plant replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Cooling Market |
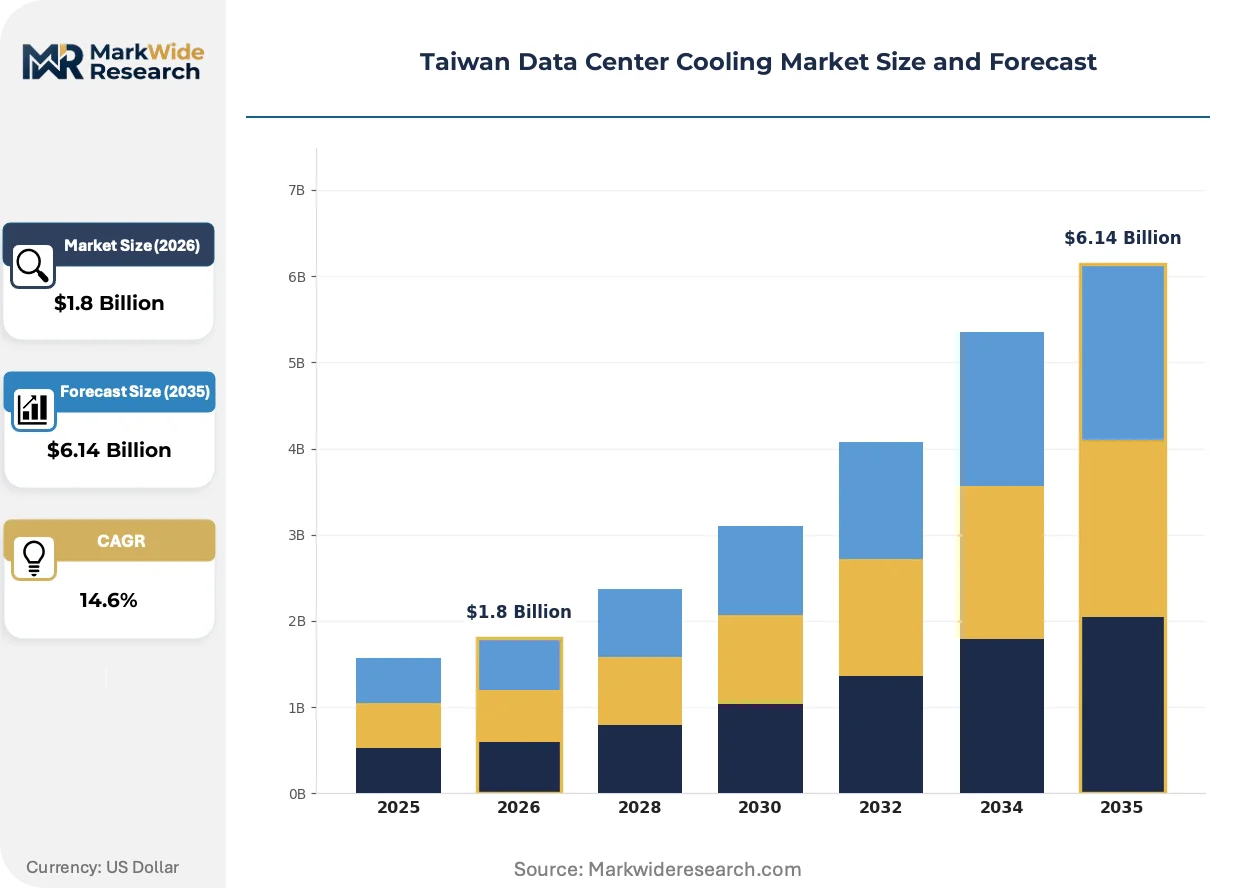
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Chilled Water, Direct Expansion, Evaporative Cooling, Liquid Cooling Deployment Model: On-Premise, Hybrid, Colocation, Cloud End User: IT & Telecom, BFSI, Government, Healthcare Component: Cooling Units, Control Systems, Distribution Systems, Piping |
| Companies Covered | Schneider Electric SE, Green Revolution Cooling, Munters Group AB, Submer Technologies, AIREDALE INTERNATIONAL AIR CONDITIONING LTD., Delta Electronics Inc., Vertiv Group Corp., Johnson Controls International PLC, Rittal GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Cooling Market Trends and Innovations
Refrigerant chemistry and heat exchanger architecture are converging to address Taiwan's subtropical humidity and seismic constraints, reshaping vendor R&D priorities toward climate-adaptive designs.
Direct-to-chip cold plates are modularizing across AI training facilities, replacing row-based rear-door heat exchangers with server-integrated microchannel blocks. Hyperscalers in Hsinchu are specifying quick-disconnect manifolds that enable rack-level maintenance without draining entire loops. This modularity is compressing deployment timelines from 14 months to 7 months for 10 MW halls.
Taiwan's Bureau of Energy is tightening enforcement of the Greenhouse Gas Reduction and Management Act, requiring facilities above 5 MW to submit verified carbon inventories annually. Operators are responding by specifying low-global-warming-potential refrigerants in chiller replacements and accelerating evaporative cooling adoption in Taoyuan's drier microclimate zones.
Facility operators are unbundling thermal performance guarantees from equipment procurement, demanding outcome-based contracts where vendors assume heat-related downtime risk. This transfer is displacing traditional capital-purchase models in enterprise colocation, with Taichung-based operators pioneering 10-year service agreements tied to PUE attainment clauses.
Taiwan Data Center Cooling Market Segmentation
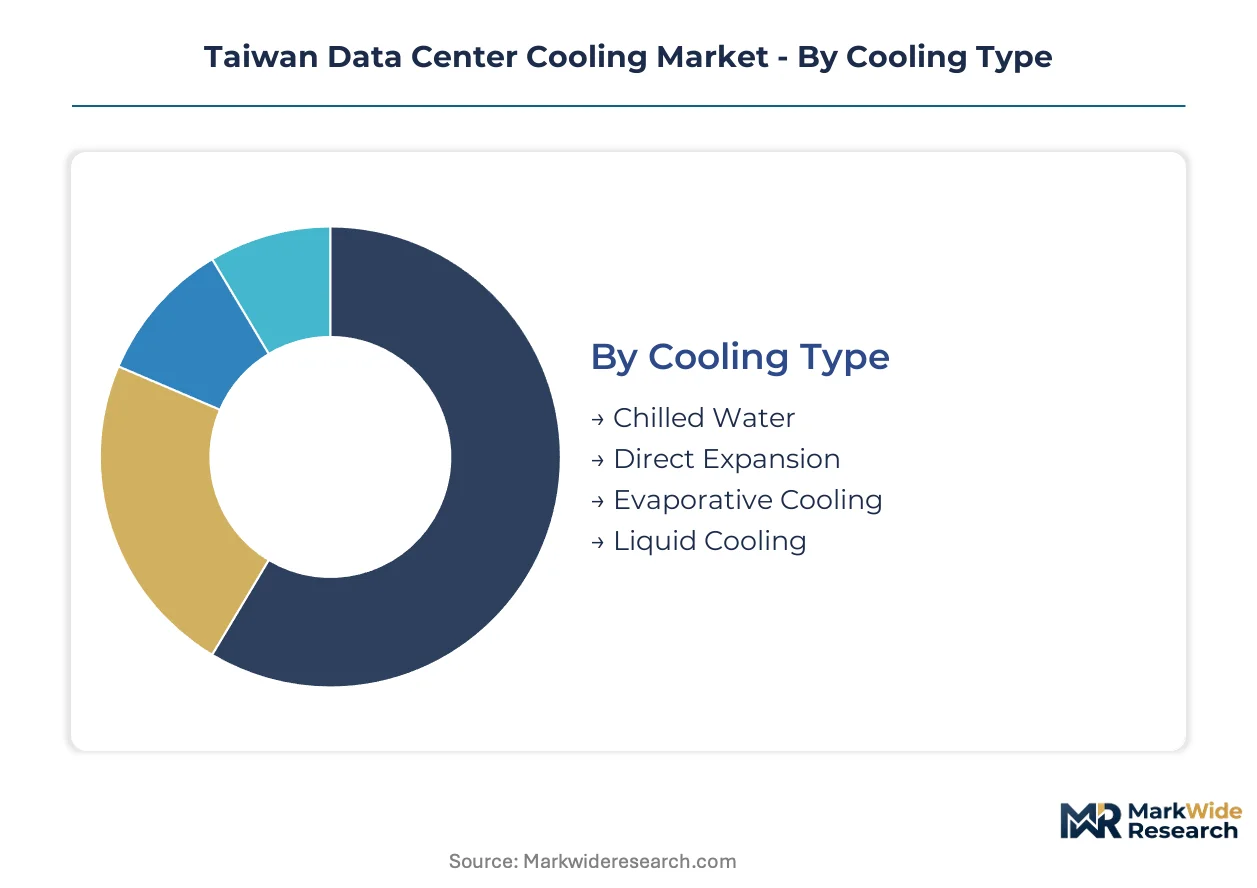
Taiwan data center cooling segmentation reveals distinct certification and procurement patterns across thermal architectures. Equipment categories face varying Bureau of Energy efficiency mandates and National Communications Commission safety protocols depending on refrigerant type and power rating.
Cooling Type:
Certification burdens cluster around refrigerant-based systems, with Taiwan's Greenhouse Gas Reduction and Management Act imposing inventory requirements on high-GWP coolants that exempt certain emerging technologies.
- Liquid Cooling:Direct-to-chip and immersion architectures circulate engineered dielectric fluids or water-glycol mixtures through cold plates or tanks. Hyperscalers in Hsinchu Science Park are specifying these systems for NVIDIA GPU clusters where rack densities exceed 50 kW, though operators face 18-24 month lead times for specialized coolant procurement.
- Chilled Water:Centralized chiller plants distribute conditioned water through CRAH units, dominating legacy enterprise facilities. Taoyuan operators are retrofitting these plants with magnetic bearing compressors to meet Bureau of Energy PUE targets below 1.3, but face stranded asset risk where pipe infrastructure cannot support liquid cooling conversion.
- Direct Expansion:Self-contained DX units with on-board refrigeration cycles serve smaller edge deployments and legacy server rooms. These systems trigger National Communications Commission electromagnetic compatibility certifications that add 8-12 weeks to deployment timelines.
- Evaporative Cooling:Adiabatic systems exploit Taiwan's subtropical humidity cycles, achieving efficiency gains in Taoyuan's drier microclimate zones. These installations avoid refrigerant inventory requirements entirely, simplifying EPA greenhouse gas reporting obligations.
Liquid cooling sits at the top of the volume ranking, with evaporative cooling climbing the fastest as Taoyuan hyperscalers seek PUE compliance without full infrastructure replacement.
Deployment Model:
Procurement patterns diverge sharply by deployment scale, with colocation operators demanding modular thermal units while cloud providers engineer integrated district cooling networks.
- Cloud:Hyperscale operators in Taipei and Taichung design dedicated liquid cooling loops tied to submarine cable landing stations, achieving economies through 10 MW+ hall standardization. These facilities face the most stringent Bureau of Energy efficiency enforcement.
- Colocation:Multi-tenant facilities in Hsinchu Science Park balance mixed rack densities, deploying hybrid air-liquid architectures that segment premium liquid-cooled suites from standard air-cooled inventory. Pricing stratifies across premium, standard, and economy tiers based on thermal service level agreements.
- Hybrid:Enterprise operators split workloads between owned facilities and cloud burst capacity, requiring portable cooling modules that interface with both environments. These deployments concentrate in Taichung where semiconductor fabs co-locate with compute infrastructure.
- On-Premise:Legacy enterprise data centers in Taipei maintain chilled water plants with limited retrofit flexibility, facing write-down pressure as GPU densities render existing CRAH infrastructure obsolete.
Cloud deployments command the largest absolute capacity additions, with colocation expanding most quickly as foundry-adjacent compute demand concentrates in central Taiwan.
End User:
IT & Telecom operators anchor demand concentration, with BFSI and healthcare segments presenting distinct thermal reliability requirements that shape equipment specification.
- IT & Telecom:Hyperscalers and carrier-neutral facilities drive liquid cooling volume, with Chunghwa Telecom and international cloud providers commissioning dedicated training clusters in northern Taiwan. These operators specify quick-disconnect manifolds that compress deployment timelines.
- BFSI:Financial institutions in Taipei prioritize continuous cooling redundancy for trading infrastructure, demanding N+1 chiller configurations with automated failover. Regulatory pressure from Taiwan's Financial Supervisory Commission drives disaster recovery investments in secondary Taichung facilities.
- Government:Public sector data centers face procurement transparency requirements that favor established chilled water vendors with local service networks. National Development Council smart city initiatives are accelerating edge deployments in Kaohsiung.
- Healthcare:Medical imaging and research compute clusters require precise humidity control alongside temperature management, with Taiwan's Ministry of Health and Welfare imposing equipment validation protocols on critical care applications.
IT & Telecom generates the steepest expansion trajectory, with healthcare gaining share fastest as biomedical research clusters expand in Hsinchu.
Component:
Supply concentration varies by component category, with cooling units sourcing primarily from domestic manufacturers while control systems depend on imported automation platforms.
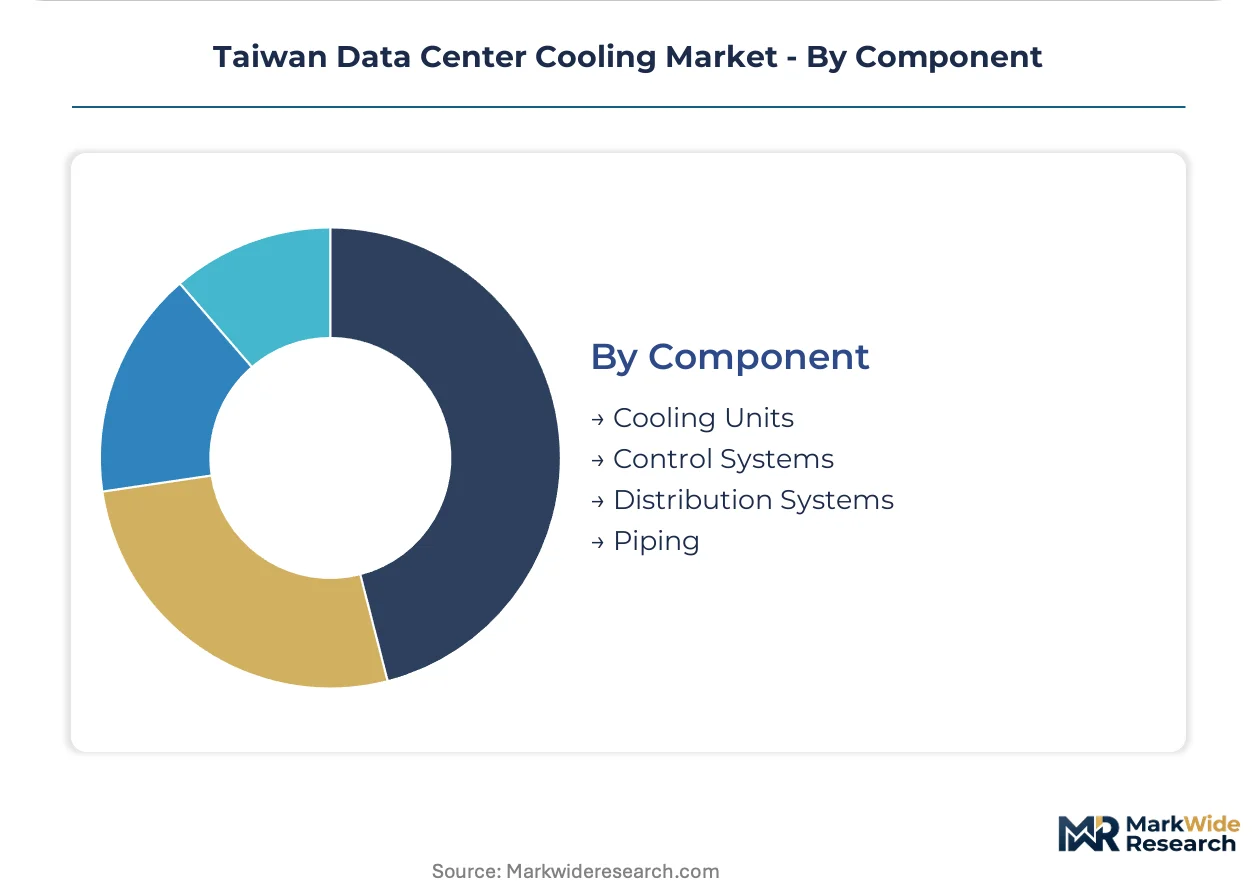
- Cooling Units:Chillers, CRAH units, and liquid cooling manifolds constitute the largest procurement category by value. Delta Electronics anchors domestic production of precision cooling equipment, though hyperscalers increasingly specify imported immersion tanks for single-phase deployments.
- Control Systems:Building management interfaces and thermal optimization software enable PUE monitoring mandated by Bureau of Energy regulations. These systems require National Communications Commission cybersecurity certifications for networked deployments.
- Distribution Systems:Pumping stations, valves, and heat exchangers move thermal energy between source and sink. Copper and nickel price volatility compresses margins on these components, with Taiwan's import exposure creating procurement risk during commodity spikes.
- Piping:Insulated distribution networks and rack-level manifolds complete thermal circuits. Quick-disconnect fittings are modularizing across Hsinchu facilities to enable maintenance without loop drainage, though dielectric fluid compatibility constrains material selection.
Cooling units represent the dominant value category, with control systems expanding most quickly as outcome-based thermal service contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors Taiwan's data center cooling demand through semiconductor-hyperscale co-location density. The island's thermal infrastructure expansion concentrates in three metropolitan corridors where grid constraints and Bureau of Energy mandates shape deployment timelines. Sub-regional differentiation emerges from proximity to submarine cable landing stations, foundry complexes, and substation capacity availability.
Northern Taiwan
Taipei and Taoyuan host hyperscale liquid cooling deployments for AI training clusters where rack densities exceed 50 kW. The Bureau of Energy enforces PUE targets below 1.3 in this corridor, disqualifying legacy chilled water systems from new builds. Linkou and Guishan districts concentrate cloud provider facilities near Chunghwa Telecom cable landing stations.
Central Taiwan
Taichung's science park expansion drives foundry-adjacent compute demand with shared district cooling economies. The National Development Council's smart machinery initiatives accelerate edge deployments in Taichung Port Zone. Fengyuan and Xitun districts cluster colocation facilities within 20 kilometers of TSMC fab complexes.
Southern Taiwan
Kaohsiung offers underutilized industrial land near submarine cable stations at 40% lower cost than northern corridors. The city's Bureau of Energy compliance pathway favors evaporative cooling exploiting subtropical humidity cycles. Cijin and Xiaogang districts attract hyperscale greenfield builds seeking port-adjacent connectivity.
Taiwan Data Center Cooling Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue immersion cooling specialization and modular edge architectures. The Taiwan market structures around three tiers: domestic precision equipment manufacturers, multinational thermal integration specialists, and niche dielectric fluid technology providers. Competitive positioning depends on Bureau of Energy certification speed, local service network density, and outcome-based contract structuring. Consolidation pressure intensifies as hyperscalers unbundle thermal performance guarantees from capital procurement.
Among Taiwan-based fabricators, Delta Electronics Inc. anchors domestic manufacturing of precision cooling equipment for local hyperscale builds. Vertiv Group Corp. and Schneider Electric SE exemplify multinational thermal integration specialists competing through energy-efficient system architectures aligned with green building certifications. These three occupy positions across the premium and standard tiers, with Delta representing captive supply advantages and Vertiv and Schneider representing outcome-based service contract capabilities.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Green Revolution Cooling |
| Munters Group AB |
| Submer Technologies |
| AIREDALE INTERNATIONAL AIR CONDITIONING LTD. |
| Delta Electronics Inc. |
| Vertiv Group Corp. |
| Johnson Controls International PLC |
| Rittal GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Taiwan's Bureau of Energy efficiency mandates gate qualified supply access and premium-tier pricing eligibility for cooling infrastructure vendors serving hyperscale deployments. Operators achieving sub-1.3 PUE certification command pricing premiums from cloud providers, while uncertified equipment faces margin compression in enterprise segments.
Pricing Analysis
Copper and nickel alloy costs pass through directly to liquid cooling manifold pricing, compressing margins for domestic fabricators during commodity spikes. Three-tier pricing structure across premium, standard, and economy levels separates Bureau of Energy-certified systems from retrofit chillers and basic DX units. Cost compression in the standard tier is intensifying because hyperscalers unbundle thermal performance guarantees from capital procurement. Enterprise colocation operators exhibit highest price sensitivity, while AI training cluster developers prioritize thermal reliability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for precision cooling units, while system integrators serve enterprise colocation retrofits. Manufacturing concentrates in Taiwan, Japan, and Germany for specialized components, with dielectric fluid chemistry sourcing primarily from US and Japanese chemical specialists. Supply chain risk centers on single-source vulnerability for engineered coolants subject to export control friction. Distribution runs through domestic fabricators with captive foundry relationships, multinational thermal integration specialists, and niche dielectric technology providers serving immersion deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan data center cooling functions as a geographic-arbitrage play where Kaohsiung's 40% land cost differential against northern corridors attracts hyperscale greenfield investment despite subtropical humidity engineering complexity.
For Market Incumbents: Acquire thermal-fluid engineering talent pools to offset Taiwan's annual output of fewer than 200 specialized engineers for two-phase flow applications. Consolidate district cooling infrastructure partnerships near Hsinchu Science Park foundry complexes to defend against modular edge competitors. Invest in Bureau of Energy certification speed as hyperscalers unbundle performance guarantees from equipment procurement. For New Entrants and Emerging Players: Launch via containerized liquid cooling units penetrating 5G edge clusters across Taiwan's eastern counties where grid constraints prohibit traditional facility construction. Target Kaohsiung Port Zone development for hyperscale greenfield builds exploiting submarine cable landing station proximity. Pursue heat reuse integration partnerships with aquaculture and greenhouse operations to monetize waste heat and offset carbon intensity reporting obligations. For Investors and Strategic Acquirers: Roll-up economics work for domestic precision equipment manufacturers because hyperscaler procurement is consolidating around vendors with captive supply advantages and local service network density. Monitor substation capacity saturation in Taoyuan and Taipei as the inflection signal indicating commissioning delays and demand diversion to southern corridors. Prioritize targets with Bureau of Energy certification pipelines and outcome-based contract structuring capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Reuse Integration Partnership | District heating agreements with aquaculture operations monetize waste heat from liquid cooling loops. |
| Modular Edge Deployment | Containerized units penetrate 5G clusters in eastern counties facing grid constraints. |
| Dielectric Fluid Supply Diversification | Reduces single-source exposure to US and Japanese chemical specialists for engineered coolants. |
| Thermal-Fluid Engineering Talent Acquisition | Addresses Taiwan's annual output gap of specialized engineers for two-phase flow applications. |
| Kaohsiung Port Zone Greenfield Build | Exploits 40% land cost differential and submarine cable landing station proximity. |
Research Methodology
Multiple input streams — hyperscale facility engineering directors, thermal integration procurement leads, Bureau of Energy compliance officers, and dielectric fluid chemistry specialists — were reconciled against secondary validation from customs trade data, hyperscaler capex disclosures, and National Communications Commission equipment certification records. Primary interviews with data center operators and cooling infrastructure vendors informed capacity expansion timelines and technology migration patterns. Bottom-up installation forecasts triangulated against top-down Bureau of Energy efficiency mandate compliance projections.
Historical deployment trajectories cross-referenced against expert panel input on GPU thermal design power roadmaps and substation capacity upgrade cycles shaped the analytical framework. Segmentation dimensions modeled include cooling architecture type, deployment model scale tier, end-user industry vertical, and regional grid constraint severity across the analysis window. CAGRs derived from facility commissioning pipelines, foundry co-location density projections, and liquid cooling adoption curves in AI training clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility for copper and nickel alloys, export control friction on dielectric fluids, and accelerated substation capacity saturation in northern corridors. Periodic stress-testing of base assumptions is recommended given regulatory enforcement trajectory uncertainty and hyperscaler procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market