
 Machine Learning Operation Technology Market | 2026-2036
Machine Learning Operation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Learning Operation Technology Market Insights
Containerized infrastructure is realigning MLOps economics as Kubernetes-native orchestration replaces monolithic model-serving architectures. Microsoft leverages its Azure ML platform to anchor enterprise workflows across hybrid environments. Amazon competes through SageMaker's integrated feature store and model monitoring stack. Google differentiates via TensorFlow Extended and custom TPU serving infrastructure that sustains inference cost advantages at scale.
Machine Learning Operation Technology encompasses the toolchain, workflows, and governance frameworks required to deploy, monitor, and retrain ML models in production environments, typically incorporating CI/CD pipelines for models, automated drift detection, and experiment tracking with sub-second inference latency requirements. Its primary purpose is bridging the gap between data science experimentation and reliable, scalable business operations. Cloud-based deployment leads in revenue contribution as enterprises prioritize elastic compute for training workloads, while edge computing segments expand fastest in manufacturing and telecommunications where low-latency inference at the point of data generation reduces bandwidth costs and regulatory exposure. Predictive maintenance applications command concentrated investment in industrial settings, though natural language processing pipelines show accelerating adoption as generative model operationalization matures.
The EU AI Act and GDPR impose documentation, explainability, and human-oversight requirements that directly shape MLOps product roadmaps and procurement criteria for vendors serving European enterprises. FDA guidance on AI-enabled medical devices in the United States drives healthcare end users toward validated, auditable model lifecycle platforms. ISO standards for AI management systems create baseline compliance expectations that influence vendor qualification across regulated industries. Stakeholders must evaluate whether their current tooling stacks can absorb emerging regulatory mandates without fragmenting operational workflows or inflating total cost of ownership.
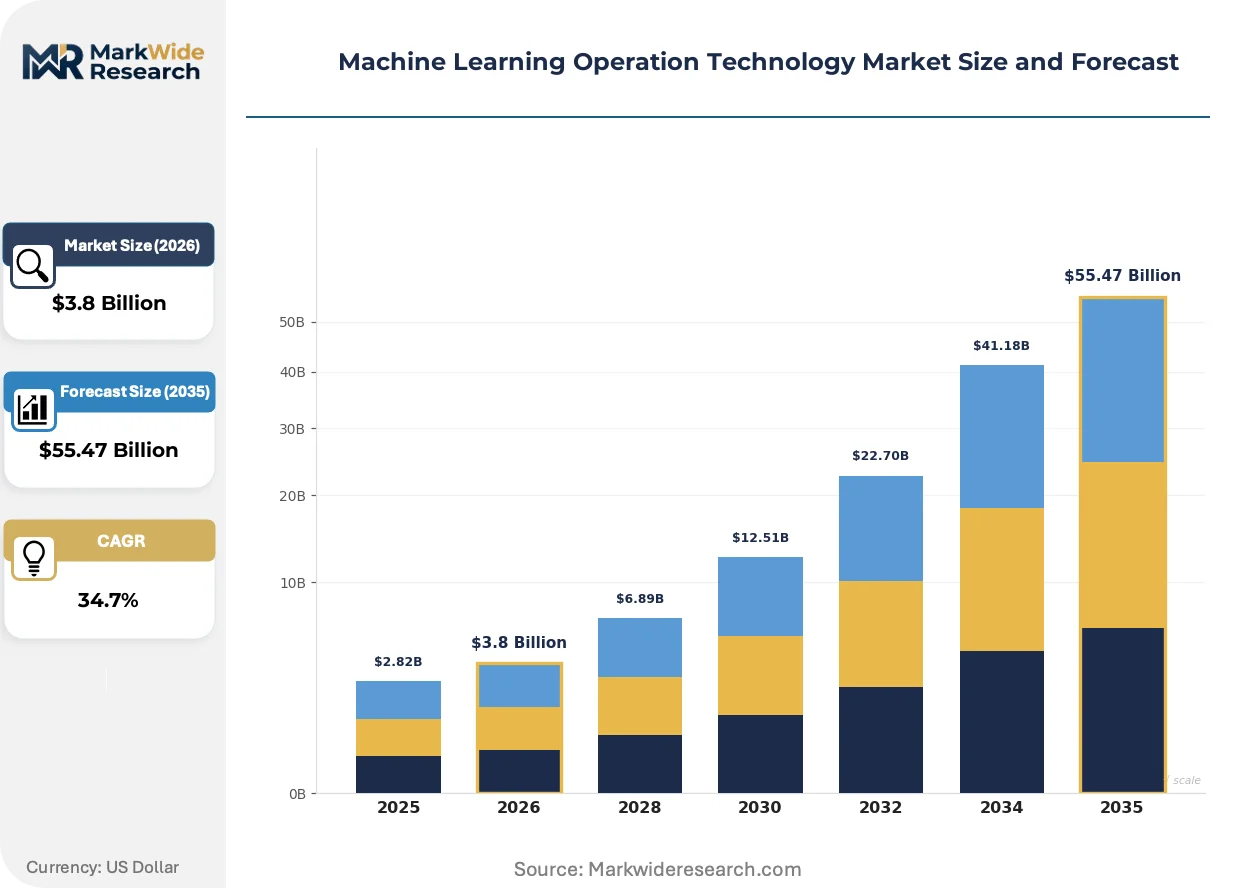
Market Dynamics
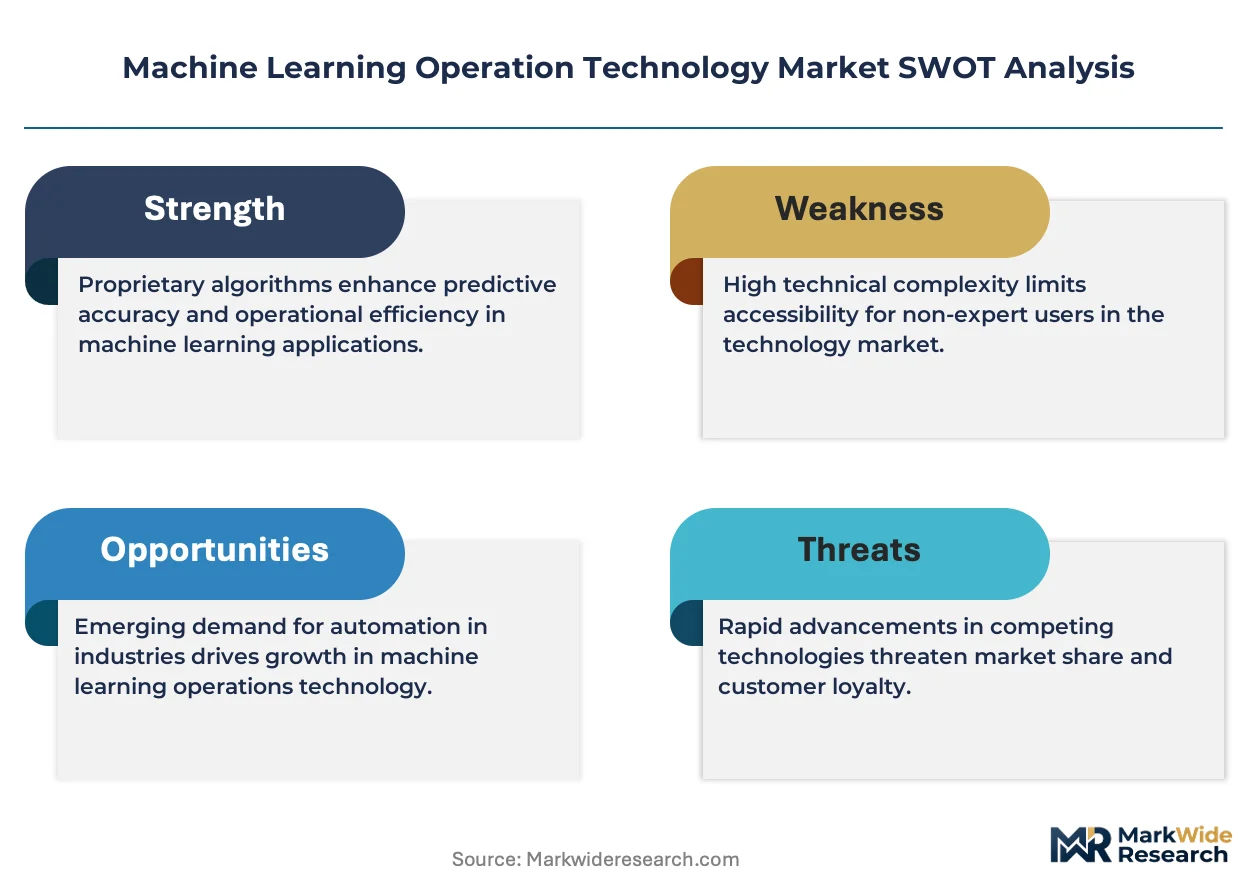
Kubernetes-native orchestration is compressing infrastructure costs and redefing competitive positioning as containerized model-serving displaces monolithic architectures across enterprise ML pipelines.
Growth Catalysts
- EU AI Act Documentation Mandates:European financial institutions must operationalize auditable model lineage, accelerating procurement of governance-integrated MLOps platforms.
- Edge Computing Convergence:Manufacturing and telecommunications sectors deploy inference-optimized pipelines at data generation points to eliminate bandwidth costs and reduce regulatory exposure.
- Healthcare Validation Requirements:FDA guidance on AI-enabled medical devices pushes hospitals toward validated, auditable model lifecycle management systems.
Market Restraints
- Specialized Talent Scarcity:Shortage of ML engineers with production systems expertise inflates implementation timelines and consulting dependency.
- Cloud Vendor Lock-in:Deep integration with proprietary feature stores and serving infrastructure raises switching costs and fragments multi-cloud strategies.
- GPU Supply Concentration:Inference and training hardware availability remains constrained by Taiwan and South Korea foundry capacity.
Strategic Opportunities
- Generative Model Operationalization:Large language model deployment pipelines represent underdeveloped tooling territory for observability and cost governance.
- ISO 42001 Alignment Services:AI management system certification creates consulting and software bundling opportunities for compliance-focused vendors.
- Feature Store Unification:Real-time and batch feature engineering convergence enables new product categories bridging data warehouse and serving layers.
Industry Challenges
- Experiment-to-Production Translation:Data science workflows lack standardized handoff protocols, causing model decay and reliability failures in live environments.
- Multi-Cloud Integration Complexity:Enterprises struggle to maintain consistent governance across Azure ML, SageMaker, and Vertex AI deployments without workflow fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Learning Operation Technology Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $55.47 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: Supervised Learning, Unsupervised Learning, Reinforcement Learning, Neural Networks Application: Fraud Detection, Predictive Maintenance, Image Recognition, Natural Language Processing End User: Healthcare, Manufacturing, Retail, Telecommunications |
| Companies Covered | Microsoft, Amazon, IBM, Google, DataRobot, SAS, Dataiku, Databricks, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Learning Operation Technology Market Trends and Innovations
Observability tooling is converging with governance frameworks as real-time model monitoring becomes inseparable from regulatory compliance workflows.
Vector database infrastructure is consolidating retrieval-augmented generation pipelines into unified serving stacks. Financial services and healthcare providers adopt these systems to ground large language model outputs in proprietary data without fine-tuning overhead. The technology is compressing time-to-deployment for domain-specific AI applications from quarters to weeks.
CSRD sustainability reporting requirements in Europe mandate carbon footprint disclosure for AI training workloads. Data center operators and cloud providers now embed emissions tracking directly into MLOps dashboards. German automotive and French luxury goods manufacturers lead procurement criteria that prioritize energy-transparent model training.
Buyers increasingly unbundle model monitoring from end-to-end platforms, selecting best-of-breed drift detection and explainability tools. Systems integrators and boutique consultancies capture implementation revenue that platform vendors previously monopolized. This pattern concentrates in United States enterprises with mature data engineering functions and multi-vendor tolerance.
Machine Learning Operation Technology Market Segmentation
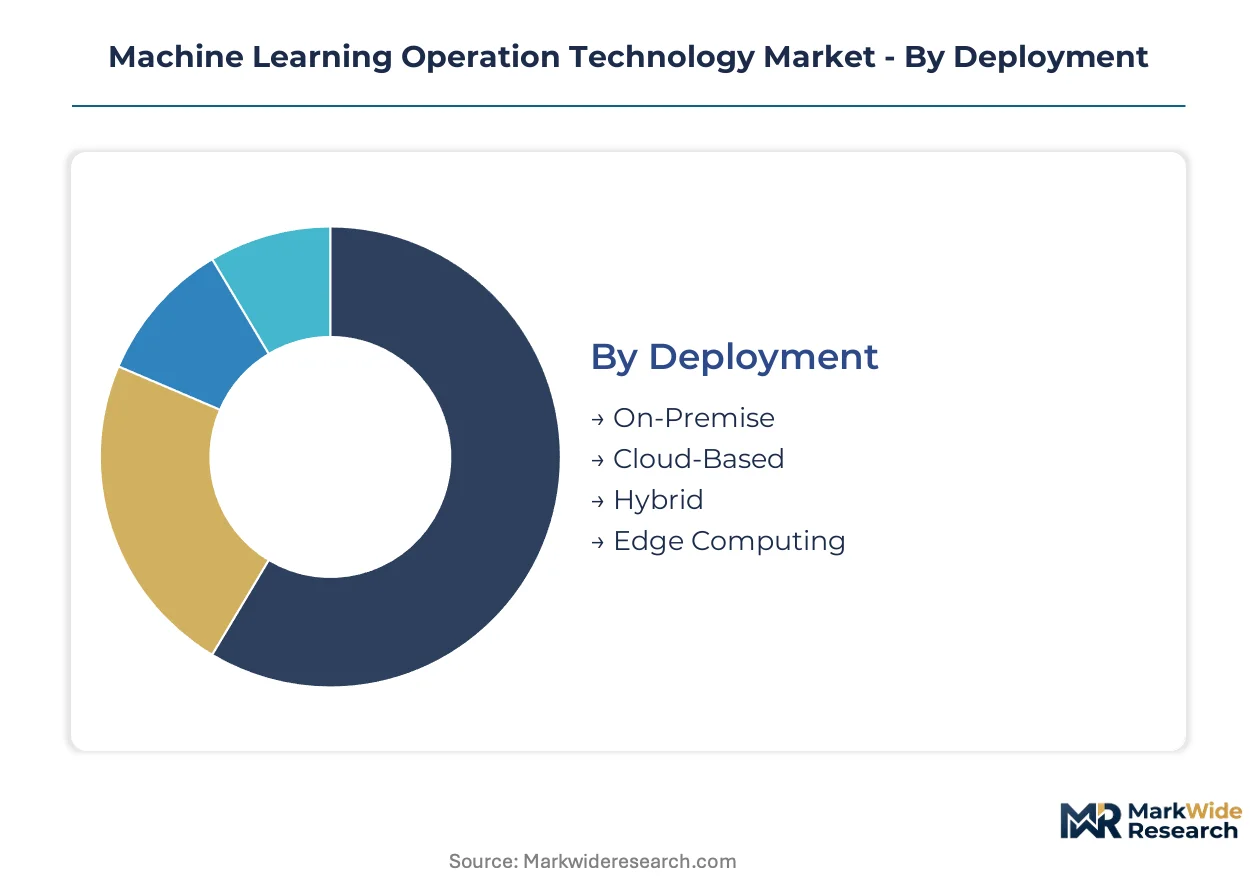
MLOps procurement patterns diverge sharply across deployment modes and application contexts, with regulatory pressure and latency requirements dictating infrastructure choices. Understanding these segment boundaries clarifies where vendor specialization yields pricing power versus where commoditization erodes margins.
Deployment:
Supply concentration in hyperscale cloud infrastructure is compressing margins for on-premise hardware vendors while creating captive demand for hybrid orchestration tools.
- Cloud-Based:Elastic compute provisioning dominates training workload economics, with financial services firms in the United States prioritizing pay-as-you-scale consumption models to align ML infrastructure costs with model revenue generation. The EU AI Act's audit trail requirements are accelerating procurement of governance-integrated cloud platforms that embed lineage tracking by default.
- Edge Computing:Inference-optimized pipelines deployed at manufacturing floors and telecommunications base stations eliminate bandwidth costs and reduce cross-border data transfer exposure under GDPR. German automotive suppliers and South Korean electronics manufacturers lead capital deployment for sub-50ms latency requirements in quality inspection and predictive maintenance workflows.
- On-Premise:Defense contractors and classified research facilities mandate air-gapped model training environments with sovereign data control.
- Hybrid:Enterprises with legacy data center investments bridge cloud burst capacity and on-premise governance for sensitive feature stores.
Cloud-Based deployments absorb the bulk of installed capacity; Edge Computing is expanding most quickly.
Technology:
Cost tier differentiation separates commoditized supervised learning tooling from premium pricing attached to reinforcement learning infrastructure for real-time decision systems.
- Neural Networks:Deep learning operationalization commands premium platform fees due to GPU cluster orchestration complexity and distributed training fault tolerance requirements. Healthcare imaging networks in the United States and computer vision deployments in Chinese manufacturing anchor demand for automated hyperparameter tuning and model parallelism management.
- Supervised Learning:Mature CI/CD integration and standardized drift detection have compressed pricing power for tabular model deployment, though regulatory documentation requirements in European banking sustain maintenance revenue streams.
- Unsupervised Learning:Anomaly detection pipelines for fraud and cybersecurity applications require specialized observability tooling for non-stationary data distributions.
- Reinforcement Learning:Robotics and autonomous system training demands simulation-to-reality transfer tooling with sparse reward signal optimization.
Supervised Learning retains the largest installed base; Reinforcement Learning is climbing the fastest as robotics operationalization matures.
Application:
Customer type stratification concentrates investment in applications where model failure carries regulatory or safety consequences, insulating pricing from pure efficiency competition.
- Fraud Detection:Real-time transaction scoring in banking and insurance demands sub-100ms inference with explainability mandates under the EU AI Act's prohibited practice provisions. United States card networks and European neobanks anchor procurement of integrated feature stores and model monitoring stacks that link drift detection to automated retraining triggers.
- Predictive Maintenance:Industrial asset health forecasting in German automotive and Japanese heavy machinery manufacturing compresses unplanned downtime costs, with edge-deployed vibration and thermal sensors feeding centralized model refinement pipelines.
- Image Recognition:Medical device validation under FDA guidance and quality inspection in semiconductor fabrication drive auditable model lifecycle requirements.
- Natural Language Processing:Generative model deployment pipelines for customer service and document processing remain underdeveloped in observability tooling, creating implementation risk.
Fraud Detection commands concentrated platform investment; Natural Language Processing is gaining share fastest as large language model operationalization accelerates.
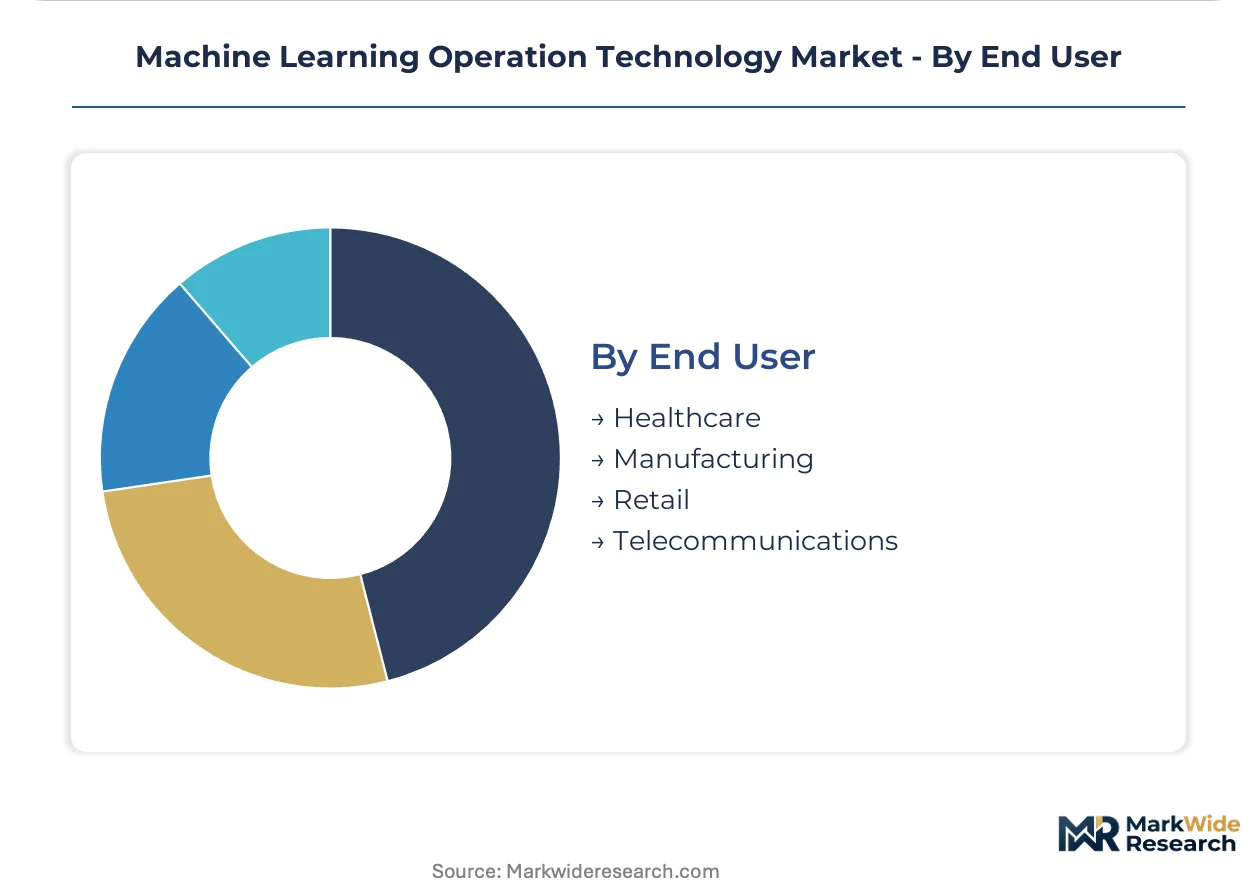
End User:
Volume concentration in manufacturing creates procurement scale advantages, while margin protection in healthcare derives from validation complexity and regulatory capture.
- Healthcare:FDA guidance on AI-enabled medical devices mandates design controls and post-market surveillance that only validated MLOps platforms can satisfy, insulating qualified vendors from price competition. United States hospital networks and German medical device manufacturers anchor demand for ISO 13485-aligned model lifecycle management with automated documentation generation.
- Manufacturing:Predictive maintenance and quality inspection at scale create the largest addressable seat count for MLOps platforms, with German automotive and Chinese electronics clusters driving standardization around OPC-UA data integration and edge-to-cloud model synchronization.
- Retail:Demand forecasting and personalization engines prioritize experimentation velocity over governance depth, compressing pricing.
- Telecommunications:Network optimization and customer churn prediction balance latency requirements with regulatory data localization mandates.
Manufacturing absorbs the bulk of platform deployments; Healthcare is expanding most quickly as diagnostic AI validation requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprises absorb the largest share of MLOps platform spending, driven by cloud infrastructure maturity and venture capital availability that accelerates deployment velocity. Regulatory pressure from the FDA and SEC shapes procurement criteria across financial services and healthcare verticals.
United States
Financial services firms in New York and San Francisco deploy governance-integrated platforms to automate model compliance under SEC oversight. FDA guidance on AI-enabled medical devices pushes Boston and Research Triangle hospital networks toward validated lifecycle management systems. The Bay Area's cloud-native startups anchor demand for Kubernetes-native orchestration tools.
Germany
Automotive manufacturers in Stuttgart and Munich drive edge-computing deployments for predictive maintenance with sub-50ms latency requirements. The EU AI Act's documentation mandates accelerate procurement of auditable lineage tracking systems. Industrial clusters in Bavaria and Baden-Württemberg standardize around OPC-UA data integration for quality inspection pipelines.
China
Electronics manufacturers in Shenzhen and semiconductor fabricators in Shanghai invest heavily in computer vision operationalization at scale. MIIT standards for AI management systems create baseline compliance expectations for domestic vendors. The Yangtze River Delta anchors demand for automated hyperparameter tuning and distributed training fault tolerance.
United Kingdom
London-based neobanks and insurance technology firms prioritize real-time fraud detection with explainability mandates under FCA supervision. The Information Commissioner's Office enforces GDPR-aligned data governance that shapes feature store procurement criteria. Cambridge and Oxford research corridors drive experimentation with retrieval-augmented generation pipeline consolidation.
South Korea
Electronics conglomerates in Seoul and Suwon deploy inference-optimized pipelines for manufacturing quality control. The MFDS regulates AI-enabled medical device software, pushing healthcare providers toward ISO 13485-aligned platforms. The Busan-Ulsan industrial corridor leads capital deployment for vibration-sensor-to-cloud model synchronization.
Machine Learning Operation Technology Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers commanding the training workload tier while boutique consultancies capture implementation revenue from unbundled monitoring tools. The vendor base concentrates around three strategic archetypes: infrastructure-anchored platforms with hybrid orchestration capabilities, best-of-breed observability specialists, and systems integrators bridging multi-cloud governance gaps. Dominant competitive moves include strategic partnerships between feature store vendors and data warehouse providers, plus geographic expansion through ISO 42001 certification services in European markets.
Within the infrastructure-anchored tier, Microsoft and Amazon exemplify platform consolidation strategies, with the former leveraging Azure ML for hybrid environment dominance and the latter integrating SageMaker's feature store with model monitoring stacks. Databricks occupies a position as the independent alternative for enterprises pursuing multi-cloud tolerance without vendor lock-in.
| Leading Market Players |
|---|
| Microsoft |
| Amazon |
| IBM |
| DataRobot |
| SAS |
| Dataiku |
| Databricks |
| Hewlett Packard Enterprise |
| Others |
Pricing and Supply Chain Analysis
Horizontal platform consolidation anchors supply positioning and pricing power as hyperscale cloud providers absorb orchestration tooling into bundled infrastructure stacks. Microsoft and Amazon leverage captive feature store and model monitoring capabilities to sustain premium pricing for governance-integrated suites, while specialized observability vendors face margin compression from unbundling trends.
Pricing Analysis
Volume concentrates in standardized supervised learning pipelines where SaaS-tiered subscriptions have compressed margins, while premium pricing persists for GPU-orchestrated neural network deployments with automated hyperparameter tuning and distributed training fault tolerance. Price differentiation rests on ISO 42001 certification alignment and EU AI Act audit trail depth. Pricing pressure intensifies in the mid-market as Databricks and independent alternatives erode proprietary platform premiums. Healthcare and financial services buyers show lowest price sensitivity due to FDA and SEC validation requirements, while retail personalization engines prioritize experimentation velocity over governance depth.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundry capacity for GPU training and inference hardware, constraining availability for enterprise ML infrastructure scaling. The supply chain draws from United States cloud hyperscalers, Chinese electronics manufacturers, and German industrial automation specialists for edge deployment components. Raw material dependencies include advanced semiconductors, high-bandwidth memory modules, and specialized cooling systems for data center clusters. Tariff exposure on Chinese-manufactured edge computing hardware elevates landed costs for telecommunications and manufacturing buyers. Distribution runs through direct enterprise sales teams, systems integrators, and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Machine Learning Operation Technology Market functions as a cost-of-compliance arena where EU AI Act documentation mandates erect barrier-to-entry moats for vendors with pre-integrated governance tooling. Incumbents possessing validated lineage tracking and automated audit generation capture pricing premiums that unbundled specialists cannot match.
For Market Incumbents: To counter unbundling pressure from best-of-breed drift detection and explainability tools, deepen integration between feature stores and data warehouse layers to restore platform stickiness. Invest in ISO 42001 certification services for European expansion, capturing consulting revenue that boutique competitors forfeit. Prioritize generative model observability tooling development before specialized entrants consolidate retrieval-augmented generation pipeline segments.
For New Entrants and Emerging Players: Capture white-space in edge-computing inference optimization for German automotive and South Korean electronics manufacturing clusters where sub-50ms latency requirements remain underserved by cloud-native incumbents. Target natural language processing pipeline observability for financial services neobanks in the United Kingdom facing FCA explainability mandates. Lead with carbon footprint disclosure dashboards to exploit CSRD sustainability reporting requirements in European procurement criteria.
For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of specialized observability firms and private equity rollup of fragmented systems integrators. Long-term viability favors vendors with healthcare FDA validation or financial services SEC compliance integration that insulates recurring revenue from pure efficiency competition. Monitor generative model deployment failure rates as an inflection signal for observability tooling demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Feature store unification with data warehouse layers restores stickiness against unbundling. |
| Geographic Expansion | ISO 42001 certification services in Germany and France capture EU AI Act compliance spending. |
| Acquisition of Specialist Firm | Vector database and retrieval-augmented generation tooling consolidates generative AI infrastructure. |
| Product Launch | Carbon footprint tracking dashboards align with CSRD mandates for German automotive procurement. |
| Strategic Partnership | OPC-UA data integration alliances with industrial automation vendors penetrate manufacturing verticals. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with MLOps platform engineers, healthcare biomedical informatics directors, financial services model risk officers, and industrial IT procurement leads validated deployment patterns and pricing dynamics. Bottom-up triangulation across cloud marketplace transaction data and top-down reconciliation against enterprise software spending benchmarks anchored volume estimates.
Bottom-up modeling of deployment mode, technology type, application context, and end-user industry dimensions generated segment-level projections across the analysis window. Top-down cross-checks against aggregate enterprise AI infrastructure spending ensured consistency with macro technology budget trends. CAGRs derived from regression analysis of historical adoption curves, adjusted for regulatory inflection points including EU AI Act implementation timelines and FDA guidance publication cycles. Generative model operationalization maturity and edge computing latency requirements served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GPU supply chain disruptions, Taiwan geopolitical developments, and European regulatory enforcement intensity. Assumptions regarding cloud migration velocity and multi-cloud tolerance patterns shape trajectory uncertainty. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Machine Learning and Data Science
Cloud Machine Learning Market
Machine Learning and Data Science
Speech-To-Text API Market
Machine Learning and Data Science
Machine Learning in Communication Market
Machine Learning and Data Science
Global Data Annotation Tools Market
Machine Learning and Data Science
AI and Advance Machine Learning in BFSI Market
Machine Learning and Data Science
Global Data Annotation Service Market
Machine Learning and Data Science
Europe Data Science Platform Market
Machine Learning and Data Science
Global Image Recognition in CPG Market
Machine Learning and Data Science
Asia-Pacific Machine Learning As a Service Market
Machine Learning and Data Science
Semantic Knowledge Discovery Software Market
Machine Learning and Data Science
Global Computational Creativity Market
Machine Learning and Data Science
Natural Language Processing Market
Machine Learning and Data Science
Global Machine Learning in Manufacturing Market
Machine Learning and Data Science
Global AI and Machine Learning Operationalization Software Market
Machine Learning and Data Science
Asia-Pacific Machine Learning in Pharmaceutical Industry Market
Machine Learning and Data Science
Automated Machine Learning Market