
 Data Center Infrastructure Management Market | 2026-2036
Data Center Infrastructure Management Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Infrastructure Management Market Intelligence
Uptime Institute Tier Certification for data center resiliency is bifurcating the vendor landscape between providers offering certified, high-availability solutions and those targeting less critical deployments. Schneider Electric leverages its integrated EcoStruxure platform to serve diverse operational requirements. Vertiv specializes in thermal and power management systems essential for maintaining stringent uptime standards. Siemens competes with its comprehensive building technology and automation portfolio tailored for complex data center environments.
Data Center Infrastructure Management (DCIM) encompasses the software and processes for monitoring and optimizing a data center's physical infrastructure. This involves real-time tracking of components like power distribution units (PDUs) and computer room air conditioners (CRACs) to improve operational efficiency. Energy Management and Cooling Optimization solutions are gaining prominence as operators seek to reduce power usage effectiveness (PUE) metrics. While on-premises remains a core deployment model, cloud-based and edge DCIM solutions are expanding rapidly to support colocation and distributed IT architectures.
The EU's Corporate Sustainability Reporting Directive (CSRD) compels European operators to adopt advanced DCIM for transparent energy and carbon accounting. In the United States, guidance from ASHRAE and the EPA's Energy Star for Data Centers program influences procurement specifications for federal and commercial clients. Globally, the ISO/IEC 30134 series provides standardized key performance indicators for data center resource efficiency. Stakeholders must decide how to balance investments in AI-driven DCIM platforms against the immediate costs of regulatory compliance and hardware upgrades.
Market Dynamics
The imperative for sustainable operations, driven by regulations and corporate ESG goals, is in direct tension with the escalating power and cooling demands of AI workloads. This conflict defines the current evolution of DCIM, forcing operators to seek more intelligent, automated infrastructure management tools.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) compels operators to implement granular energy tracking and carbon accounting, directly spurring adoption of advanced DCIM solutions for compliance and transparent reporting.
- Technological Workloads:The proliferation of AI and machine learning applications requires high-density server racks that demand sophisticated, real-time thermal and power management, which is a core capability of modern DCIM platforms.
- Financial Services Demand:The financial services industry's stringent requirements for uptime, security, and operational resiliency create persistent demand for certified, high-availability data center environments managed through comprehensive DCIM software.
Market Restraints
- High Implementation Cost:The significant upfront capital investment required for DCIM software licenses, sensor deployment, and professional integration services acts as a primary adoption barrier for small to mid-sized data center operators.
- Legacy System Integration:Integrating modern DCIM platforms with a heterogeneous mix of older, proprietary facility equipment and existing IT management tools presents considerable technical complexity and project risk for many organizations.
- Cloud Management Substitution:For enterprises migrating to public cloud, the native infrastructure management tools offered by hyperscale providers can serve as a substitute for traditional on-premises DCIM, reducing the addressable market.
Strategic Opportunities
- Edge Computing Expansion:The growth of edge computing creates a new market for lightweight, distributed DCIM solutions capable of remotely monitoring and managing hundreds or thousands of geographically dispersed micro-data centers.
- Predictive Analytics (AIOps):Integrating artificial intelligence and machine learning into DCIM platforms to enable predictive maintenance and autonomous optimization represents a significant value-add opportunity for vendors.
- Underpenetrated Geographies:Emerging data center markets in regions such as Southeast Asia, Latin America, and Africa offer substantial growth potential as they build out new capacity that requires modern management infrastructure.
Industry Challenges
- Hybrid Skills Gap:A persistent shortage of professionals with combined expertise in facilities infrastructure (power, cooling) and IT systems management hinders the effective deployment and ongoing operation of DCIM systems.
- Interoperability Standards:The lack of universal communication protocols across equipment from different manufacturers complicates data aggregation, limits automation capabilities, and can lead to vendor lock-in for data center operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Infrastructure Management Market |
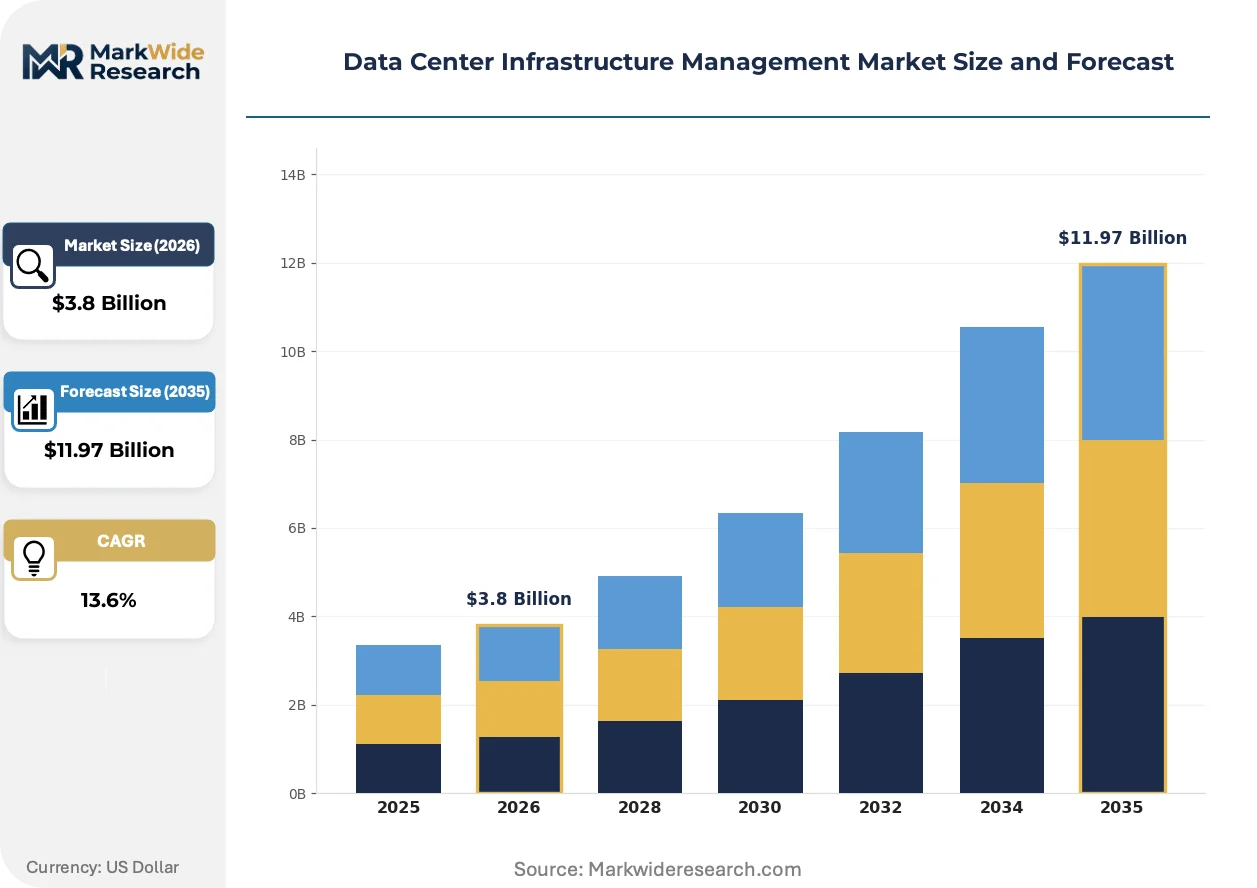
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge, Colocation Solution Type: Asset Management, Capacity Planning, Energy Management, Security Management, Cooling Optimization Application: Data Analytics, Network Performance, Compliance Monitoring, Disaster Recovery, Resource Optimization End User Industry: Telecommunications, Government Agencies, Financial Services, E-Commerce, Academia |
| Companies Covered | Schneider Electric, Vertiv, Johnson Controls, Eaton, ABB, Delta Electronics, IBM, Siemens, Panduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Infrastructure Management Market Strategic Shifts & Innovations
Automation and sustainability are fundamentally reshaping data center management. The focus is shifting from passive monitoring to proactive, AI-guided optimization, driven by both regulatory pressures for efficiency and the operational demands of next-generation computing hardware.
AI-driven predictive analytics platforms utilize machine learning to process real-time data from power and cooling infrastructure. Hyperscale and large enterprise operators are adopting these systems to forecast equipment failures and optimize energy consumption. This proactive, automated approach is supplanting reactive maintenance schedules that rely on fixed intervals or basic threshold alerts.
The ISO/IEC 30134 series of standards provides globally recognized key performance indicators for benchmarking data center resource efficiency. This framework promotes a common language for reporting metrics like Power Usage Effectiveness (PUE) and Water Usage Effectiveness (WUE). Consequently, colocation clients and enterprise customers increasingly specify compliance with these ISO standards within procurement requirements and service level agreements.
A discernible shift from perpetual on-premises software licenses toward subscription-based, cloud-hosted DCIM is occurring. This model lowers initial capital expenditure and simplifies management for organizations with distributed IT assets, including colocation and edge sites. The change is most visible among mid-sized enterprises in North America and Europe looking for scalable monitoring capabilities without managing local server infrastructure.
Data Center Infrastructure Management Market Segmentation
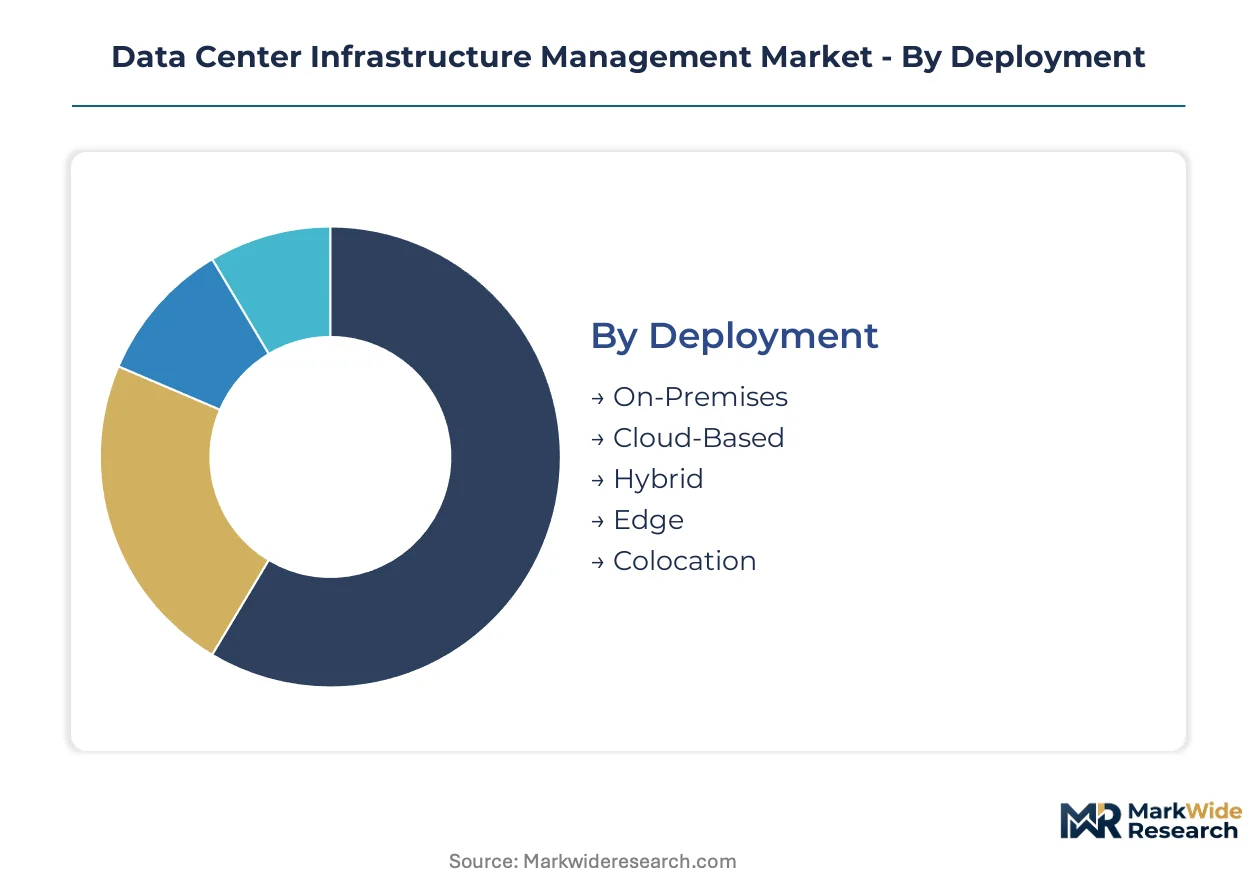
The Data Center Infrastructure Management market segments illuminate distinct operational approaches and specialized solution requirements. Understanding these divisions helps stakeholders tailor investments to specific infrastructure models, technological needs, and industry-specific compliance mandates.
Deployment:
Regulatory frameworks increasingly differentiate data center infrastructure management requirements based on deployment models, influencing compliance and operational oversight.
- Cloud-Based:Cloud-Based DCIM solutions are delivered as software-as-a-service, providing remote monitoring and management capabilities without local infrastructure. Demand concentrates in mid-sized enterprises across Europe and North America seeking scalable, cost-efficient solutions for distributed IT assets.
- On-Premises:On-Premises deployments involve DCIM software and hardware installed directly within a data center's physical facility, offering maximum control and customization. Financial services and government agencies prioritize on-premises models for stringent security protocols and data sovereignty requirements.
- Hybrid:This model combines on-premises and cloud elements, balancing granular control with the flexibility and scalability of cloud services.
- Edge:Lightweight DCIM solutions designed for geographically dispersed micro-data centers, critical for supporting IoT and low-latency applications.
- Colocation:DCIM tailored for multi-tenant facilities, providing tenants and providers with visibility into shared and dedicated infrastructure.
On-Premises deployments handle the majority of throughput; Cloud-Based solutions are the fastest mover on share.
Solution Type:
DCIM solution types are engineered to address specific operational challenges within data centers, from hardware tracking to environmental control.
- Energy Management:Energy Management solutions monitor power consumption at various levels, from rack to facility, providing granular data for efficiency analysis. Demand is intensifying across European operators compelled by the EU's CSRD to transparently report energy usage and carbon emissions.
- Cooling Optimization:Cooling Optimization systems utilize real-time data from CRACs and other cooling infrastructure to maintain optimal temperatures and airflow within data centers. Hyperscale facilities supporting AI workloads require advanced cooling optimization to prevent overheating and ensure uptime.
- Asset Management:This solution tracks physical IT and facility assets, including their location, status, and interconnections within the data center.
- Capacity Planning:Capacity Planning forecasts future resource needs for power, space, and cooling to prevent both over-provisioning and resource shortages.
- Security Management:This type of solution monitors physical access, environmental conditions, and potential cybersecurity threats affecting data center infrastructure.
Energy Management and Cooling Optimization solutions directly impact operational sustainability and cost efficiency for data center operators.
Application:
DCIM applications deliver distinct value propositions, enhancing operational intelligence and resilience across data center environments.
- Data Analytics:Data Analytics applications leverage collected DCIM data to identify patterns, predict failures, and generate actionable insights for proactive management. Adoption is accelerating among large enterprises seeking AI-driven predictive maintenance and operational efficiency gains.
- Resource Optimization:Resource Optimization applications automate the allocation and utilization of power, space, and cooling resources within the data center, maximizing operational efficiency. This application is critical for hyperscale and colocation providers managing vast and complex infrastructure.
- Network Performance:This application monitors the health, utilization, and traffic flow of network infrastructure within the data center environment.
- Compliance Monitoring:Compliance Monitoring ensures adherence to regulatory standards like the ISO/IEC 30134 series and internal operational policies.
- Disaster Recovery:This application facilitates the planning, simulation, and execution of recovery strategies for critical data center functions during unforeseen events.
Data Analytics applications are increasingly strategic for competitive differentiation, while Resource Optimization remains fundamental to cost control.
End User Industry:
End-user industries adopt DCIM based on their unique operational demands, regulatory pressures, and data processing requirements.
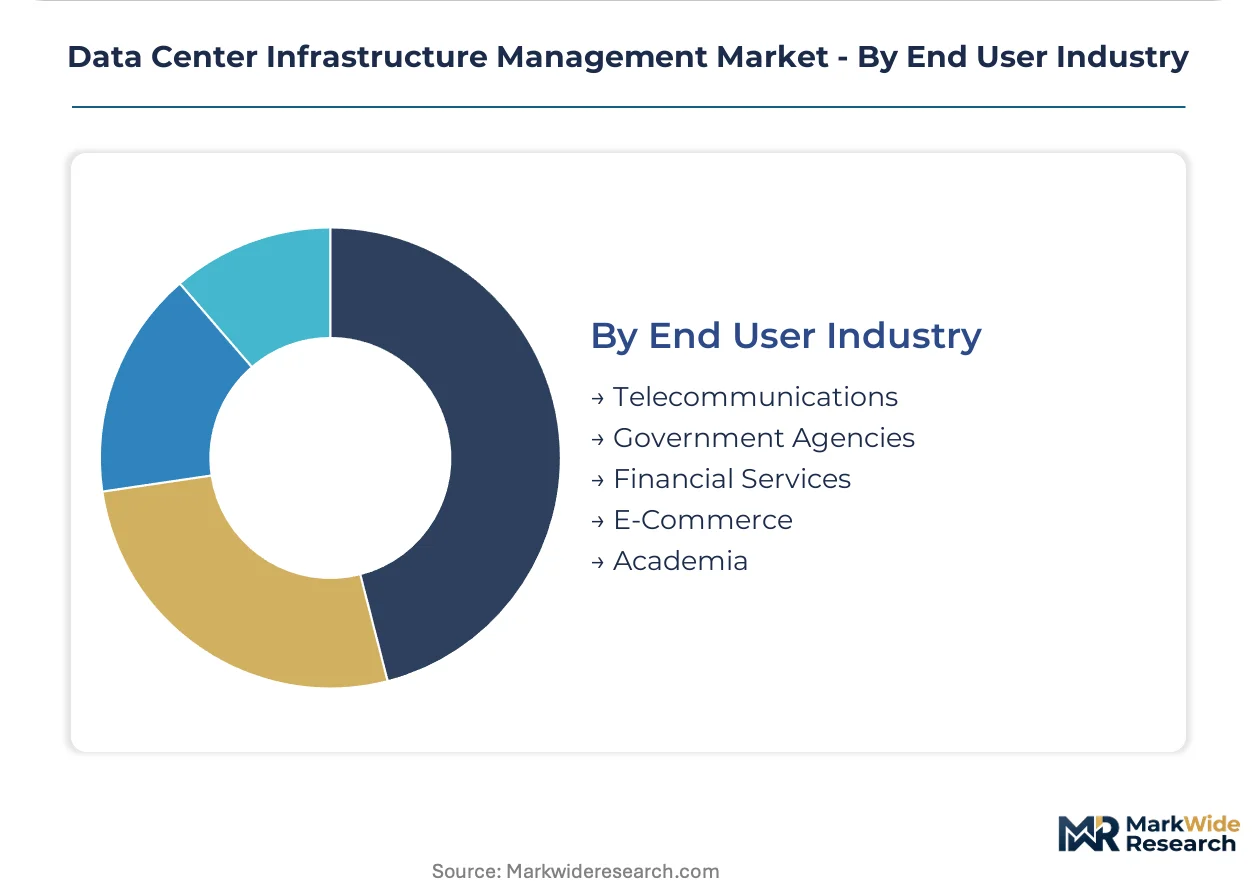
- Financial Services:The Financial Services industry requires DCIM for its extreme uptime demands, robust security protocols, and stringent regulatory compliance. Banks and trading firms invest in high-availability DCIM to prevent outages that could lead to significant financial losses.
- Telecommunications:Telecommunications providers deploy DCIM to manage vast, distributed networks of data centers and edge facilities, ensuring continuous service delivery. The industry prioritizes remote monitoring and energy efficiency for its extensive infrastructure footprint.
- Government Agencies:These agencies utilize DCIM for secure data management, energy efficiency, and compliance with federal and national guidelines.
- E-Commerce:The E-Commerce sector relies on DCIM to maintain website availability, optimize infrastructure, and manage fluctuating consumer demand.
- Academia:Academic institutions employ DCIM for managing research computing clusters and ensuring stable environments for scientific and educational workloads.
Financial Services and Telecommunications represent core demand segments, driven by critical uptime requirements and extensive infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for Data Center Infrastructure Management solutions centers on financial services and hyperscale operators. These entities require robust infrastructure oversight for critical uptime and security. Regulatory compliance and the demands of AI workloads further influence regional market dynamics.
United States
Demand for DCIM solutions in the United States stems from extensive hyperscale data center development and a large financial services sector. The EPA's Energy Star for Data Centers program influences procurement specifications for federal and commercial clients. Northern Virginia, a major data center hub, sees intensive adoption of advanced DCIM for managing massive power and cooling demands.
Germany
German enterprises prioritize DCIM for optimizing energy efficiency and ensuring data sovereignty. The EU's Corporate Sustainability Reporting Directive (CSRD) compels operators to implement granular energy tracking and carbon accounting. Data center clusters in Frankfurt, a key internet exchange point, leverage DCIM for complex power and thermal management.
Singapore
Singapore's dense urban environment and strategic location drive demand for high-density, energy-efficient data centers. The country's Green Data Centre Roadmap encourages sustainable practices, spurring DCIM adoption. Hyperscale facilities around Jurong and Punggol require sophisticated DCIM for cooling optimization in a tropical climate.
Ireland
Irish data centers, particularly those serving large technology companies, focus on scalable and resilient infrastructure management. European Union regulations, including GDPR, necessitate stringent data governance which DCIM supports. Dublin's numerous hyperscale sites utilize DCIM platforms to manage complex power distribution and environmental controls.
Japan
Japanese financial institutions and cloud providers seek DCIM for high-availability systems and disaster recovery planning. METI guidance promotes energy-efficient data center operations, favoring advanced monitoring tools. Tokyo and Osaka's data center markets integrate DCIM for precise resource allocation and operational resilience.
Data Center Infrastructure Management Market Key Industry Players
Player mix skews toward established technology conglomerates and specialized infrastructure providers. The market exhibits a tiered structure, separating vendors offering comprehensive, integrated platforms from those focusing on niche solutions. Strategic archetypes include full-stack DCIM providers and hardware-centric specialists. Companies pursue portfolio diversification and strategic partnerships to enhance their offerings in a dynamic environment.
Specialists in thermal and power management, such as Vertiv, exemplify the hardware-centric approach to DCIM, crucial for maintaining stringent uptime standards. Integrated platform providers like Schneider Electric leverage extensive portfolios to serve diverse operational requirements, often through their EcoStruxure platform. Siemens also occupies a position among comprehensive building technology and automation providers, tailoring solutions for complex data center environments.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Johnson Controls |
| Eaton |
| ABB |
| Delta Electronics |
| IBM |
| Siemens |
| Panduit |
| Others |
Cost & Logistics Intelligence
Data center capacity utilization, driven by escalating AI workloads, shapes both supply concentration and downward pressure on price floors for DCIM solutions. Hyperscale operators demand sophisticated, integrated platforms at competitive rates, influencing the broader market's value proposition.
Pricing Analysis
Cost-plus contract patterns, often indexed to project scope and system complexity, govern many DCIM platform implementations. Price differentiation stems from the level of Uptime Institute Tier Certification supported and the extent of customization required for specific data center environments. Pricing pressure stems from the increasing availability of cloud-based DCIM alternatives and the high upfront implementation costs. Financial services and hyperscale operators demonstrate lower price sensitivity due to critical uptime requirements, unlike smaller colocation facilities.
Supply Chain Analysis
Just-in-time inventory strategies are common for standard DCIM hardware components, though strategic stockpiles of specialized power electronics and sensors are maintained by larger vendors. Component supply concentrates in East Asia, particularly China, for semiconductors and specialized sensors critical to DCIM hardware. Raw material dependencies include rare earth elements for advanced circuitry and various metals for power distribution units. Geopolitical tensions represent a structural supply chain risk. Distribution runs through a mix of direct sales to large enterprises and a network of system integrators for mid-sized clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Center Infrastructure Management market presents a defensive-moat story, primarily due to the regulatory entrenchment driven by directives like the EU's CSRD and high switching costs associated with integrating complex infrastructure.
For Market Incumbents: Fortify core platform capabilities by investing heavily in AI-driven predictive analytics and autonomous optimization features. Deepen vertical integration into specialized hardware components to mitigate single-source vulnerabilities and enhance system performance. Expand certification investments to meet evolving global standards like ISO/IEC 30134, countering the threat of cloud management substitution for critical on-premises deployments.
For New Entrants and Emerging Players: Service-layer gaps in lightweight, distributed DCIM solutions for edge computing environments offer significant entry points. Target mid-sized enterprises in underpenetrated geographies like Southeast Asia and Latin America, which seek scalable, cost-efficient monitoring. A go-to-market angle focusing on subscription-based, cloud-hosted platforms with rapid deployment capabilities can gain traction.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-based DCIM providers offering comprehensive compliance and sustainability reporting features. Long-term viability rests on the market's fundamental need to manage escalating AI power demands and stringent regulatory mandates. Acquire niche AI/ML analytics firms or specialized edge DCIM developers. The signal to watch is the consistent reduction in reported Power Usage Effectiveness (PUE) metrics across client portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Predictive Maintenance Integration | Enhances infrastructure reliability and reduces operational costs for hyperscale data centers. |
| Cloud-Native DCIM Platform Development | Expands market reach to distributed IT assets and offers scalable solutions for colocation clients. |
| Uptime Institute Certification Pursuit | Validates resiliency and attracts financial services clients with stringent uptime requirements. |
| Edge Computing DCIM Specialization | Captures demand from new micro-data center deployments supporting IoT applications. |
| ESG Reporting Automation Tools | Addresses regulatory compliance, such as the EU's CSRD, for transparent energy accounting. |
Research Approach
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, ASHRAE guidelines, EPA Energy Star program data, and ISO/IEC standards. This involved extensive interviews with data center operators, IT procurement managers, facilities engineers, and regulatory compliance officers. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy and market scope validation.
The analytical framework modeled segmentation dimensions including deployment model, solution type, application, end-user industry, and regional regulatory landscape. CAGRs were derived from historical trends, expert consensus, and projected technological advancements across the analysis window. Key forecast inputs included anticipated AI workload growth and the evolving impact of global sustainability regulations on infrastructure investment.
Forecasts assume regulatory continuity in regimes like the EU, US, and Japan; material policy shifts would require re-modeling. These projections reflect current market dynamics and technological trajectories. Revision becomes warranted when geopolitical disruptions or rapid technological obsolescence cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
New Zealand Data Center Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Underwater Data Center Market
Data Center Infrastructure
Switzerland Data Center Construction Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Physical Security Market