
 ELD Compliance Software Market | 2026-2036
ELD Compliance Software Market Size, Share, and Industry Trends Forecast 2026-2036
ELD Compliance Software Market Insights
Aftermarket service revenue is tilting toward integrated fleet management ecosystems as hardware margins compress. Samsara leverages its cloud-native architecture to bundle compliance with fuel analytics and safety scoring. Trimble anchors its position through ruggedized onboard devices tied to enterprise transportation management systems. Omnitracs competes via specialized compliance alerts and regulatory update services for multi-jurisdictional operators.
Electronic logging device compliance software automates hours-of-service recording through GPS-synchronized engine data capture, transmitting duty-status logs via cellular or satellite networks to fleet dispatch centers and enforcement databases. Cloud solutions and software platforms command expanding margin pools as carriers prioritize scalable SaaS architectures over capital-intensive onboard hardware installations. Fleet operators and logistics companies represent the deepest end-user demand, with real-time tracking and compliance alerts emerging as the most defensible feature differentiators against commoditized base-tier offerings.
The Federal Motor Carrier Safety Administration mandates ELD use for interstate commercial drivers, while Canada's CCMTA enforces parallel technical standards under the Canadian ELD mandate. State-level enforcement variations in the US create compliance complexity that elevates demand for automated regulatory update engines. Stakeholders must weigh the pace of FMCSA rule revisions against platform development cycles to avoid stranded technology investments.
Market Dynamics
Fleet digitization mandates are compressing replacement cycles as carriers face escalating FMCSA enforcement penalties and insurance underwriting requirements that penalize paper-based compliance systems.
Growth Catalysts
- FMCSA Hours-of-Service Enforcement:Interstate carriers must maintain electronic logs, forcing remaining paper-based operators to adopt certified platforms.
- Telematics Convergence:Engine-connected diagnostics now synchronize duty-status recording with fuel consumption analytics and predictive maintenance alerts.
- Canada:The CCMTA ELD mandate creates parallel compliance obligations for cross-border operators, expanding addressable fleet populations.
Market Restraints
- Hardware Margin Compression:Ruggedized onboard devices face commoditization as cellular module costs decline and Chinese manufacturers expand distribution.
- Cellular Connectivity Dependency:Rural route dead zones in the Mountain West and Northern Plains create synchronization gaps that trigger false violation flags.
- State Enforcement Variation:Inconsistent roadside inspection protocols across Texas, California, and New York generate compliance complexity that elevates platform support costs.
Strategic Opportunities
- Mexico:Absence of federal ELD requirements creates first-mover positioning for platforms pre-emptively serving US-owned cross-border fleets.
- Last-Mile Delivery:E-commerce parcel carriers need lightweight mobile solutions exempt from traditional heavy-duty hardware specifications.
- API-First Architecture:Open integration protocols enable carriers to embed compliance data directly into transportation management systems without proprietary middleware.
Industry Challenges
- Driver Interface Design:Complex menu navigation during roadside inspections increases violation risk and elevates training costs for high-turnover workforces.
- Retrofit Installation Bottlenecks:Older engine diagnostic ports lack standardized data protocols, forcing custom harness fabrication that delays fleet-wide deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ELD Compliance Software Market |
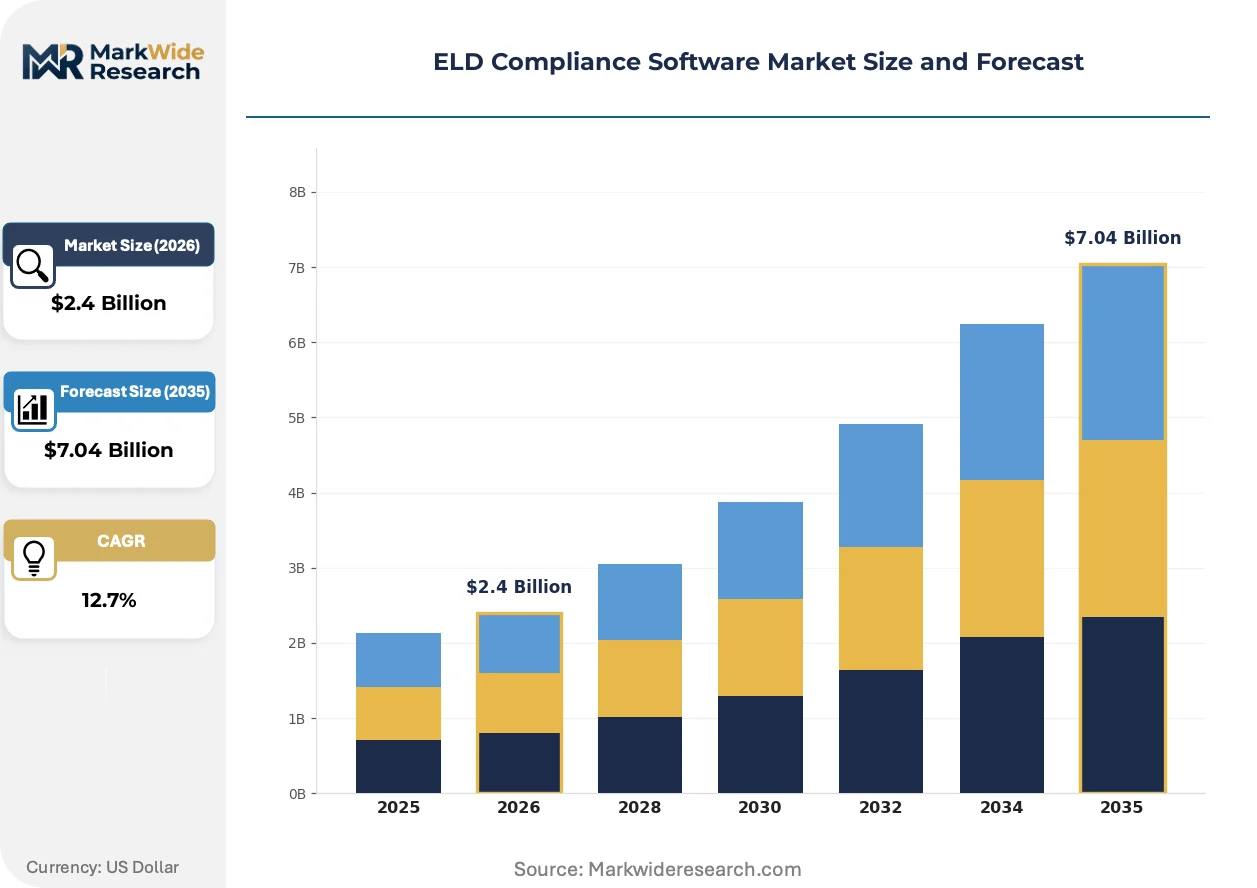
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.04 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onboard Devices, Mobile Applications, Cloud Solutions, Software Platforms End User: Fleet Operators, Independent Truckers, Logistics Companies, Transportation Services Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Feature: Real-Time Tracking, Data Analytics, Compliance Alerts, Driver Management |
| Companies Covered | Geotab, Samsara, Omnitracs, Teletrac Navman, Trimble, Verizon Connect, Motive, KeepTruckin, Zonar Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ELD Compliance Software Market Trends and Innovations
Cloud-native architectures are consolidating previously fragmented compliance, safety, and dispatch functions into unified fleet operating systems that reduce vendor management overhead.
Edge-computing onboard units with local data buffering are rendering obsolete satellite-dependent legacy systems that suffered latency gaps in cellular dead zones. Regional less-than-truckload carriers in the Appalachian corridor and Pacific Northwest are adopting these devices fastest. The shift compresses hardware refresh cycles from seven years toward four-year replacement schedules.
The FMCSA's pending automatic braking system integration rule will mandate synchronized event data recording alongside hours-of-service logs. This convergence forces platform vendors to recertify devices under expanded technical specifications. Long-haul refrigerated carriers operating temperature-controlled cargo face the steepest compliance recertification burdens.
Subscription pricing models now dominate procurement decisions as fleet operators reject capital-intensive hardware purchases. Asset-light trucking companies and third-party logistics providers are driving this transition fastest. The pattern is most visible among California-based freight brokers managing variable contract carrier networks.
ELD Compliance Software Market Segmentation
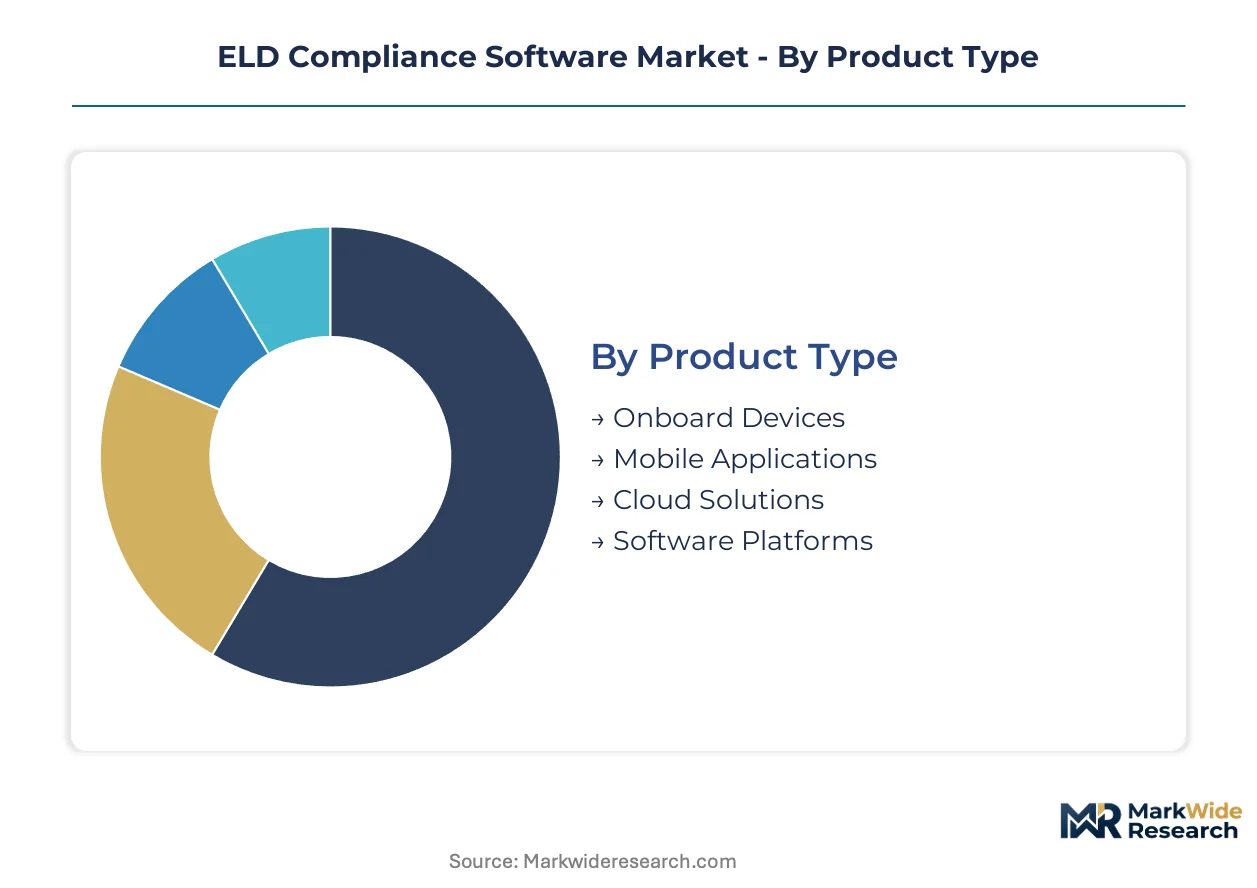
Segmentation in the ELD compliance software market reveals how carriers balance regulatory mandates against operational complexity. Fleet size, route geography, and existing technology infrastructure determine whether operators prioritize ruggedized hardware or lightweight mobile deployments.
Product Type:
Mature hardware formats now compete with emerging cloud-native architectures as carriers weigh capital expenditure against subscription flexibility.
- Onboard Devices:Ruggedized engine-connected units capture GPS-synchronized duty-status data through standardized diagnostic ports. Long-haul refrigerated carriers operating interstate routes favor these devices for their offline buffering capabilities during cellular dead zones in the Mountain West.
- Mobile Applications:Smartphone-based solutions leverage bring-your-own-device economics for smaller fleets and independent operators. Last-mile parcel carriers in urban corridors adopt these fastest, though FMCSA technical specifications limit their use to short-haul exemptions.
- Cloud Solutions:Centralized data repositories enable real-time log synchronization across distributed fleet networks.
- Software Platforms:Modular architectures integrate compliance functions with broader transportation management systems.
Onboard Devices retain volume leadership; Mobile Applications hold the steepest expansion curve.
End User:
Cost tier segmentation separates enterprise-scale procurement from owner-operator purchasing patterns.
- Fleet Operators:Multi-vehicle enterprises demand unified dashboards spanning hundreds of assets, with California-based freight brokers driving SaaS adoption for variable contract carrier networks. Their procurement prioritizes API integration with existing dispatch systems over standalone compliance features.
- Logistics Companies:Third-party providers require white-label compliance layers embedded within customer-facing shipment tracking portals. Asset-light 3PLs favor subscription pricing that scales with seasonal volume fluctuations rather than per-vehicle hardware commitments.
- Independent Truckers:Single-vehicle owners prioritize low-entry-cost solutions with minimal installation complexity.
- Transportation Services:Passenger and specialty haulers seek exemption-compliant alternatives to standard hours-of-service frameworks.
Fleet Operators dominate current revenue concentration; Logistics Companies are expanding most quickly as outsourcing accelerates.
Deployment:
Application context dictates whether carriers prioritize data sovereignty or remote accessibility.
- SaaS:Fully managed subscription models eliminate server maintenance burdens for small and mid-sized fleets. The model spreads fastest among Texas and Florida operators managing temperature-controlled cargo across variable route networks.
- Cloud-Based:Multi-tenant architectures enable rapid regulatory update deployment without device recertification delays.
- Hybrid:Mixed architectures buffer sensitive driver data locally while transmitting anonymized fleet analytics to central repositories.
- On-Premise:Self-hosted installations persist among defense contractors and government fleet operators with classified routing requirements.
SaaS captures the majority of new procurement decisions; Cloud-Based deployments gain share fastest as cellular infrastructure improves.
Feature:
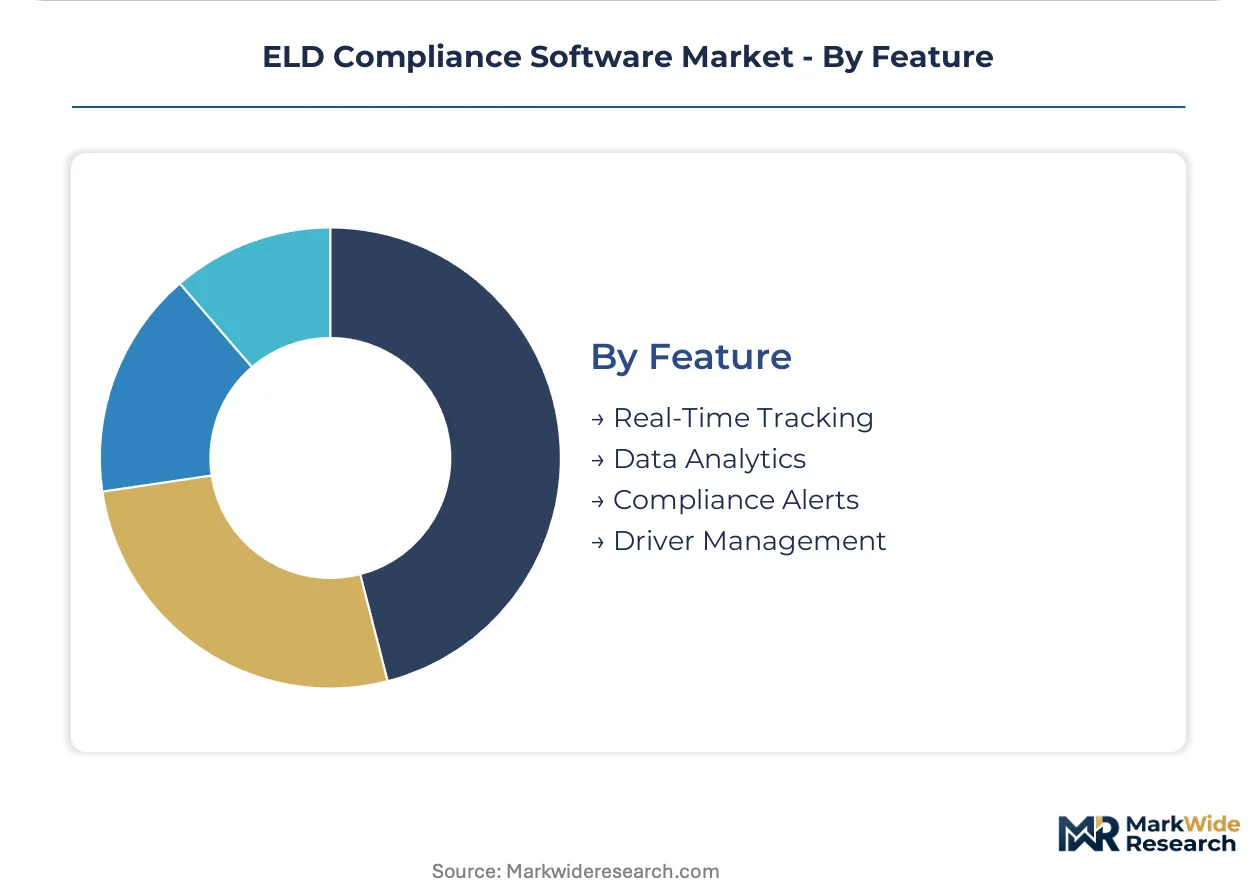
Margin concentration follows feature differentiation, with commoditized base functionality yielding to specialized analytics modules.
- Real-Time Tracking:Continuous location monitoring enables dynamic route adjustment and customer delivery notifications. Cross-border operators traversing the US-Canada corridor depend on this capability to coordinate dispatch across divergent regulatory jurisdictions.
- Compliance Alerts:Automated violation warnings prevent hours-of-service breaches during complex multi-stop sequences. Insurance underwriters increasingly mandate these alerts as a condition for preferred premium rates.
- Data Analytics:Historical pattern recognition identifies fuel inefficiency and detention time accumulation.
- Driver Management:Performance scoring and training assignment tools address high-turnover workforce challenges.
Real-Time Tracking remains the most commonly specified requirement; Compliance Alerts demonstrate the steepest growth trajectory as enforcement penalties escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fleet operators demonstrate the lowest price elasticity, absorbing premium SaaS subscriptions to avoid FMCSA enforcement penalties, while Mexican cross-border carriers remain highly price-sensitive, deferring compliance investments until federal mandates materialize.
United States
Long-haul refrigerated carriers and multi-jurisdictional operators drive demand for ruggedized onboard devices with offline buffering capabilities. FMCSA hours-of-service enforcement and escalating insurance underwriting requirements compel digitization among remaining paper-based fleets. Dallas-Fort Worth and Atlanta metropolitan corridors host the densest concentrations of fleet management technology providers serving interstate commerce.
Canada
Cross-border operators traversing the US-Canada corridor require synchronized compliance platforms addressing divergent CCMTA and FMCSA technical specifications. The Canadian ELD mandate creates parallel obligations that elevate demand for automated regulatory update engines. Southern Ontario freight corridors and Vancouver port logistics clusters concentrate adoption among temperature-controlled cargo specialists.
Mexico
US-owned cross-border fleets operating between Laredo and Mexico City represent the primary addressable demand pending federal ELD requirements. Absence of national mandates leaves procurement concentrated among carriers serving American contract logistics networks. Nuevo León and Jalisco manufacturing corridors exhibit earliest voluntary adoption to secure preferred shipper status.
Germany
Commercial vehicle telematics providers leverage EU digital tachograph standards to extend compliance platforms into North American markets through acquired subsidiaries. German engineering standards influence device certification requirements for carriers seeking FMCSA interoperability. Stuttgart automotive technology clusters and Munich software development centers anchor European vendor R&D operations.
United Kingdom
Post-Brexit regulatory divergence creates demand for multi-jurisdictional compliance platforms among UK-based logistics providers operating European route networks. British fleet operators prioritize API-first architectures enabling rapid adaptation to evolving customs and driver hour regulations. London freight technology incubators and Midlands distribution hubs concentrate SaaS procurement among asset-light third-party logistics providers.
ELD Compliance Software Market Competitive Landscape
Cloud-native platform specialists and legacy telematics hardware incumbents split the market between subscription-driven SaaS architectures and integrated device-and-software bundles. Consolidation pressure intensifies as cellular module commoditization compresses hardware margins and carriers prioritize scalable recurring revenue relationships over capital-intensive installations. Three strategic archetypes dominate: vertically integrated device-and-platform vendors, pure-play SaaS compliance specialists, and transportation management system extenders embedding ELD functions within broader logistics software. Dominant competitive moves include API-first architecture development to reduce customer switching costs and geographic expansion into Mexico to preempt federal mandate timing.
Among North American platform providers, Samsara and Omnitracs exemplify contrasting strategic positions within the cloud-native tier, while Trimble anchors the integrated hardware-software archetype through enterprise transportation management system relationships. These three companies represent the spectrum of vendor approaches to bundling compliance with adjacent fleet analytics, safety scoring, and fuel optimization modules.
| Leading Market Players |
|---|
| Geotab |
| Samsara |
| Omnitracs |
| Teletrac Navman |
| Trimble |
| Verizon Connect |
| Motive |
| KeepTruckin |
| Zonar Systems |
| Others |
Pricing and Supply Chain Analysis
Dallas-Fort Worth technology corridors concentrate cloud-native platform development capacity, concentrating pricing power among vendors bundling compliance with adjacent fleet analytics modules. Hardware manufacturing disperses across Shenzhen cellular module foundries and Mexican assembly facilities, fragmenting bargaining leverage for device-centric suppliers.
Pricing Analysis
Aftermarket service revenue from regulatory update subscriptions and compliance alert engines drives lifetime value compression as carriers reject capital-intensive hardware purchases. Three-tier pricing structure across premium, standard, and economy levels separates enterprise TMS-integrated bundles from standalone SaaS tiers and basic mobile applications. Pricing pressure stems from Chinese cellular module cost declines flooding ruggedized device markets. Asset-light third-party logistics providers demonstrate highest price sensitivity; long-haul refrigerated carriers operating interstate routes show lowest elasticity due to FMCSA enforcement penalty exposure.
Supply Chain Analysis
Export-control restrictions on GPS-synchronized engine data capture chipsets limit technology flows from US semiconductor designers to Chinese manufacturing partners. Component sourcing draws from Taiwan GPS module fabricators, South Korea memory suppliers, and Shenzhen cellular connectivity assemblers. Semiconductor lithography equipment and precision automotive-grade sensors constitute critical input dependencies. Single-source vulnerability concentrates in GPS engine synchronization chipsets where qualified alternative suppliers remain limited. Distribution runs through direct enterprise sales teams serving fleet operators above fifty vehicles, with value-added resellers penetrating owner-operator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
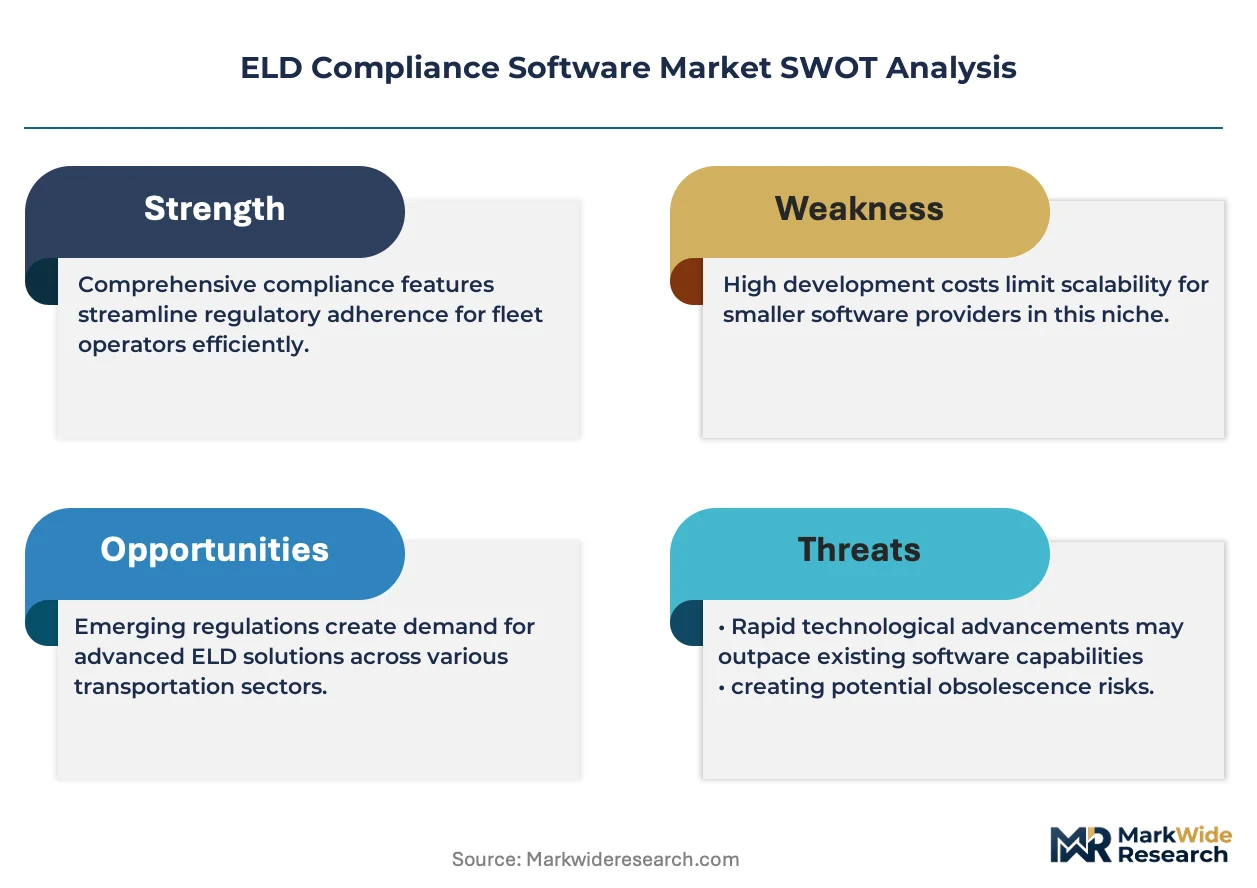
Platform engineering talent capable of FMCSA certification navigation and real-time data pipeline architecture represents the scarcest capability cluster, constraining vendor expansion velocity and elevating acquisition premiums for qualified development teams.
For Market Incumbents: Entrench market position through backward integration into edge-computing onboard unit manufacturing to escape cellular module commoditization. Acquire specialized regulatory update engine providers to automate multi-jurisdictional compliance complexity. Prioritize API-first architecture investments that reduce customer switching costs against emerging SaaS-native competitors. For New Entrants and Emerging Players: Mexican cross-border freight corridors between Laredo and Mexico City offer underpenetrated white-space as US-owned fleets pre-position for eventual federal mandate implementation. Last-mile parcel carrier mobile solutions exempt from heavy-duty hardware specifications present second entry vector. Pursue freight broker channel partnerships rather than direct fleet sales to bypass incumbent entrenched relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native platform specialists with proven FMCSA certification velocity over legacy hardware-integrated vendors facing margin compression. Long-term viability across the projection horizon rests on recurring revenue density and regulatory update automation capabilities. Watch FMCSA automatic braking system integration rule implementation timing as inflection indicator forcing device recertification investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Open integration protocols embed compliance data directly into Oracle and SAP transportation management systems. |
| Mexico Market Pre-Positioning | Early platform deployment captures US-owned cross-border fleets before federal mandate materializes. |
| Edge-Computing Hardware Refresh | Local data buffering capabilities displace satellite-dependent legacy systems in Mountain West dead zones. |
| Regulatory Update Engine Acquisition | Automated multi-jurisdictional compliance engines reduce support costs for CCMTA-FMCSA divergence. |
| Last-Mile Mobile Solution Launch | Smartphone-based platforms penetrate urban parcel carriers exempt from heavy-duty hardware specifications. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, FMCSA compliance officers, transportation management system integrators, and cellular connectivity procurement leads and refined through secondary validation against FMCSA regulatory filings, CCMTA technical standard updates, SEC 10-K disclosures from listed telematics providers, and customs import data for GPS-enabled automotive electronics. Bottom-up fleet size and deployment model estimates triangulated against top-down addressable vehicle population calculations.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions including fleet size tier, route geography complexity, deployment architecture preference, and regulatory jurisdiction exposure. CAGRs derived from installed base replacement cycle compression and SaaS subscription attach rate trajectories. Forecast inputs incorporated FMCSA enforcement penalty escalation patterns and insurance underwriting requirement diffusion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud-native specialists or hardware-software bundle vendors would shift outcomes beyond modeled ranges. Cross-checking against FMCSA-certified device registry growth rates and carrier insurance premium differential data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sales Gamification Software Market
Software & Services
Global Calendar Scheduling Software Market
Software & Services
Global Appointment Reminder Software Market
Software & Services
Cloud Communication Platform Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Interior Design Software Market
Software & Services
Website Builder Tool Market
Software & Services
Global Contract Management Software Market
Software & Services
Enterprise-Grade Saas Market
Software & Services
Multivariate Testing Software Market
Software & Services
UK Point of Sale Software Market
Software & Services
Poland IT Software and Service Market
Software & Services
Europe HR Payroll Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Gym Motion Tracking Software Market