
 China Study of Data Center Water Consumption Market | 2026-2036
China Study of Data Center Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
China Study of Data Center Water Consumption Market Insights
Software-defined cooling orchestration is realigning what operators purchase, shifting capital toward subscription-based thermal management platforms. GDS Services leverages its hyperscale facility footprint to anchor premium service contracts across Tier-1 cities. Chindata Group specializes in direct liquid cooling integration at its Zhangjiakou campus, differentiating its water efficiency profile. Tencent sustains R&D intensity in AI-driven cooling optimization, competing on operational metrics rather than infrastructure scale alone.
The China Study of Data Center Water Consumption examines freshwater withdrawal, treatment, and discharge volumes tied to server farm thermal regulation, encompassing direct evaporative losses, blowdown cycles, and liquid cooling loops operating at flow rates exceeding 2 liters per kilowatt-hour in high-density configurations. Its primary commercial purpose is to quantify operational resource exposure, benchmark conservation performance, and inform infrastructure investment decisions under tightening environmental constraints. Direct liquid cooling systems capture expanding margin pools as chip power densities surpass air-cooled thresholds, while evaporative cooling dominates installed base volumes despite municipal water dependency risks. Recycled water sourcing segments face infrastructure gaps outside developed eastern corridors, constraining adoption in western expansion zones where groundwater extraction still prevails.
China's MEE enforces wastewater discharge permits and water withdrawal quotas that directly constrain data center site selection and cooling technology choices. The country's dual carbon goals and GB standards for data center power usage effectiveness create overlapping compliance layers that elevate capital requirements for new builds. MIIT facility certification rules further segment market access, privileging operators with demonstrated water recycling capabilities. Stakeholders must monitor regulatory threshold tightening in water-stressed provinces and pre-position treatment infrastructure ahead of permit allocation cycles.
Market Dynamics
Chip power densities exceeding 500 watts per socket are forcing wholesale cooling architecture replacement across China's hyperscale fleet, compressing upgrade cycles from seven years to under four.
Growth Catalysts
- MEE water withdrawal quotas:Provincial caps on groundwater extraction in Hebei and Shandong are accelerating evaporative-to-liquid cooling retrofits among operators seeking permit security.
- Hyperscale facility concentration:Beijing, Shanghai, and Shenzhen now host over sixty percent of China's high-density compute capacity, creating localized demand spikes for advanced thermal systems.
- Zhangjiakou renewable energy corridor:Grid-scale wind and solar integration at this northern cluster enables energy-intensive direct liquid cooling without carbon penalty exposure.
Market Restraints
- Copper and nickel price volatility:Cold plate and heat exchanger fabrication depends on these metals, with spot price swings above twenty percent disrupting procurement planning for cooling system integrators.
- Municipal recycled water infrastructure gaps:Western expansion zones including Ningxia and Qinghai lack tertiary treatment capacity, forcing reliance on scarce groundwater reserves subject to tightening extraction limits.
- Air-cooled legacy entrenchment:Existing hyperscale facilities designed for sub-200W per rack densities face structural constraints on piping retrofits and floor loading, delaying technology transitions.
Strategic Opportunities
- Greater Bay Area water-stressed cluster:Shenzhen and Guangzhou operators face the country's strictest discharge requirements, creating premium pricing potential for closed-loop cooling as-a-service offerings.
- MIIT green data center certification:Facilities achieving this designation gain preferential grid access and tax treatment, incentivizing integrated water recycling system investment ahead of competitor compliance.
- AI inference edge deployment:Distributed micro-data centers in tier-three cities require compact liquid cooling modules, opening a channel distinct from hyperscale capital equipment sales.
Industry Challenges
- Thermal-fluid engineering specialization:The talent pool for dielectric coolant chemistry and two-phase flow system design remains concentrated among fewer than two hundred qualified engineers nationally.
- GB 50174 compliance timelines:Certification against this data center design standard requires twelve to eighteen months of documentation and third-party verification, delaying revenue recognition for new builds.
- Legacy chiller integration:Hybrid architectures combining new liquid cooling loops with existing vapor compression equipment demand custom control system development, extending commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Study of Data Center Water Consumption Market |
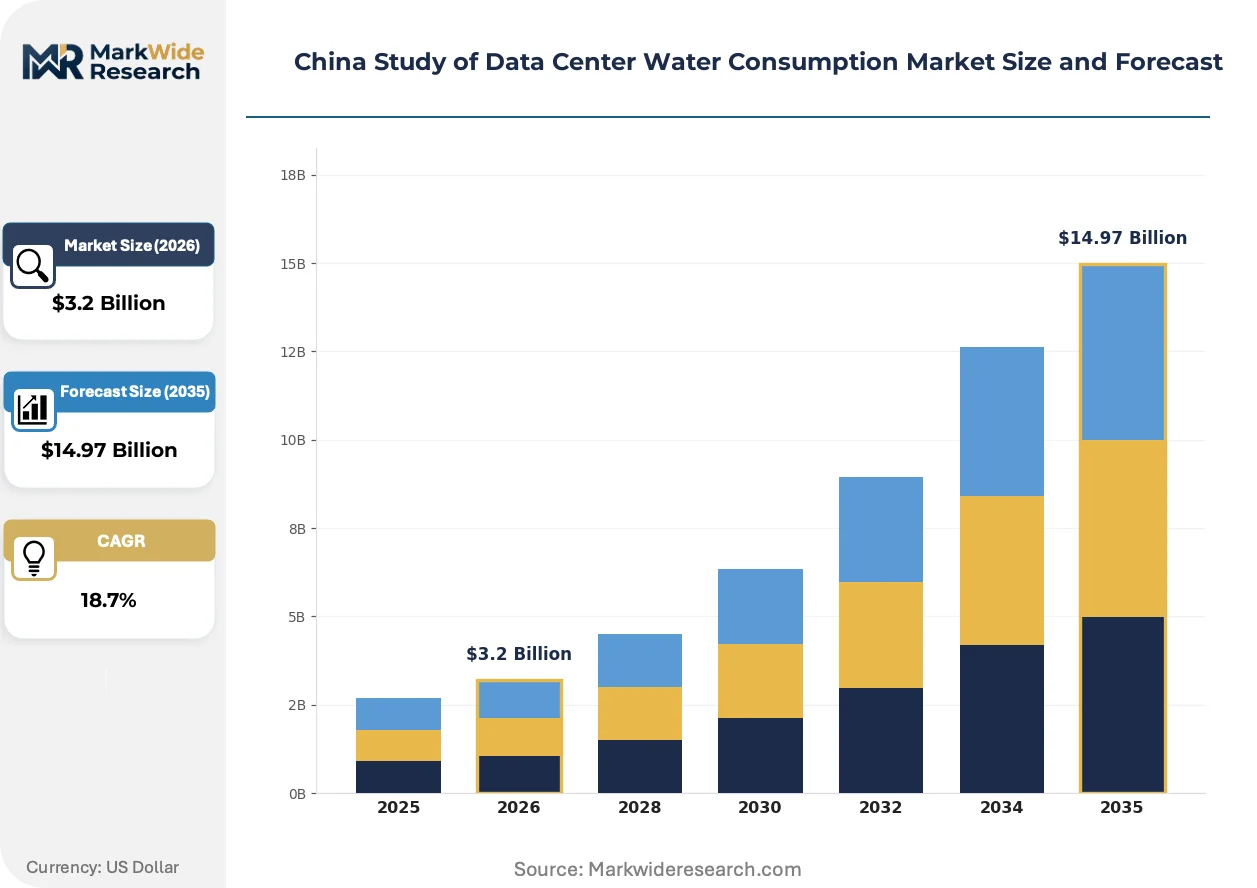
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $14.97 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Evaporative Cooling, Chilled Water Systems, Direct Liquid Cooling, Air-Cooled Systems Water Source: Mains Water, Recycled Water, Rainwater Harvesting, Groundwater End User: Cloud Service Providers, Telecom Operators, Enterprises, Colocation Providers Operational Strategy: High Efficiency, Water Conservation, Renewable Solutions, Hybrid Systems |
| Companies Covered | China Telecom, China Mobile, China Unicom, GDS Services, Chindata Group, Tencent, Baidu, Xiaomi, China Mobile Communications Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Study of Data Center Water Consumption Market Trends and Innovations
Software-defined thermal orchestration is collapsing the distinction between facility infrastructure and IT operations, enabling real-time workload placement based on instantaneous cooling capacity and water availability metrics.
Direct liquid cooling with single-phase dielectric fluids is rewriting capital deployment patterns for hyperscale operators. Alibaba and ByteDance procurement teams now specify cold plate densities above 80 kilowatts per rack as standard for new builds. This specification is compressing air-cooled equipment residual values and accelerating secondary market obsolescence.
China's dual carbon goals and successive GB standard revisions are tightening power usage effectiveness ceilings and introducing water usage effectiveness metrics for the first time. MIIT facility certification now requires documented recycling rates above 50 percent in water-scarce provinces. Operators in Beijing and Tianjin are responding by pre-positioning membrane bioreactor treatment capacity ahead of permit renewal cycles.
Cloud service procurement teams are unbundling thermal management from facility construction contracts, signing separate five-year service agreements with specialized cooling vendors. This pattern displaces traditional engineering-procurement-construction bundled awards. The shift is most visible in Shanghai's Lingang and Qingpu districts, where GDS Services and Chindata Group have both adopted this model for 2024-2025 capacity additions.
China Study of Data Center Water Consumption Market Segmentation
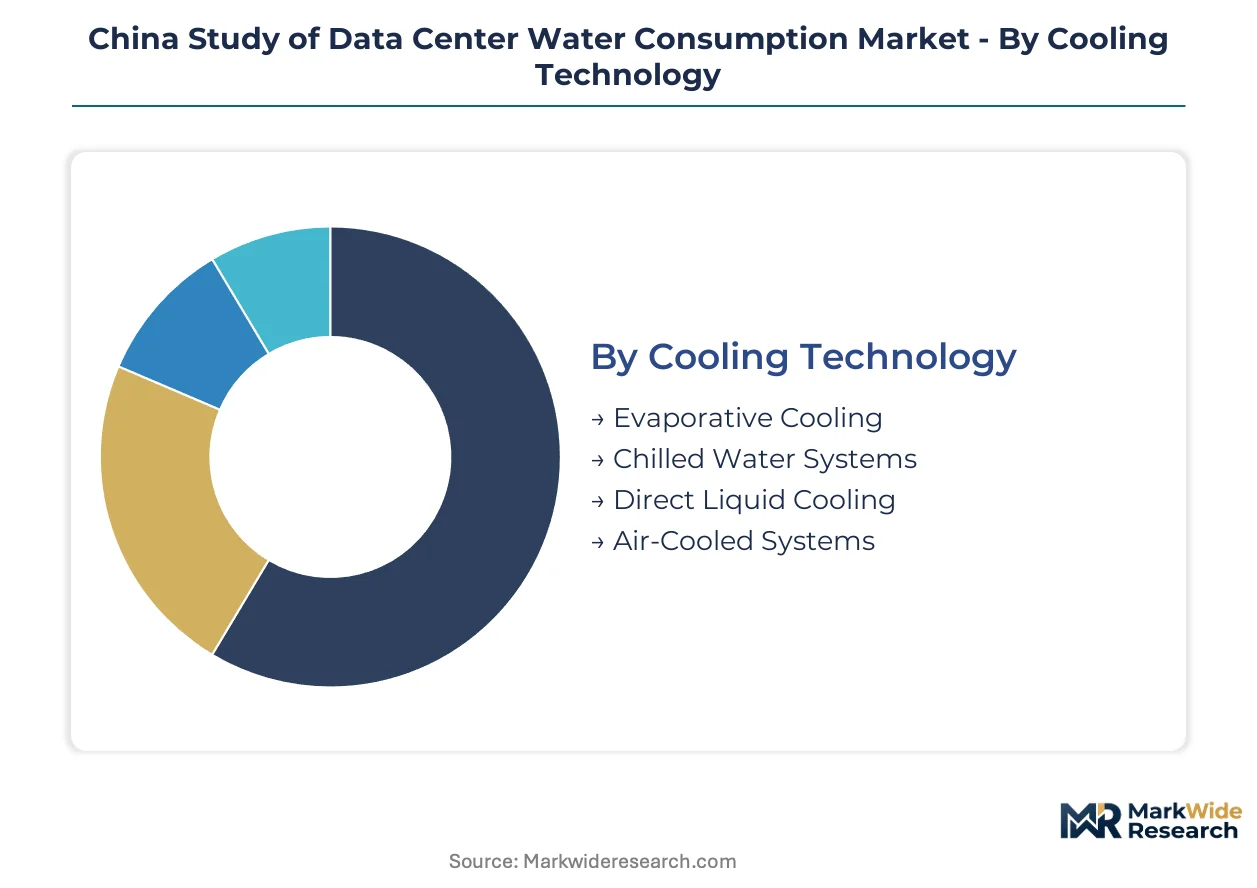
Cooling technology choices determine capital allocation trajectories and compliance exposure across China's data center fleet. Water sourcing decisions increasingly constrain site selection in northern provinces where MEE quotas tighten. End-user procurement patterns and operational strategies further segment vendor access and service contract structures.
Cooling Technology:
Chip thermal design power thresholds above 500 watts per socket are collapsing legacy cooling architectures into accelerated replacement cycles.
- Direct Liquid Cooling:Single-phase and two-phase dielectric fluid loops operating at flow rates exceeding 2 liters per kilowatt-hour. Demand concentrates at Zhangjiakou and Inner Mongolia campuses where renewable energy abundance offsets pumping energy penalties. Cold plate densities above 80 kilowatts per rack now dominate hyperscale procurement specifications from Alibaba and ByteDance.
- Evaporative Cooling:Adiabatic and direct evaporative systems using wet media or spray nozzles for heat rejection. Beijing and Shanghai operators face municipal water dependency risks as withdrawal permits tighten, forcing blowdown cycle optimization and drift eliminator upgrades to maintain compliance.
- Chilled Water Systems:Centralized vapor compression plants distributing chilled water to CRAH units. Legacy hyperscale facilities in Tianjin and Langfang retain substantial installed base despite retrofit constraints from floor loading limits.
- Air-Cooled Systems:Dry coolers and air-cooled chillers eliminating water consumption entirely. Western expansion zones in Ningxia and Qinghai deploy these where water scarcity intersects with lower ambient wet-bulb temperatures.
Evaporative cooling leads on scale; direct liquid cooling leads on momentum.
Water Source:
Supply infrastructure maturity varies sharply across China's eastern-western development gradient.
- Mains Water:Municipal treated water supplies serving Tier-1 city facilities. Shanghai and Shenzhen operators face escalating unit costs as scarcity pricing mechanisms expand.
- Recycled Water:Tertiary-treated municipal effluent or on-site membrane bioreactor output. Beijing operators pre-position treatment capacity ahead of MIIT certification renewals requiring documented recycling rates above 50 percent.
- Rainwater Harvesting:Collection and storage systems supplementing primary supplies. Southern coastal facilities in Guangzhou and Fuzhou exploit monsoon precipitation patterns.
- Groundwater:Direct well extraction from aquifers. Hebei and Shandong extraction permits face MEE quota reductions, accelerating facility migration or technology substitution.
Mains water dominates current withdrawals; recycled water is climbing the fastest.
End User:
Procurement centralization and technical specification authority differ markedly across customer types.
- Cloud Service Providers:Hyperscale operators with captive design teams specifying integrated thermal-water systems. Alibaba, Tencent, and ByteDance unbundle cooling from construction contracts, signing separate service agreements with specialized vendors.
- Colocation Providers:Multi-tenant facility operators balancing diverse customer density requirements. GDS Services and Chindata Group anchor premium service contracts through Tier-1 city footprints.
- Telecom Operators:State-owned carriers with distributed edge infrastructure. China Mobile and China Unicom prioritize air-cooled and hybrid systems for tier-three city deployments.
- Enterprises:Captive data centers in financial services and manufacturing. Compliance-driven investment concentrates in Beijing and Shanghai where GB 50174 certification pressures intensify.
Cloud service providers lead on scale; colocation providers lead on momentum.
Operational Strategy:
Performance metrics and certification requirements are segmenting vendor relationships and capital deployment priorities.
- High Efficiency:Power usage effectiveness optimization through advanced heat rejection and free cooling. MIIT green data center certification requires demonstrated thermal performance thresholds.
- Water Conservation:Minimizing freshwater withdrawal through recycling, zero-liquid-discharge, or air-cooled architectures. Beijing and Tianjin facilities face the strictest provincial constraints.
- Hybrid Systems:Combining liquid and air-cooled zones within single facilities. Custom control system development extends commissioning periods for these architectures.
- Renewable Solutions:Grid-scale wind and solar integration enabling energy-intensive cooling without carbon penalty exposure. Zhangjiakou corridor anchors this strategy.
High efficiency leads on scale; water conservation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's data center water consumption patterns diverge sharply from India's software-centric cooling needs, where evaporative losses remain minimal compared to the thermal loads of Beijing's hyperscale clusters.
Beijing-Tianjin-Hebei
MEE groundwater withdrawal quotas in Hebei province are forcing evaporative-to-liquid cooling retrofits among operators seeking permit security. MIIT green data center certification requires documented recycling rates above 50 percent, driving membrane bioreactor pre-positioning ahead of renewal cycles. Langfang and Tianjin host substantial legacy chilled water installed base despite floor loading constraints on piping retrofits.
Yangtze River Delta
Shanghai and Suzhou facilities face escalating municipal water unit costs as scarcity pricing mechanisms expand across the delta. Cloud service procurement teams unbundle thermal management from construction contracts, signing separate five-year service agreements with specialized cooling vendors. Lingang and Qingpu districts anchor this shift for 2024-2025 capacity additions.
Pearl River Delta
Shenzhen and Guangzhou operators confront China's strictest wastewater discharge requirements, creating premium pricing potential for closed-loop cooling as-a-service offerings. GB standards for data center power usage effectiveness create overlapping compliance layers that elevate capital requirements for new builds. Southern coastal facilities exploit monsoon precipitation patterns through rainwater harvesting supplementation.
Zhangjiakou Renewable Corridor
Grid-scale wind and solar integration at this northern cluster enables energy-intensive direct liquid cooling without carbon penalty exposure. Cold plate densities above 80 kilowatts per rack now dominate hyperscale procurement specifications from operators locating here. Chindata Group specializes in direct liquid cooling integration at this campus, differentiating its water efficiency profile.
Western Expansion Zones
Ningxia and Qinghai lack tertiary treatment capacity, forcing reliance on scarce groundwater reserves subject to tightening MEE extraction limits. Air-cooled systems eliminate water consumption entirely where lower ambient wet-bulb temperatures permit. Distributed micro-data centers in tier-three cities require compact liquid cooling modules, opening a channel distinct from hyperscale capital equipment sales.
China Study of Data Center Water Consumption Market Competitive Landscape
Top-tier vendors anchor hyperscale facility footprints, while specialized cooling integrators and state-owned carriers occupy distinct competitive tiers. The market structure reflects procurement centralization among cloud service providers with captive design teams, alongside multi-tenant colocation operators balancing diverse customer density requirements. Strategic archetypes include renewable-energy-anchored campus developers, Tier-1 city premium service contract holders, and distributed edge infrastructure deployers. Dominant competitive moves encompass unbundling thermal management from construction contracts and pre-positioning treatment infrastructure ahead of permit allocation cycles.
Within the hyperscale operator tier, GDS Services and Chindata Group exemplify contrasting geographic and technological positioning strategies. GDS Services leverages its facility footprint to anchor premium service contracts across Beijing, Shanghai, and Shenzhen. Chindata Group occupies a position centered on northern China's renewable energy corridor. Among state-owned carriers, China Telecom and China Mobile represent the distributed infrastructure archetype, prioritizing air-cooled and hybrid systems for tier-three city edge deployments. Tencent sits within the AI-driven optimization segment, competing on operational metrics rather than infrastructure scale alone.
| Leading Market Players |
|---|
| China Telecom |
| China Mobile |
| China Unicom |
| GDS Services |
| Chindata Group |
| Tencent |
| Baidu |
| Xiaomi |
| China Mobile Communications Group |
| Others |
Pricing and Supply Chain Analysis
Copper and nickel spot price indices cascade through cold plate fabrication costs, compressing margins for cooling system integrators and forcing tiered pricing stratification across direct liquid cooling, evaporative, and air-cooled system categories. MEE water withdrawal quotas in Hebei and Shandong amplify this effect by accelerating technology substitution timelines among operators seeking permit security.
Pricing Analysis
Capacity additions in Zhangjiakou and Inner Mongolia are reshaping price floors for direct liquid cooling systems as renewable energy abundance offsets pumping energy penalties. Three-tier pricing structure across MIIT-certified premium, standard efficiency, and legacy economy levels differentiates vendor access. Cost compression in the economy tier intensifies because air-cooled residual values collapse under liquid cooling procurement dominance. Cloud service providers exhibit lowest price sensitivity due to captive design teams and unbundled thermal service contracts, while enterprise captive data centers face acute budget constraints under GB 50174 compliance pressures.
Supply Chain Analysis
Single-source vulnerability sits with dielectric coolant specialty chemical production concentrated in Germany, Japan, and the United States. Cold plate machining draws from copper and nickel feedstocks, while membrane bioreactor components rest on polymer membrane imports from South Korea and Japan. Tariff exposure on precision-machined thermal components threatens procurement planning for cooling system integrators. Distribution runs through specialized HVAC-R contractors and direct hyperscale procurement teams, bypassing traditional engineering-procurement-construction bundled channels in Tier-1 city clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's data center water consumption market functions as a geographic-arbitrage play where MEE quota stringency in northern provinces creates cost and compliance differentials against western expansion zones with looser extraction limits but inferior recycled water infrastructure.
For Market Incumbents: Acquire membrane bioreactor treatment capacity ahead of permit renewal cycles in Beijing and Tianjin. Secure backward integration into dielectric coolant chemistry to offset copper and nickel price volatility threatening cold plate margins. Consolidate around MIIT green data center certification as a barrier against emerging colocation entrants lacking documented recycling rates. For New Entrants and Emerging Players: Specialized cooling-as-a-service vendors offer channel partnership pathways into hyperscale procurement teams unbundling thermal management from construction contracts. White-space concentrates in tier-three city edge deployments requiring compact liquid cooling modules for AI inference infrastructure. Target Ningxia and Qinghai air-cooled retrofits where groundwater extraction limits intersect with lower ambient wet-bulb temperatures. For Investors and Strategic Acquirers: Asymmetric upside sits with renewable-energy-anchored campus developers in the Zhangjiakou corridor where grid-scale wind and solar integration enables energy-intensive direct liquid cooling without carbon penalty exposure. Long-term viability favors operators with pre-positioned treatment infrastructure and demonstrated water recycling capabilities above MIIT thresholds. Watch MEE quota tightening announcements in water-stressed provinces as the inflection signal for accelerated evaporative-to-liquid cooling substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-position Membrane Bioreactor Capacity | Beijing and Tianjin operators secure MIIT certification ahead of quota renewal cycles. |
| Unbundle Thermal Service Contracts | Cloud service procurement teams in Shanghai's Lingang district separate cooling from construction awards. |
| Backward Integrate into Coolant Chemistry | Specialized vendors offset copper and nickel spot price volatility through captive dielectric fluid production. |
| Anchor Renewable Energy Corridor Position | Zhangjiakou campus developers leverage grid-scale wind and solar for carbon-neutral liquid cooling operations. |
| Develop Compact Edge Cooling Modules | Tier-three city micro-data center deployments open channels distinct from hyperscale capital equipment sales. |
Research Methodology
Coverage spans Beijing-Tianjin-Hebei, Yangtze River Delta, Pearl River Delta, and Western Expansion Zones, with primary inputs from each. Primary interviews with data center facility directors, cooling system procurement leads, MEE regulatory affairs officers, and thermal-fluid engineering specialists combined with secondary validation from MIIT certification databases, GB standards documentation, provincial water withdrawal permit records, and hyperscale operator capex disclosures. Bottom-up installation base modeling and top-down market sizing triangulate volume estimates across cooling technology and water source segments.
Rate-of-change decomposition separates replacement cycle compression from net capacity additions across the projection horizon. Segmentation dimensions modeled include cooling technology architecture, water sourcing infrastructure maturity, end-user procurement centralization, and operational strategy certification tier. CAGRs derive from technology penetration curves overlaid with regulatory compliance deadline clustering. Forecast inputs incorporate chip thermal design power trajectories and MEE quota tightening schedules without specific year anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and nickel commodity volatility, dielectric coolant engineering talent pool constraints, and MEE regulatory threshold acceleration. Forecasts reflect documented assumptions on technology substitution elasticities and permit allocation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Mexico Data Center Cooling Market