
 Saudi Arabia Data Center Cooling Market | 2026-2036
Saudi Arabia Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Cooling Market Insights
Modular cooling system bundling is pivoting procurement patterns across Saudi data center builds. Schneider Electric SE leverages its integrated power and cooling architecture to anchor large-scale projects in the Kingdom. Stulz GmbH sustains its position through precision climate control specialization for high-density server environments. Vertiv Group Corp. competes on thermal management solutions tailored to extreme ambient temperatures.
Saudi Arabia data center cooling encompasses engineered heat rejection systems designed to maintain server inlet temperatures between 18°C and 27°C per ASHRAE guidelines, utilizing refrigerants, chilled water loops, or dielectric fluids to protect IT infrastructure from thermal-induced failure. Liquid cooling is gaining traction as rack densities exceed 30 kW per cabinet, while evaporative cooling dominates in arid climates where water scarcity constraints shape system selection. Chilled water systems retain share in enterprise deployments where redundancy tiers demand centralized plant architecture. Banking and telecommunications end users drive specification intensity as latency-sensitive financial transactions and 5G core networks require uninterrupted thermal stability.
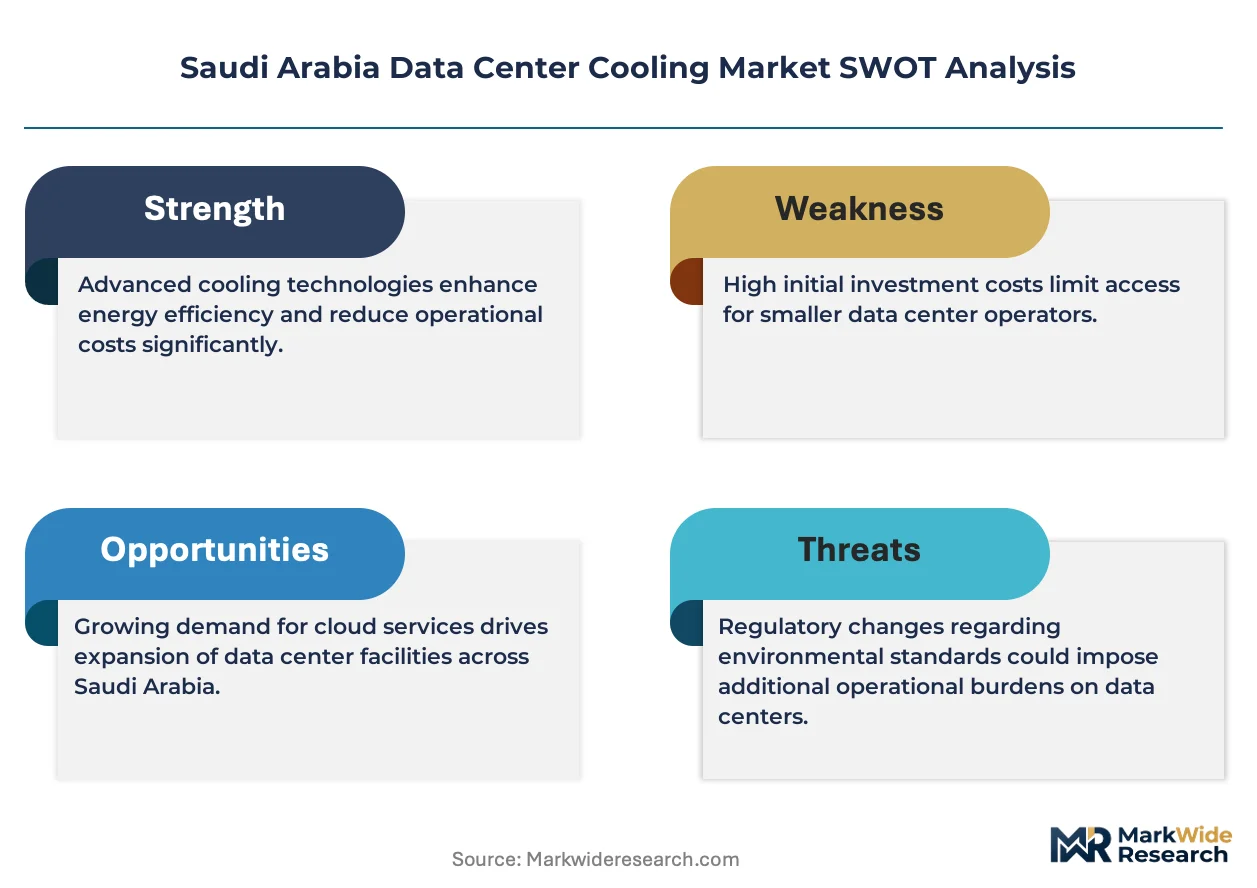
SFDA data integrity requirements for pharmaceutical logistics, MOHAP health data localization mandates, and Saudi Building Code energy efficiency standards collectively elevate cooling system compliance costs while accelerating replacement cycles. SASO efficiency labeling and the Saudi Energy Efficiency Program tighten minimum performance thresholds for imported cooling equipment. Stakeholders must weigh liquid cooling capital intensity against rising electricity tariffs and carbon accounting pressures as the Kingdom advances its data center localization agenda.
Market Dynamics
Hydrocarbon-reliant cooling architectures face intensifying scrutiny as SASO efficiency labeling tightens minimum performance thresholds for imported equipment, forcing operators to reconsider evaporative systems in water-scarce regions. The Kingdom's data center localization agenda collides with rising electricity tariffs and carbon accounting pressures, creating a procurement environment where thermal infrastructure decisions carry decade-long cost implications.
Growth Catalysts
- SFDA pharmaceutical data integrity mandates:Cold-chain logistics operators require precision climate control for drug storage databases, expanding addressable demand beyond traditional IT loads.
- Neom smart city buildouts:The linear city's zero-carbon infrastructure targets are attracting hyperscale operators who specify liquid cooling from ground-up construction.
- 5G core network densification:Telecommunications carriers are deploying edge facilities across Riyadh and Jeddah that demand uninterrupted thermal stability for latency-sensitive traffic.
Market Restraints
- Chilled water plant capital intensity:Enterprise redundancy tiers requiring N+1 or 2N configurations demand centralized mechanical infrastructure with payback periods exceeding seven years.
- Refrigerant supply concentration:Low-GWP alternative fluids remain concentrated among European and East Asian chemical suppliers, exposing Saudi projects to import dependency and currency fluctuation risk.
- Evaporative cooling water constraints:Arid climate conditions and aquifer depletion rates in the Eastern Province limit adiabatic system deployment despite favorable ambient dry-bulb temperatures.
Strategic Opportunities
- Tabuk renewable energy corridor:Wind and solar generation clusters enable carbon-neutral cooling operations that satisfy ESG-linked financing requirements for hyperscale developments.
- Dielectric fluid immersion:Direct liquid contact with server components eliminates air-handling infrastructure, compressing facility footprints and enabling 100 kW-plus rack densities.
- Saudi Energy Efficiency Program incentives:Equipment rebates for cooling systems exceeding baseline efficiency thresholds create procurement subsidies for early technology adopters.
Industry Challenges
- Thermal engineer scarcity:Liquid cooling system design and commissioning expertise remains concentrated among European and North American specialists, complicating local workforce development.
- Legacy air-cooled retrofit complexity:Existing Riyadh enterprise facilities built on raised-floor CRAC architectures face disruptive downtime risks when integrating hybrid cooling loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Cooling Market |
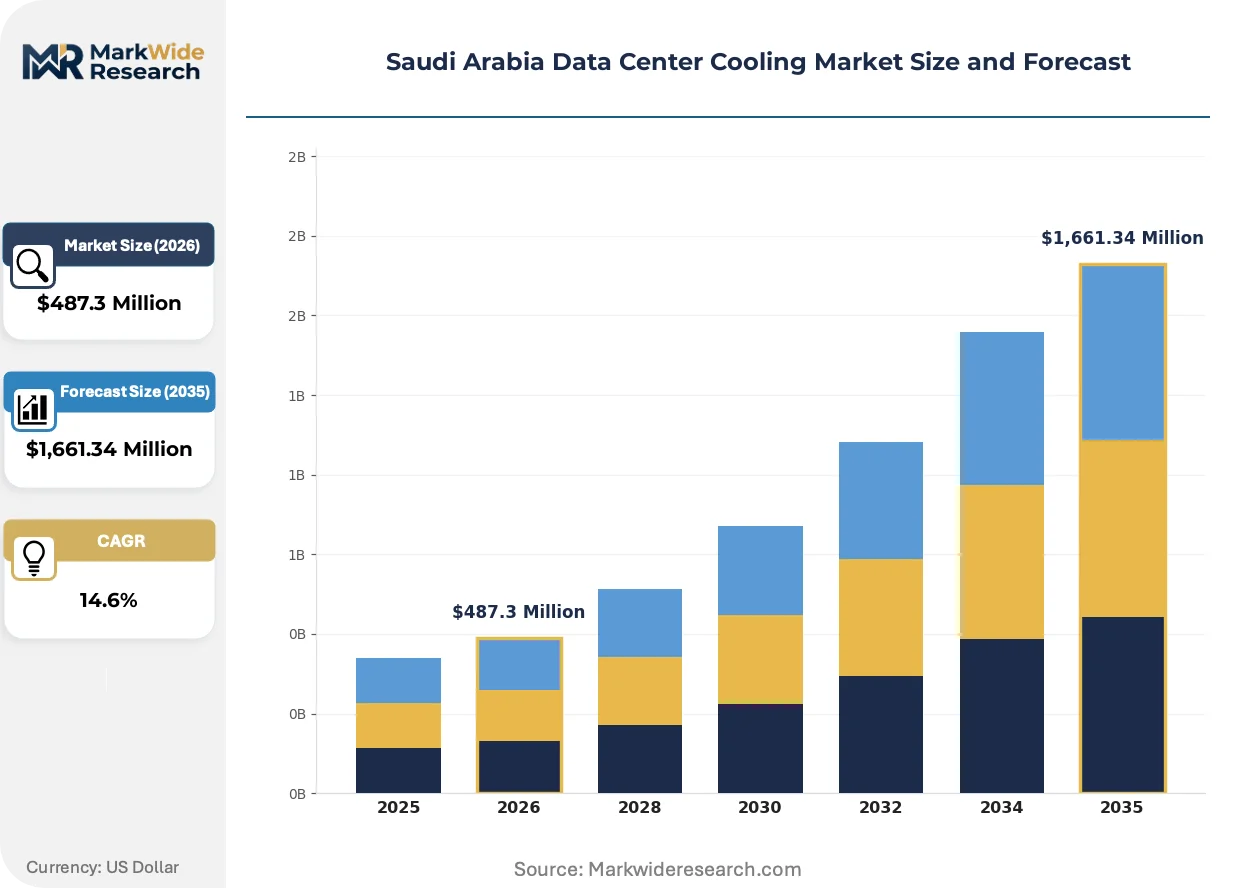
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Chilled Water Systems, Direct Expansion, Evaporative Cooling, Liquid Cooling End User: Telecommunications, IT Service Providers, Government, Banking Size: Small, Medium, Large, Enterprise Deployment Type: On-Premise, Colocation, Cloud, Hybrid |
| Companies Covered | Mitsubishi Electric Hydronics & IT Cooling Systems SpA, Stulz GmbH, Schneider Electric SE, Daikin Industries Limited, Astek Group, Vertiv Group Corp., Asetek A/S, Emerson Electric Co., Johnson Controls International PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Cooling Market Trends and Innovations
Artificial intelligence is embedding into cooling control systems, shifting thermal management from reactive setpoint adjustments to predictive load balancing that anticipates server utilization spikes before heat generation occurs.
Direct-to-chip liquid cooling is rewriting capital deployment patterns for high-density compute environments. Banking sector operators deploying GPU clusters for fraud detection are specifying cold-plate architectures that capture 80 percent of server heat at the processor. This thermal capture efficiency is compressing mechanical infrastructure footprints by half relative to traditional chilled water plants.
SASO efficiency labeling and the Saudi Energy Efficiency Program are tightening import requirements for cooling equipment. Minimum coefficient of performance thresholds now exclude legacy reciprocating compressor technologies from new construction bids. Equipment distributors are responding by accelerating inverter-driven scroll and screw compressor introductions ahead of 2027 regulatory phase-in dates.
Hyperscale operators are unbundling cooling infrastructure procurement from general contractor packages. Cloud service providers now issue separate RFPs for thermal systems, enabling direct manufacturer relationships that bypass traditional MEP subcontractor markups. This specification intensity concentrates in Riyadh and Jeddah where multi-megawatt deployments dominate pipeline activity.
Saudi Arabia Data Center Cooling Market Segmentation
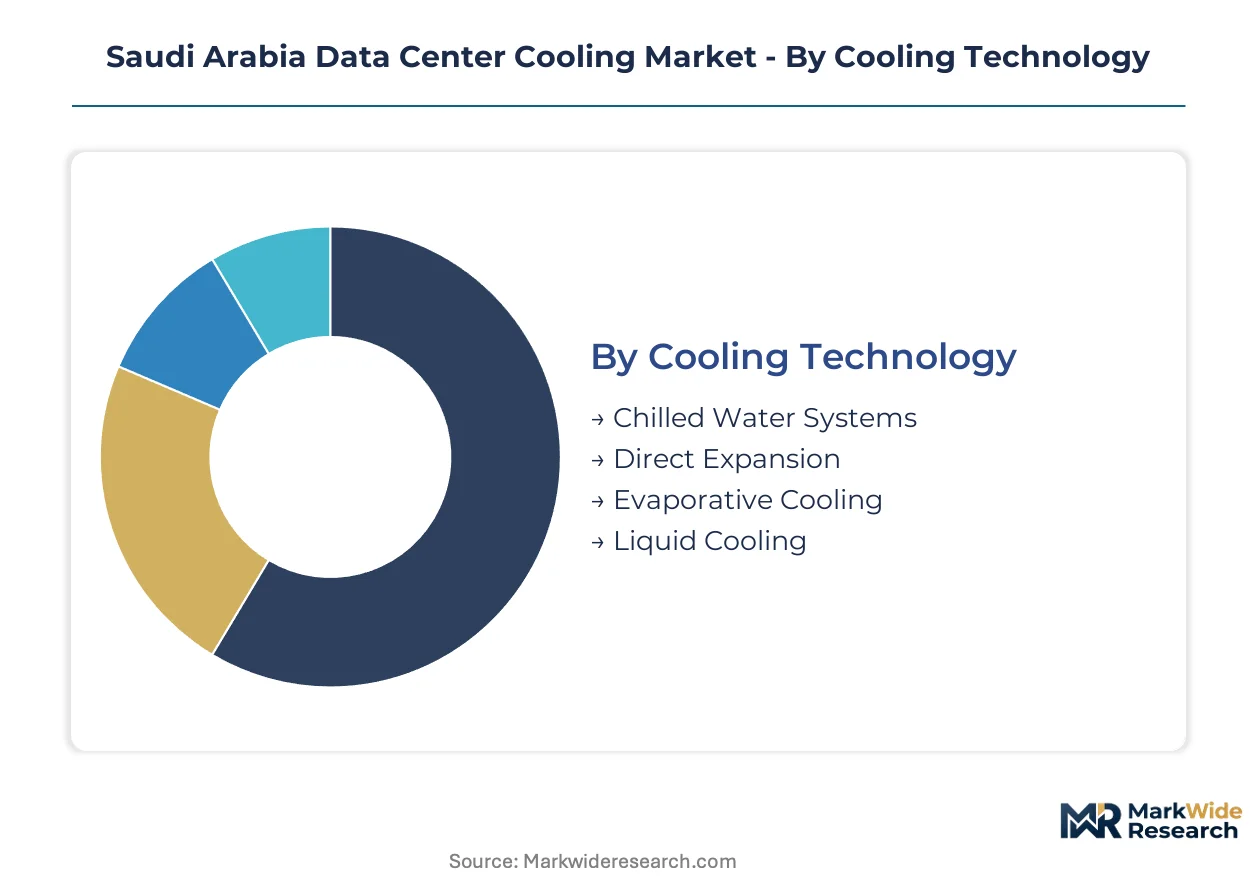
Cooling technology selection in Saudi Arabia hinges on water availability, ambient temperature extremes, and rack density trajectories. Procurement committees weight capital expenditure against decade-long operational costs shaped by electricity tariffs and SASO efficiency mandates.
Cooling Technology:
Facility designers prioritize thermal rejection efficiency against local climate constraints and regulatory compliance timelines.
- Chilled Water Systems:Centralized plant architecture utilizing cooling towers and heat exchangers to distribute conditioned water across multiple data halls. Banking sector operators in Riyadh specify these for Tier III and Tier IV redundancy requirements where N+1 mechanical resilience is mandatory.
- Liquid Cooling:Direct-to-chip and immersion architectures using dielectric fluids or water-glycol mixtures to capture heat at the server level. Hyperscale cloud builds in Neom and Riyadh are specifying liquid cooling from ground-up construction as rack densities exceed 50 kW per cabinet.
- Direct Expansion:Refrigerant-based split systems with indoor air-handling units and outdoor condensing units. Small and medium enterprise facilities in Jeddah deploy these for rapid deployment timelines where centralized plant construction is impractical.
- Evaporative Cooling:Adiabatic systems utilizing water-saturated media to pre-cool intake air before mechanical conditioning. Eastern Province deployments face constraints from aquifer depletion rates despite favorable dry-bulb temperature differentials.
Volume sits with Chilled Water Systems; growth tilts toward Liquid Cooling.
End User:
Compliance intensity and latency sensitivity create divergent specification patterns across buyer categories.
- Banking:Financial institutions deploying GPU clusters for real-time fraud detection and digital payment platforms. SFDA-aligned data localization requirements for pharmaceutical banking clients add thermal redundancy layers beyond standard IT loads.
- Telecommunications:5G core network operators building edge facilities across Riyadh and Jeddah metro areas. These deployments demand uninterrupted thermal stability for latency-sensitive subscriber traffic and network function virtualization infrastructure.
- IT Service Providers:Managed hosting and managed security providers serving mid-market enterprises. Procurement concentrates on modular cooling architectures that accommodate unpredictable client density ramps without facility reconfiguration.
- Government:National data sovereignty initiatives and smart city backends requiring localized compute infrastructure. MOHAP health data mandates and broader data localization policies are accelerating public sector facility buildouts with stringent thermal compliance documentation.
Procurement volume concentrates in Banking; Telecommunications is climbing the fastest as 5G densification accelerates.
Size:
Capital deployment scale determines mechanical infrastructure redundancy tiers and operational staffing models.
- Enterprise:Facilities exceeding 10 MW of critical IT load with dedicated central plants and 24/7 operations centers. These installations anchor demand for advanced thermal monitoring systems and predictive maintenance contracts.
- Large:5-10 MW deployments typically serving single-tenant hyperscale requirements or multi-tenant colocation. Operators in this bracket are unbundling cooling procurement from general contractor packages to secure direct manufacturer relationships.
- Medium:1-5 MW facilities balancing growth flexibility against capital efficiency. Jeddah-based operators favor modular cooling additions that align with phased rack deployment schedules.
- Small:Sub-1 MW installations including edge micro data centers and enterprise server rooms. Direct expansion systems dominate here due to installation speed and minimal plant infrastructure requirements.
Facility count peaks in Small; revenue concentration aligns with Enterprise scale.
Deployment Type:
Infrastructure ownership models reshape thermal system financing structures and technology refresh cadences.
- Cloud:Hyperscale operator-owned facilities with standardized designs replicated across multiple Saudi sites. These deployments specify liquid cooling and advanced economizer modes to minimize power usage effectiveness ratios.
- Colocation:Multi-tenant facilities where cooling is sold as a metered utility alongside rack space. Operators compete on thermal resilience guarantees and rapid density accommodation for tenant workload spikes.
- Hybrid:Architectures combining on-premise retained workloads with burst capacity to cloud regions. Cooling design must accommodate unpredictable load shifting between private infrastructure and public cloud endpoints.
- On-Premise:Enterprise-owned facilities serving single-organizational compute requirements. Legacy air-cooled architectures in established Riyadh facilities face disruptive retrofit challenges when integrating higher-density workloads.
Investment flows concentrate in Cloud; Hybrid configurations are gaining share fastest as enterprises navigate data sovereignty requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center cooling infrastructure in Saudi Arabia concentrates where hyperscale investment meets regulatory localization mandates. Consumption outpaces domestic manufacturing capacity, creating import dependency for precision thermal equipment.
Riyadh
Financial sector digitalization and sovereign cloud initiatives anchor cooling demand in the capital. SFDA pharmaceutical data integrity rules require Tier III thermal redundancy for drug logistics databases. King Abdullah Financial District operators are unbundling cooling procurement from general contractor packages to secure direct manufacturer relationships.
Eastern Province
Aramco digital infrastructure and petrochemical enterprise IT loads sustain steady equipment refresh cycles. Aquifer depletion rates constrain evaporative cooling deployment despite favorable ambient dry-bulb temperatures. Dammam industrial zones see concentrated demand for chilled water plants serving redundancy-hungry energy sector facilities.
Jeddah
Red Sea logistics corridors and Islamic banking headquarters drive edge facility construction across the metro area. MOHAP health data localization mandates accelerate medical imaging archive buildouts with stringent thermal compliance documentation. King Abdulaziz International Airport vicinity clusters host telecommunications edge nodes for 5G core densification.
Western Region
Makkah smart city backends and pilgrimage-season traffic spikes create unique thermal load volatility. Seasonal compute surges demand modular cooling architectures that accommodate unpredictable density ramps. Taif highland locations offer marginal ambient temperature advantages for free cooling economizer modes.
NEOM Northwest
The linear city's zero-carbon infrastructure targets attract hyperscale operators specifying liquid cooling from ground-up construction. Tabuk renewable energy corridor wind and solar clusters enable carbon-neutral thermal operations. THE LINE and Oxagon developments rewrite procurement specifications around 100 kW-plus rack densities and dielectric fluid immersion.
Saudi Arabia Data Center Cooling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's data center cooling procurement landscape. Electrical infrastructure majors leverage integrated power and cooling architectures to anchor large-scale projects. Precision climate control specialists sustain position through high-density server environment expertise. Thermal management vendors compete on extreme ambient temperature adaptation. Consolidation pressure intensifies as hyperscale operators unbundle cooling procurement from general contractor packages.
Within the diversified electrical infrastructure tier, Schneider Electric SE and Emerson Electric Co. exemplify integrated system providers. Vertiv Group Corp. and Stulz GmbH occupy positions among focused thermal specialists. Mitsubishi Electric Hydronics & IT Cooling Systems SpA represents Japanese industrial conglomerate participation in precision cooling segments. These archetypes reflect procurement committee preferences for either single-source accountability or best-of-breed component specialization.
| Leading Market Players |
|---|
| Mitsubishi Electric Hydronics & IT Cooling Systems SpA |
| Stulz GmbH |
| Schneider Electric SE |
| Daikin Industries Limited |
| Astek Group |
| Vertiv Group Corp. |
| Asetek A/S |
| Emerson Electric Co. |
| Johnson Controls International PLC |
| Others |
Pricing and Supply Chain Analysis
Liquid cooling system design expertise concentrated among European and North American thermal engineers widens pricing-tier spreads between premium liquid-cooled deployments and standard air-cooled installations across Saudi Arabia. Labor-cost differentials for commissioning specialized dielectric fluid immersion systems versus conventional chilled water plants directly shape procurement committee budget allocations.
Pricing Analysis
Margin tightening in standard chilled water systems reflects inverter-driven compressor technology mandates from SASO efficiency labeling ahead of regulatory phase-in dates. Project-based pricing dominates enterprise Tier III and Tier IV deployments, while subscription-style thermal-as-a-metered-utility models emerge in multi-tenant colocation facilities. Price differentiation rests on certification grade for SFDA pharmaceutical compliance versus baseline IT loads, with banking sector operators showing least price sensitivity due to fraud detection GPU cluster requirements. Small and medium enterprise facilities in Jeddah exhibit highest price sensitivity, favoring rapid-deployment direct expansion systems over capital-intensive centralized plants.
Supply Chain Analysis
Single-source vulnerability sits with low-GWP refrigerant supply concentrated among European and East Asian chemical suppliers, exposing Saudi projects to currency fluctuation risk. Manufacturing of precision cooling equipment draws from Germany, Japan, and the United States, while dielectric fluid production centers on Belgian and American specialty chemical producers. Raw material dependencies include copper heat exchangers, aluminum fin coils, and synthetic refrigerant formulations. Tariff exposure on imported cooling towers and chiller compressors complicates equipment procurement timelines. Distribution runs through authorized distributor networks serving Riyadh, Jeddah, and Dammam industrial zones, with direct manufacturer relationships gaining share as hyperscale operators unbundle thermal procurement from general contractor packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over refrigerant supply chains and localized commissioning expertise determines margin capture. Players are pursuing backward integration into dielectric fluid formulation and captive workforce development for liquid cooling system deployment.
For Market Incumbents: Extend integrated power and cooling architecture offerings to anchor Neom hyperscale developments specifying liquid cooling from ground-up construction. Consolidate position by acquiring Saudi-based commissioning specialists to overcome thermal engineer scarcity threatening project timelines. Defend against emerging pure-play liquid cooling entrants by embedding AI-driven predictive thermal management into control system software layers. For New Entrants and Emerging Players: MEP subcontractors displaced by unbundled cooling procurement represent a channel partner type capable of accelerating market access without direct hyperscale sales force investment. Target edge facility deployments in Jeddah's Red Sea logistics corridor where MOHAP health data localization mandates create thermal compliance documentation requirements underserved by incumbent distributors. Penetrate through dielectric fluid immersion system leasing models that compress customer capital deployment timelines. For Investors and Strategic Acquirers: Re-rating potential sits with liquid cooling pure-plays given Neom's zero-carbon infrastructure targets attracting hyperscale operators specifying 100 kW-plus rack densities. Long-term viability over the next decade hinges on securing Saudi Energy Efficiency Program incentive qualification and localized service capability. Acquisition target archetype: European thermal specialists with existing Middle East commissioning experience and low-GWP refrigerant formulation IP. Watch SASO regulatory phase-in enforcement as the signal indicating acceleration timing for inverter-driven compressor technology replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Fluid Supply | Captive supply of immersion cooling fluids reduces import dependency and currency exposure for Neom-scale deployments. |
| Saudi Energy Efficiency Program Certification | Equipment rebate qualification creates procurement subsidies that accelerate technology refresh cycles ahead of regulatory mandates. |
| Localized Thermal Engineer Training Programs | Workforce development partnerships with SFDA and MOHAP address commissioning scarcity constraining liquid cooling adoption. |
| Direct Manufacturer Relationship Establishment | Bypassing MEP subcontractor markups captures margin as hyperscale operators unbundle cooling procurement in Riyadh and Jeddah. |
| AI-Driven Predictive Thermal Management Platform | Anticipatory load balancing software differentiates control system offerings against reactive setpoint adjustment competitors. |
Research Methodology
Multi-period observation of hyperscale capex disclosures, SASO regulatory filing timelines, and SFDA pharmaceutical data integrity enforcement patterns anchored the trend analysis, supplemented by interviews with data center facility directors, thermal system procurement officers, MEP contractor project managers, and cooling equipment distributor principals. Secondary validation drew from Saudi Energy Efficiency Program documentation, customs import records for precision cooling equipment, and ASHRAE technical standards publications. Bottom-up facility-level demand aggregation and top-down sectoral spend analysis provided triangulation across estimation approaches.
Segment-weighting across cooling technology, end user vertical, facility size tier, and deployment ownership model structured the analytical framework throughout the projection horizon. CAGRs were derived from growth rate convergence modeling applied to hyperscale cloud buildout pipelines and enterprise replacement cycle timing. Industry-specific forecast inputs included 5G core network densification schedules and MOHAP health data localization mandate compliance deadlines.
Caveats apply where SASO efficiency labeling enforcement delays, refrigerant supply chain disruptions, or Neom infrastructure buildout pacing revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding electricity tariff trajectories and carbon accounting policy evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market