
 France Data Center Cooling Market | 2026-2036
France Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Cooling Market Insights
A shortage of certified refrigeration engineers and thermal systems specialists is unwinding near-term deployment timelines for hyperscale projects in France. Schneider Electric SE leverages its integrated building management portfolio to anchor large enterprise contracts across the Paris region. Vertiv Group Corp. competes through specialized in-row cooling architectures designed for high-density GPU clusters. Stulz GmbH dominates precision air conditioning retrofits in legacy colocation facilities where space constraints limit liquid cooling conversions.
Data center cooling encompasses the engineered systems that regulate temperature, humidity, and airflow within IT environments, typically maintaining server inlet conditions between 18°C and 27°C per ASHRAE guidelines while dissipating heat loads that now routinely exceed 30 kW per rack in AI training configurations. Liquid cooling solutions are capturing the fastest expansion trajectory as chip thermal design power thresholds render traditional air-based methods economically unviable at scale. Colocation providers represent the most concentrated buyer segment, with multi-tenant facilities driving standardized modular deployments that reduce engineering redundancy across successive buildouts.
France's RE2020 environmental regulation and the EU Energy Efficiency Directive establish binding thermal performance thresholds that compel operators to adopt free cooling and heat recovery architectures. ANSM and CNIL oversight of health data hosting under HDS certification further restricts cooling system selection for facilities processing sensitive patient records. Facility planners must weigh liquid immersion compatibility against future chip form factor uncertainty as NVIDIA and AMD diverge on package thermal specifications.
Market Dynamics
GPU thermal design power thresholds exceeding 700 watts per chip are compressing air-cooling viability windows across French hyperscale deployments, forcing immediate infrastructure recalibration.
Growth Catalysts
- EU Green Deal mandates:Binding carbon intensity targets for data center operations are accelerating free cooling adoption in Ile-de-France facilities.
- Cloud service provider expansion:French hyperscalers are commissioning multi-megawatt campuses requiring modular liquid cooling architectures at unprecedented scale.
- HDS certification requirements:ANSM and CNIL oversight of health data hosting is mandating redundant thermal systems for patient record processing facilities.
Market Restraints
- Refrigeration engineer scarcity:Certified thermal systems specialists command premium wages that inflate project labor costs by substantial margins.
- Copper and aluminum price volatility:Heat exchanger material costs fluctuate with commodity markets, squeezing equipment manufacturer margins unpredictably.
- RE2020 compliance friction:Thermal performance thresholds impose design constraints that extend engineering review cycles for legacy facility retrofits.
Strategic Opportunities
- Waste heat recovery integration:District heating network partnerships in Paris suburbs are creating revenue streams from rejected thermal energy.
- Edge computing distributed nodes:Regional cities including Lyon and Marseille are attracting micro-data center deployments with localized cooling requirements.
- Immersion cooling standardization:Convergence of dielectric fluid formulations with open compute project specifications is reducing vendor lock-in risks.
Industry Challenges
- Thermal systems integration complexity:Hybrid air-liquid architectures demand cross-functional expertise spanning HVAC, electrical, and IT infrastructure disciplines.
- Chip form factor uncertainty:Divergent NVIDIA and AMD package thermal specifications complicate long-term cooling infrastructure planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Cooling Market |
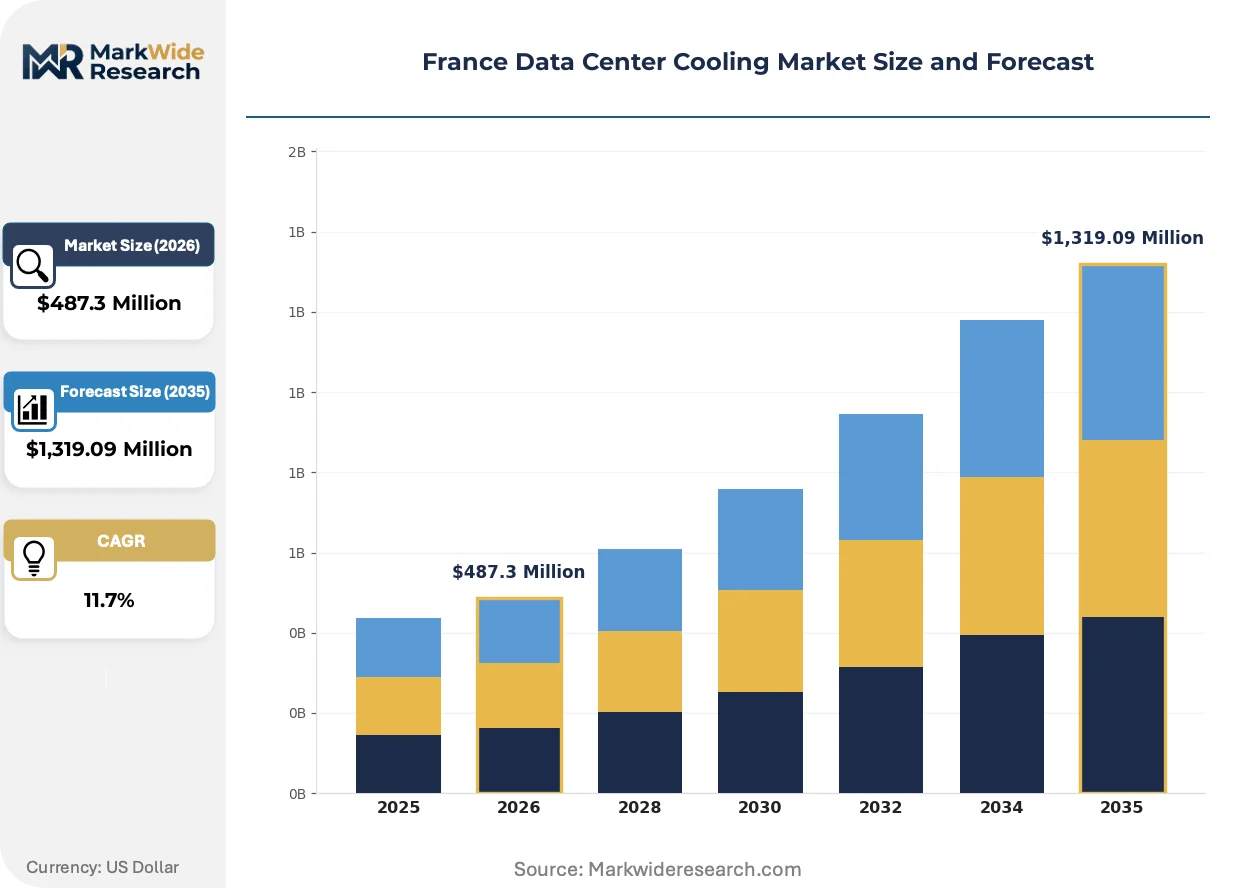
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling End User: Colocation Providers, Enterprises, Cloud Service Providers, Managed Service Providers Deployment Model: On-Premises, Off-Premises, Cloud-Based, Modular Technology: Chilling Units, Cooling Towers, In-Row Coolers, Liquid Immersion |
| Companies Covered | FläktGroup France SAS, ALFA LAVAL Corporate AB, Schneider Electric SE, Johnson Controls Inc., Legrand Group, Vertiv Group Corp., Rittal GmbH & Co. KG, OVHcloud, Stulz GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are fragmenting into multiple competing technical approaches as chip thermal loads outpace legacy infrastructure capacity. Three distinct developments are compressing conventional deployment models.
Direct-to-chip cold plate technology is fragmenting vendor competitive positions by enabling rack densities above 50 kW without facility-level reconstruction. French colocation operators are piloting these systems in Paris-area facilities to accommodate AI training clusters. The approach is fragmenting traditional mechanical contractor relationships as specialized fluid systems vendors capture specification authority.
France's RE2020 thermal regulation and the EU Energy Efficiency Directive are mandating heat recovery integration for new data center construction permits. Operators must demonstrate usable heat export capacity to municipal networks or industrial off-takers. Ile-de-France facilities face the strictest interpretation as regional authorities enforce net-zero pathway commitments.
Specification authority is migrating from facility engineering teams to IT procurement departments as thermal performance becomes a compute availability risk factor. Colocation buyers now demand liquid-ready infrastructure as a baseline requirement rather than upgrade option. This shift is most pronounced among French financial services tenants hosting algorithmic trading infrastructure.
France Data Center Cooling Market Segmentation
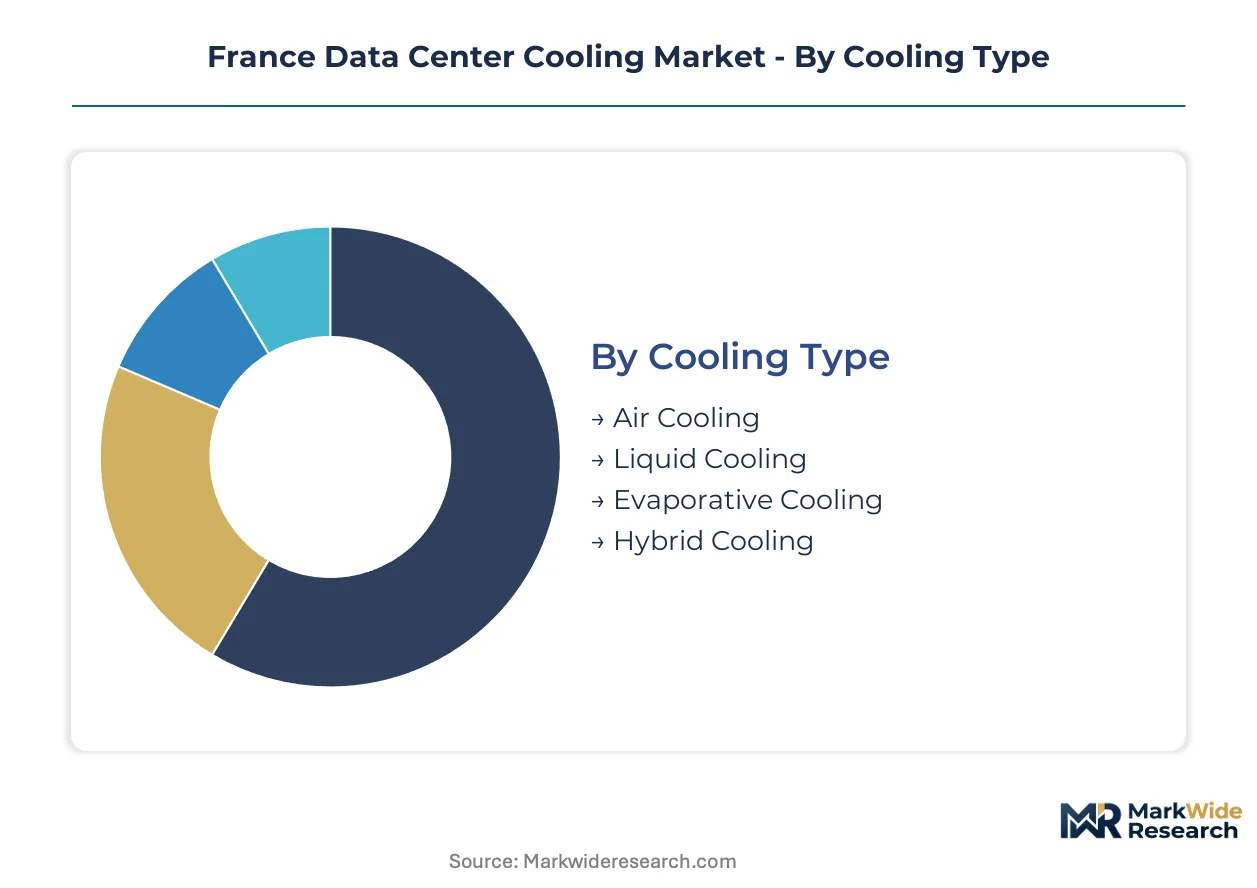
Segmentation in the France Data Center Cooling Market reveals how thermal infrastructure investments fragment across competing architectures and buyer types. Understanding these divisions exposes where liquid cooling substitutes are displacing legacy air systems and which deployment models align with regulatory pressures from ANSM and CNIL oversight.
Cooling Type:
Liquid cooling architectures exert the strongest substitution pressure on incumbent air systems as GPU thermal design power thresholds render traditional methods economically unviable at scale.
- Air Cooling:Conventional raised-floor and perimeter CRAC systems dominate legacy colocation facilities across Ile-de-France where retrofit capital constraints limit immediate conversion. Demand concentrates among smaller enterprises processing non-AI workloads with rack densities below 15 kW, though RE2020 efficiency thresholds are accelerating replacement timelines.
- Liquid Cooling:Direct-to-chip cold plates and immersion systems capture hyperscale deployments from French cloud service providers commissioning multi-megawatt AI training campuses near Paris. ANSM certification requirements for health data hosting mandate redundant thermal architectures that liquid systems satisfy more reliably than air alternatives.
- Evaporative Cooling:Adiabatic and wet-bulb approaches serve facilities leveraging free cooling hours in France's temperate climate zones, particularly attractive for edge nodes in Lyon and Marseille where water availability permits.
- Hybrid Cooling:Combined air-liquid architectures address transition risk for colocation operators hedging against chip form factor uncertainty from NVIDIA and AMD specification divergence.
Air cooling anchors the volume base while liquid cooling gains share at the steepest rate.
End User:
Buyer concentration varies sharply by procurement sophistication and regulatory exposure, with cloud hyperscalers driving standardization while healthcare-facing operators face HDS certification constraints.
- Cloud Service Providers:French hyperscalers including OVHcloud and Scaleway are commissioning modular liquid-ready infrastructure at unprecedented scale, dictating supplier specifications through consolidated procurement power.
- Colocation Providers:Multi-tenant facilities in the Paris metropolitan area drive standardized deployments that reduce engineering redundancy across successive buildouts, with Digital Realty and Equinix operations setting regional thermal benchmarks.
- Enterprises:Financial services tenants hosting algorithmic trading infrastructure now demand liquid-ready infrastructure as baseline rather than upgrade option, shifting specification authority from facility engineering to IT procurement departments.
- Managed Service Providers:Regional operators serving mid-market clients concentrate in secondary cities where RE2020 compliance friction extends engineering review cycles for smaller-scale deployments.
Colocation providers anchor the volume base while cloud service providers expand capacity at the fastest clip.
Deployment Model:
Physical asset location and ownership structure determine cooling system selection flexibility, with modular approaches capturing share where speed-to-market outweighs customization requirements.
- Modular:Prefabricated cooling plants enable rapid deployment for hyperscale campuses facing compressed construction timelines, with Schneider Electric and Vertiv supplying standardized units to Ile-de-France developments.
- On-Premises:Enterprise-owned facilities in Paris suburbs integrate waste heat recovery for district heating network partnerships, creating revenue streams from rejected thermal energy under EU Green Deal mandates.
- Off-Premises:Third-party colocation shifts thermal infrastructure risk to facility operators, with buyers selecting providers based on PUE guarantees and liquid cooling readiness.
- Cloud-Based:Abstracted infrastructure services mask underlying cooling architecture from end users, limiting direct procurement influence over thermal system selection.
On-premises deployments anchor the volume base while modular solutions expand most quickly among time-constrained hyperscalers.
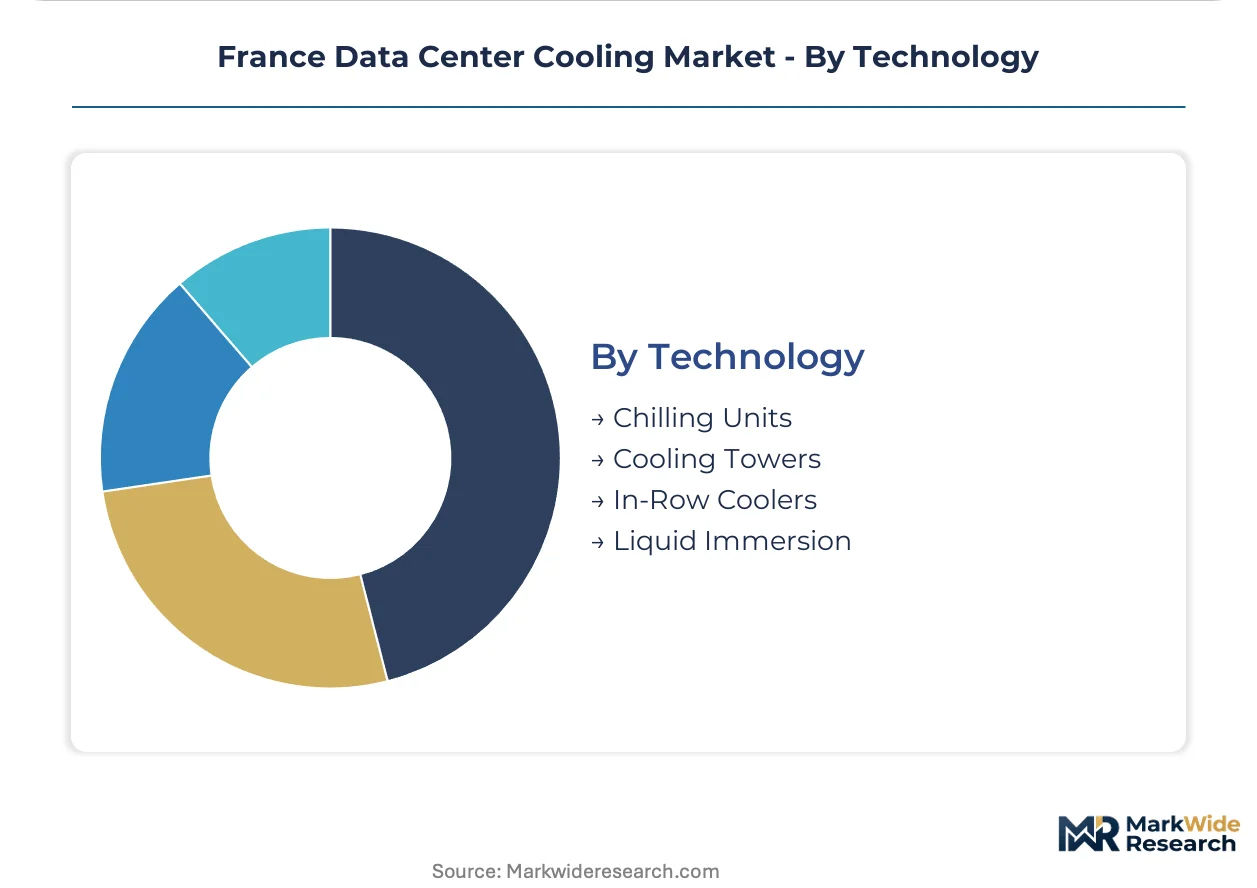
Technology:
Equipment category maturity spans decades of incremental improvement alongside emerging liquid immersion systems that challenge established vendor relationships.
- In-Row Coolers:Close-coupled architectures from Vertiv and Stulz enable high-density GPU clusters without facility-level reconstruction, capturing specification authority in Paris-area colocation retrofits where space constraints limit liquid cooling conversions.
- Liquid Immersion:Dielectric fluid systems are standardizing around Open Compute Project specifications, reducing vendor lock-in risks for French operators piloting AI training infrastructure.
- Chilling Units:Centralized compressor-based systems serve legacy facilities with established maintenance relationships, though copper and aluminum price volatility squeezes equipment manufacturer margins unpredictably.
- Cooling Towers:Evaporative heat rejection equipment supports free cooling integration required under RE2020 thermal regulation for new construction permits in Ile-de-France.
Chilling units anchor the volume base while liquid immersion climbs the fastest as chip thermal loads outpace legacy infrastructure capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM and CNIL oversight of health data hosting under HDS certification anchors thermal system selection for sensitive patient record facilities across France's primary data center corridor. The EU Green Deal and RE2020 thermal regulation establish binding efficiency thresholds that concentrate infrastructure investment in specific metropolitan zones.
Île-de-France
Paris metropolitan hyperscalers commission multi-megawatt AI training campuses requiring modular liquid cooling architectures at unprecedented scale. RE2020 mandates enforce strict thermal performance thresholds for new construction permits in this jurisdiction. The Saclay plateau and Saint-Denis tech corridor host OVHcloud and Scaleway operations setting regional cooling benchmarks.
Auvergne-Rhône-Alpes
Lyon attracts edge computing distributed nodes with localized cooling requirements distinct from hyperscale Paris deployments. The EU Energy Efficiency Directive drives free cooling adoption in this temperate climate zone. Grenoble's semiconductor research cluster generates co-location demand for precision thermal management systems.
Provence-Alpes-Côte d'Azur
Marseille emerges as a Mediterranean connectivity hub driving submarine cable landing station cooling investments. ANSM certification requirements apply to health data processing facilities serving the region's medical research institutions. The Aix-Marseille-Provence metropolis hosts managed service providers targeting mid-market clients with modular deployment models.
Hauts-de-France
Lille's proximity to Benelux markets positions the region for cross-border data center cooling infrastructure serving financial services tenants. RE2020 compliance friction extends engineering review cycles for legacy facility retrofits in this industrial transformation zone. The EuraTechnologies cluster anchors enterprise-owned facilities integrating waste heat recovery for district heating networks.
Nouvelle-Aquitaine
Bordeaux attracts cloud-based infrastructure deployments masking underlying cooling architecture from end users under abstracted service models. The region's renewable energy mix supports carbon intensity targets for data center operations under EU Green Deal mandates. The Bordeaux Technowest business park concentrates smaller-scale colocation providers serving regional enterprise demand.
France Data Center Cooling Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the France data center cooling market. The vendor base concentrates around integrated building management portfolios, specialized fluid systems architectures, and precision air conditioning retrofits. Three strategic archetypes dominate: diversified industrial conglomerates with cross-sector thermal expertise, pure-play cooling specialists with high-density GPU cluster capabilities, and regional service providers with HDS certification compliance depth. Competitive moves center on strategic partnerships for district heating network integration and portfolio diversification into liquid immersion standardization.
Among France-based operators, OVHcloud exemplifies the cloud-native infrastructure archetype with consolidated procurement power over supplier specifications. Vertiv Group Corp. and Stulz GmbH occupy positions as specialized cooling architects serving distinct density tiers—Vertiv through in-row systems for high-performance computing, Stulz through precision conditioning for legacy facility constraints. Schneider Electric SE anchors the integrated building management tier with enterprise contract concentration across the Paris region.
| Leading Market Players |
|---|
| FläktGroup France SAS |
| ALFA LAVAL Corporate AB |
| Schneider Electric SE |
| Johnson Controls Inc. |
| Legrand Group |
| Vertiv Group Corp. |
| Rittal GmbH & Co. KG |
| OVHcloud |
| Stulz GmbH |
| Others |
Pricing and Supply Chain Analysis
ANSM and CNIL HDS certification gates both supplier qualification and price differentiation simultaneously, as uncertified thermal systems vendors remain excluded from health data hosting contracts regardless of cost position. This regulatory screening compresses price competition within the qualified vendor pool while allowing premium capture for HDS-compliant liquid cooling architectures.
Pricing Analysis
Paris metropolitan hyperscalers pay substantial premiums over Lyon and Marseille deployments for liquid-ready infrastructure with immediate availability. Three-tier pricing structure across premium HDS-certified, standard enterprise-grade, and economy retrofit tiers reflects certification depth and thermal density ratings. Cost compression in economy air-cooling tiers is intensifying because copper and aluminum commodity volatility squeezes manufacturer margins. Cloud service providers exhibit lowest price sensitivity due to consolidated procurement power, while managed service providers serving mid-market regional clients face acute margin pressure.
Supply Chain Analysis
Extended lead times for specialized refrigeration compressors and dielectric fluid formulations have normalized across French procurement channels. Manufacturing concentrates in Germany, Italy, and the Netherlands for precision cooling components, with final assembly and commissioning anchored in Ile-de-France facilities. Raw material dependencies center on copper heat exchangers, aluminum cold plates, and fluorinated dielectric fluids sourced from Belgian and German chemical producers. Single-source vulnerability runs through specialized fluid systems vendors certified for HDS-compliant deployments. Distribution runs through mechanical contractors with ANSM certification rather than traditional HVAC wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France data center cooling market rewards vendors who control scarce certified engineering capacity, as refrigeration specialist shortages constrain deployment velocity more than capital availability. Winners will capture specification authority before thermal performance migrates fully to IT procurement departments.
For Market Incumbents: Secure exclusive contracting relationships with ANSM-certified thermal systems engineers to defend against fluid systems vendors capturing specification authority in high-density GPU deployments. Prioritize backward integration into dielectric fluid formulation capabilities to reduce exposure to Belgian and German chemical supplier concentration. Capacity addition in Lyon and Marseille edge markets creates defensive moats against modular competitors. For New Entrants and Emerging Players: Anchor in immersion cooling standardization efforts around Open Compute Project specifications to reduce vendor lock-in risks for French colocation operators piloting AI infrastructure. The most penetrable white space sits in legacy facility retrofits where space constraints limit liquid cooling conversions but RE2020 compliance deadlines force thermal system replacement. Target managed service providers in secondary cities with modular prefabricated cooling plants that compress engineering review cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid cooling sub-segments as direct-to-chip cold plate deployments require specialized fluid systems expertise rather than commodity HVAC components. Long-term viability over the next decade rests on controlling certification depth rather than manufacturing scale. Acquisition targets should display ANSM HDS compliance track records alongside district heating network partnership capabilities. The signal to watch is specification authority migration from facility engineering to IT procurement departments within French financial services tenants.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigeration Engineer Certification Programs | ANSM-certified talent pipelines unlock HDS-compliant contract access for hyperscale health data facilities. |
| District Heating Network Partnerships | RE2020 waste heat recovery mandates create revenue streams from rejected thermal energy in Paris suburbs. |
| Liquid Immersion Standardization | Open Compute Project alignment reduces vendor lock-in risks for French AI training infrastructure deployments. |
| Modular Prefabricated Cooling Plants | Standardized units compress construction timelines for OVHcloud and Scaleway multi-megawatt campuses. |
| Hybrid Air-Liquid Architecture Development | Transition-hedging designs address NVIDIA and AMD chip form factor uncertainty for colocation operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, equipment manufacturer disclosures, and hyperscaler capex announcements. Primary interviews engaged data center facility engineers, thermal systems procurement officers, ANSM certification auditors, and mechanical contractors specializing in HDS-compliant deployments. Secondary validation drew from ANSM regulatory bulletins, CNIL data hosting guidance, EU Energy Efficiency Directive implementation reports, and RE2020 technical compliance documentation. Bottom-up project pipeline analysis triangulates against top-down market sizing across cooling type, end user, and deployment model dimensions.
Segmentation dimensions modeled include cooling architecture category, buyer procurement sophistication, physical deployment structure, and equipment technology tier across the projection horizon. CAGRs derive from unit economics analysis of hyperscale construction pipelines, retrofit replacement cycles for legacy colocation facilities, and edge computing node proliferation in secondary metropolitan zones. Forecast inputs incorporate chip thermal design power trajectory assumptions, RE2020 enforcement intensity variations by region, and certified engineering labor supply elasticity.
Decision-makers should treat outputs as directional under base assumptions of sustained AI training infrastructure investment and stable ANSM certification requirements; material deviation in GPU thermal specifications or regulatory enforcement would warrant model refresh. Chip form factor uncertainty from NVIDIA and AMD represents the primary forecast revision trigger. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market