
 Data Center Liquid Immersion Cooling Market | 2026-2036
Data Center Liquid Immersion Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Liquid Immersion Cooling Market Intelligence
Aftermarket service revenue is narrowing as original equipment manufacturers consolidate fluid management, hardware refresh, and thermal monitoring under bundled contracts. 3M Company leverages its fluorochemical supply chain to control dielectric fluid formulations across multiple vendor ecosystems. Submer Technologies anchors European deployments with modular tank designs that simplify facility retrofits. Green Revolution Cooling specializes in open-bath single-phase systems for high-density GPU clusters.
Data center liquid immersion cooling submerges server hardware in thermally conductive, electrically insulating fluid to dissipate heat without air circulation, operating with fluid temperatures typically between 40°C and 60°C and achieving power usage effectiveness ratios below 1.03. The technology eliminates fan energy, reduces mechanical wear, and enables heat capture for district heating or industrial reuse. Single-phase dielectric fluids currently dominate installed capacity due to simpler fluid handling and lower infrastructure cost, while two-phase systems capture growing interest where extreme density exceeds 100 kW per rack. Hyperscale data centers represent the primary application segment, though edge computing deployments are expanding fastest as distributed AI inference drives thermal challenges beyond conventional air cooling limits.
The U.S. EPA Energy Star program and DOE Better Buildings Challenge establish efficiency benchmarks that favor liquid cooling retrofits in legacy facilities, while the EU F-Gas Regulation restricts synthetic refrigerants and redirects investment toward fluid-based alternatives. China's GB standards for data center energy efficiency, administered by MIIT, mandate PUE thresholds that push operators toward immersion architectures. Facility planners must weigh fluid compatibility roadmaps against server refresh cycles as chip thermal design power crosses thresholds where air cooling becomes economically unviable.
Market Dynamics
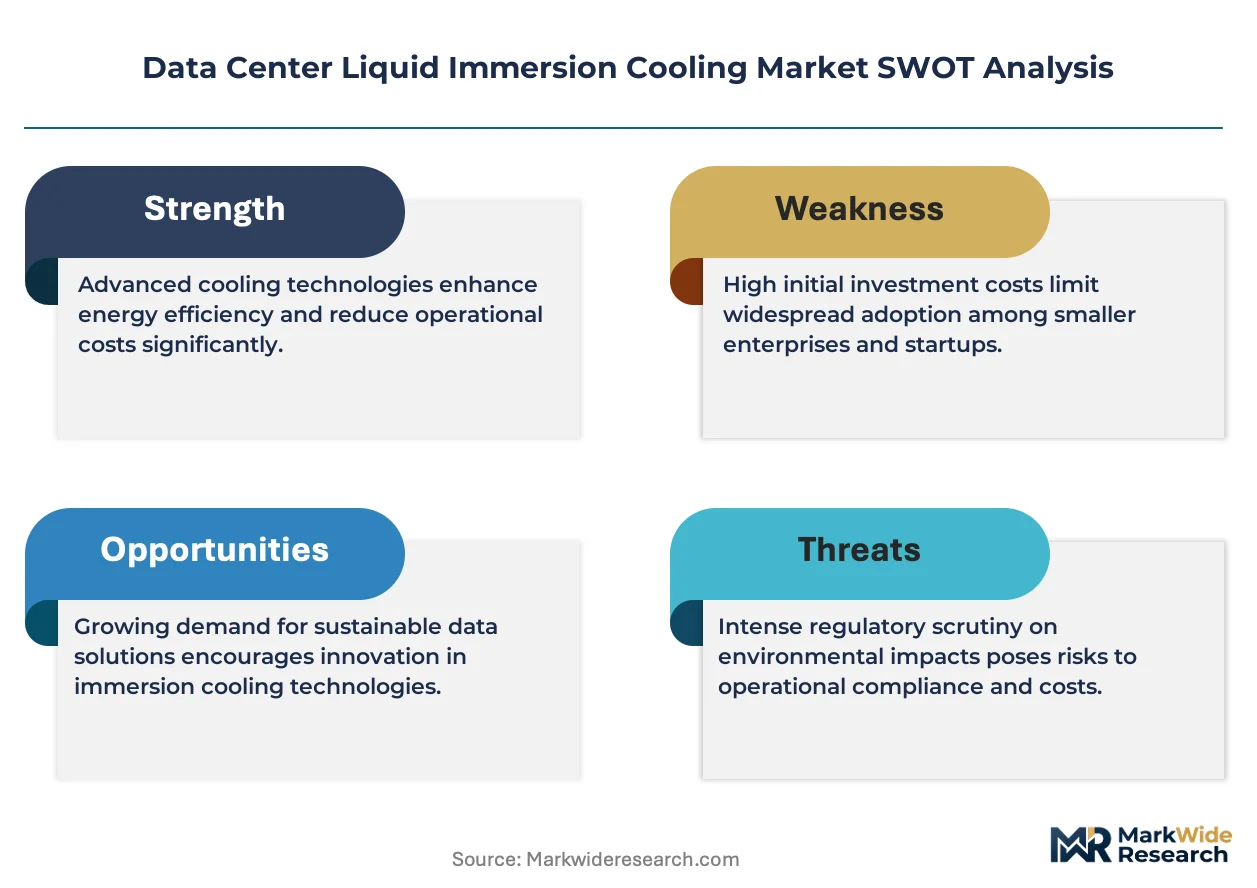
Hyperscale operators face an inflection point where GPU thermal design power thresholds render conventional air cooling economically unviable, forcing wholesale infrastructure redesign around liquid immersion architectures.
Growth Catalysts
- AI Training Cluster Density:Hyperscale facilities deploying NVIDIA H100 and Blackwell architectures require immersion systems to manage rack densities exceeding 100 kW, creating immediate procurement pull.
- EU F-Gas Regulation:Synthetic refrigerant phase-down mandates redirect capital expenditure toward dielectric fluid alternatives in Frankfurt, Amsterdam, and Dublin data center corridors.
- Heat Recovery Economics:District heating integration in Nordic markets transforms cooling from cost center to revenue stream, accelerating facility retrofits in Norway and Finland.
Market Restraints
- Dielectric Fluid Supply Concentration:Fluorochemical feedstock production concentrates among three chemical conglomerates, creating input cost volatility and allocation risk during demand surges.
- Facility Retrofit Capex Burden:Legacy raised-floor data centers require structural reinforcement, fluid containment systems, and piping infrastructure that extends payback periods beyond standard depreciation cycles.
- ASHRAE Certification Gaps:Incomplete thermal guidelines for two-phase immersion create design uncertainty and insurer hesitation for early deployments.
Strategic Opportunities
- Edge AI Inference Nodes:Distributed inference workloads in Singapore, Japan, and South Korea drive demand for compact single-phase tank systems at cellular base stations and metro edge facilities.
- China GB Standard Compliance:MIIT-mandated PUE thresholds below 1.3 for new data center construction create regulatory tailwind for immersion adoption in Beijing, Shanghai, and Guizhou clusters.
- Fluid Formulation Convergence:Partnerships between server OEMs and chemical suppliers to qualify universal dielectric fluids reduce customer switching costs and expand addressable market.
Industry Challenges
- Immersion-Specific Technician Shortage:Fluid handling, leak detection, and server maintenance protocols require specialized training that existing HVAC and IT operations teams lack.
- Warranty Coordination Complexity:Server OEMs, fluid suppliers, and tank manufacturers maintain separate warranty frameworks, creating coverage gaps and dispute resolution overhead for multi-vendor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Liquid Immersion Cooling Market |
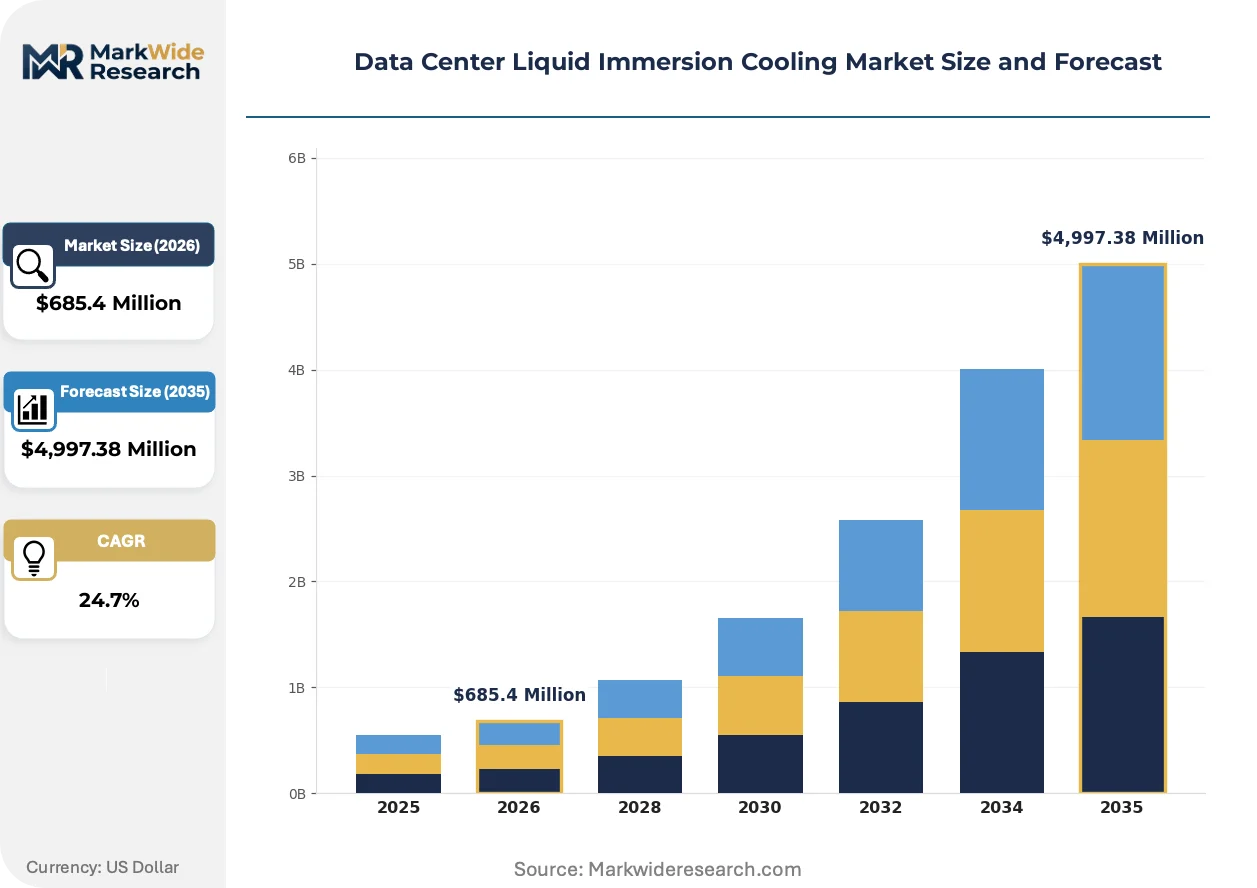
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,997.38 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Single-Phase, Two-Phase, Dielectric Fluids, Fluorocarbon, Mineral Oils Application: Hyperscale Data Centers, Colocation Facilities, Edge Computing, Cloud Service Providers, High Performance Computing End User Type: Telecom Operators, Financial Institutions, Government Agencies, Research Organizations, Content Delivery Networks Deployment Model: On-Premise, Managed Services, Hybrid Models, Cloud-Integrated, Dedicated Facilities |
| Companies Covered | Iceotope Technologies, 3M Company, Submer Technologies, Engineered Fluids, Fujitsu Limited, LiquidStack, Asperitas, Alibaba Cloud, Green Revolution Cooling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Liquid Immersion Cooling Market Strategic Shifts & Innovations
Fluid engineering and thermal management architectures are converging to address the gap between chip-level heat generation and facility-level energy recovery, reshaping how operators evaluate cooling infrastructure investments.
Two-phase immersion systems using engineered fluorochemicals is virtualizing the thermal management layer by enabling direct-to-chip heat extraction without mechanical pumps. Hyperscale operators in Northern Virginia and Singapore are piloting these systems for AI training clusters exceeding 150 kW per rack. The technology is virtualizing traditional chilled water infrastructure, compressing facility mechanical footprints by 60 percent and eliminating secondary heat exchangers.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of legacy dielectric fluids across European supply chains. Chemical suppliers must submit comprehensive safety dossiers by 2025 for continued market access. German and Dutch data center operators are accelerating qualification of alternative synthetic and natural ester fluids to preempt supply disruption.
Colocation buyers are consolidating procurement decisions under single-source liquid cooling contracts that bundle hardware, fluid, and thermal monitoring. This displaces the traditional model of separate HVAC and IT equipment purchasing. The shift is most visible in Frankfurt and London financial services colocation, where risk-averse operators prefer unified service-level agreements over fragmented vendor management.
Data Center Liquid Immersion Cooling Market Segmentation
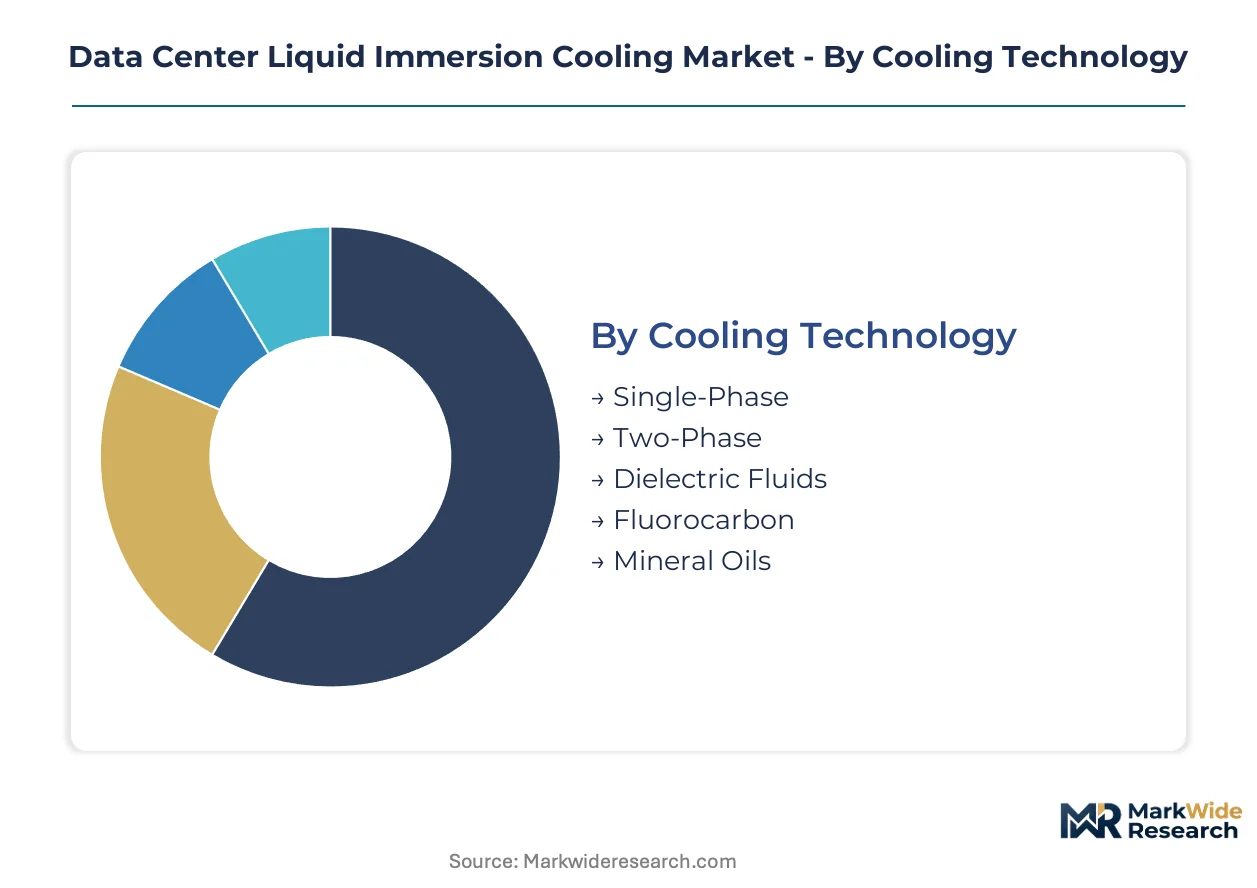
Segmentation reveals how thermal management requirements diverge across facility types and deployment architectures. Procurement cycles, technical specifications, and vendor relationships vary substantially between hyperscale operators and edge computing deployers.
Cooling Technology:
Replacement cycles stretch from months for consumable fluids to decades for infrastructure hardware, creating divergent vendor engagement models across this category.
- Single-Phase:Systems circulate dielectric fluid through sealed tanks without phase change, using pumps and heat exchangers to reject thermal loads. Hyperscale operators in Northern Virginia and Singapore favor single-phase architectures for their mechanical simplicity and compatibility with existing facility infrastructure. The technology dominates current procurement volumes due to lower capital intensity and established maintenance protocols.
- Two-Phase:Boiling dielectric fluids absorb heat through latent vaporization, achieving higher heat flux density per unit volume. AI training clusters exceeding 150 kW per rack in Frankfurt and Tokyo are piloting two-phase systems where rack density economics override infrastructure complexity. ASHRAE guideline gaps and insurer hesitation currently constrain mainstream adoption.
- Dielectric Fluids:Synthetic formulations engineered for electrical insulation and thermal conductivity, typically hydrocarbon or fluorochemical based. Fluid selection locks operators into multi-year supply contracts with chemical conglomerates.
- Fluorocarbon:Perfluorinated compounds offering exceptional chemical stability and non-flammability. REACH authorization pressures in Europe are forcing qualification of alternative formulations.
- Mineral Oils:Natural ester and synthetic hydrocarbon fluids providing lower-cost alternatives to engineered fluorochemicals. Nordic district heating integrations favor mineral oils for their biodegradability and heat transfer compatibility.
Single-phase systems anchor the volume base while two-phase configurations gain share at the steepest rate.
Application:
Capital deployment intensity separates facilities spending $50 million per megawatt from those deploying $500,000 edge nodes, reshaping vendor sales motions.
- Hyperscale Data Centers:Purpose-built facilities exceeding 50 megawatts of critical IT load, operated by cloud providers and large technology enterprises. GPU cluster thermal densities in Northern Virginia and Singapore are forcing wholesale infrastructure redesign around liquid immersion architectures.
- Colocation Facilities:Multi-tenant data centers leasing space to enterprise customers with varying density requirements. Frankfurt and London financial services colocation is consolidating procurement under bundled liquid cooling contracts with unified service-level agreements.
- Edge Computing:Distributed computing nodes positioned close to data sources for latency-sensitive applications. Metro edge facilities in Japan and South Korea are deploying compact single-phase tanks for AI inference workloads.
- Cloud Service Providers:Hyperscale operators delivering infrastructure-as-a-service platforms. Procurement concentrates among five global operators driving standardization of immersion tank designs.
- High Performance Computing:Research and government supercomputing facilities with extreme density requirements. National laboratories in the United States and Germany are early adopters of two-phase systems for exascale computing clusters.
Hyperscale data centers command the largest capital commitment per site while edge computing nodes are expanding most quickly in unit terms.
End User Type:
Risk tolerance and procurement sophistication fragment this category from regulated financial institutions to experimental research organizations.
- Telecom Operators:Communication infrastructure providers managing central offices, mobile switching centers, and emerging edge facilities. 5G network densification in Singapore and South Korea is driving immersion adoption at cellular base stations.
- Financial Institutions:Banks, exchanges, and trading firms operating low-latency colocation infrastructure. Frankfurt-based financial services operators prefer unified vendor contracts to minimize operational risk exposure.
- Government Agencies:Federal, state, and municipal entities with data sovereignty and security requirements. United States Department of Energy efficiency mandates are accelerating liquid cooling retrofits in legacy federal facilities.
- Research Organizations:Universities and national laboratories conducting computationally intensive scientific workloads. German and Dutch research centers are qualifying alternative dielectric fluids ahead of REACH authorization deadlines.
- Content Delivery Networks:Distributed caching infrastructure operators optimizing for throughput and energy efficiency. Cache node deployments concentrate in network-dense metropolitan markets.
Cloud service providers and hyperscale operators anchor infrastructure volume while government agencies are expanding procurement most rapidly under efficiency mandates.
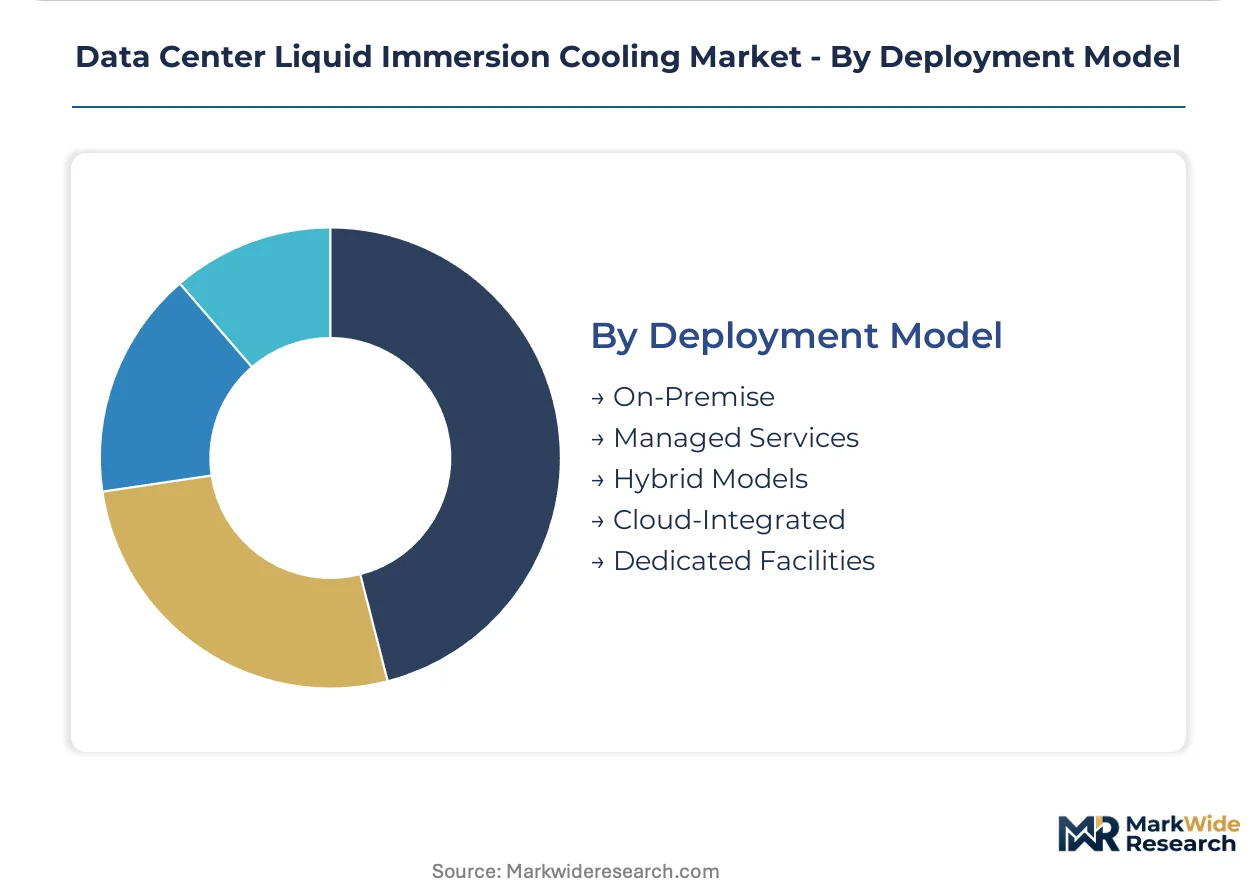
Deployment Model:
Operational control preferences separate this category from fully captive facilities to outsourced thermal management arrangements.
- On-Premise:Enterprise-owned and operated facilities with direct capital responsibility for cooling infrastructure. Legacy raised-floor data centers require structural reinforcement and fluid containment systems that extend payback periods.
- Managed Services:Third-party operation of immersion cooling infrastructure under long-term service contracts. Colocation buyers in London and Frankfurt are shifting toward bundled procurement of hardware, fluid, and thermal monitoring.
- Hybrid Models:Combinations of captive and outsourced infrastructure across different workload tiers. Financial institutions use hybrid approaches to segregate sensitive trading infrastructure from general IT workloads.
- Cloud-Integrated:Liquid cooling deployed within hyperscale cloud provider facilities under reserved capacity arrangements. GPU cluster reservations with major cloud providers include immersion-cooled infrastructure options.
- Dedicated Facilities:Single-tenant purpose-built data centers with customized thermal architectures. AI training cluster operators in Northern Virginia favor dedicated facilities for security and density optimization.
On-premise deployment retains the largest installed base while managed services are climbing the fastest as colocation operators consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets pursuing heat recovery economics and those prioritizing density maximization for AI training workloads. Nordic operators treat cooling infrastructure as revenue-generating assets through district heating integration, while Asian hyperscalers optimize for rack-level thermal management above 100 kW. European deployments navigate fluorochemical regulatory constraints that reshape fluid supply chains.
United States
Northern Virginia data center clusters drive procurement for GPU-intensive AI training facilities exceeding 150 kW per rack. The EPA Energy Star program and DOE Better Buildings Challenge establish efficiency benchmarks that accelerate liquid cooling retrofits in legacy federal facilities. Dallas-Fort Worth and Phoenix markets are expanding immersion deployments as secondary locations to Virginia's capacity-constrained primary corridor.
Germany
Frankfurt's financial services colocation sector consolidates procurement under bundled liquid cooling contracts with unified service-level agreements. The EU F-Gas Regulation restricts synthetic refrigerants and redirects capital expenditure toward dielectric fluid alternatives. REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of legacy fluids across German supply chains ahead of 2025 deadlines.
Singapore
Metro edge facilities and cellular base stations deploy compact single-phase tank systems for distributed AI inference workloads. The tropical climate and land constraints make air cooling economically unviable for new hyperscale construction. Government efficiency mandates for data center PUE thresholds push operators toward immersion architectures in the Jurong and Changi cluster zones.
China
MIIT-administered GB standards mandate PUE thresholds below 1.3 for new data center construction in Beijing, Shanghai, and Guizhou clusters. Domestic cloud providers are standardizing immersion tank designs for captive AI training infrastructure. The Yangtze River Delta and Pearl River Delta regions concentrate deployment activity where regulatory enforcement is strictest.
Netherlands
Amsterdam data center corridor operators accelerate qualification of alternative synthetic and natural ester fluids to preempt REACH-related supply disruption. District heating integration in Rotterdam and Utrecht transforms cooling from cost center to revenue stream. Dutch research centers are early adopters of two-phase systems for exascale computing clusters.
Data Center Liquid Immersion Cooling Market Key Industry Players
Capability concentration sits with chemical conglomerates controlling fluorochemical feedstock formulations; scale advantage sits with tank fabricators serving hyperscale deployment volumes. The market structure organizes around three strategic archetypes: fluid suppliers locking operators into multi-year supply contracts, modular tank manufacturers simplifying facility retrofits, and integrated system providers bundling hardware with thermal monitoring. Dominant competitive moves include strategic partnerships between server OEMs and chemical suppliers for fluid qualification, and geographic expansion into Nordic markets pursuing heat recovery economics.
Within the fluid formulation tier, 3M Company represents the archetype of supply chain control through fluorochemical expertise. Submer Technologies occupies a position among European modular tank specialists addressing facility retrofit complexity. Green Revolution Cooling exemplifies the open-bath system approach for high-density GPU clusters. These three anchors illustrate how vendor relationships consolidate around bundled procurement models displacing traditional separate HVAC and IT equipment purchasing.
| Leading Market Players |
|---|
| Iceotope Technologies |
| 3M Company |
| Submer Technologies |
| Engineered Fluids |
| Fujitsu Limited |
| LiquidStack |
| Asperitas |
| Alibaba Cloud |
| Green Revolution Cooling |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors carry fluorochemical feedstocks that anchor dielectric fluid pricing, translating supply concentration into tiered contract premiums for hyperscale operators while forcing modular tank vendors toward project-based structures to absorb input volatility.
Pricing Analysis
Long-term offtake agreements dominate procurement between hyperscale operators and chemical conglomerates, locking in fluid supply across multi-year horizons. Three-tier pricing structure across premium fluorochemical, standard synthetic ester, and economy mineral oil levels separates warranty-backed installations from bare-metal deployments. Cost compression in economy-tier mineral oils is intensifying because Nordic district heating integrations commoditize heat recovery value. Edge computing deployers exhibit highest price sensitivity due to distributed unit economics, while financial services colocation in Frankfurt shows lowest sensitivity under unified service-level agreement preferences.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for server OEMs qualifying immersion tank components. Fluorochemical feedstock production concentrates in the United States, Japan, and Germany, drawing from specialized petrochemical intermediates and precision-machined heat exchanger assemblies. Single-source vulnerability persists for engineered perfluorinated compounds amid REACH authorization timelines. Distribution runs through direct OEM partnerships for hyperscale volumes and regional systems integrators for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data center liquid immersion cooling is exiting a capex-constrained trough as GPU thermal density thresholds force infrastructure replacement cycles, positioning the market for cyclical recovery through the AI training buildout.
For Market Incumbents: Build captive fluid formulation capabilities to lock hyperscale operators into multi-year supply moats. Deepen backward integration into fluorochemical feedstocks to preempt allocation risk during demand surges. Expand certification engineering teams to close ASHRAE guideline gaps that currently constrain two-phase system adoption.
For New Entrants and Emerging Players: Metro edge facilities in Southeast Asia represent the most penetrable entry point given tropical climate constraints and distributed AI inference demand. Compact single-phase tank systems for cellular base stations offer lowest competitive density versus hyperscale vendor relationships. Pursue managed service contracts rather than equipment sales to bypass incumbent hardware bundling.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant thermal management divisions holding legacy dielectric fluid IP. Five-to-ten year viability hinges on qualification velocity for REACH-compliant formulations. Watch Nordic district heating integration rates as the inflection signal for heat-recovery economics scaling beyond pilot installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluid Formulation Partnership | Server OEM collaboration with 3M accelerates universal dielectric qualification across vendor ecosystems. |
| Modular Tank Platform Launch | Submer's retrofit-focused designs reduce facility conversion timelines for legacy raised-floor data centers. |
| Geographic Expansion | Green Revolution Cooling targets Nordic markets where district heating transforms cooling into revenue streams. |
| Long-term Supply Agreement | Hyperscale operators lock fluorochemical volumes to secure allocation during AI cluster deployment surges. |
| Certification Investment | ASHRAE guideline development reduces insurer hesitation for two-phase immersion pilot programs. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with data center facility directors, thermal engineering leads at server OEMs, procurement officers at colocation operators, and chemical supply chain managers; and secondary validation through EPA Energy Star filings, DOE Better Buildings Challenge disclosures, EU F-Gas Regulation implementation reports, MIIT GB standard documentation, and hyperscaler capital expenditure disclosures. Bottom-up tank deployment estimates triangulated against top-down fluid consumption projections.
Forecast inputs considered cooling technology segmentation, application density tiers, end-user risk profiles, and regional regulatory clusters across the projection horizon. CAGRs derived from installation volume trajectories, fluid replacement cycle economics, and infrastructure payback period sensitivity. Modeled variables included GPU thermal design power evolution, REACH authorization timelines, and district heating integration penetration.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting data center financing costs or construction labor availability would shift the trajectory. Forecasts reflect documented assumptions on chip power trajectories and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market