
 Iaas/Hosting Infrastructure Services Market | 2026-2036
Iaas/Hosting Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Iaas/Hosting Infrastructure Services Market Foresight
Enterprise buyer fragmentation across mid-market SaaS vendors and healthcare systems is repositioning procurement authority away from centralized IT departments toward line-of-business owners. Amazon Web Services leverages its hyperscale footprint to dominate commercial workloads, while Microsoft Azure anchors enterprise hybrid environments through deep Active Directory integration. Google Cloud Platform competes on Kubernetes-native infrastructure and AI-optimized silicon.
Infrastructure as a Service and hosting infrastructure services deliver compute, storage, and networking resources through virtualized or bare-metal provisioning over internet protocol networks, with service-level agreements typically guaranteeing 99.99% uptime and sub-50-millisecond latency for tier-1 workloads. Public cloud deployments absorb the majority of new capacity as enterprises retire owned data centers, while hybrid cloud architectures capture the fastest expansion by letting regulated workloads remain on-premises while bursting peak demand to off-site facilities. Container orchestration within the technology dimension now defines platform selection, with serverless functions gaining traction for event-driven microservices.
FCC guidelines on net neutrality and data center interconnection shape bandwidth pricing and peering arrangements across United States facilities, while EU GDPR and the EU AI Act impose data localization and algorithmic audit obligations that constrain cross-border workload migration. ISO 27001 and SOC 2 Type II certifications have become baseline requirements for vendor qualification in financial services and government procurement. Stakeholders must weigh sovereign cloud mandates against the operational complexity of multi-vendor management as regulatory fragmentation intensifies.
Market Dynamics
Container orchestration is consolidating procurement authority around platform-native capabilities, forcing infrastructure vendors to embed Kubernetes control planes directly into their compute offerings or surrender enterprise workloads to hyperscale competitors.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic audit requirements and data residency rules are compelling financial services firms to expand sovereign cloud deployments across Germany, France, and the Netherlands.
- Healthcare system digitization:Hospital networks and clinical research organizations are migrating imaging archives and genomics pipelines to HIPAA-compliant hosted environments with sub-50-millisecond latency guarantees.
- Bare-metal provisioning:High-frequency trading platforms and quantitative hedge funds are driving demand for single-tenant physical servers with direct hardware access and deterministic performance.
Market Restraints
- Energy cost volatility:Electricity prices in Ireland and the Netherlands are compressing margins for hyperscale data center operators dependent on grid power rather than captive renewable generation.
- Silicon supply concentration:Advanced GPU and AI accelerator availability remains constrained by foundry capacity concentrated in Taiwan, limiting infrastructure scaling for machine learning workloads.
- Cross-border data friction:GDPR Article 44 restrictions on international transfers are fragmenting workload architectures and raising compliance costs for multi-region deployments.
Strategic Opportunities
- Edge computing convergence:5G network slicing and distributed micro data centers are enabling ultra-low-latency hosting for autonomous vehicle telemetry and industrial IoT control systems.
- India's data localization requirements:RBI and TRAI mandates for financial and telecom data residency are creating demand for in-country infrastructure builds by global and domestic operators.
- Carbon-aware scheduling:Integration of renewable energy forecasting with workload orchestration is differentiating sustainable hosting offerings for ESG-mandated procurement.
Industry Challenges
- Platform engineering talent scarcity:Shortages of site reliability engineers and Kubernetes-certified architects are extending deployment timelines and inflating compensation costs.
- Multi-cloud integration complexity:Enterprises managing workloads across heterogeneous environments face operational overhead from inconsistent APIs, security postures, and cost visibility tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iaas/Hosting Infrastructure Services Market |
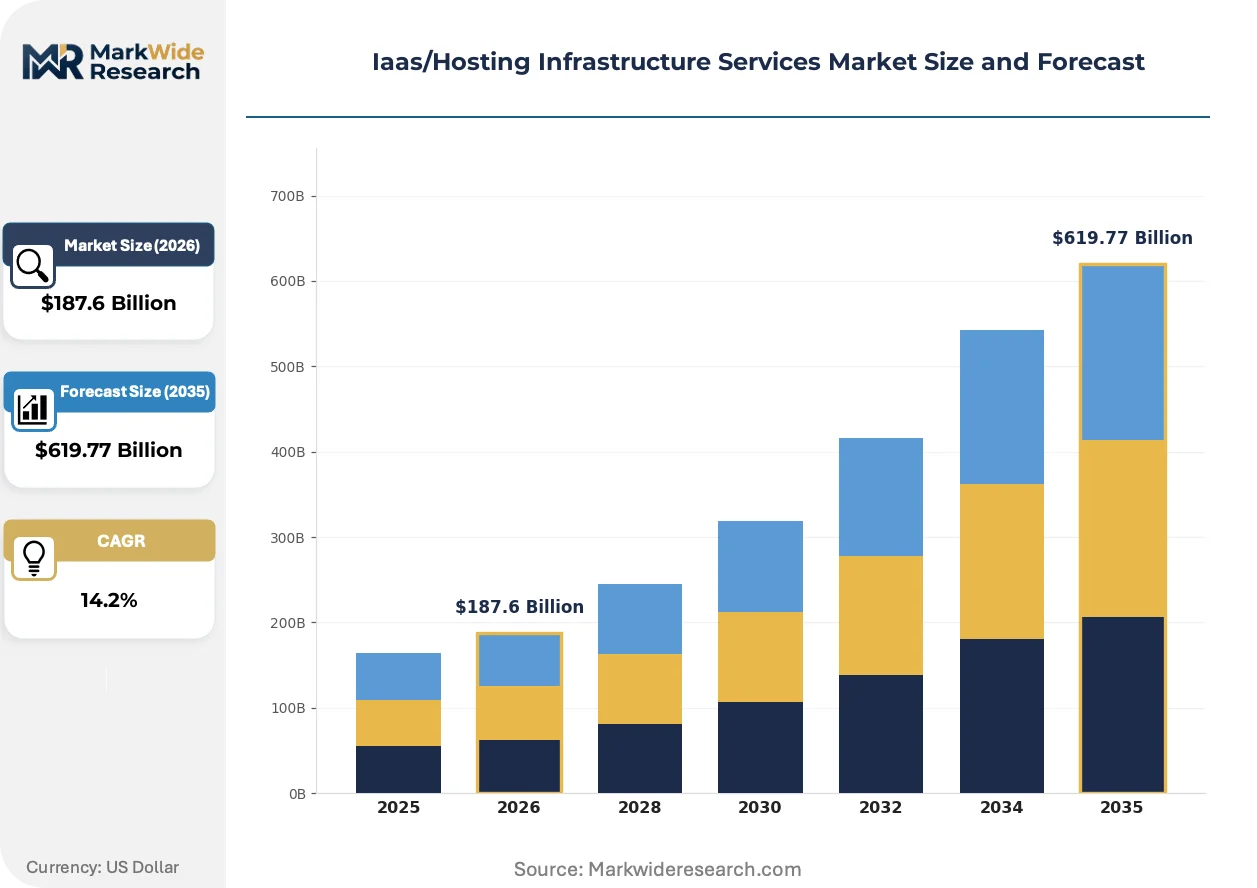
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Deployment Model: On-Premises, Off-Premises, Managed Hosting, Colocation Customer Type: Startups, SMEs, Enterprises, Government Technology: Containers, Virtualization, Bare Metal, Serverless |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Cloud, DigitalOcean, Hewlett Packard Enterprise, Oracle Cloud, Verizon, Red Hat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iaas/Hosting Infrastructure Services Market Shifts & Advancements
Serverless computing architectures and carbon-intelligent workload placement are compressing traditional infrastructure procurement cycles, while regulatory fragmentation is forcing vendors to engineer region-specific compliance layers into standardized platforms.
Arm-based silicon is consolidating its position in cloud-native compute tiers, offering superior performance-per-watt ratios for containerized microservices and edge inference workloads. SaaS vendors and mobile backend providers are migrating production environments to Graviton and Ampere instances at accelerating velocity. This architecture shift is consolidating vendor differentiation around custom silicon design rather than commodity x86 provisioning.
REACH chemical restrictions and EU Green Deal energy efficiency standards are mandating refrigerant transitions and PUE disclosures for data center operations across member states. Operators must retrofit cooling systems and publish granular carbon intensity metrics to maintain eligibility for public sector contracts. Germany and France are imposing the strictest enforcement timelines, with facility certifications required by national environmental agencies.
Line-of-business units are displacing centralized IT departments as primary procurement decision-makers for infrastructure services, particularly in mid-market enterprises and healthcare systems. Vendor selection criteria now emphasize developer experience and API-native integration over traditional SLA benchmarks. This pattern is most pronounced in the United States, where shadow IT budgets and low-code platform adoption have accelerated decentralized technology spending.
Iaas/Hosting Infrastructure Services Market Segmentation
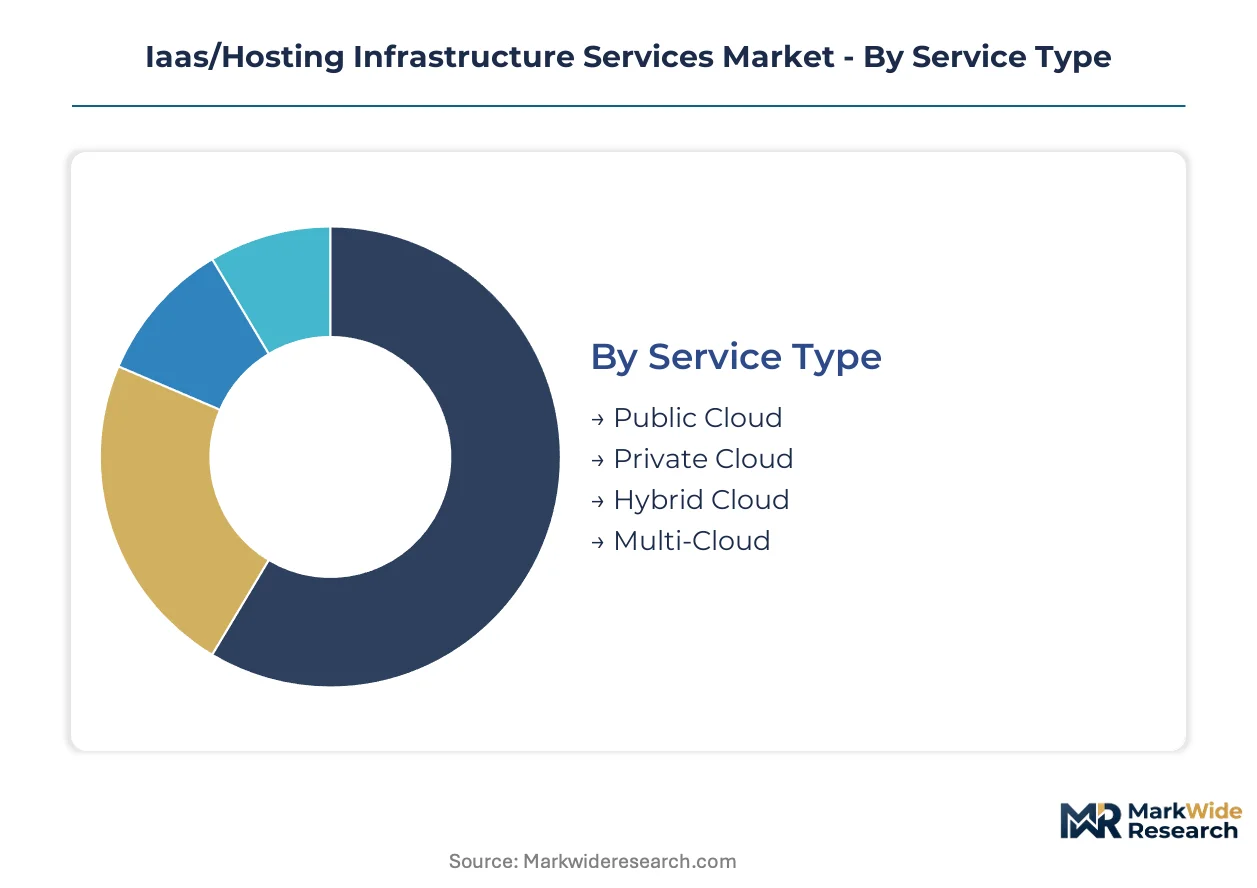
Infrastructure procurement patterns diverge sharply across deployment architectures and operational models. Buyers weigh sovereignty requirements against elasticity needs, while technology choices increasingly lock enterprises into specific vendor ecosystems.
Service Type:
Supply concentration among hyperscale operators tilts commercial dynamics toward platform-native capabilities and egress fee structures.
- Public Cloud:Shared infrastructure pools deliver elastic compute and storage through consumption-based metering. Financial services firms in Germany favor public deployments for non-regulatory workloads despite sovereign cloud mandates for core systems.
- Private Cloud:Single-tenant environments provision dedicated resources with customized security postures. Healthcare systems across France and the Netherlands deploy private infrastructure for imaging archives requiring HIPAA-equivalent data residency.
- Hybrid Cloud:Unified orchestration spans on-premises and off-premises resources. Bursting peak demand to external facilities while retaining sensitive data locally addresses GDPR Article 44 transfer restrictions.
- Multi-Cloud:Workload distribution across heterogeneous platforms mitigates vendor lock-in. Operational overhead from inconsistent APIs and security postures challenges enterprise platform engineering teams.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Deployment Model:
Cost tier differentiation separates capital-intensive facility ownership from operational expenditure models favored by mid-market buyers.
- On-Premises:Owned data centers retain physical control over hardware and environmental systems. Energy cost volatility in Ireland compresses margins for operators dependent on grid power rather than captive renewable generation.
- Off-Premises:Third-party facilities absorb capital expenditure and operational complexity. Sub-50-millisecond latency guarantees from tier-1 providers satisfy high-frequency trading platforms in London and Frankfurt.
- Managed Hosting:Service providers assume infrastructure lifecycle management and security patching. ISO 27001 certification has become baseline for financial services vendor qualification.
- Colocation:Shared facility space with customer-managed equipment balances control and cost. REACH refrigerant restrictions and EU Green Deal standards mandate cooling system retrofits across German and French facilities.
Volume concentrates in Off-Premises. Margin expansion favors Managed Hosting.
Customer Type:
Application maturity and procurement authority reshape vendor engagement strategies across organizational scales.
- Startups:Cloud-native architectures and serverless functions minimize upfront infrastructure commitment. API-native integration and developer experience dominate vendor selection over traditional SLA benchmarks.
- SMEs:Mid-market enterprises delegate procurement authority to line-of-business owners rather than centralized IT departments. Shadow IT budgets in the United States accelerate decentralized technology spending.
- Enterprises:Complex workload portfolios demand hybrid architectures with consistent governance frameworks. Container orchestration consolidates procurement around platform-native Kubernetes capabilities.
- Government:Public sector contracts require SOC 2 Type II certification and granular carbon intensity disclosures. Sovereign cloud mandates in Germany prioritize data localization and algorithmic audit trails under EU AI Act compliance.
Procurement velocity peaks with Startups. Contract value concentrates with Enterprises.
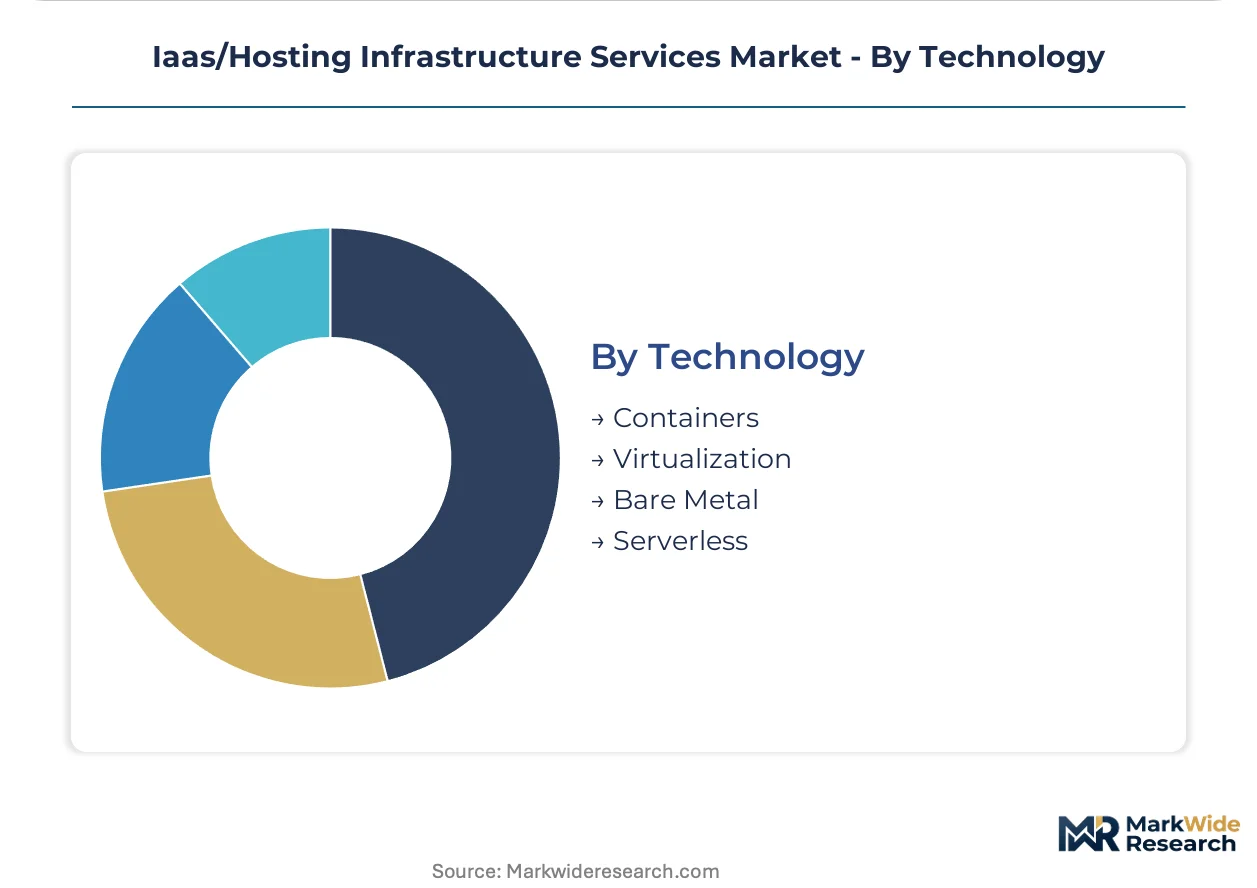
Technology:
Silicon architecture shifts and abstraction layers redefine performance-per-watt optimization and operational paradigms.
- Containers:Microservice packaging with Kubernetes orchestration enables portable, scalable deployment patterns. Bare-metal provisioning for high-frequency trading demands deterministic performance that containerized workloads increasingly approximate.
- Virtualization:Hypervisor-based resource abstraction remains prevalent in legacy enterprise environments. VMware and Microsoft hypervisors anchor enterprise hybrid environments through deep Active Directory integration.
- Bare Metal:Single-tenant physical servers provide direct hardware access without virtualization overhead. Quantitative hedge funds in London and New York drive demand for deterministic latency in tick-to-trade pipelines.
- Serverless:Event-driven function execution eliminates infrastructure provisioning overhead. Carbon-aware scheduling integrates renewable energy forecasting with workload orchestration for ESG-mandated procurement.
Adoption momentum favors Containers. Performance-critical workloads retain Bare Metal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent clusters in Germany, the United States, India, and the Netherlands anchor infrastructure deployment decisions. Sovereign cloud mandates and data residency requirements reshape procurement authority across these geographies.
United States
Financial services firms in New York and Chicago drive demand for bare-metal provisioning with deterministic latency for high-frequency trading. FCC net neutrality guidelines shape bandwidth pricing and peering arrangements for hyperscale data center interconnection. The Northern Virginia data center corridor maintains the densest concentration of cloud capacity worldwide.
Germany
EU AI Act compliance mandates and GDPR Article 44 restrictions compel financial institutions toward sovereign cloud deployments with algorithmic audit trails. Germany's national environmental agencies enforce REACH refrigerant transitions and PUE disclosure requirements under EU Green Deal standards. The Frankfurt Rhine-Main metro hosts Europe's largest financial services infrastructure cluster.
India
RBI data localization requirements for financial services and TRAI mandates for telecom data residency accelerate in-country infrastructure builds. India's central bank and telecommunications regulator impose strict cross-border transfer limitations on payment and subscriber data. Mumbai and Bangalore concentrate domestic cloud operator expansion and global hyperscale region launches.
Netherlands
Energy cost volatility compresses margins for grid-dependent hyperscale operators while renewable-powered facilities gain procurement preference. EU Green Deal energy efficiency standards mandate cooling system retrofits and granular carbon intensity disclosures for public sector eligibility. The Amsterdam metro area anchors continental peering exchanges and submarine cable landing points.
United Kingdom
Healthcare system digitization drives migration of imaging archives and genomics pipelines to HIPAA-equivalent hosted environments. The UK's data protection framework maintains GDPR-aligned restrictions on international transfers post-Brexit. London's financial district sustains demand for sub-50-millisecond latency guarantees from tier-1 colocation providers.
Iaas/Hosting Infrastructure Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Hyperscale operators with integrated platform ecosystems anchor commercial workloads, while regional specialists capture sovereign compliance mandates. Three archetypes dominate: full-stack cloud providers, managed hosting specialists, and infrastructure software vendors. Capacity expansion in renewable-powered facilities and strategic partnerships for edge computing distribution represent the dominant competitive vectors.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud Platform occupy positions defined by platform-native capabilities and egress fee structures. AWS exemplifies the commercial workload anchor through hyperscale footprint dominance. Microsoft Azure represents enterprise hybrid environment integration through directory services alignment. Google Cloud Platform sits within the Kubernetes-native and AI-optimized silicon specialization vector.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Cloud |
| DigitalOcean |
| Hewlett Packard Enterprise |
| Oracle Cloud |
| Verizon |
| Red Hat |
| Others |
Supply & Pricing Matrix
Financial services procurement teams in Frankfurt and London anchor pricing power for tier-1 infrastructure services, consolidating contract negotiations around consumption-based metering with committed use discounts rather than spot-market spot instances.
Pricing Analysis
Bundled managed services with integrated security and compliance layers command premium positioning against unbundled raw compute and storage provisioning. Three-tier pricing structure across premium sovereign cloud, standard enterprise multi-tenant, and economy spot-instance tiers separates buyers by data residency requirements and latency sensitivity. Cost compression in economy tiers is intensifying because hyperscale operators are absorbing GPU supply constraints into margin structures rather than passing through silicon scarcity premiums. Startups and cloud-native developers exhibit highest price sensitivity, while quantitative trading firms and government agencies accept substantial premiums for deterministic bare-metal performance and algorithmic audit trails.
Supply Chain Analysis
Direct-to-enterprise sales channels handle hyperscale buyer demand, while managed service providers and systems integrators intermediate mid-market and healthcare system procurement. Taiwan, South Korea, and the United States concentrate advanced GPU and AI accelerator foundry capacity, creating single-source vulnerability for machine learning infrastructure scaling. Supply chain architecture draws from specialized cooling equipment manufacturers in Germany, power distribution systems from Chinese industrial suppliers, and subsea cable infrastructure from Japanese and European consortiums. Tariff exposure on Chinese-manufactured power electronics and cooling components threatens margin stability for facility operators dependent on imported environmental systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
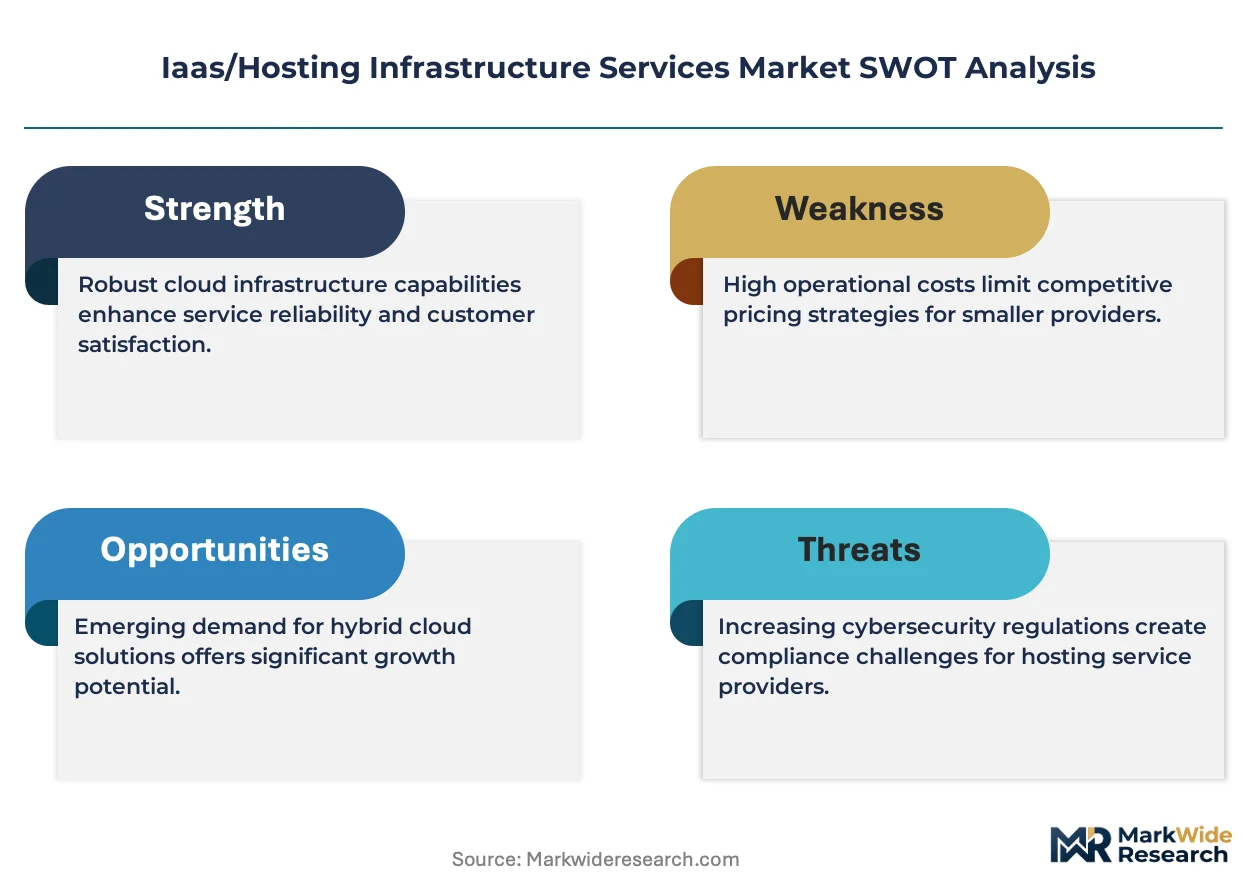
Infrastructure as a Service functions as a stable compounder, with regulatory compliance mandates for data residency and algorithmic transparency generating durable replacement demand across financial services and government verticals.
For Market Incumbents: Deepen sovereign cloud certification investments in Germany and India to preempt emerging regional specialists from capturing EU AI Act and RBI data localization mandates. Prioritize captive renewable generation partnerships in the Netherlands and Ireland to offset energy cost volatility compressing grid-dependent operator margins. Vertical integration into Arm-based silicon design, following AWS Graviton and Ampere Computing roadmaps, protects against foundry concentration risk while delivering performance-per-watt differentiation for containerized workloads.
For New Entrants and Emerging Players: API-first developer experience platforms offer the most penetrable entry vector against entrenched hyperscale incumbents, particularly for mid-market SaaS vendors delegating procurement authority to line-of-business engineering teams. Carbon-aware workload scheduling with renewable energy forecasting addresses ESG-mandated procurement emerging in European enterprise and public sector accounts. Target India's domestic cloud infrastructure builds under RBI and TRAI data localization requirements, where global hyperscale presence remains underdeveloped relative to demand velocity.
For Investors and Strategic Acquirers: Hyperscale cloud operators with sovereign compliance capabilities are the most active acquirers in this space, consolidating regional specialists with established data center footprints and government security clearances. Acquisition target archetypes include managed Kubernetes platform engineering firms and edge computing micro data center operators with 5G network slicing partnerships. Platform engineering talent scarcity extending deployment timelines serves as the critical signal to watch for infrastructure scaling bottlenecks and vendor switching cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act compliance in Germany and France locks in public sector contract eligibility. |
| Arm-Based Silicon Migration | Graviton and Ampere instances reduce power consumption for containerized microservices workloads. |
| Edge Computing Partnership | 5G network slicing with automotive OEMs enables autonomous vehicle telemetry hosting. |
| Carbon-Aware Scheduling | Renewable energy forecasting integration differentiates offerings for ESG-mandated procurement. |
| Managed Kubernetes Platform | Embedded control planes capture enterprise workloads from hyperscale competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud infrastructure procurement officers, platform engineering directors, data center facility managers, and regulatory compliance leads with secondary validation against hyperscaler capex disclosures, SEC filings, EU regulatory impact assessments, and national data center energy efficiency reports. Bottom-up triangulation across service type adoption curves and top-down reconciliation against aggregate infrastructure spending patterns anchored volume and value estimates.
Segment-weighting approaches distributed forecast contributions across deployment architecture, customer organization scale, and technology abstraction layer dimensions over the projection horizon. CAGRs were derived from fitted adoption curves incorporating sovereign cloud mandate implementation timelines, healthcare system digitization spending trajectories, and bare-metal provisioning demand from quantitative trading platform expansion. Forecast inputs included foundry capacity constraints for AI accelerators, renewable energy cost curves, and cross-border data transfer restriction enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for serverless function architectures displacing container orchestration would alter the outlook. Forecasts reflect documented assumptions on regulatory implementation timelines and silicon supply normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
Poland Data Center Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
South America Data Center Server Market