
 Malaysia Data Center Market | 2026-2036
Malaysia Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Data Center Market Insights
Multi-source infrastructure procurement is realigning how enterprises and cloud operators secure capacity across Peninsular Malaysia. Amazon Web Services Inc. leverages its early hyperscale commitments to anchor build-to-suit developments in Iskandar Puteri. Microsoft Corp. competes through direct land acquisitions that sustain long-term expansion options in Cyberjaya. Google LLC differentiates by prioritizing renewable energy partnerships that align with corporate sustainability mandates.
Malaysia data centers are mission-critical facilities housing servers, storage systems, and network equipment within controlled environments maintaining temperatures between 18°C and 27°C and humidity at 40-60% RH, designed to deliver continuous compute, storage, and connectivity services for enterprise and consumer applications. Cloud Computing deployments currently dominate new capacity additions as hyperscalers seek sovereign hosting alternatives to Singapore. Edge Computing represents the fastest-growing technology segment, driven by latency-sensitive applications in manufacturing and autonomous systems across Johor and Selangor. Colocation maintains stable margins among mid-market enterprises preferring operational flexibility over capital-intensive owned infrastructure.
Malaysia's Energy Commission enforces building energy efficiency standards that shape cooling system specifications and power usage effectiveness targets for new facilities. The Malaysian Communications and Multimedia Commission governs licensing frameworks that determine market access for foreign operators and cross-border data flows. BIS-equivalent standards for electrical safety and fire suppression systems further constrain equipment sourcing and facility design. Stakeholders must weigh regulatory compliance timelines against the accelerating construction cycles demanded by hyperscale tenants.
Market Dynamics
Hyperscale cloud commitments are compressing construction timelines across Peninsular Malaysia while BIS-equivalent electrical safety standards and Energy Commission efficiency mandates force simultaneous compliance redesigns. This tension between tenant speed demands and regulatory certification cycles defines current market structure.
Growth Catalysts
- National Cloud Policy:Malaysia's sovereign hosting framework accelerates public sector data migration requirements, creating dedicated demand streams for accredited local facilities.
- Johor-Singapore bandwidth arbitrage:Submarine cable landings at Iskandar Puteri attract latency-sensitive financial services and gaming platforms seeking cost advantages over Singapore operations.
- Liquid cooling adoption:Direct-to-chip thermal management technologies enable higher rack densities, allowing operators to maximize land-constrained sites in Cyberjaya and Greater Kuala Lumpur.
Market Restraints
- Copper and aluminum input volatility:Busbar and cabling material costs fluctuate with commodity markets, squeezing mechanical and electrical contractor margins on fixed-price hyperscale builds.
- Southeast Asian switchgear concentration:Medium-voltage electrical distribution equipment relies on a limited supplier base concentrated in Thailand and Vietnam, creating delivery timeline vulnerability.
- Diesel generator emissions thresholds:Energy Commission efficiency standards constrain backup power system specifications, extending equipment sourcing cycles for Tier III certification.
Strategic Opportunities
- East Malaysia latency gap:Sarawak and Sabah remain underserved by hyperscale infrastructure, presenting first-mover advantages for edge computing deployments serving offshore oil and gas operations.
- Green building code alignment:Malaysia's energy efficiency certification pathways unlock preferential financing and expedited permitting for renewable-powered facilities.
- AI training cluster convergence:GPU-intensive workloads intersect with liquid cooling infrastructure, enabling premium pricing for specialized high-density halls in Iskandar Puteri.
Industry Challenges
- Critical facilities engineering talent scarcity:Malaysia produces insufficient MEP designers and commissioning specialists, forcing reliance on expatriate contractors and inflating project overhead.
- Legacy enterprise system integration:Financial institutions migrating from on-premise infrastructure require hybrid connectivity architectures that complicate colocation contract structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Data Center Market |
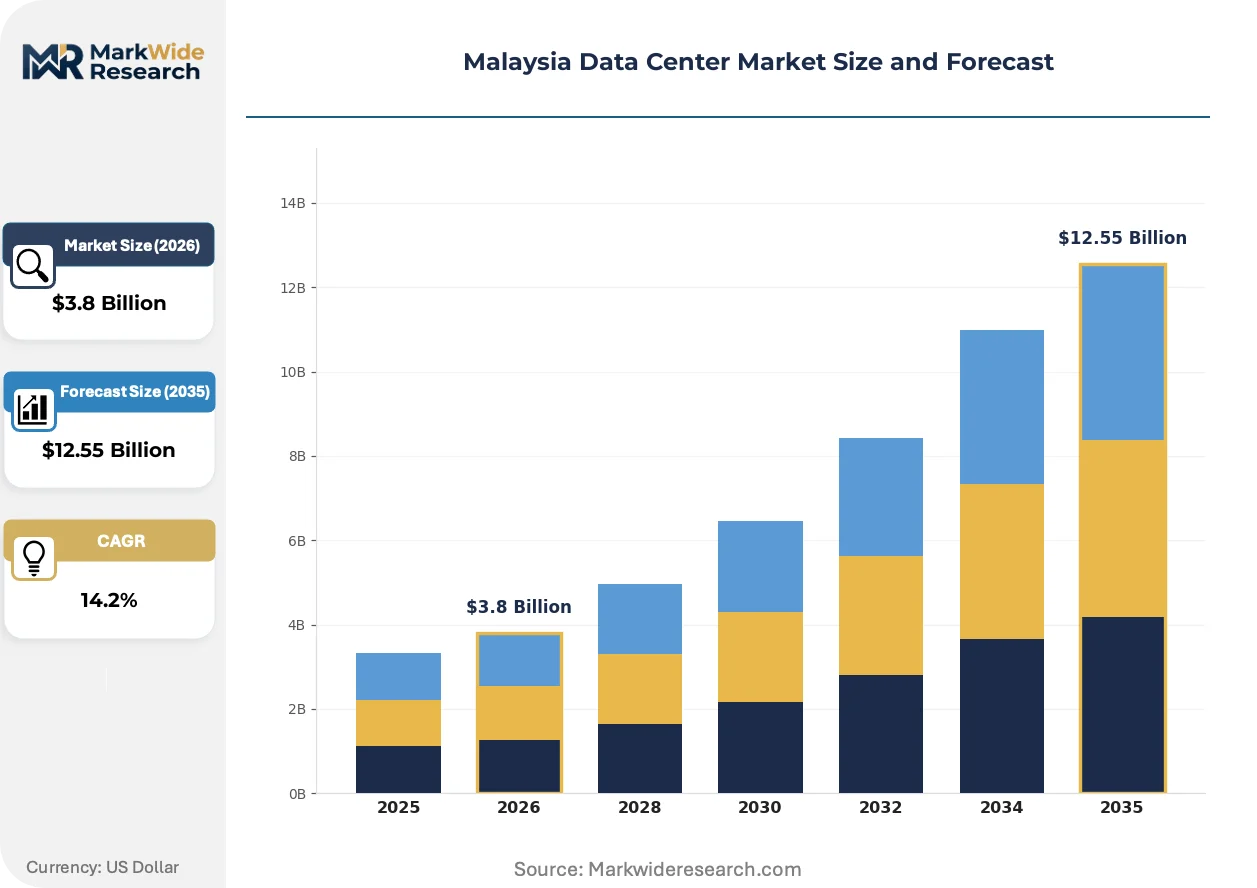
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Edge Computing, Hybrid Cloud, Colocation Service Type: Managed Services, Infrastructure as a Service, Disaster Recovery, Network Services End User: Telecommunication, BFSI, IT & Services, Healthcare Deployment: On-premises, Off-premises, Multi-cloud, Private Cloud |
| Companies Covered | Amazon Web Services Inc., Microsoft Corp., Google LLC, Equinix Inc., Keppel Data Centres Pte. Ltd., Bridge Data Centres, NTT DATA, Vantage Data Centers, Telekom Malaysia Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Data Center Market Trends and Innovations
Operational technology convergence is dissolving boundaries between facility infrastructure and IT workload management, enabling predictive maintenance and autonomous environmental control. This integration demands new skill profiles and vendor partnerships across the Malaysian supply chain.
Immersion cooling systems are unifying thermal management and fire suppression functions through dielectric fluid technologies. Hyperscale operators in Cyberjaya are piloting these systems for AI training clusters. The technology is unifying previously separate mechanical and safety engineering disciplines, compressing vendor qualification timelines.
Malaysia's Energy Commission enforces building energy efficiency standards that now mandate real-time power usage effectiveness monitoring and annual efficiency reporting. New facilities must demonstrate cooling system optimization before receiving operational licenses. Financial services tenants in Greater Kuala Lumpur are responding by specifying liquid cooling requirements in build-to-suit contracts.
Enterprise procurement of data center capacity is fragmenting across multiple delivery models simultaneously. Mid-market manufacturers in Selangor now combine wholesale colocation for primary workloads with on-premise edge nodes for quality control systems. This hybrid pattern is most visible among automotive suppliers building smart factory infrastructure in the Iskandar Malaysia corridor.
Malaysia Data Center Market Segmentation
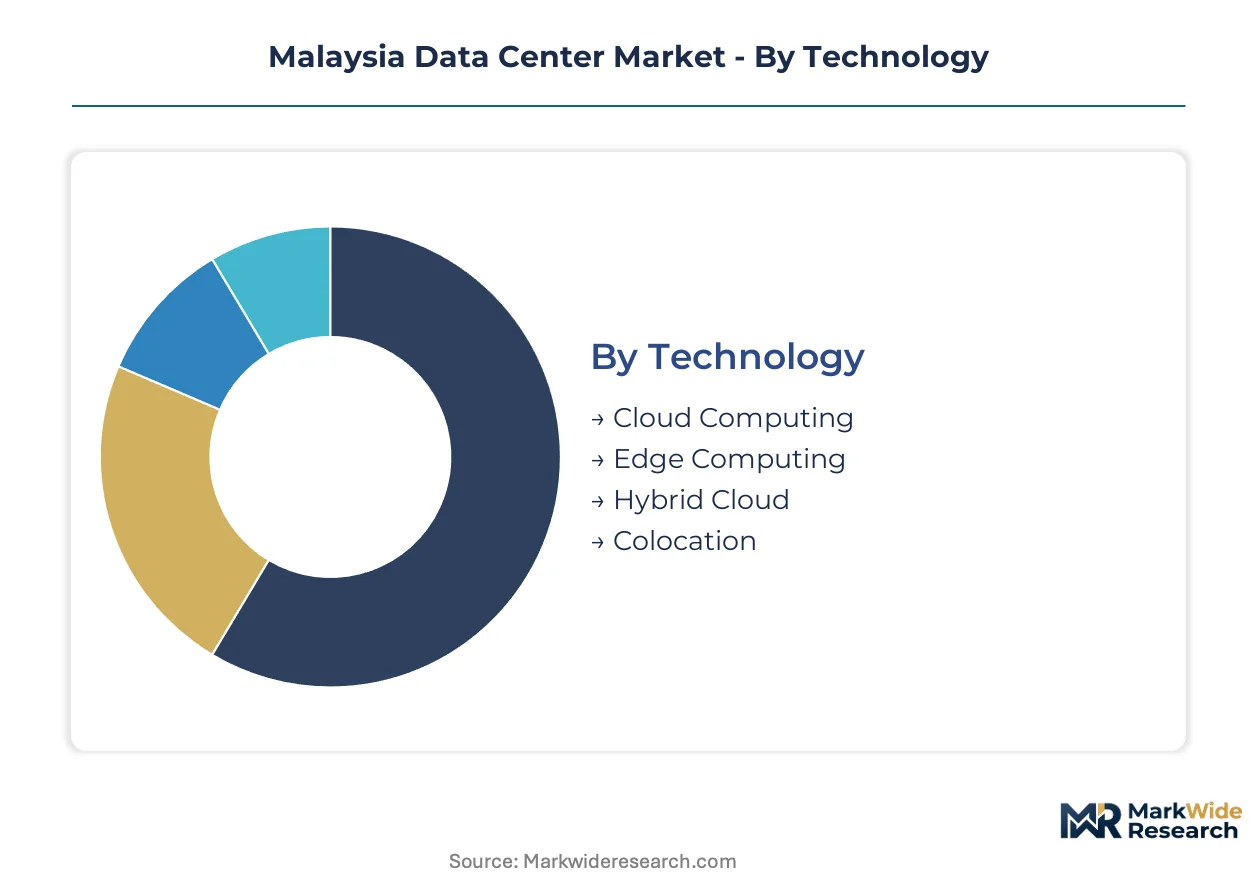
Malaysia data center procurement fragments across four intersecting dimensions. Technology choices determine cooling infrastructure requirements. Service type selections drive contract complexity. End user profiles shape compliance burdens. Deployment models dictate capital allocation timelines.
Technology:
Certification requirements vary sharply by thermal density and redundancy tier. Cloud Computing and Edge Computing deployments face divergent Energy Commission efficiency mandates and BIS-equivalent electrical safety standards.
- Cloud Computing:Hyperscale server farms require Tier III redundancy certification and liquid cooling compatibility for GPU-intensive workloads. Demand concentrates in Iskandar Puteri where submarine cable landings enable sovereign hosting alternatives to Singapore, constrained by diesel generator emissions thresholds for backup power certification.
- Edge Computing:Distributed micro-facilities deploy modular containment with direct-to-chip thermal management for latency-sensitive manufacturing automation. Johor and Selangor automotive suppliers drive procurement for quality control systems, limited by critical facilities engineering talent scarcity in MEP design.
- Hybrid Cloud:Split workload architectures combining on-premise control planes with burst capacity to colocation facilities. Financial institutions in Greater Kuala Lumpur favor this model for regulatory data residency compliance.
- Colocation:Wholesale and retail rack leasing with operational flexibility for mid-market enterprises. Stable margins persist among manufacturers preferring opex models over capital-intensive owned infrastructure.
Leading the category by volume: Cloud Computing. Growing fastest: Edge Computing.
Service Type:
Margin structures diverge based on operational responsibility allocation. Managed Services and Infrastructure as a Service command premium pricing where talent scarcity inflates delivery costs.
- Managed Services:Third-party operational control of server, storage, and network infrastructure with guaranteed SLAs. BFSI tenants in Greater Kuala Lumpur specify 24/7 remote hands requirements, constrained by Malaysia's limited pool of commissioning specialists.
- Infrastructure as a Service:Virtualized compute and storage resources delivered on consumption-based pricing. Gaming platforms at Iskandar Puteri cable landings drive demand for low-latency block storage.
- Disaster Recovery:Geographically separated replication sites with automated failover orchestration. Healthcare providers prioritize this service for patient data protection under national cloud accreditation.
- Network Services:Cross-connect provisioning, DDoS mitigation, and software-defined WAN integration. Telecommunication carriers bundle these with submarine cable capacity.
Highest margin capture: Managed Services. Fastest contract velocity: Infrastructure as a Service.
End User:
Regulatory intensity shapes facility selection criteria across verticals. BFSI and Healthcare face the strictest data residency and audit requirements under Malaysia's National Cloud Policy.
- BFSI:Banking, financial services, and insurance institutions require hybrid connectivity architectures for legacy core banking migration. Cyberjaya facilities attract these tenants with green building code alignment for expedited permitting.
- Telecommunication:5G core network hosting and content delivery infrastructure. Submarine cable operators at Iskandar Puteri anchor demand for carrier-neutral interconnection.
- IT & Services:Systems integrators and SaaS providers reselling capacity to downstream enterprises. Selangor-based vendors serve smart factory implementations in the Iskandar Malaysia corridor.
- Healthcare:Electronic medical record hosting and telemedicine infrastructure. National Cloud Policy accreditation requirements limit vendor selection to certified local facilities.
Most certification-intensive: BFSI. Expanding most quickly: IT & Services.
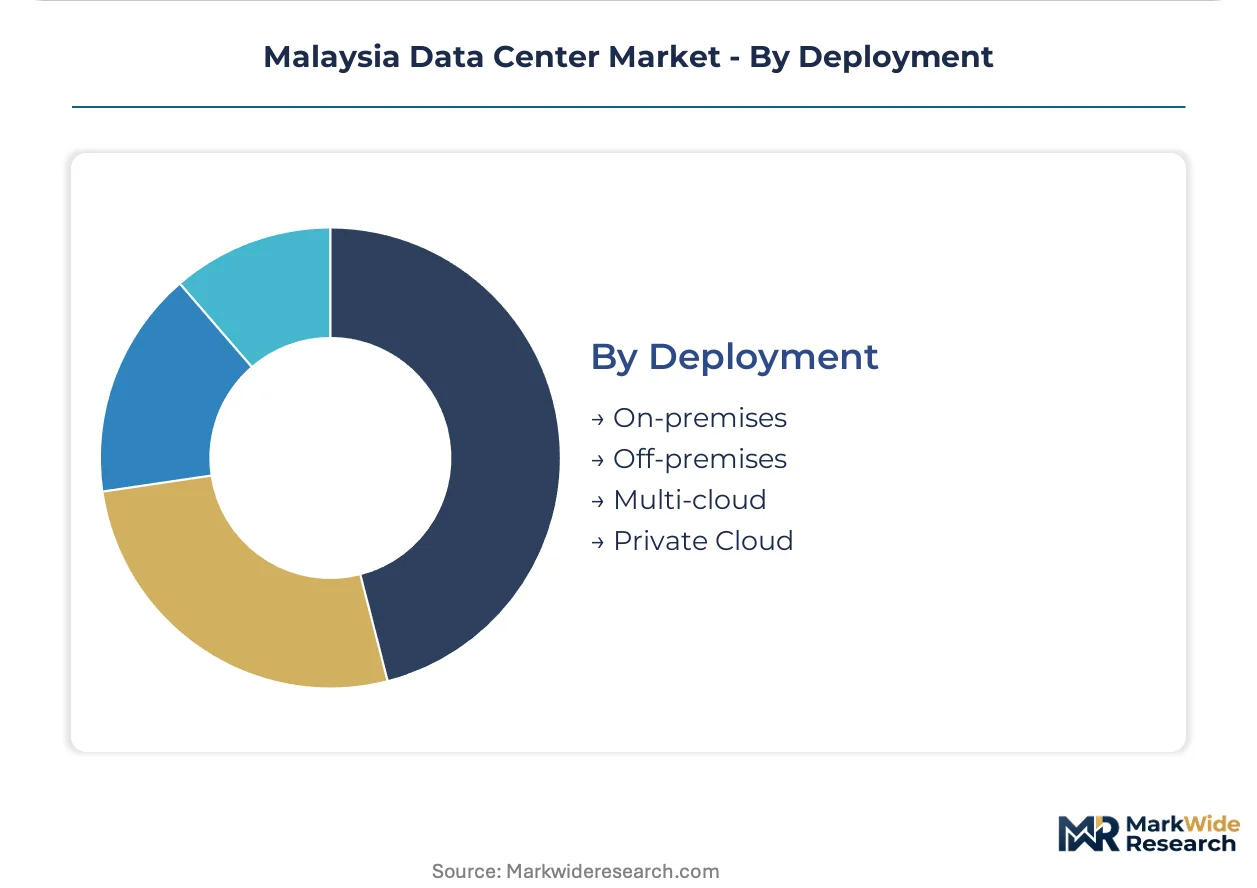
Deployment:
Capital efficiency trade-offs dominate enterprise decision frameworks. Private Cloud and Multi-cloud configurations optimize for workload-specific performance and compliance requirements.
- Private Cloud:Single-tenant dedicated infrastructure with custom security policies. Government agencies mandate this deployment under sovereign hosting frameworks, constrained by Energy Commission real-time PUE monitoring requirements.
- Multi-cloud:Orchestrated workloads across AWS, Microsoft, and Google environments with unified management planes. Enterprises mitigate vendor lock-in while optimizing for specific service capabilities.
- On-premises:Enterprise-owned facilities retaining full operational control. Legacy manufacturers in Selangor maintain these for proprietary quality control systems.
- Off-premises:Third-party colocation or cloud with no owned physical infrastructure. Mid-market enterprises favor this model for operational flexibility.
Dominant enterprise selection: Multi-cloud. Steepest expansion trajectory: Private Cloud.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate supply from Sabah's Mamut Mine historically anchored Malaysian electrical infrastructure buildouts. This feedstock locality shaped early data center power distribution engineering standards across Peninsular Malaysia.
Greater Kuala Lumpur
Hyperscale cloud commitments and submarine cable landings drive capacity concentration in Cyberjaya and Iskandar Puteri. The Malaysian Energy Commission enforces real-time PUE monitoring for all new facilities. Cyberjaya facilities attract financial services tenants seeking green building code alignment for expedited permitting.
Johor
Bandwidth arbitrage against Singapore operations attracts gaming platforms and latency-sensitive financial services to Iskandar Puteri cable landings. The Iskandar Malaysia corridor hosts automotive suppliers building smart factory edge infrastructure. Liquid cooling pilots for AI training clusters are compressing vendor qualification timelines in this zone.
Selangor
Mid-market manufacturers combine wholesale colocation with on-premise edge nodes for quality control systems. The National Cloud Policy accreditation requirements limit vendor selection to certified local facilities. Smart factory implementations in automotive supply chains dominate procurement patterns here.
Sarawak
Offshore oil and gas operations create underserved demand for edge computing infrastructure. Renewable energy availability from hydroelectric resources supports green building code alignment for new facilities. First-mover advantages exist for specialized deployments serving extractive industries.
Malaysia Data Center Market Competitive Landscape
Global majors compete with regional champions across sovereign hosting certification and submarine cable interconnection. The market exhibits tiered concentration with hyperscale cloud operators anchoring build-to-suit developments while regional specialists capture colocation margins. Three archetypes dominate: vertically integrated hyperscalers securing direct land positions, carrier-neutral interconnection specialists, and infrastructure-focused real estate investment trusts. Capacity expansion and renewable energy partnerships represent the dominant competitive moves as tenants mandate sustainability alignment.
Among US-based hyperscalers, Amazon Web Services Inc., Microsoft Corp., and Google LLC occupy the premium-tier anchor positions. These entities exemplify the vertically integrated archetype through direct land acquisition strategies that sustain long-term expansion optionality. Singapore-based Keppel Data Centres Pte. Ltd. and regional specialists including Telekom Malaysia Berhad represent the infrastructure-focused tier, capturing stable margins through operational flexibility offerings for mid-market enterprises.
| Leading Market Players |
|---|
| Amazon Web Services Inc. |
| Microsoft Corp. |
| Google LLC |
| Equinix Inc. |
| Keppel Data Centres Pte. Ltd. |
| Bridge Data Centres |
| NTT DATA |
| Vantage Data Centers |
| Telekom Malaysia Berhad |
| Others |
Pricing and Supply Chain Analysis
Copper busbar and medium-voltage cabling costs cascade from Southeast Asian smelters through Tier III certification premiums to hyperscale build-to-suit contracts in Cyberjaya and Iskandar Puteri. Energy Commission efficiency mandates and BIS-equivalent electrical safety standards compress contractor margins while liquid cooling compatibility requirements widen pricing spreads between certified and uncertified facilities.
Pricing Analysis
Warranty and remote hands service bundling separates premium managed services contracts from bare-metal colocation leases in Greater Kuala Lumpur. Pricing stratifies across Tier III-certified hyperscale halls, Tier II enterprise facilities, and uncertified edge micro-sites based on redundancy level and cooling density. Cost compression in wholesale colocation intensifies as hyperscale tenants negotiate long-term offtake agreements with renewable energy riders. Mid-market manufacturers in Selangor exhibit highest price sensitivity, while BFSI institutions in Cyberjaya prioritize compliance certification over per-rack economics.
Supply Chain Analysis
Refurbishment flows for diesel generators and switchgear components loop from decommissioned facilities in Singapore back to Johor reconditioning specialists. Medium-voltage electrical distribution equipment draws from concentrated manufacturing bases in Thailand and Vietnam, while precision cooling systems source from Japanese and German component suppliers. Single-source vulnerability in Southeast Asian switchgear creates delivery timeline exposure for Tier III certification projects. Distribution runs through carrier-neutral interconnection hubs at Iskandar Puteri cable landings, with final-mile integration performed by Malaysian mechanical and electrical contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid cooling infrastructure deployment lags GPU-intensive workload demand, creating a supply-constrained environment that props pricing for high-density halls in Iskandar Puteri and Cyberjaya.
For Market Incumbents: Acquire land positions with renewable energy interconnection agreements in Cyberjaya and Iskandar Puteri to anchor long-term expansion optionality. Defend against hyperscale self-build threats by embedding managed services capabilities into wholesale contracts. Commissioning specialist scarcity inflates project overhead; backward integration into critical facilities engineering training programs reduces expatriate contractor dependence. For New Entrants and Emerging Players: Direct-to-enterprise digital sales channels bypass established distributor relationships in the mid-market colocation segment. Target Sarawak edge computing deployments serving offshore oil and gas operations, where hyperscale infrastructure remains absent. Position modular containment systems with direct-to-chip thermal management for automotive suppliers building smart factory infrastructure in the Iskandar Malaysia corridor. For Investors and Strategic Acquirers: Malaysia Energy Commission real-time PUE monitoring mandate enforcement is the leading indicator that green building code alignment will determine facility financing access. Five-to-ten year viability favors infrastructure-focused real estate investment trusts with operational flexibility offerings for mid-market enterprises. Monitor hyperscale renewable energy partnership announcements as signals of sovereign hosting demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Partnership | Energy Commission efficiency mandates unlock preferential financing for solar and hydro-powered facilities in Cyberjaya. |
| Liquid Cooling Infrastructure Deployment | Direct-to-chip thermal management enables premium pricing for AI training clusters in land-constrained Iskandar Puteri sites. |
| Submarine Cable Interconnection Expansion | Bandwidth arbitrage against Singapore operations attracts latency-sensitive gaming platforms to Iskandar Puteri landings. |
| Critical Facilities Engineering Talent Development | MEP designer scarcity forces reliance on expatriate contractors; captive training programs reduce project overhead inflation. |
| East Malaysia Edge Computing Buildout | Sarawak and Sabah remain underserved by hyperscale infrastructure, presenting first-mover advantages for extractive industry serving. |
Research Methodology
Document review covered Malaysian Energy Commission licensing frameworks, BIS-equivalent electrical safety standards, and submarine cable landing infrastructure databases, complemented by interviews with data center facility operators, hyperscale cloud procurement officers, mechanical and electrical contractors, and Malaysian Communications and Multimedia Commission regulatory affairs leads. Secondary validation drew from customs and trade data for copper and aluminum imports, SEC filings of US-based hyperscalers, and project development databases tracking construction timelines across Peninsular Malaysia. Bottom-up capacity installation counts and top-down cloud capex allocation estimates were triangulated to establish market sizing.
Market value and capacity outputs across the projection horizon reflect segmented modeling across technology type, service tier, end-user vertical, and deployment configuration dimensions. CAGRs were derived from historical hyperscale commitment patterns, National Cloud Policy implementation trajectories, and green building code adoption curves. Industry-specific forecast inputs included diesel generator emissions threshold compliance timelines and liquid cooling technology penetration rates for GPU-intensive workloads.
The model holds under stable Energy Commission enforcement of real-time PUE monitoring and continued submarine cable landing investments at Iskandar Puteri; deviation in sovereign hosting policy implementation or copper commodity volatility would shift capacity addition timelines. Practitioners should monitor hyperscale land acquisition announcements and renewable energy interconnection permit approvals for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
Europe Data Center Server Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Connected Distribution Center Market