
 Global Data Center Rack PDU Market | 2026-2036
Global Data Center Rack PDU Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Rack PDU Market Foresight
Buyer concentration among hyperscale cloud and colocation providers is repositioning procurement leverage toward enterprise-grade intelligent units with embedded monitoring. Schneider Electric SE leverages its integrated energy management portfolio to anchor large-scale deployment contracts across Europe and North America. Vertiv Group Corp. sustains competitive density through thermal-electrical co-design capabilities that reduce total facility energy overhead. Eaton Corporation plc differentiates via its North American manufacturing scale and channel control in utility-interactive power architectures.
A data center rack PDU is an electrical distribution device mounted within a server rack, delivering conditioned power to IT equipment through multiple outlet configurations typically ranging from 120V to 480V with current ratings from 16A to 60A; its primary purpose is to enable safe, measurable, and remotely controllable power delivery to servers, storage, and network gear. Intelligent PDUs with outlet-level metering and switching command the strongest margin pools as operators pursue granular power usage effectiveness tracking. Edge facilities represent the fastest-growing deployment category, though on-premises installations still occupy the largest revenue base due to legacy refresh cycles in financial and government sectors.
Regulatory frameworks including the EU Energy Efficiency Directive, EPA ENERGY STAR for data centers, and India's BIS electrical safety standards are mandating measurable power distribution at the rack level, which directly elevates demand for metered and switched PDU architectures over basic units. The U.S. Department of Energy and China's MIIT are separately tightening operational efficiency benchmarks for new facility construction. Stakeholders must monitor how divergent efficiency certification timelines across jurisdictions reshape product portfolio prioritization and regional manufacturing localization decisions.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and mandating outlet-level intelligence as standard, forcing manufacturers to embed metering and switching capabilities into base rack PDU configurations rather than treating them as premium upgrades.
Growth Catalysts
- EU Energy Efficiency Directive:The mandate for granular power monitoring at the rack level is eliminating basic PDU sales across European data center construction corridors.
- Hyperscale facility expansion:Cloud operators in the United States, Germany, and India are standardizing intelligent PDUs across greenfield deployments exceeding 50MW each.
- 480V three-phase distribution:Higher-voltage architectures are reducing copper conductor requirements and accelerating demand for compatible rack-level distribution units.
Market Restraints
- Copper price volatility:Conductor materials constitute 35-45% of PDU manufacturing cost, and LME copper fluctuations compress margin predictability for producers.
- Semiconductor supply concentration:Metering and control chip fabrication concentrates in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Legacy 120V infrastructure:North American enterprise facilities face stranded asset risk when upgrading to 208V/415V intelligent PDUs, slowing refresh cycles.
Strategic Opportunities
- India's data center corridor:Mumbai, Chennai, and Hyderabad are adding 400MW+ capacity annually with limited local PDU manufacturing, creating import substitution openings.
- Edge computing micro-facilities:10-100kW deployments in manufacturing plants and retail distribution centers require compact switched PDUs with cellular management backhaul.
- CE marking plus BIS dual certification:Vendors achieving concurrent European and Indian electrical safety approvals capture cross-regional procurement consolidation.
Industry Challenges
- Firmware security certification:IEC 62443-4-2 industrial cybersecurity standards for power distribution devices require 12-18 month validation cycles that delay product launches.
- Integration with DCIM platforms:API compatibility with Schneider Electric, Vertiv, and proprietary hyperscale management systems demands dedicated engineering resources per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Rack PDU Market |
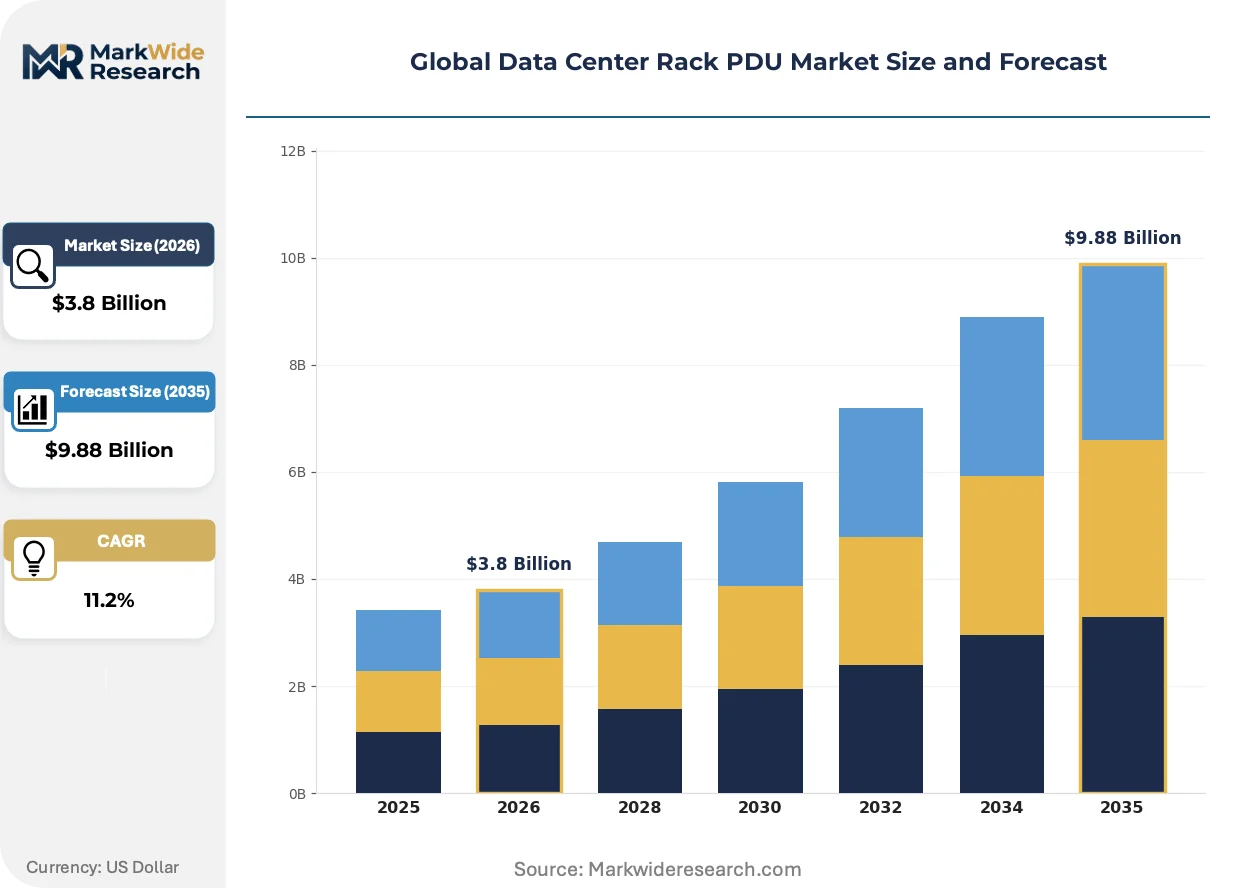
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic PDU, Metered PDU, Switched PDU, Intelligent PDU Deployment: On-Premises, Colocation, Cloud Data Centers, Edge Facilities Application: Server Management, Network Equipment, Storage Systems, Power Monitoring End User: Telecom Operators, Financial Institutions, Government Agencies, Research Organizations |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Eaton Corporation plc, Legrand SA, ABB Ltd, Hewlett Packard Enterprise Company, Cyber Power Systems (USA), Inc., Tripp Lite, Leviton Manufacturing Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Rack PDU Market Shifts & Advancements
Intelligence migration from facility-level to rack-level is compressing the acceptable latency for power telemetry and control commands, redefining what constitutes a baseline rack PDU versus a premium unit.
Three-phase 415V intelligent PDUs with outlet-level monitoring and remote switching are overtaking single-phase 208V basic units in new hyperscale construction. Amazon Web Services, Microsoft Azure, and Google Cloud mandate switched outlet control for every rack in facilities exceeding 30MW. This voltage architecture is overtaking legacy distribution by eliminating step-down transformers and reducing facility-level energy loss from 8-12% to under 4%.
The EU Energy Efficiency Directive's 2024 enforcement deadline for granular power measurement is mandating metered-by-outlet architectures across all new data center builds in Germany, France, and the Netherlands. Operators must report PUE at the rack level to national energy agencies. Colocation providers in Frankfurt and Amsterdam are responding by specifying intelligent PDUs with ±1% billing-grade accuracy as standard equipment.
Consolidated procurement through hyperscale engineering teams is displacing distributor-led specification for rack-level power infrastructure. Direct manufacturer engagement with cloud operators' facility engineering groups now governs 60-70% of intelligent PDU volume in the United States. This concentration is most visible in Northern Virginia's Data Center Alley, where AWS, Microsoft, and Google operate dedicated supply chain teams negotiating multi-year rack PDU frameworks.
Global Data Center Rack PDU Market Segmentation
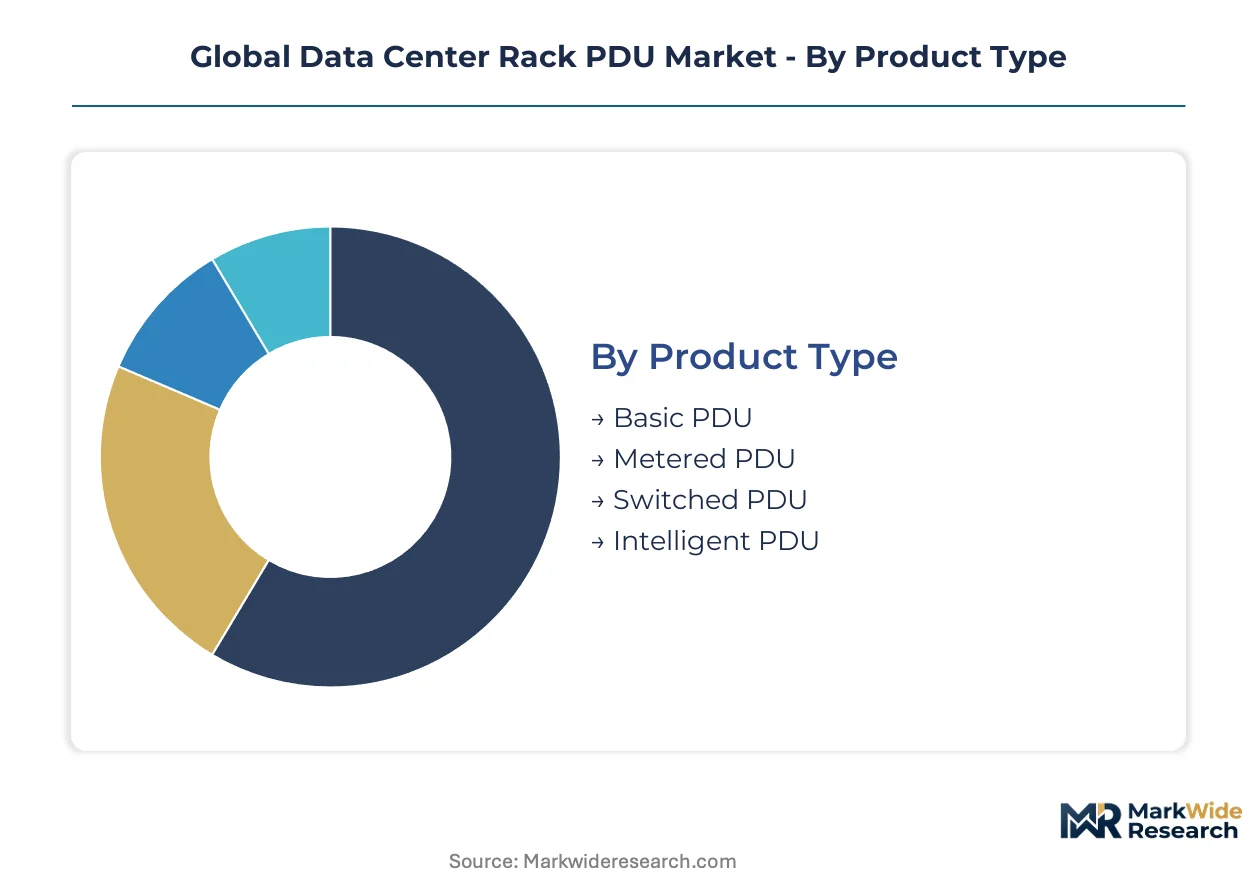
Intelligent power distribution architectures fragment across voltage requirements, facility scale, and regulatory compliance tiers. Buyers select rack PDU configurations based on whether they need passive distribution, aggregate metering, or granular outlet-level control with DCIM integration.
Product Type:
Hyperscale procurement teams distinguish vendors by embedded intelligence depth rather than outlet count alone.
- Intelligent PDU:Outlet-level metering and switching enable ±1% billing-grade accuracy for PUE reporting to EU energy agencies. Amazon Web Services, Microsoft Azure, and Google Cloud mandate these units for every rack in facilities exceeding 30MW.
- Switched PDU:Remote outlet control allows sequential server startup and emergency power shedding without technician dispatch. Frankfurt and Amsterdam colocation providers specify these for tenant billing transparency.
- Metered PDU:Aggregate inlet-level measurement satisfies India's BIS electrical safety standards for new data center construction in Mumbai and Hyderabad.
- Basic PDU:Passive distribution without instrumentation persists in legacy North American enterprise facilities facing stranded asset risk during 120V-to-208V upgrades.
Volume sits with Metered PDU for mid-tier deployments; growth tilts toward Intelligent PDU.
Deployment:
Facility scale determines voltage architecture and telemetry latency requirements.
- Cloud Data Centers:415V three-phase intelligent PDUs eliminate step-down transformers and cut facility-level energy loss from 8-12% to under 4%. Northern Virginia's Data Center Alley concentrates procurement through direct manufacturer engagement.
- Edge Facilities:Compact 10-100kW deployments in manufacturing plants and retail distribution centers require switched PDUs with cellular management backhaul. These units are expanding most quickly across Germany's industrial corridors.
- Colocation:Multi-tenant facilities in Frankfurt and Amsterdam standardize metered-by-outlet architectures to comply with EU Energy Efficiency Directive rack-level PUE reporting mandates.
- On-Premises:Financial institutions and government agencies in the United States drive legacy refresh cycles for 208V single-phase units despite slower upgrade timelines.
Revenue concentrates in Cloud Data Centers; steepest expansion trajectory belongs to Edge Facilities.
Application:
Power density and uptime requirements vary sharply between compute, network, and storage loads.
- Server Management:High-density GPU clusters demand 60A intelligent PDUs with thermal-electrical co-design capabilities to reduce total facility energy overhead.
- Power Monitoring:Granular telemetry for PUE optimization at the rack level is mandatory under EPA ENERGY STAR for data centers and China's MIIT efficiency benchmarks.
- Network Equipment:Switch and router loads favor 16A-20A metered PDUs with redundant feed configurations for telecommunications operators.
- Storage Systems:Disk array power profiles require switched outlet sequencing to manage inrush current during facility startup sequences.
Deployment share favors Server Management; regulatory pressure is elevating Power Monitoring fastest.
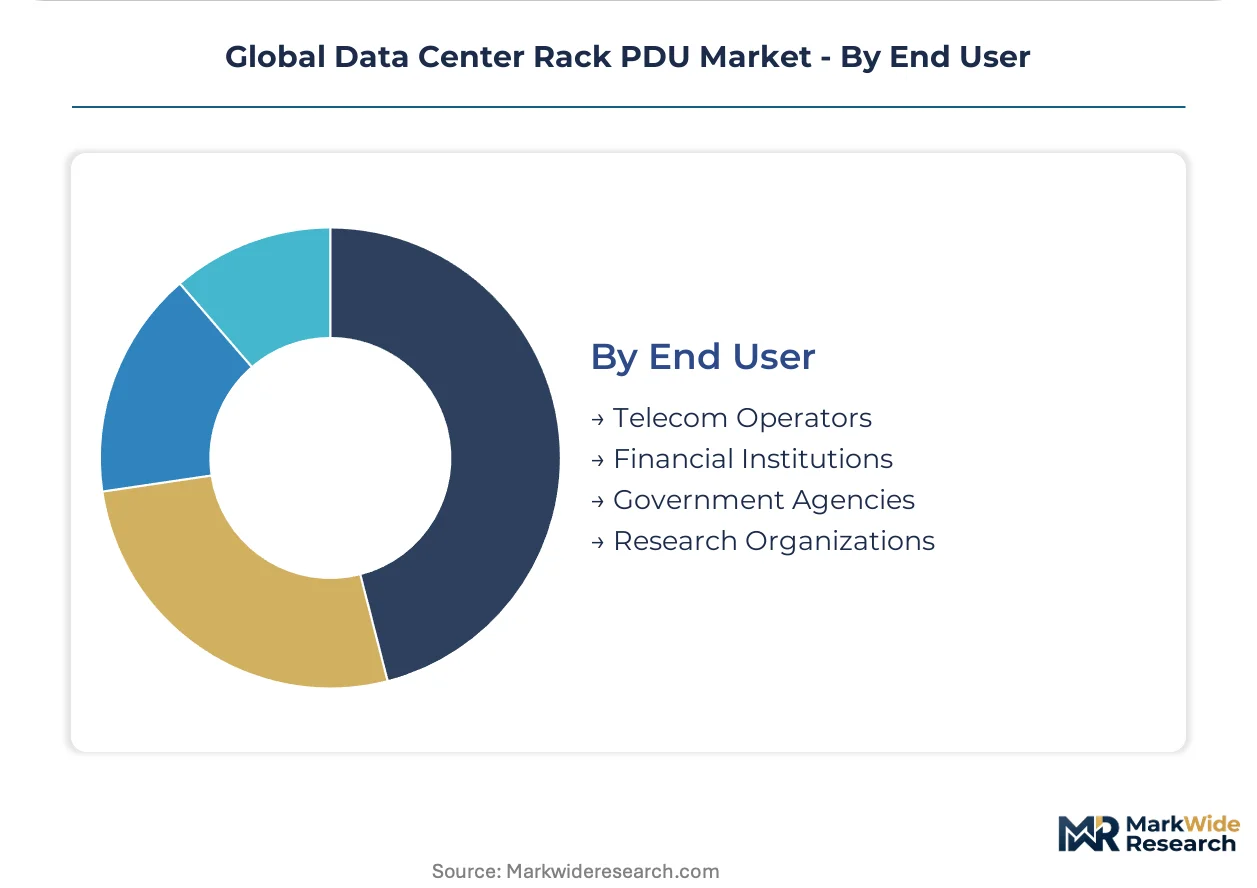
End User:
Procurement sophistication ranges from centralized engineering teams to distributed IT operations.
- Financial Institutions:Trading floor uptime requirements and SEC audit trails drive demand for redundant intelligent PDUs with outlet-level logging in New York and London.
- Telecom Operators:5G edge infrastructure deployments in India and Germany require compact switched PDUs with IP65 environmental ratings for outdoor cabinet installations.
- Government Agencies:FedRAMP and comparable certification requirements in the United States and Europe impose 12-18 month firmware security validation cycles per IEC 62443-4-2 standards.
- Research Organizations:Supercomputing facilities favor 480V three-phase metered PDUs to minimize copper conductor requirements in high-density compute environments.
Spending scale rests with Financial Institutions; contract velocity is highest among Telecom Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper conductor supply chains from Chile and Peru anchor manufacturing cost structures across major data center construction corridors. Facility operators in Germany, the United States, and India are driving procurement volume for intelligent rack PDUs. Regulatory mandates for granular power monitoring are reshaping specification standards in each market.
United States
Northern Virginia's Data Center Alley concentrates hyperscale procurement through direct manufacturer engagement with AWS, Microsoft, and Google engineering teams. The EPA ENERGY STAR for data centers program mandates measurable power distribution at the rack level for certification eligibility. Ashburn and Manassas sub-markets are adding 50MW+ facilities annually with 415V three-phase intelligent PDUs as standard equipment.
Germany
Frankfurt and Berlin data center clusters are expanding capacity to serve EU cloud sovereignty requirements and AI training workloads. The EU Energy Efficiency Directive's 2024 enforcement deadline for rack-level PUE reporting is eliminating basic PDU sales across new construction. Colocation providers in Frankfurt specify metered-by-outlet architectures with ±1% billing-grade accuracy for tenant transparency.
India
Mumbai, Chennai, and Hyderabad are adding 400MW+ data center capacity annually with limited local PDU manufacturing capability. The Bureau of Indian Standards (BIS) electrical safety standards mandate aggregate inlet-level measurement for new facility construction. Mumbai's Navi Mumbai and Thane sub-markets are attracting hyperscale investments requiring import substitution for intelligent power distribution units.
Netherlands
Amsterdam's data center market is constrained by power grid capacity limits while demand from financial services and cloud operators persists. The EU Energy Efficiency Directive applies Dutch enforcement mechanisms for granular rack-level monitoring in facilities exceeding 500kW. Amsterdam Science Park and Schiphol Rijk industrial zones are retrofitting existing facilities with intelligent PDUs to comply with reporting mandates.
China
Beijing-Tianjin-Hebei and Yangtze River Delta clusters are expanding under MIIT operational efficiency benchmarks for new facility construction. The Ministry of Industry and Information Technology (MIIT) is tightening PUE requirements below 1.3 for hyperscale licenses. Langfang and Nantong sub-markets are deploying 480V three-phase metered PDUs to minimize copper conductor requirements in high-density compute environments.
Global Data Center Rack PDU Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-specific form factors and cellular management integration. The vendor base concentrates among electrical infrastructure conglomerates with integrated energy management portfolios and specialized power distribution fabricators with thermal-electrical co-design capabilities. Three archetypes dominate: integrated energy management platforms, thermal-electrical co-design specialists, and regional manufacturing-scale operators. Competitive moves center on multi-year framework agreements with hyperscale engineering teams and firmware security certification acceleration under IEC 62443-4-2 standards.
Within the integrated platform tier, Schneider Electric SE and Eaton Corporation plc represent archetypes of European and North American manufacturing-scale positioning. Vertiv Group Corp. exemplifies the thermal-electrical co-design specialist model. These three anchors demonstrate how vendor concentration follows hyperscale procurement consolidation in Northern Virginia, Frankfurt, and Mumbai construction corridors.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation plc |
| Legrand SA |
| ABB Ltd |
| Hewlett Packard Enterprise Company |
| Cyber Power Systems (USA), Inc. |
| Tripp Lite |
| Leviton Manufacturing Co., Inc. |
| Others |
Supply & Pricing Matrix
Three-phase 415V intelligent PDU migration simultaneously compresses copper conductor requirements and concentrates procurement leverage among hyperscale engineering teams in Northern Virginia and Frankfurt. This voltage architecture shift reduces facility-level energy loss while eliminating step-down transformers, reshaping both manufacturing cost structures and supplier consolidation dynamics.
Pricing Analysis
Warranty and firmware-update bundling separates premium intelligent PDU tiers from unbundled basic units, with Schneider Electric and Vertiv embedding decade-long service commitments into hyperscale framework agreements. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth—outlet-level metering with IEC 62443-4-2 cybersecurity validation commands substantial premiums over aggregate inlet measurement. Cost compression in mid-tier metered PDUs is intensifying because Indian and German colocation providers are standardizing billing-grade accuracy as baseline specifications. Small-to-mid enterprise facilities in North America exhibit highest price sensitivity due to stranded 120V infrastructure risk, while hyperscale cloud operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for metering and control chip fabrication, exposing lead times to geopolitical friction in the Taiwan Strait. Copper conductor supply draws from Chile and Peru, with conductor materials constituting the dominant cost component in PDU manufacturing. Semiconductor supply concentration and LME copper volatility represent the primary structural risks compressing margin predictability for producers. Distribution runs through direct manufacturer engagement with hyperscale engineering teams, displacing traditional distributor-led specification in 60-70% of intelligent PDU volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center rack PDU market is consolidating around firmware security certification and hyperscale framework contracting, with IEC 62443-4-2 validation timelines forcing smaller fabricators toward exit or acquisition.
For Market Incumbents: Hedge against margin erosion by accelerating in-house production of metering chipsets and securing captive supply agreements with Chilean copper suppliers. Vertiv's thermal-electrical co-design capabilities demonstrate how backward integration into power management firmware reduces dependency on Taiwanese semiconductor foundries. Prioritize multi-year framework agreements with AWS, Microsoft, and Google engineering teams in Northern Virginia to lock out emerging competitors. For New Entrants and Emerging Players: Cellular-enabled switched PDUs for 10-100kW edge micro-facilities offer the most penetrable white-space target, with Germany's industrial corridors and India's 5G infrastructure deployments showing limited incumbent saturation. Target Mumbai, Chennai, and Hyderabad data center construction corridors where local manufacturing gaps create import substitution openings. Pursue dual CE marking plus BIS certification to capture cross-regional procurement consolidation among colocation providers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated energy management platforms seeking thermal-electrical co-design capabilities. Long-term viability favors vendors with demonstrated hyperscale framework contracting velocity and accelerated IEC 62443-4-2 certification cycles. Watch for inflection signals in India's 400MW annual capacity additions and the EU Energy Efficiency Directive enforcement trajectory across German and Dutch facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Security Certification Acceleration | IEC 62443-4-2 validation cycles determine hyperscale qualification timelines and framework contract eligibility. |
| Dual Certification Achievement | Concurrent CE marking and BIS approvals enable cross-regional procurement consolidation in Europe and India. |
| Copper Supply Backward Integration | Captive sourcing from Chilean and Peruvian mining operations insulates margins from LME price volatility. |
| Cellular Management Integration | Edge facility deployments in German industrial corridors require compact switched PDUs with remote backhaul capability. |
| Hyperscale Framework Contracting | Direct engagement with AWS, Microsoft, and Google engineering teams in Northern Virginia displaces distributor channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with data center facility engineering directors, colocation procurement managers, electrical infrastructure OEM supply chain leads, and hyperscale cloud operator sustainability officers. SEC 10-K disclosures, EU Energy Efficiency Directive implementation reports, Indian BIS certification databases, and copper trade flow statistics from Chile and Peru provided validation. Bottom-up unit shipment estimates triangulated against top-down facility construction pipeline analysis across the United States, Germany, India, Netherlands, and China.
Granularity-level modeling tracked voltage architecture, intelligence tier, deployment scale, and regional regulatory cluster across the projection horizon. The analytical framework derived CAGRs from facility construction pipeline data, hyperscale capex disclosures, and regulatory mandate enforcement timelines. Segmentation dimensions included product type, deployment category, application, and end-user industry. Copper price volatility assumptions and semiconductor lead time scenarios fed sensitivity analysis throughout the forecast period.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruption in Taiwan Strait semiconductor supply, abrupt copper supply shocks from Chilean mining operations, and accelerated voltage standard shifts beyond 415V three-phase adoption. Forecasts reflect assumptions about regulatory enforcement consistency and hyperscale facility construction schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
United Kingdom Data Center Power Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
APAC Green Data Center Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Europe Data Center Physical Security Market