
 Beijing Data Center Market | 2026-2036
Beijing Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Beijing Data Center Market Insights
Colocation service revenue is reconfiguring margin pools away from pure infrastructure leasing toward managed hybrid orchestration. GDS leverages its wholesale campus footprint to anchor premium connectivity contracts in the Beijing corridor. Chindata Group sustains power cost advantages through direct utility partnerships in Hebei border zones. Huawei Cloud Computing Technologies dominates sovereign cloud deployments for state-affiliated end users.
Beijing data centers constitute purpose-built facilities housing servers, storage systems, and network equipment with power densities routinely exceeding 15 kW per rack, designed to deliver continuous compute, storage, and interconnection services for enterprise and consumer workloads. Hyperscale facilities absorb the majority of new power capacity allocations as cloud providers expand AI training clusters, while edge deployments concentrate near Beijing's manufacturing corridors to serve latency-sensitive industrial IoT applications. Enterprise data centers face structural pressure as finance and government end users migrate workloads to colocation and hybrid environments.
MIIT enforces PUE thresholds below 1.3 for new facilities in the Beijing-Tianjin-Hebei region, compelling operators to adopt liquid cooling and renewable power sourcing. GB standards for data center energy efficiency, administered by SAMR, dictate equipment procurement and facility design parameters that filter through to construction and service contracts. Stakeholders must monitor power quota allocation rhythms and carbon intensity benchmarks to time capacity expansion decisions.
Market Dynamics
MIIT's carbon neutrality mandates for data centers are compressing facility design cycles and forcing wholesale energy procurement restructuring across Beijing's operator base.
Growth Catalysts
- Financial cloud migration:State banks and securities firms are consolidating on-premise infrastructure into colocation campuses, generating sustained demand for high-density rack configurations.
- MIIT PUE enforcement:Sub-1.3 efficiency thresholds for new Beijing-Tianjin-Hebei facilities are accelerating liquid cooling retrofits and renewable power purchase agreements.
- Tongzhou sub-center concentration:Coordinated land and power allocations in this municipal district are channeling hyperscale investment into purpose-built campus developments.
Market Restraints
- Power quota scarcity:Municipal energy bureaus ration annual electricity allocations, capping aggregate data center expansion regardless of capital availability.
- Lithium-ion supply concentration:Battery backup system procurement depends on a narrow supplier base concentrated in eastern provinces, exposing operators to input cost volatility.
- Cooling equipment import dependency:Precision air conditioning and liquid cooling manifolds rely on foreign component sourcing subject to customs processing delays.
Strategic Opportunities
- Daxing district edge deployment:Manufacturing corridors south of Beijing's core present underserved latency requirements for industrial IoT and autonomous logistics workloads.
- Hebei cross-border zones:Direct utility partnerships in bordering provinces offer power cost arbitrage for operators willing to manage inter-provincial fiber connectivity.
- GB standard certification services:SAMR-administered energy efficiency protocols create adjacent revenue streams for testing and compliance consulting.
Industry Challenges
- Liquid cooling technician scarcity:Immersion and direct-to-chip cooling architectures require specialized installation and maintenance skills absent from conventional HVAC labor pools.
- Dual carbon timeline compression:Operators must synchronize facility commissioning with renewable energy procurement contracts that carry 10-15 year lock-in terms.
- Legacy workload migration friction:State-affiliated enterprises maintain decades-old application stacks resistant to containerization and cloud-native restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beijing Data Center Market |
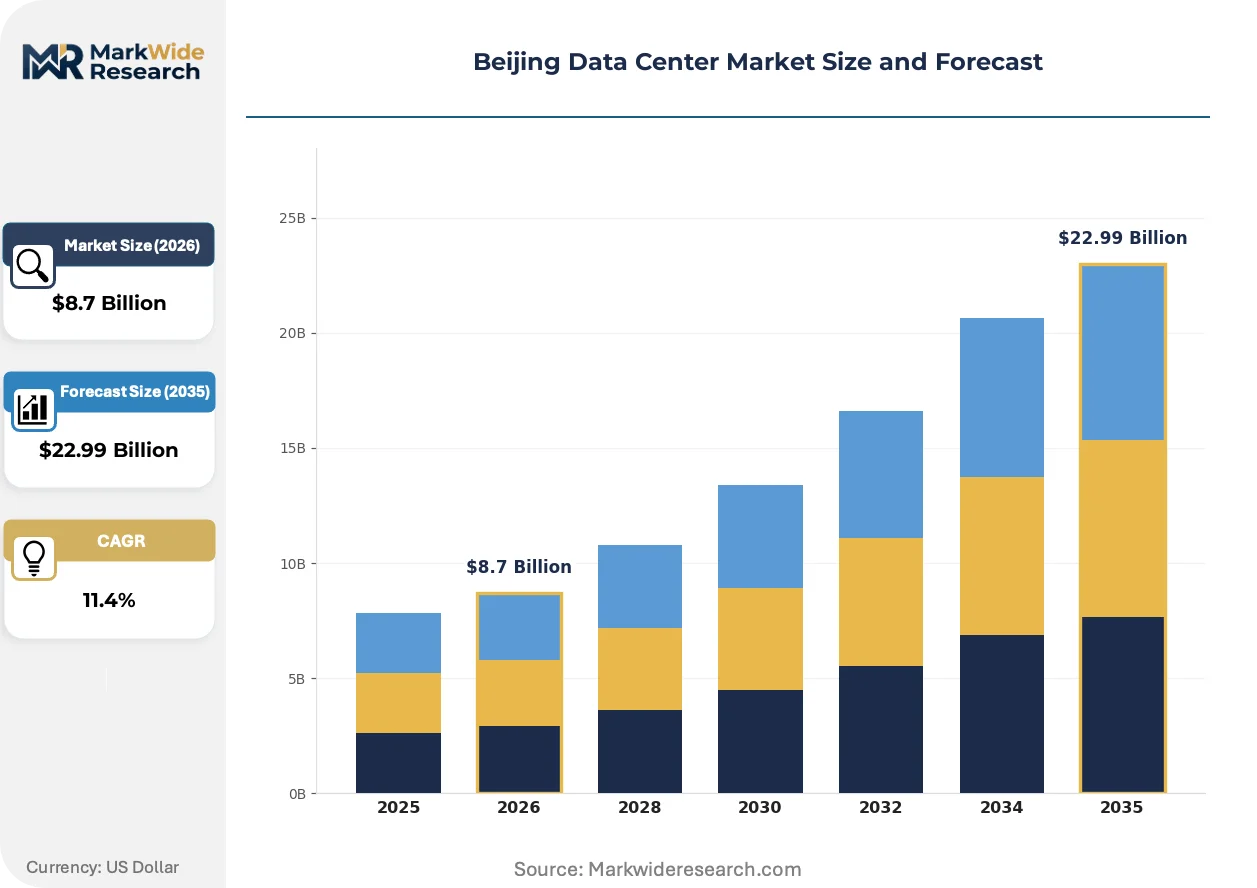
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premise, Colocation, Hybrid, Cloud Service Type: IaaS, PaaS, SaaS, DaaS Data Center Type: Enterprise, Edge, Retail, Hyperscale End User: IT Services, Telecommunications, Government, Finance |
| Companies Covered | Global Data Solutions Co., Ltd. (GDS), Chindata Group Holdings Ltd, Alibaba Cloud, Huawei Cloud Computing Technologies Co., Ltd, 21Vianet Group (VNET), Tencent Holdings, Amazon Web Services (AWS), Microsoft Azure, China Telecom Corporation Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beijing Data Center Market Trends and Innovations
Liquid cooling architectures and sovereign cloud requirements are bifurcating facility design standards, separating premium AI-training campuses from general-purpose enterprise colocation.
Direct liquid cooling (DLC) systems using dielectric fluids are penetrating hyperscale deployments above 30 kW per rack densities. Cloud operators building AI training clusters in Beijing's northern districts are specifying DLC as baseline infrastructure. Air-cooled legacy designs are rendering obsolete for new high-performance computing commitments.
MIIT's dual carbon implementation rules are tightening carbon intensity benchmarks for data center power sourcing. Operators must document renewable energy certificates matching annual consumption or face quota restrictions. Wholesale renewable procurement is accelerating among facilities serving state-affiliated financial end users.
Buyers are unbundling managed services from pure infrastructure leases, contracting orchestration and security operations separately from rack and power agreements. Systems integrators and cloud service providers are capturing this value migration. Finance sector procurement teams in Beijing's central business district are driving this specification shift.
Beijing Data Center Market Segmentation
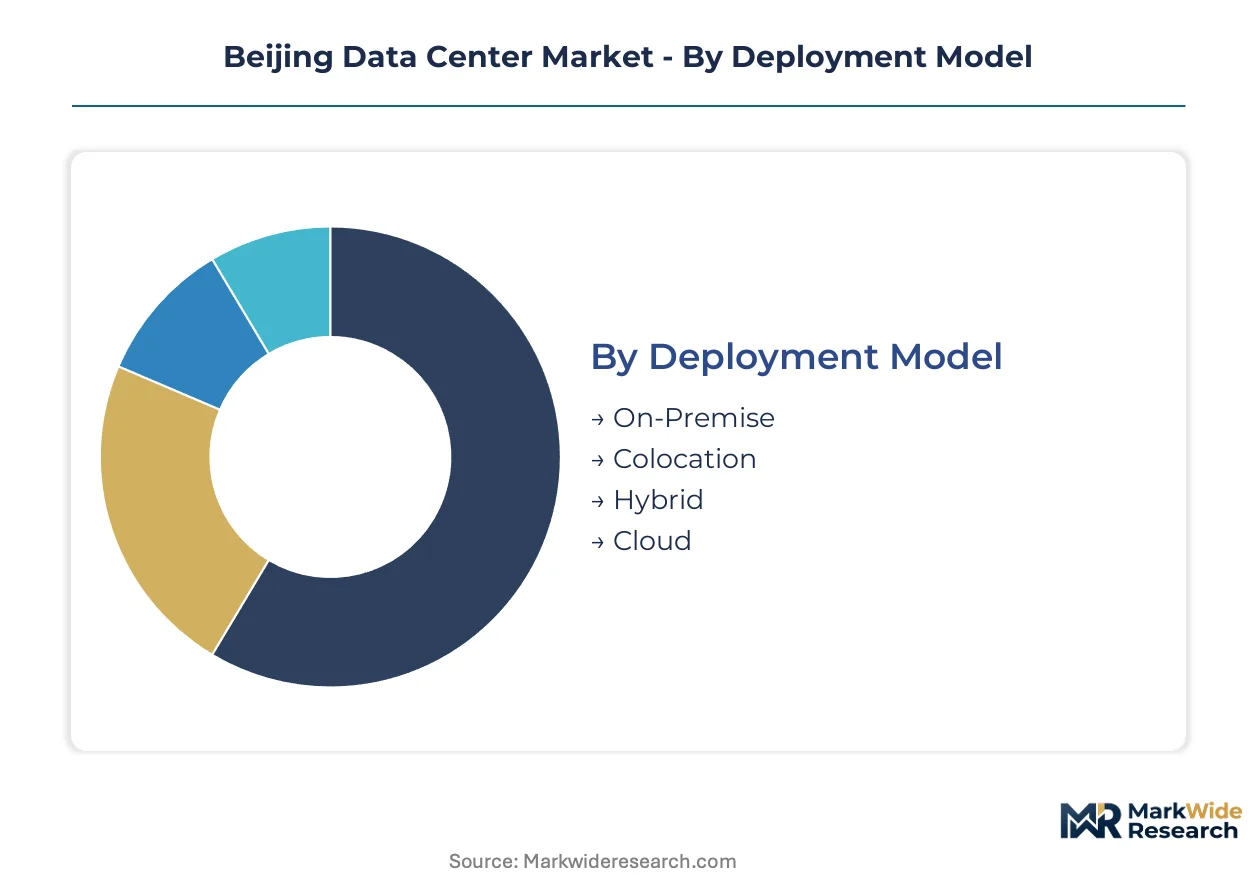
Deployment model choices in Beijing reflect power quota scarcity and MIIT efficiency mandates. Service type selection tracks cloud provider competition for state-affiliated workloads. Data center type and end user segmentation reveal how regulatory pressure and sovereign computing requirements reshape facility economics.
Deployment Model:
Organizations distribute compute across ownership structures based on workload sensitivity, capital constraints, and carbon compliance timelines.
- On-Premise:State-owned enterprises and defense contractors maintain captive facilities for classified data processing. MIIT PUE enforcement renders legacy designs uncompetitive for new construction.
- Colocation:Finance and telecommunications operators lease wholesale space in Tongzhou and Daxing campuses to bypass land acquisition bottlenecks. GDS and Chindata Group anchor this segment with direct utility partnerships.
- Hybrid:Securities firms and regional banks orchestrate tiered workloads across owned and leased infrastructure. Procurement teams unbundle managed services from pure rack agreements.
- Cloud:Huawei Cloud Computing Technologies dominates sovereign cloud deployments for government end users. AI training clusters absorb disproportionate power allocations in northern Beijing districts.
The dominant share belongs to Colocation, while Cloud is closing the gap fastest.
Service Type:
Revenue pools shift toward orchestration layers as infrastructure commoditizes under efficiency mandates.
- IaaS:Bare-metal provisioning with liquid-cooled racks serves AI training workloads exceeding 30 kW per rack. Hyperscale operators in Beijing's northern corridor specify direct liquid cooling as baseline infrastructure.
- PaaS:Container orchestration and database services attract fintech developers migrating from legacy mainframe environments. SAMR-administered GB standards complicate cross-border platform integration.
- SaaS:Vertical applications for government and finance sectors require data residency certifications. Domestic software vendors capture procurement preference over foreign competitors.
- DaaS:Virtual desktop infrastructure concentrates in Daxing district edge nodes serving manufacturing logistics. Latency requirements below 10 milliseconds drive proximity to industrial corridors.
IaaS commands the largest revenue base, though PaaS is expanding most quickly as containerization penetrates state-affiliated enterprises.
Data Center Type:
Facility classification separates premium AI-training campuses from general-purpose enterprise capacity under diverging design standards.
- Enterprise:Captive facilities operated by state banks and telecommunications carriers face structural pressure. Workload migration to colocation and hybrid environments accelerates as power quotas tighten.
- Edge:Micro facilities near Beijing's manufacturing corridors serve autonomous logistics and industrial IoT. Daxing district land allocations favor sub-10 MW deployments with direct fiber to Hebei border zones.
- Retail:Multi-tenant configurations below 500 kW cater to small and medium enterprises with standardized rack contracts. Margin compression intensifies as wholesale campuses absorb larger tenants.
- Hyperscale:Single-tenant campuses exceeding 50 MW absorb majority of new power allocations. Cloud providers commission AI training clusters with dielectric fluid cooling systems and renewable power purchase agreements.
Hyperscale facilities hold the dominant position, while Edge deployments are gaining share fastest through Daxing district manufacturing proximity.
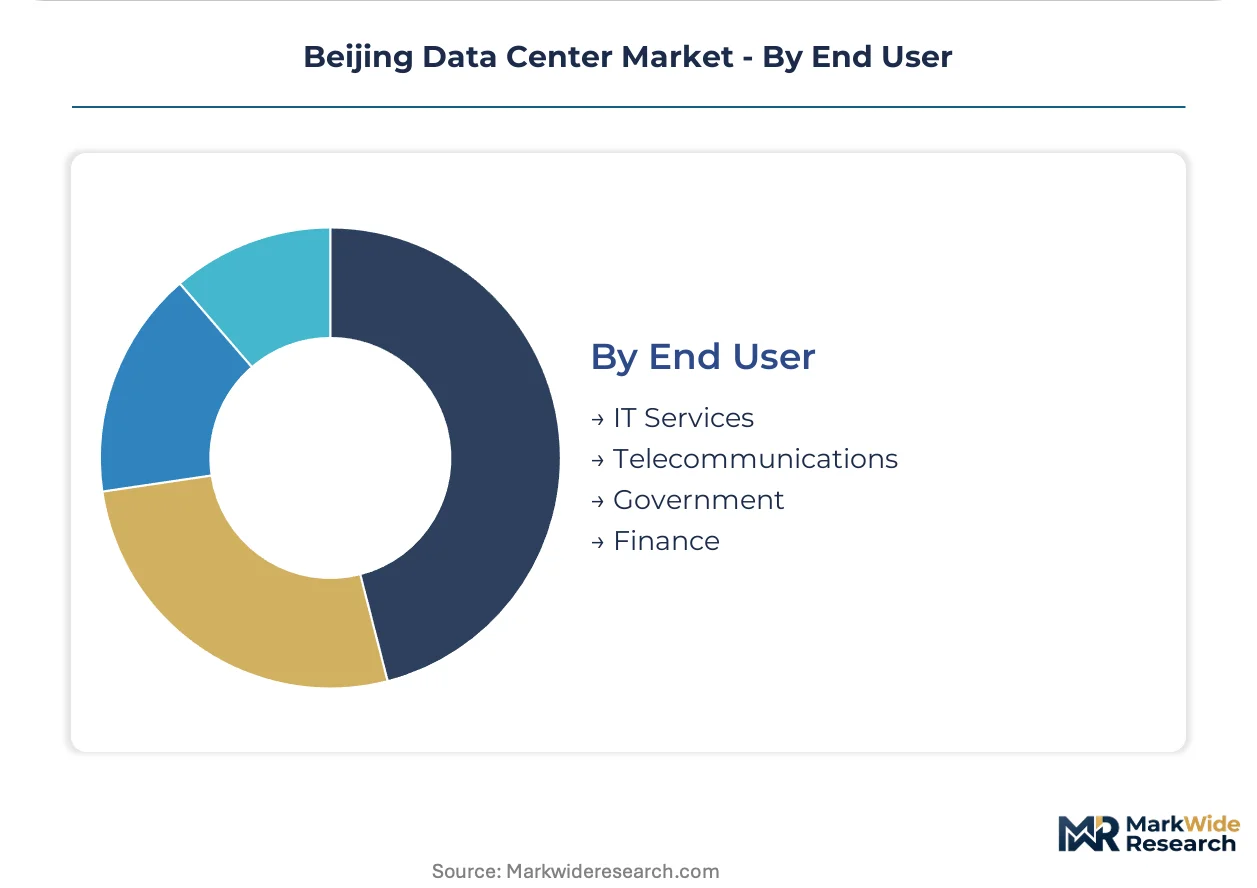
End User:
Sector-specific compliance requirements and workload characteristics drive divergent procurement specifications across Beijing's operator base.
- IT Services:Domestic cloud providers and systems integrators lease wholesale space for resale to enterprise clients. Managed hybrid orchestration contracts capture margin migration from pure infrastructure.
- Telecommunications:State-owned carriers consolidate central office facilities into hyperscale campuses. 5G core network functions drive edge compute requirements in suburban districts.
- Government:Municipal and provincial agencies mandate sovereign cloud deployment with data residency guarantees. Huawei Cloud Computing Technologies maintains procurement preference for classified workloads.
- Finance:State banks and securities firms consolidate on-premise infrastructure into colocation campuses. Dual carbon timeline compression forces synchronization of facility commissioning with 10-15 year renewable energy contracts.
Finance commands the dominant share, while Government is closing the gap fastest through sovereign cloud procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing data center consumption patterns diverge sharply from other Chinese metros, with sovereign cloud mandates and dual carbon timelines driving procurement specifications that prioritize compliance over cost arbitrage.
Shanghai
Financial services concentration in Lujiazui and Zhangjiang Hi-Tech Park generates demand for low-latency colocation serving securities trading and cross-border payment systems. MIIT enforces identical PUE thresholds as Beijing-Tianjin-Hebei, though municipal authorities offer denser power quota allocations per square kilometer. Lingang New Area hosts hyperscale campuses where cloud providers commission liquid-cooled infrastructure for AI model training.
Shenzhen
Hardware manufacturing ecosystems in Nanshan and Longgang districts create edge compute requirements for supply chain optimization and quality control automation. Guangdong Province energy bureaus operate less restrictive power rationing than northern counterparts, permitting faster facility commissioning cycles. Qianhai Shenzhen-Hong Kong Cooperation Zone attracts cross-border data exchange infrastructure subject to specialized cybersecurity review.
Guizhou
Cool climate and abundant hydropower resources position Guiyang and Anshun as destinations for batch processing and cold storage workloads. Big Data Comprehensive Pilot Zone policies exempt certain facilities from standard MIIT efficiency benchmarks to encourage provincial economic development. State-affiliated operators dominate capacity construction, with limited private colocation penetration.
Inner Mongolia
Wind and solar resource abundance in Hohhot and Ordos supports hyperscale campuses serving Beijing latency requirements through dedicated fiber routes. Regional energy pricing advantages attract cloud providers seeking renewable power purchase agreement arbitrage. SAMR-administered GB standards apply with modified enforcement timelines reflecting infrastructure development priorities.
Tianjin
Binhai New Area industrial corridors generate manufacturing IoT demand complementing Beijing financial and government workloads. Inter-provincial power grid integration permits load balancing across municipal boundaries under coordinated MIIT supervision. Jing-Jin-Ji integration policies facilitate fiber connectivity and disaster recovery site placement for capital-region operators.
Beijing Data Center Market Competitive Landscape
Capability concentration sits with hyperscale cloud platforms possessing sovereign cloud certifications; scale advantage sits with wholesale colocation operators controlling direct utility relationships. The vendor base stratifies across three tiers: state-affiliated telecommunications carriers with legacy central office assets, independent data center developers with municipal land allocations, and hyperscale cloud providers building self-operated training clusters. Dominant competitive moves include power purchase agreement structuring for renewable sourcing and liquid cooling technology partnerships with foreign equipment suppliers.
Within the wholesale colocation tier, GDS and Chindata Group occupy positions defined by direct utility partnerships and cross-border fiber connectivity management. Huawei Cloud Computing Technologies exemplifies the sovereign cloud archetype, anchoring state-affiliated procurement pipelines through data residency guarantees. These three entities collectively represent the competitive structure shaping Beijing facility economics.
| Leading Market Players |
|---|
| Global Data Solutions Co., Ltd. (GDS) |
| Chindata Group Holdings Ltd |
| Alibaba Cloud |
| Huawei Cloud Computing Technologies Co., Ltd |
| 21Vianet Group (VNET) |
| Tencent Holdings |
| Amazon Web Services (AWS) |
| Microsoft Azure |
| China Telecom Corporation Ltd |
| Others |
Pricing and Supply Chain Analysis
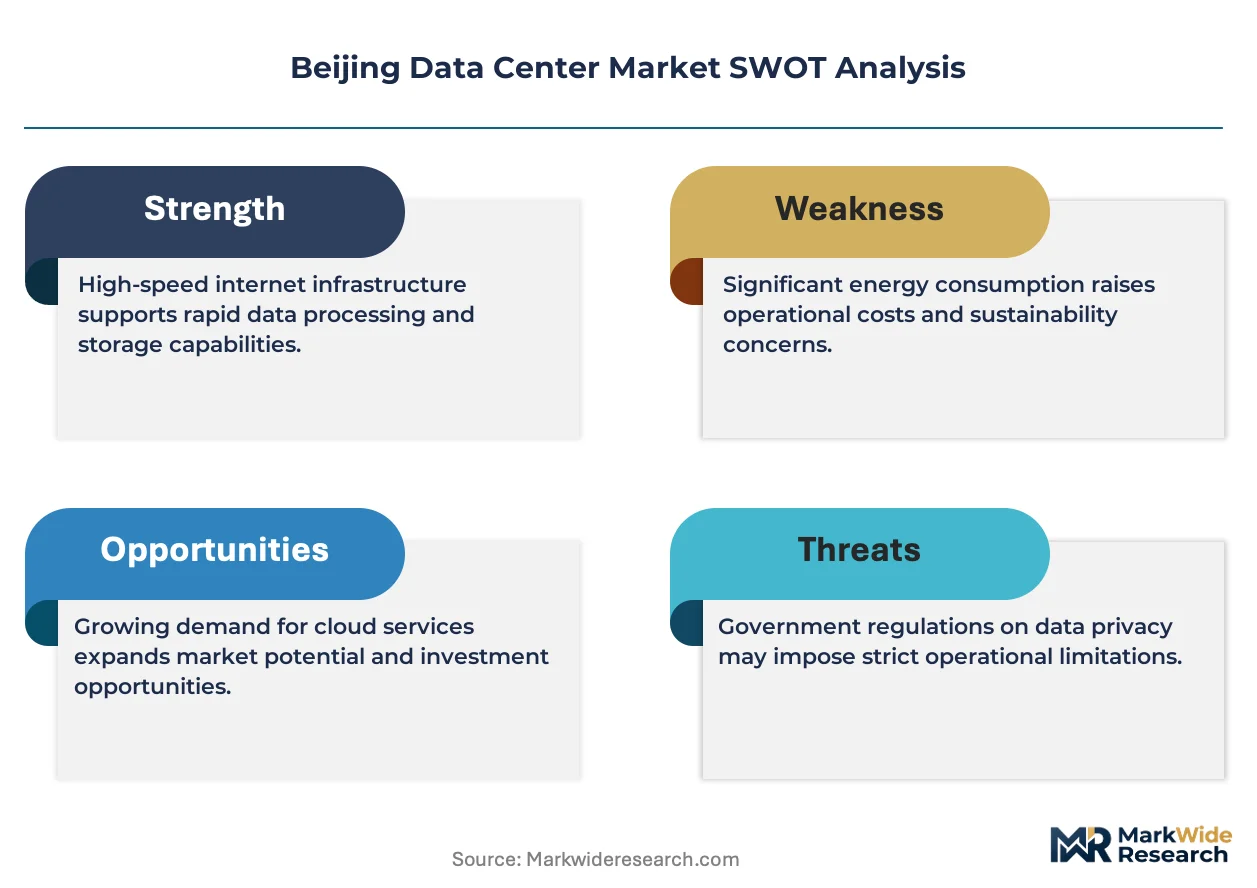
MIIT power quota rationing as a regulatory chokepoint determines both the premium commanded by facilities holding grandfathered allocations and the geographic shape of supply chain relocation toward Hebei border zones. This scarcity dynamic compresses margin pools for air-cooled legacy designs while amplifying pricing power for liquid-cooled campuses with renewable energy contracts.
Pricing Analysis
Long-term offtake contracts with municipal energy bureaus anchor pricing stability for hyperscale operators, while spot-market power purchases expose retail colocation providers to volatility. Price differentiation rests on PUE certification tier and direct utility partnership status, with sub-1.3 efficiency facilities commanding substantial premiums. Cost compression in standard-tier rack configurations is intensifying because wholesale campuses absorb larger tenants with volume discounts. State-affiliated financial end users exhibit lowest price sensitivity due to dual carbon compliance mandates, while small and medium enterprises in retail colocation show highest elasticity.
Supply Chain Analysis
US export controls on advanced semiconductors and precision cooling components limit flows of GPU accelerators and dielectric fluid manifolds to Beijing facility builders. Manufacturing concentration centers on China, South Korea, and Japan for lithium-ion battery systems, precision air conditioning units, and optical transmission equipment. Raw material dependencies include rare earth elements for magnetic components, high-purity copper for busbars, and fluorinated fluids for immersion cooling. Single-source vulnerability pervades specialized HVAC component sourcing. Distribution runs through state-affiliated telecommunications carriers and independent systems integrators serving enterprise procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beijing's data center market sits at a platform-economics inflection where sovereign cloud interoperability requirements and MIIT carbon accounting systems are redefining competitive moats around certification depth rather than scale alone.
For Market Incumbents: Entrench power purchase agreement portfolios through direct utility partnerships in Hebei cross-border zones, locking in renewable sourcing ahead of dual carbon timeline compression. Acquire liquid cooling technician capabilities through specialized training partnerships or selective hiring from foreign equipment suppliers, addressing the critical skills gap threatening commissioning schedules. State-affiliated cloud providers building sovereign AI training clusters represent the primary substitution threat. For New Entrants and Emerging Players: Daxing district edge deployment zones offer the most penetrable white-space for sub-10 MW facilities serving manufacturing IoT latency requirements below 10 milliseconds. Hebei border zones present second-tier opportunity for power cost arbitrage through inter-provincial fiber connectivity management. A go-to-market angle anchored to GB standard certification consulting services captures adjacent revenue from compliance-driven procurement teams. For Investors and Strategic Acquirers: MIIT's 2025 PUE enforcement milestone reshapes the acquisition landscape toward facilities with liquid cooling infrastructure and documented renewable energy certificate matching. Long-term viability favors wholesale colocation operators with direct utility relationships and sovereign cloud certification pathways. The signal to watch is municipal power quota reallocation rhythms, which determine aggregate expansion capacity regardless of capital availability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Utility Partnership | Secures renewable power purchase agreements ahead of MIIT dual carbon enforcement timelines. |
| Liquid Cooling Infrastructure Deployment | Enables PUE sub-1.3 compliance required for new Beijing-Tianjin-Hebei facility commissioning. |
| Hebei Cross-Border Zone Expansion | Captures power cost arbitrage through inter-provincial fiber connectivity to Beijing demand centers. |
| Sovereign Cloud Certification Investment | Unlocks procurement pipelines from state-affiliated government and financial end users. |
| GB Standard Compliance Consulting | Generates adjacent revenue from SAMR-administered energy efficiency protocol implementation. |
Research Methodology
A spread of perspectives from data center operations executives, municipal energy bureau planning officers, cloud platform procurement leads, and cooling systems integration specialists converged on the working assumptions underlying facility economics and power quota allocation rhythms. Secondary validation drew from MIIT policy circulars, SAMR GB standard documentation, municipal land use planning filings, and hyperscaler capital expenditure disclosures. Bottom-up rack-level demand modeling and top-down regional capacity aggregation were triangulated against utility-scale power allocation data.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation dimensions spanning deployment model, service type, data center type, and end user vertical. CAGRs were derived from facility commissioning schedules, power quota release patterns, and workload migration trajectories from enterprise to colocation environments. AI training cluster density requirements and sovereign cloud procurement acceleration served as industry-specific forecast inputs.
Practitioners should monitor MIIT PUE threshold adjustments, municipal power quota reallocation announcements, and US semiconductor export control expansion for early signals of forecast revision. Material shifts in renewable energy procurement contract availability or liquid cooling equipment import processing timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Global Data Center Accelerator Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Server Operating Environments Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Server Station Market