
 Micro Data Center Market | 2026-2036
Micro Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Data Center Market Analysis
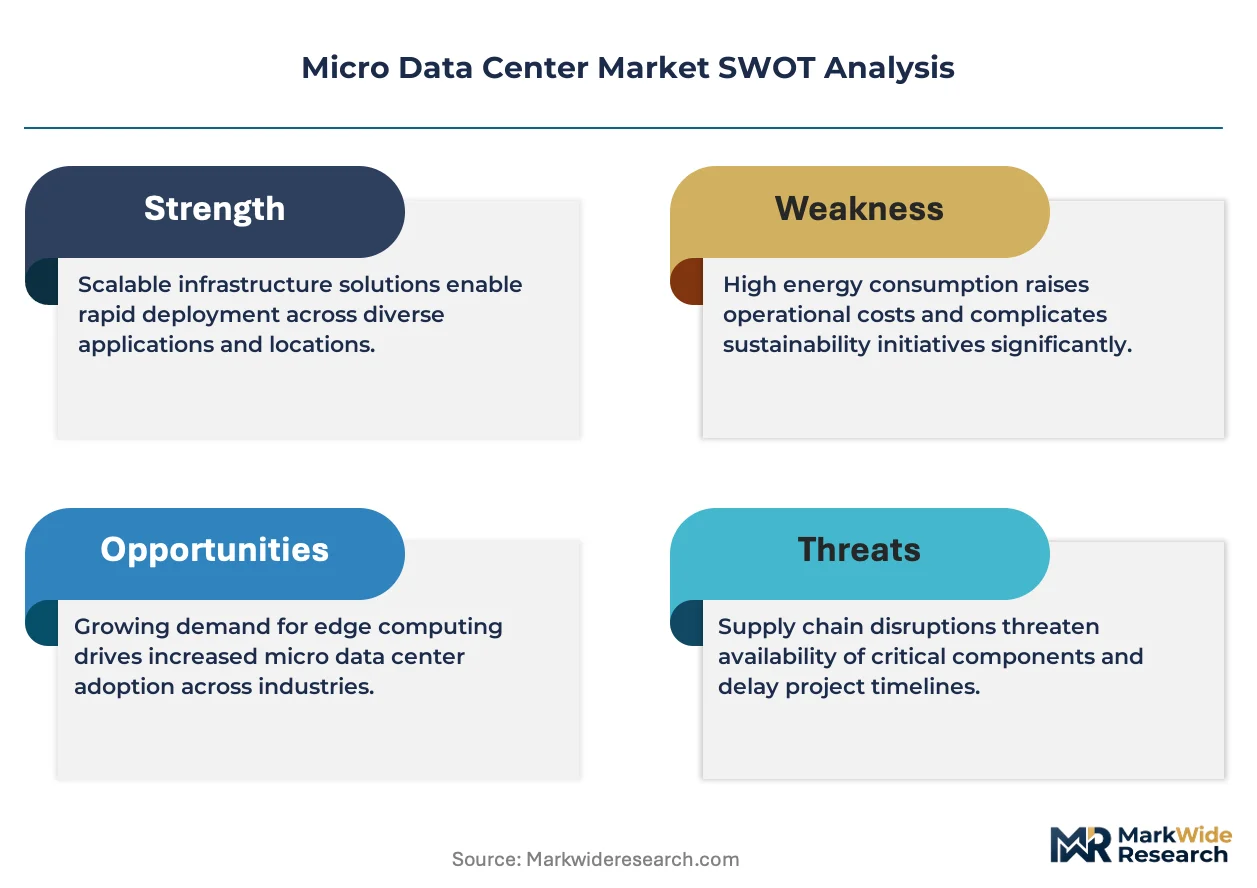
ISO/IEC 22237 data center certification is collapsing the supplier base to firms with documented thermal and power resilience. HPE leverages its liquid-cooled Apollo line to anchor high-density edge deployments. Schneider Electric differentiates through prefabricated modular architectures that compress site commissioning cycles. Vertiv dominates precision cooling subsystems for rack-mount configurations in telecom shelters.
Micro data centers are self-contained IT infrastructure enclosures, typically under 500 square feet, integrating power distribution, cooling, and network connectivity for localized compute workloads with sub-10 millisecond latency requirements. Their primary purpose is to process data at the network edge rather than transmitting volumes to centralized hyperscale facilities. Modular product types command margin premiums due to factory-integrated quality control and rapid field deployment, while liquid cooling technology segments capture expanding share as rack densities exceed 30 kW per cabinet. Rack-mount formats sustain volume leadership among retail and healthcare end users with constrained floor space.
FCC equipment authorization rules in the US, EU Code of Conduct for Data Centres efficiency standards, and China's GB 50174 data center design codes collectively elevate barrier-to-entry for uncertified suppliers. NHTSA-connected vehicle guidelines in the US and ETSI MEC standards in Europe further specify edge latency benchmarks that micro data center architectures must satisfy. Stakeholders must weigh captive deployment against colocation economics as sovereign data localization mandates proliferate across jurisdictions.
Market Dynamics
Edge computing latency requirements below ten milliseconds are compressing deployment timelines and forcing infrastructure closer to data sources than traditional centralized facilities permit.
Growth Catalysts
- Telecom 5G densification:Mobile network operators in Germany are deploying modular enclosures at base station sites to support ultra-reliable low-latency communication for industrial automation clusters.
- NMPA cybersecurity frameworks:China's data localization mandates require certified edge infrastructure for sensitive workloads, accelerating procurement of GB 50174-compliant modular units.
- Liquid cooling maturation:Direct-to-chip thermal management is enabling rack densities above thirty kilowatts without mechanical refrigeration, opening high-performance edge applications previously restricted to hyperscale facilities.
Market Restraints
- Copper and rare earth input volatility:Power distribution components and permanent magnet materials in precision cooling systems face price instability from concentrated mining operations in specific geographies.
- ISO/IEC 22237 certification scarcity:Documented thermal and power resilience testing capacity is limited to a shrinking pool of accredited laboratories, extending vendor qualification cycles.
- Colocation economics pressure:Shared edge facilities in urban cores offer lower upfront capital requirements than captive deployments, constraining direct equipment sales to enterprise buyers.
Strategic Opportunities
- India manufacturing automation:PLI scheme incentives for electronics production are driving demand for localized compute infrastructure in industrial corridors around Chennai and Bengaluru.
- Connected vehicle infrastructure:NHTSA guidelines for vehicle-to-everything communication are mandating roadside edge nodes for real-time collision avoidance systems.
- ETSI MEC standardization:European telecom interoperability specifications are creating specification-compliant product categories that command margin premiums over proprietary alternatives.
Industry Challenges
- Thermal engineering talent scarcity:Design of liquid-cooled edge enclosures requires specialized fluid dynamics expertise that outpaces current vocational training pipeline output.
- Legacy facility integration friction:Brownfield sites with constrained electrical service and physical access complicate modular unit placement and commissioning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Data Center Market |
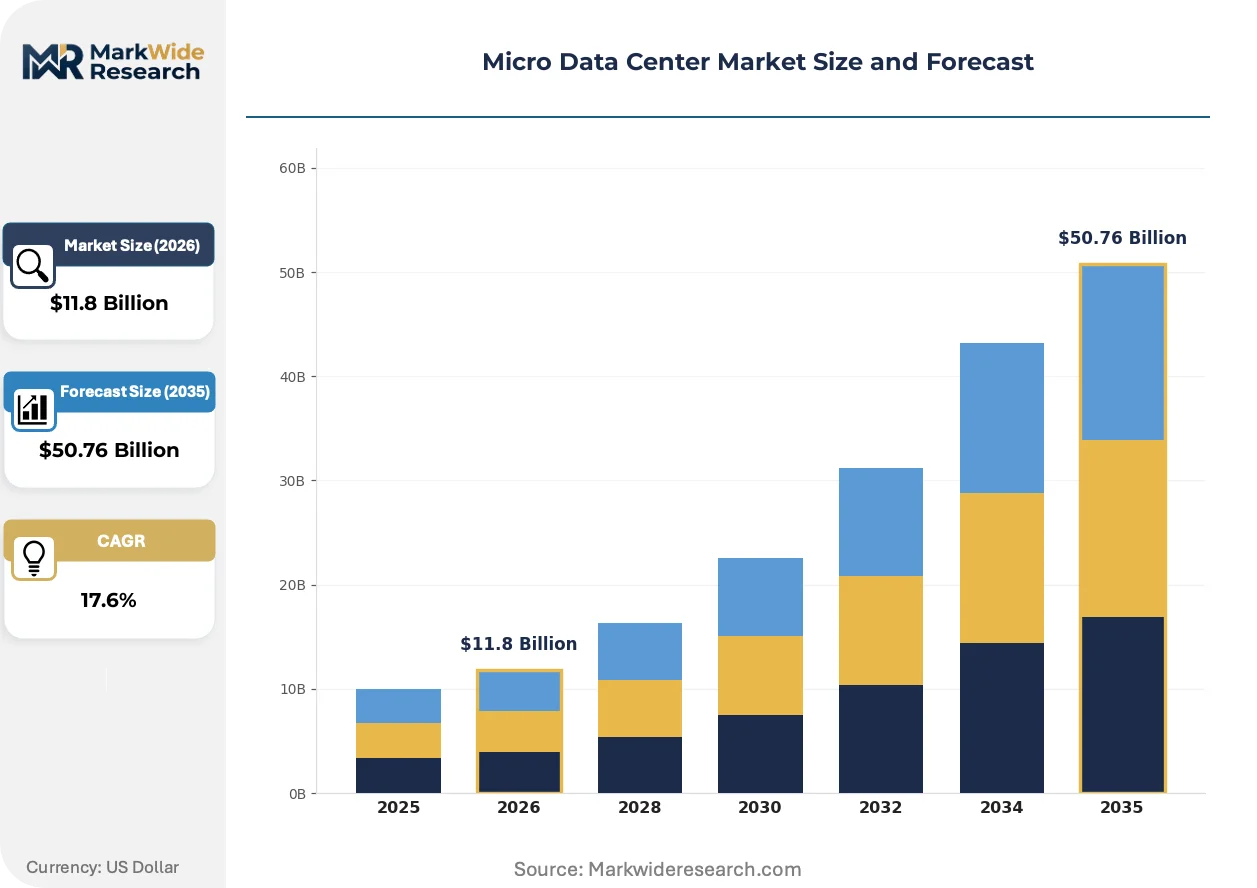
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $50.76 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Integrated, Modular, Edge Computing, Rack-Mount Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling End User: IT Enterprises, Telecom Providers, Retail, Healthcare Power Capacity: 10 kW, 20 kW, 50 kW, 100 kW |
| Companies Covered | HPE, Huawei, Schneider Electric, EdgeConneX, Equinix, Vertiv, Dell Technologies, Supermicro, NPOD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Data Center Market Emerging Trajectories
Three concurrent developments are restructuring how edge infrastructure is specified, deployed, and monetized across industrial and commercial settings.
Immersion cooling technology is miniaturizing. Single-phase dielectric fluid systems now fit within standard shipping container footprints, enabling deployment at cellular tower bases and factory floors previously restricted to air-cooled alternatives. Automotive and semiconductor manufacturers in South Korea and Taiwan are piloting these configurations for quality control analytics. The technology is miniaturizing thermal management from facility-scale to rack-scale, collapsing the mechanical infrastructure layer that previously dominated edge site design.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in precision cooling subsystems. Manufacturers must redesign compressor-based units using lower global-warming-potential working fluids before 2030 bans take effect. Telecom shelter deployments across Spain, Italy, and Poland face compressed retrofit timelines as existing equipment reaches end-of-life.
Buyers are unbundling hardware acquisition from operational support, demanding metered power and cooling service contracts with uptime guarantees rather than capital purchases. This consumption-model pivot is most advanced among German automotive suppliers and Japanese electronics assemblers with distributed production networks. Equipment vendors respond with residual-value-retention financing structures that transfer operational risk while preserving balance-sheet flexibility for customers.
Micro Data Center Market Segmentation
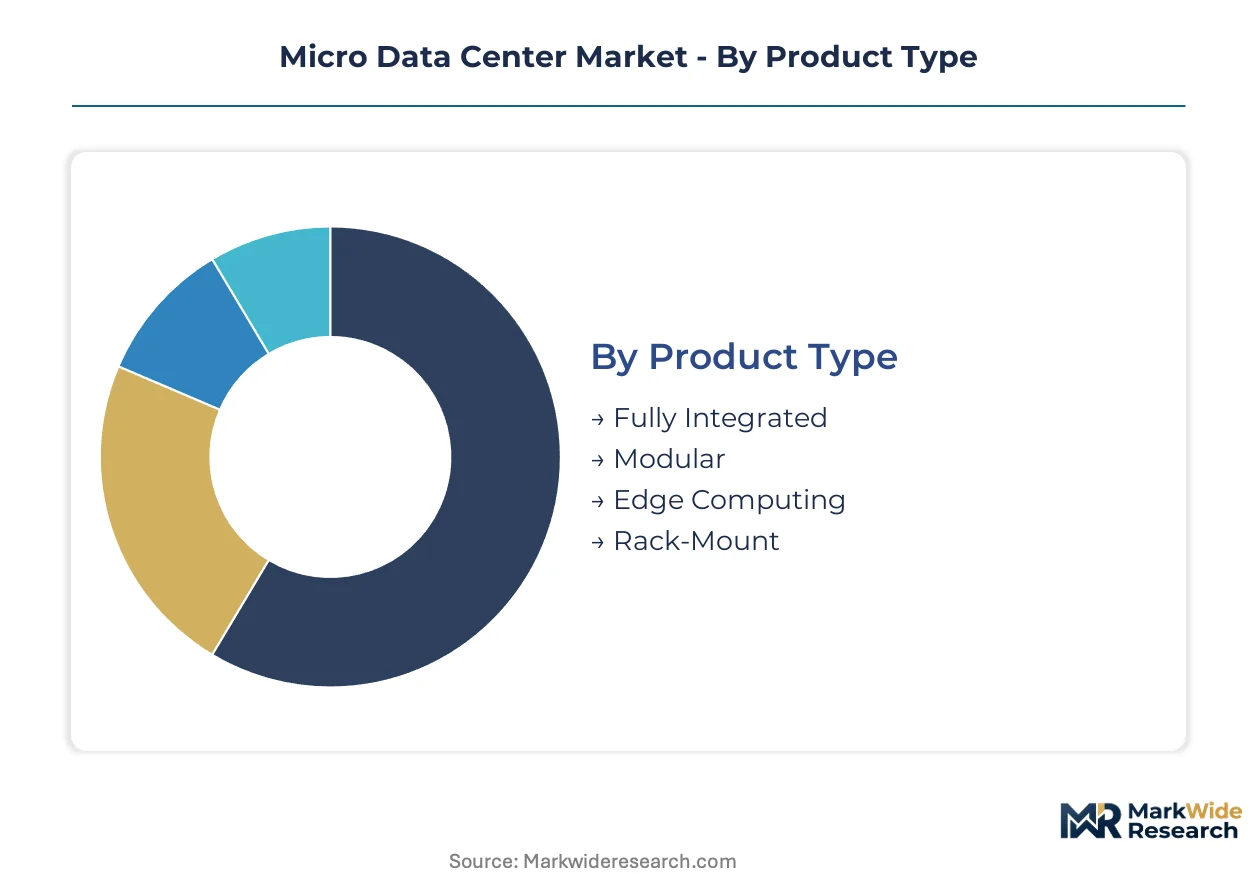
Segmentation in micro data centers reveals how procurement criteria diverge between latency-sensitive edge deployments and centralized processing requirements. Buyers prioritize factory-integrated quality control in modular formats for rapid field deployment, while thermal management specifications increasingly dictate supplier selection as rack densities escalate.
Product Type:
Substitution pressure intensifies as integrated systems compete against configurable modular alternatives that reduce vendor lock-in.
- Fully Integrated:Self-contained enclosures ship with pre-installed power distribution, cooling, and network connectivity from single-source suppliers. German automotive suppliers favor these for brownfield factory floors where commissioning speed outweighs customization flexibility.
- Modular:Factory-integrated subsystems enable rapid field assembly with documented thermal and power resilience per ISO/IEC 22237 protocols. Telecom providers in Spain and Italy specify these for 5G base station densification timelines that compress traditional construction cycles.
- Edge Computing:Compact form factors optimized for sub-10 millisecond latency workloads at network peripheries.
- Rack-Mount:Standardized 19-inch enclosures for constrained floor spaces in retail and healthcare settings.
Modular configurations anchor the volume base while edge computing formats gain share at the steepest rate.
Cooling Technology:
Cost tier stratification separates premium thermal management from commodity air-cooled alternatives as power densities climb.
- Liquid Cooling:Direct-to-chip and cold plate systems dissipate heat from processors exceeding 30 kW per cabinet without mechanical refrigeration. South Korean semiconductor manufacturers pilot these for quality control analytics where thermal stability directly impacts yield rates.
- Immersion Cooling:Single-phase dielectric fluid systems now fit standard shipping container footprints, collapsing mechanical infrastructure layers at cellular tower bases. Taiwan electronics assemblers deploy these for distributed production networks requiring minimal site preparation.
- Air Cooling:Conventional forced-air systems dominate legacy installations with sub-15 kW densities.
- Hybrid Cooling:Combined air-liquid approaches for transitional rack densities and mixed workload environments.
Air cooling sustains the installed base while liquid cooling climbs the fastest as high-performance edge applications proliferate.
End User:
Application requirements fragment procurement patterns across latency tolerance, uptime guarantees, and physical security mandates.
- Telecom Providers:Mobile network operators deploy modular enclosures at base station sites for ultra-reliable low-latency communication. ETSI MEC standardization in Europe creates specification-compliant product categories that command margin premiums.
- Healthcare:HIPAA-compliant edge nodes process imaging and patient monitoring data with strict data localization. NMPA cybersecurity frameworks in China accelerate procurement of certified modular units for sensitive workloads.
- IT Enterprises:Captive deployments versus colocation economics drive hardware versus service contract decisions.
- Retail:Constrained floor spaces and distributed point-of-sale systems favor rack-mount configurations.
Telecom providers anchor demand volume while healthcare expands most quickly under regulatory compliance pressure.
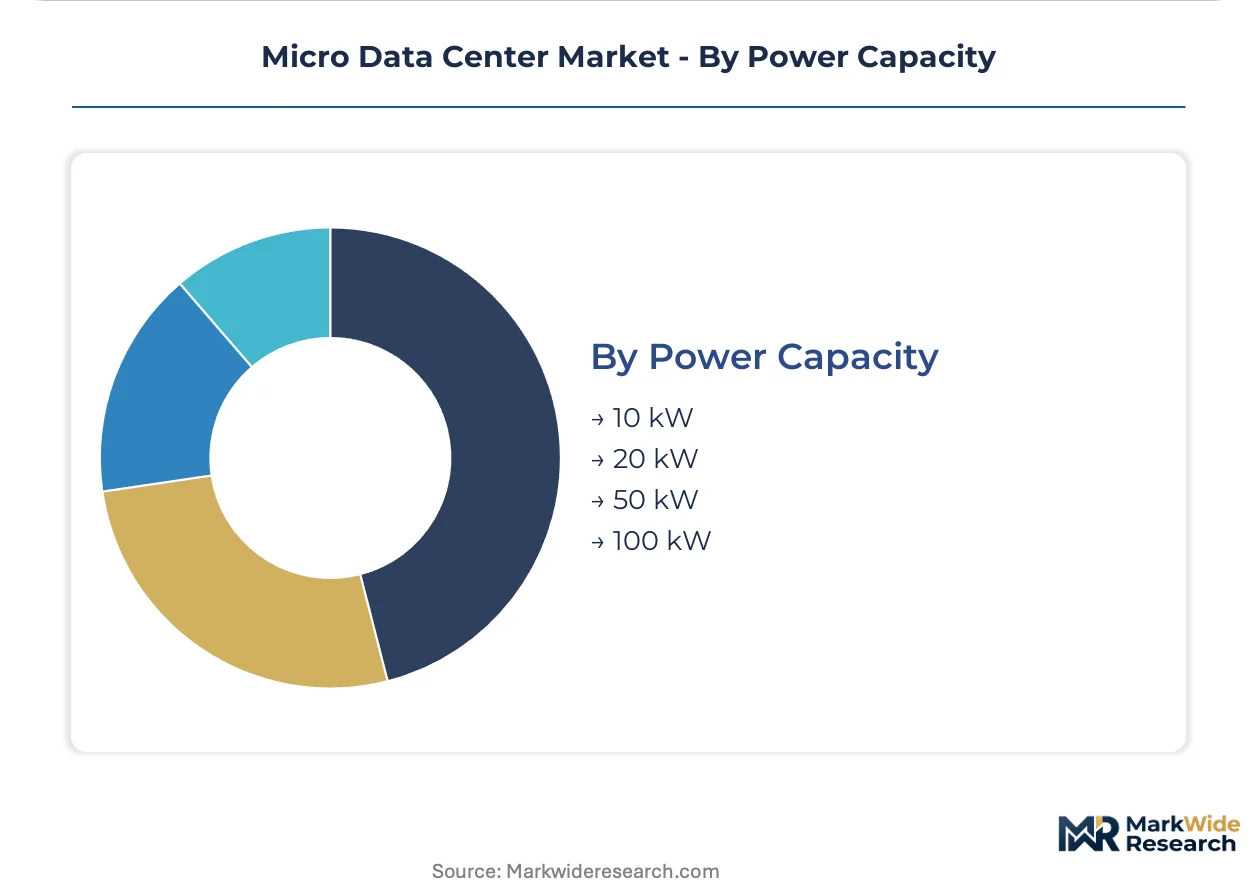
Power Capacity:
Customer type segmentation separates hyperscale-proximate densities from enterprise edge requirements.
- 50 kW:High-density enclosures serve AI inference and video analytics at manufacturing facilities. PLI scheme incentives in India drive localized compute infrastructure in industrial corridors around Chennai.
- 100 kW:Extreme density configurations previously restricted to hyperscale facilities now deploy at automotive proving grounds. NHTSA-connected vehicle guidelines mandate roadside edge nodes for real-time collision avoidance systems.
- 10 kW:Entry-level specifications for remote office and small retail deployments.
- 20 kW:Mid-range capacity for standard enterprise edge workloads and distributed IT.
20 kW specifications anchor the volume base while 100 kW configurations gain share fastest at the high-performance edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom providers and industrial automation clusters constitute the dominant buyer archetypes across major markets, with procurement patterns diverging sharply between latency-sensitive edge deployments and captive enterprise installations. Regulatory mandates around data localization and cybersecurity certification are compressing supplier qualification timelines in every geography. Site commissioning constraints favor modular architectures that minimize field construction.
Germany
Industrial automation clusters in Baden-Württemberg and Bavaria drive modular micro data center installations for factory-floor analytics. The KBA and federal cybersecurity frameworks mandate certified edge infrastructure for connected vehicle testing facilities. Stuttgart's automotive supplier corridor deploys liquid-cooled enclosures for real-time quality control systems.
United States
NHTSA-connected vehicle guidelines and FCC equipment authorization rules accelerate roadside edge node deployment for collision avoidance systems. Texas and California anchor demand through autonomous vehicle proving grounds and hyperscale edge extensions. Phoenix and Dallas metro areas concentrate modular unit installations for telecom 5G densification.
China
NMPA cybersecurity frameworks and GB 50174 data center design codes mandate certified edge infrastructure for sensitive healthcare and financial workloads. The Yangtze River Delta and Pearl River Delta industrial corridors deploy modular units under data localization requirements. Shenzhen electronics assemblers pilot immersion cooling for distributed production networks.
India
PLI scheme incentives for electronics manufacturing drive localized compute infrastructure demand in Tamil Nadu and Karnataka industrial corridors. The CEA and TRAI frameworks shape power and connectivity specifications for edge deployments. Chennai and Bengaluru cluster modular installations for semiconductor testing and automotive component manufacturing.
South Korea
MFDS regulatory alignment with international data standards accelerates certified edge infrastructure for healthcare AI workloads. Semiconductor manufacturers in Gyeonggi Province deploy liquid-cooled enclosures for wafer inspection analytics. The Seoul Capital Area concentrates rack-mount configurations for retail and financial services edge nodes.
Micro Data Center Market Vendor Landscape
Player mix skews toward diversified infrastructure conglomerates with thermal management heritage, creating a tiered structure where certification capabilities separate premium suppliers from commodity assemblers. Consolidation pressure intensifies as ISO/IEC 22237 documentation requirements collapse the accredited supplier base. Three archetypes dominate: integrated systems vendors with liquid cooling portfolios, modular prefabrication specialists with compressed commissioning workflows, and precision cooling subsystem providers for rack-mount configurations. Competitive moves center on strategic partnerships for certification laboratory access and geographic expansion through local assembly licensing.
Within the diversified infrastructure tier, Schneider Electric and Vertiv exemplify contrasting positioning strategies, with the former anchoring prefabricated modular architectures and the latter dominating precision cooling subsystems for telecom shelter deployments. HPE occupies a distinct position through liquid-cooled server integration for high-density edge configurations. Huawei represents the vertically integrated conglomerate archetype with captive component supply chains spanning power distribution and thermal management. These three anchors illustrate how certification access and thermal engineering depth separate sustainable competitors from assembly-dependent entrants.
| Leading Market Players |
|---|
| HPE |
| Huawei |
| Schneider Electric |
| EdgeConneX |
| Equinix |
| Vertiv |
| Dell Technologies |
| Supermicro |
| NPOD |
| Others |
Supply Flow & Price Mechanics
ISO/IEC 22237 certification scarcity gates both supplier qualification and price differentiation simultaneously, collapsing the accredited vendor base to firms with documented thermal resilience while commanding margin premiums for factory-integrated modular units over commodity rack-mount alternatives.
Pricing Analysis
Cost-plus contracts with copper and rare earth indexation dominate procurement for power distribution components and permanent magnet cooling systems. Three-tier pricing structure across ISO-certified premium, standard modular, and economy rack-mount levels separates buyers by uptime guarantee requirements. Pricing pressure stems from colocation economics in urban cores that undercut captive deployment capital costs. Telecom providers exhibit highest price sensitivity due to 5G densification volume requirements, while German automotive suppliers prioritize commissioning speed over unit economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion compress modular unit delivery timelines for European telecom deployments. Manufacturing concentrates in China, Germany, and the United States for precision cooling subsystems and power distribution components. Supply chains draw from copper mining operations in Chile, rare earth processing in China, and semiconductor-grade refrigerants from Japanese chemical producers. Single-source vulnerability in ISO/IEC 22237 accredited laboratory capacity extends vendor qualification cycles. Distribution runs through direct OEM channels for enterprise buyers and systems integrators for telecom shelter deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermal engineering talent shortages constrain expansion velocity, with fluid dynamics expertise outpacing vocational training pipeline output across every major manufacturing cluster.
For Market Incumbents: Shield certification moats by securing exclusive laboratory accreditation partnerships before capacity constraints harden. Deepen backward integration into liquid cooling component manufacturing to offset copper and rare earth input volatility. Prioritize captive production of precision cooling subsystems over outsourced assembly to defend margin position against modular prefabrication specialists. For New Entrants and Emerging Players: GB 50174 fast-track certification in China offers the most penetrable entry point under NMPA cybersecurity localization mandates. Target Indian industrial corridors around Chennai and Bengaluru where PLI scheme incentives outpace established vendor presence. Lead with metered power and cooling service contracts rather than capital sales to bypass incumbent financing relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular prefabrication specialists lacking liquid cooling portfolios. Five-to-ten year viability hinges on thermal engineering depth rather than assembly scale. Watch ETSI MEC standardization compliance rates as the inflection signal for specification-premium capture versus commodity margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 22237 Certification Investment | Accredited thermal resilience documentation collapses supplier base to certified firms. |
| Liquid Cooling Technology Licensing | Direct-to-chip thermal management enables rack densities above thirty kilowatts. |
| Prefabricated Modular Manufacturing Scale-Up | Factory-integrated quality control compresses German automotive site commissioning cycles. |
| ETSI MEC Standardization Compliance | European telecom interoperability specifications command margin premiums over proprietary alternatives. |
| Immersion Cooling Pilot Deployment | Single-phase dielectric fluid systems fit cellular tower footprints previously restricted to air cooling. |
Methodological Framework
A spread of perspectives from data center engineering directors, telecom infrastructure procurement leads, thermal systems R&D heads, and modular manufacturing plant managers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings, hyperscaler capex disclosures, ETSI standardization documents, and national regulator equipment authorization databases. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment forecasts.
Segmentation dimensions modeled span product type, cooling technology, end user vertical, power capacity tier, and regional regulatory cluster across the analysis window. CAGRs derive from installed base replacement cycles, density escalation curves, and localization mandate implementation timelines. Forecast inputs incorporate 5G base station densification schedules, industrial automation cluster expansion, and connected vehicle roadside node deployment under NHTSA guidelines.
Underlying assumptions cover certification laboratory capacity expansion, copper price stabilization, and refrigerant transition timelines, with deviation risk concentrated in rare earth supply disruptions and ISO/IEC 22237 accreditation bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Norway Data Center Rack Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Brazil Data Center Power Market
Data Center Infrastructure
Russia Data Center Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Nigeria Data Center Server Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market