
 Hosting Infrastructure Services Market | 2026-2036
Hosting Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hosting Infrastructure Services Market Analysis
Asset-light leasing and colocation financing is narrowing the capital barrier for mid-tier enterprises seeking Tier III+ reliability without balance-sheet ownership of physical plant. Amazon Web Services leverages its hyperscale build program to sustain pricing power across compute and storage tiers. Microsoft Azure anchors enterprise trust through deep integration with existing productivity stacks and hybrid management tooling. Equinix competes on interconnection density, operating carrier-neutral campuses that control cross-border traffic exchange points.
Hosting infrastructure services encompass the physical and virtualized compute, storage, and networking resources delivered from data centers to support application workloads, typically measured by power density per rack exceeding 15 kW in modern facilities and uptime guarantees tied to tiered redundancy architectures. Their primary commercial purpose is to replace capital-intensive on-premises IT ownership with scalable operational expenditure models. Cloud hosting and hybrid deployment configurations currently lead segment momentum, as large enterprises navigate latency requirements against sovereignty concerns. Dedicated hosting retains margin strength in regulated verticals where single-tenant isolation remains non-negotiable, while container-based virtualization is displacing traditional hypervisor approaches in DevOps-intensive environments.
FERC grid interconnection rules, EU Energy Efficiency Directive standards for data center power usage effectiveness, and OSHA electrical safety requirements collectively shape where and how providers can expand physical footprint. Compliance with these frameworks directly determines permitting timelines and operational cost structures for new builds. Stakeholders must monitor whether carbon border adjustments and evolving building code electrification mandates alter the geographic calculus for capacity additions.
Market Dynamics
Hyperscale cloud providers are consolidating control over critical interconnection nodes, forcing mid-tier colocation operators into specialized niches around latency-sensitive workloads and sovereign data requirements.
Growth Catalysts
- EU AI Act compliance mandates:Financial services and healthcare enterprises in Germany, France, and the Netherlands require certified data residency and algorithmic audit trails, driving demand for sovereign cloud capacity with verifiable chain-of-custody documentation.
- High-frequency trading infrastructure:Frankfurt's proximity to European securities exchanges creates concentrated demand for sub-10-microsecond co-location, with proprietary microwave and fiber networks linking trading venues to compute clusters.
- Liquid cooling adoption:Power densities exceeding 30 kW per rack in AI training facilities are rendering traditional air-cooling architectures economically unviable, accelerating retrofit cycles in legacy facilities.
Market Restraints
- Copper and electrical component cost volatility:Busbar and switchgear lead times extending beyond 52 weeks are compressing project IRRs and delaying hyperscale campus energization schedules.
- Frankfurt-Amsterdam-London corridor concentration:Over 60 percent of Western European cross-border capacity transits through three metropolitan fiber nodes, creating systemic resilience risk without geographic diversification.
- FERC interconnection queue backlogs:Grid connection studies for new data center loads in PJM and ERCOT territories now average 36 months, constraining greenfield development timelines.
Strategic Opportunities
- Nordic renewable energy arbitrage:Norway and Sweden offer sub-€40/MWh hydroelectric power with natural free-air cooling advantages, attracting hyperscale builds for batch AI training workloads tolerant of latency.
- Modular edge containerization:Factory-integrated power and cooling modules enable 90-day deployment cycles for 5G radio access network densification and autonomous vehicle data ingestion points.
- EU Energy Efficiency Directive incentives:Waste heat recovery mandates for data centers above 1 MW are creating district heating partnerships with municipal utilities in Copenhagen and Stockholm.
Industry Challenges
- Electrical trades specialization gap:Medium-voltage commissioning technicians with data center-specific arc-flash certification command 40 percent wage premiums, constraining workforce scaling for multiple simultaneous builds.
- Uptime Institute Tier III operational certification:The 12-18 month documentation and testing cycle for concurrent maintainability validation delays revenue recognition on capital deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hosting Infrastructure Services Market |
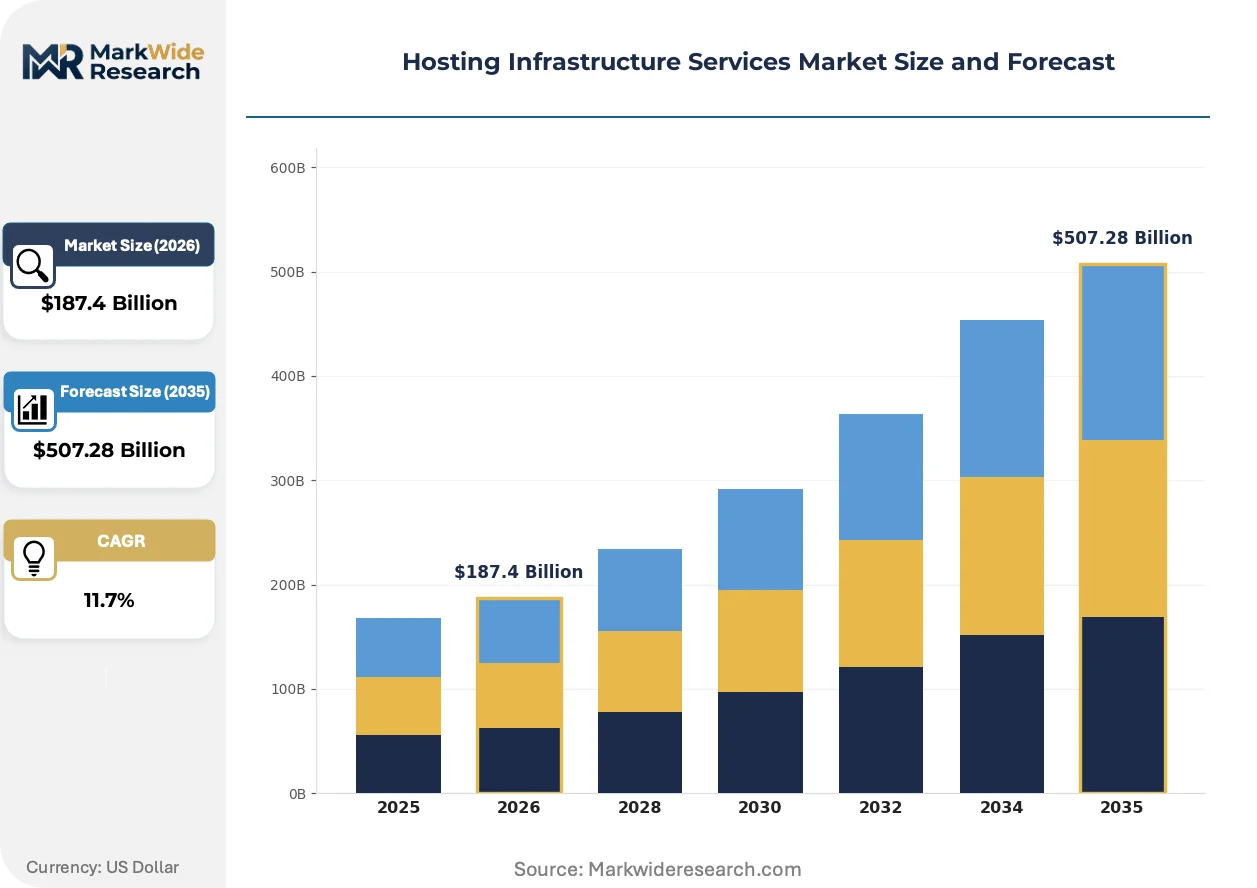
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Hosting, Cloud Hosting, VPS Hosting, Shared Hosting Technology: Virtualization, Containers, Load Balancing, CDN Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions |
| Companies Covered | IBM Cloud, VMware, Amazon Web Services (AWS), Dell Technologies, Cisco Systems, Microsoft Azure, Oracle Cloud Infrastructure, Equinix, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hosting Infrastructure Services Market Emerging Trajectories
Computational workloads are fragmenting across specialized silicon architectures and geographic footprints, decoupling the historical correlation between enterprise data gravity and facility ownership.
Immersion cooling using synthetic dielectric fluids is rendering obsolete raised-floor air-handling units in high-performance computing deployments. Hyperscale AI training clusters in Taiwan and Singapore are adopting single-phase immersion for GPU densities exceeding 50 kW per rack. The technology is compressing facility footprints by 60 percent while eliminating mechanical refrigeration energy overhead.
The EU AI Act's risk-based classification system for foundation models is mandating algorithmic documentation and third-party audit infrastructure. Providers serving regulated European enterprises must maintain immutable logging architectures with 10-year retention horizons. German automotive manufacturers and French pharmaceutical firms are pre-qualifying facilities based on existing ISO 27001 and anticipated AI Act certification scopes.
Enterprise buyers are unbundling managed services from infrastructure leases, contracting compute capacity through spot-market mechanisms while retaining operational control through Kubernetes-native orchestration. Financial services firms in London and Singapore are disintermediating traditional colocation resale channels, procuring directly from hyperscale regions with self-managed network overlays. This pattern concentrates margin pressure on value-added resellers lacking proprietary interconnection assets.
Hosting Infrastructure Services Market Segmentation
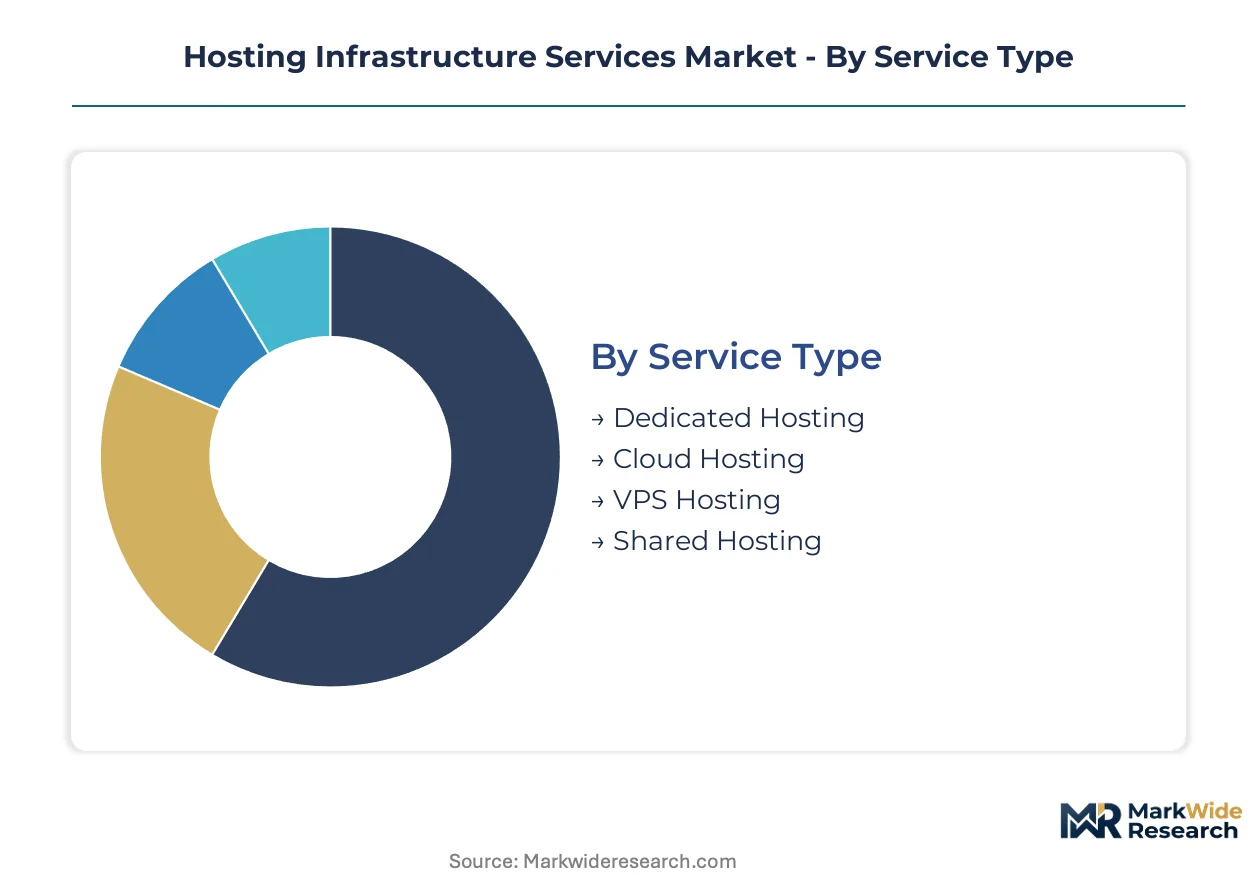
Hosting infrastructure services fragment across four distinct dimensions that determine procurement patterns, margin structures, and vendor specialization. Service type defines the tenancy model and operational responsibility split. Technology selection dictates hardware efficiency and orchestration complexity. Deployment architecture governs data sovereignty and latency trade-offs. End-user scale shapes pricing mechanisms and support intensity.
Service Type:
Enterprises select hosting models based on workload isolation requirements, compliance mandates, and capital efficiency preferences across the use-case spectrum.
- Cloud Hosting:Multi-tenant virtualized resources provisioned on-demand through API-driven orchestration, enabling elastic scaling without physical infrastructure ownership. Financial services firms in Frankfurt and healthcare systems in the Netherlands are consolidating here to satisfy EU AI Act audit trail requirements while avoiding stranded capacity.
- Dedicated Hosting:Single-tenant physical servers with exclusive network and storage resources, maintaining isolation for regulated workloads. German automotive manufacturers and French pharmaceutical companies pre-qualify these environments for anticipated algorithmic certification scopes under emerging EU frameworks.
- VPS Hosting:Partitioned virtual servers with guaranteed resource allocation on shared hardware, bridging cost efficiency with administrative control.
- Shared Hosting:Communal server resources with standardized configurations, serving cost-sensitive web presence workloads.
The dominant share belongs to Cloud Hosting, while Dedicated Hosting is closing the gap fastest as sovereign data requirements intensify.
Technology:
Cost tier differentiation separates legacy virtualization from container-native architectures optimized for density and deployment velocity.
- Containers:Operating-system-level virtualization packaging applications with dependencies into portable runtime units, displacing hypervisor overhead in DevOps-intensive environments. Kubernetes-native orchestration is disintermediating traditional managed service channels as London and Singapore financial firms procure directly from hyperscale regions with self-managed network overlays.
- Virtualization:Hardware-abstraction layers enabling multiple operating systems on single physical hosts, retaining dominance in legacy enterprise migration scenarios. VMware and Hyper-V environments persist where existing operational tooling and staff certification create switching costs.
- Load Balancing:Traffic distribution mechanisms across compute pools to maintain availability and optimize resource utilization.
- CDN:Geographically distributed edge servers caching content closer to end-users to reduce latency and origin load.
Container adoption is expanding most quickly among cloud-native enterprises, while virtualization maintains entrenched positions in regulated verticals with extended depreciation cycles.
Deployment:
Application criticality and data classification determine whether organizations retain on-premises control, delegate fully to public operators, or architect hybrid intermediates.
- Hybrid Cloud:Interoperable private and public infrastructure with workload portability and unified management planes, capturing momentum as large enterprises navigate latency requirements against sovereignty concerns. German enterprises particularly favor this model to maintain sensitive data on-premises while bursting transactional workloads to Frankfurt hyperscale regions.
- Public Cloud:Shared infrastructure operated by third-party providers with consumption-based economics and global footprint expansion.
- Private Cloud:Dedicated cloud infrastructure operated for single organization use, whether on-premises or at colocation facilities.
- On-Premises:Traditional data center ownership with full capital responsibility and operational control.
Hybrid Cloud configurations command the strategic center as regulatory fragmentation accelerates multi-environment architectures.
End User:
Customer scale segments procurement sophistication, contract structure, and vendor relationship intensity from standardized self-service to bespoke enterprise engagements.
- Large Enterprises:Complex multi-year agreements with customized service level agreements, dedicated account management, and direct hyperscale procurement bypassing resale channels. These organizations unbundle managed services from infrastructure leases, contracting compute through spot-market mechanisms while retaining operational control.
- SMEs:Standardized packages with limited customization, higher per-unit pricing, and greater reliance on channel partners and value-added resellers.
- Government Agencies:Sovereign cloud mandates with certified data residency, domestic personnel screening, and immutable logging architectures with extended retention horizons.
- Educational Institutions:Volume-discounted agreements supporting research computing, administrative systems, and student-facing services with fluctuating seasonal demand.
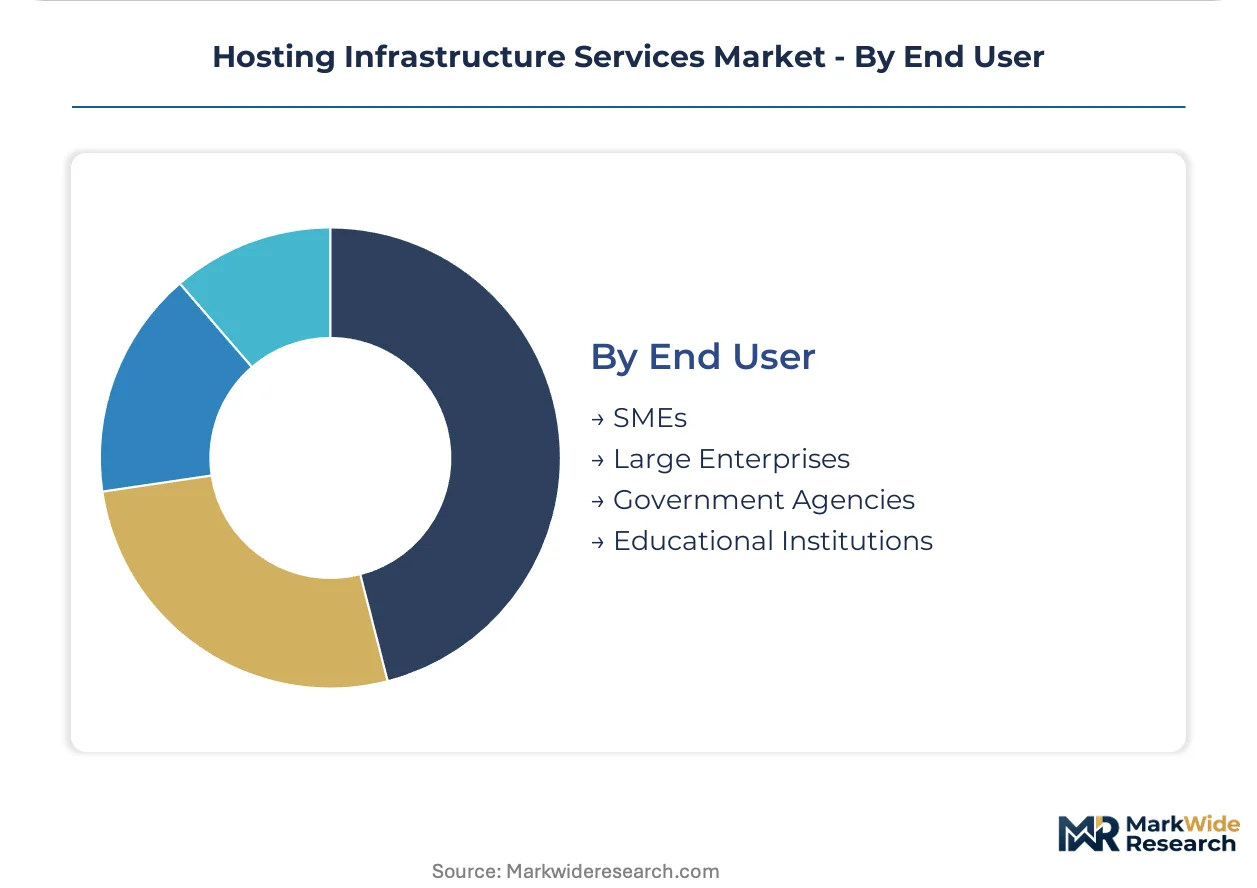
Large Enterprises generate the predominant revenue concentration, though Government Agencies are gaining share fastest as public sector digitalization and compliance mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German hyperscale markets exceeds Nordic baseload regions by approximately 35 percent, reflecting Frankfurt's irreplaceable connectivity density against Norway's renewable energy cost advantages. This asymmetry reshapes where providers deploy latency-sensitive versus batch-optimized capacity.
United States
Virginia's Data Center Alley and Dallas-Fort Worth anchor domestic demand, with FERC interconnection queue backlogs averaging 36 months in PJM and ERCOT territories. The Inflation Reduction Act's clean energy tax credits accelerate renewable-powered campus development in Texas and Arizona. Northern Virginia's Loudoun County maintains the world's highest concentration of commissioned hyperscale capacity.
Germany
Frankfurt's proximity to European securities exchanges generates sub-10-microsecond co-location demand from high-frequency trading firms. EU AI Act compliance mandates require certified data residency and algorithmic audit trails for financial services and healthcare enterprises. The Rhine-Main metropolitan region attracts hyperscale builds from multiple continents seeking Tier III+ reliability.
United Kingdom
London's financial services sector drives sovereign cloud requirements with immutable logging architectures and 10-year retention horizons. The Financial Conduct Authority's operational resilience rules mandate minimum recovery time objectives for critical trading infrastructure. Slough and Docklands data center clusters concentrate cross-border fiber capacity linking European and transatlantic routes.
Netherlands
Amsterdam's AMS-IX internet exchange ranks among Europe's largest traffic nodes, creating interconnection-dependent demand from content delivery networks. The Dutch Data Center Association's sustainability covenant mandates power usage effectiveness reporting above 1 MW threshold. North Holland's Haarlemmermeer municipality hosts multiple hyperscale campuses leveraging North Sea cable landing stations.
Singapore
Maritime Southeast Asia's digital gateway status attracts AI training clusters requiring 50+ kW per rack densities with single-phase immersion cooling. The Infocomm Media Development Authority's data center energy efficiency standards restrict new builds to 100 MW annual power budget allocations. Tuas and Jurong industrial zones concentrate submarine cable terminations linking Asia-Pacific markets.
Hosting Infrastructure Services Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cooling, power distribution, and networking substrates. The vendor base stratifies into three tiers: hyperscale cloud operators with captive generation capacity, carrier-neutral colocation providers with interconnection assets, and managed service intermediaries facing margin compression. Strategic differentiation concentrates on geographic footprint expansion, liquid cooling retrofit capabilities, and sovereign certification pre-qualification.
Within the hyperscale operator archetype, Amazon Web Services and Microsoft Azure exemplify platform-scale leverage through build programs sustaining pricing power across compute tiers. Equinix occupies a distinctive position among carrier-neutral providers, operating interconnection-dense campuses that control cross-border traffic exchange points. These three entities represent contrasting competitive vectors: operational scale, productivity stack integration, and physical network density.
| Leading Market Players |
|---|
| IBM Cloud |
| VMware |
| Amazon Web Services (AWS) |
| Dell Technologies |
| Cisco Systems |
| Microsoft Azure |
| Oracle Cloud Infrastructure |
| Equinix |
| Google Cloud Platform |
| Others |
Supply Flow & Price Mechanics
Frankfurt-Amsterdam fiber corridors carry the cost dynamics that concentrate supply-side leverage among Tier III+ facility operators while fragmenting downstream price differentiation between sovereign-certified and standard colocation tiers. This logistics chokepoint amplifies margin compression for mid-tier providers lacking proprietary interconnection assets.
Pricing Analysis
The customization-premium spread between configured-to-order sovereign cloud deployments and standard multi-tenant colocation runs wide, with certified data residency and algorithmic audit trail capabilities commanding substantial uplifts. Three-tier pricing structure across premium certified, standard enterprise, and economy self-service levels reflects ISO 27001 pre-qualification status and liquid cooling readiness. Pricing pressure stems from hyperscale direct procurement bypassing traditional resale channels, compressing margins for value-added intermediaries. SMEs exhibit highest price sensitivity through standardized package selection, while large financial services firms in Frankfurt absorb premiums for sub-10-microsecond latency guarantees.
Supply Chain Analysis
Contract manufacturing concentration rests with Schneider Electric, Vertiv, and Stulz for precision cooling systems, plus Delta and Eaton for power distribution units, creating concentrated sourcing leverage for facility infrastructure. Supply chains draw from Taiwan and China for switchgear components, Germany for precision engineering, and the United States for automation controls. Copper busbar and electrical component lead time volatility creates single-source vulnerability for hyperscale campus energization schedules. Distribution runs through direct OEM relationships for hyperscale operators and regional systems integrators for mid-tier deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed interconnection and sovereign certification services represent the fastest-expanding recurring-revenue layer, outpacing raw infrastructure lease economics as enterprises unbundle operational control from physical capacity procurement.
For Market Incumbents: Entrench defensive positioning through liquid cooling retrofit capabilities in legacy Frankfurt and London facilities, while securing EU AI Act pre-certification scopes ahead of mandatory compliance deadlines. Backward integration into renewable power sourcing through long-term purchase agreements with Nordic hydroelectric utilities mitigates margin pressure from grid interconnection queue delays. For New Entrants and Emerging Players: Modular edge containerization for 5G radio access network densification in secondary German metropolitan regions represents the most penetrable entry point, with 90-day deployment cycles enabling rapid market presence establishment. Direct procurement channels bypassing traditional colocation resale intermediaries offer the strongest go-to-market angle for Kubernetes-native orchestration specialists. For Investors and Strategic Acquirers: Carve-out targets emerge from carrier-neutral colocation providers with interconnection-dense campus assets in the Rhine-Main metropolitan region but lacking hyperscale balance sheet scale for sovereign certification investment. Long-term viability centers on facilities achieving concurrent maintainability validation with verifiable chain-of-custody documentation. The signal to watch is FERC interconnection queue clearance rates as inflection indicator for greenfield development capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Program | Enables 30+ kW per rack densities for AI training clusters in legacy Frankfurt facilities. |
| Sovereign Cloud Certification | Positions facilities for EU AI Act algorithmic audit trail mandates in German automotive verticals. |
| Nordic Renewable Energy Arbitrage | Captures sub-€40/MWh hydroelectric power for batch AI workloads tolerant of latency. |
| Modular Edge Containerization | Compresses deployment cycles to 90 days for 5G densification and autonomous vehicle data ingestion. |
| Direct Hyperscale Procurement Channel | Bypasses value-added reseller margin compression for London and Singapore financial services firms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center facility managers, hyperscale cloud procurement officers, colocation sales directors, electrical commissioning technicians, and municipal utility planning officers. Secondary validation drew from FERC interconnection filings, EU Energy Efficiency Directive compliance databases, Uptime Institute Tier certification records, and hyperscaler capital expenditure disclosures. Bottom-up capacity build tracking and top-down market sizing triangulation anchored volume estimates.
Calibration against historical energization schedules and announced campus expansions informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, technology layer, and end-user scale, with regional regulatory cluster effects layered across geographies. CAGRs were derived from capacity commissioning timelines and power density evolution curves, incorporating liquid cooling adoption rates and sovereign certification penetration as industry-specific forecast inputs.
Practitioners should monitor FERC interconnection queue clearance velocities, copper and electrical component lead time trajectories, and EU AI Act implementing regulation releases for early signals of forecast revision. Quarterly review of hyperscale announcement pipelines and Tier III+ certification award rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
US Data Center Construction Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Nigeria Data Center Rack Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
Global Data Center RFID Market
Data Center Infrastructure
Spain Data Center Market