
 Data Center Rack Solutions Market | 2026-2036
Data Center Rack Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Rack Solutions Market Outlook
Multi-sourced rack procurement is expanding across hyperscale operators that previously relied on single-vendor frameworks. Schneider Electric leverages its integrated power and cooling portfolio to anchor long-term supply contracts with cloud providers. Rittal sustains its position through deep specialization in thermal-optimized enclosure systems. Vertiv competes aggressively on modular architectures that reduce field assembly time for wholesale colocation builds.
Data center rack solutions are structural mounting frameworks engineered to standardized EIA-310-D dimensions, typically fabricated from cold-rolled steel with static load ratings spanning 1,500 to 3,000 pounds, designed to organize, protect, and cool servers, switches, and power distribution units within controlled environments. Enclosed rack systems command premium positioning due to integrated airflow containment and physical security requirements at financial services and government facilities. High-capacity and ultra-high-capacity segments are gaining share as GPU-intensive AI training clusters push per-rack power densities beyond 30 kilowatts, forcing structural reinforcement and cable management upgrades. Steel remains the dominant material platform, though aluminum content is rising in edge deployments where weight reduction simplifies transport and rapid installation.
The U.S. Environmental Protection Agency's ENERGY STAR specifications for data center equipment shape procurement criteria for federal and enterprise buyers, while the EU's F-Gas Regulation and Ecodesign requirements drive enclosure thermal efficiency mandates across European deployments. China's GB standards for electronic equipment mechanical structures impose local certification burdens on imported rack systems. Stakeholders must monitor how jurisdictional efficiency standards fragment product platforms and whether modular, region-configurable designs can contain compliance costs without sacrificing manufacturing scale.
Market Dynamics
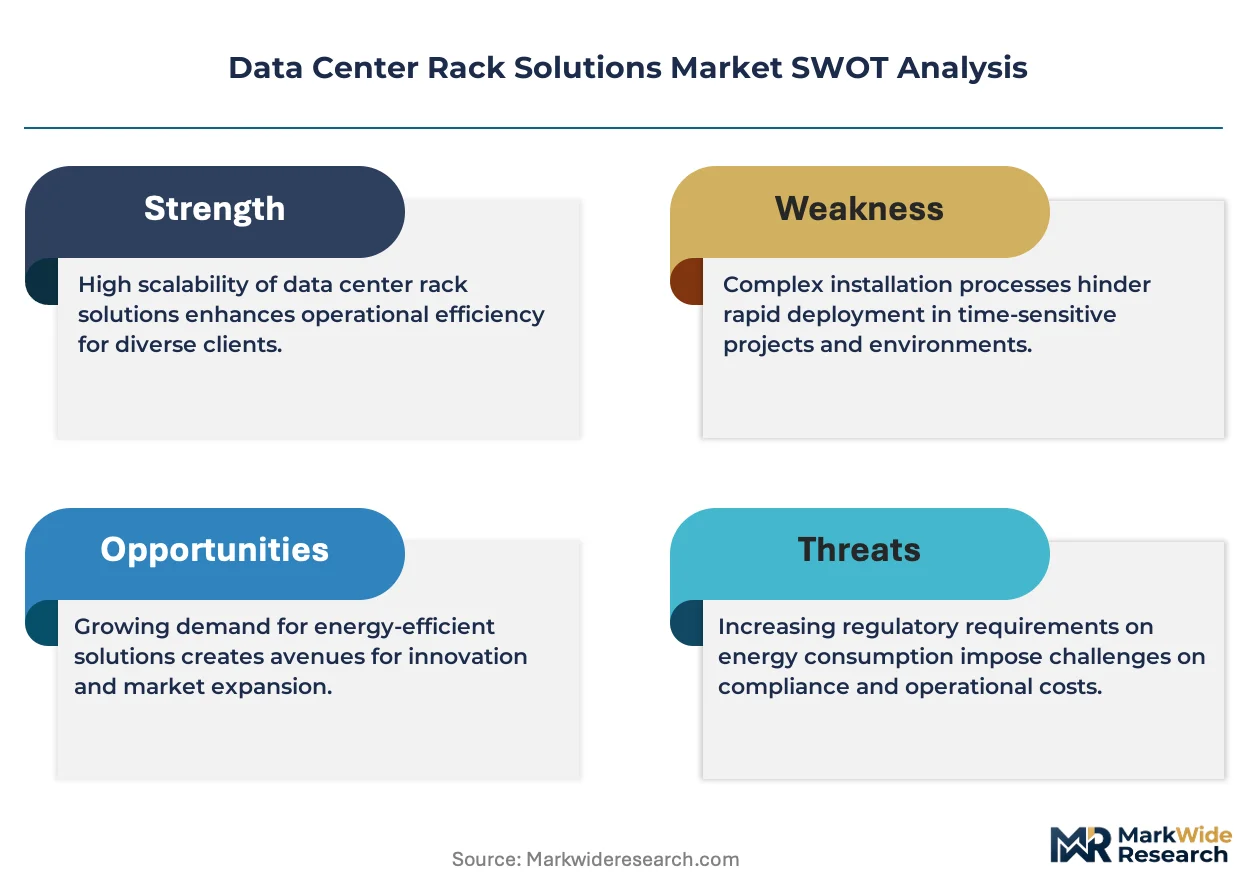
GPU-intensive AI training clusters are forcing structural reinforcement of rack systems as per-rack power densities exceed 30 kilowatts, compressing deployment timelines and demanding integrated thermal management from enclosure suppliers.
Growth Catalysts
- EU Energy Efficiency Directive:Tightening power usage requirements for data center infrastructure are accelerating replacement cycles across European hyperscale facilities.
- Hyperscale campus expansion:Cloud providers are aggressively expanding physical footprints in Northern Virginia and Dallas-Fort Worth, concentrating rack demand in these clusters.
- Aluminum adoption:Edge deployments are driving rising aluminum content for weight reduction, simplifying transport and enabling rapid installation in distributed locations.
Market Restraints
- Steel price volatility:Cold-rolled steel input costs create margin pressure for manufacturers fabricating high-capacity rack systems.
- Chinese certification burden:GB standards for electronic equipment mechanical structures impose local compliance costs on imported rack systems entering China.
- Thermal design ceiling:Passive cooling architectures face hard limits when densities exceed 50 kilowatts per rack without liquid cooling integration.
Strategic Opportunities
- Modular region-configurable designs:Product platforms that adapt to fragmented jurisdictional efficiency standards without sacrificing manufacturing scale.
- Integrated power-cooling bundles:Long-term supply contracts anchored by combined enclosure and thermal management offerings for cloud providers.
- Edge computing infrastructure:Lightweight aluminum rack systems for rapid-deployment edge nodes in telecommunications and retail verticals.
Industry Challenges
- Field assembly skill gaps:Modular architectures requiring reduced installation time depend on scarce technicians trained in precision cable management and thermal containment sealing.
- Multi-vendor integration complexity:Hyperscale operators shifting from single-vendor frameworks face coordination costs across power, cooling, and enclosure suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Rack Solutions Market |
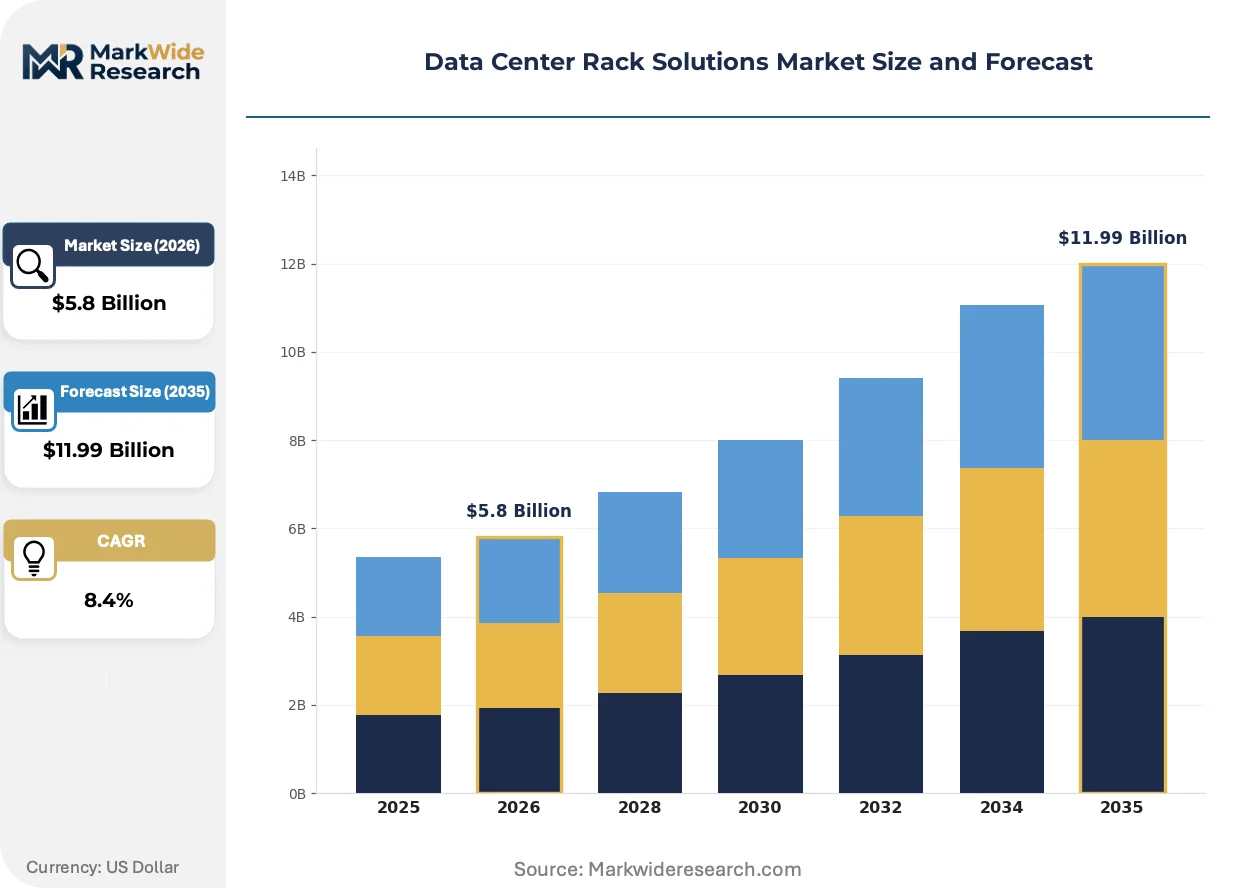
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Specialty Rack Material: Steel, Aluminum, Plastic, Composite Capacity: Standard Capacity, High Capacity, Custom Capacity, Ultra High Capacity End User: Telecom, IT Services, Cloud Providers, Enterprises |
| Companies Covered | Schneider Electric, Hewlett Packard Enterprise, Rittal, Eaton, Vertiv, Dell Technologies, Fujitsu, Legrand, Chatsworth Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Rack Solutions Market Strategic Shifts
Intelligent rack systems are converging power distribution, environmental monitoring, and physical access control into unified platforms that reduce operational overhead for facility operators.
AI-driven thermal management is automating real-time airflow adjustments based on server workload patterns. Hyperscale operators in Northern Virginia are deploying these systems at scale to optimize cooling energy consumption. The technology is automating manual tuning processes that previously required continuous engineering intervention.
EPA ENERGY STAR specifications for data center equipment are reshaping federal and enterprise procurement criteria in the United States. Compliance documentation now requires verified thermal performance metrics that favor enclosed rack systems with integrated containment. Financial services and government facilities are prioritizing certified configurations despite premium positioning.
Hyperscale buyers are consolidating vendor relationships around integrated platform providers rather than sourcing racks, power, and cooling separately. Wholesale colocation builders are driving this consolidation to compress project timelines and reduce interface risk. The United States market exhibits this pattern most acutely, with multi-year framework agreements replacing transactional procurement.
Data Center Rack Solutions Market Segmentation
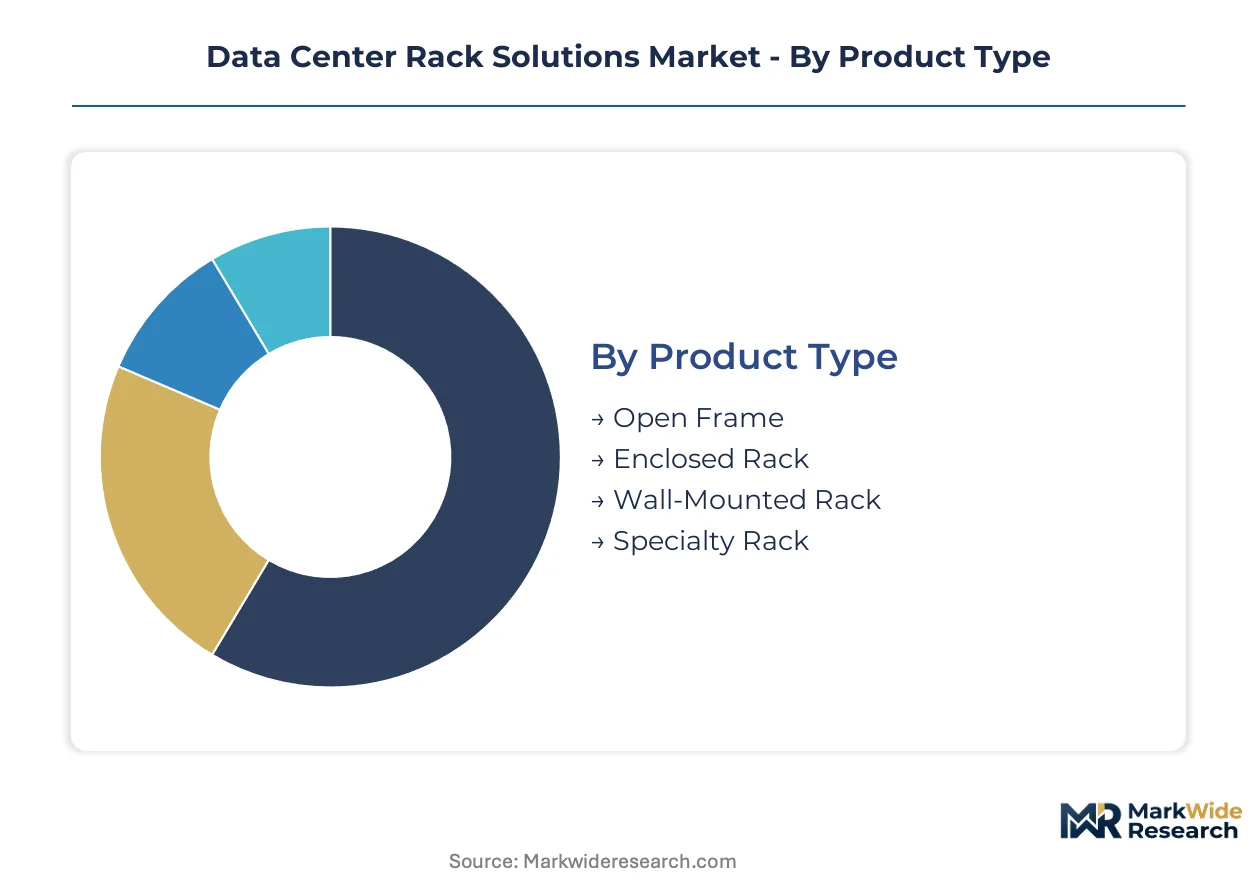
Segmentation in the Data Center Rack Solutions Market reveals how rack specifications align with distinct deployment physics and procurement economics. Rack architecture, material composition, load capacity, and buyer type each create separate competitive arenas with divergent margin profiles and technical requirements.
Product Type:
Enclosure architecture determines thermal containment capability, physical security posture, and field assembly complexity across deployment scenarios.
- Open Frame:Structural mounting frameworks without side panels or doors, fabricated from cold-rolled steel with static load ratings between 1,500 and 2,500 pounds. Demand concentrates in hyperscale cloud campuses in Northern Virginia where unrestricted airflow and rapid equipment access take priority over physical security.
- Enclosed Rack:Fully enclosed cabinet systems with integrated side panels, front and rear doors, and optional top-mounted cable management. Financial services and government facilities in Dallas-Fort Worth drive procurement due to integrated airflow containment and physical access control requirements.
- Wall-Mounted Rack:Compact enclosure systems designed for vertical wall attachment, typically supporting 150 to 400 pounds of equipment load. Telecom edge nodes and retail IT closets deploy these for space-constrained distributed infrastructure.
- Specialty Rack:Custom-configured frameworks engineered for non-standard equipment form factors or extreme environmental conditions. Military and industrial verticals specify these for shock-resistant or EMI-shielded deployments.
Mature deployment sits with Open Frame. Newer deployment is concentrated in Enclosed Rack.
Material:
Substrate selection trades structural rigidity against transport economics and corrosion resistance in target operating environments.
- Steel:Cold-rolled carbon steel remains the dominant fabrication platform for high-capacity rack systems, delivering static load ratings exceeding 3,000 pounds with cost-efficient raw material sourcing. Hyperscale builders in Northern Virginia specify steel for core data hall infrastructure where weight is not a transport constraint.
- Aluminum:Lightweight alloy systems reduce rack weight by 40 to 60 percent compared to steel equivalents, enabling rapid deployment in distributed edge locations. Telecom operators across Dallas-Fort Worth metro cell sites favor aluminum for helicopter-lift and rooftop installations where crane access is limited.
- Plastic:Polymer-based enclosures for low-load networking equipment in clean office environments. Enterprise branch offices deploy these for aesthetic integration with commercial interiors.
- Composite:Fiber-reinforced hybrid materials combining structural properties with electromagnetic interference shielding. Aerospace and defense contractors specify these for mobile command center applications.
Volume concentration favors Steel. Margin expansion is climbing the fastest in Aluminum.
Capacity:
Load rating specifications track directly with power density trajectories and the structural reinforcement required for GPU-intensive compute clusters.
- Standard Capacity:Racks rated for 1,500 to 2,000 pounds static load, accommodating traditional server densities below 10 kilowatts per rack. Legacy enterprise data centers continue replacement cycles with these specifications.
- High Capacity:Reinforced frameworks supporting 2,000 to 2,500 pounds with enhanced vertical rail strength and base anchoring systems. Wholesale colocation builders deploy these for multi-tenant flexibility across varying tenant densities.
- Ultra High Capacity:Structurally augmented systems engineered for 3,000+ pound loads and 30+ kilowatt power densities from AI training clusters. Cloud providers in Northern Virginia are standardizing on these for GPU server deployments.
- Custom Capacity:Application-specific engineering for non-standard equipment weights or seismic zone requirements. Research institutions and government laboratories commission these for unique supercomputing configurations.
Procurement volume centers on Standard Capacity. Specification escalation is most pronounced in Ultra High Capacity.
End User:
Buyer category determines procurement scale, technical specification authority, and vendor relationship structure from transactional to framework-based.
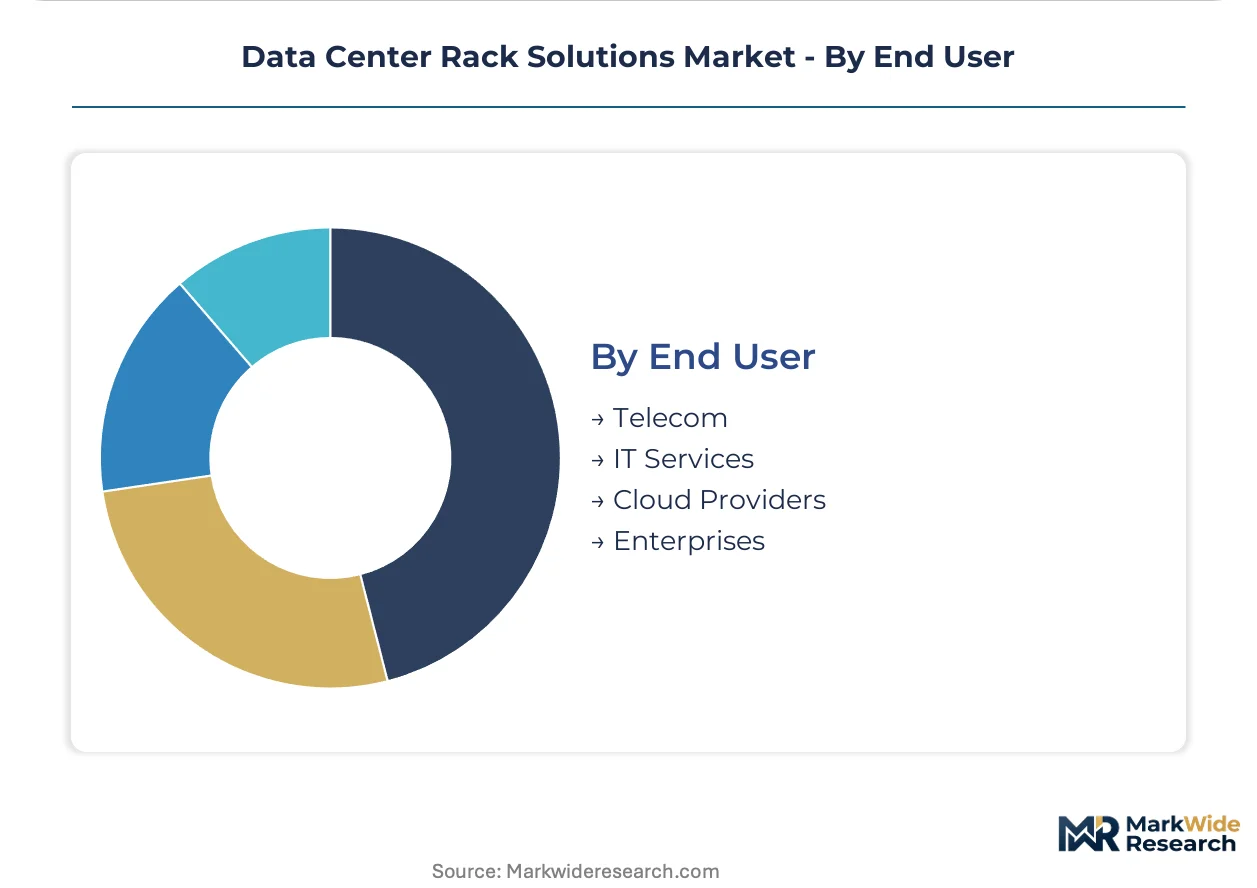
- Cloud Providers:Hyperscale operators procuring racks through multi-year framework agreements with integrated power and cooling bundling. These buyers in Northern Virginia and Dallas-Fort Worth drive consolidation around platform providers capable of single-source accountability.
- IT Services:Managed service providers and systems integrators deploying racks across distributed client footprints. These buyers prioritize modular architectures that reduce field assembly time and technician skill requirements.
- Telecom:Network operators deploying edge computing infrastructure across cell sites and central offices. Weight reduction and rapid installation capabilities dominate procurement criteria for rooftop and roadside cabinet deployments.
- Enterprises:Corporate IT departments with mixed on-premises and colocation requirements. These buyers respond to EPA ENERGY STAR procurement criteria for federal compliance and sustainability reporting.
Framework contracting is established with Cloud Providers. Procurement modernization is advancing most quickly in IT Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-rolled steel mills in the Great Lakes region supply the structural feedstock for North American rack fabrication. This material anchor shapes procurement patterns across three distinct national markets with divergent regulatory and deployment characteristics.
United States
Hyperscale cloud campuses in Northern Virginia and Dallas-Fort Worth drive concentrated rack demand from cloud providers and wholesale colocation builders. EPA ENERGY STAR specifications for data center equipment reshape federal and enterprise procurement criteria, favoring enclosed systems with verified thermal performance. Northern Virginia's Data Center Alley hosts the densest concentration of ultra-high-capacity rack deployments for GPU-intensive AI clusters.
Germany
Industrial automation and automotive data infrastructure sustain steady replacement cycles for high-capacity enclosure systems. The EU F-Gas Regulation and Ecodesign requirements impose strict thermal efficiency mandates on European deployments, accelerating upgrade timelines. Frankfurt's financial services hub generates premium demand for physically secure enclosed racks with integrated airflow containment.
China
Domestic cloud expansion and state-backed AI research facilities propel specification escalation toward ultra-high-capacity frameworks. GB standards for electronic equipment mechanical structures impose local certification burdens on imported rack systems, favoring domestic fabrication. Beijing-Tianjin-Hebei corridor clusters concentrate hyperscale construction with state-directed procurement frameworks.
Japan
Edge computing rollout across dense urban metros and disaster-resilient distributed infrastructure drives aluminum rack adoption for weight-constrained installations. METI efficiency guidelines shape procurement criteria for telecommunications and enterprise data infrastructure. Tokyo-Osaka corridor facilities prioritize modular architectures that compress field assembly timelines in space-constrained environments.
United Kingdom
Financial services data centers in London and growing colocation capacity in Slough and Manchester sustain demand for thermally optimized enclosed systems. The UK implementation of EU-derived efficiency standards maintains regulatory pressure on thermal containment performance. London's hyperscale entry points concentrate multi-tenant rack specifications requiring flexible density accommodation.
Data Center Rack Solutions Market Competitive Environment
Multi-year framework contracting dominates the current landscape as hyperscale operators consolidate vendor relationships around integrated platform providers. The vendor base organizes into three tiers: diversified electrical equipment conglomerates with captive rack portfolios, pure-play enclosure specialists with deep thermal engineering expertise, and IT infrastructure OEMs bundling racks with server and storage hardware. Three strategic archetypes define competitive positioning: integrated power-cooling-enclosure bundlers, modular architecture specialists, and edge-optimized lightweight fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers align fabrication capacity with hyperscale construction timelines.
Among diversified electrical equipment conglomerates, Schneider Electric, Eaton, and Legrand occupy positions anchored by integrated power distribution portfolios that enable bundled supply contracting with cloud providers. These companies exemplify the platform-provider archetype that wholesale colocation builders increasingly favor to compress project timelines and reduce interface risk across power, cooling, and enclosure subsystems.
| Leading Market Players |
|---|
| Schneider Electric |
| Hewlett Packard Enterprise |
| Rittal |
| Eaton |
| Vertiv |
| Dell Technologies |
| Fujitsu |
| Legrand |
| Chatsworth Products |
| Others |
Value Chain & Pricing Dynamics
Cold-rolled steel futures pricing on the Chicago Mercantile Exchange cascades through fabrication tiers into three distinct procurement brackets: framework-contract hyperscale bundles, project-based colocation specifications, and transactional enterprise replacement cycles. The commodity's volatility compresses margins for domestic manufacturers while rewarding integrated suppliers with captive steel sourcing from Great Lakes mills.
Pricing Analysis
Warranty and field-service bundling separate premium enclosure providers from commodity fabricators, with integrated thermal containment validation and multi-year structural guarantees commanding substantial premiums over bare-metal transactional sales. Price differentiation rests on UL 2416 certification tier and EPA ENERGY STAR thermal verification status, with certified configurations favored by federal and financial services buyers despite higher acquisition costs. Cost compression in standard-capacity steel racks is intensifying because Chinese import competition and raw material volatility squeeze mid-tier fabricators. Cloud providers exhibit lowest price sensitivity due to lifecycle cost framing, while enterprise IT departments face acute budget constraints driving aggressive vendor consolidation.
Supply Chain Analysis
Precision welding technician availability in Ohio, Pennsylvania, and Michigan constrains domestic fabrication capacity expansion despite robust order backlogs from hyperscale construction timelines. Manufacturing concentrates in the United States, China, and Germany, with Chinese producers dominating aluminum extrusion for edge-optimized lightweight systems. Cold-rolled steel coil, aluminum 6061-T6 alloy, and precision hardware components constitute critical input dependencies. Tariff exposure on Chinese aluminum and steel derivatives threatens margin stability for manufacturers without alternative sourcing arrangements. Distribution runs through direct OEM relationships with cloud providers, regional electrical distributors serving enterprise accounts, and systems integrators for edge deployment projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Energy Efficiency Directive's tightening power usage requirements erect substantial compliance barriers that favor established platform providers with integrated thermal engineering capabilities over pure-play metal fabricators lacking certification infrastructure.
For Market Incumbents: Hedge against margin erosion in standard-capacity steel segments by accelerating backward integration into precision thermal containment manufacturing and securing long-term offtake agreements with cold-rolled steel mills in the Great Lakes region. The threat of modular architecture specialists displacing traditional enclosure suppliers demands immediate capability investments in liquid-cooling-ready rack platforms.
For New Entrants and Emerging Players: Wholesale colocation builders in secondary United States markets represent the most penetrable channel partner type for establishing initial revenue traction and reference accounts. Edge computing infrastructure for telecom operators offers white-space expansion potential, with aluminum lightweight systems for rooftop and cell site deployments underserved by incumbent steel-focused portfolios. A go-to-market strategy emphasizing rapid-deployment field services and technician training programs addresses the critical skill gap constraining competitor installation timelines.
For Investors and Strategic Acquirers: Distressed-cycle entries favor modular architecture specialists with established hyperscale reference accounts in Northern Virginia and Dallas-Fort Worth during periods of capital market tightening. Long-term viability over the projection horizon depends on thermal management integration capabilities rather than commodity enclosure fabrication. The inflection signal to monitor is liquid cooling attachment rates in GPU-intensive AI training clusters, which will determine which platform providers capture specification escalation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Power-Cooling Bundle Development | Schneider Electric and Vertiv anchor long-term cloud provider contracts through combined enclosure and thermal management offerings. |
| Aluminum Fabrication Capacity Expansion | Edge deployment growth in telecom verticals demands lightweight alloy systems for weight-constrained rooftop installations. |
| Regional Certification Infrastructure Investment | EU F-Gas Regulation and EPA ENERGY STAR compliance requirements favor manufacturers with localized testing capabilities. |
| Modular Architecture Platform Launch | Wholesale colocation builders compress project timelines through reduced field assembly requirements and standardized configurations. |
| Strategic Partnership with Hyperscale Cloud Providers | Multi-year framework agreements in Northern Virginia and Dallas-Fort Worth consolidate vendor relationships around single-source accountability. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with data center facility engineers, procurement officers at cloud providers, thermal management specialists, electrical distribution channel managers, and enclosure manufacturing executives. SEC 10-K disclosures, EPA ENERGY STAR certification databases, EU Ecodesign directive implementation reports, and steel industry association production statistics provided demand-side and supply-side validation. Bottom-up rack shipment estimates by capacity tier and material composition were cross-referenced against top-down hyperscale capex allocation patterns.
Granularity-level modeling operated at product type, material substrate, load capacity tier, and end-user category dimensions, with geographic demand disaggregated to metropolitan cluster level for Northern Virginia, Dallas-Fort Worth, Frankfurt, and Beijing-Tianjin-Hebei corridor. CAGRs were derived from regression analysis against hyperscale construction permit data and GPU server deployment trajectories. Forecast inputs included AI training cluster power density escalation curves and edge computing node rollout schedules from telecommunications operators.
Several conditions sit outside the modeled scope, including potential revisions to EPA ENERGY STAR specifications, abrupt steel tariff regime changes, and breakthrough liquid cooling technologies that could obsolete passive thermal containment architectures. Forecasts reflect assumptions about hyperscale construction continuity and regulatory stability across the analysis window. Material deviation in named triggers—particularly EU directive enforcement intensity or Chinese GB standards reciprocity—warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Asia-Pacific Data Center Infrastructure Management Market
Data Center Infrastructure
Austria Data Center Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
New Jersey Data Center Market