
 Poland Data Center Market | 2026-2036
Poland Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Data Center Market Insights
Asset-light leasing and sale-and-leaseback structures is reshaping competitive entry in the Poland data center sector, allowing operators to scale without full capital ownership. Vantage Data Centers leverages its global development playbook to secure power and land positions around Warsaw. Beyond.pl anchors its position through specialized high-security facilities serving defense and public sector clients. Orange Polska competes by integrating its national fiber backbone directly into data center connectivity offerings.
Data centers are purpose-built facilities housing servers, storage systems, and network equipment with controlled power density of 5-30 kW per rack and precision cooling maintaining 18-27°C ambient temperature, serving as the physical infrastructure for digital commerce, cloud computing, and enterprise IT operations. Colocation remains the dominant product type in Poland, absorbing demand from mid-market enterprises seeking outsourced facility management without hyperscale commitments. Edge deployments represent the fastest-growing product segment, driven by latency-sensitive applications in manufacturing and autonomous systems across Silesian industrial zones.
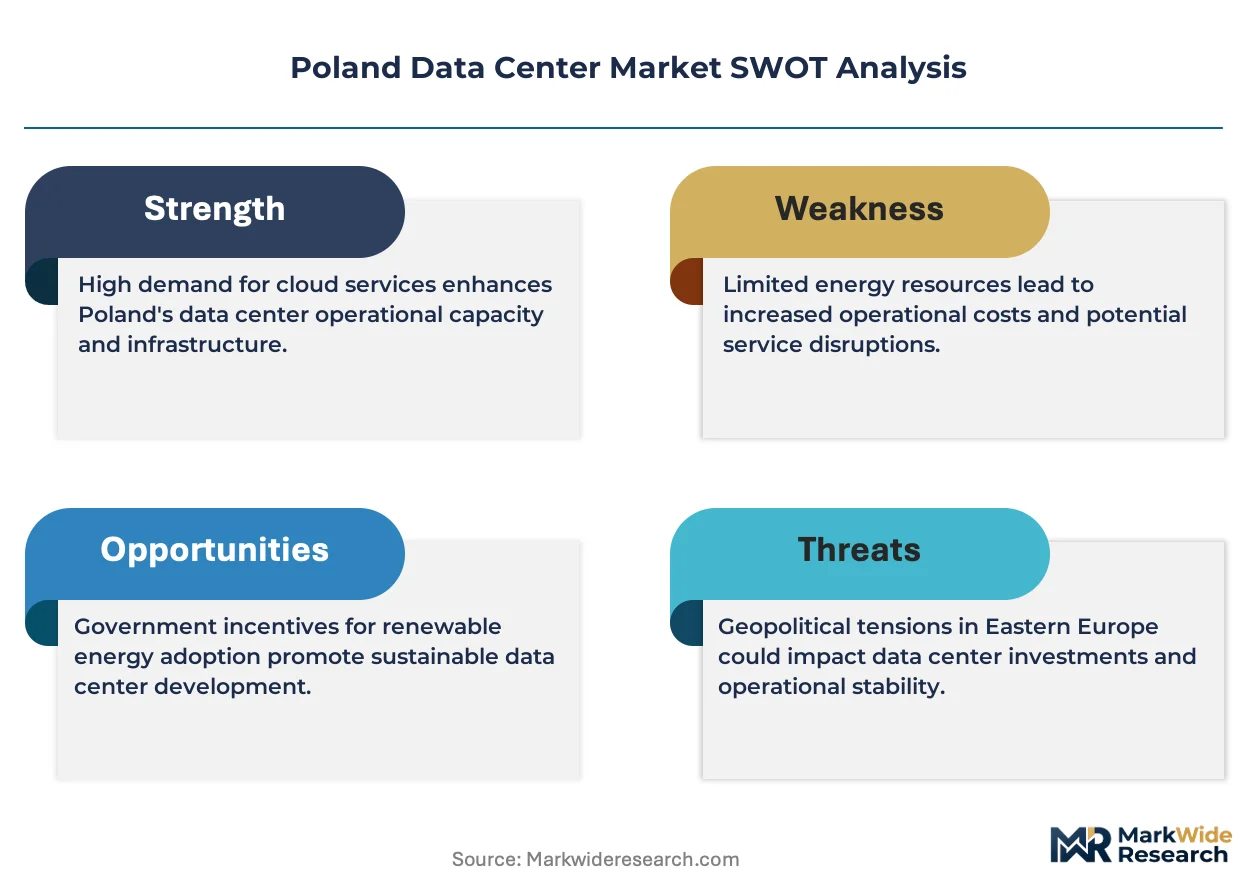
Polish Office of Electronic Communications (UKE) licensing requirements shape market access for telecommunications-integrated facilities, while EU Energy Efficiency Directive mandates drive PUE optimization investments. The Polish Energy Regulatory Office oversees power connection agreements that often determine project viability and timeline. Stakeholders must monitor grid interconnection queue positions and renewable energy certificate availability as primary constraints on expansion planning.
Market Dynamics
Poland's data center sector faces a structural power constraint as grid interconnection queues stretch 24-36 months, forcing operators to secure substation access before land acquisition and compressing viable development windows around Warsaw's fiber-rich corridors.
Growth Catalysts
- EU Green Deal compliance:Mandatory PUE optimization under the EU Energy Efficiency Directive accelerates facility modernization investments across Polish metropolitan zones.
- Financial services expansion:Warsaw's banking and fintech clusters drive demand for Tier III+ colocation with sub-10ms latency to Frankfurt.
- National Cloud Strategy:Polish government mandates for sovereign data hosting create dedicated procurement streams for defense and public sector facilities.
Market Restraints
- Grid interconnection bottlenecks:Polish Energy Regulatory Office queue positions determine project viability, with 110kV+ connections requiring 30-month lead times.
- Labor scarcity in critical systems:Certified data center engineers command 40% wage premiums versus general electrical trades, constraining operational scaling.
- Land concentration around Warsaw:Suitable brownfield sites within 50km of the city center trade at 3x peripheral valuations, elevating entry capital requirements.
Strategic Opportunities
- Krakow secondary cluster emergence:Lower land costs and Jagiellonian University talent pipelines attract edge computing deployments for manufacturing automation.
- Liquid cooling technology convergence:Direct-to-chip and immersion systems enable 50kW+ rack densities for AI training workloads.
- Renewable energy certificate arbitrage:Polish wind and solar PPA availability supports carbon-neutral facility positioning for EU CSRD-reporting enterprises.
Industry Challenges
- UKE licensing complexity:Telecommunications-integrated facilities face 12-18 month approval cycles for cross-border fiber connectivity.
- Legacy enterprise migration friction:Mainframe-dependent Polish manufacturers resist workload portability to colocation environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Data Center Market |
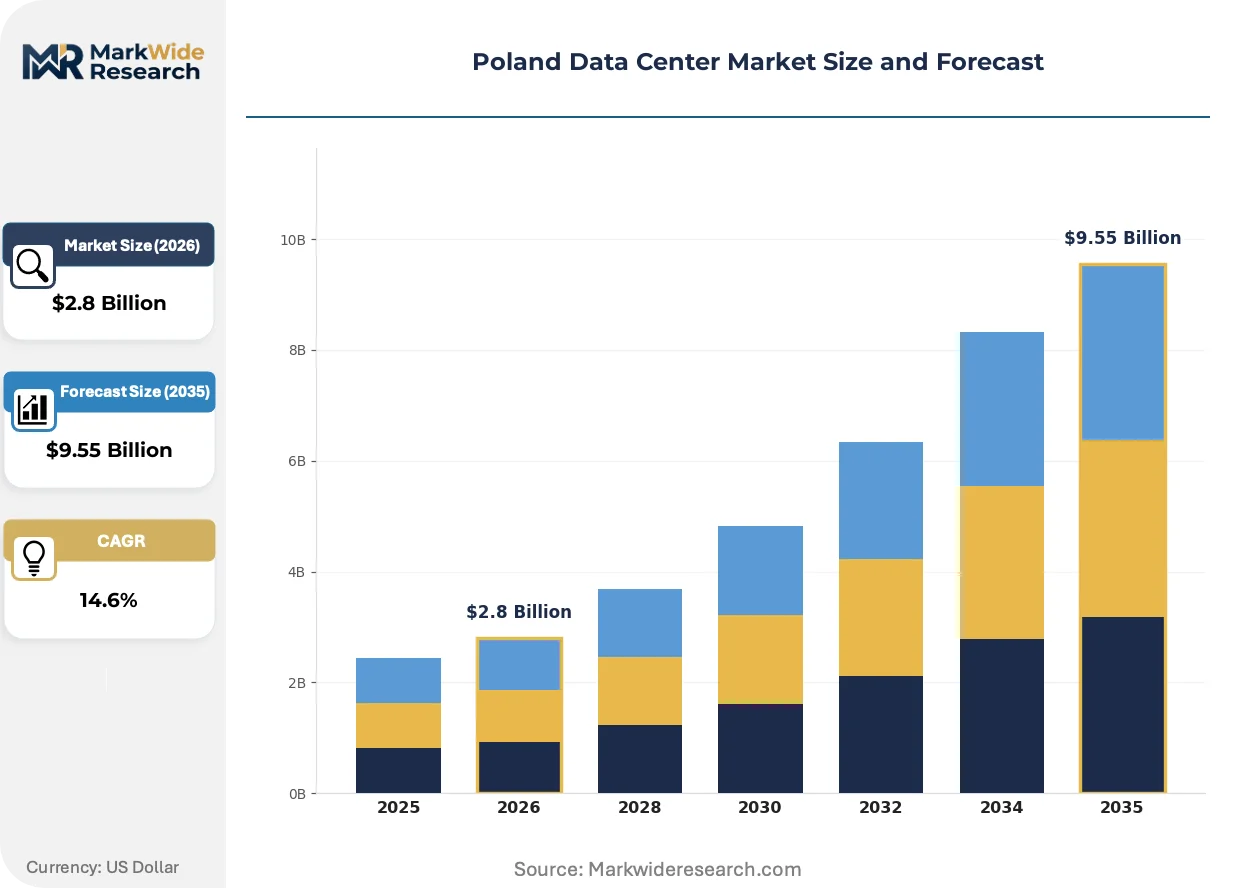
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Hyperscale, Edge, Managed Hosting Service Type: Infrastructure as a Service, Platform as a Service, Backup as a Service, Disaster Recovery as a Service End User: Telecommunication, BFSI, Healthcare, E-commerce Deployment Model: On-Premise, Hybrid, Cloud, Multi-Cloud |
| Companies Covered | Atman, Beyond.pl, Equinix, Orange Polska, T-Mobile Polska, Data4 Group, Vantage Data Centers, Netia, 3S Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Data Center Market Trends and Innovations
Facility architecture and operational models across Poland are pivoting toward density-optimized designs as AI compute requirements reshape power and cooling specifications. Three developments dominate this transition.
Immersion cooling is migrating from niche cryptocurrency mining deployments to mainstream enterprise adoption. Polish operators serving financial services clients are piloting single-phase dielectric fluid systems for 40kW GPU racks. This technology is migrating from proof-of-concept status to standard configuration in Warsaw's newest facilities, compressing mechanical infrastructure footprints by 60%.
EU CSRD disclosure mandates now require granular Scope 3 emissions reporting from data center operators. Polish facilities must track embodied carbon in concrete and steel construction plus upstream power generation. Colocation providers with renewable energy certificates and circular material programs capture preference from ESG-mandated enterprise procurement teams.
Buyers are consolidating vendor relationships around integrated platform offerings rather than discrete space-power-cooling contracts. Mid-market Polish enterprises favor operators bundling managed security, cloud interconnect, and remote hands services. This consolidation is most visible in Silesian industrial zones where manufacturing firms seek single-source accountability for OT-IT convergence workloads.
Poland Data Center Market Segmentation
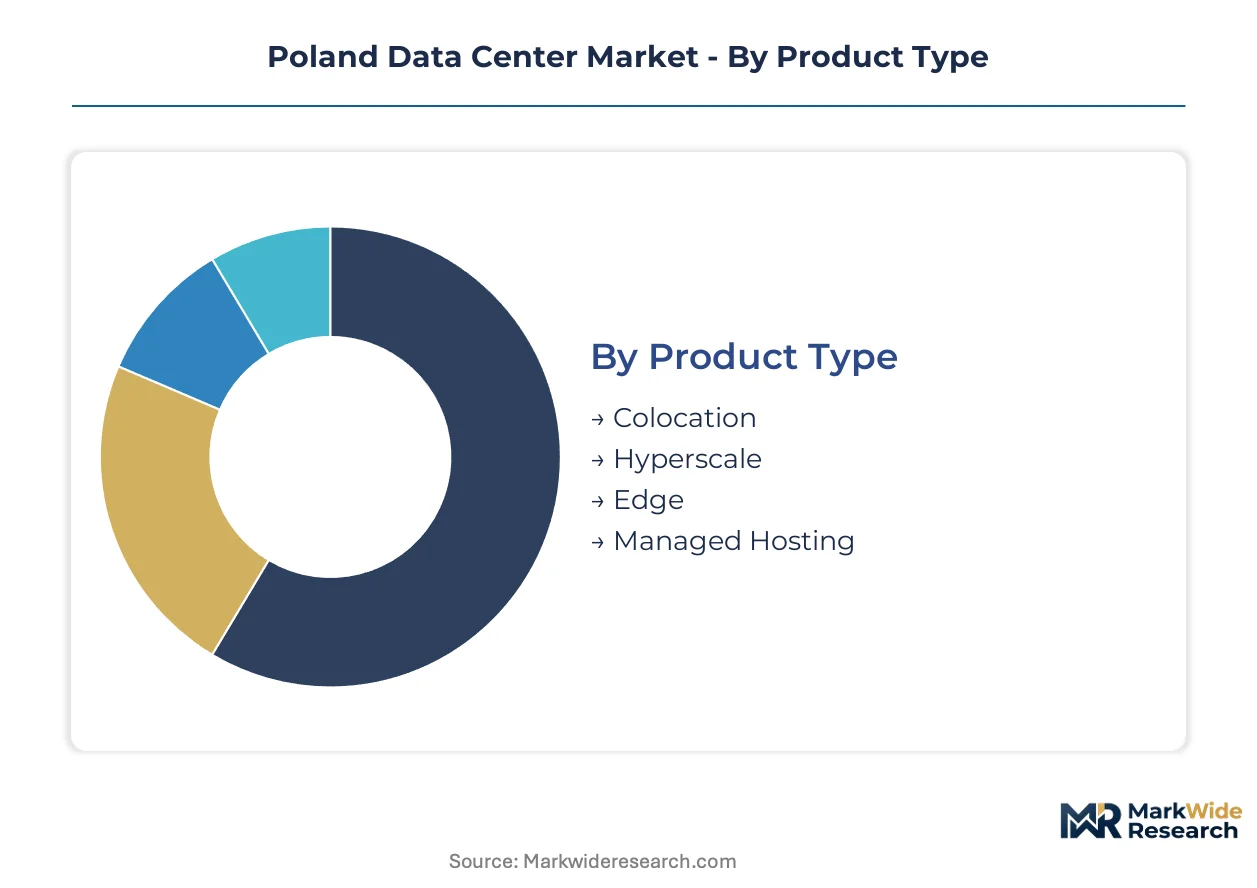
Poland's data center market exhibits distinct demand profiles across infrastructure formats and service layers, with procurement patterns diverging between Warsaw's financial district concentration and Krakow's emerging industrial edge. Understanding these segment boundaries clarifies where capital deployment meets actual consumption.
Product Type:
Mature hyperscale facilities anchor the Warsaw corridor while edge architectures emerge fastest in Silesian manufacturing zones.
- Colocation:Third-party facilities providing shared space, power, and cooling with standardized SLAs. Warsaw banking clusters and Krakow fintech operations absorb Tier III+ capacity for sub-10ms Frankfurt latency requirements. The segment commands stable procurement from mid-market enterprises avoiding hyperscale capital commitments.
- Hyperscale:Purpose-built campuses exceeding 20MW with dedicated substations and direct fiber trunks. Cloud service providers dominate absorption around Warsaw's fiber-rich corridors where grid interconnection queues determine project sequencing. Polish Energy Regulatory Office approvals for 110kV+ connections stretch 30 months.
- Edge:Distributed sub-5MW facilities positioned for latency-sensitive workloads. Silesian automotive and logistics automation drives deployment near factory floors. Jagiellonian University talent pipelines support Krakow secondary cluster formation.
- Managed Hosting:Single-tenant dedicated infrastructure with operational outsourcing. Defense and public sector clients favor this format under National Cloud Strategy sovereign hosting mandates.
Colocation retains volume leadership; edge computing holds the steepest expansion curve.
Service Type:
Platform layers command premium pricing against commodity infrastructure, with backup and recovery services accelerating under EU operational resilience directives.
- Infrastructure as a Service:Virtualized compute, storage, and network resources delivered on demand. Polish manufacturers migrating mainframe workloads favor this entry point for OT-IT convergence without facility capital.
- Platform as a Service:Development environments with managed middleware and database services. Warsaw fintech clusters consume PaaS for rapid application deployment with embedded compliance tooling.
- Backup as a Service:Automated data protection with geographically distributed replication. EU CSRD disclosure mandates drive enterprise procurement for granular recovery point objectives.
- Disaster Recovery as a Service:Standby infrastructure with defined recovery time objectives. Financial institutions under ECB operational resilience requirements anchor demand for synchronous replication between Warsaw and secondary sites.
Infrastructure as a Service captures the widest enterprise penetration; disaster recovery as a service posts the most rapid regulatory-driven adoption.
End User:
Financial services concentration in Warsaw creates tiered demand profiles distinct from healthcare's compliance-driven procurement.
- Telecommunication:Carrier-neutral interconnection and content delivery infrastructure. Orange Polska's national fiber backbone integration shapes competitive positioning for network-dense facilities.
- BFSI:Tier III+ colocation with sub-10ms latency to Frankfurt trading venues. Warsaw's banking cluster drives the highest power density requirements per rack among Polish verticals.
- Healthcare:HIPAA-aligned data residency for patient records and imaging archives. Public hospital digitization programs create procurement streams for managed hosting with sovereign data guarantees.
- E-commerce:Scalable cloud-adjacent capacity for seasonal demand spikes. Last-mile delivery optimization in Warsaw and Krakow metropolitan zones drives edge deployment for inventory management systems.
BFSI dominates premium capacity absorption; e-commerce demonstrates the most elastic demand scaling.
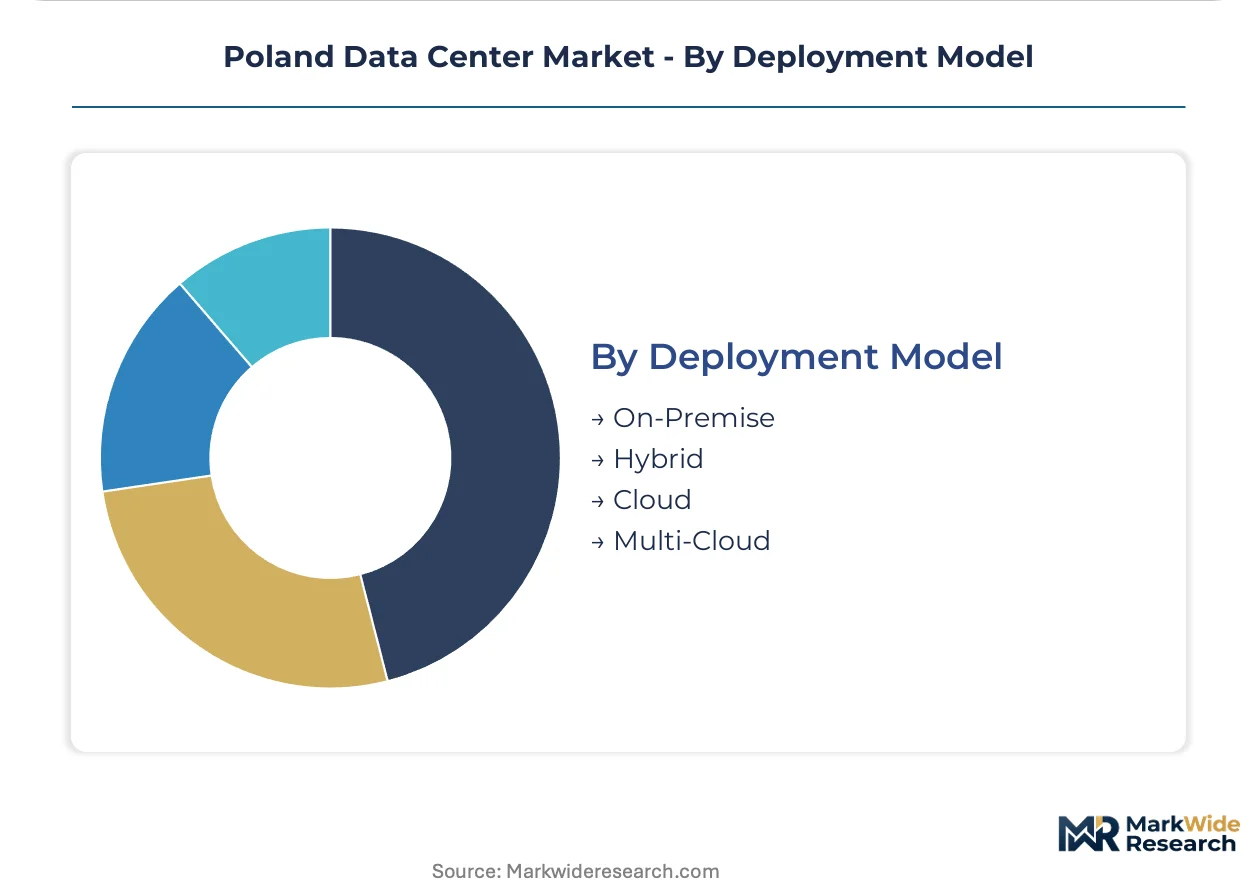
Deployment Model:
Hybrid architectures resolve sovereignty requirements against cloud agility, with multi-cloud complexity emerging as a distinct operational challenge.
- On-Premise:Enterprise-owned facilities with captive infrastructure. Legacy Polish manufacturers with mainframe dependencies retain this model despite colocation migration pressure.
- Hybrid:Integrated on-premise and cloud resources with unified orchestration. National Cloud Strategy mandates for sovereign data hosting drive this architecture among defense contractors.
- Cloud:Fully outsourced public cloud consumption. Mid-market Polish enterprises favor this for workload portability without facility management overhead.
- Multi-Cloud:Distributed workloads across two or more public cloud providers. Large enterprises with EU CSRD reporting requirements use this to optimize carbon intensity by geography.
Hybrid deployments retain strategic priority for regulated industries; multi-cloud configurations expand most quickly among ESG-mandated enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland commands a 40% price premium over Czech Republic for prime data center land within 30km of Warsaw, reflecting fiber density asymmetries and grid interconnection queue advantages that concentrate developer capital in the Polish corridor.
Warsaw Metropolitan Corridor
Warsaw's banking and fintech clusters absorb Tier III+ colocation capacity for sub-10ms latency to Frankfurt trading venues. The Polish Office of Electronic Communications enforces telecommunications licensing for cross-border fiber facilities. Ursus and Pruszków subzones host hyperscale campuses where Vantage Data Centers and Equinix compete for 110kV substation access.
Krakow Secondary Cluster
Jagiellonian University computer science pipelines feed edge computing deployments for Silesian manufacturing automation. EU Green Deal PUE mandates accelerate facility modernization investments across Lesser Poland Voivodeship. Krakow Technology Park anchors secondary market formation with 30% lower land costs than Warsaw periphery.
Silesian Industrial Zone
Automotive and logistics automation drive latency-sensitive edge demand near factory floors in Katowice and Gliwice. Polish Energy Regulatory Office queue positions for 110kV connections stretch 24-30 months, constraining expansion timelines. Beyond.pl operates specialized high-security facilities serving defense contractors under National Cloud Strategy mandates.
Tri-City Northern Hub
Gdańsk-Gdynia-Sopot corridor attracts submarine cable landing stations and content delivery infrastructure. Orange Polska integrates its national fiber backbone into carrier-neutral interconnection facilities. Pomeranian Special Economic Zone incentives support disaster recovery site development for Warsaw financial institutions.
Wrocław Western Gateway
German cross-border enterprise demand flows through Wrocław for EU CSRD-compliant sovereign hosting. Lower Silesian Voivodeship offers grid interconnection advantages versus congested Warsaw queues. Netia and T-Mobile Polska compete for telecommunications-integrated facilities serving automotive supply chain digitization.
Poland Data Center Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in land acquisition and power positioning. The Poland data center market structures around three archetypes: global hyperscale developers securing substation access, telecommunications carriers leveraging fiber backbone integration, and specialized operators serving sovereign security requirements. Competitive moves concentrate on sale-and-leaseback structures for capital efficiency and renewable energy certificate arbitrage for ESG positioning.
Among global developers, Vantage Data Centers and Equinix exemplify the hyperscale archetype through Warsaw corridor land banking. Beyond.pl occupies a distinct position serving defense and public sector clients with National Cloud Strategy compliance. Orange Polska anchors the telecommunications-integrated tier, representing how national fiber backbone ownership shapes facility connectivity offerings.
| Leading Market Players |
|---|
| Atman |
| Beyond.pl |
| Equinix |
| Orange Polska |
| T-Mobile Polska |
| Data4 Group |
| Vantage Data Centers |
| Netia |
| 3S Group |
| Others |
Pricing and Supply Chain Analysis
Chinese electrical equipment and German precision cooling systems concentrate upstream supply, anchoring margin capture in Polish facility operations and managed services rather than commodity infrastructure deployment.
Pricing Analysis
The customization-premium spread between configured-to-order hyperscale builds and standardized colocation racks runs wide. Contract structures favor long-term offtake agreements with escalators tied to power costs and PUE performance. Price differentiation rests on Tier III+ certification status and fiber cross-connect density. Cost compression in standard colocation intensifies as Warsaw land scarcity elevates entry capital, while financial services buyers show lowest price sensitivity due to ECB operational resilience mandates.
Supply Chain Analysis
Tariff exposure between China and the EU dominates supply chain risk for electrical switchgear and precision cooling components. Manufacturing concentrates in China, Germany, and the USA for critical power distribution units and chillers. Raw material dependencies span copper for busbars, rare earth elements for high-efficiency transformers, and engineered fluids for immersion cooling systems. Single-source vulnerability persists in 110kV+ substation equipment where lead suppliers control Polish Energy Regulatory Office certification pathways. Distribution runs through Warsaw-based systems integrators with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security and remote hands services expand faster than raw colocation space, creating a service-attach opportunity where recurring revenue multiples exceed infrastructure yields.
For Market Incumbents: Insulate core Warsaw corridor positions through backward integration into renewable energy certificate portfolios and captive substation development. Secure Polish Energy Regulatory Office queue priority through early land banking in Ursus and Pruszków subzones. Counter emerging edge computing entrants by bundling cloud interconnect with sovereign-compliant managed hosting for defense contractors. For New Entrants and Emerging Players: Build out Krakow secondary cluster presence where Jagiellonian University talent pipelines lower operational wage premiums versus Warsaw. Target Silesian manufacturing automation with sub-5MW edge facilities positioned for OT-IT convergence workloads. Penetrate via platform-as-a-service bundling rather than commodity space-power-cooling contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hyperscale developers holding mature Warsaw land positions with expiring hold periods. Long-term viability hinges on renewable energy certificate arbitrage capability and UKE telecommunications licensing moats. Watch Polish Energy Regulatory Office queue clearance velocity as the inflection signal for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Substation Access Securement | Polish Energy Regulatory Office queue positions determine project viability and capital deployment sequencing. |
| Liquid Cooling Technology Adoption | Direct-to-chip systems enable 50kW+ rack densities for AI training workloads in Warsaw facilities. |
| Renewable Energy Certificate Arbitrage | Polish wind and solar PPA availability supports carbon-neutral positioning for EU CSRD-reporting enterprises. |
| Platform Integration Bundling | Managed security and cloud interconnect services capture preference from mid-market Polish manufacturers. |
| Krakow Secondary Cluster Expansion | Jagiellonian University pipelines and 30% lower land costs attract edge computing for Silesian automation. |
Research Methodology
Desk research of UKE licensing databases, Polish Energy Regulatory Office interconnection filings, and EU CSRD disclosure precedents preceded structured interviews with data center development executives, critical facilities engineers, and enterprise IT procurement officers. Primary fieldwork with Warsaw-based colocation operators and Krakow edge facility developers was cross-referenced against hyperscaler capex disclosures and renewable energy certificate market data. Bottom-up capacity absorption modeling was triangulated with top-down infrastructure investment flow analysis.
Assumptions around Polish grid interconnection queue durations, EU Green Deal PUE compliance timelines, and National Cloud Strategy procurement volumes were held fixed across baseline scenarios while stress-testing sensitivity to labor wage inflation and renewable energy certificate price volatility. Segmentation dimensions modeled include facility scale tier, service layer complexity, end-use vertical, and deployment architecture. CAGRs were derived from installed base evolution and incremental capacity absorption curves, incorporating power density trends and liquid cooling adoption rates as technology-specific inputs.
Stress conditions across grid interconnection delays, EU regulatory enforcement intensity, and German cross-border demand elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sovereign data hosting mandates and carbon disclosure requirements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Indonesia Data Center Construction Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Norway Data Center Rack Market