
 Asia-Pacific Containerized Data Center Market | 2026-2036
Asia-Pacific Containerized Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Containerized Data Center Market Outlook
Software-defined power management is hardening as a discrete revenue layer within containerized data center contracts. Schneider Electric leverages its global energy management footprint to anchor large-scale deployments across Australia and Singapore. Huawei Technologies competes through integrated 5G-to-edge propositions that bundle radio access with modular compute infrastructure. Delta Electronics specializes in thermal and power subsystems, sustaining margin pools in cooling solutions where technical differentiation commands pricing power.
Containerized data centers are self-contained, transportable facilities built within standardized shipping enclosures, typically housing IT equipment, power distribution, and cooling systems in densities exceeding 100 kW per rack for edge and remote deployments. Standard containers dominate volume shipments for rapid-deployment scenarios, while customized containers capture premium pricing from financial and healthcare clients requiring bespoke physical security and compliance configurations. Edge computing deployments are accelerating fastest within the deployment dimension as telecommunications carriers push compute closer to subscribers.
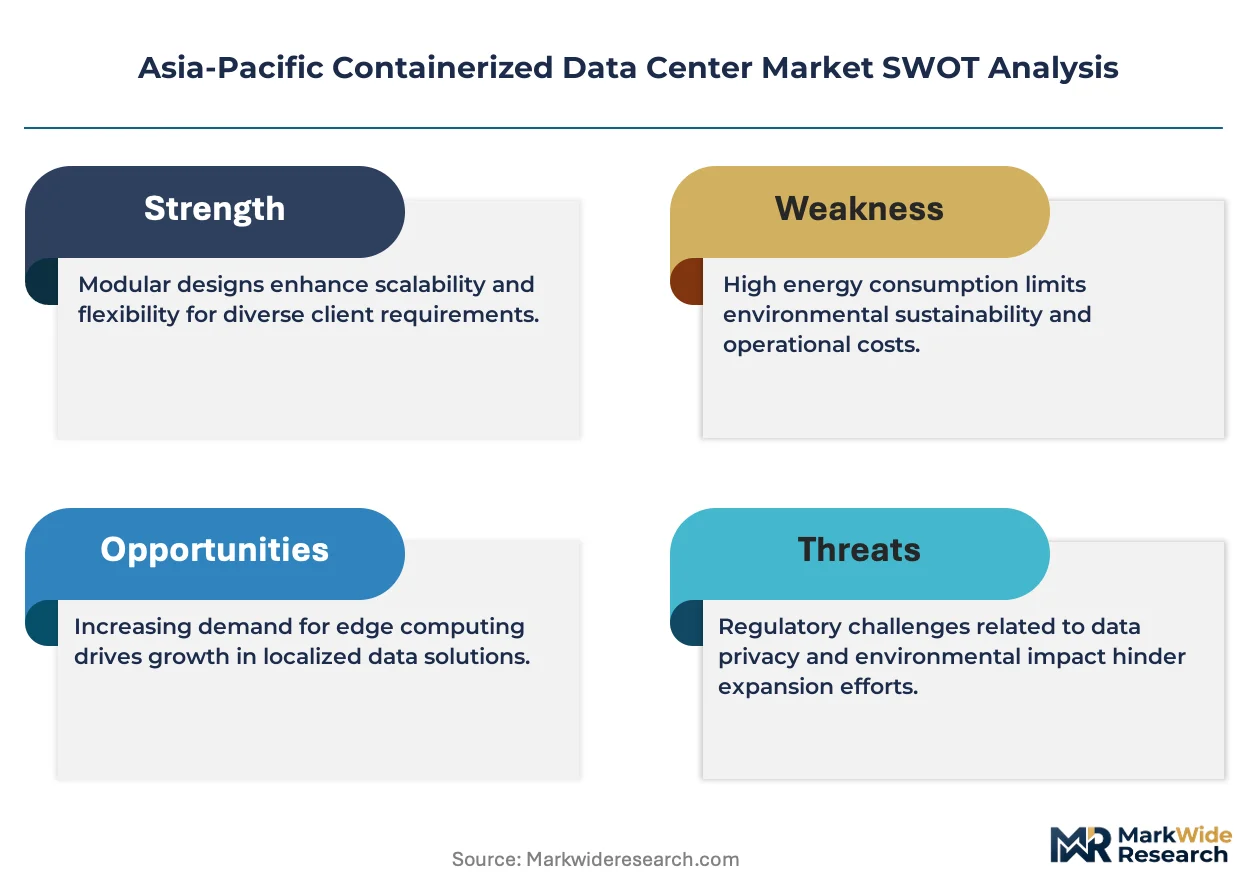
India's CEA mandates power usage effectiveness thresholds for data center operations, while China's MEE enforces dual carbon compliance timelines that shape cooling technology selection across the region. Japan's METI promotes edge infrastructure standardization through JIS-aligned efficiency benchmarks, creating certification requirements that filter market access for foreign suppliers. Stakeholders must monitor regulatory divergence on energy efficiency and carbon accounting as these frameworks mature and begin to constrain cross-border equipment procurement.
Market Dynamics
China's MEE dual carbon mandates are compressing cooling technology selection timelines across the Asia-Pacific, forcing facility operators to abandon air-cooled architectures before end-of-life cycles complete.
Growth Catalysts
- 5G Radio Densification:Telecommunications carriers in Thailand, Vietnam, and the Philippines are deploying containerized edge nodes within 10 kilometers of subscriber clusters to meet latency thresholds for autonomous systems and industrial automation.
- India's CEA Efficiency Mandates:Power usage effectiveness thresholds for data center operations are accelerating replacement cycles in Maharashtra and Karnataka, where hyperscale cloud providers are building distributed capacity outside traditional Mumbai-Delhi corridors.
- Liquid Cooling Maturation:Direct-to-chip and immersion architectures are crossing total-cost-of-equipment parity with precision air systems at densities above 80 kW per rack, unlocking deployment in tropical climates previously considered unsuitable for high-performance compute.
Market Restraints
- Copper and Rare Earth Input Volatility:Power distribution units and thermal management subsystems depend on copper busbars and neodymium-doped magnetic components, exposing margin structures to commodity price swings from Chinese and Chilean supply concentration.
- Transport Infrastructure Gaps:Last-mile road weight limits and bridge clearance restrictions in Indonesia, the Philippines, and rural India constrain 40-foot high-cube container mobility, fragmenting addressable demand to coastal and major highway-adjacent sites.
- Grid Interconnection Queues:Utility approval timelines for multi-megawatt connections in Australia and Japan extend 18-36 months, misaligning with enterprise customers' 90-120 day deployment requirements for edge capacity.
Strategic Opportunities
- Vietnam and Indonesia Greenfield Deployment:Domestic cloud and fintech operators in Ho Chi Minh City and Jakarta are procuring containerized capacity ahead of hyperscale entry, creating first-mover positioning for modular infrastructure suppliers.
- Japan's METI Edge Standardization:JIS-aligned efficiency benchmarks are creating certification requirements that filter market access, rewarding early compliance investment with preferred supplier status for telecommunications and automotive edge projects.
- AI Inference at Cell Tower Base:Convergence of GPU-accelerated compute with 5G baseband processing is opening co-location revenue streams where containerized facilities house both radio and inference workloads for computer vision and natural language applications.
Industry Challenges
- Immersion Cooling Technician Scarcity:Dielectric fluid handling, leak detection, and server-level maintenance protocols require specialized training absent from standard HVAC and electrical contractor curricula across the region.
- Multi-Regulatory Certification Overlap:Equipment suppliers must simultaneously satisfy China's GB standards, India's BIS requirements, and Australia's electrical safety frameworks, extending product qualification timelines and fragmenting SKU portfolios.
- Legacy DCIM Integration Friction:Containerized facilities with software-defined power management must interface with enterprise data center infrastructure management platforms built for monolithic facilities, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Containerized Data Center Market |
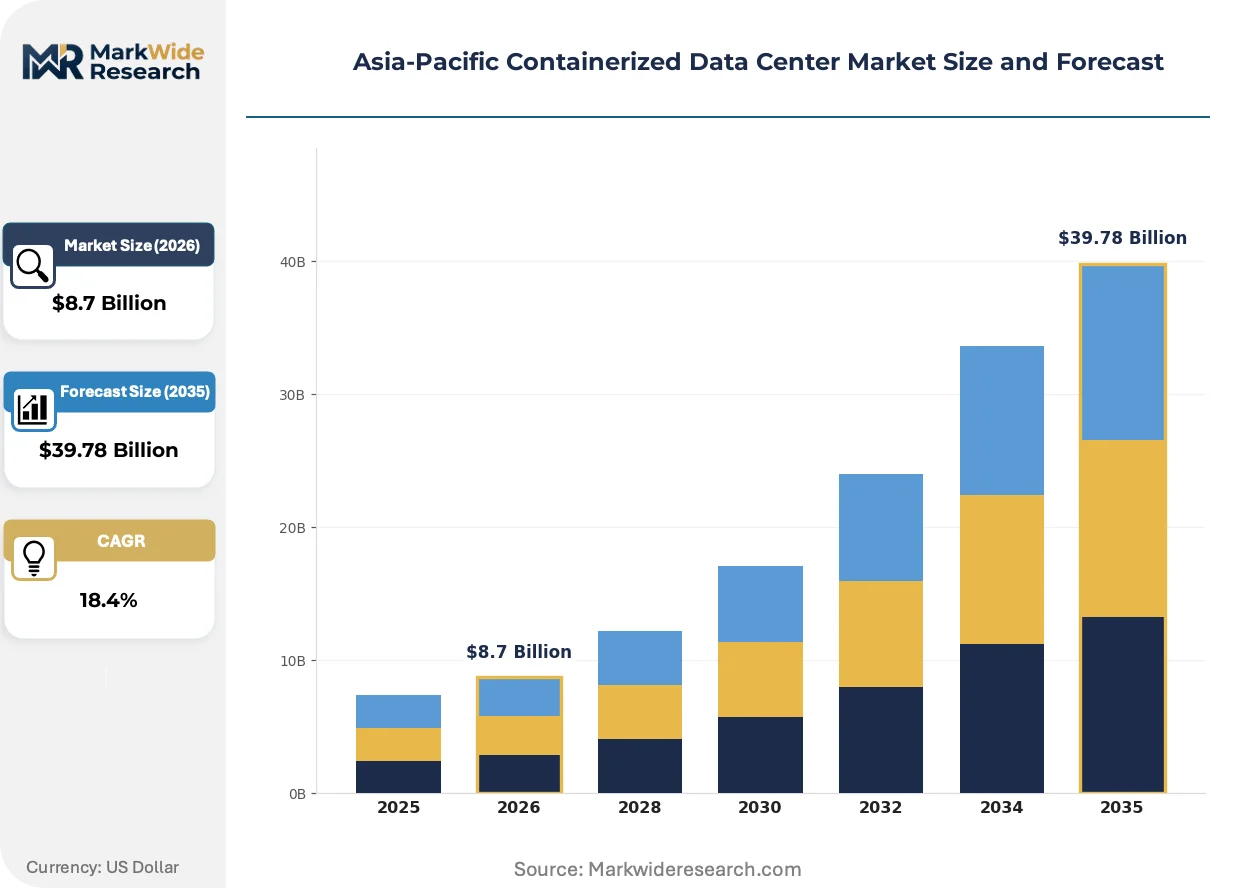
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Containers, Customized Containers, Modular Containers, Micro Data Centers End User: Telecommunications, BFSI, Retail, Healthcare Deployment: On-Premise, Off-Premise, Edge Computing, Hybrid Technology: Cooling Solutions, Power Management, Security Solutions, Monitoring Systems |
| Companies Covered | Huawei Technologies, Delta Electronics, Vertiv Holdings, Schneider Electric, Fuji Electric, Hewlett Packard Enterprise, Fujitsu, Rittal, ZTE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Containerized Data Center Market Strategic Shifts
Software-defined control architectures are dissolving the boundary between power, cooling, and compute management, enabling autonomous optimization loops that respond to grid pricing signals and workload thermal signatures in real time.
Direct liquid cooling is modularizing deployment architectures across Southeast Asia. Dielectric fluid distribution manifolds and cold-plate server designs from Taiwanese and Korean component suppliers are displacing raised-floor air handlers in new builds. Telecommunications operators in Singapore and Australia are adopting these systems at 150-250 kW per rack densities, compressing facility footprints by 60 percent and enabling edge placement in constrained real estate.
China's MEE enforcement timelines for dual carbon compliance are hardening cooling technology selection criteria. Facility operators must document renewable energy procurement and carbon intensity per computation, with non-compliance triggering operating permit reviews. This regulatory pressure is concentrating demand in liquid-cooled and solar-hybrid containerized units, particularly in Guangdong and Jiangsu provinces where provincial environmental bureaus conduct unannounced audits.
Enterprise procurement patterns are fragmenting across ownership models. Hyperscale cloud providers in India and Japan are shifting toward containerized capacity leases with 36-60 month terms, displacing traditional build-operate-transfer arrangements. This behavioral shift compresses supplier cash conversion cycles and demands modular equipment with standardized interconnects for rapid redeployment between customer sites, with the phenomenon most visible in Bangalore's Electronic City and Tokyo's Otemachi financial district clusters.
Asia-Pacific Containerized Data Center Market Segmentation
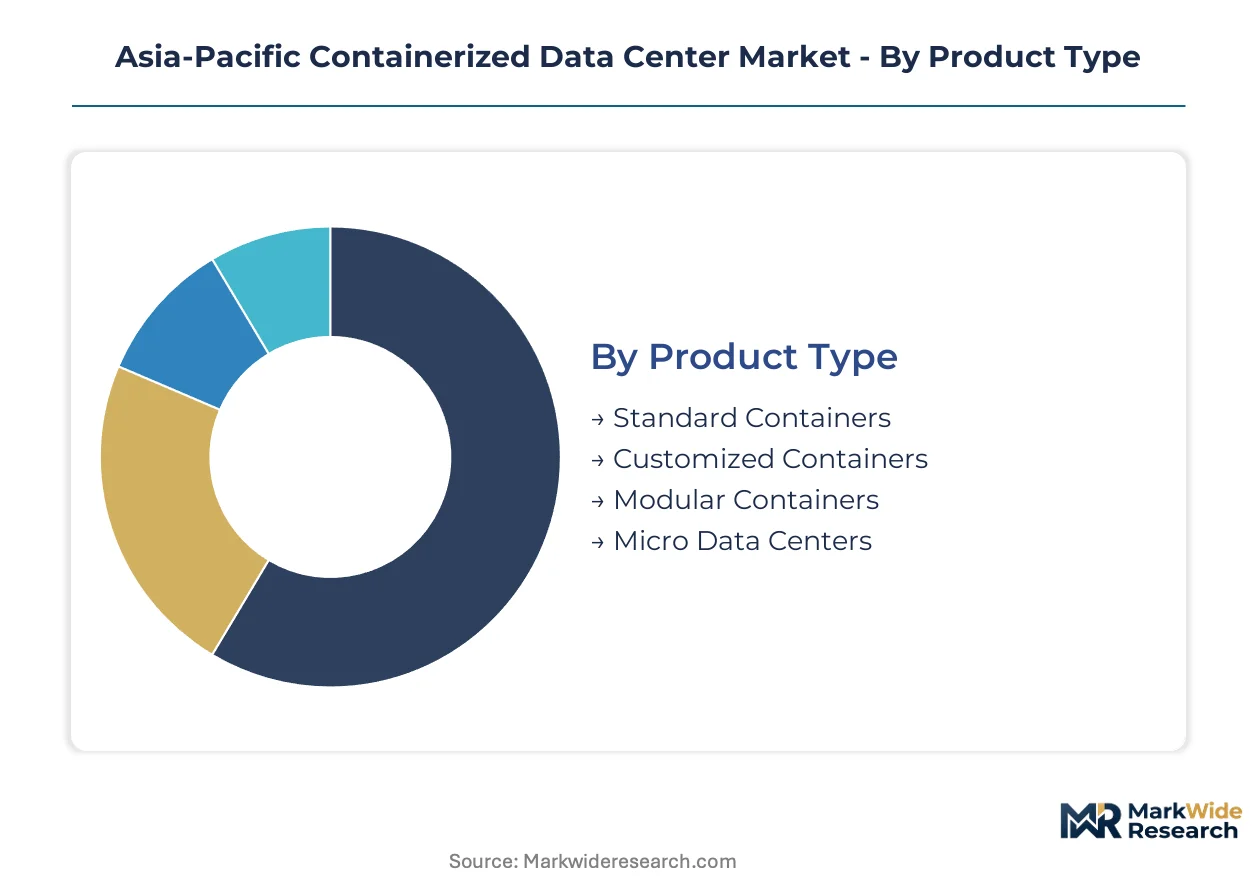
Segmentation in the Asia-Pacific containerized data center market reveals divergent procurement patterns across product architectures and deployment models. Facility operators in tropical climates prioritize thermal performance specifications, while telecommunications carriers emphasize rapid deployment timelines over customization depth.
Product Type:
Standard containers dominate volume shipments across Southeast Asia, while customized units command premium pricing from compliance-sensitive verticals.
- Standard Containers:Pre-engineered 20-foot and 40-foot ISO shipping enclosures with fixed power and cooling densities up to 100 kW per rack. Demand concentrates in Thailand and Vietnam where telecommunications carriers deploy rapid-response edge nodes for 5G radio densification.
- Customized Containers:Bespoke physical security configurations, biometric access controls, and compliance-hardened enclosures tailored to financial and healthcare data sovereignty requirements. BFSI procurement in Singapore and Australia drives specification complexity for multi-tenant financial trading infrastructure.
- Modular Containers:Factory-integrated power and cooling subsystems enabling incremental capacity scaling through standardized interconnects.
- Micro Data Centers:Sub-100 kW self-contained units for retail branch and remote industrial deployments.
Mature deployment sits with Standard Containers. Newer deployment is concentrated in Customized Containers.
End User:
Customer procurement patterns split between latency-sensitive telecommunications infrastructure and compliance-bound enterprise verticals.
- Telecommunications:5G network operators procuring edge compute capacity within 10 kilometers of subscriber clusters. Deployment accelerates in the Philippines and Indonesia where spectrum auctions mandate coverage timelines.
- BFSI:Banking and insurance operators requiring physical segregation, audit trails, and sovereign data residency. India's RBI guidelines on data localization concentrate demand in Maharashtra and Karnataka for distributed disaster recovery.
- Retail:Omnichannel operators deploying point-of-sale analytics and inventory management at distribution centers.
- Healthcare:Hospital networks and diagnostic chains requiring HIPAA-aligned and local-equivalent privacy controls for patient imaging data.
Procurement scale concentrates with Telecommunications. Margin expansion sits with BFSI.
Deployment:
Ownership models fragment across capital retention preferences and operational capability gaps.
- On-Premise:Enterprise-owned and operated facilities on captive real estate. Manufacturing conglomerates in Japan's Aichi Prefecture and South Korea's Gyeonggi Province favor this model for intellectual property protection.
- Off-Premise:Third-party operated facilities with utility-style capacity contracts. Australian mining operators leverage off-premise deployments in Western Australia's Pilbara region to bypass grid interconnection queues.
- Edge Computing:Distributed compute placement proximal to data generation sources. Expanding most quickly across Southeast Asia as MNOs densify radio access networks.
- Hybrid:Orchestrated workloads across on-premise containerized units and hyperscale cloud regions.
Legacy infrastructure persists in On-Premise. Capacity expansion concentrates in Edge Computing.
Technology:
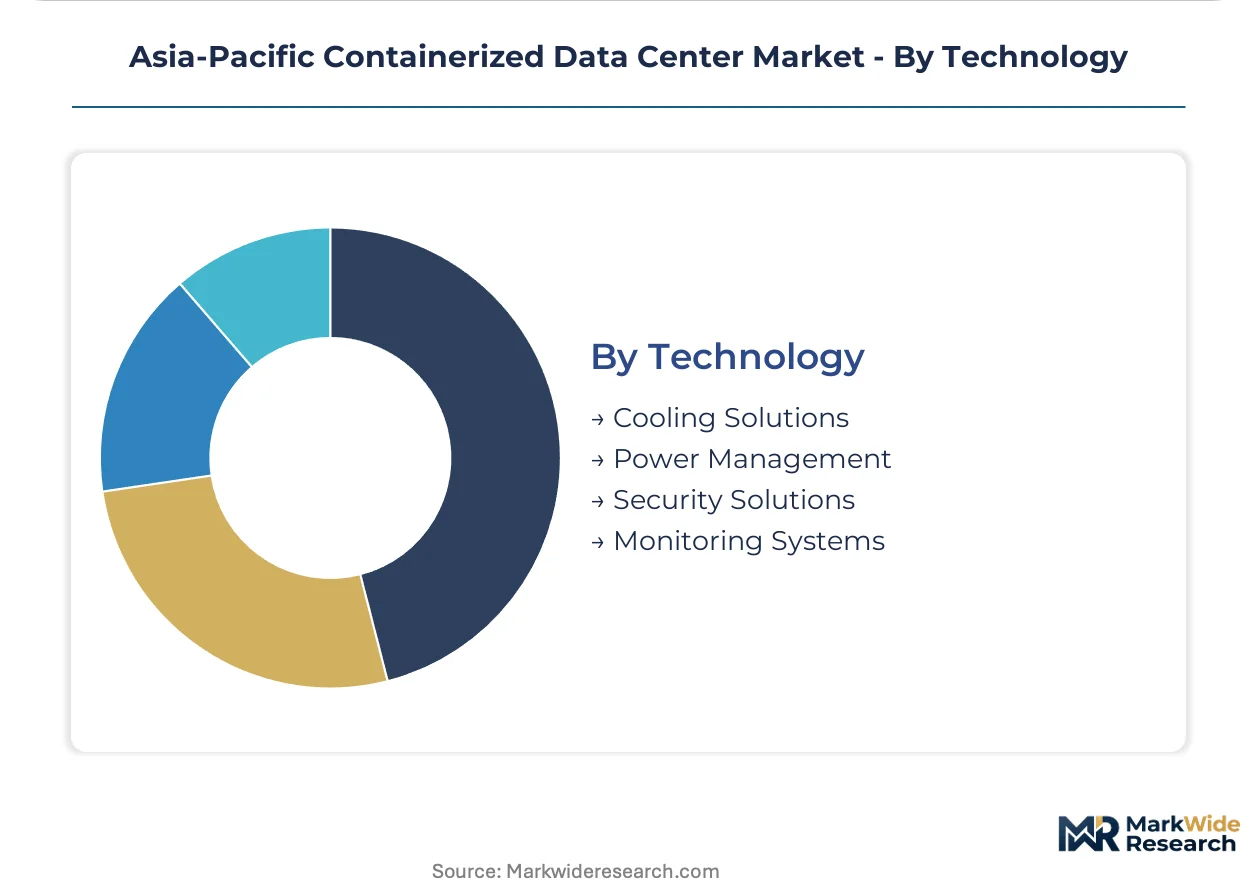
Subsystem selection increasingly determines total deployment economics as rack densities climb past air-cooling thresholds.
- Cooling Solutions:Direct-to-chip liquid cooling, immersion baths, and precision air handlers. China's MEE dual carbon enforcement accelerates liquid cooling adoption in Guangdong and Jiangsu provinces ahead of compliance deadlines.
- Power Management:Software-defined power distribution with grid-interactive load shaping. Singapore's SP Group tariff structures reward facilities with demand-response capability.
- Security Solutions:Physical access controls, electromagnetic shielding, and tamper-evident enclosures.
- Monitoring Systems:DCIM platforms with predictive thermal and electrical anomaly detection.
Technical differentiation clusters in Cooling Solutions. Procurement standardization sits with Monitoring Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of containerized data center enclosures and thermal subsystems, while consumption concentrates in India, Japan, and Southeast Asian telecommunications markets. This production-consumption divide shapes regional trade flows and supplier positioning across the Asia-Pacific.
China
Guangdong and Jiangsu provinces drive domestic demand for liquid-cooled containerized units as provincial environmental bureaus enforce MEE dual carbon compliance timelines. The MEE mandates renewable energy documentation and carbon intensity accounting per computation workload. Shenzhen and Suzhou industrial clusters host hyperscale operators procuring solar-hybrid modular facilities ahead of permit review deadlines.
India
Hyperscale cloud providers are building distributed capacity in Maharashtra and Karnataka outside traditional Mumbai-Delhi corridors. The CEA mandates power usage effectiveness thresholds that accelerate replacement cycles in existing facilities. Bangalore's Electronic City cluster concentrates procurement of containerized edge nodes for 5G densification and fintech disaster recovery infrastructure.
Japan
Telecommunications carriers and automotive manufacturers procure edge-standardized containerized facilities under METI-promoted JIS efficiency benchmarks. METI certification requirements filter market access for foreign suppliers and reward early compliance investment. Tokyo's Otemachi financial district and Aichi Prefecture manufacturing zones favor enterprise-owned on-premise deployments for intellectual property protection.
Australia
Mining operators in Western Australia's Pilbara region leverage off-premise containerized deployments to bypass grid interconnection queues that extend 18-36 months. SP Group tariff structures in Singapore reward demand-response capability, influencing procurement specifications across the broader Oceania region. Sydney and Melbourne clusters concentrate telecommunications edge capacity for 5G radio densification.
Vietnam
Domestic cloud and fintech operators in Ho Chi Minh City procure containerized capacity ahead of anticipated hyperscale entry, creating first-mover positioning opportunities. Spectrum auctions in the Philippines and Indonesia mandate coverage timelines that accelerate telecommunications carrier procurement across Southeast Asia. Containerized edge nodes deploy within 10 kilometers of subscriber clusters to meet latency thresholds for industrial automation.
Asia-Pacific Containerized Data Center Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific containerized data center market. Integrated infrastructure conglomerates with captive manufacturing facilities face competition from specialist subsystem suppliers and software-defined power management vendors. Three strategic archetypes dominate: full-stack system integrators bundling radio access with modular compute, thermal and power subsystem specialists commanding margin pools in cooling solutions, and global energy management platforms anchoring large-scale deployments. Competitive moves concentrate on geographic expansion into Vietnam and Indonesia greenfield markets and technology licensing partnerships for liquid cooling architectures.
Among Asia-Pacific-based conglomerates, Huawei Technologies and ZTE represent full-stack system integrators competing through 5G-to-edge bundled propositions. Delta Electronics, a Taiwan-based specialist, exemplifies the thermal and power subsystem archetype where technical differentiation sustains pricing power. Schneider Electric, a France-based multinational, anchors the global energy management platform tier across Australia and Singapore deployments. These three companies occupy distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Huawei Technologies |
| Delta Electronics |
| Vertiv Holdings |
| Schneider Electric |
| Fuji Electric |
| Hewlett Packard Enterprise |
| Fujitsu |
| Rittal |
| ZTE |
| Others |
Value Chain & Pricing Dynamics
Captive manufacturing of thermal subsystems in Taiwan and Guangdong anchors both supply security and margin retention for containerized data center producers serving Asia-Pacific telecommunications carriers. This integration choice insulates pricing power against copper and rare earth volatility while compressing procurement cycles for liquid cooling manifolds and power distribution units.
Pricing Analysis
Cost compression in standard container tiers reflects copper busbar and neodymium magnet input volatility from Chinese and Chilean supply concentration. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and customization depth, with BFSI procurement in Singapore commanding 40-60 percent premiums for biometric-hardened enclosures. Pricing pressure intensifies in telecommunications segments as 5G radio densification timelines compress vendor qualification windows. Hyperscale cloud providers in India exhibit highest price sensitivity through 36-60 month lease structures, while healthcare operators in Japan demonstrate lowest sensitivity due to data sovereignty mandates.
Supply Chain Analysis
Technician scarcity for dielectric fluid handling in Shenzhen and Suzhou industrial clusters constrains immersion cooling subsystem output expansion. Manufacturing concentrates in China, Taiwan, and South Korea, with final assembly drawing from precision metal fabrication in Dongguan and semiconductor-grade cooling component production in Hsinchu. Single-source vulnerability sits with neodymium-doped magnetic components from Chinese rare earth processors. Distribution runs through direct OEM relationships for hyperscale deployments and systems integrator channels for enterprise edge projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over liquid cooling intellectual property and renewable energy procurement systems determines long-term positioning. Players are pursuing backward integration into thermal subsystem manufacturing to defend margin pools.
For Market Incumbents: Anticipate margin compression from Chinese MEE compliance deadlines accelerating technology refresh cycles. Defend position by deepening captive manufacturing of direct-to-chip cooling manifolds in Taiwan and securing JIS certification ahead of METI enforcement timelines. Channel control through exclusive distribution partnerships with Vietnam and Indonesia telecommunications carriers provides defensive moats against modular subsystem specialists. For New Entrants and Emerging Players: Digital-channel partnerships with cloud brokerage platforms offer lowest-friction customer acquisition for containerized edge capacity. Target white-space in Indonesia's rural grid-constrained zones where 40-foot high-cube mobility limitations fragment incumbent reach. Ho Chi Minh City fintech procurement ahead of hyperscale entry represents the most penetrable geography. Position through software-defined power management overlays that integrate with existing enterprise DCIM platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to global energy management platforms seeking Asia-Pacific thermal subsystem capabilities. Long-term viability hinges on renewable energy procurement integration and carbon intensity accounting systems aligned with MEE dual carbon mandates. Acquisition target archetype: Taiwan-based specialists with JIS-certified liquid cooling portfolios and Vietnamese distribution relationships. Watch MEE unannounced audit enforcement intensity as inflection indicator for compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Subsystems | Captive production of dielectric fluid manifolds in Taiwan insulates margins from rare earth volatility. |
| JIS Certification Investment | METI-aligned efficiency benchmarks in Japan filter supplier access for telecommunications edge projects. |
| Software-Defined Power Management Launch | Grid-interactive load shaping capabilities unlock SP Group tariff arbitrage in Singapore deployments. |
| Vietnam Greenfield Distribution Partnership | Domestic cloud operator relationships in Ho Chi Minh City establish positioning ahead of hyperscale entry. |
| Immersion Cooling Technician Training Program | Specialized curricula addressing dielectric fluid handling scarcity accelerate deployment velocity in tropical climates. |
Study Parameters
Multi-period observation of CEA-mandated PUE thresholds and MEE dual carbon enforcement timelines anchored the trend analysis, supplemented by interviews with facility operators, thermal subsystem procurement leads, telecommunications network planning officers, and enterprise IT infrastructure directors. Secondary validation drew from CEA circulars, METI JIS standard publications, MEE environmental compliance bulletins, and hyperscaler capital expenditure disclosures. Bottom-up triangulation across deployment unit counts and top-down validation against aggregate capacity announcements ensured consistency.
Segment-weighting across product architecture, deployment model, end-user vertical, and cooling technology dimensions structured the analytical framework over the projection horizon. CAGRs derived from logistic diffusion curves modeling liquid cooling adoption rates against air-cooled replacement cycles. Forecast inputs incorporated grid interconnection queue timelines from Australian utilities and spectrum auction coverage mandates from Philippines and Indonesia regulators.
The model holds under stable enforcement of MEE dual carbon timelines and CEA efficiency mandates; deviation in regulatory audit intensity or rare earth export restrictions would shift replacement demand patterns and cooling technology selection criteria. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Switchgear for Data Centers Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
South Africa Data Center Physical Security Market