
 Philippines Data Center Power Market | 2026-2036
Philippines Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Power Market Insights
High-density liquid cooling integration is reconfiguring power distribution architectures across Philippine facilities. Schneider Electric SE leverages its integrated EcoStruxure platform to dominate prefabricated power modules for tropical climates. Vertiv Group Corp. sustains competitive positioning through thermal-electrical co-design capabilities purpose-built for Southeast Asian humidity profiles. Eaton Corporation plc anchors its presence via intelligent rack power distribution units engineered for mission-critical uptime in archipelago conditions.
Data center power encompasses the complete electrical infrastructure—uninterruptible power supplies, switchgear, diesel rotary uninterruptible power supply systems, and battery energy storage—engineered to maintain continuous operation within facilities housing server, storage, and networking equipment. The power source dimension shows diesel generators retaining baseline reliability status while battery storage and renewable hybrid configurations capture the fastest expansion trajectory. Service type segmentation reveals managed power services generating premium margins as operators outsource electrical infrastructure oversight. End-user concentration among financial institutions and telecom providers reflects regulatory compliance demands and 24/7 service obligations that mandate redundant power architectures.
The Department of Energy enforces grid interconnection standards that shape backup power redundancy requirements for certified data center facilities. BIS-equivalent electrical safety certifications and the CEA's building energy codes constrain equipment selection and facility design parameters. Stakeholders must monitor how evolving renewable portfolio standards and carbon disclosure obligations will redefine total cost of ownership calculations for power infrastructure investments across the Philippine archipelago.
Market Dynamics
Hyperscale cloud deployments from global technology platforms are reconfiguring rack density requirements across Philippine facilities, forcing power infrastructure suppliers to engineer liquid-cooled distribution architectures that can sustain tropical operational conditions.
Growth Catalysts
- Renewable Portfolio Standards:The Department of Energy's renewable energy integration mandates are accelerating hybrid power architecture adoption among facility operators seeking certification compliance.
- Financial Sector Digitalization:Digital payment processors and banking institutions now mandate redundant power architectures for real-time transaction processing uptime obligations.
- Liquid Cooling Integration:High-density server racks are driving demand for thermal-electrical co-designed power modules purpose-built for Southeast Asian humidity profiles.
Market Restraints
- Grid Interconnection Standards:The Department of Energy enforces backup power redundancy requirements that inflate capital expenditure thresholds for certified facilities.
- Equipment Certification Delays:BIS-equivalent electrical safety certifications and CEA building energy codes constrain equipment selection timelines and facility design flexibility.
- Diesel Generator Dependency:Baseline reliability requirements perpetuate fossil fuel infrastructure despite carbon disclosure obligations from institutional investors.
Strategic Opportunities
- Cebu Secondary Market:Metro Manila capacity constraints are redirecting hyperscale investment toward Cebu, creating demand for modular power infrastructure in underdeveloped clusters.
- Battery Energy Storage Convergence:Lithium-ion systems paired with intelligent rack power distribution units enable peak shaving and grid stabilization services for utility partnerships.
- Managed Power Services:Facility operators are outsourcing electrical infrastructure oversight to specialized vendors, generating premium service margins beyond equipment sales.
Industry Challenges
- Tropical Climate Engineering:Power distribution equipment must withstand corrosion, humidity cycling, and typhoon exposure that accelerate degradation rates versus temperate designs.
- Skilled Technician Scarcity:Mission-critical uptime requirements demand certified electrical engineers with hybrid renewable-diesel system expertise that remains concentrated in Metro Manila.
- Legacy Infrastructure Integration:Brownfield facilities face complex retrofit challenges when upgrading from air-cooled to liquid-cooled power architectures without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Power Market |
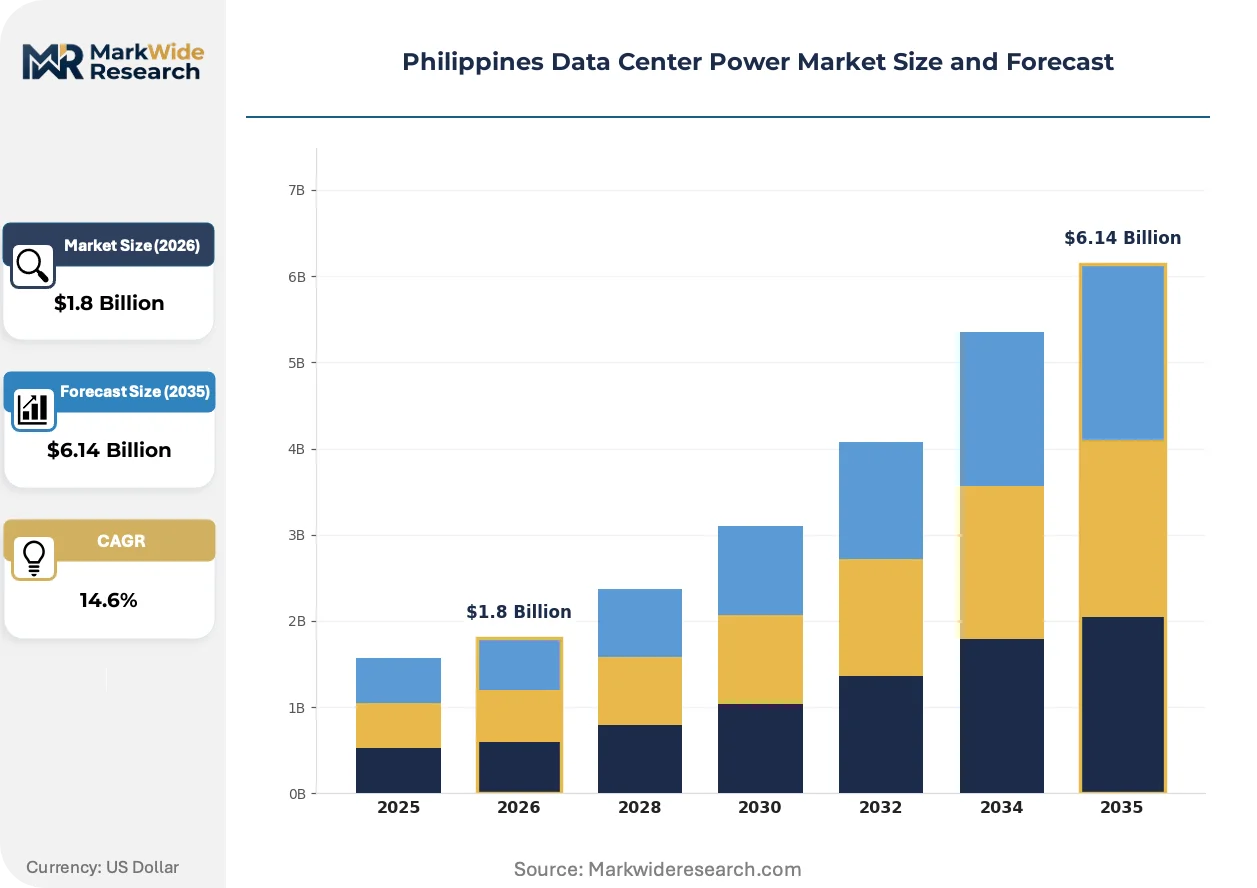
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid, Diesel Generators, Renewable Energy, Battery Storage Service Type: Managed Services, Colocation, Hyperconvergence, Direct Power Purchase End User: Financial Institutions, E-commerce, Telecom Providers, Government Agencies Size: Small, Medium, Large, Hyper-scale |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Eaton Corporation plc, ABB Ltd., Cummins Inc., Mitsubishi Electric, Fuji Electric, Legrand, Caterpillar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Power Market Trends and Innovations
Philippine data center power infrastructure is undergoing architectural transformation as rack densities climb and regulatory pressure intensifies. Three distinct vectors are reconfiguring supplier strategies and buyer procurement patterns.
Software-defined power management is virtualizing electrical infrastructure control across distributed facility portfolios. Large colocation operators in Metro Manila are deploying centralized monitoring platforms that orchestrate load balancing across multiple sites. This technology is virtualizing traditional site-by-site power engineering, compressing operational headcount requirements while enabling real-time capacity optimization.
The Department of Energy's renewable energy integration mandates are reshaping capital allocation toward hybrid architectures. Certified facilities must now demonstrate grid interconnection standards compliance with documented backup redundancy configurations. Financial institutions and digital payment processors face the steepest compliance burden, as their transaction processing obligations trigger the most stringent uptime certification tiers.
Facility operators are unbundling electrical infrastructure oversight from in-house engineering teams. Colocation providers and hyperscale tenants now contract managed power services that transfer operational risk to specialized vendors. This pattern concentrates procurement authority among procurement departments rather than engineering functions, most visibly among telecom providers with archipelago-wide distributed infrastructure portfolios.
Philippines Data Center Power Market Segmentation
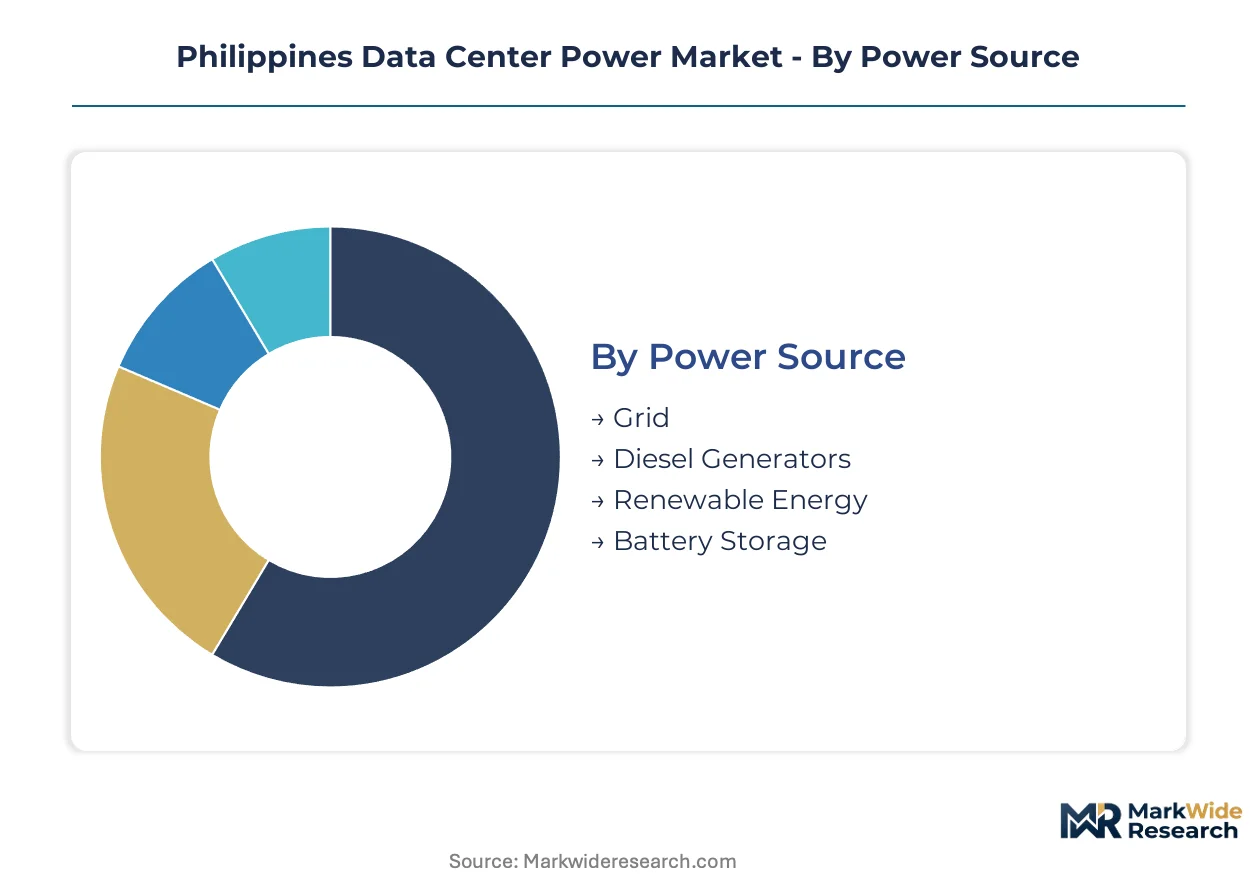
Power infrastructure procurement patterns in Philippine data centers diverge sharply across operational scale and regulatory exposure. Segment-specific requirements for backup redundancy, renewable integration timelines, and thermal-electrical co-design create distinct supplier engagement models across the archipelago.
Power Source:
Replacement cycles stretch from 15-year diesel generator baselines to 8-year battery storage refresh intervals, compressing capital planning horizons for hybrid architectures.
- Grid:Primary feedstock for Metro Manila and Cebu facilities with documented interconnection redundancy to Department of Energy standards. Financial institutions in Makati CBD mandate dual-feed substations with automatic transfer switching for real-time transaction uptime.
- Diesel Generators:Rotary and static UPS systems configured for tropical humidity cycling with corrosion-resistant enclosures. Baseline reliability anchor for certified Tier III facilities despite carbon disclosure pressure from institutional capital providers.
- Renewable Energy:Solar-hybrid configurations accelerating under renewable portfolio standards.
- Battery Storage:Lithium-ion rack-mount systems enabling peak shaving and grid stabilization services.
Diesel generators dominate installed base. Battery storage is where expansion concentrates.
Service Type:
Margin structures stratify between capital-intensive equipment sales and recurring managed services revenue streams with divergent customer lifetime values.
- Managed Services:Outsourced electrical infrastructure oversight transferring operational risk to specialized vendors. Telecom providers with archipelago-wide distributed portfolios concentrate procurement authority among procurement departments rather than engineering functions.
- Colocation:Shared power infrastructure with standardized redundancy tiers attracting mid-market enterprises seeking certification compliance without capital deployment.
- Hyperconvergence:Integrated compute-storage-networking stacks with software-defined power orchestration.
- Direct Power Purchase:Long-term renewable energy procurement agreements bypassing utility intermediaries.
Colocation anchors revenue volume. Managed services is climbing the fastest.
End User:
Regulatory compliance intensity and 24/7 uptime obligations create tiered demand for redundant power architectures across institutional categories.
- Financial Institutions:Banking and digital payment processors with real-time transaction processing mandates driving the most stringent certification requirements. Bangko Sentral ng Pilipinas oversight compels documented backup redundancy with sub-15-second failover protocols.
- Telecom Providers:Archipelago-wide infrastructure portfolios requiring standardized power modules across island clusters with divergent grid reliability profiles.
- E-commerce:Flash sale and logistics uptime requirements driving modular UPS deployment.
- Government Agencies:Bureaucratic procurement cycles with extended vendor qualification timelines.
Financial institutions command premium pricing. E-commerce is gaining share fastest.
Size:
Capital deployment thresholds and in-house engineering capabilities determine procurement centralization versus distributed decision-making across facility scales.
- Hyperscale:Cloud platform deployments above 10MW with liquid-cooled power distribution engineered for tropical operational conditions. Custom prefabricated electrical modules with integrated thermal management dominate procurement specifications.
- Large:Enterprise and colocation facilities with dedicated substations and on-site generation.
- Medium:Regional data centers in secondary cities with standardized modular UPS configurations.
- Small:Edge and micro-facilities with compact rack-mount power protection.
Hyperscale facilities absorb disproportionate supplier engineering resources. Medium-sized deployments in Cebu show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine data center power equipment flows primarily from manufacturing hubs in China, Japan, and South Korea into Metro Manila and Cebu deployment sites. Regional supply chains concentrate on tropical-grade electrical infrastructure with corrosion-resistant specifications.
Metro Manila
Makati CBD and Taguig financial districts drive concentrated demand from banking institutions requiring dual-feed substations with automatic transfer switching. The Department of Energy enforces grid interconnection standards with documented backup redundancy for certified Tier III facilities. Colocation clusters in Quezon City and Pasig absorb modular UPS deployments from hyperscale cloud entrants.
Cebu
Secondary market expansion redirects hyperscale investment from capacity-constrained Manila toward Mactan and Cebu City industrial zones. Renewable portfolio standards accelerate solar-hybrid power architecture adoption among new facility developments. Submarine cable landing stations in Lapu-Lapu City anchor submarine connectivity infrastructure requiring redundant diesel-battery hybrid systems.
Central Luzon
Clark Freeport Zone and Subic Bay attract disaster-recovery data center investments with lower seismic risk profiles than Metro Manila. The Philippine Economic Zone Authority offers fiscal incentives for power infrastructure investments in designated technology parks. Bataan and Pampanga provinces host emerging edge facility deployments serving provincial banking networks.
Davao Region
Mindanao's largest metropolitan area supports disaster-resilient backup sites for Manila-based financial institutions. Grid reliability challenges from islanded generation profiles mandate enhanced on-site diesel generator capacity versus Luzon facilities. Davao del Sur and Davao City concentrate government agency data center deployments with extended procurement cycles.
Philippines Data Center Power Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers with tropical climate engineering capabilities. European and American electrical infrastructure specialists dominate prefabricated power module supply, while Japanese and Korean manufacturers anchor rotating machinery and switchgear segments. Two strategic archetypes define competitive positioning: integrated EcoStruxure-type platform vendors and thermal-electrical co-design specialists. Dominant competitive moves include geographic expansion into Cebu secondary markets and portfolio diversification into managed power services.
Within the integrated platform tier, Schneider Electric SE and Vertiv Group Corp. represent archetypal positioning. Schneider Electric SE exemplifies the full-stack vendor model with tropical-grade prefabricated modules. Vertiv Group Corp. occupies a position emphasizing thermal-electrical integration for Southeast Asian humidity profiles. Eaton Corporation plc anchors the intelligent power distribution segment with rack-level solutions engineered for archipelago uptime requirements.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation plc |
| ABB Ltd. |
| Cummins Inc. |
| Mitsubishi Electric |
| Fuji Electric |
| Legrand |
| Caterpillar |
| Others |
Pricing and Supply Chain Analysis
Manila-Cebu container freight corridors transmit cost volatility from Chinese manufacturing hubs directly into Philippine data center power equipment landed costs, compressing margins for distributors while enabling tiered pricing stratification based on import timing and volume scale.
Pricing Analysis
Next-generation liquid-cooled power modules command substantial premiums over air-cooled legacy systems and emerging solid-state battery alternatives, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and thermal performance specifications. Price differentiation centers on UL-listed tropical-grade enclosures versus standard industrial ratings, with hyperscale cloud operators showing lowest price sensitivity due to total cost of ownership optimization mandates. Cost compression in standard-tier modular UPS is intensifying because of Chinese supplier capacity expansion, while managed power services generate recurring revenue premiums that offset equipment margin erosion.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for Philippine data center operators, forcing inventory positioning adjustments and alternative supplier qualification. Manufacturing concentrates in China, South Korea, and Japan for switchgear, power semiconductors, and precision cooling components, with lithium-ion cells and corrosion-resistant aluminum alloys representing critical input dependencies. Single-source vulnerability persists for tropical-grade enclosure coatings engineered for typhoon and salt-air exposure. Distribution runs through authorized electrical distributors in Metro Manila with direct manufacturer relationships for hyperscale accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the Philippine data center power market as hyperscale requirements diverge from mid-market colocation needs, with liquid cooling integration and renewable hybrid mandates creating distinct supplier niches.
For Market Incumbents: Pre-empt emerging competition from Chinese electrical equipment manufacturers by deepening tropical climate engineering capabilities and securing exclusive managed services contracts with Bangko Sentral ng Pilipinas-regulated financial institutions. Anchor procurement relationships through backward integration into battery energy storage assembly within Philippine Economic Zone Authority-designated parks. For New Entrants and Emerging Players: Pursue white-space positioning in Cebu's secondary market for modular power infrastructure, where hyperscale investment is redirecting from capacity-constrained Metro Manila and local supplier presence remains thin. Target direct power purchase agreement facilitation as a service layer, leveraging the Department of Energy's renewable portfolio standards compliance burden to establish initial customer relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-held electrical distribution businesses with dormant data center power capabilities and established relationships with Philippine utility providers. Long-term viability hinges on renewable-diesel hybrid system integration expertise rather than pure-play diesel generator legacy. Monitor Bangko Sentral ng Pilipinas certification tier upgrades as the signal indicating accelerated infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Tropical-Grade Certification Investment | UL-listed humidity-cycling validation opens access to Tier III facility mandates from financial institutions. |
| Cebu Geographic Expansion | Mactan industrial zone proximity to submarine cable landing stations captures hyperscale power module demand. |
| Managed Power Services Launch | Operational risk transfer contracts with telecom providers generate recurring margins beyond equipment sales. |
| Battery Storage Integration Partnership | Lithium-ion peak shaving capabilities align with Department of Energy grid interconnection standards. |
| Liquid Cooling Co-Development | Thermal-electrical integration with server OEMs secures specification lock-in for high-density deployments. |
Research Methodology
A standing panel of data center facility directors, electrical infrastructure procurement managers, Department of Energy certification officers, and hyperscale cloud platform engineers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from SEC filings of listed electrical equipment suppliers, Philippine Economic Zone Authority investment statistics, and Bangko Sentral ng Pilipinas regulatory circulars. Bottom-up facility-level capacity aggregation was triangulated against top-down national power infrastructure investment flows.
Scenario-bracketing framed the analytical approach, with segmentation dimensions spanning power source architecture, service type tier, end-user regulatory exposure, and facility scale category across the projection horizon. CAGRs were derived from installed base replacement cycles, renewable portfolio standard compliance timelines, and hyperscale deployment pipeline visibility. Forecast inputs incorporated tropical climate degradation rates for electrical equipment and skilled technician availability constraints in secondary cities.
Sensitivities concentrate around Department of Energy enforcement intensity for grid interconnection standards, Chinese supplier pricing volatility, and Bangko Sentral ng Pilipinas certification tier revisions. Forecasts reflect documented assumptions regarding hyperscale investment redirection timing and renewable energy cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Asia-Pacific Data Center Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Italy Data Center Server Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
India Data Center Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
France Data Center Storage Market