
 Froth Flotation Chemicals Market | 2026-2036
Froth Flotation Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Froth Flotation Chemicals Market Analysis
Premium formulated reagents and commodity-grade bulk chemicals is decoupling as ore complexity rises. Solvay leverages its specialty alkyl hydroxamate collectors to command positions in rare earth and oxide mineral circuits. BASF SE anchors large-volume xanthate supply across South American copper belts through backward integration into carbon disulfide production. Clariant AG differentiates with tailor-made fatty amine collectors for reverse flotation in Brazil's iron ore industry.
Froth flotation chemicals are surface-active formulations—collectors, frothers, depressants, and modifiers—that alter mineral-water interfacial properties to enable selective particle attachment to air bubbles, with collector chemistries typically specified by active ingredient concentration, chain length distribution, and pH operating range. Their primary purpose is to concentrate target minerals from finely ground ore slurries into a froth phase for downstream smelting or hydrometallurgical extraction. Collector formulations dominate value capture in the product type dimension, as copper-molybdenum selective collectors carry formulation premiums over bulk sulfide reagents. Mining industry end users represent the deepest demand pool, though water treatment applications in tailings remediation are gaining traction as closure liabilities mount.
EPA effluent guidelines in the United States and REACH registration requirements in Europe constrain permissible frother chemistries, particularly for polyglycol ethers with aquatic toxicity profiles. Chile's SMA and Peru's OEFA enforce regional discharge standards that directly shape reagent selection in Andean copper operations. Stakeholders must monitor regulatory divergence between jurisdictions with strict aquatic toxicity protocols and those prioritizing production volume, as this split will determine where next-generation bio-based formulations achieve commercial scale first.
Market Dynamics
Ore grade degradation across Chilean and Peruvian copper belts is forcing miners to process more tonnage per unit of metal output, directly amplifying reagent consumption intensity and favoring suppliers with formulation customization capabilities.
Growth Catalysts
- Chile's SMA discharge protocols:Stricter effluent limits under the environmental regulator are accelerating adoption of bio-based frother chemistries in Andean copper operations.
- Iron ore beneficiation expansion:Australia's Pilbara region requires high-volume collector programs as producers chase lower-grade hematite and magnetite deposits.
- Alkyl hydroxamate collectors:Rare earth and oxide mineral circuits are demanding specialty formulations that enable selective flotation of complex polymetallic ores.
Market Restraints
- Carbon disulfide supply concentration:Xanthate production depends on this volatile feedstock, with price swings compressing margins for bulk sulfide reagent manufacturers.
- Aquatic toxicity thresholds:EPA effluent guidelines and REACH registration requirements are constraining polyglycol ether frother chemistries in regulated jurisdictions.
- Technical limitation in saline water:High-ionic-strength process water degrades conventional collector performance, forcing costly circuit modifications or freshwater sourcing.
Strategic Opportunities
- Brazilian reverse flotation demand:Tailor-made fatty amine collectors for iron ore desilication represent underpenetrated white space as Vale expands Carajás processing capacity.
- Water treatment tailings remediation:Closure liability pressures are opening aftermarket applications for modified reagents in acid mine drainage control.
- EU Green Deal chemistry mandates:Biodegradable frother development incentives are creating first-mover advantages for European formulation houses.
Industry Challenges
- Process metallurgist scarcity:Deep expertise in site-specific reagent optimization is retiring faster than training programs replace it, extending commissioning timelines.
- Legacy DCS integration friction:Automated reagent dosing systems require costly retrofitting to connect with decades-old plant control architectures.
- Multi-jurisdiction REACH compliance:Divergent chemical registration timelines between Europe and importing mining economies delay product launches by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Froth Flotation Chemicals Market |
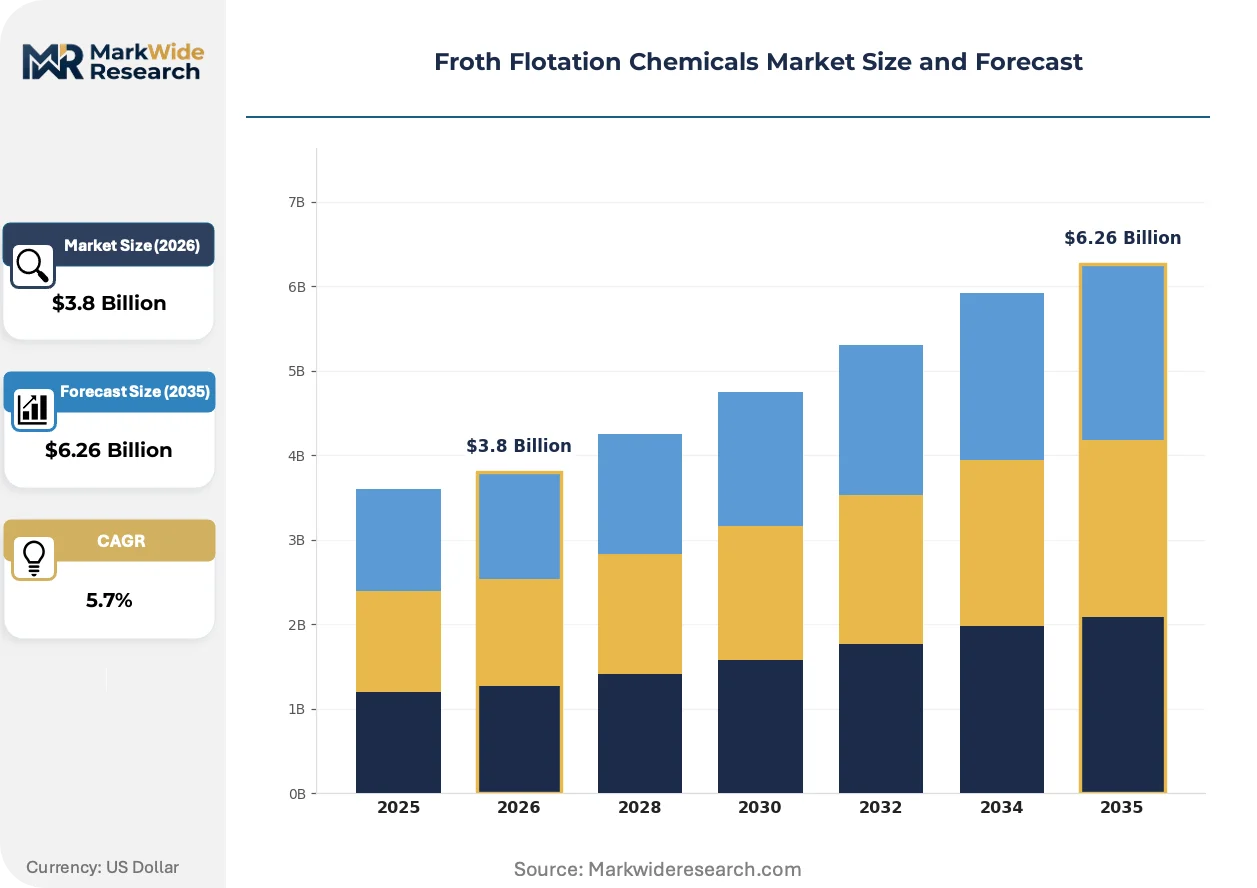
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flotation Collectors, Frothers, Depressants, Modifiers Application: Mineral Processing, Water Treatment, Oil Sands Recovery, Recycling End User: Mining Industry, Chemical Industry, Environmental Agencies, Oil & Gas Companies Form: Liquid, Powder, Emulsified, Granular |
| Companies Covered | Nouryon, Solvay, BASF SE, Arkema, Kemira, Clariant AG, NASACO, Chevron Phillips Chemical Company LLC, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Froth Flotation Chemicals Market Emerging Trajectories
Formulation science and digital process control are converging to displace empirical reagent selection with predictive mineralogy-based dosing, compressing variability in recovery rates.
Machine learning-based froth imaging is rewriting how operators optimize reagent addition in real time. Major copper concentrators in Chile and Peru are deploying computer vision systems that correlate bubble surface characteristics with grade-recovery curves. This technology is compressing the feedback loop between laboratory testwork and plant performance, enabling step-change reductions in reagent overconsumption.
REACH authorization requirements for certain glycol ether frothers are forcing European suppliers to accelerate biodegradable alternative development. The industrial consequence is a bifurcation in product portfolios between legacy chemistries acceptable in permissive jurisdictions and next-generation formulations certified for EU discharge. Copper-molybdenum selective collectors face the steepest substitution pressure, as their molecular complexity complicates registration dossiers.
Site-specific blending contracts are displacing spot procurement of commodity xanthates across South American copper belts. Procurement teams at major concentrators are consolidating supplier relationships to capture formulation expertise embedded in technical service agreements. This behavioral shift is most visible in Peru's Cerro Verde and Antamina operations, where multi-year supply partnerships now bundle reagent supply with on-site metallurgical support.
Froth Flotation Chemicals Market Segmentation
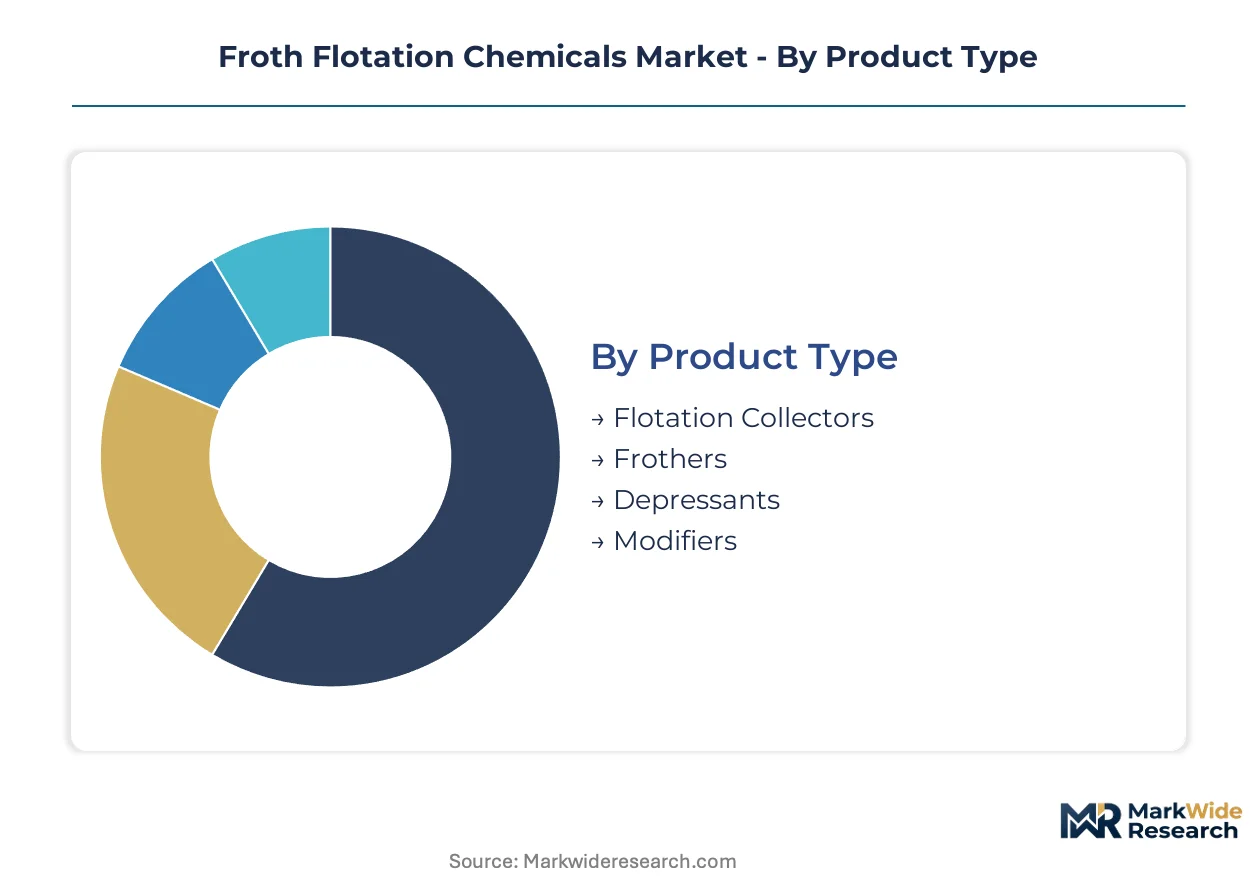
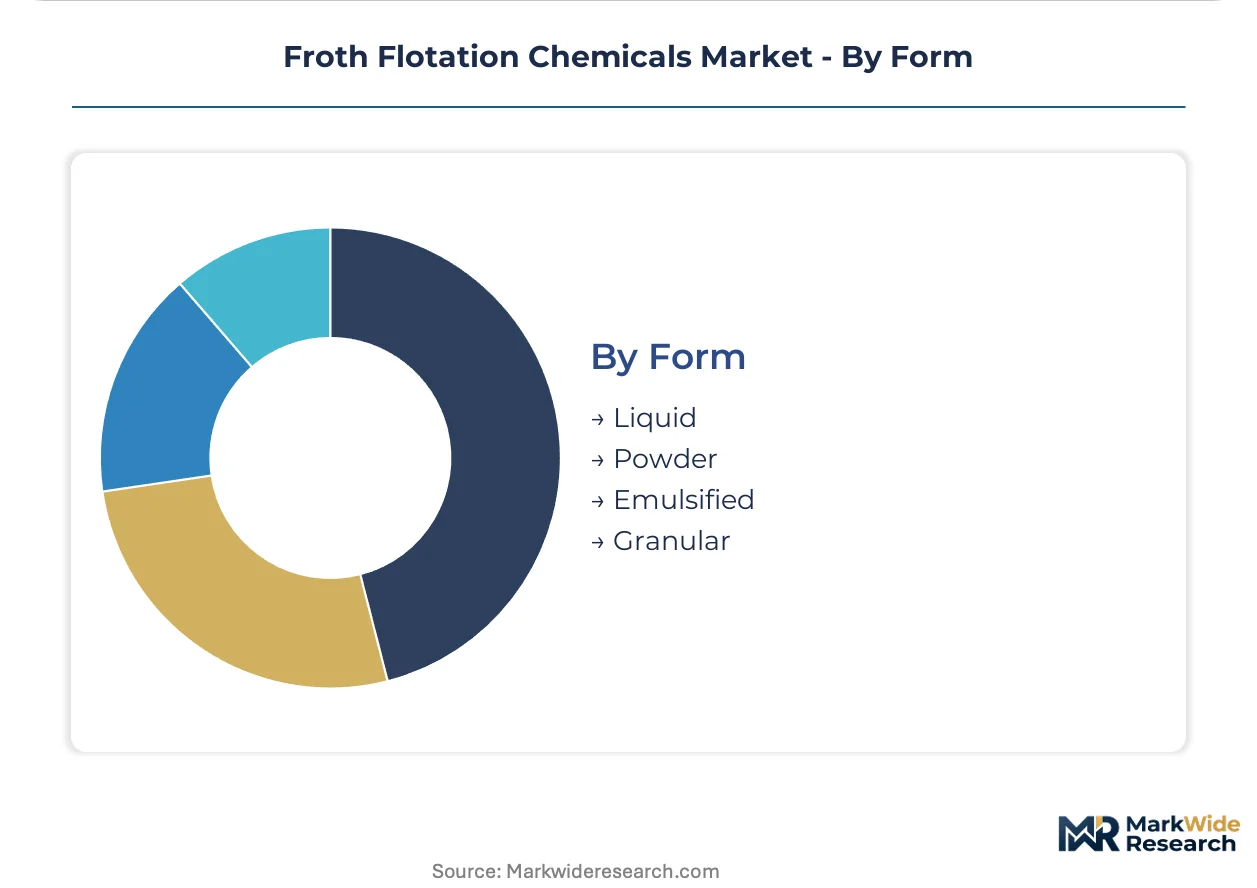
Froth flotation chemicals segment along four functional dimensions that determine formulation chemistry, delivery method, and value capture. Each axis reflects distinct procurement logics and technical requirements that suppliers must navigate.
Product Type:
Reagent replacement cycles accelerate as ore complexity rises and discharge standards tighten across mining jurisdictions.
- Flotation Collectors:Surface-active agents with thiol, hydroxamate, or amine head groups that render target minerals hydrophobic for bubble attachment. Demand concentrates in Chilean copper-molybdenum circuits where selective separation of sulfide minerals commands formulation premiums. Ore grade degradation across Andean belts amplifies consumption intensity per ton of metal produced.
- Frothers:Polyglycol ether and alcohol-based formulations that stabilize foam structure and control bubble size distribution. Australia's Pilbara iron ore operations require high-volume programs as producers process lower-grade hematite deposits. Stricter effluent protocols under Chile's SMA regulator are accelerating bio-based formulation adoption.
- Depressants:Inorganic salts and organic polymers that selectively inhibit flotation of gangue minerals. Sodium cyanide and zinc sulfate formulations dominate copper-lead separation circuits.
- Modifiers:pH regulators, dispersants, and activators that condition pulp chemistry for optimal collector performance. Lime and sulfuric acid represent commodity volume placements.
Volume placements concentrate in Flotation Collectors; the faster expansion belongs to Frothers as regulatory pressure builds for biodegradable alternatives.
Application:
Customer procurement maturity varies sharply across applications, with mining operations demanding integrated technical service while environmental buyers prioritize compliance certification.
- Mineral Processing:Primary demand axis spanning base metal sulfide flotation, iron ore beneficiation, and rare earth recovery. Chile's Escondida and Peru's Cerro Verde anchor collector consumption. Site-specific blending contracts are displacing spot procurement across South American copper belts.
- Water Treatment:Tailings remediation and acid mine drainage control represent emerging aftermarket demand as closure liabilities mount. Modified reagents from mining applications find secondary use in effluent polishing.
- Oil Sands Recovery:Bitumen flotation from Athabasca deposits requires tailored frother formulations for high-temperature, high-solids conditions.
- Recycling:Secondary raw material recovery from electronic waste and industrial slag employs adapted collector chemistries for complex feed streams.
Revenue gravity sits with Mineral Processing; Water Treatment is climbing the fastest as regulatory enforcement intensifies.
End User:
Buying power concentration differs radically between consolidated mining majors and fragmented environmental compliance buyers.
- Mining Industry:Integrated concentrators and heap leach operations represent the deepest demand pool. Vale's Carajás expansion in Brazil drives fatty amine collector demand for reverse flotation desilication. Procurement teams are consolidating supplier relationships to capture embedded metallurgical expertise.
- Chemical Industry:Formulation houses and toll manufacturers purchase intermediate reagents for downstream blending and private-label supply.
- Environmental Agencies:Government remediation programs and superfund sites procure modified reagents for legacy mine site rehabilitation.
- Oil & Gas Companies:Steam-assisted gravity drainage and produced water treatment operations require specialized frother chemistries.
Contract value concentrates in Mining Industry; Environmental Agencies are expanding most quickly as closure obligations proliferate.
Form:
Logistics economics and dosing automation compatibility drive form selection, with liquid formulations dominating high-volume continuous operations.
- Liquid:Ready-to-dose solutions preferred by automated reagent systems at major concentrators. Xanthate solutions and emulsified collectors ship in bulk ISO tanks to Chilean and Peruvian ports.
- Powder:Solid xanthate salts and granular lime for remote operations lacking liquid handling infrastructure.
- Emulsified:High-activity collector dispersions that improve dispersion kinetics in saline process water.
- Granular:Controlled-release formulations for heap leach applications requiring extended reagent contact time.
Shipment volumes concentrate in Liquid; Emulsified forms are gaining share fastest as high-ionic-strength water challenges conventional reagent performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antofagasta anchors the highest reagent consumption intensity as Chilean copper concentrators process declining ore grades through expanded flotation circuits. The Andean mining belt stretches across multiple jurisdictions where environmental regulators are tightening discharge protocols. Each national market presents distinct procurement logics shaped by ore chemistry, water scarcity, and enforcement regimes.
Chile
Copper-molybdenum selective collectors command formulation premiums at Escondida and Los Pelambres as ore complexity rises. Chile's SMA environmental regulator enforces stricter effluent limits that accelerate bio-based frother adoption. Antofagasta Region concentrators are consolidating supplier relationships into multi-year technical service contracts.
Peru
Cerro Verde and Antamina operations drive bulk xanthate consumption across the southern copper belt. Peru's OEFA environmental authority imposes discharge standards that shape reagent selection in Andean circuits. Arequipa and Ancash processing clusters are deploying machine learning-based froth imaging to optimize collector dosing.
Australia
Pilbara iron ore beneficiation requires high-volume collector programs as hematite grades decline. The country's national environmental regulator enforces aquatic toxicity thresholds that constrain polyglycol ether frother chemistries. Western Australia operations are expanding emulsified collector use to handle high-ionic-strength process water.
Brazil
Vale's Carajás expansion drives demand for tailor-made fatty amine collectors in reverse flotation desilication circuits. ANVISA chemical registration requirements influence import timelines for specialty formulations. Pará state processing facilities are adopting site-specific blending contracts to capture embedded metallurgical expertise.
United States
Arizona and Nevada copper operations consume bulk sulfide reagents for porphyry ore processing. EPA effluent guidelines constrain permissible frother chemistries, particularly for formulations with aquatic toxicity profiles. Southwestern concentrators face technical limitations when processing with saline groundwater, forcing freshwater sourcing or circuit modifications.
Froth Flotation Chemicals Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity, with specialty alkyl hydroxamate and selective collectors capturing value above bulk xanthate supply. The vendor base organizes into three strategic archetypes: integrated chemical majors with backward integration into feedstocks, specialty formulation houses with site-specific technical service capabilities, and regional toll blenders serving remote mining districts. Competitive dynamics center on multi-year supply partnerships bundling reagent delivery with on-site metallurgical support, alongside accelerated development of biodegradable frother alternatives for regulated jurisdictions.
Within the integrated chemical tier, BASF SE and Solvay anchor positions through captive supply chains and specialty formulation portfolios. Clariant AG exemplifies the technical-service archetype with tailored collector programs for specific ore chemistries. Nouryon occupies a position bridging bulk commodity supply and specialty water treatment applications. These three entities represent distinct competitive vectors: feedstock integration, formulation customization, and aftermarket environmental remediation.
| Leading Market Players |
|---|
| Nouryon |
| Solvay |
| BASF SE |
| Arkema |
| Kemira |
| Clariant AG |
| NASACO |
| Chevron Phillips Chemical Company LLC |
| Dow |
| Others |
Supply Flow & Price Mechanics
Site-specific blending contracts across Chilean and Peruvian copper belts are consolidating procurement into multi-year technical service partnerships, forcing suppliers to embed metallurgical expertise into pricing and compressing spot-market margins for commodity xanthate producers.
Pricing Analysis
Value-based pricing anchored to metal recovery rates dominates premium collector formulations, with alkyl hydroxamate and selective copper-molybdenum reagents commanding premiums over bulk sulfide programs. Price differentiation separates certified bio-based frothers for EU and Chilean SMA compliance from legacy polyglycol ethers acceptable in permissive jurisdictions. Cost compression in commodity xanthate tiers is intensifying because carbon disulfide feedstock volatility squeezes manufacturer margins. Junior mining operators in Brazil's Pará state exhibit highest price sensitivity, while integrated majors at Escondida and Cerro Verde prioritize technical service bundling over unit cost.
Supply Chain Analysis
Regional distribution centers in Antofagasta, Arequipa, and Perth anchor hub-and-spoke patterns that position liquid reagent inventories close to concentrator demand. Manufacturing concentration centers on Belgium, Germany, and China for specialty formulation houses, with Brazil and Australia hosting toll-blending operations for remote mining districts. Raw material dependencies rest on carbon disulfide for xanthate synthesis, fatty acids for amine collectors, and polyglycol feedstocks for frother production. Single-source vulnerability in carbon disulfide supply creates structural risk exposure for bulk reagent manufacturers. Distribution runs through bulk ISO tank shipments to port terminals, with final-mile delivery via specialized chemical transport to mine sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in froth flotation chemicals is consolidating around backward integration races, with formulation houses pursuing captive carbon disulfide production and mining majors locking in multi-year supply partnerships to secure metallurgical expertise.
For Market Incumbents: Extend technical service capabilities into on-site process optimization to defend against digital disruptors offering machine learning-based dosing systems. Deepen backward integration into carbon disulfide production to insulate margin structures from feedstock volatility. Lock in five-year supply partnerships with Chilean SMA-regulated operations before biodegradable frother certification becomes mandatory. For New Entrants and Emerging Players: Launch via water treatment tailings remediation channels to bypass entrenched supplier relationships in core mining procurement. Target Brazil's Carajás reverse flotation expansion for fatty amine collector white space. Pursue ANVISA fast-track registration for specialty formulations to compress entry timelines against established European suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with specialty formulation houses possessing REACH-compliant biodegradable portfolios given EU Green Deal chemistry mandates accelerating substitution timelines. Long-term viability favors suppliers with dual capability across premium selective collectors and environmental remediation reagents. Watch Chilean SMA enforcement intensity as inflection signal for bio-based formulation adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Disulfide | Captive feedstock supply insulates BASF-style bulk xanthate producers from raw material price swings. |
| Biodegradable Frother Certification | REACH-compliant formulations unlock premium positioning in EU and Chilean SMA-regulated jurisdictions. |
| Machine Learning Dosing Partnerships | Computer vision integration at Cerro Verde-type operations compresses reagent overconsumption and locks in technical service contracts. |
| Tailings Remediation Reagent Repositioning | Modified mining reagents for acid mine drainage control open aftermarket revenue as closure liabilities mount. |
| Site-Specific Blending Joint Ventures | Localized formulation capacity in Pará state reduces import dependency and captures Vale's Carajás expansion demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with concentrator metallurgists, procurement leads at major mining houses, chemical distribution channel partners, and technical R&D directors at formulation houses. Bottom-up reagent consumption estimates triangulated against top-down mining production forecasts and ore grade degradation curves. SEC 10-K disclosures from listed chemical suppliers, Chilean SMA environmental compliance databases, and Australian Bureau of Statistics mining trade data provided validation anchors.
Reconciliation of shipment volumes, import records, and concentrator consumption surveys informed the analytical framework across the analysis window. Segmentation dimensions modeled include functional reagent type, ore chemistry application, end-user procurement maturity, and regional regulatory cluster. CAGRs derived from slope-log analysis of reagent intensity per ton of metal produced, overlaid with ore grade decline trajectories and water treatment aftermarket expansion curves.
Feedstock price volatility, regulatory enforcement timing, and mining capex cycle turns are the dominant revision risks to consumption forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
1-Octanol Market