
 Antiscalant Market | 2026-2036
Antiscalant Market Size, Share, and Industry Trends Forecast 2026-2036
Antiscalant Market Analysis
Modular dosing systems bundled with remote monitoring is repositioning procurement patterns for large water treatment operators. Solenis leverages its captive supply of phosphonate chemistries to secure long-term municipal contracts. Kemira Oyj anchors Nordic industrial demand through backward integration into acrylic acid intermediates. Dow Chemical dominates membrane-specific formulations for reverse osmosis desalination plants.
Antiscalants are threshold inhibitors that interfere with crystal nucleation and growth, typically formulated with phosphonic acids, carboxylic polymers, or maleic-based copolymers at active concentrations between 2–10 ppm to prevent scale deposition on heat transfer surfaces and membrane elements. The phosphonate segment leads value contribution due to established performance in calcium carbonate suppression, though organic polymer formulations are gaining fastest in zero-liquid-discharge configurations where thermal stability above 120°C becomes critical. Application demand from desalination commands premium pricing for NSF-certified liquid formulations, while oil and gas field injection sustains volume throughput for emulsion-grade products.
EPA discharge limits under the Clean Water Act constrain phosphorus loading from cooling tower blowdown, forcing reformulation toward polyacrylate and maleic acid alternatives in US power generation. REACH registration requirements and the EU Green Deal chemicals strategy accelerate substitution timelines for persistent phosphonates across European municipal utilities. Stakeholders must monitor regulatory divergence between California's Safer Consumer Products framework and emerging state-level restrictions, as compliance fragmentation threatens to fragment formulation standardization and inflate qualification costs for multi-jurisdictional suppliers.
Market Dynamics
Regulatory pressure on phosphorus discharge is forcing wholesale reformulation across power generation and municipal utilities, compressing legacy phosphonate demand while accelerating polymer chemistry qualification cycles.
Growth Catalysts
- Desalination capacity expansion:Saudi Arabia, the United Arab Emirates, and Chile are commissioning reverse osmosis trains at record pace, each requiring NSF-certified antiscalant supply contracts.
- REACH chemical substitution mandates:ECHA registration deadlines and the EU Green Deal chemicals strategy are compelling European utilities to replace persistent phosphonates with biodegradable alternatives.
- Zero-liquid-discharge adoption:Thermal stability requirements above 120°C in ZLD configurations are pulling maleic-based copolymers into brine concentrator applications.
Market Restraints
- Acrylic acid supply concentration:Backward integration into acrylic acid intermediates limits supplier diversity, with Nordic and Gulf producers controlling critical feedstock.
- Phosphorus input cost volatility:Phosphoric acid and phosphonate precursor pricing fluctuates with phosphate rock mining output and fertilizer market diversion.
- Membrane compatibility limitations:Polymer molecular weight thresholds constrain formulation options for high-recovery nanofiltration systems.
Strategic Opportunities
- Modular dosing system bundling:Remote monitoring integration is creating new procurement channels for large water treatment operators seeking predictive maintenance capabilities.
- California regulatory divergence:The Safer Consumer Products framework is opening premium positioning for early-qualified phosphorus-free formulations ahead of federal alignment.
- Oilfield produced water reuse:Permian Basin operators are expanding emulsion-grade antiscalant demand for high-salinity injection water conditioning.
Industry Challenges
- Qualification timeline compression:NSF/ANSI 60 certification cycles and membrane manufacturer compatibility testing create 18-24 month barriers to formulation launches.
- Multi-jurisdictional compliance fragmentation:Divergent state-level phosphorus restrictions in the US threaten to splinter standardization and inflate supplier qualification costs.
- Formulation chemist scarcity:Specialized expertise in threshold inhibition mechanisms and polymer synthesis is concentrating among incumbent suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiscalant Market |
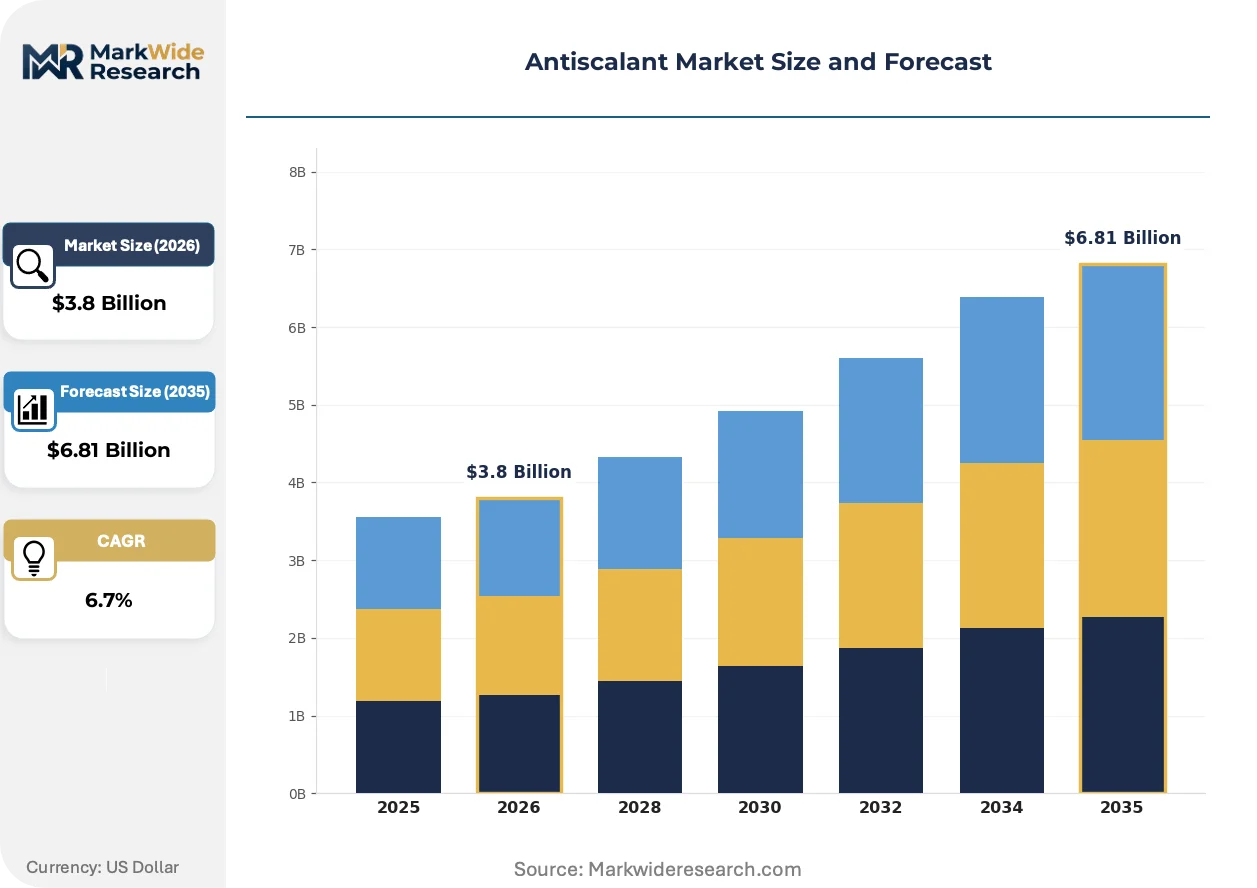
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphonates, Polyacrylate, Maleic Acid, Organic Polymer Application: Desalination, Water Treatment, Oil & Gas, Industrial Processes End User: Power Generation, Municipal, Oil Field, Chemical Plant Formulation: Liquid, Powder, Emulsion, Granule |
| Companies Covered | Solenis, Solvay SA, The Dow Chemical Company, Avista Technologies, Kemira Oyj, Ecolab, Clariant AG, Veolia, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiscalant Market Emerging Trajectories
Active chemistry substitution, digital dosing integration, and procurement model restructuring are converging to reshape competitive positioning and supplier relationships across water treatment verticals.
Phosphorus-free polymer formulations is overtaking phosphonate-based chemistries in European municipal tenders. ECHA registration requirements and the EU Green Deal chemicals strategy are compressing substitution timelines. German and Dutch utilities are now specifying biodegradable polyacrylate and maleic acid alternatives in multi-year framework agreements.
EPA discharge limits under the Clean Water Act are constraining phosphorus loading from cooling tower blowdown. US power generators are reformulating toward polyacrylate alternatives to maintain NPDES permit compliance. Texas and Florida utilities face the tightest enforcement windows, accelerating qualification of maleic-based copolymers.
Large water treatment operators are consolidating chemical procurement under performance-based contracts bundling antiscalant supply with remote monitoring. Traditional distributor relationships are compressing as municipal and industrial buyers seek predictive dosing optimization. Saudi desalination corridors and Chilean mining districts show the fastest adoption of integrated chemical-plus-service agreements.
Antiscalant Market Segmentation
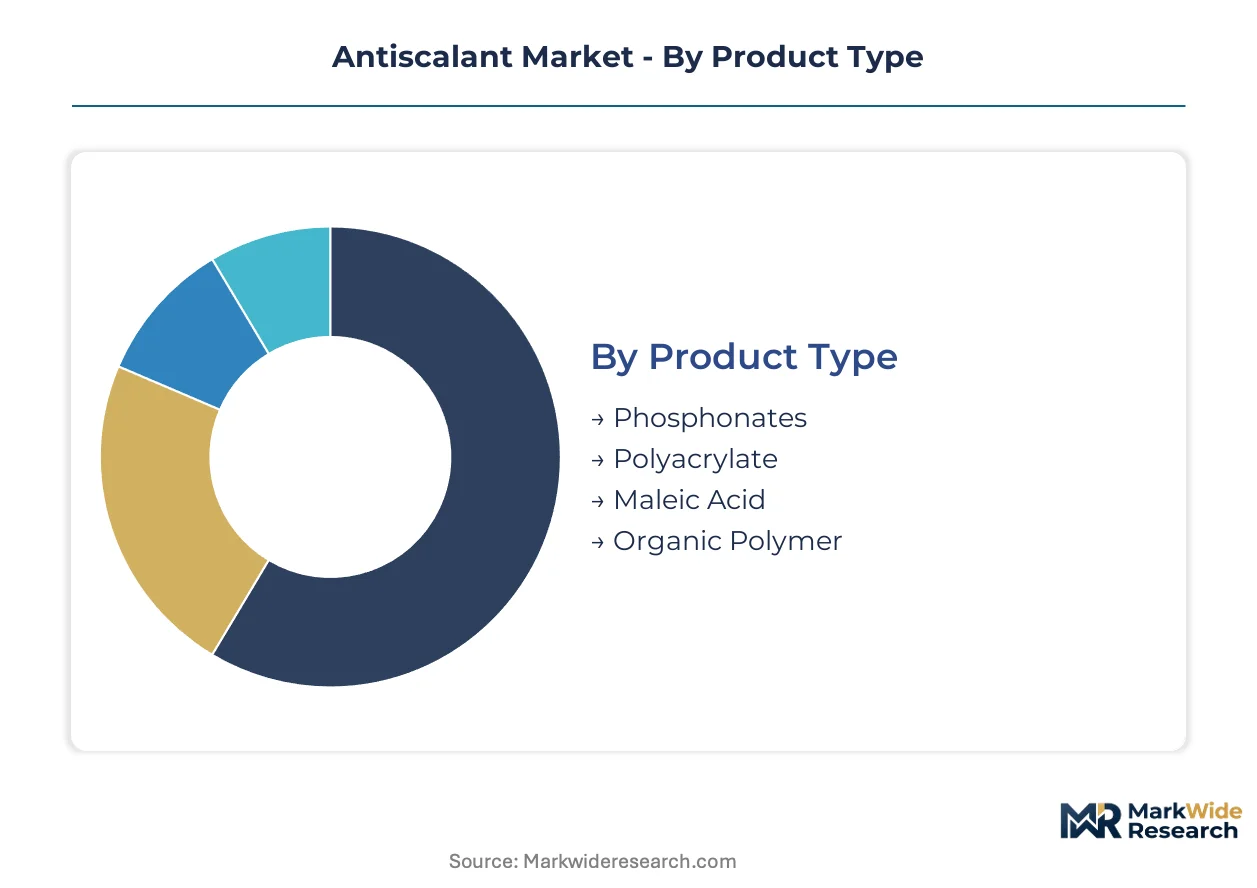
Antiscalant procurement decisions hinge on thermal stability thresholds, membrane compatibility requirements, and discharge permit constraints. Buyers segment supply by active chemistry, application severity, and formulation logistics to balance performance guarantees with regulatory compliance.
Product Type:
Cost tier dictates chemistry selection, with phosphonate premiums justified by proven nucleation inhibition against polymer alternatives trading performance for environmental acceptability.
- Phosphonates:Organophosphorus compounds such as HEDP and PBTC deliver threshold inhibition at 2-5 ppm for calcium carbonate and sulfate scales. Demand concentrates in Saudi Arabian and Chilean desalination corridors where NSF-certified liquid formulations command supply contracts from reverse osmosis operators seeking membrane warranty protection.
- Polyacrylate:Synthetic polymers with molecular weights of 2,000-10,000 g/mol disperse colloidal particles and sequester metal ions. European municipal utilities under REACH substitution mandates are accelerating qualification of biodegradable polyacrylate alternatives to replace persistent phosphonates in cooling tower and boiler applications.
- Maleic Acid:Copolymers with thermal stability exceeding 120°C serve brine concentrators in zero-liquid-discharge configurations.
- Organic Polymer:Bio-based and synthetic biodegradable formulations address EU Green Deal chemicals strategy requirements for persistent chemical phase-out.
Volume sits with phosphonates; growth tilts toward polyacrylate as REACH deadlines compress substitution timelines.
Application:
Severity of scale deposition risk and membrane replacement costs determine formulation specification and dosing automation investment.
- Desalination:Reverse osmosis and thermal distillation plants require antiscalants compatible with polyamide membranes at recovery rates above 75%. Saudi Arabia, the United Arab Emirates, and Chilean mining districts drive premium pricing for NSF/ANSI 60 certified liquids with remote monitoring integration.
- Water Treatment:Municipal and industrial softening, filtration, and membrane systems employ threshold inhibitors to extend equipment life. US power generators under EPA Clean Water Act discharge limits are reformulating cooling tower blowdown treatment toward phosphorus-free alternatives to maintain NPDES permit compliance.
- Oil & Gas:Produced water reinjection and enhanced oil recovery operations utilize emulsion-grade antiscalants for high-salinity, high-temperature reservoir conditions.
- Industrial Processes:Boiler water treatment, evaporators, and heat exchangers in chemical and manufacturing facilities deploy scale inhibitors tailored to specific foulant chemistries.
Revenue concentrates in desalination; expansion accelerates fastest in oilfield produced water reuse as Permian Basin operators tighten injection water specifications.
End User:
Procurement scale and technical specification authority separate framework agreement holders from spot buyers.
- Power Generation:Coal, gas, and nuclear facilities operate closed-loop cooling systems requiring continuous scale control. Texas and Florida utilities face the tightest EPA enforcement windows for phosphorus discharge, accelerating maleic-based copolymer qualification for cooling tower applications.
- Municipal:Drinking water and wastewater treatment plants specify NSF-certified formulations with documented membrane compatibility. German and Dutch utilities now mandate biodegradable alternatives in multi-year chemical supply frameworks.
- Oil Field:Upstream operators conditioning injection water for reservoir pressure maintenance generate volume demand for emulsion and liquid formulations.
- Chemical Plant:Process water systems in petrochemical and specialty chemical manufacturing require customized inhibition packages for complex foulant matrices.
Contract value peaks with power generators; municipal qualification velocity is climbing fastest as European substitution mandates take effect.
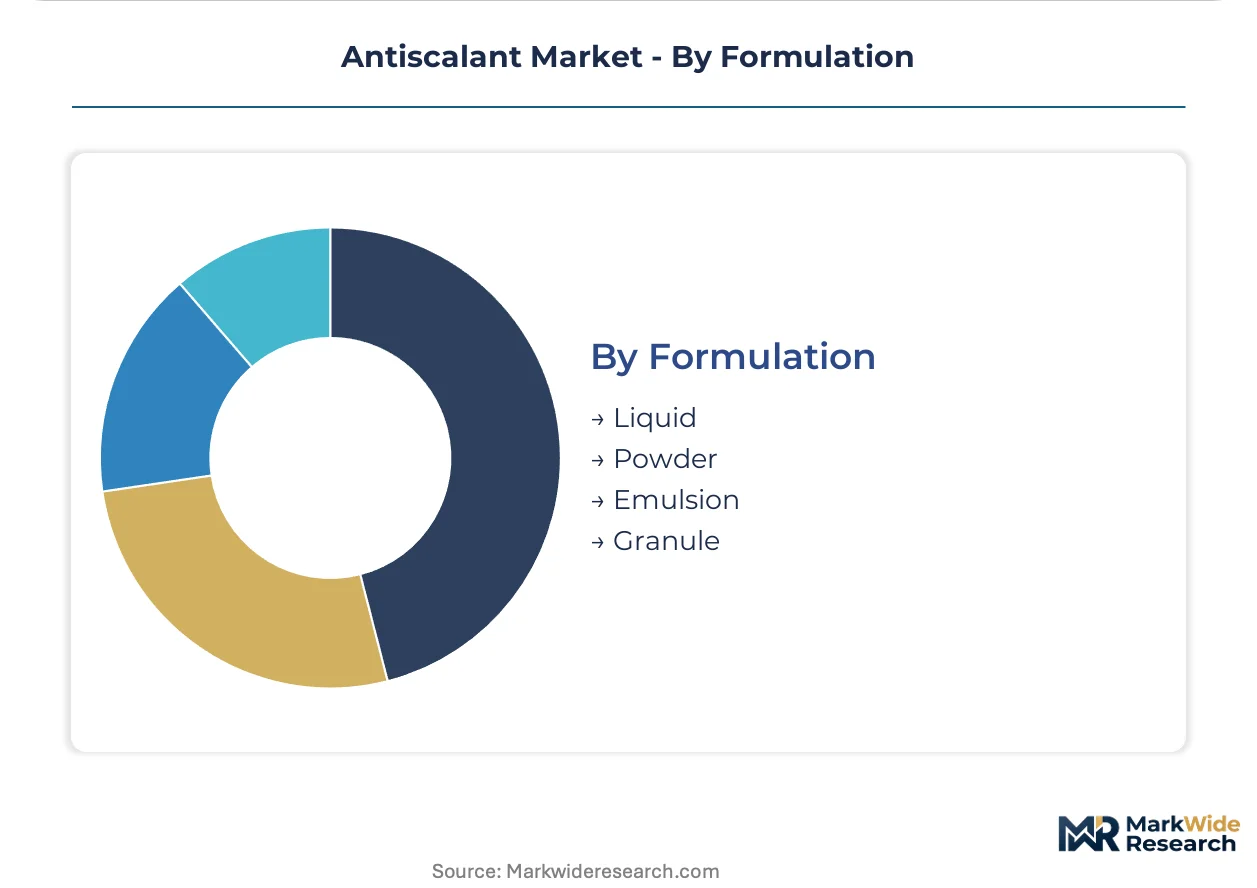
Formulation:
Logistics economics and dosing system compatibility shape physical form selection across remote and urban deployment contexts.
- Liquid:Ready-to-dose solutions dominate large-scale municipal and desalination installations with automated feed systems. NSF-certified liquid formulations from Dow Chemical and Solenis anchor premium positioning in membrane-specific applications.
- Powder:Dry concentrates reduce shipping costs for remote oilfield and mining operations with on-site dissolution capabilities.
- Emulsion:Oil-compatible dispersions serve produced water treatment in high-salinity upstream environments.
- Granule:Controlled-release solid formulations address intermittent dosing requirements in smaller industrial boiler systems.
Shipment volume favors liquid; powder is gaining fastest in remote extraction corridors where freight economics override dosing convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antiscalant production clusters in industrial chemical corridors while consumption concentrates in water-stressed regions with heavy desalination investment. This geographic split shapes supply chain logistics and regional formulation preferences.
Saudi Arabia
Desalination capacity expansion along the Red Sea and Arabian Gulf coastlines drives premium demand for NSF-certified phosphonate formulations. The Saline Water Conversion Corporation mandates membrane-compatible chemistries in all new reverse osmosis trains. Jubail Industrial City hosts the densest concentration of antiscalant blending facilities serving both domestic plants and export markets across the Gulf.
United States
Power generation utilities in Texas and Florida face accelerated EPA enforcement windows for phosphorus discharge limits under the Clean Water Act. The NPDES permit system constrains cooling tower blowdown chemistry, forcing reformulation toward maleic-based copolymers. Permian Basin oilfield operators generate expanding volume demand for emulsion-grade products conditioning high-salinity injection water.
Germany
REACH registration deadlines and the EU Green Deal chemicals strategy compress substitution timelines for persistent phosphonates in municipal utilities. ECHA mandates drive qualification of biodegradable polyacrylate alternatives in cooling and boiler applications. The Rhine-Ruhr industrial corridor anchors backward integration into acrylic acid intermediates, securing feedstock for polymer-based reformulations.
Chile
Mining districts in the Atacama Desert commission reverse osmosis trains for copper and lithium extraction processes, requiring thermal-stable antiscalant formulations. The National Geology and Mining Service regulates water reuse standards that elevate specification thresholds for membrane protection. Antofagasta and Calama cluster the heaviest dosing system deployments with remote monitoring integration.
United Arab Emirates
Abu Dhabi and Dubai utilities specify long-term framework agreements bundling antiscalant supply with predictive maintenance services. MOHAP drinking water standards and Emirates Authority for Standardization and Metrology certification requirements filter supplier eligibility. Jebel Ali industrial zone concentrates blending capacity for re-export across Middle East and North African desalination markets.
Antiscalant Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where captive feedstock access separates sustainable margin positions from commodity pressure. The vendor base spans multinational chemical conglomerates with water treatment divisions, regional specialists with backward integration into intermediates, and technology-focused membrane compatibility laboratories. Two strategic archetypes dominate: phosphonate-anchored incumbents defending desalination premiums, and polymer-focused challengers capturing European substitution mandates. Competitive moves concentrate on M&A targeting dosing system integrators and capacity expansion into acrylic acid intermediates.
Within the diversified conglomerate tier, Solenis and The Dow Chemical Company exemplify positions built on captive phosphonate supply and membrane-specific formulation expertise. Kemira Oyj represents the regional specialist archetype with Nordic industrial anchoring through upstream acrylic acid integration. These three occupy distinct competitive spaces without direct overlap in customer procurement patterns.
| Leading Market Players |
|---|
| Solenis |
| Solvay SA |
| The Dow Chemical Company |
| Avista Technologies |
| Kemira Oyj |
| Ecolab |
| Clariant AG |
| Veolia |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
REACH substitution mandates across European municipal utilities are forcing suppliers to requalify polymer formulations, compressing margin structures as R&D amortization accelerates and phosphonate incumbents defend desalination premiums.
Pricing Analysis
Margin tightening in NSF-certified phosphonate tiers reflects captive supply advantages held by desalination-focused incumbents. Three-tier pricing structure separates membrane-specific premium formulations from standard cooling tower chemistries and economy-grade oilfield emulsions. Cost-down pressure on polyacrylate alternatives accelerates because acrylic acid feedstock concentration limits supplier diversity. Municipal buyers in Germany and the Netherlands exhibit highest price sensitivity as framework agreements consolidate volume.
Supply Chain Analysis
Phosphonate production rests on phosphoric acid and phosphonate precursor availability tied to phosphate rock mining corridors in Morocco, China, and the United States. Acrylic acid intermediates for polymer formulations draw from Nordic and Gulf petrochemical complexes. Single-source vulnerability concentrates in maleic anhydride supply for thermal-stable copolymers. Distribution runs through regional blending facilities in Jubail Industrial City and the Rhine-Ruhr corridor serving membrane-specific and municipal applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic acid intermediate scarcity props pricing power for backward-integrated suppliers while constraining polymer formulation expansion.
For Market Incumbents: Cement phosphonate supply advantages in Saudi Arabian and Chilean desalination corridors through long-term SWCC and mining operator contracts. Accelerate maleic-based copolymer capacity in Texas and Florida to capture EPA-driven power utility reformulation. Threat vector concentrates in European polymer challengers capturing REACH-mandated substitution. For New Entrants and Emerging Players: Begin with biodegradable polyacrylate qualification for German and Dutch municipal frameworks where incumbent phosphonate positions are weakening. Target Permian Basin oilfield produced water reuse for emulsion-grade volume entry. Go-to-market angle emphasizes remote monitoring bundling to differentiate from commodity chemical distributors. For Investors and Strategic Acquirers: The window for entry favors acrylic acid backward-integrated specialists with European regulatory qualification velocity. Long-term viability hinges on phosphorus-free chemistry portfolios aligned with ECHA deadlines and California Safer Consumer Products frameworks. Watch for NSF/ANSI 60 certification backlog clearance as inflection signal for formulation launch capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Secures feedstock for REACH-compliant polymer formulations in European municipal tenders. |
| NSF/ANSI 60 Certification Investment | Unlocks premium positioning in Saudi desalination corridors requiring membrane warranty protection. |
| Modular Dosing System Acquisition | Enables predictive maintenance bundling with chemical supply in Chilean mining districts. |
| Phosphorus-Free Formulation R&D | Addresses EPA Clean Water Act limits tightening across Texas and Florida power generators. |
| Long-Term Desalination Framework Agreements | Locks in volume with Abu Dhabi and Dubai utilities specifying integrated service contracts. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with water treatment plant managers, municipal procurement leads, membrane manufacturer technical directors, and chemical distribution channel partners combined with secondary validation from ECHA registration databases, EPA NPDES permit records, and desalination operator procurement disclosures. Bottom-up formulation demand modeling and top-down chemical industry revenue triangulation cross-checked segment outputs.
Reconciliation of production volume data, import-export flows, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include active chemistry type, application severity tier, formulation logistics format, and regional regulatory cluster. CAGRs derived from curve-fitting historical qualification cycle data against announced desalination capacity additions and REACH substitution deadlines. Industry-specific inputs incorporated thermal stability thresholds for ZLD configurations and membrane compatibility testing protocols.
Regulatory timeline slippage, phosphonate substitution acceleration, and acrylic acid supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on qualification cycle durations and municipal framework award patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Global Neopentyl Glycol Market